
 Mobile Generators Market | 2026-2036
Mobile Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Generators Market Analytics
A shift from single-source procurement to multi-source supplier networks is expanding across the mobile generators sector. Cummins leverages its integrated engine-generator manufacturing to control cost structures in industrial ratings. Honda Power Equipment anchors the compact gasoline segment through retail channel density and brand recognition. Caterpillar dominates heavy-duty applications with dealer service networks that sustain uptime commitments for mining and oilfield clients.
Mobile generators are self-contained engine-alternator sets mounted on wheeled or skid frames, typically producing 1 kW to 3,000 kW of electrical output through electromagnetic induction from combustion-driven prime movers. Diesel configurations retain the largest installed base due to thermal efficiency and fuel availability, though biogas variants are gaining traction in agricultural and waste-processing installations where methane capture supplies free or low-cost feedstock. Construction applications command the deepest revenue pool because project timelines demand reliable off-grid power, while emergency response represents the fastest-growing application as climate-intensified disasters multiply deployment frequency.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe enforce particulate matter and nitrogen oxide limits that add exhaust aftertreatment cost and complexity to diesel units. India's Central Pollution Control Board has tightened emission norms for gensets under 800 kW, forcing manufacturers to re-engineer engines for the country's construction and telecom tower markets. Stakeholders must monitor how battery-hybrid load management systems reshape total cost of ownership calculations against conventional combustion-only architectures.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are forcing diesel engine redesigns across the mobile generator supply base, adding exhaust aftertreatment hardware that compresses margins and extends engineering cycles for manufacturers serving construction and emergency response fleets.
Growth Catalysts
- Grid Instability in India:Unreliable utility power across the country's infrastructure corridor drives rental fleet deployment for construction and telecom tower applications.
- EPA Tier 4 Final Standards:US emissions enforcement accelerates replacement demand as older diesel units face operational restrictions in federally regulated worksites.
- Battery-Hybrid Architectures:Load management systems combining lithium-ion storage with combustion prime movers reduce fuel burn and runtime hours for variable-demand applications.
Market Restraints
- Aftertreatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add 15-25% to engine bill-of-materials, squeezing price-competitive segments.
- Steel and Copper Volatility:Alternator windings and skid frames expose manufacturers to commodity input swings that resist full pass-through in rental contract pricing.
- Biogas Feedstock Inconsistency:Agricultural and waste-processing installations face methane supply variability that limits generator uptime guarantees.
Strategic Opportunities
- Telecom Tower Electrification:India's tower operators seek hybrid solutions combining solar, battery, and backup generation to cut diesel logistics costs in remote locations.
- Emergency Response Modernization:Climate-intensified disaster frequency in Southeast Asia creates demand for rapidly deployable, containerized power modules.
- EU Green Deal Alignment:Stage V-compliant rental fleets qualify for public infrastructure tenders that specify low-emission equipment, opening municipal procurement channels.
Industry Challenges
- Emissions Calibration Expertise Gap:Field service networks lack technicians trained on aftertreatment diagnostics and regeneration protocols, extending downtime for Tier 4 Final units.
- Hybrid System Integration Complexity:Synchronizing battery inverters with traditional alternators requires control software competencies outside legacy generator engineering cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Generators Market |
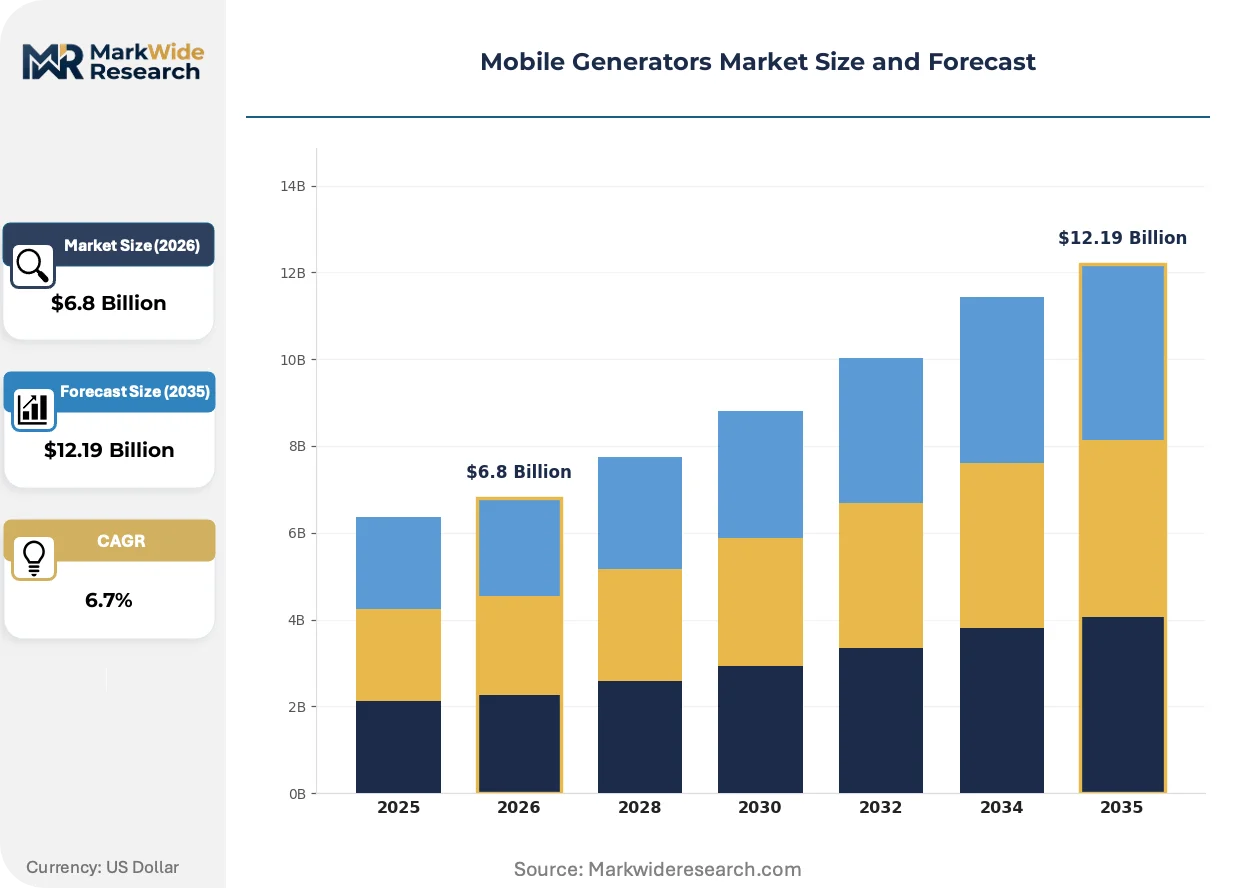
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Diesel, Gasoline, Propane, Biogas Power Rating: Portable, Standby, Industrial, Recreational Application: Construction, Events, Emergency Response, Outdoor Activities Size: Compact, Mid-Size, Large, Heavy-Duty |
| Companies Covered | Cummins, Briggs & Stratton, Generac Power Systems, Champion Power Equipment, Caterpillar, Honda Power Equipment, Kohler Co., Westinghouse Electric Corporation, Yamaha Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Generators Market Evolving Landscape
Digital load profiling and predictive maintenance algorithms are redefining how mobile power assets are specified, operated, and monetized across rental and owned-fleet models.
Telematics-enabled remote monitoring is automating dispatch decisions for rental fleets. Construction contractors in the United States now expect real-time fuel level, runtime, and fault code visibility through smartphone interfaces. This capability compresses response times for refueling and service calls, shifting competitive advantage from equipment availability to uptime assurance.
EU Stage V regulations enforce particulate matter and nitrogen oxide limits that exceed prior Stage IV thresholds. Engine manufacturers must integrate diesel particulate filters and selective catalytic reduction across the 19-560 kW power band. Agricultural and construction applications in Germany and France face the steepest compliance costs, accelerating interest in factory-certified rental units that transfer regulatory risk.
Telecom infrastructure operators in India are consolidating vendor relationships under decade-long managed power contracts. Tower companies now specify hybrid solar-diesel-battery architectures rather than procuring generators separately. This bundling displaces standalone equipment sales with integrated energy-as-a-service models, concentrating purchasing authority among four national tower operators.
Mobile Generators Market Segmentation
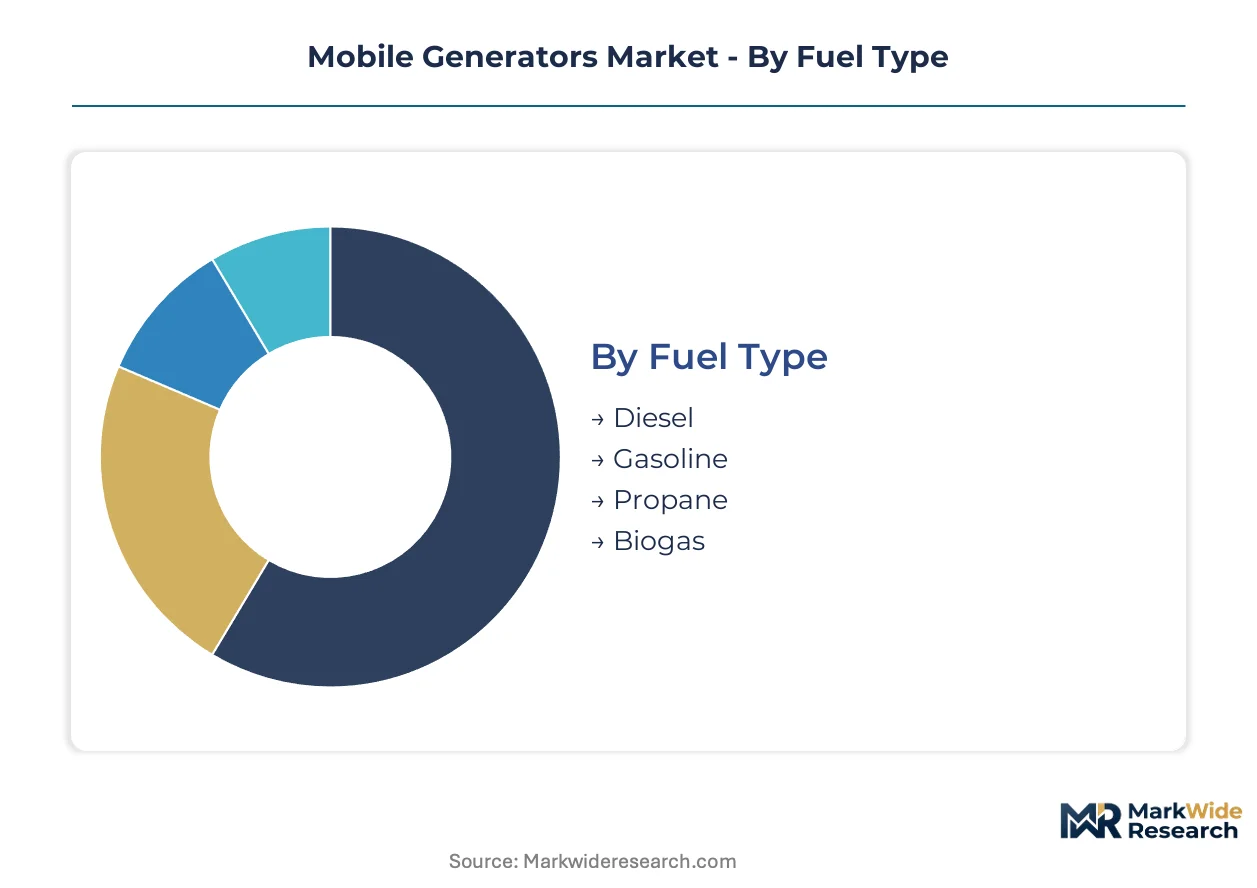
Mobile generators serve divergent duty cycles across construction sites, emergency deployments, and recreational use cases. Fuel chemistry, power output, and physical footprint each dictate procurement patterns and total cost of ownership calculations for fleet operators and rental houses.
Fuel Type:
Diesel thermal efficiency and gasoline energy density anchor divergent procurement logics across rental and owned-fleet models.
- Diesel:Compression-ignition engines deliver superior fuel economy and torque density for sustained high-load operation. Construction contractors in India's infrastructure corridor specify diesel units for multi-month project timelines where fuel logistics dominate operating cost.
- Gasoline:Spark-ignition architectures enable lighter chassis designs and faster cold-start capability for intermittent duty. Homeowners and small contractors in the United States favor gasoline portability for residential backup and light commercial applications where runtime hours remain modest.
- Propane:Cleaner combustion profile suits indoor-adjacent events and food service operations with ventilation constraints.
- Biogas:Methane-fueled units exploit captive feedstock at agricultural and waste-processing installations.
Mature deployment sits with diesel. Newer deployment is concentrated in biogas where methane capture infrastructure enables near-zero fuel cost.
Power Rating:
Output classification separates occasional-use residential assets from continuous-duty industrial machines.
- Industrial:Units exceeding 150 kW employ heavy-frame alternators and liquid-cooled engines for 24/7 operation. Mining and oilfield operators in Australia and Canada specify industrial ratings with parallel capability for megawatt-scale temporary power.
- Standby:Automatic transfer switch integration enables sub-10-second restoration for critical facilities. Hospital and data center operators in Germany prioritize standby ratings with NFPA 110 compliance for life-safety certification.
- Portable:Wheeled chassis under 15 kW serve tradespeople and emergency responders requiring rapid repositioning.
- Recreational:Inverter-based output suits sensitive electronics in camping and tailgating contexts.
Revenue concentration aligns with industrial ratings. Volume expansion is climbing the fastest in portable segments driven by rental fleet standardization.
Application:
End-use context determines runtime expectations, environmental exposure, and regulatory compliance burdens.
- Construction:Off-grid power demands span welding, crane operation, and site lighting across multi-year infrastructure builds. Contractors in Indonesia and Vietnam deploy mobile generators for grid-independent work camps where utility extension remains uneconomical.
- Emergency Response:Containerized and skid-mounted configurations enable air-lift deployment to disaster zones. Fire departments and national guard units in the Philippines and Thailand are expanding climate-response fleets as typhoon frequency intensifies.
- Events:Temporary entertainment and exhibition power requires low-noise enclosures and rapid setup.
- Outdoor Activities:Camping and mobile retail applications prioritize compact footprint and quiet operation.
Construction commands the deepest revenue pool. Emergency response is gaining share fastest as disaster preparedness budgets expand across Southeast Asian governments.
Size:
Physical envelope constraints dictate transport modality and site access requirements.
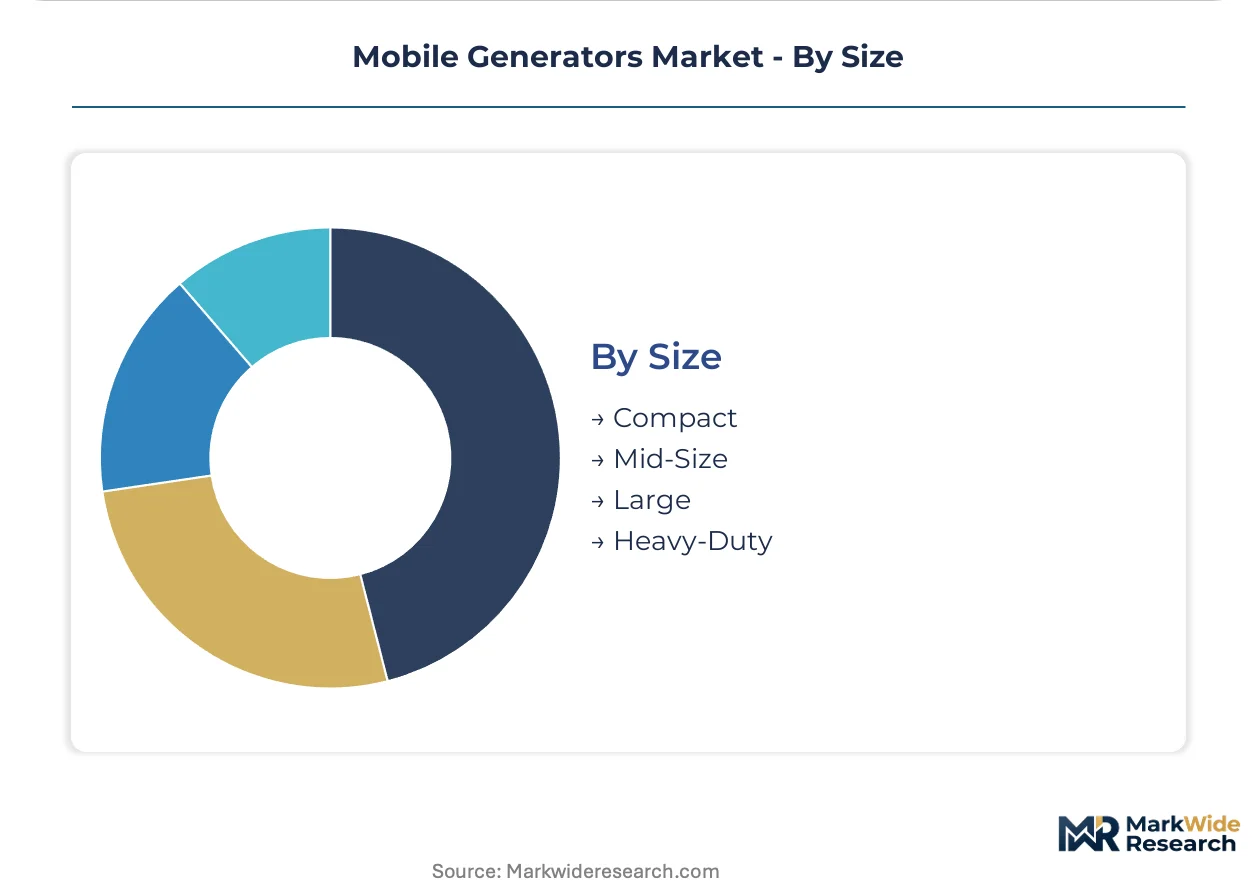
- Heavy-Duty:Trailer-mounted or skid-based units exceeding 500 kW require dedicated hauling equipment and crane-assisted placement. Remote mining operations in Western Australia and Chilean copper belts specify heavy-duty ratings for autonomous operation without grid backup.
- Compact:Hand-carriable units under 3 kW serve residential backup and mobile retail where vehicle cargo capacity limits selection. Urban contractors in Tokyo and Singapore favor compact gasoline units for elevator-transport to high-rise renovation sites.
- Mid-Size:Wheeled cart designs bridge residential and light commercial duty cycles.
- Large:Towable configurations serve medium-duration construction and event applications.
Specification gravity centers on heavy-duty for industrial procurement. Compact segments are expanding most quickly as urban density constrains equipment transport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's infrastructure corridor concentrates the steepest rental fleet deployment as grid instability forces construction and telecom operators toward captive power solutions. Southeast Asian disaster preparedness budgets and North American emissions compliance deadlines create divergent demand profiles across major economies.
United States
EPA Tier 4 Final enforcement accelerates replacement cycles for diesel units operating in federally regulated worksites. The Department of Energy and state-level air quality boards restrict older generator operation in non-attainment zones. Texas and California construction markets drive demand for telematics-enabled rental fleets with real-time fuel monitoring.
India
The Central Pollution Control Board's tightened emission norms for gensets under 800 kW force engine re-engineering for construction and telecom tower markets. The country's national infrastructure regulator mandates backup power for critical facilities. Maharashtra and Karnataka infrastructure corridors deploy rental fleets for multi-year highway and metro projects.
Germany
EU Stage V regulations enforce particulate matter and nitrogen oxide limits exceeding prior thresholds across the 19-560 kW power band. The Federal Motor Transport Authority enforces compliance certification for mobile machinery. Bavaria and North Rhine-Westphalia construction markets favor factory-certified rental units that transfer regulatory risk to lessors.
Australia
Mining and oilfield operators in Western Australia specify industrial ratings with parallel capability for megawatt-scale temporary power. The national clean energy regulator tracks diesel displacement in remote operations. Pilbara and Bowen Basin mining camps deploy autonomous heavy-duty units without grid backup for extraction operations.
Indonesia
Construction contractors deploy mobile generators for grid-independent work camps where utility extension remains uneconomical across archipelago geography. The national energy ministry prioritizes rural electrification programs. Java and Sumatra infrastructure builds concentrate rental fleet deployment for port and highway construction timelines.
Mobile Generators Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from combustion-only architectures into battery-hybrid systems. The market structures around three tiers: integrated engine-generator builders with captive powertrain production, specialized rental fleet operators with service network density, and regional assemblers sourcing alternators and engines from third parties. Strategic archetypes include emissions compliance specialists, telematics-enabled fleet managers, and agricultural biogas system integrators. Capacity expansion and technology licensing represent the dominant competitive moves as firms address aftertreatment engineering gaps.
Among integrated powertrain manufacturers, Cummins and Caterpillar exemplify the heavy-duty industrial tier with in-house engine production and dealer service networks. Honda Power Equipment anchors the compact gasoline segment through retail channel presence. These three names represent divergent scale positions: Cummins and Caterpillar occupy continuous-duty industrial applications, while Honda Power Equipment concentrates intermittent-use consumer and light commercial markets.
| Leading Market Players |
|---|
| Cummins |
| Briggs & Stratton |
| Generac Power Systems |
| Champion Power Equipment |
| Caterpillar |
| Honda Power Equipment |
| Kohler Co. |
| Westinghouse Electric Corporation |
| Yamaha Motor Corporation |
| Others |
Value Network & Pricing Analysis
Skilled diesel aftertreatment technicians concentrated in the US Midwest and Germany command wage premiums that widen pricing spreads between premium-tier EPA Tier 4 Final units and standard-tier legacy equipment. Labor-cost differentials in calibration expertise directly map to three-tier pricing structures across warranty-bundled, service-unbundled, and gray-market import segments.
Pricing Analysis
Warranty and field-service bundling separates premium OEM offerings from unbundled third-party alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales coverage depth. Cost compression in economy tiers intensifies because steel and copper volatility resists full pass-through in rental contract pricing. Small contractors and residential backup buyers exhibit highest price sensitivity, while mining operators prioritize uptime assurance over unit economics.
Supply Chain Analysis
Regional distribution centers in Texas, Maharashtra, and Bavaria operate hub-and-spoke patterns for alternator windings and engine blocks. Manufacturing draws from China for steel stampings, India for copper windings, and Germany for precision injection components. Single-source vulnerability in selective catalytic reduction catalyst substrates creates chokepoint exposure. Distribution runs through authorized dealer networks that control parts availability and service scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
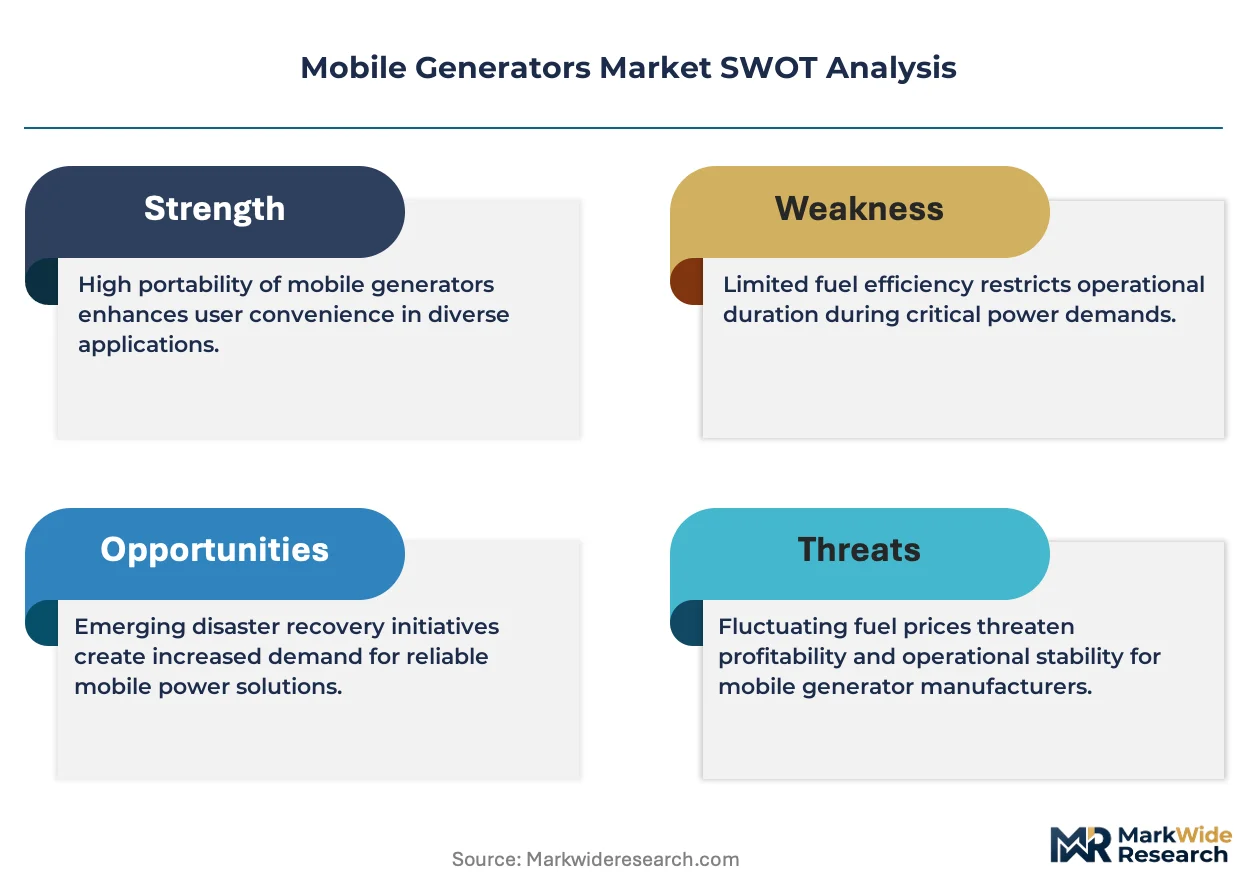
The mobile generators sector sits in a combustion-to-hybrid technology transition, with battery-inverter integration displacing conventional alternator-only architectures in variable-load applications.
For Market Incumbents: Acquire field-service networks with EPA Tier 4 Final diagnostics capabilities to close the emissions calibration expertise gap threatening uptime commitments. Deepen backward integration into lithium-ion battery management systems to control hybrid system integration complexity. Battery-hybrid entrants and rental fleet telematics mandates represent the primary threats to equipment-only revenue models. For New Entrants and Emerging Players: Containerized solar-diesel-battery hybrid systems offer a technology-first wedge into Southeast Asian disaster-response procurement channels. Target Indonesia and Philippines emergency preparedness budgets where climate-intensified deployment frequency outpaces incumbent response capacity. Pursue managed power contracts with tower operators in India's telecom infrastructure corridor. For Investors and Strategic Acquirers: Re-rating potential sits with emissions compliance specialists given EU Stage V and EPA Tier 4 Final enforcement accelerating replacement demand. Long-term viability favors asset-light fleet managers over capital-intensive engine manufacturers. Watch biogas feedstock infrastructure development as the signal indicating agricultural segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration | Battery-inverter synchronization capabilities capture telecom tower managed power contracts in India. |
| Aftertreatment Certification Investment | EPA Tier 4 Final and EU Stage V compliance opens municipal procurement channels requiring low-emission equipment. |
| Telematics Platform Deployment | Real-time fuel monitoring and predictive maintenance algorithms shift competitive advantage to uptime assurance. |
| Regional Service Network Expansion | Density in Maharashtra and Texas construction corridors compresses response times for refueling and repair calls. |
| Biogas System Integration | Methane capture infrastructure at agricultural installations enables near-zero fuel cost positioning against diesel alternatives. |
Research Methodology
Multi-period observation of rental fleet deployment patterns, emissions compliance deadlines, and commodity input costs anchored the trend analysis, supplemented by interviews with plant engineers, rental fleet operations managers, aftermarket service heads, and OEM procurement teams. Secondary validation drew from EPA enforcement databases, EU Stage V certification registries, Central Pollution Control Board notifications, customs trade records, and SEC equipment manufacturer filings. Bottom-up unit economics modeling triangulated against top-down infrastructure spending projections.
Segment-weighting across fuel type, power rating, application, and physical size dimensions drove volume and value allocation throughout the forecast period. CAGRs were derived from regression analysis against macroeconomic indicators and sector-specific demand drivers including grid instability indices, construction spending, and disaster frequency data. Hybrid adoption curves and aftertreatment cost pass-through rates served as critical forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, breakthrough battery chemistries, and geopolitical disruptions to steel or copper supply. Forecasts reflect documented assumptions about emissions enforcement consistency and infrastructure spending continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Diesel Generator Market
Generators
South Africa Diesel Generator Market
Generators
North America Gasoline Gensets Market
Generators
Construction Prime Power Generators Market
Generators
China Generator Sets Market
Generators
Southeast Asia Portable Generator Market
Generators
China Gas Generator Market
Generators
Europe Gas Generator Market
Generators
Power Generator for Military Market
Generators
Generator [Up to 100 Kva] Market
Generators
Residential Gas Generator Market
Generators
Military Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Containerized Solar Generators Market
Generators
Reciprocating Power Generating Engine Market
Generators
India Portable Generator Market