
 Heat Recovery Steam Generator Sales Market | 2026-2036
Heat Recovery Steam Generator Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Recovery Steam Generator Sales Market Insights
Modular HRSG bundling with gas turbine packages is expanding as original equipment manufacturers consolidate procurement workflows for combined cycle power projects. Siemens Energy AG leverages its turbine-HRSG integration expertise to anchor long-term service contracts across European and Middle Eastern installations. Babcock & Wilcox Enterprises Inc. competes through specialized shop-fabricated modular designs that reduce field construction duration. Doosan Heavy Industries & Construction dominates Asian utility tenders with vertically integrated manufacturing of pressure vessels and heat transfer surfaces.
A heat recovery steam generator captures exhaust thermal energy from gas turbines or industrial processes to produce steam for power generation, process heating, or mechanical drive applications. These systems operate at exhaust gas temperatures between 500°C and 600°C, utilizing finned-tube economizers, evaporators, and superheaters arranged in vertical or horizontal gas flow configurations. Horizontal drum designs lead the product type landscape due to established maintenance protocols and broad OEM service networks. Combined cycle technology configurations represent the fastest-expanding segment as utilities prioritize efficiency gains over simple-cycle peaking capacity. Dual pressure systems command premium positioning where fuel cost differentials justify the added capital intensity of multiple steam pressure levels.
The Environmental Protection Agency enforces New Source Performance Standards that mandate heat rate improvements, directly stimulating HRSG upgrades at existing natural gas facilities. The International Organization for Standardization provides ISO 16528 boiler and pressure vessel frameworks that govern material selection and welding qualifications for cross-border equipment shipments. Stakeholders must monitor carbon border adjustment mechanisms and emerging hydrogen cofiring compatibility requirements as these frameworks increasingly determine equipment specification and market access eligibility.
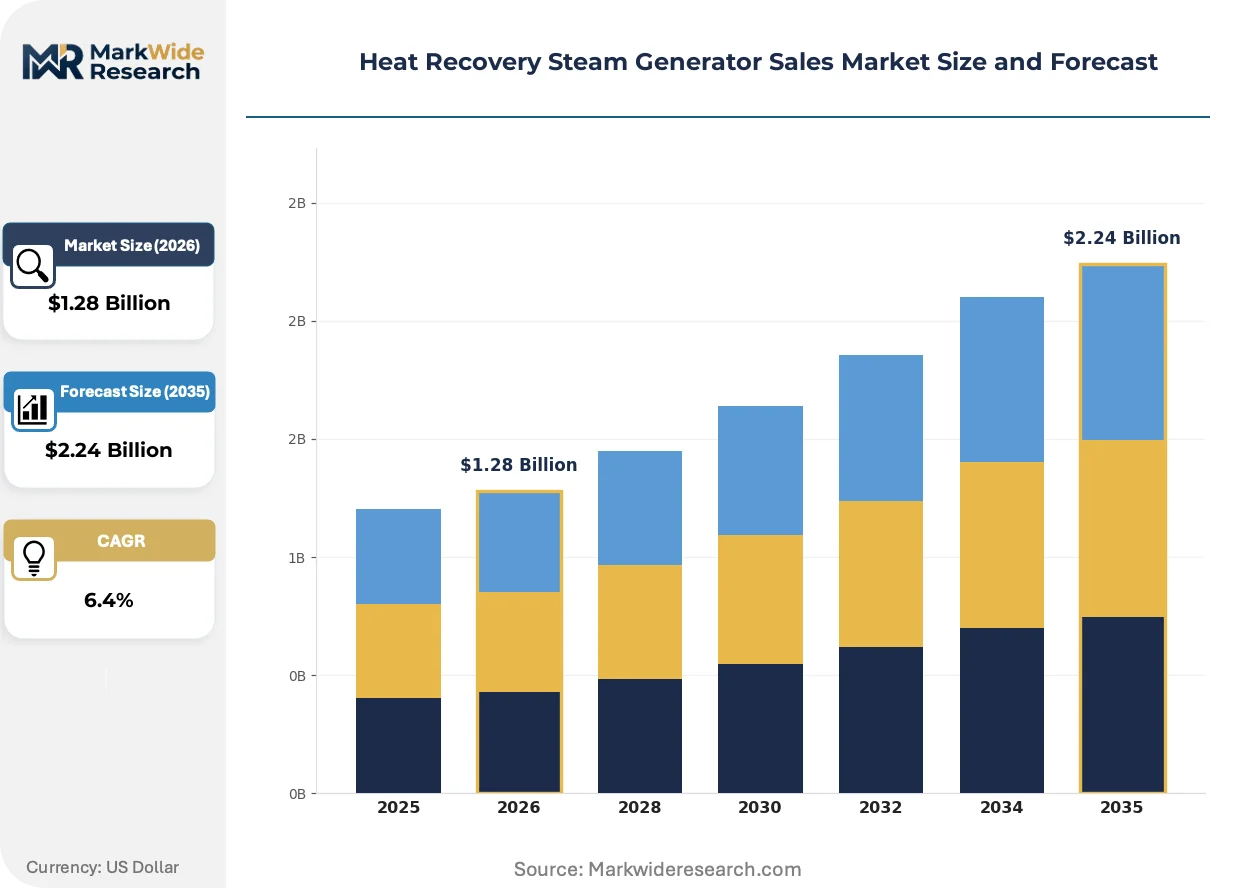
Market Dynamics
Combined cycle power plant operators are consolidating procurement around pre-engineered modular HRSG packages that compress construction schedules and reduce field labor dependencies. This structural shift toward integrated turbine-boiler sourcing is compressing the vendor landscape and elevating turnkey performance guarantees as the primary selection criterion.
Growth Catalysts
- EPA New Source Performance Standards:Heat rate mandates for natural gas facilities are accelerating replacement cycles at aging simple-cycle plants. Operators in Texas and Pennsylvania are prioritizing HRSG retrofits to avoid emissions penalties.
- Modular fabrication techniques:Shop-built pressure vessel modules reduce field construction duration by eliminating on-site welding of critical seams. Fabricators in South Korea and Japan are expanding automated tube-fin welding capacity.
- Saudi Arabia utility-scale gas expansion:The kingdom's independent power project pipeline is specifying dual-pressure HRSG configurations for combined cycle blocks exceeding 400 MW. EPC contractors are pre-qualifying suppliers with regional fabrication footprints.
Market Restraints
- Specialized alloy cost volatility:Nickel and chromium price swings directly impact superheater tube economics. Japanese steel mills control premium alloy supply for high-temperature applications.
- Chinese pressure vessel dominance:Concentrated manufacturing of boiler drums and headers creates single-source risk for Western project developers. Tariff exposure on Chinese steel imports compounds supply security concerns.
- Steam temperature metallurgical limits:Current austenitic stainless grades constrain superheated steam conditions below 565°C. Advanced nickel superalloys remain prohibitively expensive for utility-scale deployment.
Strategic Opportunities
- Hydrogen cofiring compatibility:HRSG burners and ducting designed for hydrogen-natural gas blends command premium positioning. German and Dutch utilities are specifying 30% hydrogen-ready configurations in current tenders.
- Carbon border adjustment mechanisms:EU CBAM compliance documentation is becoming a gatekeeping requirement for equipment imports. Suppliers with ISO 14064-certified fabrication facilities gain preferential access.
- Industrial process heat integration:Refinery and petrochemical operators are specifying HRSG units for combined heat and power applications. Gulf Coast chemical complexes represent underpenetrated demand.
Industry Challenges
- ASME Section I certification timelines:Pressure vessel code stamping requires extensive third-party witness testing. Backlogs at authorized inspection agencies are extending delivery schedules.
- Welding technician scarcity:Qualified pressure vessel welders for P91 and P92 chrome-moly tube materials are in short supply. Training programs at community colleges are not keeping pace with retirement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Recovery Steam Generator Sales Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Modular, Industrial End User: Power Plants, Oil Refineries, Chemical Plants, Manufacturing Facilities Technology: Single Pressure, Dual Pressure, Combined Cycle, Water Tube Application: Energy Recovery, Waste Heat Recovery, Combined Heat and Power, District Heating |
| Companies Covered | Babcock & Wilcox Enterprises Inc., Doosan Heavy Industries & Construction, General Electric Company, Bharat Heavy Electricals Limited, John Cockerill, Siemens Energy AG, Nooter/Eriksen Inc., CMI Energy, Mitsubishi Heavy Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Recovery Steam Generator Sales Market Trends and Innovations
Digital twin modeling and additive manufacturing are reshaping how HRSG components are designed, validated, and produced. These capabilities are compressing prototype cycles and enabling geometry optimization previously constrained by conventional machining.
Compact once-through steam generator designs are decentralizing project execution for distributed combined cycle applications. Small-scale industrial operators in the US Midwest are adopting these units for 50-150 MW installations. The technology is decentralizing the traditional split between utility-scale drum boilers and simple-cycle peakers.
REACH regulation amendments on per- and polyfluoroalkyl substances are restricting fluoropolymer coatings used in HRSG finned tubes. European fabricators are qualifying ceramic-based corrosion barriers as replacements. Combined cycle projects in Germany and the Netherlands are specifying PFAS-free heat transfer surfaces to preempt compliance deadlines.
Long-term service agreements are unbundling from original equipment sales as power plant operators seek specialized third-party maintenance providers. Independent service contractors are capturing HRSG inspection and tube replacement contracts from OEM service arms. This pattern is most visible in the US Southeast where merchant plant ownership has fragmented.
Heat Recovery Steam Generator Sales Market Segmentation
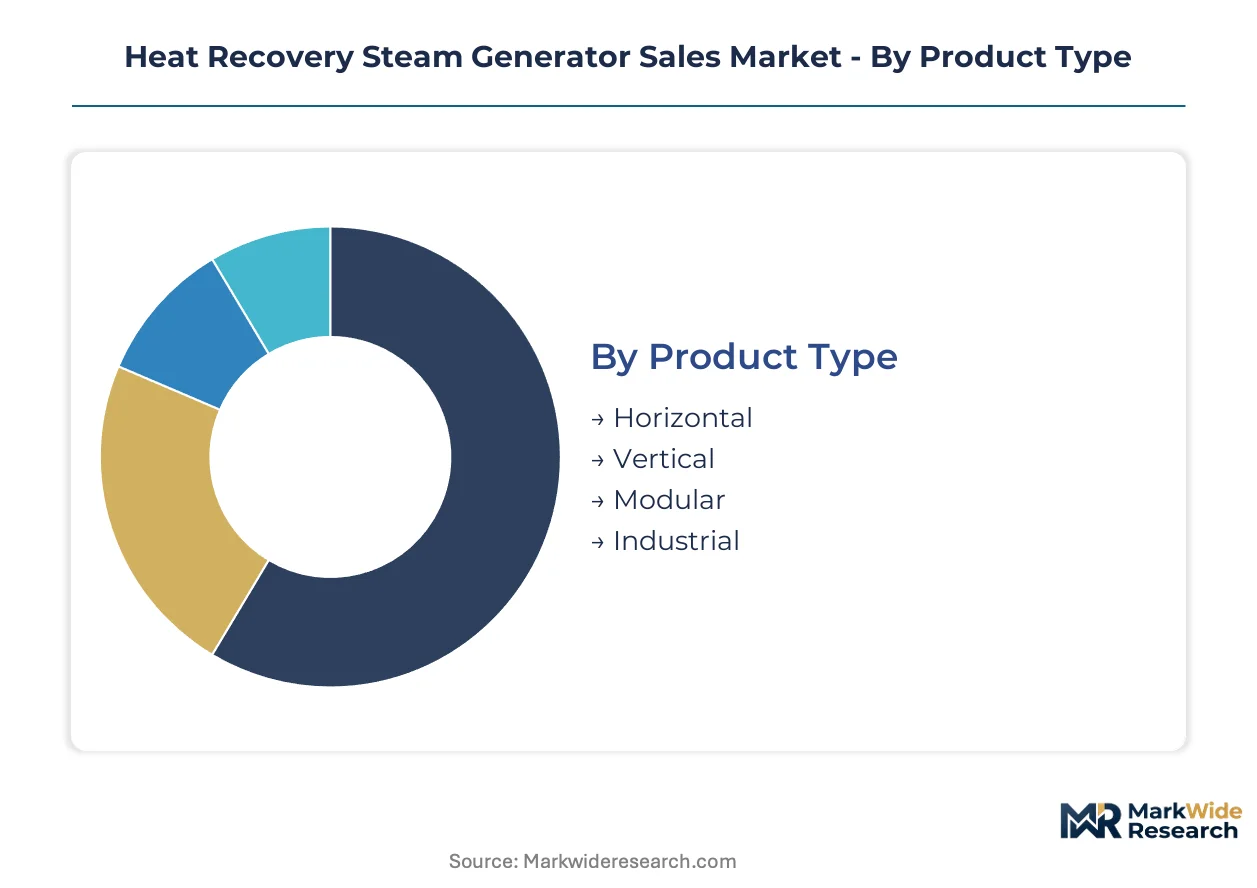
HRSG procurement patterns diverge sharply between utility-scale combined cycle installations and industrial distributed generation. Segment boundaries are blurring as modular designs penetrate smaller footprints and once-through configurations challenge traditional drum boilers.
Product Type:
Standalone HRSG units dominate utility tenders while embedded modular packages capture industrial cogeneration projects seeking compressed construction windows.
- Horizontal:Drum orientation permits established maintenance protocols and broad OEM service networks. Texas and Pennsylvania utilities specify horizontal configurations for 400 MW combined cycle blocks to minimize forced outage risk.
- Modular:Shop-fabricated pressure vessel modules eliminate field welding of critical seams. South Korean fabricators are expanding automated tube-fin welding capacity to serve Middle Eastern independent power projects.
- Vertical:Reduced footprint suits constrained plant layouts in urban industrial zones. Japanese steel mills supply specialized alloy headers for high-temperature vertical configurations.
- Industrial:Compact once-through designs serve 50-150 MW distributed generation. US Midwest chemical processors are adopting these units for process steam integration.
Horizontal designs lead volumes today; modular configurations are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive utility projects from industrial operators prioritizing operational flexibility over peak efficiency.
- Power Plants:Combined cycle operators specify dual-pressure HRSG configurations where fuel cost differentials justify added capital intensity. Saudi Arabia's independent power project pipeline is pre-qualifying suppliers with regional fabrication footprints.
- Chemical Plants:Gulf Coast petrochemical complexes represent underpenetrated demand for combined heat and power applications. Refinery operators are specifying HRSG units for process steam and mechanical drive.
- Oil Refineries:Hydrogen-ready burner specifications are emerging in German and Dutch tenders. European fabricators are qualifying 30% hydrogen cofiring compatibility.
- Manufacturing Facilities:District heating integration drives specification in Nordic industrial zones. Ceramic-based corrosion barriers are replacing fluoropolymer coatings under REACH amendments.
Power plants anchor revenue concentration; chemical plants are expanding procurement most rapidly.
Technology:
Application maturity separates proven single-pressure systems from advanced configurations constrained by metallurgical limits.
- Combined Cycle:Heat rate mandates under EPA New Source Performance Standards are accelerating replacement cycles at aging simple-cycle plants. Operators are prioritizing HRSG retrofits to avoid emissions penalties.
- Dual Pressure:Multiple steam pressure levels extract maximum thermal energy from gas turbine exhaust. Current austenitic stainless grades constrain superheated steam conditions below 565°C.
- Single Pressure:Simplified configuration reduces capital outlay for peaking applications. ASME Section I certification timelines extend delivery schedules through third-party witness testing backlogs.
- Water Tube:High heat flux tolerance suits high-cycling operation in merchant power markets. Qualified pressure vessel welders for P91 and P92 chrome-moly materials are in short supply.
Combined cycle technology commands premium positioning; dual pressure systems are climbing the fastest.
Application:
Customer type stratification separates efficiency-focused utilities from industrial operators seeking thermal integration.
- Energy Recovery:Captures exhaust thermal energy from gas turbines operating between 500°C and 600°C. Finned-tube economizers, evaporators, and superheaters maximize heat extraction.
- Combined Heat and Power:Simultaneous electricity and process steam production improves overall thermal efficiency. Long-term service agreements are unbundling from original equipment sales as operators seek specialized third-party maintenance.
- Waste Heat Recovery:Industrial process integration recovers thermal energy from cement, steel, and glass manufacturing. EU CBAM compliance documentation is becoming a gatekeeping requirement for equipment imports.
- District Heating:Urban heat networks in Northern Europe specify HRSG units for centralized thermal distribution. Suppliers with ISO 14064-certified fabrication facilities gain preferential market access.
Energy recovery dominates installed base; combined heat and power is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The heat recovery steam generator industry traces its modern scaling to post-1970s combined cycle deployment in the United States, where gas turbine exhaust heat capture became standardized for utility power generation. This American foundation established the engineering templates and certification protocols that now govern procurement across major energy markets worldwide.
United States
Texas and Pennsylvania utilities are accelerating HRSG retrofits to comply with EPA New Source Performance Standards heat rate mandates. The Environmental Protection Agency enforces emissions penalties that make aging simple-cycle plants economically unviable without exhaust heat recovery upgrades. Houston anchors the Gulf Coast fabrication corridor where modular pressure vessel modules serve domestic combined cycle projects.
China
Utility-scale gas turbine installations in coastal provinces are driving procurement of vertically integrated HRSG packages. The Ministry of Ecology and Environment enforces dual carbon goals that prioritize efficiency gains in natural gas-fired generation. Shanghai and Jiangsu province host concentrated manufacturing of boiler drums and heat transfer surfaces for both domestic and export markets.
Saudi Arabia
The kingdom's independent power project pipeline specifies dual-pressure HRSG configurations for combined cycle blocks exceeding 400 MW. The Saudi Food and Drug Authority and national procurement frameworks emphasize regional fabrication footprints for equipment qualification. Eastern Province industrial zones concentrate EPC contractor pre-qualification activities for utility-scale tenders.
Germany
Utilities in the Rhine-Ruhr and Bavaria regions are specifying 30% hydrogen-ready HRSG configurations in current tenders. ECHA REACH regulation amendments on per- and polyfluoroalkyl substances are restricting fluoropolymer coatings and accelerating ceramic-based corrosion barrier adoption. Dortmund and Munich industrial clusters host qualification programs for PFAS-free heat transfer surfaces.
South Korea
Fabricators are expanding automated tube-fin welding capacity to serve Middle Eastern independent power projects with shop-built modular designs. The Ministry of Trade, Industry and Energy supports export-oriented pressure vessel manufacturing through technology development programs. Ulsan and Changwon anchor the heavy industrial belt where HRSG module fabrication integrates with shipyard and energy equipment supply chains.
Heat Recovery Steam Generator Sales Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and turnkey performance guarantee capabilities. The vendor landscape compresses around integrated turbine-boiler sourcing as combined cycle operators consolidate procurement workflows. Three archetypes dominate: vertically integrated energy equipment conglomerates, specialized pressure vessel fabricators, and regional turnkey contractors. Competitive moves center on automated manufacturing expansion and long-term service agreement unbundling from original equipment sales.
Among vertically integrated conglomerates, Siemens Energy AG and General Electric Company occupy positions defined by turbine-HRSG integration expertise and anchored service networks. Doosan Heavy Industries & Construction exemplifies the regional fabrication archetype with concentrated Asian utility tender participation. Specialized pressure vessel expertise is represented by Babcock & Wilcox Enterprises Inc. and Nooter/Eriksen Inc., which sit within the shop-fabricated modular design tier. Mitsubishi Heavy Industries Ltd. and John Cockerill anchor geographic positions in Japanese and Belgian industrial equipment markets respectively. Bharat Heavy Electricals Limited represents state-affiliated utility-scale fabrication capacity concentrated in domestic Indian tenders.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises Inc. |
| Doosan Heavy Industries & Construction |
| General Electric Company |
| Bharat Heavy Electricals Limited |
| John Cockerill |
| Siemens Energy AG |
| Nooter/Eriksen Inc. |
| CMI Energy |
| Mitsubishi Heavy Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap pressure vessel fabricators in South Korea and Japan anchor premium alloy supply chains, translating concentrated nickel and chromium sourcing into disciplined pricing tiers that separate turnkey performance guarantees from commodity module sales.
Pricing Analysis
Project-based long-term contracting dominates procurement, with pricing stratifying across premium, standard, and economy tiers based on ASME Section I certification depth and after-sales service bundling. Cost compression in standard-grade configurations is intensifying because Chinese boiler drum imports undercut Western fabrication rates. Merchant power operators in Texas exhibit acute price sensitivity, while Saudi utility-scale IPPs prioritize performance guarantees over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle combined cycle turbine bundling, while EPC contractors source modular packages through qualified supplier networks. Manufacturing concentrates in China, South Korea, and Japan, with Chinese mills controlling boiler drum and header production. Supply chains draw from nickel superalloy feedstock, chrome-moly tube stock, and automated welding equipment. Single-source vulnerability in Chinese pressure vessel manufacturing compounds tariff exposure on steel imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HRSG market functions as a regulatory compounder, with EPA New Source Performance Standards heat rate mandates forcing replacement cycles that sustain demand independent of power price cycles.
For Market Incumbents: Acquire automated tube-fin welding capacity to compress delivery schedules and defend against South Korean fabricators expanding Middle Eastern market share. Anchor long-term service contracts through turbine-HRSG integration expertise, while investing in P91/P92 welder training programs to preempt technician scarcity bottlenecks. For New Entrants and Emerging Players: EPC contractors in Saudi Arabia's Eastern Province represent the most penetrable channel for modular HRSG qualification. Target hydrogen-ready burner specifications in German and Dutch tenders as a technical differentiation wedge, leveraging ceramic-based corrosion barrier expertise to circumvent REACH fluoropolymer restrictions. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized pressure vessel fabricators lacking turbine integration capabilities. Long-term viability hinges on hydrogen cofiring compatibility and carbon border adjustment documentation. Watch EU CBAM enforcement timelines as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Manufacturing Expansion | South Korean fabricators deploy robotic tube-fin welding to serve Saudi IPP deadlines. |
| Hydrogen-Ready Configuration Development | German utilities specify 30% hydrogen blends in Rhine-Ruhr tender specifications. |
| Long-Term Service Agreement Unbundling | Independent contractors capture inspection contracts from OEM service arms in the US Southeast. |
| PFAS-Free Heat Transfer Surface Qualification | Dortmund fabricators replace fluoropolymer coatings under ECHA REACH amendments. |
| Regional Fabrication Footprint Establishment | Eastern Province pre-qualification requirements favor suppliers with Saudi-based module assembly. |
Research Methodology
Coverage spans the United States, China, Saudi Arabia, Germany, and South Korea, with primary inputs from each. The research combines interviews with utility planning officers, EPC contractors, pressure vessel fabricators, and aftermarket service heads with secondary validation through EIA data, EPA emissions filings, FERC project databases, and IEA power generation reports. Bottom-up project pipeline tracking triangulates against top-down capacity expansion forecasts.
Segmentation models operate at product type, end user, technology, and application granularity across the projection horizon. CAGRs derive from installed base replacement cycles, gas turbine order backlogs, and regulatory compliance timelines. Fuel cost differentials, metallurgical temperature limits, and hydrogen cofiring readiness curves inform technology adoption trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementation and nickel alloy price volatility. Base assumptions include sustained EPA enforcement, Saudi IPP pipeline execution, and Chinese export capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Asia-Pacific Portable Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Dual-Fuel Generator Market
Generators
North West Europe Diesel Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Commercial Generator Market
Generators
Reciprocating Power Generating Engine Market
Generators
North America Gas Generator Market
Generators
Natural Gas Generator Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Industrial Generator Market
Generators
Industrial Generator Sets Market
Generators
Diesel Generator Market
Generators
China Generator Sets Market
Generators
Europe Gas Generator Market
Generators
Europe Portable Generator Market