
 North America Gasoline Gensets Market | 2026-2036
North America Gasoline Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gasoline Gensets Market Analysis
Modular power packages are decoupling generator sales from installation services, letting buyers mix portable units with transfer switch add-ons. Generac Holdings Inc. leverages its dealer network to control the full installation channel. Honda Power Equipment differentiates through inverter technology leadership in quiet-operation segments. Champion Power Equipment competes on price-positioned portable units stocked at national retail chains.
North America gasoline gensets are spark-ignition internal combustion engines rated typically from 1 kW to 20 kW, burning gasoline to drive an alternator producing alternating current for off-grid or backup electrical supply. Portable units dominate unit volumes in the product type dimension while standby systems capture premium margin pools tied to automatic transfer switching. Residential end users anchor absolute demand as storm-related outage frequency rises across southeastern and Gulf Coast states, though commercial emergency services segments show faster growth in mobile command and disaster response applications.
EPA certifies gasoline engines under 40 CFR Part 90 nonroad emission standards while CARB enforces stricter California-specific limits that de facto shape national product design. OSHA workplace safety rules and NFPA 110 emergency power standards constrain commercial installation practices. Stakeholders must monitor state-level building code revisions and utility interconnection rules as distributed generation policy fragments across jurisdictions.
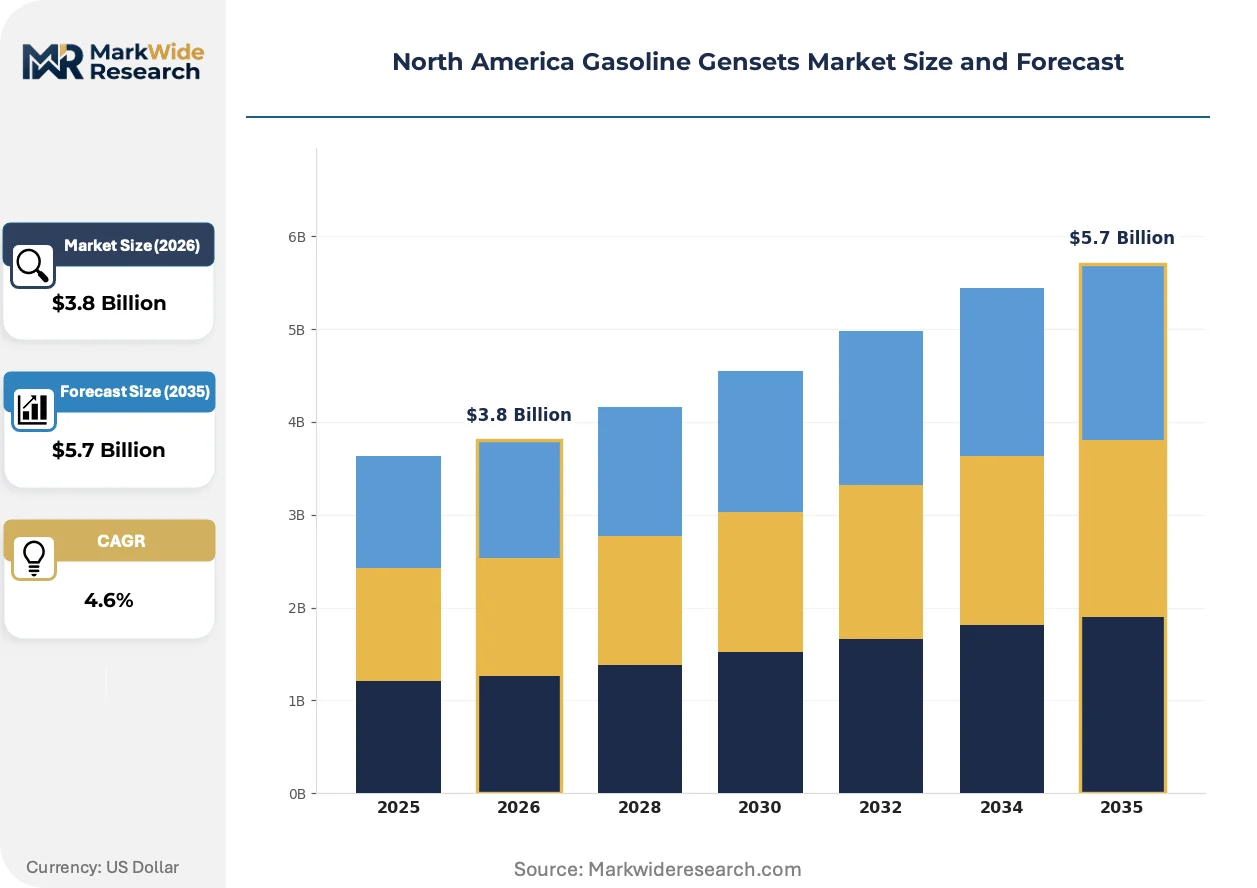
Market Dynamics
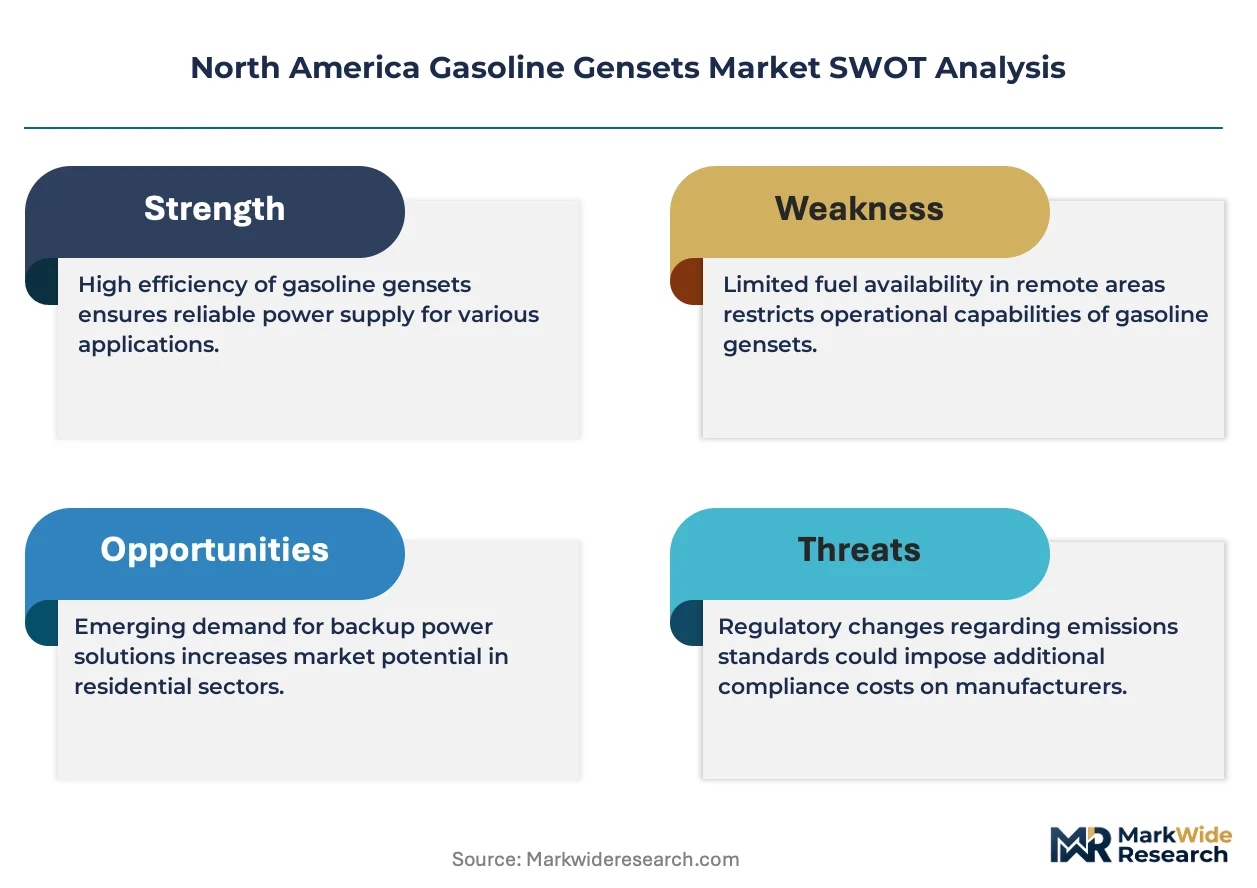
EPA Tier 4 emissions compliance and CARB certification mandates are compressing engine supplier margins while forcing rapid product redesign cycles across the North American gasoline genset supply base.
Growth Catalysts
- Grid Instability in Hurricane Corridors:Texas, Florida, and Louisiana utilities report sustained outage frequency increases, driving residential standby system penetration in coastal counties. Homeowners in these states prioritize automatic transfer switching for seamless backup power.
- NFPA 110 Commercial Mandates:Healthcare facilities and emergency services across the United States face stricter emergency power availability requirements, expanding mobile command unit deployments and disaster response fleet specifications.
- Inverter Technology Maturation:Advanced inverter gensets now deliver sine-wave output quality suitable for sensitive electronics, opening segments previously served only by battery storage or diesel units.
Market Restraints
- Steel and Aluminum Input Volatility:Generator enclosures and engine castings face commodity price swings that compress manufacturer margins without full passthrough elasticity to retail pricing.
- CARB Certification as De Facto National Barrier:California Air Resources Board standards force single-SKU national compliance strategies, raising engineering costs for products sold outside California.
- Lithium-Ion Substitution Pressure:Residential battery storage paired with solar photovoltaic arrays captures backup power demand in new construction segments, particularly in California and Hawaii where net metering policies favor electrochemical storage.
Strategic Opportunities
- Underpenetrated Canadian Prairie Provinces:Alberta and Saskatchewan rural electrification gaps and remote work cabin demand create whitespace for portable gasoline genset distribution through agricultural supply cooperatives.
- Telecom Tower Backup Spec Shift:Cellular network operators in Mexico face diesel theft and fuel logistics constraints, creating opening for gasoline-fueled micro-gensets in secondary market tower installations.
- Smart Transfer Switch Integration:WiFi-enabled load management hardware converging with genset control systems enables utility demand-response program participation, creating new revenue streams for residential standby system vendors.
Industry Challenges
- EPA Certification Timeline Compression:Engine family recertification cycles under 40 CFR Part 90 now demand 18-24 month lead times, constraining product refresh velocity and inventory planning.
- Dealer Technician Training Deficits:Complex inverter diagnostics and emissions system troubleshooting require specialized competencies that rural dealer networks struggle to staff and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gasoline Gensets Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Prime, Inverter End User: Residential, Commercial, Industrial, Emergency Services Size: Small, Medium, Large, Extra Large Technology: Conventional, Hybrid, Smart, Fuel-efficient |
| Companies Covered | Generac Holdings Inc., Honda Power Equipment, Briggs & Stratton, Champion Power Equipment, A-iPower, All-Power America, Yamaha Motor Co., Ltd., Kohler Co., Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gasoline Gensets Market Emerging Trajectories
Digital load management and emissions control integration are redefining product architecture, while channel fragmentation separates hardware sales from installation services.
Inverter generator technology is absorbing market share from conventional portable units by delivering sub-3% total harmonic distortion output suitable for medical devices and precision electronics. RV owners and food truck operators across the southern United States now specify inverter models as baseline equipment. This capability expansion is absorbing demand that previously required dual-fuel or diesel alternatives, compressing the addressable market for conventional open-frame gasoline units.
CARB's 2024 small off-road engine standards are forcing carburetor-to-fuel-injection transitions across the California market, with spillover effects into national product lines. Engine manufacturers face recalibration costs and supply chain requalification for fuel system components. The standby generator segment is responding fastest, with EFI-equipped models now standard in premium residential offerings sold from San Diego to Sacramento.
Home improvement retailers are unbundling generator hardware from installation services, letting consumers purchase portable units online and source electrical contractors separately. This disintermediation pressures traditional dealer networks that historically captured margin across both product and labor. The pattern is most visible in Texas and Florida, where big-box inventory depth and same-day pickup options reshape purchase behavior during storm season demand spikes.
North America Gasoline Gensets Market Segmentation
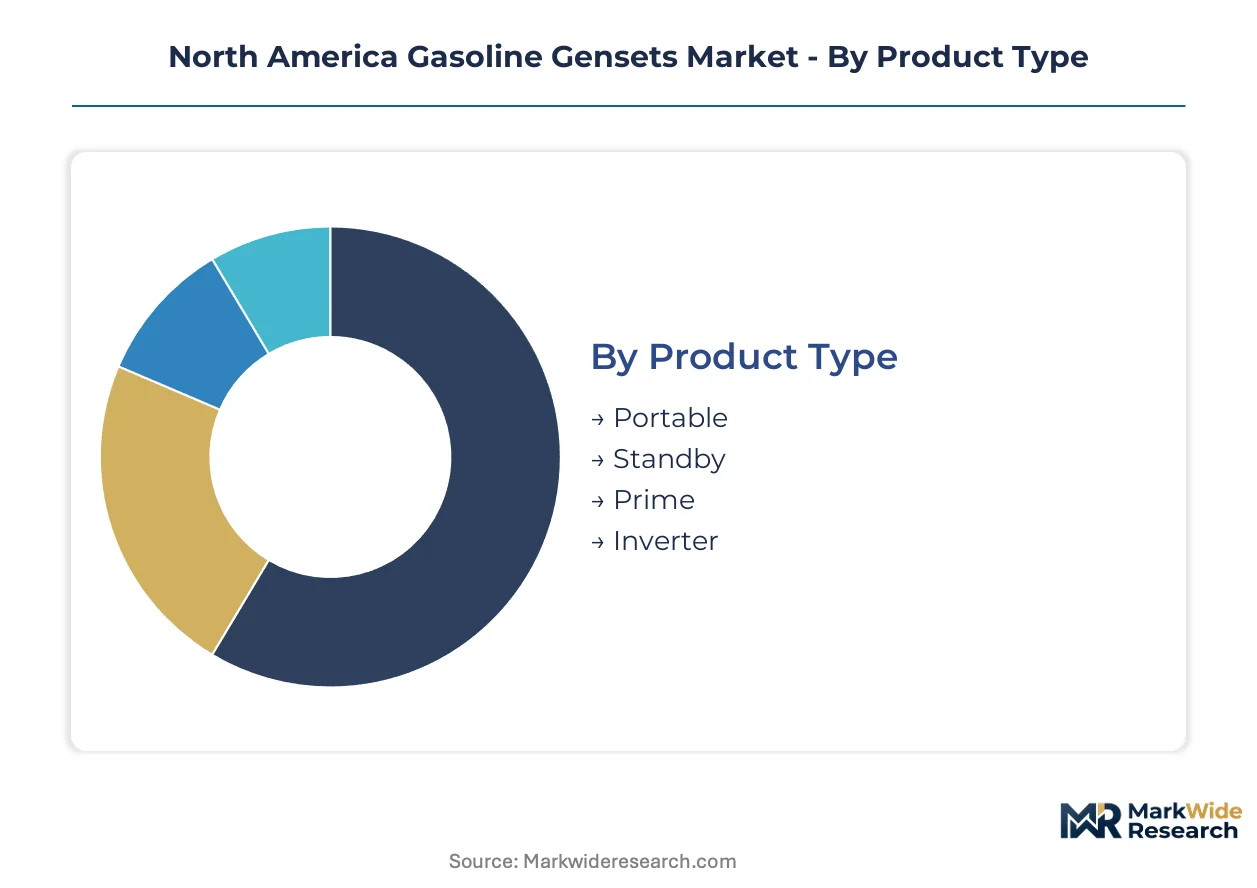
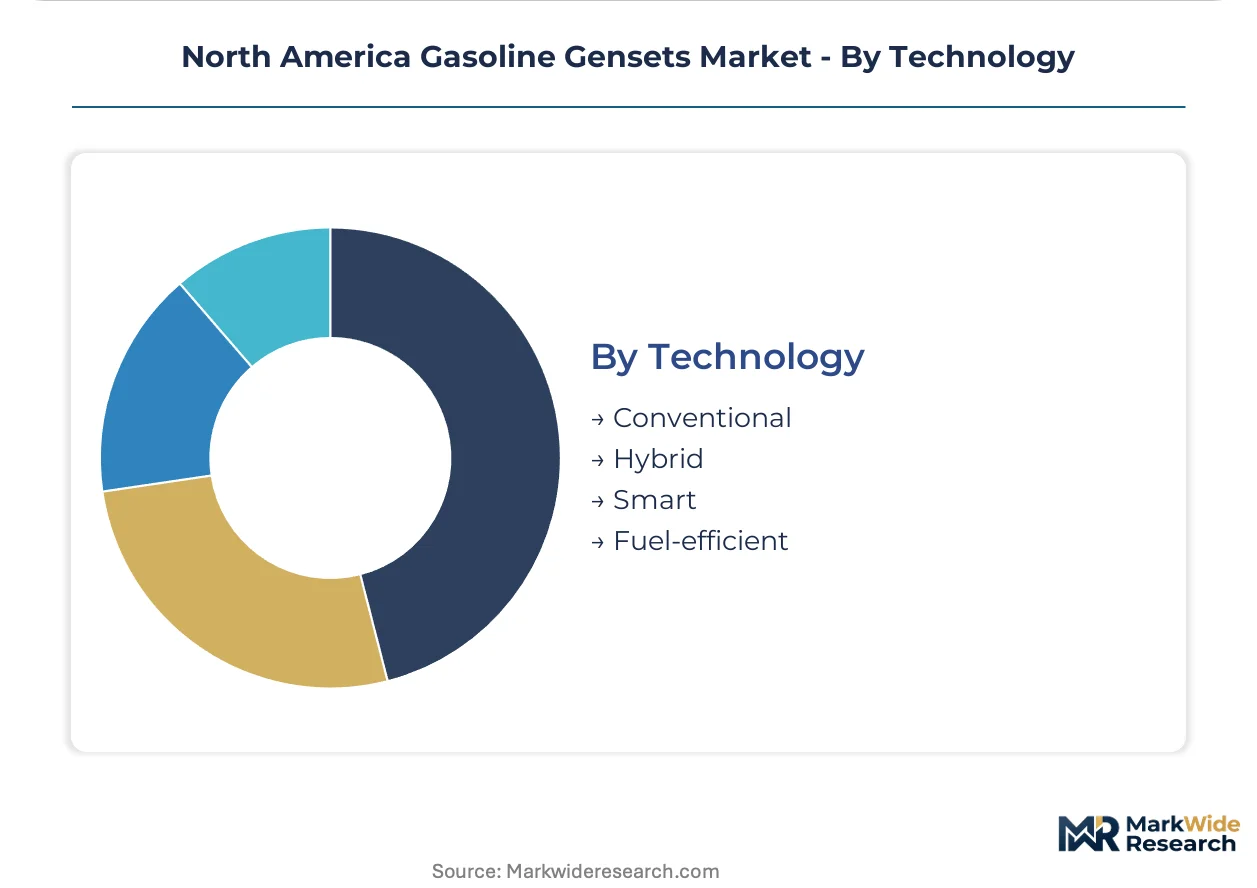
Segmentation in the North America gasoline gensets market reveals how regulatory compliance costs, installation complexity, and end-use reliability requirements fragment pricing power and channel strategy across distinct buyer clusters.
Product Type:
EPA 40 CFR Part 90 certification applies universally, while CARB standards create bifurcated compliance burdens that reshape product development priorities across portable and stationary segments.
- Portable:Units rated 1-10 kW with recoil or electric start, housed in tubular frames with wheel kits for mobility. Demand concentrates in Texas and Florida during hurricane season, where big-box retail pickup and price sensitivity dominate purchase behavior.
- Standby:Permanently installed systems with automatic transfer switching, typically 8-20 kW, enclosed in weather-resistant housings. Coastal counties in Louisiana and the Carolinas drive penetration as grid instability and homeowner insurance requirements tighten.
- Prime:Continuous-duty units for off-grid construction sites and remote work locations. Alberta oilfield services and Saskatchewan agricultural operations specify these for seasonal power needs.
- Inverter:Electronic load-matching engines delivering sub-3% THD output for sensitive electronics. RV parks across Arizona and food truck clusters in Texas cities absorb volumes as sine-wave quality becomes baseline expectation.
Portable sits at the top of the volume ranking, with Inverter climbing the fastest.
End User:
Customer procurement patterns separate emergency-mandated buyers with rigid NFPA 110 compliance deadlines from discretionary residential purchasers responding to weather events.
- Residential:Single-family homeowners prioritizing automatic backup for HVAC and refrigeration loads. Southeast Texas and South Florida suburban developments show highest standby system attachment rates following repeated grid failures.
- Commercial:Small retail, restaurants, and offices requiring business continuity during outages. California's PSPS (Public Safety Power Shutoff) events drive gas station and pharmacy backup specifications.
- Industrial:Light manufacturing and warehouse facilities with critical process loads. Mexican maquiladora zones near the Texas border use gasoline units for auxiliary power where natural gas infrastructure is absent.
- Emergency Services:Mobile command centers, disaster response fleets, and temporary medical facilities. FEMA deployment protocols and state emergency management specifications standardize portable genset requirements.
Residential commands absolute unit volumes, while Emergency Services expands most quickly on federal preparedness funding cycles.
Size:
Physical envelope and shipping constraints segment manufacturing cost structures, with small units enabling direct-to-consumer e-commerce and large systems requiring dealer-led installation services.
- Small:Under 3 kW, handheld or wheeled units for camping and light residential use. National park concessionaires and remote cabin owners in the Canadian Rockies specify these for minimal environmental footprint.
- Medium:3-8 kW range covering essential residential circuits and small commercial loads. Florida building codes increasingly require this capacity tier as minimum hurricane preparedness equipment.
- Large:8-15 kW whole-house systems with load-shedding capabilities. Texas Hill Country estates and California wildfire-prone counties drive premium positioning for automatic operation.
- Extra Large:15-20 kW and above for estate homes and small commercial campuses. Limited gasoline adoption above this threshold as diesel and propane alternatives capture commercial reliability requirements.
Medium size dominates shipment counts, with Large gaining share fastest on residential whole-house protection trends.
Technology:
CARB's 2024 small off-road engine standards accelerate technology transitions, with fuel injection and electronic control modules becoming cost-justified even in price-sensitive portable segments.
- Conventional:Carbureted engines with fixed-speed operation and higher harmonic distortion. Budget-conscious buyers in rural Mississippi and Alabama continue specifying these where inverter premiums are resisted.
- Hybrid:Gasoline-battery combinations enabling silent operation modes and peak load buffering. California solar-plus-storage adopters use these as bridge backup during battery depletion events.
- Smart:WiFi-enabled units with remote monitoring, automatic exercise scheduling, and utility interconnection readiness. Texas municipal utility demand-response pilots create early adoption clusters.
- Fuel-efficient:Electronic fuel injection and variable-speed engines reducing consumption 15-25% versus carbureted equivalents. CARB compliance requirements make this the default specification for California-bound products.
Conventional retains volume leadership, with Smart showing steepest expansion trajectory on connected-home integration priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The gasoline genset industry traces its North American scaling to post-war suburban electrification and hurricane-belt emergency preparedness campaigns that established portable power as a household staple across coastal states.
United States
Texas, Florida, and Louisiana utilities report sustained outage frequency increases from extreme weather events. EPA 40 CFR Part 90 certification governs engine emissions nationwide. Houston and Miami metropolitan areas drive standby system penetration as homeowner insurance requirements tighten.
Canada
Alberta and Saskatchewan rural electrification gaps sustain demand for portable units in agricultural and remote work applications. Environment Canada air quality guidelines influence provincial equipment specifications. Prairie Provinces distribution runs through agricultural supply cooperatives serving seasonal oilfield and farming operations.
Mexico
Cellular network operators face diesel theft and fuel logistics constraints in secondary market tower installations. Federal electricity commission interconnection rules shape backup power procurement. Maquiladora zones near the Texas border specify gasoline units where natural gas infrastructure remains absent.
California
Public Safety Power Shutoff events drive gas station and pharmacy backup specifications across wildfire-prone counties. CARB 2024 small off-road engine standards force carburetor-to-fuel-injection transitions. San Diego-to-Sacramento corridor shows fastest EFI-equipped standby generator adoption.
North America Gasoline Gensets Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive dealer networks controlling installation channels. Market concentration is moderate, with national retail distribution competing against localized service-oriented dealer systems. Two strategic archetypes dominate: full-channel integrators capturing margin across hardware and labor, and technology-focused specialists differentiating through inverter output quality. Primary competitive moves include dealer network expansion and smart connectivity feature integration.
Among North American equipment manufacturers, Generac Holdings Inc., Honda Power Equipment, and Champion Power Equipment occupy distinct positioning tiers. Generac exemplifies the full-channel integrator archetype through its captive installation network. Honda represents technology-focused differentiation anchored in power electronics expertise. Champion sits within the price-accessible portable segment distributed through national retail chains.
| Leading Market Players |
|---|
| Generac Holdings Inc. |
| Honda Power Equipment |
| Briggs & Stratton |
| Champion Power Equipment |
| A-iPower |
| All-Power America |
| Yamaha Motor Co., Ltd. |
| Kohler Co. |
| Cummins Inc. |
| Others |
Supply Flow & Price Mechanics
CARB-EFI certification tiers split the gasoline genset landscape into California-compliant premium SKUs and carbureted economy units, forcing manufacturers to maintain parallel component pipelines and dual inventory pools that inflate working capital requirements while compressing margin flexibility on non-compliant stock.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the North American gasoline genset trade, with CARB certification grade and transfer switch bundling as primary price differentiation drivers. Cost compression in portable economy segments is intensifying because steel and aluminum input volatility prevents full passthrough to retail. Residential buyers in hurricane corridors show lowest price sensitivity where insurance mandates apply, while recreational purchasers in camping and RV segments resist inverter premiums most aggressively.
Supply Chain Analysis
Dual-sourcing requirements from major retailers and dealer networks force engine manufacturers to qualify multiple fuel injection system suppliers alongside legacy carburetor vendors, extending component validation timelines. Manufacturing concentrates in China, Japan, and the United States for engine blocks and alternator assemblies. Supply chain risk centers on single-source vulnerability for EFI control modules qualified to CARB standards. Distribution runs through captive dealer networks for standby systems and big-box retail for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America gasoline gensets constitute a late-cycle quality story as residential buyers shift toward whole-house standby systems with automatic transfer switching and smart load management integration.
For Market Incumbents: Anchor market position through backward integration into EFI engine production and captive control module supply, insulating margin structures from CARB recertification cost spikes. Defend dealer network density in Texas and Florida where installation service bundling retains pricing power against retail disintermediation. Prioritize technician certification programs to close diagnostic capability gaps on inverter and smart-connected units. For New Entrants and Emerging Players: The mid-market price-point gap between premium Honda inverter positioning and Champion economy portable tiers creates whitespace for specification-focused challengers. Target Canadian Prairie Provinces through agricultural supply cooperatives where incumbent dealer networks remain thin. Pursue white-label partnerships with telecom tower operators in Mexico seeking gasoline alternatives to diesel theft exposure. For Investors and Strategic Acquirers: Consolidation pressure builds where CARB compliance costs strand sub-scale engine suppliers lacking EFI development resources. Frame long-term viability around smart connectivity and utility demand-response program participation as battery substitution accelerates in new construction segments. Monitor FEMA preparedness funding cycles as inflection indicator for emergency services segment growth velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EFI Engine Platform Standardization | CARB 2024 compliance forces unified fuel injection architectures across portable and standby product lines. |
| Smart Transfer Switch Integration | WiFi-enabled load management opens utility demand-response revenue streams for residential standby vendors. |
| Dealer Network Capacity Expansion | Captive installation channels in Texas and Florida defend margin pools against retail disintermediation. |
| Telecom Tower Backup Specification | Mexican cellular operators face diesel theft constraints that favor gasoline micro-genset penetration. |
| Canadian Prairie Distribution Partnership | Alberta and Saskatchewan agricultural cooperatives offer underpenetrated whitespace for portable unit sales. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with generator OEM product managers, dealer network operators, utility demand-response program administrators, and residential contractor installers with secondary validation against EPA certification databases, CARB executive orders, EIA electricity reliability metrics, and NFPA 110 standard documentation. Bottom-up shipment data triangulated against top-down utility outage frequency modeling.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product type, end user category, power rating tier, and technology architecture including conventional, inverter, hybrid, and smart-connected variants. CAGRs derived from trend extrapolation of residential standby penetration rates and commercial emergency services fleet specifications, with battery substitution elasticity and steel input cost indices as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for residential solar-plus-storage paired with smart inverters would alter the outlook for gasoline standby demand in new construction segments. Deviation in FEMA preparedness funding allocation or state-level building code harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Diesel Generator Market
Generators
Asia-Pacific Portable Generator Market
Generators
Military Generator Market
Generators
Asia Pacific Electric Generators Market
Generators
South America Diesel Generator Market
Generators
Silent Generator Market
Generators
Generator Sets Market
Generators
Europe Turbo Generator Market
Generators
Commercial Generator Market
Generators
Mobile Generators Market
Generators
Generator Rental Market
Generators
Containerized Solar Generators Market
Generators
Wind Turbine Alternator Market
Generators
South America Gas Generator Market
Generators
India Portable Generator Market
Generators
South Africa Diesel Generator Market