
 Middle East and Africa Gas Generator Market | 2026-2036
Middle East and Africa Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Gas Generator Market Foresight
The capability gap between integrated engine manufacturers and assembly-dependent competitors is unwinding competitive dynamics across the Middle East and Africa gas generator landscape. Caterpillar Inc leverages its captive engine foundry network to control lead times on heavy-frame industrial units destined for Nigerian oilfield electrification. Cummins Inc sustains aftermarket density through regional parts depots in Dubai and Johannesburg that reduce mean time to repair for continuous-power installations. Himoinsa anchors its position in hybrid-ready portable sets that integrate with solar-battery microgrids for remote telecom towers in East Africa.
A gas generator converts chemical energy from natural gas, biogas, or associated petroleum gas into electrical output through internal combustion or turbine prime movers, typically achieving thermal efficiencies between 35 and 48 percent in modern reciprocating configurations. The equipment serves as grid-connected peaking plant, islanded backup supply, or baseload distributed generation for facilities lacking reliable utility infrastructure. Stationary generators occupy the dominant margin pool across the Middle East and Africa, reflecting long-duration contracts for data center and hospital applications that specify dual-fuel flexibility. Reciprocating engines lead technology adoption due to their load-following precision and lower capital cost per kilowatt versus turbines below 20 megawatt scale. Hybrid systems represent the fastest-expanding technology category as developers combine gas generation with battery energy storage to capture renewable intermittency arbitrage in South African commercial estates.
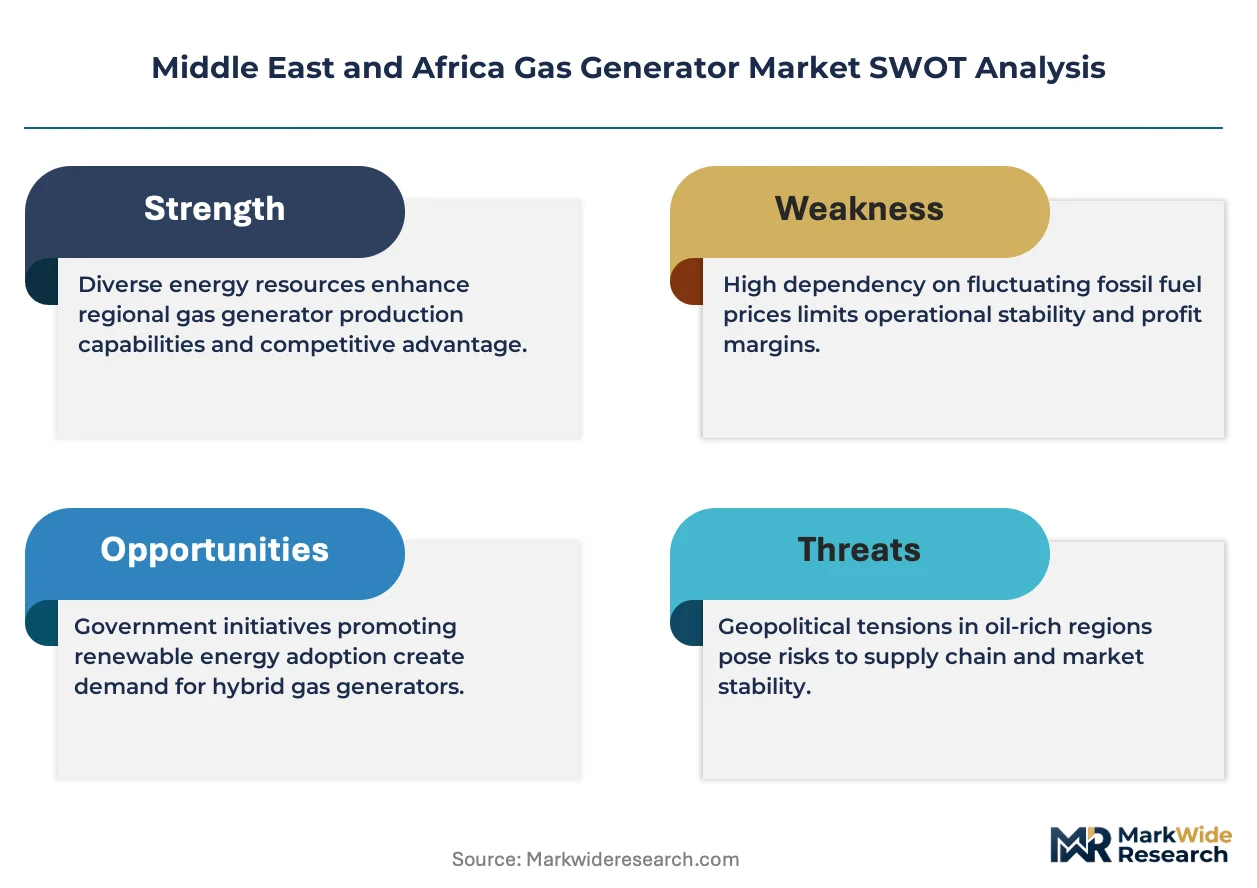
SFDA emissions protocols in Saudi Arabia and South Africa's National Environmental Management Air Quality Act constrain sulfur oxide and nitrogen oxide outputs from new stationary generator installations, pushing manufacturers toward selective catalytic reduction and lean-burn combustion architectures. The UAE's MOHAP building codes and Dubai Municipality technical guidelines mandate acoustic enclosures and automatic transfer switches for healthcare and high-rise backup power systems, creating specification barriers for non-certified suppliers. Stakeholders must monitor how Egypt's regulatory alignment with EU F-Gas Regulation affects methane slip requirements for gas engines deployed across Suez Canal Economic Zone industrial parks.
Market Dynamics
SFDA emissions protocols and Saudi Arabia's national energy efficiency mandates are compressing the addressable market for conventional rich-burn gas generators while expanding specification premiums for lean-burn and dual-fuel architectures. Manufacturers with captive combustion engineering capabilities capture margin as assembly-dependent competitors face certification delays.
Growth Catalysts
- Grid reliability volatility:Oil and gas facility operators across the Gulf Cooperation Council are expanding backup power procurement as frequency fluctuations damage sensitive subsea control systems.
- Pipeline gas access corridors:Nigeria's Lagos-Abuja industrial belt enables distributed generation deployment without LNG logistics premiums, anchoring manufacturing estate demand.
- Hybrid-ready specifications:Telecom infrastructure operators in East Africa now require generator sets with integrated solar-battery microgrid compatibility for remote tower electrification.
Market Restraints
- Steel and copper input volatility:Alternator stator windings and acoustic enclosure fabrication face commodity price swings that compress fixed-price contract margins.
- Engine block casting concentration:Heavy-frame reciprocating engine cylinder blocks rely on a limited foundry base in Western Europe and East Asia, creating lead time vulnerability.
- SFDA certification friction:Saudi Arabia's tightening emissions thresholds extend type-approval timelines by 8-14 months for manufacturers lacking in-house testing facilities.
Strategic Opportunities
- Egypt Suez Canal Economic Zone:Industrial park developers seek gas generation partners as the zone aligns with EU F-Gas Regulation methane slip requirements for export-oriented manufacturing.
- South African commercial estate hybridization:Battery energy storage convergence with gas generation captures renewable intermittency arbitrage for retail and office complexes.
- UAE healthcare infrastructure mandates:MOHAP building codes and Dubai Municipality technical guidelines create specification barriers that certified suppliers can exploit.
Industry Challenges
- Combustion calibration expertise scarcity:Lean-burn architecture deployment requires specialized field engineers familiar with NOx mapping and selective catalytic reduction tuning.
- Dual-fuel system integration complexity:Automatic transfer switch and fuel train certification for diesel-gas flexibility extends commissioning timelines for hospital and data center projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Gas Generator Market |
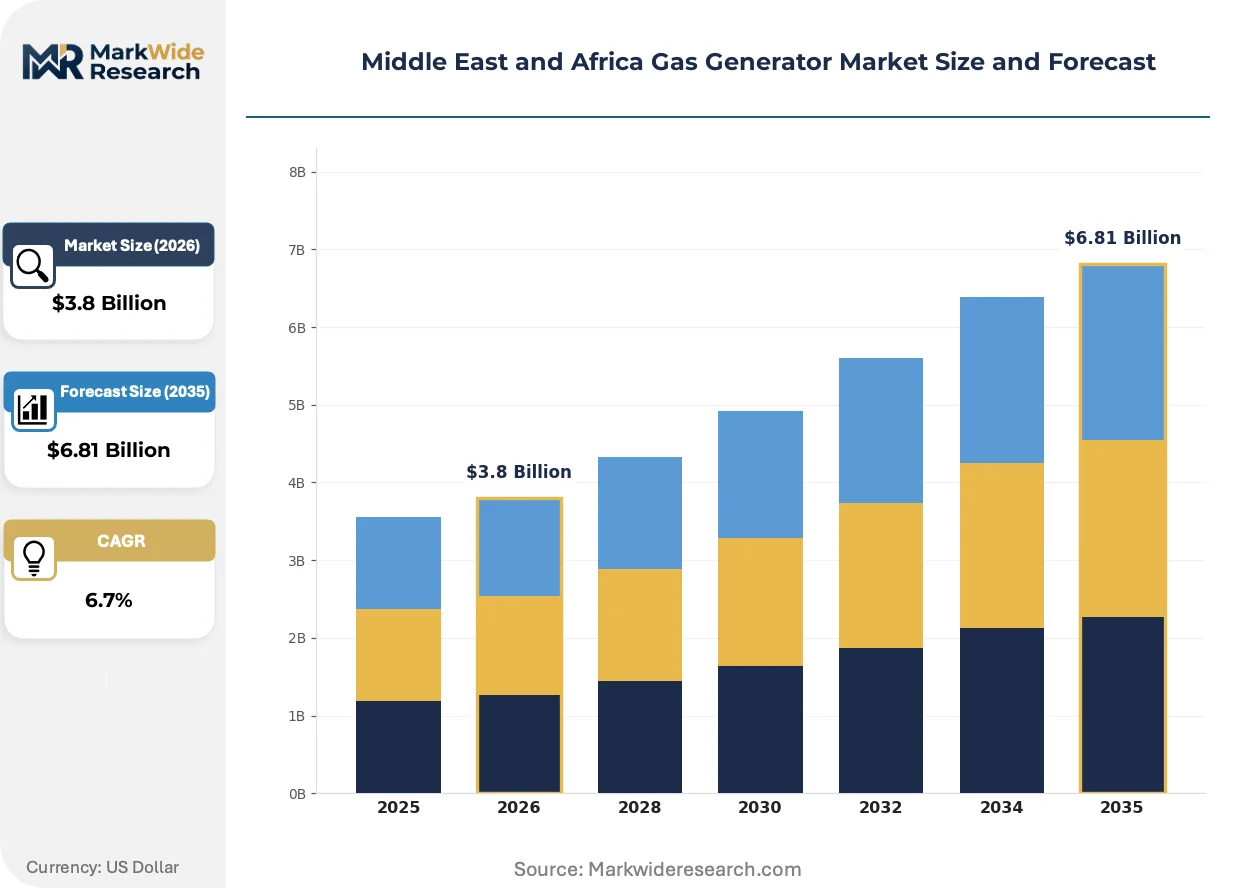
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Stationary Generators, Industrial Generators, Commercial Generators Application: Emergency Power, Peak Shaving, Backup Power, Continuous Power End User: Residential, Commercial, Industrial, Government Technology: Reciprocating Engines, Turbines, Fuel Cells, Hybrid Systems |
| Companies Covered | Generac Power Systems Inc, Cummins Inc, Caterpillar Inc, Himoinsa, Kohler Co, Atlas Copco AB, Wartsila Oyj Abp, Perkins Engines Company Limited, MTU Onsite Energy Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Gas Generator Market Shifts & Advancements
Digital twin-based predictive maintenance and modular power plant architectures are compressing traditional service revenue models while opening new performance-contracting structures. Equipment suppliers face pressure to embed intelligence or cede aftermarket value to third-party analytics platforms.
Containerized modular generator sets with factory-integrated heat recovery and exhaust after-treatment are fragmenting the project engineering value chain. Nigerian oilfield electrification contractors now specify plug-and-play 10-20 megawatt blocks that slash site installation labor. EPC firms with legacy stick-built capabilities face margin compression as procurement shifts toward equipment-led turnkey supply.
South Africa's National Environmental Management Air Quality Act amendments are forcing sulfur oxide and nitrogen oxide measurement protocols for stationary combustion installations above 1 megawatt. Industrial users in Gauteng and KwaZulu-Natal provinces accelerate selective catalytic retrofits on existing gas generator fleets. Manufacturers with certified lean-burn architectures capture replacement demand as rich-burn units face operational restrictions.
Power purchase agreement structures for captive industrial generation are displacing traditional equipment ownership models across the Gulf Cooperation Council. Saudi petrochemical complexes and UAE aluminum smelters now contract energy-as-a-service from independent power producers who retain generator asset ownership. This concentrates procurement influence among a smaller pool of creditworthy offtakers while fragmenting vendor access to end-user relationships.
Middle East and Africa Gas Generator Market Segmentation
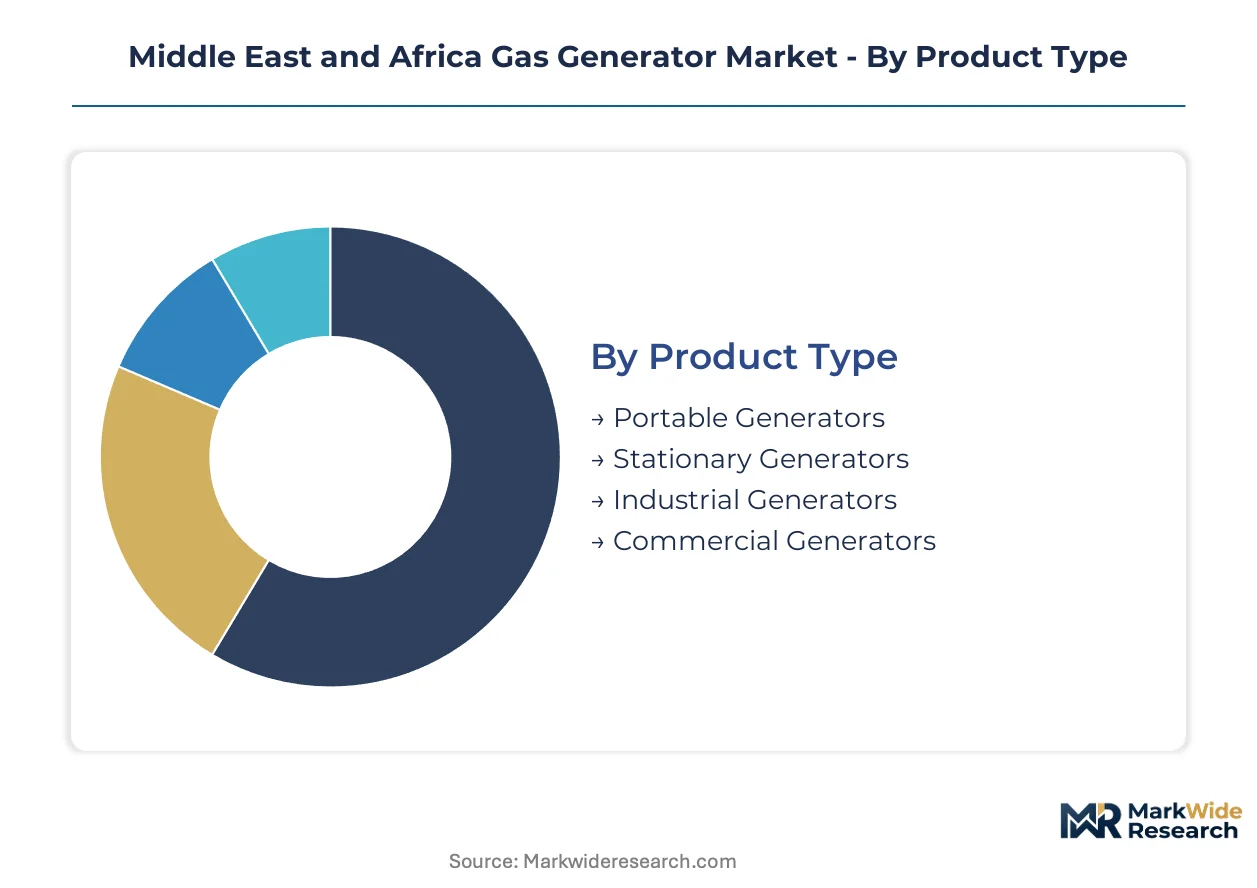
Gas generator procurement patterns across the Middle East and Africa diverge sharply between domestic infrastructure projects and export-oriented industrial zones, with regulatory environments and fuel access determining specification requirements. Segment boundaries blur as hybrid architectures and dual-fuel flexibility reshape traditional equipment categories.
Product Type:
Portable generator demand concentrates in domestic telecom and construction applications, while stationary and industrial units serve export-led manufacturing and hydrocarbon processing corridors.
- Stationary Generators:Fixed-installation units with integrated acoustic enclosures and automatic transfer switches dominate hospital and data center contracts across Saudi Arabia and the UAE. SFDA emissions mandates and MOHAP building codes in Dubai specify these configurations for healthcare infrastructure, creating specification premiums for certified suppliers.
- Industrial Generators:Heavy-frame reciprocating engines above 1 megawatt anchor Nigerian oilfield electrification and Suez Canal Economic Zone manufacturing parks. Factory-integrated heat recovery and exhaust after-treatment now come standard as Egyptian regulators align with EU F-Gas methane slip protocols.
- Portable Generators:Mobile sets with solar-battery microgrid compatibility serve remote telecom towers in East Africa.
- Commercial Generators:Mid-scale units address retail and office backup requirements in South African commercial estates.
Stationary generators hold the largest share; momentum sits with industrial generators as Egyptian and Nigerian project pipelines accelerate.
Application:
Cost tier stratification separates emergency and backup power specifications—where price sensitivity dominates residential and small commercial procurement—from continuous power contracts where fuel efficiency and uptime guarantees command premiums.
- Continuous Power:Baseload generation for facilities lacking grid access or requiring process-critical uptime, including Nigerian oilfield operations and remote mining installations. Power purchase agreement structures now displace equipment ownership across Gulf Cooperation Council petrochemical complexes.
- Emergency Power:Automatic-start systems for life-safety loads in UAE healthcare facilities and high-rise buildings. Dubai Municipality technical guidelines mandate specific transfer switch performance and enclosure acoustic ratings.
- Backup Power:Scheduled-operation units for commercial estates facing grid reliability volatility.
- Peak Shaving:Load-following installations capturing demand charge arbitrage in South African commercial and industrial rate structures.
Continuous power claims the dominant margin pool; peak shaving applications are climbing fastest as battery-gas hybrid economics improve.
End User:
Volume concentration tilts toward industrial offtakers with captive fuel infrastructure, while government procurement—though smaller in unit count—shapes standard-setting through technical mandates.
- Industrial:Manufacturing estates, hydrocarbon processing facilities, and mining operations across Nigeria's Lagos-Abuja corridor and Egypt's Suez Canal zone. Pipeline gas access eliminates LNG logistics premiums, enabling distributed generation deployment at scale.
- Commercial:Retail complexes, office towers, and hospitality assets in South Africa's Gauteng and KwaZulu-Natal provinces. National Environmental Management Air Quality Act amendments force selective catalytic retrofits on existing fleets above 1 megawatt.
- Government:Public infrastructure including healthcare, defense, and municipal water treatment.
- Residential:Standalone backup systems for high-net-worth households in grid-unreliable areas.
Industrial end users command the largest equipment value; commercial estates are gaining share fastest through hybridization mandates.
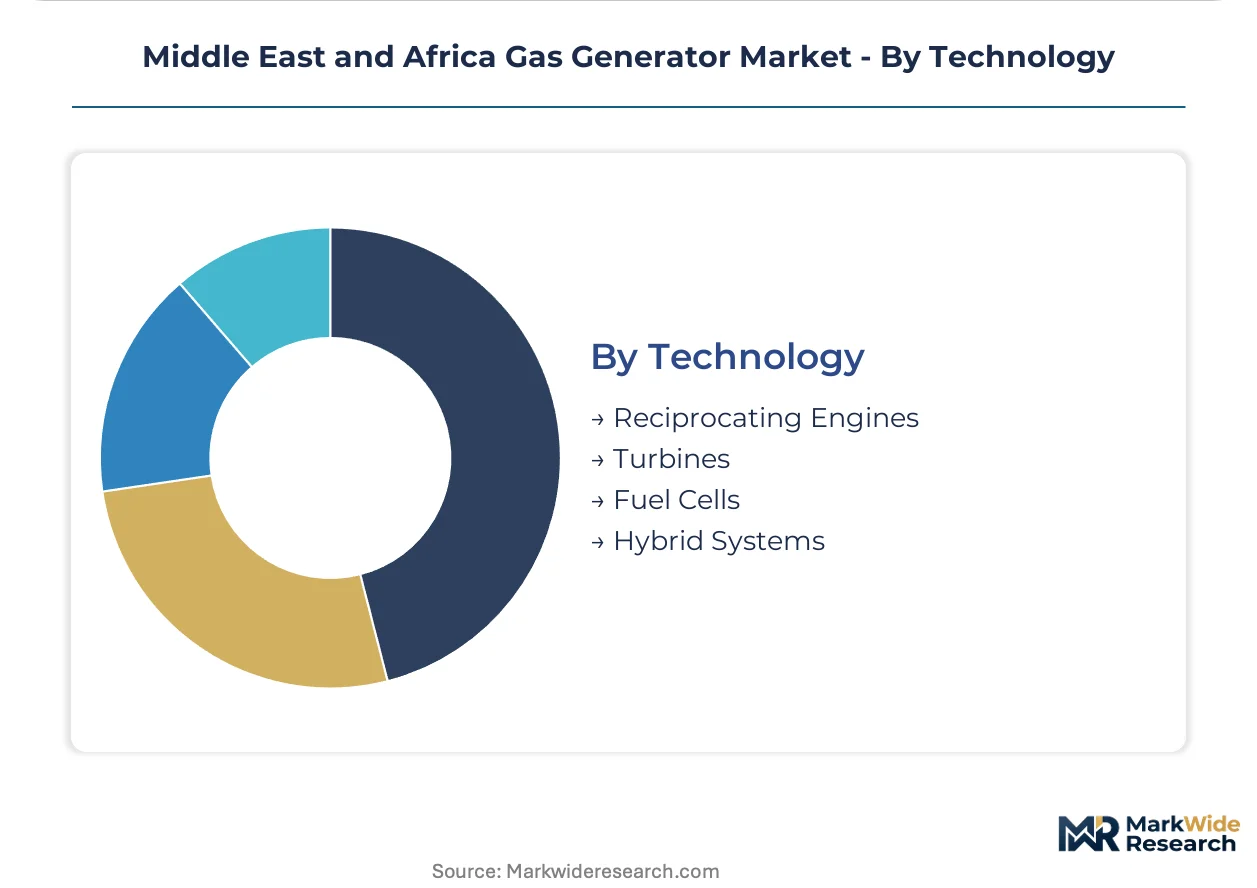
Technology:
Supply concentration in engine block casting and combustion calibration expertise favors reciprocating architectures below 20 megawatts, while turbine and fuel cell alternatives remain import-dependent with extended lead times.
- Reciprocating Engines:Internal combustion configurations achieving 35-48 percent thermal efficiency in modern lean-burn architectures. Load-following precision and lower capital cost per kilowatt dominate adoption across Nigerian manufacturing and Saudi petrochemical installations.
- Hybrid Systems:Gas generation paired with battery energy storage to capture renewable intermittency arbitrage. South African commercial developers now specify these configurations as standard for new retail and office complexes.
- Turbines:Gas turbine prime movers for large-scale baseload above 20 megawatt.
- Fuel Cells:Electrochemical conversion systems with minimal emissions profile.
Reciprocating engines retain the dominant installed base; hybrid systems show the steepest expansion trajectory as microgrid economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Nigeria's pipeline-connected manufacturing belt show the lowest price elasticity, while South African commercial estates facing hybridization mandates absorb premium specifications. Saudi Arabia's SFDA compliance costs filter out cost-driven procurement entirely. Egyptian industrial zones sit between these poles, balancing EU-aligned emissions standards against capital constraints.
Saudi Arabia
SFDA emissions protocols and national energy efficiency mandates compress conventional rich-burn generator demand while expanding premiums for lean-burn architectures. The Riyadh-Eastern Province industrial corridor anchors petrochemical complex electrification. Power purchase agreement structures displace equipment ownership, concentrating procurement influence among creditworthy offtakers.
United Arab Emirates
MOHAP building codes and Dubai Municipality technical guidelines mandate acoustic enclosures and automatic transfer switches for healthcare infrastructure. Dubai's data center cluster specifies dual-fuel flexibility for long-duration contracts. Certification barriers filter non-compliant suppliers from hospital and high-rise backup power tenders.
Nigeria
Pipeline gas access across the Lagos-Abuja industrial corridor eliminates LNG logistics premiums for manufacturing estate distributed generation. Oilfield electrification contractors specify containerized modular sets with factory-integrated heat recovery. Lead time vulnerability from heavy-frame engine block casting concentration in Western Europe and East Asia constrains project timelines.
South Africa
National Environmental Management Air Quality Act amendments force selective catalytic retrofits on existing gas generator fleets above 1 megawatt in Gauteng and KwaZulu-Natal. Battery energy storage convergence with gas generation captures renewable intermittency arbitrage for retail and office complexes. Commercial developers now specify hybrid configurations as standard for new builds.
Egypt
Suez Canal Economic Zone industrial park developers seek gas generation partners as Egyptian regulators align with EU F-Gas Regulation methane slip requirements. Factory-integrated exhaust after-treatment comes standard for export-oriented manufacturing specifications. Plug-and-play 10-20 megawatt modular blocks fragment traditional project engineering value chains.
Middle East and Africa Gas Generator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East and Africa gas generator landscape. Captive engine foundry networks control lead times for heavy-frame industrial units, while assembly-dependent competitors face certification delays from SFDA testing friction. Three archetypes dominate: integrated engine manufacturers with combustion engineering capabilities, regional assembly specialists dependent on imported blocks, and hybrid-system integrators targeting telecom microgrids. Competitive moves concentrate on selective catalytic reduction certification acceleration and modular power plant architectures that compress site installation labor.
Within the integrated manufacturer tier, Caterpillar Inc and Cummins Inc anchor positions through contrasting supply chain configurations. Caterpillar leverages foundry control for Nigerian oilfield electrification lead times. Cummins sustains aftermarket density through regional parts depots in Dubai and Johannesburg. Himoinsa occupies a specialist position in hybrid-ready portable sets for East African telecom infrastructure. These three exemplify how combustion calibration expertise and captive manufacturing capabilities separate premium-tier suppliers from assembly-dependent competitors facing extended SFDA type-approval timelines.
| Leading Market Players |
|---|
| Generac Power Systems Inc |
| Cummins Inc |
| Caterpillar Inc |
| Himoinsa |
| Kohler Co |
| Atlas Copco AB |
| Wartsila Oyj Abp |
| Perkins Engines Company Limited |
| MTU Onsite Energy Corporation |
| Others |
Supply & Pricing Matrix
Power purchase agreement structures lock in both generator asset ownership and fuel cost visibility for Saudi petrochemical complexes and UAE aluminum smelters, compressing spot-market exposure while concentrating procurement influence among creditworthy offtakers. This contract-pattern dominance shields integrated manufacturers from commodity volatility while assembly-dependent competitors absorb steel and copper input swings on fixed-price tenders.
Pricing Analysis
Aftermarket service contracts and spare parts depots drive lifetime value differentiation between Caterpillar's regional hub model and Cummins' distributed stocking strategy. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates SFDA-approved lean-burn architectures from rich-burn alternatives facing operational restrictions. Pricing pressure stems from steel and copper commodity volatility compressing fixed-price contract margins for acoustic enclosure fabrication. Industrial end users in Nigeria's pipeline-connected corridor show the lowest price sensitivity, while South African commercial estates absorb premium specifications under hybridization mandates.
Supply Chain Analysis
Germany and Finland anchor heavy-frame reciprocating engine cylinder block casting for industrial generator prime movers deployed across Nigerian oilfield electrification. Alternator stator windings draw from copper wire drawing concentration in China and India, while selective catalytic reduction catalyst substrates source from South Korean ceramics specialists. Single-source vulnerability in Western European foundry capacity creates lead time risk for projects above 10 megawatt. Distribution runs through Dubai and Johannesburg regional parts depots serving continuous-power installations with mean-time-to-repair guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around hybrid-ready specifications as East African telecom infrastructure operators mandate solar-battery microgrid compatibility, creating service-layer niches underserved by traditional equipment-only vendors.
For Market Incumbents: Consolidate combustion calibration expertise through selective acquisition of lean-burn engineering specialists facing SFDA certification delays. Add captive testing facility capacity in Saudi Arabia to compress type-approval timelines that currently extend 8-14 months for assembly-dependent rivals. Deepen backward integration into alternator stator winding production to offset copper commodity volatility on fixed-price hospital and data center contracts. For New Entrants and Emerging Players: Predictive maintenance analytics platforms represent the service-layer gap where integrated manufacturers cede aftermarket value to third-party providers. Target South African commercial estate hybridization as the most penetrable segment, where battery-gas convergence economics outpace incumbent equipment-only positioning. Pursue EPC partnership models for Egyptian Suez Canal Economic Zone plug-and-play modular blocks that fragment traditional project engineering value chains. For Investors and Strategic Acquirers: Regional assembly specialists with SFDA testing relationships and lean-burn certification pipelines offer acquisition exposure to Saudi Arabia's tightening emissions threshold expansion. Long-term viability hinges on hybrid-system integration capabilities across the 5-10 year window as microgrid economics mature. Watch selective catalytic retrofit acceleration in Gauteng and KwaZulu-Natal as the inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Lean-Burn Certification Investment | SFDA type-approval acceleration unlocks Saudi petrochemical complex procurement concentration. |
| Hybrid System Integration Partnership | Battery energy storage convergence captures South African commercial estate renewable arbitrage. |
| Regional Parts Depot Expansion | Dubai and Johannesburg stocking density reduces mean-time-to-repair for continuous-power contracts. |
| Modular Power Plant Architecture | Factory-integrated 10-20 megawatt blocks slash Nigerian oilfield site installation labor. |
| Captive Foundry Capacity Addition | Engine block casting control insulates against Western European and East Asian lead time vulnerability. |
Research Methodology
Initial hypotheses were tested against primary input from EPC contractors, IPP project developers, plant maintenance directors, and aftermarket service heads, then refined through secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up equipment shipment aggregation and top-down macroeconomic triangulation converged on segment-level estimates. Primary fieldwork concentrated on Saudi petrochemical complexes, Nigerian manufacturing estates, and South African commercial developments.
Variance decomposition across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type shaped the analytical framework. CAGRs were derived from modeled segment trajectories across the analysis window, with cross-validation against pipeline gas access corridors and hybridization mandate penetration curves. Forecast inputs incorporated SFDA emissions protocol alignment timelines and EU F-Gas Regulation methane slip adoption rates for Egyptian industrial zone specifications.
Underlying assumptions cover regulatory enforcement continuity, commodity price band stability, and pipeline gas infrastructure expansion, with deviation risk concentrated in engine block casting supply disruption and SFDA certification timeline extension. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Reciprocating Power Generating Engine Market
Generators
Digital Inverter Generator Market
Generators
Global Diesel Gensets Market
Generators
North America Diesel Generator Market
Generators
Power Generator Rental Market
Generators
South America Gas Generator Market
Generators
Silent Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
North America Gas Generator Market
Generators
Generator Sales Market
Generators
Emergency Power Generators Sales Market
Generators
Hand Crank Power Generator Market
Generators
Turbo Generator Market
Generators
Tanzania Diesel Generator Market
Generators
East Africa Diesel Generator Market