
 China Gas Generator Market | 2026-2036
China Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
China Gas Generator Market Outlook
GB/T 2820 certification is collapsing the supplier pool for grid-parallel gas generator systems in China. Cummins Inc leverages its localized engine production base in Wuhan to sustain cost competitiveness against import-dependent rivals. Caterpillar Inc anchors its position through captive distribution networks servicing Sinopec's petrochemical complexes. Weichai Power differentiates via in-house combustion R&D tailored to low-calorific domestic natural gas.
A gas generator converts chemical energy from gaseous fuels into electrical power through internal combustion or turbine-driven alternators, with prime movers typically rated between 10 kW and 50 MW and requiring precise air-fuel ratio control to manage NOx emissions below 250 mg/Nm³. These units serve continuous industrial baseload, emergency backup, and remote off-grid applications where grid extension proves uneconomical. Industrial generators dominate installed capacity across China's coastal manufacturing belts, while standby generators capture margin pools in healthcare and data center verticals demanding sub-10-second start compliance. Natural gas configurations lead fuel type demand, though biogas segments gain structural support from provincial carbon-neutrality procurement mandates.
MIIT enforces GB 20891 emission tiers for non-road gas engines, compelling manufacturers to adopt after-treatment systems or risk market exclusion. SAMR administers CCC certification for electrical safety, creating a dual-gate compliance burden that filters out uncertified assemblers. The National Energy Administration's distributed generation guidelines further shape project economics by streamlining grid interconnection protocols for captive power installations. Stakeholders must monitor how provincial carbon intensity benchmarks redefine fuel eligibility and generator dispatch priority in industrial park energy planning.
Market Dynamics
MIIT's diesel emission crackdown is redirecting industrial power procurement toward gas-fired alternatives across China's coastal manufacturing belts, compressing deployment timelines for captive generation projects.
Growth Catalysts
- GB 20891 Tier IV mandates:MIIT's tightened non-road engine standards are disqualifying diesel backup units from industrial parks, forcing facility managers toward certified gas alternatives.
- Shanghai Lingang industrial cluster:District heating integration projects in this Pudong satellite zone are specifying biogas-ready generators for combined heat and power compliance.
- Grid instability premiums:Eastern China manufacturing hubs facing summer peak-load curtailments are paying dispatch premiums for sub-10-second start gas units.
Market Restraints
- LNG price volatility:Industrial consumers in Guangdong province face feedstock cost swings that erode operating cost advantages versus grid power.
- Import dependency for high-speed turbochargers:Domestic suppliers lack precision-machining capability for 50 MW-class turbine components, concentrating sourcing risk with German and Swiss specialists.
- Pipeline delivery constraints:Western China project developers encounter priority allocation disputes with residential heating customers during winter drawdown periods.
Strategic Opportunities
- Chengdu-Chongqing economic circle:Sichuan province's shale gas production growth is creating stranded gas economics favorable for distributed generation clusters.
- Hydrogen blending pilots:MIIT-funded demonstration projects in Ningbo are testing 20% hydrogen co-firing in retrofitted gas engines for steel sector decarbonization.
- Carbon accounting integration:Provincial carbon-neutrality procurement mandates in Jiangsu are biasing RFP scoring toward biogas and landfill gas configurations.
Industry Challenges
- Combustion calibration expertise:Low-calorific domestic gas variations require site-specific tuning that outstrips available field engineering capacity.
- Dual certification timelines:SAMR electrical safety review and MIIT emission type-approval processes run sequentially rather than in parallel, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Gas Generator Market |
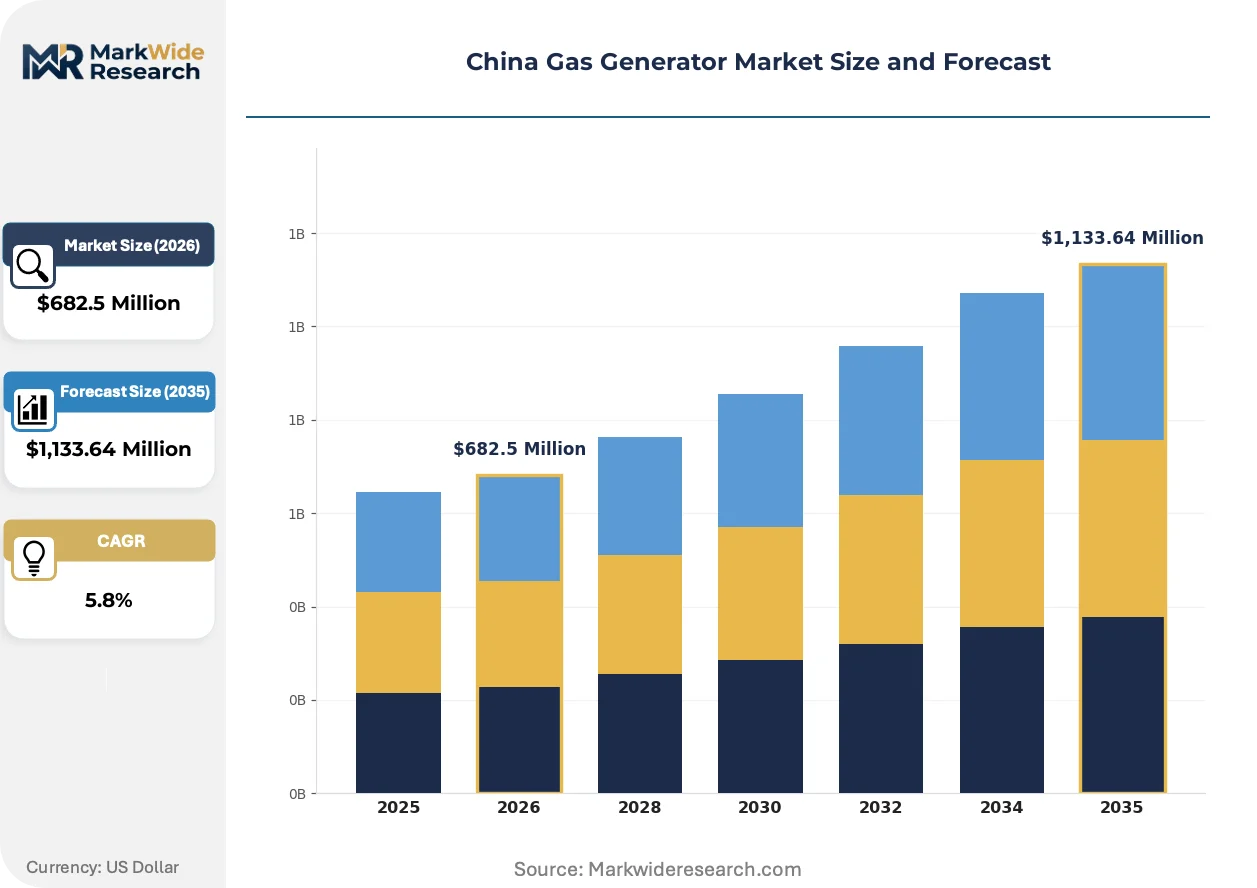
| Market Size in 2026 | $682.5 Million |
| Market Size in 2035 | $1,133.64 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Industrial Generators End User: Manufacturing, Healthcare, Commercial, Residential Fuel Type: Natural Gas, LPG, Biogas, Propane Application: Power Generation, Backup Power, Remote Locations, Critical Applications |
| Companies Covered | Cummins Inc, Caterpillar Inc, General Electric Company, Yanmar Co, Kirloskar Electric Company Limited, GRETECH, Loncin Holdings Ltd, Yuchai, Weichai Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Gas Generator Market Strategic Shifts
Digital control architectures and fuel-flexible combustion systems are redefining equipment specifications across China's procurement landscape, with buyers prioritizing retrofit-ready platforms over fixed-configuration units.
Lean-burn pre-chamber ignition technology is bifurcating the mid-power segment between high-efficiency industrial baseload buyers and cost-optimized standby purchasers. Petrochemical complexes in Shandong province are specifying these systems for 8,000+ hour annual run profiles. The technology is compressing margins for conventional spark-ignited alternatives while enabling premium pricing for integrated heat-recovery packages.
GB/T 2820 grid-parallel certification is restructuring supplier qualification requirements for synchronized operation applications. SAMR's electrical safety enforcement is filtering out uncertified assemblers from hospital and data center verticals. Tier-1 procurement departments in Beijing and Shenzhen are now mandating third-party grid-code compliance verification prior to bid acceptance.
Equipment-as-service contracting is displacing traditional capital purchase models in district heating applications. Municipal energy bureaus in Tianjin and Hangzhou are signing 15-year availability agreements that transfer operational risk to OEM service networks. This shift concentrates aftermarket revenue with manufacturers maintaining captive technical teams across eastern provinces.
China Gas Generator Market Segmentation
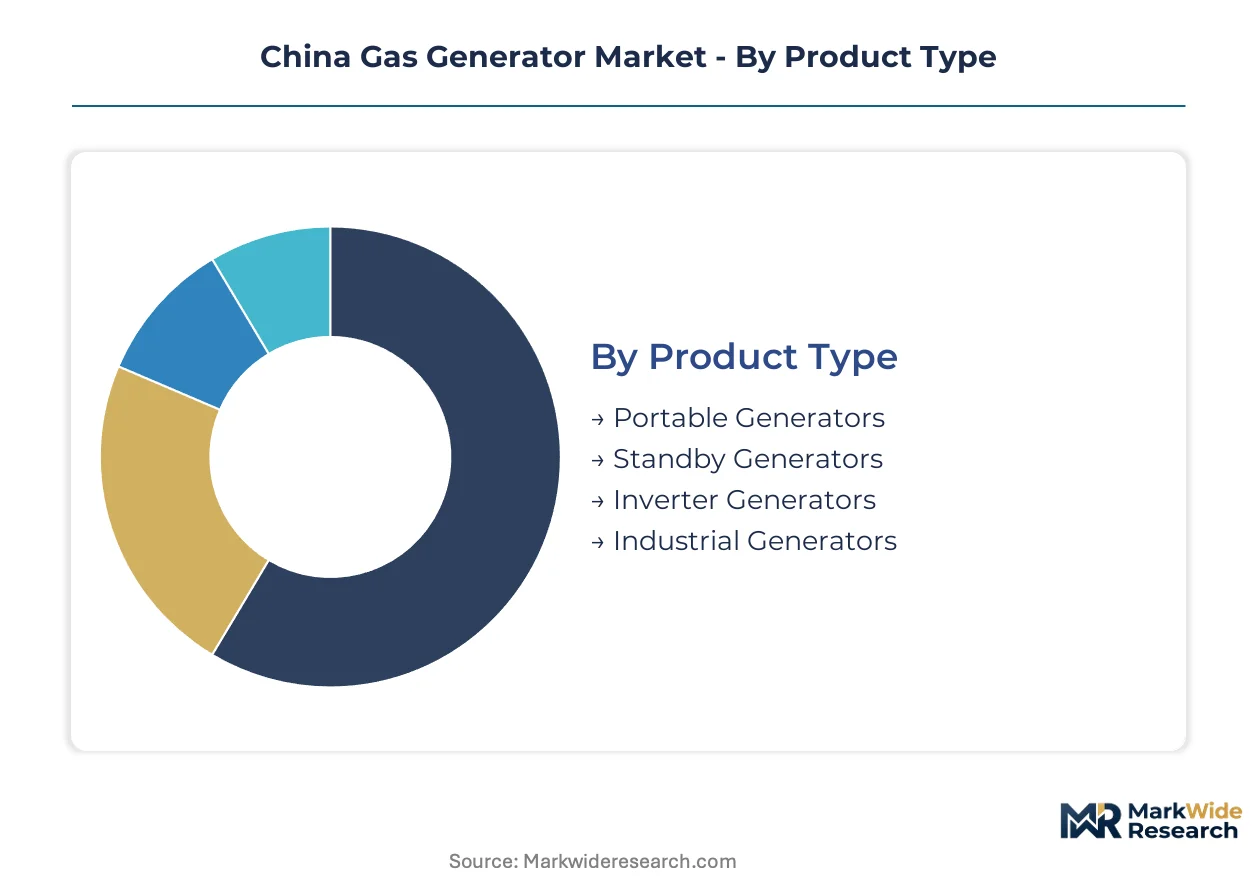
China's gas generator procurement channels bifurcate sharply between project-engineered industrial sales and distributor-driven standby units. Segment-specific certification requirements and fuel infrastructure access create divergent margin structures across these channels.
Product Type:
Channel mix splits between direct OEM engagement for high-capacity industrial units and authorized dealer networks for sub-500 kW standby configurations.
- Industrial Generators:Prime movers rated 1 MW to 50 MW with lean-burn pre-chamber ignition and integrated heat recovery. Sinopec petrochemical complexes in Shandong specify these for 8,000+ hour annual baseload profiles under GB/T 2820 grid-parallel certification.
- Standby Generators:Automatic-start units from 50 kW to 2 MW targeting sub-10-second compliance. Beijing and Shenzhen data centers mandate third-party grid-code verification through SAMR-certified channels.
- Portable Generators:Mobile sub-10 kW units for construction site power.
- Inverter Generators:Variable-speed compact units for precision-sensitive commercial loads.
Industrial generators dominate installed base. Standby generators are where expansion concentrates.
End User:
Cost tier segmentation separates capital-intensive manufacturing procurement from operating-expense-driven healthcare and commercial verticals.
- Manufacturing:Continuous baseload and peak-shaving installations across Yangtze River Delta facilities. MIIT's GB 20891 Tier IV diesel bans are redirecting procurement toward certified gas alternatives with 15-year equipment-as-service contracts emerging in Tianjin.
- Healthcare:Life-safety backup systems requiring dual SAMR electrical and MIIT emission certification. Municipal hospital clusters in Beijing specify biogas-ready configurations under district heating integration mandates.
- Commercial:Retail and office building emergency power with shorter runtime requirements.
- Residential:Single-family backup units concentrated in high-income coastal districts.
Manufacturing captures the largest procurement volume. Healthcare is climbing the fastest on regulatory compliance spending.
Fuel Type:
Supply concentration for turbocharger and fuel injection components shapes fuel-flexible platform economics.
- Natural Gas:Pipeline-fed configurations optimized for 35-45 MJ/Nm³ calorific value. Weichai Power's in-house combustion R&D addresses low-calorific domestic gas variations across Sichuan shale gas fields.
- Biogas:Anaerobic digester and landfill gas systems with H₂S scrubbing. Jiangsu provincial carbon-neutrality procurement mandates bias RFP scoring toward these configurations.
- LPG:Bottled fuel for off-grid and mobile applications.
- Propane:Stored-liquid systems for remote industrial sites.
Natural gas anchors current deployment. Biogas is gaining share fastest on carbon accounting integration.
Application:
Volume concentration varies by grid reliability and interconnection economics across eastern versus western provinces.
- Backup Power:Grid-failure protection for critical infrastructure. Eastern China manufacturing hubs facing summer peak-load curtailments pay dispatch premiums for fast-start units.
- Power Generation:Continuous industrial baseload and captive power. Chengdu-Chongqing economic circle developers exploit stranded Sichuan shale gas economics for distributed clusters.
- Remote Locations:Off-grid mining and infrastructure projects in pipeline-constrained western regions.
- Critical Applications:Life-safety and data integrity systems with zero-failure tolerance.
Backup power holds the deepest installed base. Power generation is where project pipelines are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial carbon intensity benchmarks and industrial park energy directives are redistributing gas generator procurement across China's manufacturing belts. MIIT's emission tier enforcement and NEA grid interconnection protocols create divergent deployment economics by region.
Yangtze River Delta
Manufacturing facilities across Shanghai and Jiangsu are expanding procurement as MIIT tightens diesel emission limits. Jiangsu provincial carbon-neutrality procurement mandates bias RFP scoring toward biogas and landfill gas configurations. Shanghai Lingang industrial cluster specifies biogas-ready generators for combined heat and power compliance.
Pearl River Delta
Data centers in Shenzhen and Guangzhou mandate third-party grid-code verification through SAMR-certified channels for sub-10-second start units. Industrial consumers in Guangdong face LNG feedstock cost swings that erode operating cost advantages versus grid power. Municipal energy bureaus in Shenzhen are signing 15-year availability agreements.
Beijing-Tianjin-Hebei
Municipal hospital clusters in Beijing specify biogas-ready configurations under district heating integration mandates. Tianjin municipal energy bureaus are transferring operational risk to OEM service networks through equipment-as-service contracting. SAMR electrical safety enforcement filters uncertified assemblers from critical infrastructure verticals.
Sichuan-Chongqing Economic Circle
Sichuan province's shale gas production growth creates stranded gas economics favorable for distributed generation clusters. Western China project developers encounter pipeline priority allocation disputes with residential heating customers during winter drawdown periods. Chengdu developers exploit captive shale gas for industrial baseload installations.
Shandong Peninsula
Petrochemical complexes specify lean-burn pre-chamber ignition systems for 8,000+ hour annual run profiles. GB/T 2820 grid-parallel certification restructures supplier qualification requirements for synchronized operation. Weichai Power anchors position through in-house combustion R&D tailored to low-calorific domestic natural gas.
China Gas Generator Market Competitive Environment
Player mix skews toward diversified engine manufacturers with captive distribution networks and localized production bases. The supplier pool compresses around GB/T 2820 certification requirements for grid-parallel systems. Three archetypes dominate: multinational engine specialists with Chinese manufacturing presence, domestic powertrain conglomerates with in-house R&D, and regional assemblers serving sub-500 kW standby segments. Competitive moves concentrate on backward integration into combustion technology and captive service network expansion.
Within the multinational tier, Cummins Inc and Caterpillar Inc exemplify divergent localization strategies. Cummins leverages its Wuhan production base to sustain cost competitiveness against import-dependent rivals. Caterpillar anchors position through captive distribution networks servicing petrochemical complexes. Among domestic conglomerates, Weichai Power occupies a position defined by in-house combustion calibration for low-calorific domestic gas variations.
| Leading Market Players |
|---|
| Cummins Inc |
| Caterpillar Inc |
| General Electric Company |
| Yanmar Co |
| Kirloskar Electric Company Limited |
| GRETECH |
| Loncin Holdings Ltd |
| Yuchai |
| Weichai Power |
| Others |
Value Chain & Pricing Dynamics
Long-term equipment-as-service contracts in Tianjin and Hangzhou lock in both turbocharger supply access and fifteen-year price visibility for municipal energy bureaus, insulating district heating operators from LNG feedstock volatility while concentrating aftermarket revenue with OEMs maintaining captive technical teams across eastern provinces.
Pricing Analysis
Cost-plus contracts with Shanghai LNG indexation dominate procurement for industrial baseload units across the Yangtze River Delta. Price differentiation rests on GB/T 2820 grid-parallel certification grade and integrated heat-recovery bundling. Cost compression in sub-500 kW standby tiers is intensifying because unauthorized assemblers undercut SAMR-certified channels. Manufacturing facilities show lowest price sensitivity; municipal hospital clusters face tightest capital constraints.
Supply Chain Analysis
Germany and Switzerland produce precision-machined 50 MW-class turbocharger components that domestic Chinese suppliers cannot replicate. High-speed turbine assemblies, lean-burn pre-chamber ignition modules, and H₂S scrubbing systems for biogas configurations draw from European specialist foundries. Single-source vulnerability concentrates in turbocharger sourcing for large industrial units. Distribution runs through captive OEM service networks for project-engineered sales and authorized dealer channels for standby configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combustion calibration expertise for low-calorific domestic gas variations represents the critical capability gap separating qualified suppliers from market exit, with site-specific tuning demands outstripping available field engineering capacity across Sichuan shale gas fields.
For Market Incumbents: Fortify backward integration into fuel-flexible combustion R&D to defend against emerging hydrogen-blending specialists capturing steel sector decarbonization projects. Expand captive service network density in the Chengdu-Chongqing economic circle to preempt stranded gas economics plays by regional assemblers. For New Entrants and Emerging Players: Lead with biogas-ready generator configurations targeting Jiangsu provincial carbon-neutrality procurement mandates where RFP scoring biases create immediate white-space. Penetrate the healthcare vertical through dual SAMR-MIIT certification investment, exploiting compliance burdens that filter uncertified rivals from Beijing municipal hospital clusters. For Investors and Strategic Acquirers: Domestic powertrain conglomerates with in-house combustion calibration capabilities present the most defensible acquisition profile for long-term positioning across China's distributed generation buildout. Monitor MIIT hydrogen co-firing demonstration project outcomes in Ningbo as the inflection signal for fuel-flexible platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Combustion R&D | Weichai Power's captive fuel-flexible technology anchors positioning against import-dependent rivals. |
| GB/T 2820 Certification Investment | Grid-parallel compliance collapses supplier pools and enables premium pricing in synchronized applications. |
| Equipment-as-Service Contracting | Tianjin municipal bureaus transfer operational risk to OEMs through fifteen-year availability agreements. |
| Hydrogen Blending Pilot Participation | MIIT-funded Ningbo demonstrations test 20% co-firing for steel sector decarbonization pathways. |
| Captive Distribution Network Expansion | Caterpillar's Sinopec servicing infrastructure locks out competitors from petrochemical complex renewals. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant engineers at Yangtze River Delta manufacturing facilities, MIIT emission compliance officers, municipal energy bureau procurement directors, and aftermarket service heads at captive OEM networks. Secondary validation drew from MIIT GB standard filings, SAMR certification registries, NEA distributed generation guidelines, and provincial carbon-neutrality procurement mandate documentation. Bottom-up project pipeline assessment triangulated against top-down fuel consumption forecasts.
Across the projection horizon, the analytical framework modeled segmentation across product type, fuel configuration, end-use vertical, and regional regulatory cluster. CAGRs were derived from installation volume trajectories and unit economics by capacity tier. Industry-specific forecast inputs included shale gas production curves from Sichuan fields and MIIT emission tier enforcement timelines.
Forecasts assume regulatory continuity in MIIT emission standards and SAMR certification regimes; material policy shifts would require re-modeling. Specific risks include LNG price volatility eroding gas-to-grid competitiveness and pipeline allocation disputes disrupting western province deployment. Recalibration cycles align with material shifts in provincial carbon intensity benchmarks and grid interconnection protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
India Diesel Generator Market
Generators
Europe Gas Turbine Market
Generators
Dual-Fuel Generator Market
Generators
Portable Inverter Generators Market
Generators
Railway Generators Market
Generators
North America Diesel Generator Market
Generators
Containerized Solar Generators Market
Generators
Mobile Generators Market
Generators
Asia-Pacific Gas Generator Market
Generators
Construction Generator Sets Market
Generators
Middle-East and Africa Generator Sets Market
Generators
United States Diesel Generator Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
Power Generator Rental Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Residential Generators Market