
 Manganese Mining Market | 2026-2036
Manganese Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Manganese Mining Market Intelligence
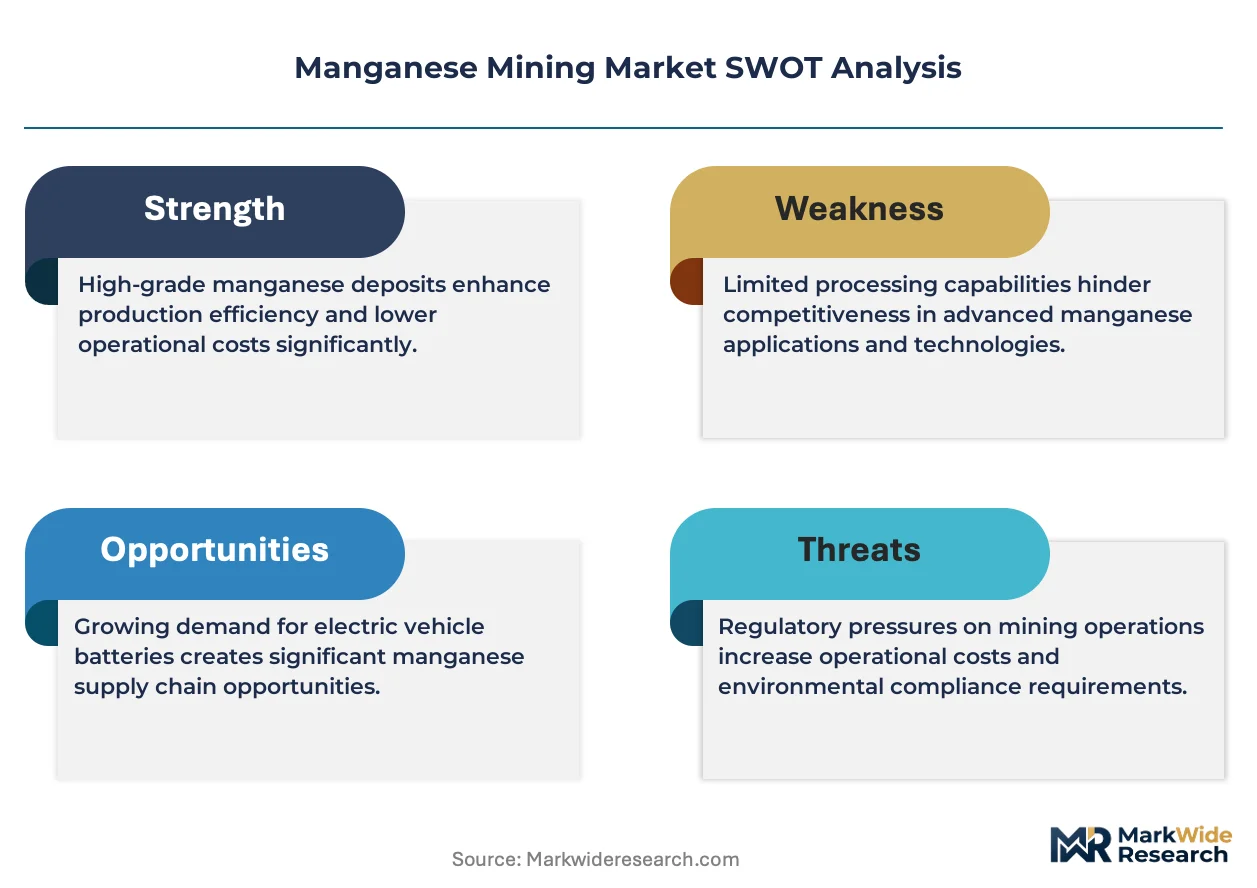
ISO 14001 environmental management certification is rotating as a baseline qualifier for tier-one offtake contracts in manganese supply chains. Vale SA leverages captive rail and port infrastructure in Brazil to sustain cost-advantaged export volumes. South32 Limited anchors its competitive position through integrated ownership of the GEMCO operation in Australia. Eramet SA specializes in high-purity manganese products for battery-grade specifications, differentiating its portfolio from standard metallurgical ore.
Manganese mining extracts ore containing manganese dioxide or carbonate minerals, typically processed through crushing, screening, and beneficiation to achieve grades between 35% and 55% Mn content for commercial use. The output serves primarily as a deoxidizing and alloying agent in steelmaking, with emerging demand from battery cathode chemistries requiring high-purity electrolytic manganese metal. Open pit operations dominate volume extraction due to lower stripping ratios and economies of scale in large basins, while underground methods retain relevance where overburden depths exceed economic limits for surface methods. High-grade ore commands premium pricing in battery manufacture applications, whereas medium-grade material serves as the workhorse feedstock for standard steel production with thinner margin pools.
South Africa's Department of Mineral Resources and Energy enforces mining charter requirements on local procurement and beneficiation that shape investment timelines for new projects. Australia's EPBC Act environmental assessments add permitting layers for greenfield developments near sensitive ecosystems. Stakeholders must monitor how evolving battery cathode formulations alter manganese purity specifications and redirect capital toward beneficiation assets capable of upgrading lower-grade reserves.
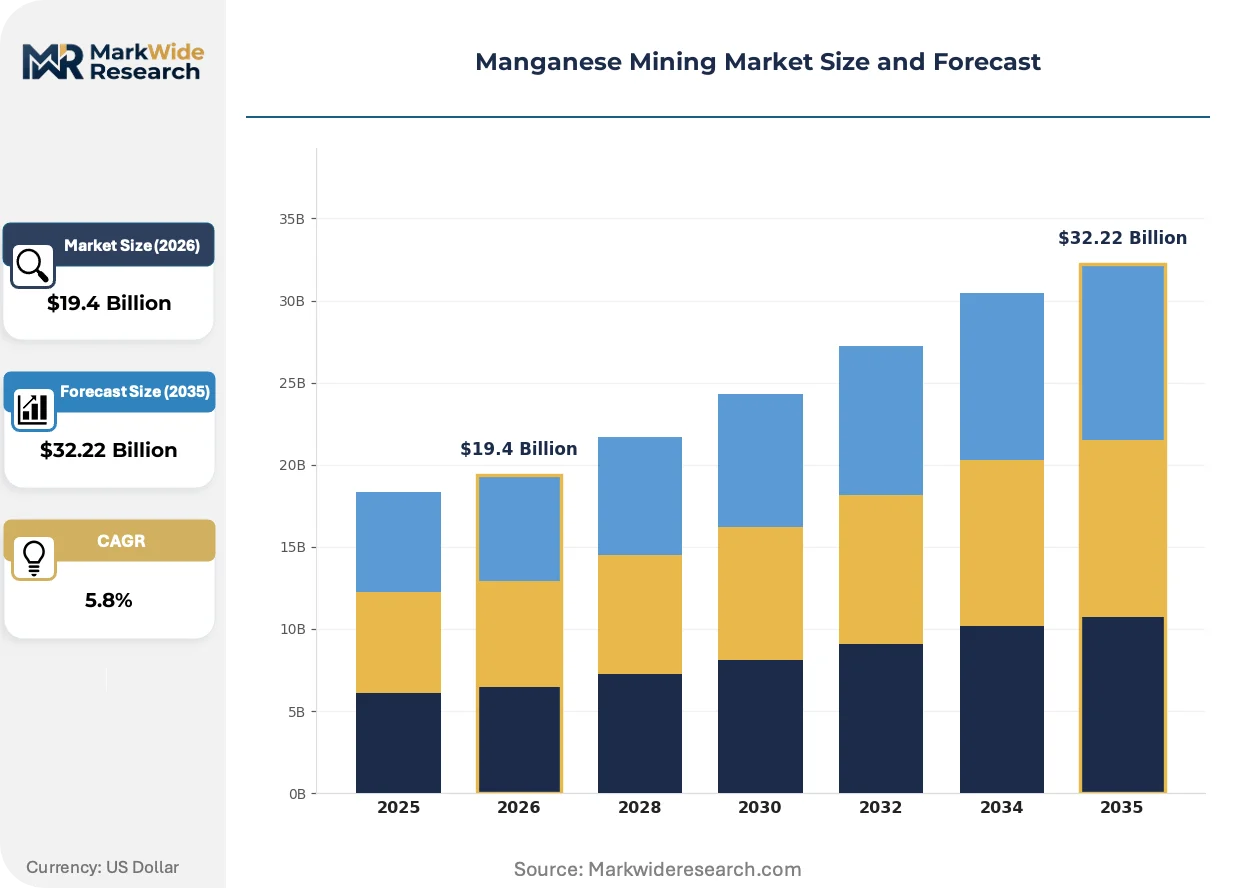
Market Dynamics
China's dual carbon goals and GB standards on emissions intensity are tightening eligibility for mine operators, compressing supply from high-carbon intensity producers while battery fabricators scale manganese offtake for lithium-ion cathode formulations. This regulatory-demand tension is redrawing competitive access to tier-one offtake contracts.
Growth Catalysts
- High-purity manganese demand:Battery-grade specifications for lithium-ion cathode chemistries are pulling beneficiation capacity toward electrolytic manganese metal production.
- South Africa's mining charter:Local procurement and beneficiation mandates are accelerating investment timelines for integrated mine-to-metal projects in the Kalahari manganese field.
- ISO 14001 certification:Environmental management standards are rotating as baseline qualifiers for tier-one supply chain eligibility among steel and battery manufacturers.
Market Restraints
- Electricity cost volatility:Electrolytic manganese metal production requires intensive power input, exposing margins to grid price swings in South Africa and Australia.
- Supply basin concentration:The Kalahari manganese field dominates export-grade ore, creating geographic vulnerability to rail and port disruptions.
- Nickel-cobalt substitution:Lithium iron phosphate cathodes are displacing manganese-rich formulations in select battery applications.
Strategic Opportunities
- Brazilian Atlantic corridor:Captive rail and port infrastructure offers cost-advantaged export routes for medium-grade ore to Atlantic basin steelmakers.
- Australia's EPBC Act pathways:Environmental assessment frameworks near sensitive ecosystems create first-mover advantages for compliant greenfield developers.
- High-purity beneficiation:Integrated ownership of crushing, screening, and hydrometallurgical upgrading assets captures premium pricing from battery manufacturers.
Industry Challenges
- Metallurgical skill scarcity:Hydrometallurgical process engineering talent is concentrated among legacy electrolytic manganese metal producers, constraining new entrant ramp speeds.
- Permitting timeline compression:Australia's EPBC Act assessments and South Africa's mining charter compliance are extending project development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manganese Mining Market |
| Market Size in 2026 | $19.4 Billion |
| Market Size in 2035 | $32.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mining Method: Open Pit, Underground, Alluvial, Heap Leaching Ore Grade: High Grade, Medium Grade, Low Grade, Ultra Low Grade Application: Steel Production, Battery Manufacture, Chemical Industry, Fertilizers, Electronics End User: Steel Manufacturers, Chemical Producers, Battery Fabricators, Fertilizer Companies |
| Companies Covered | Vale SA, African Rainbow Minerals Limited, South32 Limited, MOIL Limited, Jupiter Mines Limited, BHP Group Limited, Anglo American plc, OM Holdings Limited, Eramet SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manganese Mining Market Strategic Shifts & Innovations
Processing technology and purity specifications are diverging between metallurgical and battery-grade supply chains, forcing capital allocation decisions that will lock in product positioning for decades.
High-purity electrolytic manganese metal production is bifurcating supply chain configurations. Battery manufacturers are adopting 99.9% purity specifications for cathode active materials, compressing margins for standard ferromanganese producers. This technology split is enabling integrated mine-to-metal operators to capture tier-one offtake premiums while relegating crush-and-screen exporters to thinner margin pools.
REACH regulations in Europe are tightening disclosure requirements for heavy metal content in imported manganese products. Industrial consequence includes mandatory supply chain due diligence for EU-based battery fabricators. High-purity producers with certified beneficiation assets are responding by pre-qualifying European offtake contracts ahead of compliance deadlines.
Long-term offtake contracting is displacing spot market purchases among battery-grade buyers. Cathode manufacturers are securing five-to-ten-year supply agreements directly with integrated miners, bypassing traditional trader intermediaries. This pattern is most visible in South Korea and Japan, where METI industrial policy encourages strategic mineral stockpiling through direct producer relationships.
Manganese Mining Market Segmentation
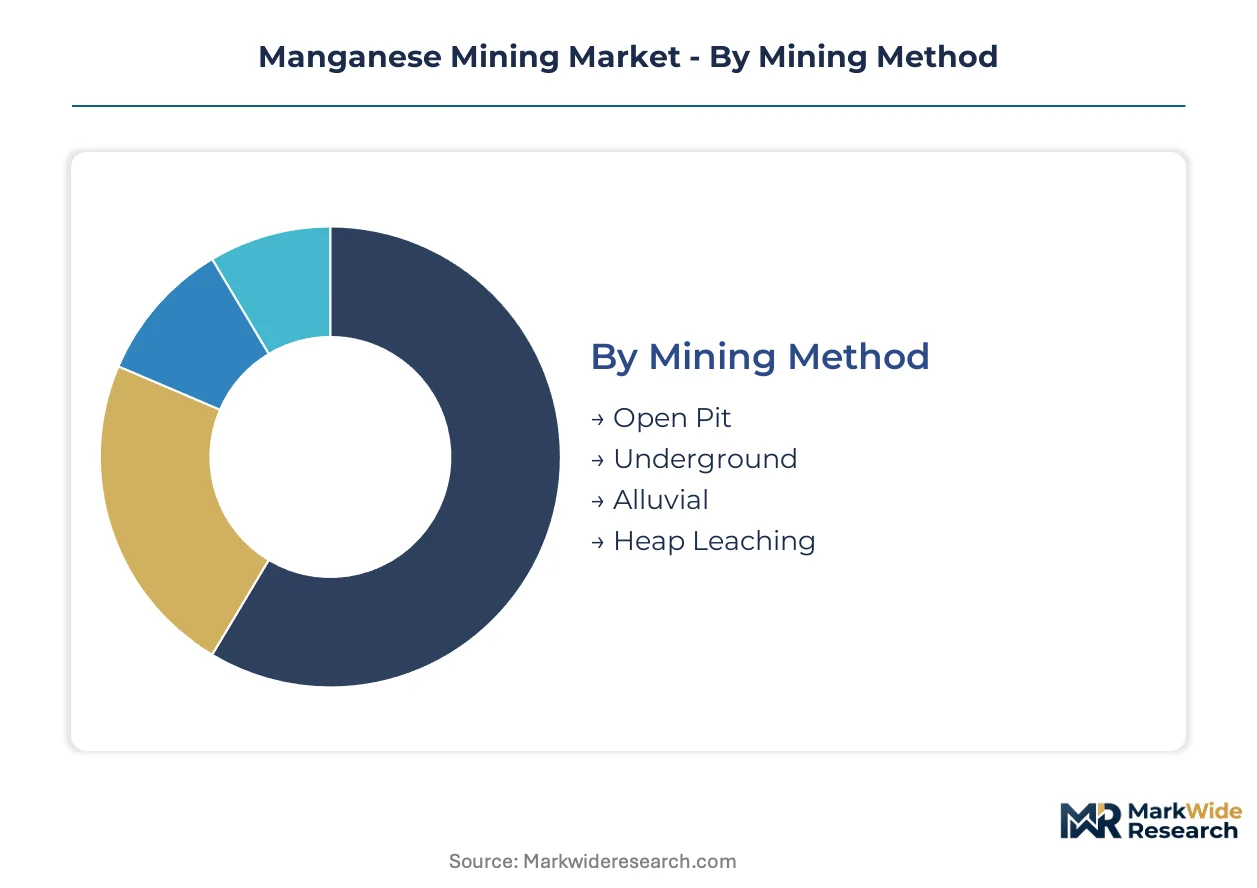
Manganese mining segmentation reveals how extraction economics, ore chemistry, and end-use purity requirements fragment capital allocation across vastly different margin pools. Mining method and ore grade classifications determine baseline cost structures, while application and end-user segments dictate beneficiation intensity and pricing power.
Mining Method:
Underground and alluvial operations face the most acute substitution pressure from open-pit expansions in South Africa's Kalahari basin, where economies of scale crush marginal cost structures.
- Open Pit:Surface extraction dominates volume through lower stripping ratios and mechanized economies in large basins. Demand concentrates in South Africa's Kalahari field, where GEMCO and Assmang operations feed Atlantic and Pacific basin steelmakers through integrated rail-port corridors.
- Underground:Room-and-pillar and longwall methods apply where overburden depths exceed economic limits for surface stripping. South Africa's Hotazel formation hosts narrow-reef extraction for high-grade lumpy ore, constrained by ventilation costs and labor intensity.
- Alluvial:Placer deposits in Brazil's Amazon basin and West African drainage systems yield oxide-rich fines through dredging and sluicing. Gabon's Moanda plateau supplies sedimentary accumulations to Eramet's coastal processing complex.
- Heap Leaching:Hydrometallurgical recovery from low-grade oxide stockpiles, applied selectively in Arizona and New Mexico operations where acid-soluble manganese permits chemical extraction without full beneficiation circuits.
Open pit anchors the volume base while heap leaching gains share at the steepest rate as battery-grade specifications pull investment toward hydrometallurgical upgrading assets.
Ore Grade:
Cost tier stratification separates premium battery feedstock from commodity steel inputs, with beneficiation intensity determining final product positioning.
- High Grade:Ore exceeding 48% Mn content commands tier-one pricing for electrolytic manganese metal production. Battery fabricators in South Korea and Japan specify this grade for cathode active material precursors, with long-term offtake contracts displacing spot purchases.
- Medium Grade:Material between 35% and 48% Mn serves as the workhorse feedstock for standard ferromanganese and silicomanganese alloys. Chinese blast furnace operators blend this grade with domestic low-grade ore to meet GB standards on emissions intensity.
- Low Grade:Sub-35% Mn ore requires dense media separation or magnetic beneficiation to achieve commercial specifications. Indian producers leverage this feedstock through sintering and pelletizing circuits for domestic steel mill integration.
- Ultra Low Grade:Below 25% Mn content, typically processed through hydrometallurgical leaching or discarded to waste dumps. Experimental bioleaching pilots in Australia target this material for battery-grade recovery, constrained by sulfur-oxidizing bacterial cultivation costs.
Medium grade captures the greatest volume share while high grade climbs fastest as battery cathode formulations tighten purity specifications.
Application:
Customer type divergence splits the market between price-taking steel mills and specification-driven battery manufacturers, with chemical and fertilizer applications occupying intermediate margin positions.
- Steel Production:Deoxidizing and alloying applications consume the majority of manganese output as ferromanganese and silicomanganese. Chinese integrated mills blend domestic and imported ore to optimize slag chemistry and sulfur control in basic oxygen furnaces.
- Battery Manufacture:High-purity electrolytic manganese metal and manganese sulfate for lithium-ion cathodes, principally NMC and LMO chemistries. South Korean cathode producers secure direct mine relationships to bypass trader intermediaries and ensure supply chain due diligence compliance.
- Chemical Industry:Manganese dioxide for dry cell batteries, potassium permanganate for water treatment, and manganese carbonate for pigment manufacture. European REACH regulations tighten heavy metal disclosure requirements for imported chemical intermediates.
- Fertilizers:Manganese sulfate and chelated forms address micronutrient deficiency in alkaline soils. Brazilian agriculture distributors blend manganese into NPK formulations for soybean and corn cultivation in Cerrado regions.
- Electronics:Specialized manganese-zinc ferrites for inductor cores and transformer applications. Japanese electronics manufacturers specify ultra-low impurity grades from Australian and South African integrated producers.
Steel production retains the dominant volume position while battery manufacture expands most quickly as electric vehicle production scales in China, Europe, and North America.
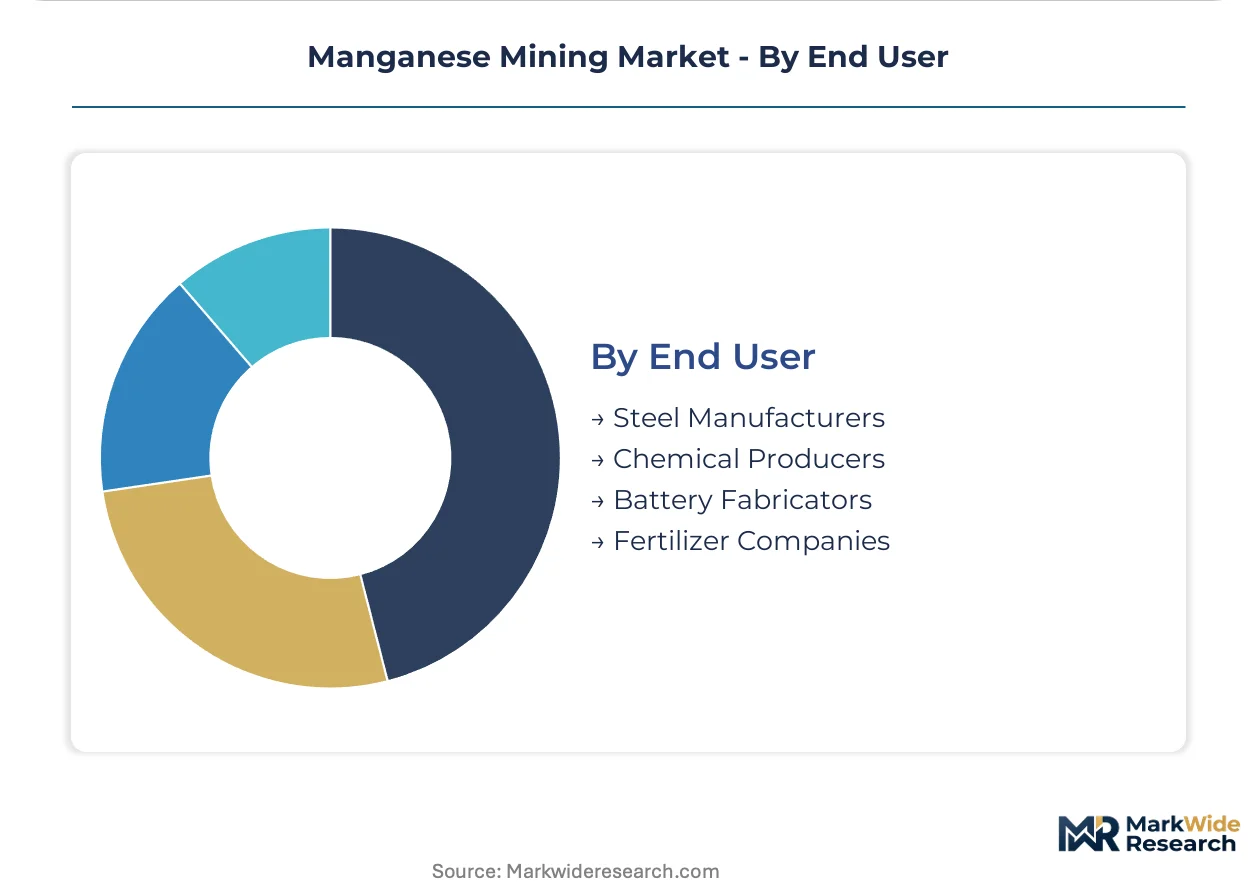
End User:
Supply concentration geography determines procurement risk profiles, with battery fabricators diversifying sourcing while steel manufacturers optimize for delivered cost to coastal mills.
- Steel Manufacturers:Integrated blast furnace operators and electric arc furnace mini-mills purchase ferromanganese and silicomanganese alloys. Posco, Nippon Steel, and ArcelorMittal negotiate annual contracts indexed to manganese ore benchmarks from South African and Australian supply basins.
- Chemical Producers:Specialty manganese compound manufacturers require consistent impurity profiles for battery-grade and technical-grade outputs. Eramet's Gabon operations and CITIC Dameng's Chinese facilities dominate this segment through integrated mine-to-chemical processing.
- Battery Fabricators:Cathode active material producers specify 99.9% purity electrolytic manganese metal and high-purity manganese sulfate. LG Chem, Samsung SDI, and CATL secure five-to-ten-year offtake agreements directly with integrated miners to ensure supply security.
- Fertilizer Companies:Agricultural input blenders incorporate manganese micronutrients into compound fertilizers. Mosaic and Nutrien source manganese sulfate from Chinese and Indian producers for North and South American distribution networks.
Steel manufacturers anchor procurement volumes while battery fabricators drive the steepest contract restructuring toward direct producer relationships and certified beneficiation assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery fabricators in South Korea and Japan concentrate tier-one offtake contracting for high-purity manganese. Steel mills across Atlantic and Pacific basins anchor medium-grade ore procurement. Mining charter compliance and carbon intensity regulations are redrawing investment eligibility across supply basins.
South Africa
The Kalahari manganese field supplies export-grade ore to Atlantic basin steelmakers. The Department of Mineral Resources and Energy enforces mining charter requirements on local procurement and beneficiation. Hotazel and Kuruman host integrated rail-port corridors feeding GEMCO and Assmang operations.
Australia
GEMCO operation on Groote Eylandt anchors high-purity electrolytic manganese metal output for Asian battery manufacturers. The EPBC Act environmental assessments add permitting layers for greenfield developments near sensitive ecosystems. Darwin and Queensland ports concentrate beneficiation infrastructure for Pacific basin exports.
Brazil
Vale SA leverages captive rail and port infrastructure to sustain cost-advantaged export volumes to Atlantic basin steelmakers. ANVISA and environmental licensing frameworks shape operational compliance timelines. Carajás and Azul mine complexes in Pará state feed integrated logistics corridors.
China
Blast furnace operators blend imported medium-grade ore with domestic low-grade reserves to meet GB standards on emissions intensity. MIIT and dual carbon goals tighten eligibility for high-carbon intensity producers. Guangxi and Guizhou provinces concentrate domestic manganese mining and ferroalloy smelting capacity.
Gabon
Eramet SA specializes in high-purity manganese products for battery-grade specifications from Moanda plateau sedimentary deposits. The country's national mining code shapes foreign investment frameworks for integrated mine-to-metal projects. Franceville and Libreville host coastal processing complexes serving European chemical and battery markets.
Manganese Mining Market Key Industry Players
Player mix skews toward integrated miners with captive beneficiation assets and trader-dependent exporters with thinner margin positions. Market structure concentrates around South African and Australian supply basins where rail-port integration determines cost competitiveness. Strategic archetypes include integrated mine-to-metal operators, crush-and-screen exporters, and hydrometallurgical specialists. Dominant competitive moves encompass backward integration into beneficiation assets and long-term offtake contracting with battery fabricators.
Among diversified mining conglomerates, BHP Group Limited and Anglo American plc exemplify scale-driven archetypes with multi-commodity portfolios spanning iron ore to base metals. Vale SA anchors the Brazilian supply corridor through captive logistics infrastructure. Specialists in high-purity manganese products include Eramet SA, which occupies a position within the battery-grade beneficiation tier serving European and Asian cathode manufacturers.
| Leading Market Players |
|---|
| Vale SA |
| African Rainbow Minerals Limited |
| South32 Limited |
| MOIL Limited |
| Jupiter Mines Limited |
| BHP Group Limited |
| Anglo American plc |
| OM Holdings Limited |
| Eramet SA |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracting with take-or-pay provisions locks in supply access and price visibility for battery fabricators sourcing high-purity electrolytic manganese metal from South African and Australian integrated producers. This contract structure concentrates procurement power among cathode manufacturers in South Korea and Japan while compressing margin flexibility for traders and non-integrated exporters.
Pricing Analysis
Cost-plus contracts indexed to South African manganese ore benchmarks dominate medium-grade ferromanganese procurement by Atlantic basin steelmakers. Price differentiation rests on beneficiation intensity and ISO 14001 certification tier, with battery-grade specifications commanding substantial premiums over standard metallurgical ore. Pricing pressure stems from electricity cost volatility in electrolytic manganese metal production, particularly in South Africa's grid-constrained regions. Steel manufacturers exhibit highest price sensitivity due to thin alloy margins, while battery fabricators prioritize supply security over unit cost.
Supply Chain Analysis
Port congestion at Richards Bay and Durban underwrites delivery risk for Kalahari basin exports to European and Asian markets. Supply concentrates in South Africa, Australia, and Gabon, with raw material dependencies spanning diesel fuel for open-pit haulage, sulfuric acid for hydrometallurgical leaching, and metallurgical coke for ferroalloy smelting. Single-source vulnerability runs through South Africa's Transnet rail corridor, which feeds the bulk of export-grade ore. Distribution runs through integrated mine-port-rail operators and trader intermediaries serving spot market purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among battery cathode manufacturers securing direct mine relationships, fragmenting traditional trader channels as procurement shifts toward specification-driven, certified supply chains.
For Market Incumbents: Shield margin pools by accelerating backward integration into hydrometallurgical beneficiation assets capable of battery-grade output. Prioritize ISO 14001 certification and long-term offtake anchoring with South Korean and Japanese cathode producers to defend against nickel-cobalt substitution in lithium iron phosphate chemistries. Capacity expansion in Australia's EPBC Act-compliant corridors offers first-mover positioning as greenfield permitting timelines extend. For New Entrants and Emerging Players: Lead with heap leaching pilots targeting ultra-low-grade stockpiles in Arizona and New Mexico, where acid-soluble manganese permits chemical extraction without full beneficiation circuits. Brazil's Atlantic corridor presents the most penetrable geography for medium-grade ore exports, given Vale SA's captive logistics infrastructure and ANVISA environmental frameworks that favor compliant developers. A go-to-market angle anchored on Atlantic basin steel mill annual contract indexing bypasses spot market volatility. For Investors and Strategic Acquirers: Capital is best deployed toward integrated mine-to-metal operators with certified high-purity beneficiation assets and existing battery fabricator relationships. Long-term viability over the next decade hinges on positioning within cathode supply chains rather than commodity steel inputs. Watch for inflection signals in lithium iron phosphate market share trajectories, as displacement of manganese-rich formulations would redirect capital toward hydrometallurgical flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beneficiation | Captures premium pricing from battery manufacturers specifying 99.9% purity electrolytic manganese metal. |
| Long-term Supply Agreement | Secures five-to-ten-year offtake anchoring with LG Chem and Samsung SDI, bypassing trader intermediaries. |
| Green Certification Program | Pre-qualifies European offtake contracts ahead of REACH heavy metal disclosure compliance deadlines. |
| Capacity Expansion | Builds EPBC Act-compliant greenfield positioning in Australia's Northern Territory near Darwin export corridors. |
| Joint Venture | Combines South African mining charter compliance with integrated rail-port infrastructure for Kalahari basin access. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with mine operations directors, ferroalloy procurement managers at integrated steel mills, cathode material sourcing leads at battery fabricators, and hydrometallurgical process engineers. Secondary validation drew from South African Department of Mineral Resources and Energy mining charter filings, Australian EPBC Act environmental assessment registers, Chinese MIIT emissions intensity disclosures, and Transnet freight volume statistics. Bottom-up ore production tallies and top-down end-use consumption estimates were triangulated to anchor volume and value outputs.
Across the analysis window, the forecasting framework modeled extraction method, ore grade tier, application segment, and end-user procurement archetype as core segmentation dimensions. CAGRs were derived from elasticity-adjusted demand projections for steel production and battery manufacture, incorporating electrolytic manganese metal capacity expansion pipelines and GB standards compliance trajectories in Chinese blast furnace operations.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle production scaling or nickel-cobalt substitution thresholds would require recalibration. Practitioners should keep alternative scenarios live as lithium iron phosphate cathode chemistry adoption and South African grid reliability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Californium Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market