
 Cobalt Nitrate Market | 2026-2036
Cobalt Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Nitrate Market Analysis
African cobalt concentrate supply is recalibrating as artisanal mining restrictions tighten material flows into Chinese refineries. Umicore leverages its integrated refining and battery materials platform to secure qualified supply chains for European cathode producers. American Elements anchors North American demand through its specialty chemicals portfolio serving aerospace and electronics end users. Merck KGaA competes on reagent-grade purity standards for analytical and pharmaceutical applications.
Cobalt nitrate is an inorganic cobalt(II) salt with the formula Co(NO₃)₂·6H₂O, typically appearing as red crystalline prisms soluble in water and polar organic solvents; manufacturers produce it via dissolution of cobalt metal or cobalt oxide in nitric acid followed by controlled crystallization, and the compound serves primarily as a precursor for cobalt-containing catalysts, ceramic pigments, and battery cathode materials. Industrial grade material dominates volume throughput due to catalyst and pigment manufacturing scale, while laboratory and reagent grades command margin premiums from pharmaceutical and analytical laboratories. Battery electrolyte applications represent the fastest-expanding demand pool as automotive OEMs qualify cobalt nitrate-derived salts for solid-state and advanced lithium-ion cell architectures.
REACH registration requirements in Europe and China's MEE hazardous chemical inventory rules are elevating documentation and purity thresholds for cross-border cobalt nitrate shipments. The EPA and OSHA frameworks in the United States impose worker exposure limits and waste handling protocols that shape domestic production economics. Stakeholders must monitor evolving cobalt sourcing ethics regulations and cathode chemistry substitution trends to anticipate demand inflection points.
Market Dynamics
Battery cathode chemistry qualification cycles are compressing lead times for cobalt nitrate precursors as automotive OEMs accelerate solid-state lithium-ion development programs. This technical pull is restructuring procurement relationships between Chinese refiners and European cathode producers.
Growth Catalysts
- REACH Registration Tiering:ECHA's updated substance evaluation protocols are forcing purity upgrades across imported cobalt nitrate streams, creating qualified supplier premiums for compliant refiners serving EU battery material plants.
- Artisanal Mining Restrictions:DRC supply chain due diligence mandates are consolidating concentrate flows toward mechanized producers, improving traceability documentation for downstream cathode manufacturers.
- Solid-State Electrolyte Formulation:Cobalt nitrate-derived salts are qualifying for sulfide-based solid-state cell architectures, opening precursor specifications beyond conventional liquid electrolyte applications.
Market Restraints
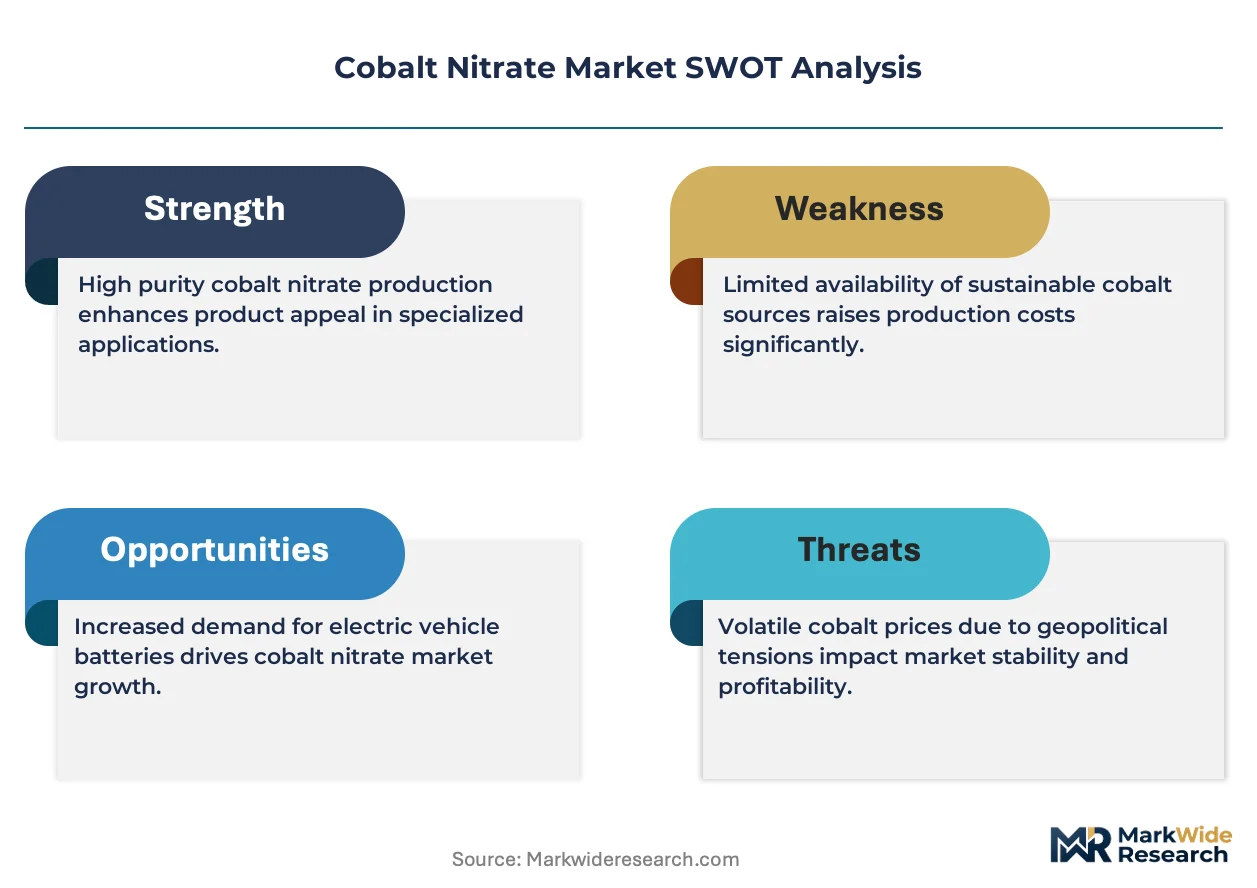
- Cobalt Metal Price Volatility:Concentrate processing economics swing with LME cobalt pricing, compressing nitrate refining margins during downturn cycles and destocking phases.
- Chinese Refining Dominance:Over 80% of global cobalt chemical processing concentrates in Chinese integrated clusters, creating single-geography supply vulnerability for non-Chinese cathode producers.
- High-Nickel Cathode Substitution:NMC 811 and NCA chemistries are reducing cobalt loadings per kilowatt-hour, threatening long-term nitrate demand intensity per battery pack.
Strategic Opportunities
- North American Cathode Capacity:US IRA production tax credits are incentivizing battery material plant construction, creating qualified supply chain openings for non-Chinese cobalt nitrate sources.
- Reagent-Grade Pharmaceutical Applications:Cobalt nitrate serves as a catalyst precursor in active pharmaceutical ingredient synthesis, a segment insulated from battery chemistry substitution pressures.
- GB Standard Harmonization:China's MEE hazardous chemical inventory alignment with REACH documentation frameworks is easing dual-compliance burdens for exporters serving both markets.
Industry Challenges
- Analytical Chemist Shortage:Battery material plants require ICP-MS and XRF specialists for incoming cobalt nitrate purity verification, creating hiring bottlenecks in qualified labor markets.
- Multi-Jurisdiction Certification Timelines:Simultaneous REACH, GB standard, and EPA TSCA filings for new nitrate grades extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Nitrate Market |
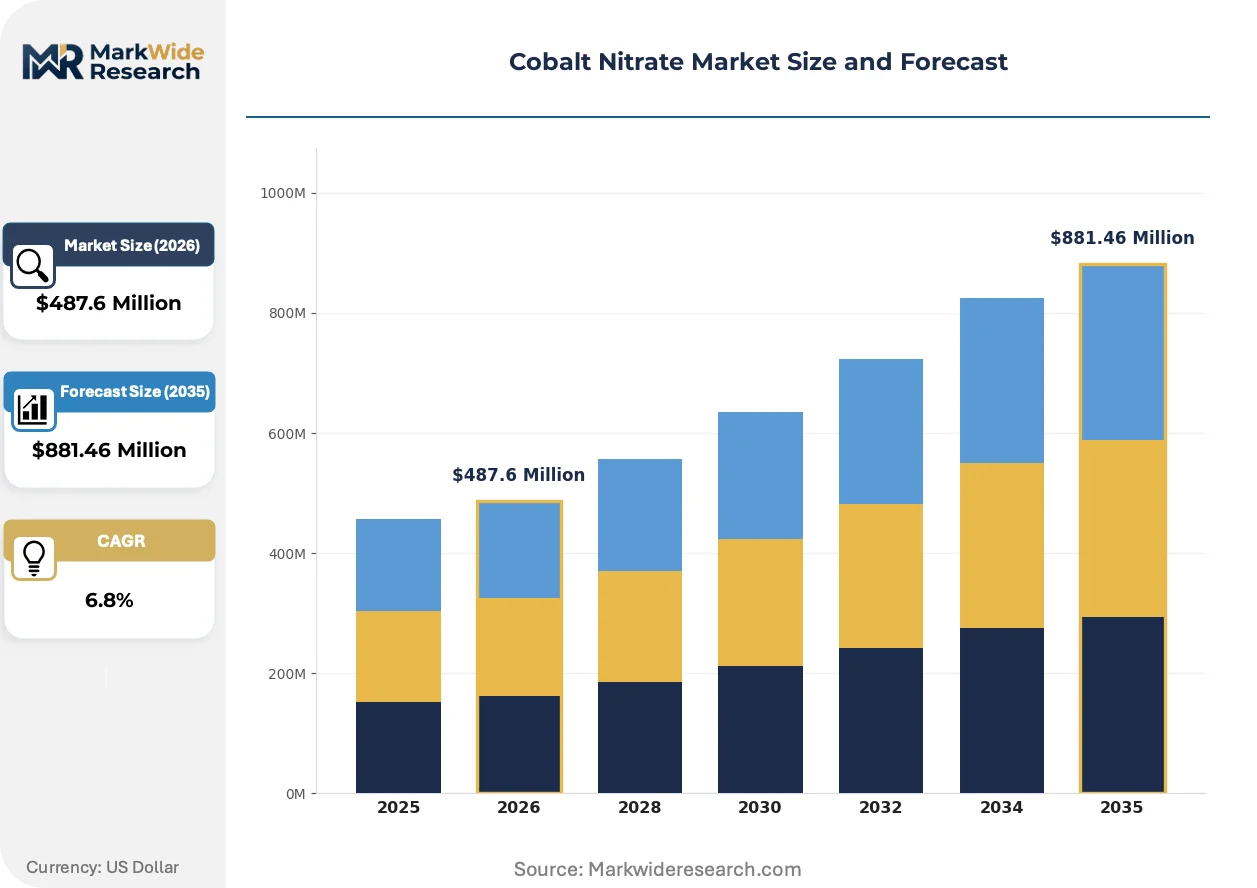
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Reagent Grade, Technical Grade Application: Catalysts, Pigments, Battery Electrolytes, Feed Additives End User: Aerospace, Electronics, Agriculture, Automotive Packaging Type: Bags, Drums, IBC Totes, Bottles |
| Companies Covered | Sigma-Aldrich Corporation, Umicore, American Elements, GFS Chemicals, Strem Chemicals, Thermo Fisher Scientific, Merck KGaA, Honeywell International, Alfa Aesar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Nitrate Market Emerging Trajectories
Process intensification in cobalt refining is compressing crystallization throughput times while analytical-grade specifications are fragmenting product portfolios. These technical currents are reshaping capital deployment and quality management systems across the supply base.
Continuous flow crystallization technology is converging with automated particle size distribution control to yield cobalt nitrate hexahydrate with tighter moisture and impurity specifications. European specialty chemical producers are piloting these systems to qualify for automotive OEM direct-supply agreements. The technology is converging with in-line Raman spectroscopy to enable real-time quality release, compressing batch certification cycles from days to hours.
China's MEE hazardous chemical inventory rules are expanding documentation requirements for cobalt compound cross-border movements, forcing exporters to retrofit supply chain traceability systems. The industrial consequence is a bifurcation between integrated producers with captive concentrate sources and merchant refiners exposed to documentation gaps. Battery-grade material shipments are most affected, with cathode producers now requiring third-party audited chain-of-custody certificates.
Long-term offtake contracting is displacing spot market purchasing for battery-grade cobalt nitrate as cathode producers secure qualified supply ahead of plant ramp-ups. Direct refiner-to-cathode-plant relationships are replacing distributor intermediaries in high-volume corridors. This pattern is most visible in South Korean and Japanese battery material supply chains, where qualification timelines favor relationship stability over price optimization.
Cobalt Nitrate Market Segmentation
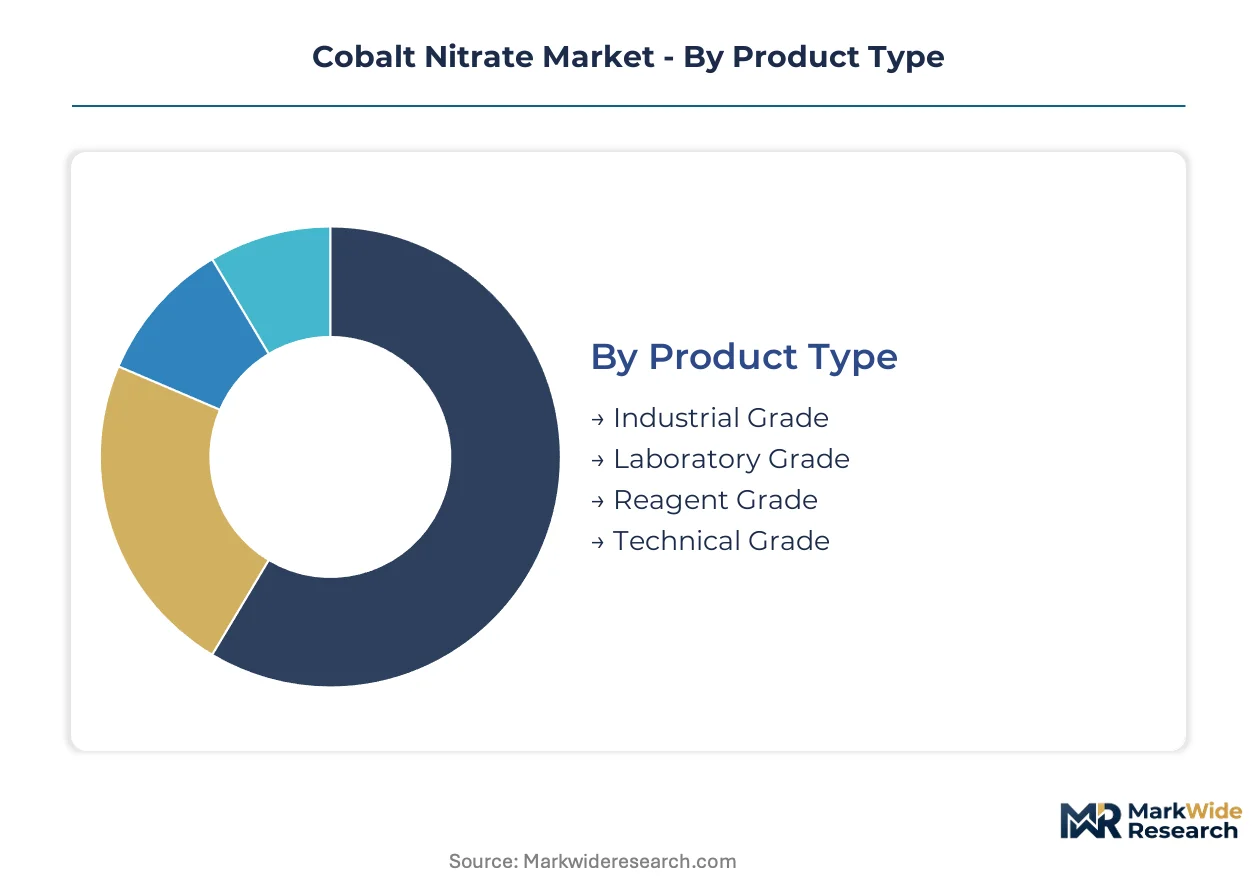
Cobalt nitrate segmentation reflects divergent purity requirements across catalyst manufacturing, battery materials, and analytical laboratories. Grade differentiation determines pricing tiers and regulatory compliance burdens, while application-specific formulations reshape procurement patterns among cathode producers and specialty chemical buyers.
Product Type:
Grade differentiation separates standalone commodity sales from embedded precursor systems requiring certificate-of-analysis documentation.
- Industrial Grade:Cobalt nitrate hexahydrate with 98-99% purity serves catalyst manufacturing and ceramic pigment production at volume scale. Chinese refiners dominate this segment, supplying cobalt sulfate and nitrate precursors to European catalyst plants under REACH-registered material safety data sheets.
- Laboratory Grade:Higher purity specifications with documented impurity profiles support academic research and quality control laboratories. Demand concentrates in German and Japanese analytical instrument clusters where ICP-MS verification protocols require batch-certified material.
- Reagent Grade:Pharmaceutical synthesis and USP-grade applications demand trace metal certification below 10 ppm total impurities.
- Technical Grade:Intermediate purity tier bridges industrial and laboratory specifications for pilot-scale battery material development.
Industrial grade leads volumes today; laboratory grade is gaining share fastest.
Application:
Application segmentation tracks cost-tier divergence between mature industrial uses and emerging battery material specifications.
- Catalysts:Cobalt nitrate serves as a precursor for hydrodesulfurization and oxidation catalysts in petroleum refining. Demand anchors in US Gulf Coast and Rotterdam refining corridors where EPA and ECHA emissions regulations mandate catalyst replacement cycles.
- Pigments:Ceramic colorants and glass decolorizers consume technical-grade material with controlled iron and copper contamination limits. Italian and Spanish tile manufacturers qualify specific Chinese refiners for consistent hue performance.
- Battery Electrolytes:Solid-state and advanced lithium-ion architectures are qualifying cobalt nitrate-derived salts for sulfide electrolyte formulations. South Korean cathode producers are compressing qualification timelines to secure supply ahead of plant ramp-ups.
- Feed Additives:Trace mineral supplementation in livestock nutrition requires food-grade certification under EU feed additive regulations.
Catalyst applications dominate current offtake; battery electrolytes show the steepest expansion trajectory.
End User:
End user segmentation maps customer-type concentration across defense-sensitive aerospace programs and price-sensitive agricultural distributors.
- Aerospace:Superalloy and turbine blade coatings require reagent-grade cobalt nitrate with full material traceability. US Department of Defense sourcing mandates exclude material from unverified supply chains, favoring North American specialty chemical producers.
- Electronics:Semiconductor polishing compounds and magnetic thin films demand ultra-low sodium and potassium specifications. Japanese electronics material plants specify particle size distribution controls below 50 microns.
- Agriculture:Fertilizer and feed additive applications prioritize cost efficiency over purity premiums, sourcing industrial-grade material through distributor networks.
- Automotive:Battery cell manufacturers are establishing direct refiner relationships to bypass intermediaries in high-volume corridors.
Electronics end users command the highest purity premiums; automotive buyers are expanding volume fastest.
Packaging Type:
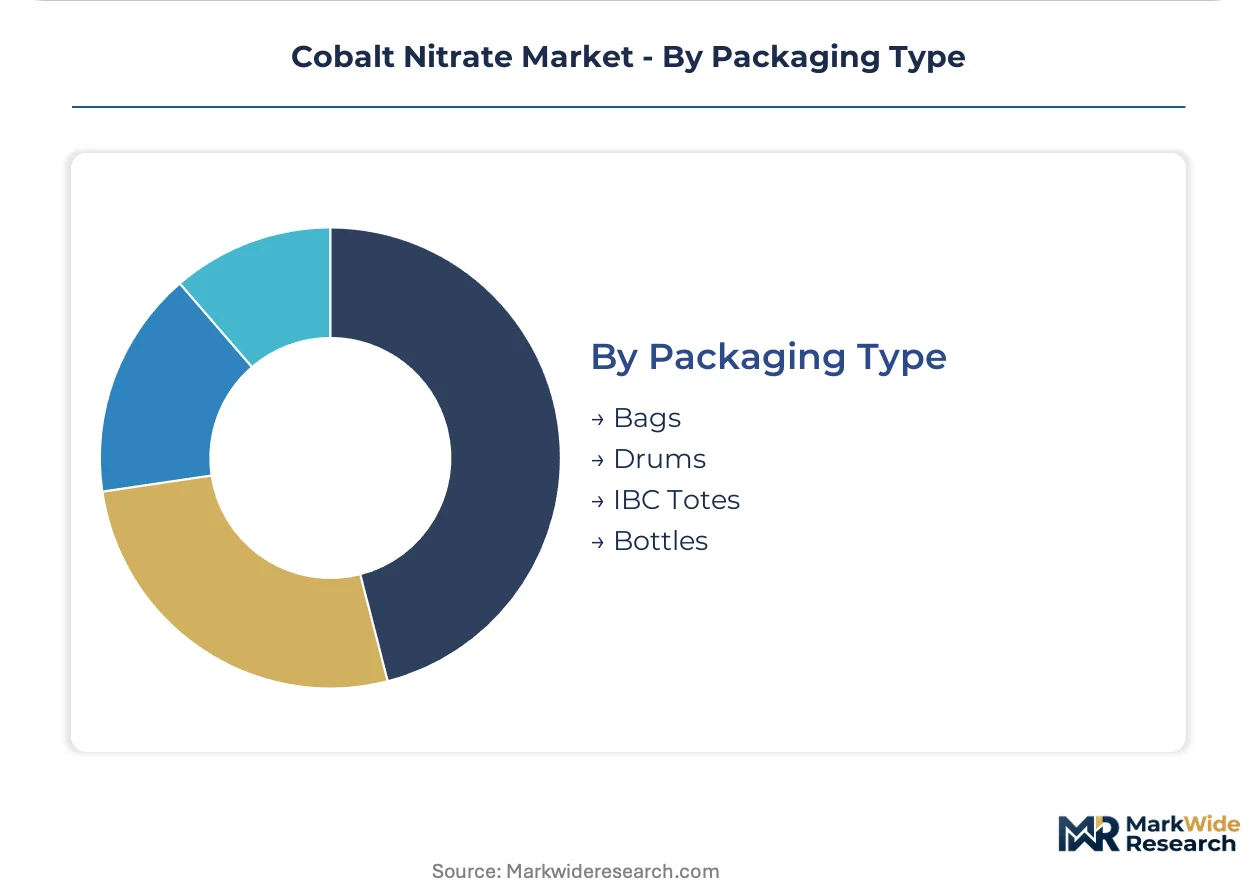
Packaging segmentation reflects volume-scale and contamination-risk differentiation across supply chain nodes.
- Bags:Multi-layer laminated sacks with moisture barriers serve pigment and catalyst manufacturers at 25-50 kg scale. Italian ceramic producers specify heat-sealed inner liners to prevent caking during Mediterranean humidity exposure.
- Drums:Steel and fiber drums with UN certification dominate laboratory and mid-volume industrial shipments. German chemical distributors require drum labeling in both German and English for cross-border EU movements.
- IBC Totes:Intermediate bulk containers reduce handling costs for battery material plants consuming metric-ton quantities monthly. Chinese refiners are qualifying IBC designs with EPDM gaskets for sulfide electrolyte precursor shipments.
- Bottles:Amber glass and HDPE bottles with tamper-evident closures serve reagent-grade pharmaceutical and analytical laboratory markets.
Drums represent the most widely deployed format today; IBC totes are climbing the fastest as cathode plants scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands cobalt nitrate refining capacity while Germany anchors European specialty chemical demand, creating divergent supply chain architectures across major consuming regions.
China
Battery cathode plants in the Yangtze River Delta and Pearl River Delta pull industrial-grade cobalt nitrate at scale for NMC precursor manufacturing. MEE hazardous chemical inventory rules mandate third-party chain-of-custody documentation for all cross-border shipments. Ganzhou and Jingmen host integrated refining clusters where mechanized concentrate processing is displacing artisanal-sourced material.
Germany
Catalyst manufacturers along the Rhine corridor and pharmaceutical laboratories in Bavaria sustain reagent-grade demand with REACH-registered purity specifications. ECHA substance evaluation protocols force importers to upgrade analytical documentation or exit the market. Ludwigshafen's chemical parks host qualified distributors serving battery material plants in Poland and Hungary.
United States
IRA production tax credits are accelerating cathode plant construction in Michigan and Kentucky, creating qualified supply chain openings for non-Chinese cobalt nitrate sources. EPA TSCA filing requirements extend certification timelines for new battery-grade material entrants. The Gulf Coast refining corridor maintains steady catalyst precursor offtake from established industrial relationships.
Japan
Electronics material plants in Osaka and Nagoya specify ultra-low alkali metal impurities for semiconductor polishing applications. METI supply chain resilience initiatives are subsidizing domestic stockpiling of critical battery chemicals including cobalt compounds. South Korean cathode producers are compressing qualification timelines to secure Japanese-refined material for solid-state electrolyte programs.
South Korea
Battery material plants in Gwangju and Ulsan are establishing direct refiner relationships to bypass distributor intermediaries in high-volume corridors. MFDS pharmaceutical-grade certification creates a parallel demand stream for reagent-tier cobalt nitrate in active ingredient synthesis. POSCO and LG Chem affiliate facilities are piloting sulfide electrolyte formulations requiring specialized precursor specifications.
Cobalt Nitrate Market Vendor Landscape
Chinese refiners anchor the volume tier; European and North American specialists hold premium-grade positioning through purity certification and traceability documentation. The vendor base stratifies across integrated mining-refining conglomerates, specialty chemical distributors, and reagent-grade laboratory suppliers. Three archetypes dominate: mechanized African concentrate processors with captive refining assets, European REACH-registered specialty chemical houses, and North American reagent distributors serving pharmaceutical and aerospace end users. Capacity expansion and qualification-driven partnership formation are the dominant competitive moves as cathode producers consolidate supplier panels ahead of plant ramp-ups.
Within the European specialty chemical tier, Umicore exemplifies integrated refining and battery materials platform positioning, while Merck KGaA occupies the analytical-grade purity segment for pharmaceutical applications. Among North American suppliers, American Elements represents the specialty chemicals portfolio archetype serving defense-sensitive aerospace programs with full material traceability. Sigma-Aldrich Corporation sits within the laboratory reagent distribution tier, anchoring academic and industrial R&D demand through global catalog networks. These three companies illustrate how geographic origin and certification depth determine competitive positioning rather than scale alone.
| Leading Market Players |
|---|
| Sigma-Aldrich Corporation |
| Umicore |
| American Elements |
| GFS Chemicals |
| Strem Chemicals |
| Thermo Fisher Scientific |
| Merck KGaA |
| Honeywell International |
| Alfa Aesar |
| Others |
Supply Flow & Price Mechanics
LME cobalt metal pricing cascades through nitrate refining economics, compressing margins for merchant processors while integrated Chinese refiners absorb volatility through captive concentrate sourcing. Battery-grade purity premiums widen during concentrate supply disruptions as cathode producers pay qualification security over spot optimization.
Pricing Analysis
Distributor margins in European battery material corridors absorb documentation and certification costs that direct refiner-to-cathode-plant relationships bypass through long-term offtake contracting. Three-tier pricing structure across reagent, laboratory, and industrial grades separates pharmaceutical synthesis applications from ceramic pigment volume buyers, with REACH-registered material commanding certification premiums. Cost compression in industrial-grade shipments intensifies as Chinese mechanized concentrate processing expands output. Agricultural distributors exhibit highest price sensitivity, while aerospace programs with DoD traceability mandates show lowest elasticity.
Supply Chain Analysis
ICP-MS and XRF specialist shortages in German and South Korean battery material hubs constrain incoming cobalt nitrate purity verification throughput, extending batch release timelines. Supply concentrates in Chinese Yangtze and Pearl River Delta refining clusters, with secondary processing nodes in Belgian Antwerp-Rotterdam corridor and Japanese Osaka-Nagoya electronics belt. Raw material flows draw from mechanized DRC concentrate operations, Australian laterite intermediates, and Indonesian mixed hydroxide precipitate. Single-geography processing vulnerability in Chinese integrated clusters exposes non-Chinese cathode producers to documentation disruption under MEE hazardous chemical inventory enforcement. Distribution runs through qualified distributor networks for laboratory-grade shipments, while battery-grade volumes shift toward direct refiner relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where North American IRA production tax credits offset Chinese refining cost advantages for qualified non-Chinese supply chains.
For Market Incumbents: Deploy backward integration into mechanized African concentrate sourcing to secure traceability documentation ahead of DRC supply chain due diligence mandate expansion. Deepen certification investment in REACH-registered analytical-grade capacity to defend margin position against high-nickel cathode substitution threats in battery applications. Channel control through direct refiner-to-cathode-plant contracting displaces distributor intermediaries in South Korean and Japanese corridors. For New Entrants and Emerging Players: Launch via reagent-grade pharmaceutical applications insulated from battery chemistry substitution pressures, targeting USP-grade catalyst precursor synthesis with MFDS certification pathway. White-space concentration in North American aerospace superalloy coatings with DoD traceability mandates excludes established Chinese suppliers. Penetrate through specialty chemical distributors serving academic and industrial R&D laboratories with batch-certified material. For Investors and Strategic Acquirers: Asymmetric upside sits with European REACH-registered specialty chemical houses with integrated refining and battery materials platforms. Long-term viability over the analysis window hinges on qualification-driven partnership formation with automotive OEM solid-state electrolyte programs. Acquisition target archetype: mechanized concentrate processors with captive nitrate refining assets and third-party audited chain-of-custody systems. Monitor cathode chemistry qualification timeline compression as inflection indicator for precursor demand intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanized Concentrate Sourcing | DRC due diligence mandates favor traceable supply chains over artisanal-exposed merchant refiners. |
| REACH-Registered Analytical-Grade Capacity Expansion | ECHA substance evaluation protocols force purity upgrades across imported cobalt nitrate streams. |
| Direct Refiner-to-Cathode-Plant Contracting | South Korean battery material producers compress qualification timelines ahead of solid-state ramp-ups. |
| Continuous Flow Crystallization Technology Deployment | Automated particle size control qualifies European producers for automotive OEM direct-supply agreements. |
| Reagent-Grade Pharmaceutical Certification Investment | MFDS and USP-grade pathways insulate revenue from NMC 811 cobalt loading reduction. |
Methodological Framework
Multiple input streams — primary interviews with cobalt refinery plant managers, cathode producer procurement leads, and specialty chemical distribution channel partners, plus secondary validation through customs trade data, SEC 10-K filings, and ECHA REACH registration databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured qualification timeline dynamics and purity verification protocols across German, South Korean, and North American battery material corridors. Secondary sources included cobalt concentrate trade flow tracking, MEE hazardous chemical inventory filings, and automotive OEM supply chain disclosure documents.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of grade tier, end-use application, packaging format, and regional production hub. CAGRs were derived from application-specific demand elasticity analysis and substitution threat assessment in cathode chemistry evolution. Forecast inputs incorporated solid-state electrolyte formulation qualification timelines, artisanal mining restriction enforcement trajectories, and IRA production tax credit utilization rates in North American cathode plant construction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt metal price volatility extremes and regulatory enforcement discontinuities. Assumptions reflect documented qualification patterns, concentrate supply reconfiguration timelines, and chemistry substitution elasticity. Material deviation in cathode chemistry adoption rates or DRC supply chain due diligence mandate scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Garnet Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Cesium Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Precious Metals E-Waste Recovery Market