
 LAMEA Dimethyl Phosphate Market | 2026-2036
LAMEA Dimethyl Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Dimethyl Phosphate Market Insights
Buyer concentration among agricultural chemical distributors is expanding across the LAMEA region as cooperatives and large-scale farming enterprises consolidate procurement volumes. OCP SA anchors phosphate value chain integration from mining through downstream derivative production in Morocco. The Mosaic Company leverages its established logistics infrastructure to compete in Brazilian and Argentine agricultural markets. ICL Group Ltd. differentiates through specialty phosphate expertise serving industrial solvent and flame retardant segments.
Dimethyl phosphate functions as an organophosphate ester synthesized through methanol-phosphorus pentoxide reaction or trimethyl phosphate partial hydrolysis, serving primarily as a chemical intermediate for agrochemical synthesis and as a solvent or reagent in pharmaceutical manufacturing. Agricultural chemicals dominates product type demand as phosphate ester intermediates feed herbicide and pesticide production across Brazil and South Africa. Flame retardants represents the fastest-growing product type segment as electronics manufacturers in the UAE and Israel adopt phosphorus-based halogen-free alternatives. Liquid form leads distribution volumes due to handling efficiency in bulk chemical transport, though granular formulations gain traction in precision agriculture applications.
Brazil's ANVISA chemical registration requirements and South Africa's Department of Agriculture, Land Reform and Rural Development fertilizer control regulations shape product compliance costs and market access timelines for dimethyl phosphate derivatives. Saudi Arabia's SFDA and Israel's Ministry of Health pharmaceutical standards influence solvent-grade specifications for API manufacturing applications. Stakeholders must monitor evolving national chemical inventories across LAMEA jurisdictions as regulatory divergence between Mercosur, GCC, and African regional frameworks creates compliance complexity for cross-border suppliers.
Market Dynamics
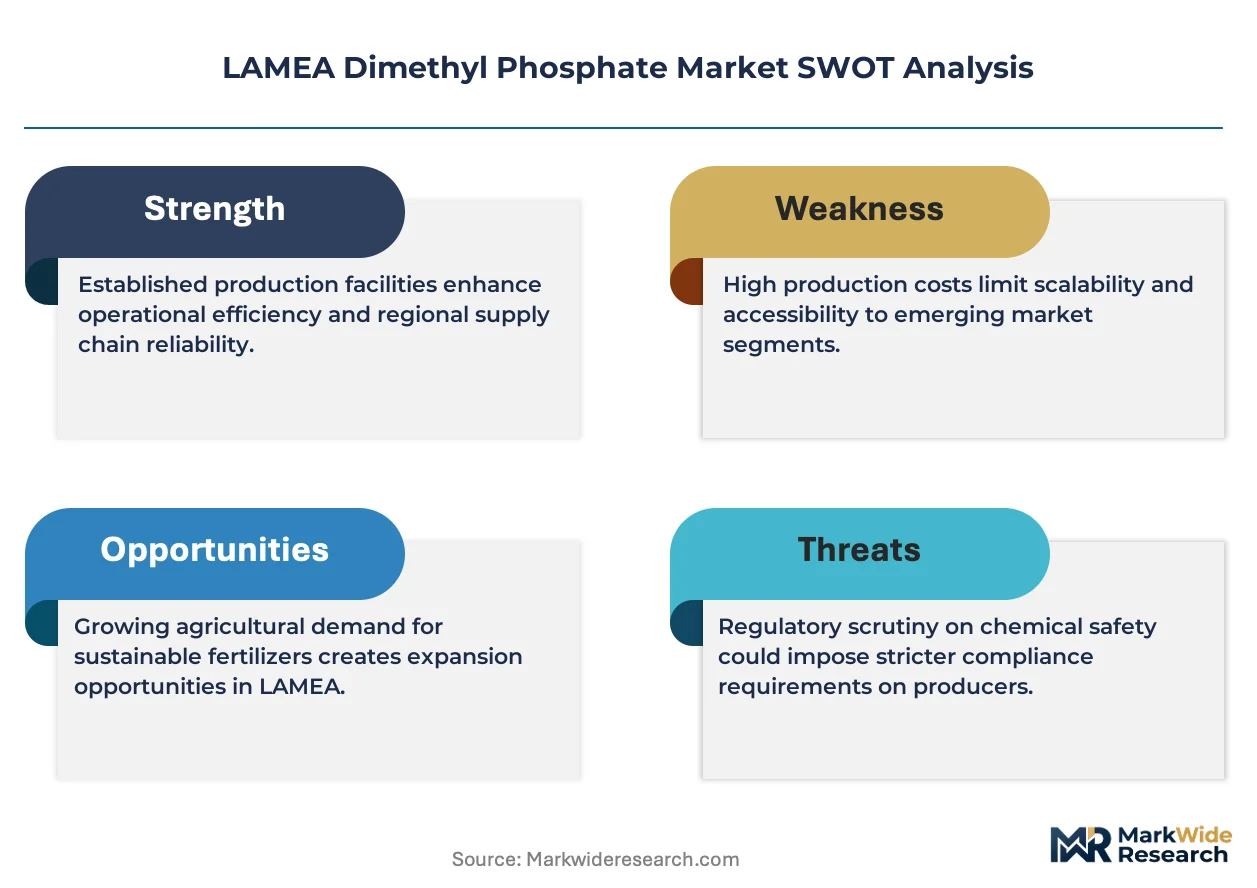
REACH-aligned chemical safety protocols are compressing product registration timelines across LAMEA export corridors while agricultural chemical distributors consolidate procurement volumes into fewer hands.
Growth Catalysts
- Phosphate-based fertilizer intermediates:Agricultural chemical formulators across Brazil's Cerrado belt are expanding procurement of dimethyl phosphate derivatives to feed herbicide synthesis pipelines.
- ANVISA chemical registration alignment:Brazil's regulatory harmonization with international standards is accelerating market access for compliant phosphate ester suppliers.
- Halogen-free flame retardant mandates:Electronics manufacturers in the UAE and Israel are adopting phosphorus-based alternatives for consumer device casings and circuit boards.
Market Restraints
- Methanol feedstock volatility:Input cost swings for methanol-phosphorus pentoxide reaction chemistry compress margin predictability for formulators.
- OCP SA supply concentration:Moroccan phosphate value chain integration creates dependency risk for derivative producers lacking captive phosphate rock access.
- Granular formulation technical barriers:Precision agriculture applications require particle size distribution control that liquid-handling infrastructure cannot easily replicate.
Strategic Opportunities
- Saudi specialty chemical zones:SFDA-aligned manufacturing clusters offer tariff-advantaged export positioning for pharmaceutical-grade solvent production.
- South African fertilizer control modernization:Department of Agriculture, Land Reform and Rural Development regulatory updates create first-mover advantage for compliant registrants.
- API manufacturing solvent convergence:Israel's Ministry of Health pharmaceutical standards and UAE MOHAP requirements are driving demand for high-purity dimethyl phosphate in active pharmaceutical ingredient synthesis.
Industry Challenges
- Cross-border compliance talent scarcity:Mercosur, GCC, and African regional regulatory divergence requires specialized registration expertise that distributor networks struggle to staff.
- Legacy liquid infrastructure capex:Granular formulation adoption demands silo and pneumatic handling investments that cooperatives defer during fertilizer price cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Dimethyl Phosphate Market |
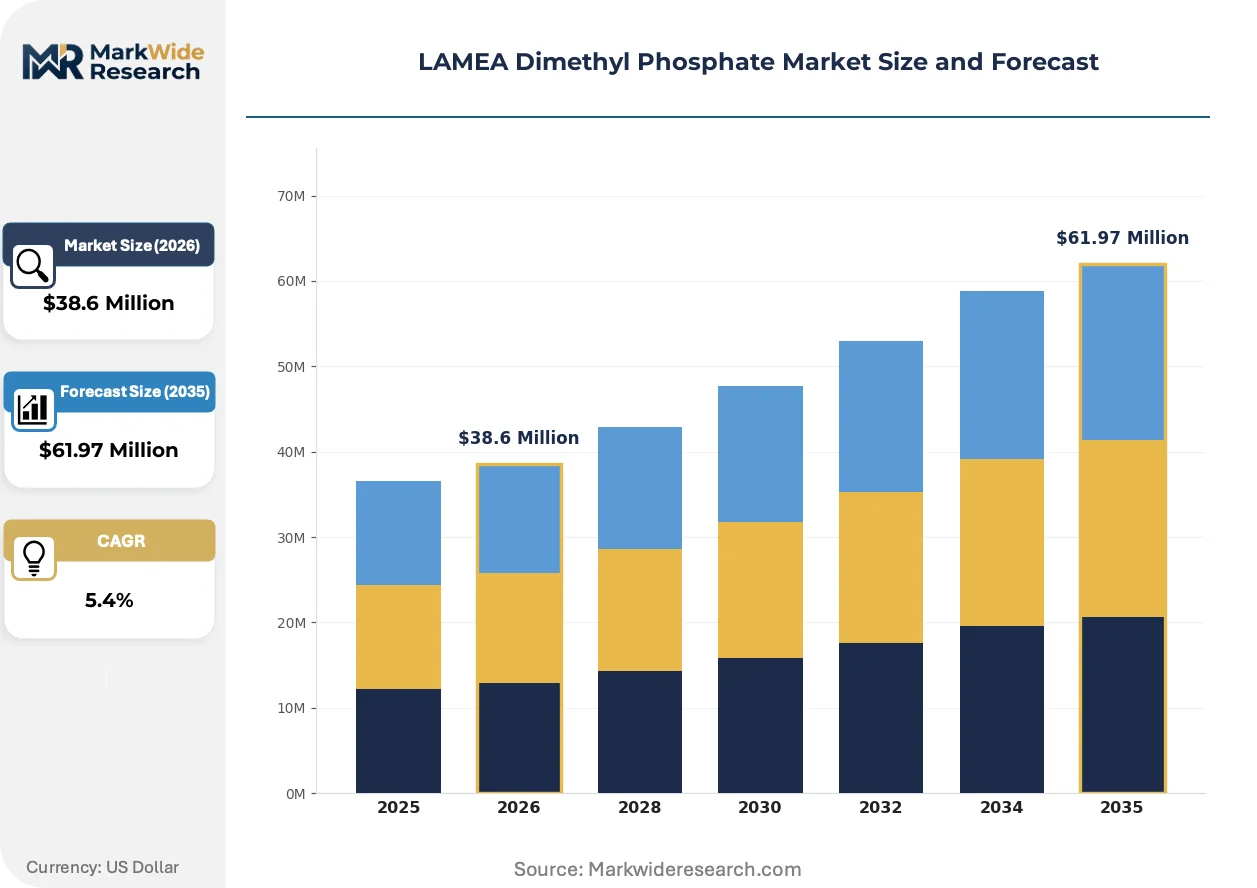
| Market Size in 2026 | $38.6 Million |
| Market Size in 2035 | $61.97 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural Chemicals, Industrial Solvents, Personal Care Products, Flame Retardants End Use Industry: Agriculture, Pharmaceuticals, Cosmetics, Electronics Form: Liquid, Powder, Granular, Solution Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale |
| Companies Covered | OCP SA, The Mosaic Company, ICL Group Ltd., PJSC PhosAgro, Nutrien Limited, Ma'aden, Yara International ASA, EuroChem Group AG, Innophos Holdings, Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Dimethyl Phosphate Market Trends and Innovations
Process intensification and regulatory harmonization are compressing traditional synthesis pathways while buyer consolidation reshapes channel economics across Latin America, the Middle East, and Africa.
Continuous-flow methanol-phosphorus pentoxide reaction systems are expanding into commercial dimethyl phosphate production. Brazilian agrochemical formulators are retrofitting batch plants with modular flow chemistry units to reduce solvent waste and thermal degradation losses. This technology is expanding into mid-scale producers who previously lacked capital for dedicated continuous processing lines, compressing the cost gap between commodity and specialty grade outputs.
REACH-aligned chemical safety protocols are mandating extended toxicological dossiers for phosphate ester registrations in key LAMEA export corridors. South Africa's Department of Agriculture, Land Reform and Rural Development and Brazil's ANVISA are cross-referencing ECHA hazard classifications, extending registration timelines by 12-18 months for non-compliant legacy products. Agricultural chemical distributors with pre-registered portfolios are capturing shelf space from smaller competitors facing documentation gaps.
Cooperative procurement consolidation is displacing fragmented distributor networks across Brazil's Cerrado and South Africa's grain belt. Large-scale farming enterprises are negotiating direct supply agreements with phosphate derivative manufacturers, bypassing traditional chemical traders. This pattern is most visible in Argentina's soybean belt where crop input cooperatives now represent 40% of phosphate ester intermediate volumes, forcing legacy distributors to unbundle technical advisory services from product supply.
LAMEA Dimethyl Phosphate Market Segmentation
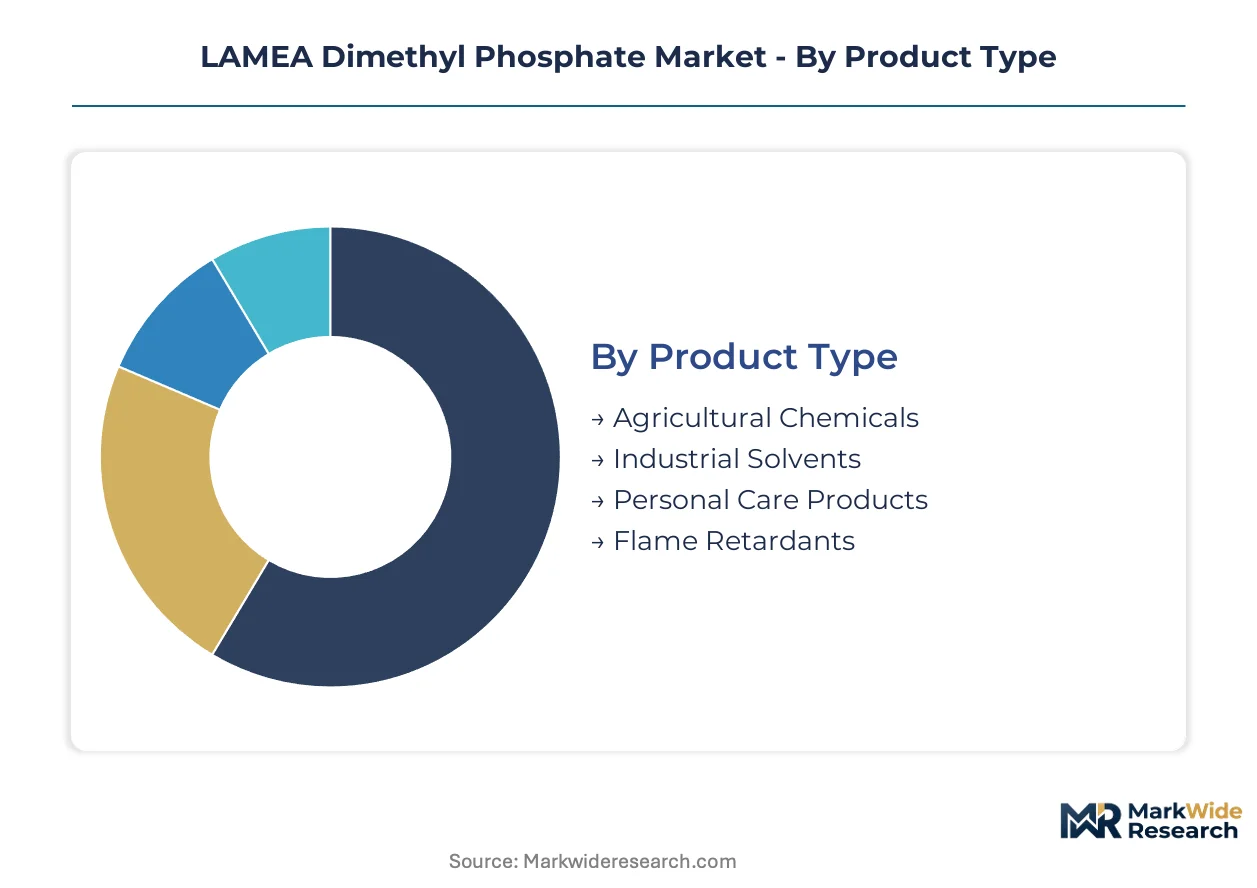
Dimethyl phosphate derivatives serve divergent functional requirements across LAMEA's agricultural, pharmaceutical, and industrial sectors. Specification-grade differentiation determines pricing power and regulatory compliance burdens for suppliers navigating Brazil's ANVISA registration pathways and Saudi Arabia's SFDA-aligned manufacturing zones.
Product Type:
Chemical functionality and purity specifications define procurement criteria across phosphate ester applications.
- Agricultural Chemicals:Phosphate ester intermediates synthesized through methanol-phosphorus pentoxide reaction feed herbicide and pesticide production pipelines. Demand concentrates in Brazil's Cerrado belt where cooperatives consolidate procurement volumes for glyphosate and organophosphate synthesis.
- Flame Retardants:Halogen-free phosphorus-based formulations serve electronics manufacturers in the UAE and Israel seeking RoHS-aligned alternatives for consumer device casings. Steepest expansion trajectory as circuit board producers adopt phosphate ester additives meeting thermal stability specifications.
- Industrial Solvents:High-purity grades serve API manufacturing applications under Israel's Ministry of Health pharmaceutical standards.
- Personal Care Products:Low-toxicity derivatives function as pH adjusters and emulsifiers in cosmetic formulations regulated by ANVISA.
Mature deployment sits with Agricultural Chemicals. Newer deployment is concentrated in Flame Retardants.
End Use Industry:
Application-specific purity tiers and volume scales shape supplier-customer contracting structures.
- Agriculture:Phosphate-based fertilizer intermediates dominate procurement volumes across Latin American cooperatives and South African grain belt enterprises. Brazil's Department of Agriculture, Land Reform and Rural Development fertilizer control regulations mandate registration documentation that compliant suppliers leverage for shelf space capture.
- Pharmaceuticals:Solvent-grade dimethyl phosphate serves active pharmaceutical ingredient synthesis under SFDA and UAE MOHAP standards. Expanding most quickly as regional API manufacturing clusters seek REACH-aligned chemical safety protocols for export corridor access.
- Electronics:Flame retardant applications concentrate in Israeli and Emirati circuit board manufacturing zones.
- Cosmetics:Personal care formulations require low-impurity specifications under ANVISA cosmetic registration requirements.
Volume leadership resides with Agriculture. Margin expansion concentrates in Pharmaceuticals.
Form:
Physical state determines handling infrastructure investments and precision agriculture compatibility.
- Liquid:Bulk chemical transport efficiency sustains distribution dominance across Brazilian and Argentine agricultural markets. Established tanker and drum logistics networks minimize switching costs for cooperatives.
- Granular:Particle size distribution control enables precision agriculture applications in South Africa's mechanized farming zones. Technical barriers around silo and pneumatic handling infrastructure constrain adoption cycles.
- Powder:Specialty chemical applications in pharmaceutical and electronics manufacturing favor controlled-dispersion formulations.
- Solution:Pre-diluted formats reduce on-site handling complexity for small-scale cosmetic and agrochemical formulators.
Installed base favors Liquid. Capex cycles are redirecting toward Granular.
Distribution Channel:
Buyer scale and technical advisory requirements determine channel economics across LAMEA jurisdictions.
- Direct Sales:Large-scale farming enterprises and pharmaceutical manufacturers negotiate supply agreements bypassing traditional chemical traders. Concentrated procurement volumes in Brazil's soybean belt and Saudi specialty chemical zones compress distributor margins.
- Wholesale:Agricultural chemical distributors with pre-registered portfolios capture intermediate volumes from cooperatives requiring technical advisory bundling.
- Retail:Small-scale formulators and cosmetic compounders access packaged quantities through regional chemical supply houses.
- E-commerce:Digital procurement platforms emerge for standardized solvent grades serving research and pilot-scale manufacturing.
Relationship-heavy contracting dominates Direct Sales. Digital penetration is advancing fastest in E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for dimethyl phosphate concentrates in Brazil's Cerrado agricultural belt and Saudi Arabia's specialty chemical manufacturing zones, with procurement consolidation among cooperatives and large-scale farming enterprises reshaping distribution economics across Latin America, the Middle East, and Africa.
Brazil
Cooperatives in Mato Grosso and Goiás drive phosphate ester intermediate procurement for glyphosate synthesis pipelines. ANVISA chemical registration alignment with REACH protocols compresses market access timelines for compliant suppliers. São Paulo-based formulators retrofit batch plants with modular flow chemistry units to reduce solvent waste.
Saudi Arabia
SFDA-aligned manufacturing clusters in Jubail Industrial City attract pharmaceutical-grade solvent production investments. The kingdom's specialty chemical zones offer tariff-advantaged export positioning for API manufacturing feedstocks. Riyadh-based distributors negotiate direct supply agreements with phosphate derivative manufacturers.
South Africa
Mechanized farming zones in Free State and North West provinces generate granular formulation demand for precision agriculture applications. The Department of Agriculture, Land Reform and Rural Development fertilizer control modernization creates first-mover advantage for compliant registrants. Durban's chemical handling infrastructure sustains bulk liquid distribution dominance.
Israel
Electronics manufacturers in Tel Aviv and Haifa adopt phosphorus-based halogen-free flame retardants for circuit board production. The Ministry of Health pharmaceutical standards drive high-purity dimethyl phosphate demand for API synthesis. Negev-based research clusters advance continuous-flow methanol-phosphorus pentoxide reaction systems.
United Arab Emirates
Consumer device casing producers in Dubai Silicon Oasis integrate phosphate ester additives meeting RoHS-aligned thermal stability specifications. MOHAP pharmaceutical standards converge with Israel's Ministry of Health requirements for solvent-grade specifications. Jebel Ali's logistics infrastructure supports re-export positioning across GCC markets.
LAMEA Dimethyl Phosphate Market Competitive Landscape
Moroccan producers anchor one tier through phosphate value chain integration; Israeli and Brazilian specialists hold differentiated positions in pharmaceutical and agricultural chemical segments respectively. Market structure reflects moderate concentration with OCP SA's upstream mining-to-derivatives integration creating supply-side leverage. Three archetypes dominate: vertically integrated phosphate miners, specialty chemical formulators with regulatory pre-registration advantages, and regional distributors with cooperative procurement relationships. Capacity expansion in Saudi specialty chemical zones and strategic partnerships for REACH-aligned toxicological dossiers represent the dominant competitive vectors.
Within the integrated mining tier, OCP SA exemplifies captive phosphate rock access extending through downstream derivative production. The Mosaic Company and ICL Group Ltd. occupy positions spanning agricultural chemical distribution and specialty phosphate expertise respectively. PJSC PhosAgro represents the scale-driven Russian producer archetype serving export corridors into Latin American markets. These three anchors illustrate how geographic origin and value chain positioning determine competitive options across LAMEA procurement networks.
| Leading Market Players |
|---|
| OCP SA |
| The Mosaic Company |
| ICL Group Ltd. |
| PJSC PhosAgro |
| Nutrien Limited |
| Ma'aden |
| Yara International ASA |
| EuroChem Group AG |
| Innophos Holdings, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive phosphate rock access through Moroccan mining-to-derivatives integration anchors supply positioning and pricing power for LAMEA dimethyl phosphate suppliers. OCP SA's upstream control over phosphate value chains enables margin capture that outsourced methanol-dependent formulators cannot replicate, compressing competitive options for derivative producers across Brazil and Saudi Arabia.
Pricing Analysis
Volume leadership in agricultural chemicals trades against margin expansion in pharmaceutical solvents. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade levels reflects ANVISA registration status and REACH-aligned toxicological dossier completeness. Cost compression in commodity agricultural intermediates is intensifying because methanol feedstock volatility erodes formulator margins. Cooperatives in Brazil's Cerrado belt exhibit highest price sensitivity, while API manufacturers under SFDA and Israel's Ministry of Health standards show lowest sensitivity due to purity certification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Moroccan phosphate rock concentration feeding downstream derivative production. Supply draws from Morocco, Saudi Arabia, and Russia as primary phosphate value chain nodes, with methanol sourcing tethered to regional petrochemical complexes in the GCC and Latin America. Tariff exposure across Mercosur-GCC trade corridors threatens re-export economics for Jebel Ali-based distributors. Distribution runs through direct sales agreements with large-scale farming enterprises and pharmaceutical manufacturers, bypassing traditional wholesale channels in concentrated procurement zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow methanol-phosphorus pentoxide reaction systems are displacing legacy batch processing infrastructure across LAMEA dimethyl phosphate manufacturing. This technology transition compresses cost structures for compliant producers while stranding capital in conventional plants.
For Market Incumbents: Deepen captive phosphate access through joint ventures with Moroccan or Saudi mining interests to offset methanol cost volatility. Secure ANVISA pre-registration portfolios before South Africa's Department of Agriculture, Land Reform and Rural Development completes fertilizer control modernization, as compliant dossiers capture shelf space from documentation-deficient competitors. Prioritize flow chemistry retrofits in São Paulo and Jubail facilities to reduce solvent waste losses below batch plant levels. For New Entrants and Emerging Players: Small-scale cosmetic formulators in Argentina's interior provinces represent an underserved buyer archetype requiring packaged solution formats and technical advisory bundling. Precision agriculture cooperatives in South Africa's Free State offer white-space access for granular formulation specialists with pneumatic handling expertise. Pursue regulatory consultancy partnerships with local registration agents to compress market access timelines against established distributors lacking Mercosur-specific compliance talent. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical formulators with REACH-aligned toxicological dossiers and pre-registered portfolios across multiple LAMEA jurisdictions. Long-term viability favors producers with backward integration into phosphate rock or forward integration into API manufacturing solvent supply agreements. Watch for ANVISA registration backlog clearance as an inflection indicator for competitive shelf space reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | OCP SA's captive rock access secures margin capture unavailable to methanol-dependent formulators. |
| Continuous-Flow Chemistry Retrofit | Brazilian agrochemical plants reduce thermal degradation losses through modular reaction systems. |
| REACH-Aligned Toxicological Dossier Investment | Pre-registered suppliers capture ANVISA shelf space from legacy products facing documentation gaps. |
| Direct Supply Agreement with Cooperatives | Mato Grosso farming enterprises bypass traditional distributors for phosphate ester intermediate procurement. |
| SFDA-Aligned Pharmaceutical-Grade Capacity | Jubail manufacturing clusters attract API solvent investments under Saudi pharmaceutical standards. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and industry association publications underwrites the qualitative findings in this analysis. Primary interviews with agrochemical formulators, phosphate derivative procurement leads, pharmaceutical manufacturing executives, and specialty chemical distribution partners combined with secondary validation from ANVISA registration portals, ECHA hazard classifications, and SEC 10-K disclosures. Bottom-up volume triangulation against top-down value estimates ensures cross-verification of market sizing across the analysis window.
Comparable-period anchoring to historical trade flow patterns and capacity utilization rates established the forecast baseline. The projection horizon models segmentation across product type, end-use industry, physical form, and distribution channel dimensions, with regional regulatory cluster effects incorporated for Brazil, Saudi Arabia, South Africa, Israel, and UAE markets. CAGRs derive from fitted growth curves adjusted for methanol feedstock volatility patterns and cooperative procurement consolidation trajectories. Forecast inputs include phosphate rock export volumes from Moroccan customs data and pharmaceutical-grade solvent demand signals from SFDA manufacturing cluster investments.
Revisions become necessary when REACH-aligned regulatory divergence accelerates across Mercosur, GCC, and African frameworks, or when methanol-phosphorus pentoxide feedstock economics shift abruptly. Forecasts reflect assumptions around cooperative procurement consolidation rates and continuous-flow technology adoption curves that material uncertainty could invalidate. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Scouring Agents Market
Chemicals
Thioacetic Acid Market
Chemicals
Global Thiophene Market
Chemicals
Hexamine Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Myclobutanil Market
Chemicals
Laboratory Chemicals Market
Chemicals
Malonic Acid Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Flooring Chemicals Market
Chemicals
Global Phenoxyethanol Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Isoamyl Acetate Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Medical Grade Zinc Sulfate Market