
 Titanium Ore Market | 2026-2036
Titanium Ore Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Ore Market Outlook
Ultra-high-grade rutile concentrate is rotating toward premium valuation tiers as chloride-route pigment producers tighten feedstock specifications. Rio Tinto leverages vertical integration from mine to pigment to sustain margin capture across the value chain. Iluka Resources anchors its competitive position through long-life mineral sand assets in Western Australia. Tronox Holdings plc differentiates via chloride-process technology leadership and captive ore supply.
Titanium ore encompasses ilmenite, rutile, and leucoxene minerals containing titanium dioxide in concentrations ranging from 35% to 95%, extracted through surface mining of heavy mineral sands and subsequent gravity, magnetic, and electrostatic separation. These ores serve primarily as feedstock for titanium dioxide pigment production and titanium metal sponge via the Kroll process. Ilmenite dominates volume flows due to its abundance, while rutile commands structural premium pricing because of its higher TiO2 content and lower processing energy requirements for chloride-route pigment manufacture. The aerospace end-use segment concentrates margin pools, with high-grade and ultra-high-grade sponge feedstock drawing disproportionate investment focus from producers.
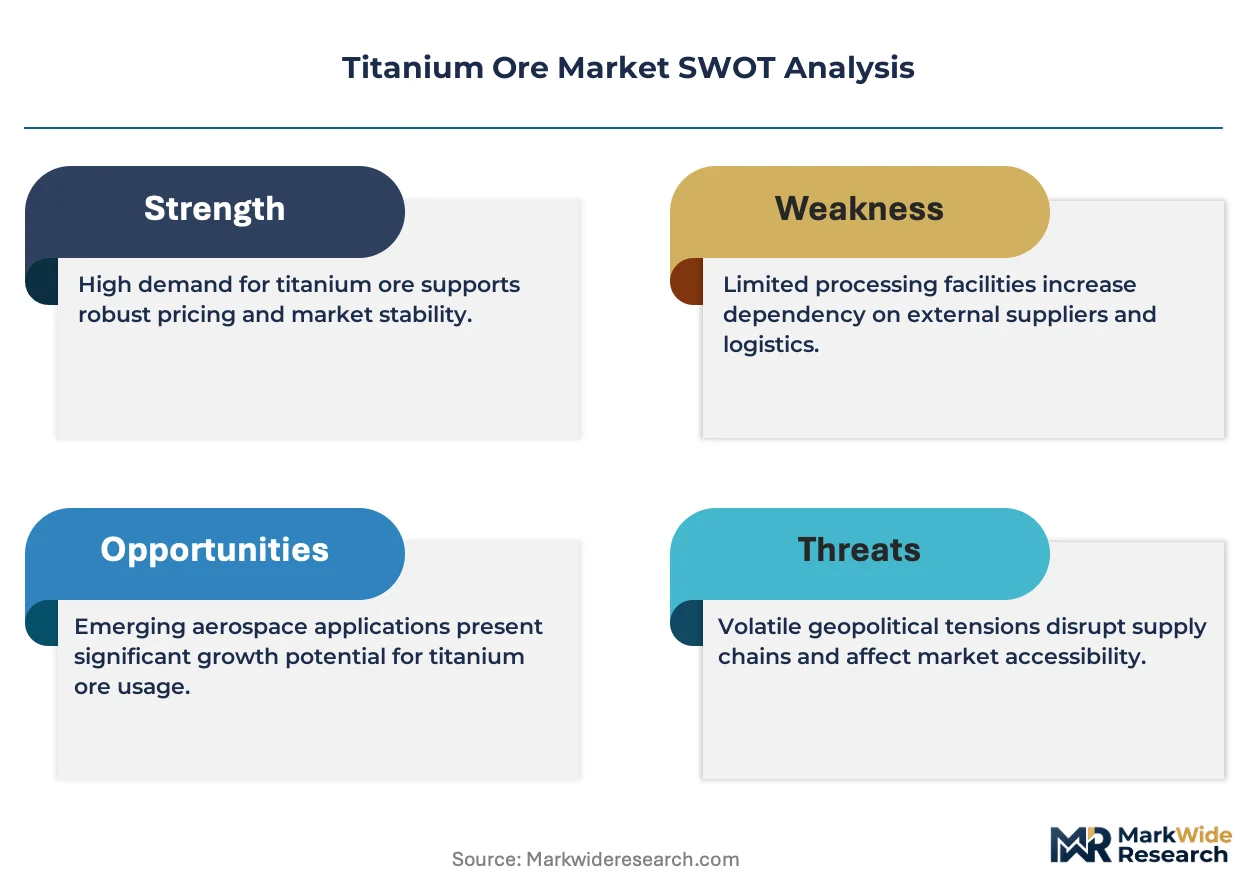
Australia's environmental regulators enforce stringent rehabilitation bonds for heavy mineral sand operations, while China's MEE imposes discharge limits on acid-leaching circuits used in synthetic rutile production. REACH in Europe mandates registration and hazard communication for titanium dioxide classification, directly shaping import specifications and product liability exposure for ore traders. Stakeholders must monitor evolving carbon border adjustments and traceability mandates that threaten to bifurcate market access between certified low-carbon feedstock and conventional supply.
Market Dynamics
Chloride-route pigment producers are tightening feedstock specifications, compressing acceptable impurity thresholds for titanium ore and bifurcating supply tiers between ultra-high-grade rutile and standard ilmenite streams.
Growth Catalysts
- Aerospace sponge procurement:Airframe and engine manufacturers are expanding long-term offtake agreements for high-grade titanium metal feedstock. Kroll-process sponge demand concentrates investment focus on premium ore grades.
- Western Australia heavy mineral districts:Concentrated ilmenite and rutile deposits in established mining corridors sustain scalable feedstock supply for chloride pigment producers.
- China's dual carbon goals:Stricter tailings regulations and discharge limits from MEE are forcing domestic processors toward cleaner synthetic rutile production methods.
Market Restraints
- Energy cost volatility:The Kroll process and chloride-route pigment manufacture are electricity-intensive, exposing margin structures to power price swings in smelting jurisdictions.
- Heavy mineral sand concentration:Mineable ore reserves cluster in Western Australia and South Africa, creating geographic supply risk for non-integrated pigment producers.
- REACH titanium dioxide classification:ECHA hazard communication mandates impose registration burdens and product liability exposure for ore traders serving European pigment manufacturers.
Strategic Opportunities
- Low-carbon feedstock certification:Emerging carbon border adjustments in Europe and traceability mandates are creating premium market access for certified low-carbon titanium ore streams.
- Synthetic rutile technology convergence:Becher process and reduction-roast-leach circuits are advancing energy efficiency, opening retrofit potential at legacy ilmenite upgrading facilities.
- India pigment capacity expansion:Domestic chloride-route plants under construction are generating new regional demand for imported high-grade rutile concentrate.
Industry Challenges
- Acid-leaching circuit compliance:China's MEE discharge limits on synthetic rutile production require capital-intensive wastewater treatment retrofits at existing upgrading plants.
- Heavy mineral sand rehabilitation bonds:Australia's environmental regulators mandate substantial upfront financial assurances for mine closure and landform reconstruction.
- Sponge-grade specification drift:Aerospace OEMs are tightening interstitial element limits on titanium metal feedstock, forcing ore processors to invest in additional beneficiation stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Ore Market |
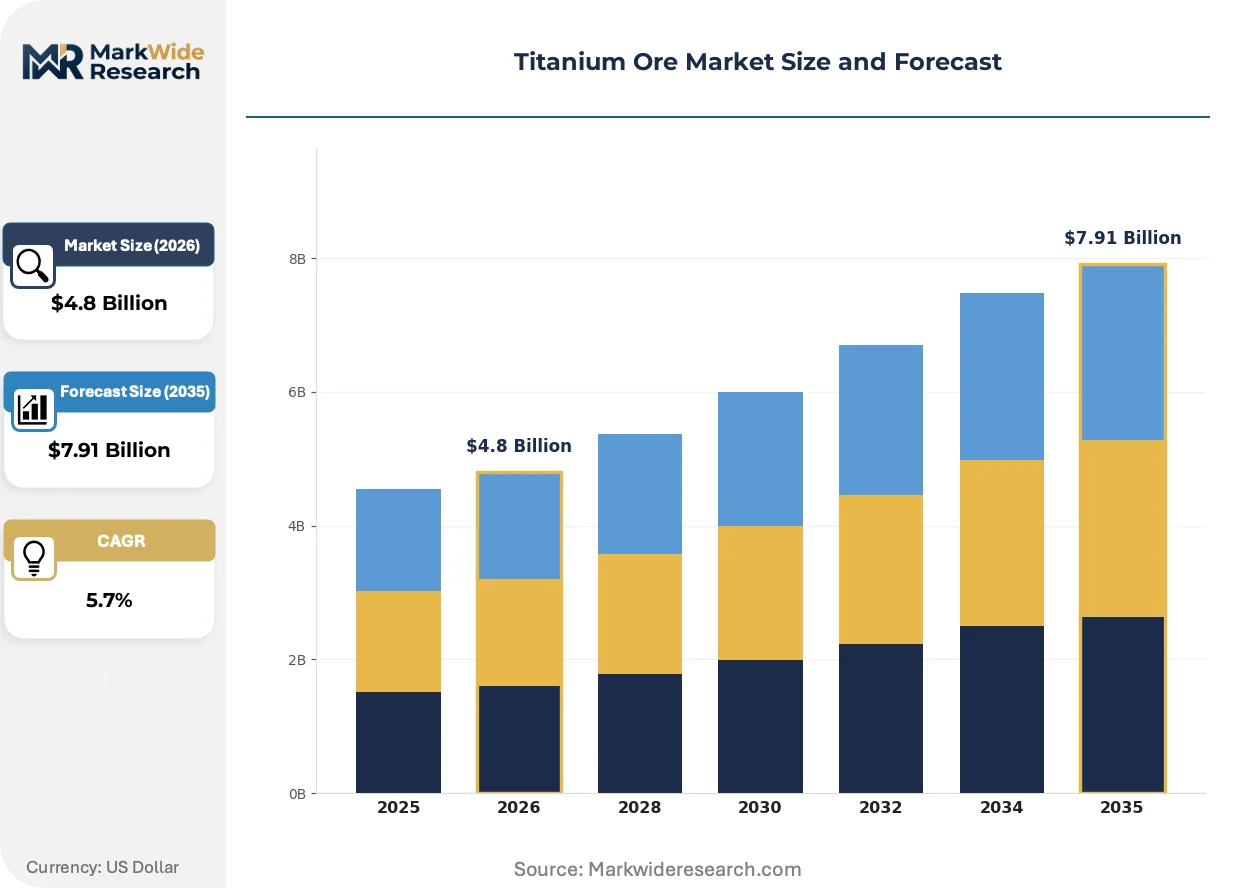
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ilmenite, Rutile, Leucoxene, Others End Use Industry: Aerospace, Automotive, Medical, Construction Form: Powder, Ingot, Sponge, Scrap Quality Grade: Low-Grade, High-Grade, Ultra-High-Grade, Others |
| Companies Covered | Iluka Resources Limited, Lomon Billions Group, Rio Tinto, Pangang Group Vanadium Titanium & Resources, The Chemours Company, Tronox Holdings plc, VSMPO-AVISMA Corporation, Toho Titanium Co. Ltd., Kenmare Resources plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Ore Market Strategic Shifts
Electrochemical reduction technologies and digital process control systems are compressing energy intensity and yield variability across titanium metal and pigment production chains.
Electrolytic titanium production via the FFC Cambridge process is miniaturizing the traditional Kroll reduction pathway. Specialty alloy producers and additive manufacturing feedstock suppliers are piloting modular electrochemical cells for sponge-grade metal. This technology is miniaturizing capital requirements and enabling distributed production closer to aerospace fabrication clusters.
REACH titanium dioxide classification under ECHA mandates is reshaping import documentation and hazard communication obligations for ore traders. The regulation forces explicit substance registration and downstream user notification for TiO2-containing materials. Pigment manufacturers serving European coatings and plastics markets are restructuring supply contracts to transfer compliance liability upstream.
Long-term offtake contracting is displacing spot market procurement for high-grade rutile concentrate. Chloride-route pigment producers are locking in multi-year supply agreements directly with heavy mineral sand operators to secure feedstock traceability for carbon accounting. This pattern concentrates most visibly in Western Australia, where Rio Tinto and Iluka Resources anchor contracted volume flows to Asian and European pigment plants.
Titanium Ore Market Segmentation
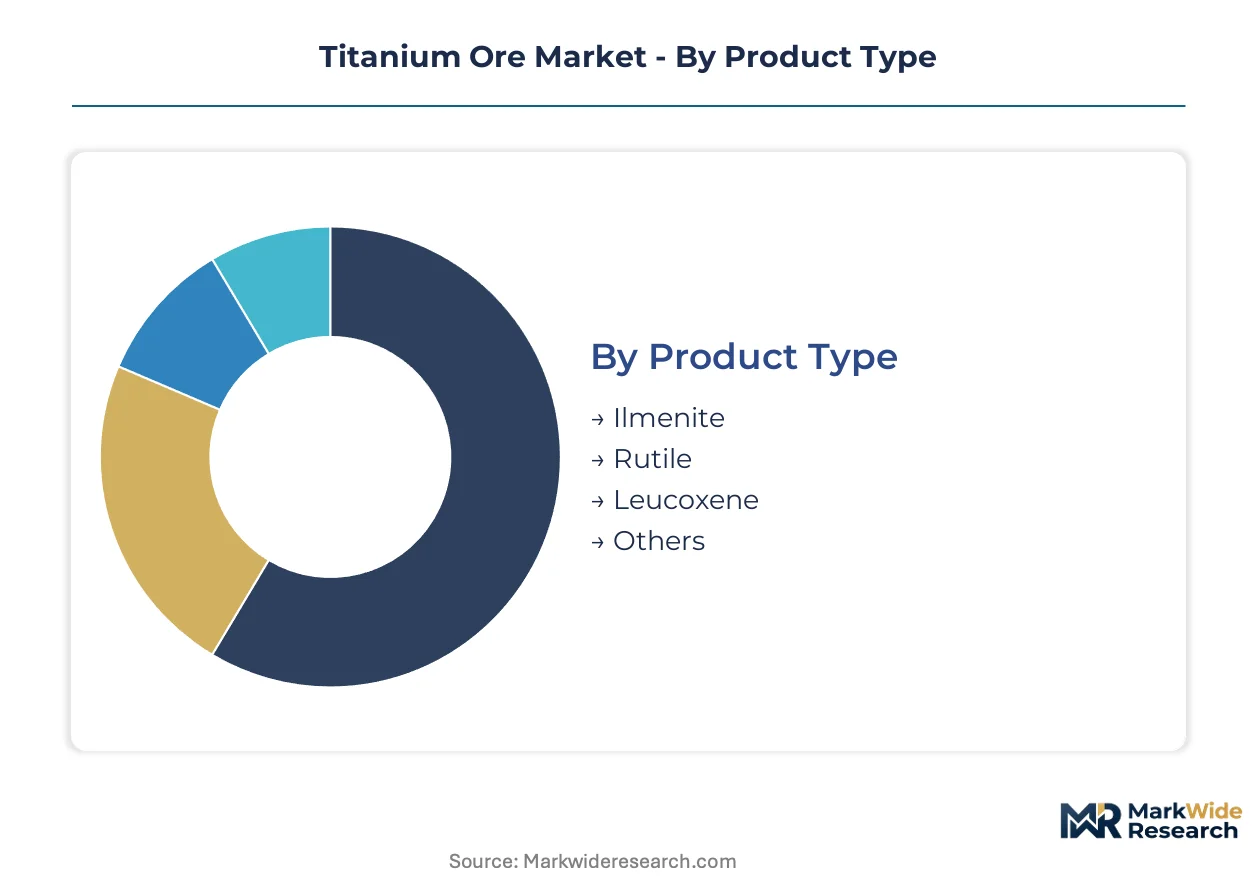
Titanium ore segmentation tracks distinct mineral chemistries, metallurgical forms, and purity specifications that command divergent pricing and end-use access. Understanding these divides clarifies where margin pools concentrate and which upgrade investments yield commercial leverage.
Product Type:
Ilmenite dominates domestic supply chains across heavy mineral sand districts, while rutile and leucoxene concentrate in export-oriented premium feedstock streams.
- Ilmenite:Titanium dioxide content ranges from 35% to 65%, making it the most abundant titanium ore globally. Demand concentrates in sulfate-route pigment plants across India and China, constrained by energy-intensive upgrading requirements for chloride compatibility.
- Rutile:Natural rutile contains 92% to 95% TiO2, serving as the preferred feedstock for chloride-process pigment manufacture without pre-treatment. Western Australian heavy mineral sand operators export the majority of global supply to Asian and European pigment producers seeking traceability for carbon accounting.
- Leucoxene:An altered ilmenite with intermediate TiO2 grades between 65% and 90%, sourced primarily from mature mineral sand deposits in South Africa and Australia for blending applications.
- Others:Anatase and perovskite deposits in Brazil and Russia supply niche ceramic and specialty chemical applications with limited scale.
Ilmenite holds the largest share; momentum sits with rutile as chloride-route pigment capacity expands.
End Use Industry:
Cost tier stratification separates commodity pigment feedstock from aerospace-grade metal sponge, with medical and construction occupying intermediate value positions.
- Aerospace:Titanium sponge derived from high-grade ore feeds airframe structures and jet engine components requiring strength-to-weight ratios exceeding aluminum alloys. Boeing and Airbus supply chains source exclusively from certified low-interstitial sponge producers in Japan and the US.
- Automotive:Exhaust system components and valve train hardware utilize standard-grade titanium metal from Russian and Chinese sponge producers, with European OEMs tightening scrap-recycling mandates under EU Green Deal carbon thresholds.
- Medical:Surgical implants and prosthetic devices demand ultra-high-purity sponge with oxygen content below 800 ppm, processed through electron beam melting of carefully selected rutile-derived feedstock.
- Construction:Architectural coatings and corrosion-resistant piping represent volume applications for standard ilmenite, with Chinese infrastructure stimulus directing regional procurement patterns.
Aerospace commands the steepest premium pricing; automotive represents the fastest-expanding volume application as lightweighting mandates tighten.
Form:
Supply concentration in sponge and ingot reflects Kroll process economics, while powder and scrap distribution patterns track additive manufacturing adoption and circular economy regulations.
- Powder:Plasma-rotating electrode and gas-atomized powders serve additive manufacturing feedstock for aerospace bracketry and medical implants, with US and European powder producers qualifying lots against ASTM F2924 specifications.
- Ingot:Vacuum-arc remelted ingots constitute the primary mill product for forging and rolling operations, with Russian VSMPO-AVISMA and Japanese Toho Titanium controlling the majority of global merchant supply.
- Sponge:The Kroll process produces porous titanium metal from rutile or synthetic rutile reduction, with Ukrainian and Kazakh producers disrupting traditional supply flows.
- Scrap:Turnings, solids, and cluster scrap recycle through specialty melters in the US, UK, and Japan, with aerospace-grade scrap commanding premiums over standard commercial classifications.
Ingot holds the largest share; powder is gaining share fastest as metal additive manufacturing capacity scales.
Quality Grade:
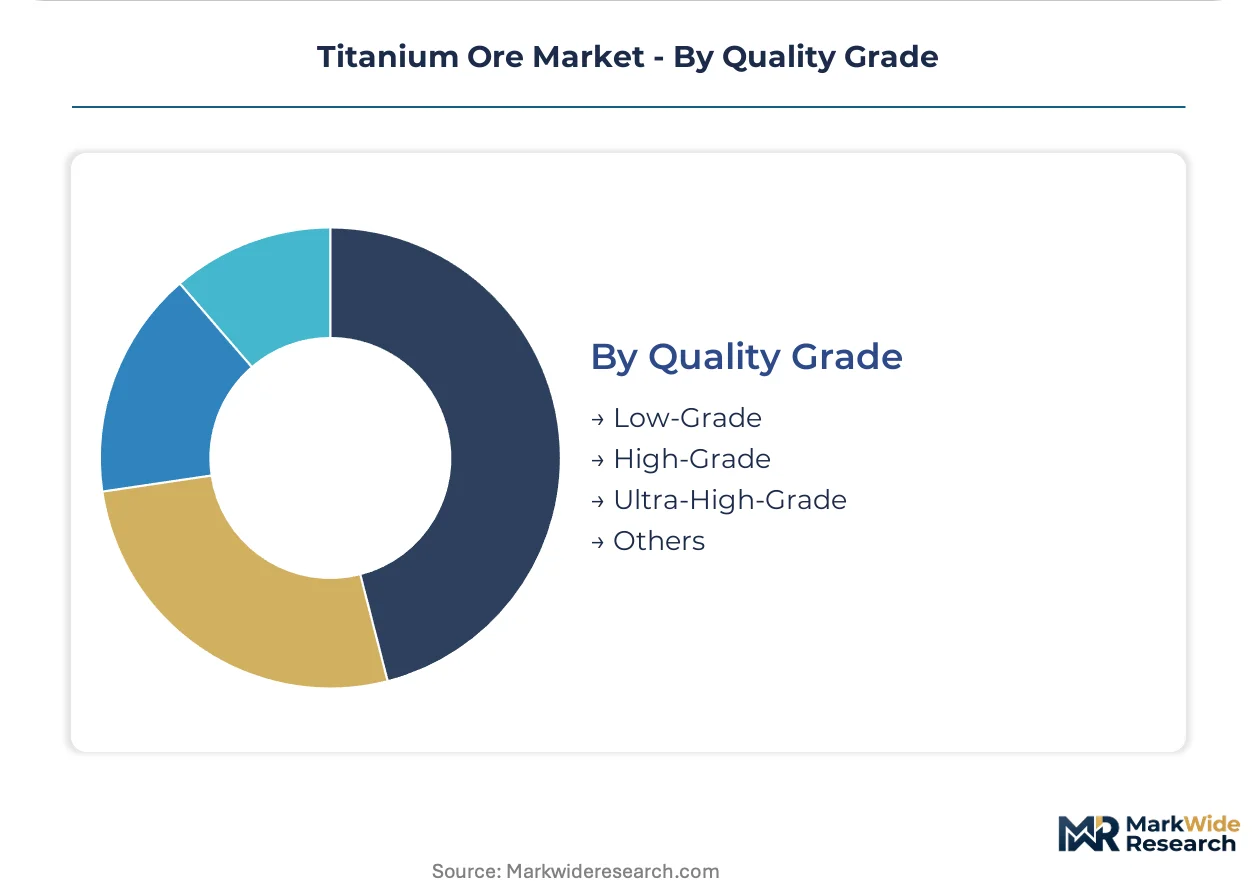
Customer type stratification separates pigment producers purchasing bulk low-grade ore from aerospace OEMs specifying interstitial element limits below 100 ppm for critical rotating components.
- Low-Grade:Standard ilmenite and unprocessed heavy mineral sand concentrates serve sulfate-route pigment plants and welding electrode coatings, with Chinese domestic mines supplying the majority of regional demand.
- High-Grade:Synthetic rutile and beneficiated ilmenite with 85% to 92% TiO2 content feed chloride pigment plants in Mississippi and Yanbu, with Tronox and Chemours operating dedicated upgrading circuits.
- Ultra-High-Grade:Natural rutile and electron-beam-refined sponge meet aerospace and medical specifications for oxygen, nitrogen, and iron content, with Australian and South African mines supplying the concentrated feedstock base.
- Others:Intermediate grades and off-specification materials serve foundry and chemical applications with relaxed purity requirements.
Low-grade material holds the largest share; ultra-high-grade commands the steepest expansion trajectory as aerospace procurement tightens certification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy mineral sand deposits cluster in Western Australia and South Africa, concentrating mineable reserves in established mining corridors. Chloride-route pigment plants in Mississippi and Yanbu draw feedstock from these concentrated districts. Regulatory pressure on acid-leaching circuits is reshaping synthetic rutile production economics in major processing jurisdictions.
Australia
Western Australia's heavy mineral sand districts supply concentrated ilmenite and rutile to Asian pigment producers. TGA environmental regulators enforce substantial rehabilitation bonds for mine closure and landform reconstruction. Perth-based operators anchor contracted volume flows to European and Asian chloride-route plants seeking carbon traceability.
China
Domestic ilmenite processors face tightening discharge limits from MEE on synthetic rutile acid-leaching circuits. The country's dual carbon goals are forcing capital-intensive wastewater treatment retrofits at upgrading facilities. Sichuan and Hainan provinces host the majority of synthetic rutile capacity undergoing compliance-driven technology convergence.
United States
Mississippi chloride-route pigment plants source high-grade rutile concentrate through long-term offtake agreements. EPA regulations on heavy mineral sand tailings management shape permitting timelines for domestic exploration projects. Florida's established mining corridor sustains limited domestic heavy mineral sand extraction for regional pigment supply.
South Africa
Richards Bay mineral sand deposits supply leucoxene and rutile for blending applications in pigment manufacture. The country's environmental regulators mandate financial provisions for rehabilitation of coastal dune mining operations. KwaZulu-Natal processing facilities face pressure to upgrade energy efficiency in reduction-roast-leach circuits.
Ukraine
Titanium sponge producers have disrupted traditional supply flows to European aerospace fabricators. The country's national mining regulator oversees ilmenite extraction from central Ukrainian deposits. Ongoing geopolitical instability constrains operational continuity at sponge-grade metal facilities.
Titanium Ore Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the titanium ore value chain. Heavy mineral sand operators concentrate in Western Australia and South Africa, while integrated pigment manufacturers control chloride-process technology. The market structure separates upstream miners, midstream upgraders, and downstream pigment and metal producers. Dominant competitive moves include long-term offtake contracting for feedstock traceability and captive ore supply integration.
Within the integrated mining-to-pigment tier, Rio Tinto and Iluka Resources exemplify vertical control from heavy mineral sand extraction to pigment manufacture. Tronox Holdings plc occupies a position emphasizing chloride-process technology leadership. Among specialty metal producers, VSMPO-AVISMA Corporation and Toho Titanium Co. Ltd. represent the sponge-grade supply base serving aerospace certification requirements.
| Leading Market Players |
|---|
| Iluka Resources Limited |
| Lomon Billions Group |
| Rio Tinto |
| Pangang Group Vanadium Titanium & Resources |
| The Chemours Company |
| Tronox Holdings plc |
| VSMPO-AVISMA Corporation |
| Toho Titanium Co. Ltd. |
| Kenmare Resources plc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Western Australian heavy mineral sand operations shapes both supply concentration and price floors for titanium ore. Chloride-route pigment producers in Mississippi and Yanbu absorb transport premiums to secure rutile concentrate traceability, while China's MEE discharge limits on synthetic rutile acid-leaching circuits compress margin structures for domestic upgraders.
Pricing Analysis
REACH titanium dioxide classification under ECHA dictates the pricing tier structure for ore traders serving European pigment manufacturers. Contract-based long-term offtake agreements dominate high-grade rutile procurement, with quality grade and certification level for carbon traceability driving price differentiation. Pricing pressure stems from energy cost volatility in Kroll-process sponge production, squeezing margin structures for non-integrated metal producers. Pigment manufacturers exhibit highest price sensitivity on standard ilmenite feedstock, while aerospace OEMs accept premiums for ultra-high-grade sponge with interstitial elements below 100 ppm.
Supply Chain Analysis
Inventory cycles at Richards Bay and Western Australian port terminals extend lead times for Asian pigment plants during monsoon disruptions. Mineable reserves cluster in Australia, South Africa, and Ukraine, with heavy mineral sand concentration creating geographic supply risk for non-integrated producers. The supply chain draws from ilmenite, rutile, and synthetic rutile feedstocks, with acid-leaching circuit compliance costs in China and rehabilitation bond requirements in Australia amplifying tariff exposure. Distribution runs through long-term offtake contracting directly from heavy mineral sand operators to chloride-route pigment plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolytic titanium production via the FFC Cambridge process is disrupting traditional Kroll reduction economics, compressing capital requirements and enabling distributed sponge manufacturing closer to aerospace fabrication clusters.
For Market Incumbents: Shield market position through captive ore supply integration and backward integration into synthetic rutile upgrading circuits. Rio Tinto and Iluka Resources exemplify vertical control from Western Australian heavy mineral sand extraction to pigment manufacture. Defend against electrochemical reduction technology disruption by piloting modular FFC Cambridge cells for specialty alloy feedstock.
For New Entrants and Emerging Players: Lead with low-carbon feedstock certification to capture premium market access under emerging EU carbon border adjustments. India's expanding chloride-route pigment capacity represents the most penetrable geography, with domestic plants under construction generating new regional demand for imported high-grade rutile concentrate. Pursue direct supply agreements with heavy mineral sand operators bypassing established trader networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heavy mineral sand operators with long-life assets and established carbon traceability systems. Long-term viability over the projection horizon hinges on feedstock tier access for aerospace sponge certification. Watch for FFC Cambridge process commercialization scale as the inflection signal for Kroll process displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rutile | Tronox and Chemours secure captive feedstock for Mississippi chloride plants, insulating margin structures from spot market volatility. |
| Long-term Supply Agreement | Perth-based operators anchor contracted volume flows to European pigment manufacturers seeking carbon accounting traceability. |
| Green Manufacturing Transition | Becher process retrofits at Chinese upgrading facilities address MEE discharge limits while reducing energy intensity. |
| Capacity Expansion | Western Australian heavy mineral sand districts sustain scalable rutile supply for Asian aerospace sponge procurement growth. |
| Joint Venture | Specialty alloy producers partner with electrochemical cell developers to pilot distributed titanium sponge production. |
Study Parameters
Cross-validation between primary interviews with heavy mineral sand operators and secondary trade data anchors the qualitative findings in this study. Plant managers at Western Australian and South African extraction facilities, procurement leads at chloride-route pigment plants in Mississippi and Yanbu, and technical R&D directors at sponge-grade metal producers provided operational perspectives. Secondary sources include customs and trade flow databases, SEC 10-K filings from integrated pigment manufacturers, and TGA environmental compliance records. Bottom-up segment sizing triangulates against top-down value chain estimates across mineral chemistry, metallurgical form, and end-use industry dimensions.
Sensitivity analysis on energy cost assumptions and aerospace procurement trajectories shapes the analytical framework across the projection horizon. Segmentation modeling spans product type, end-use industry, form, and quality grade, with regional production hub clusters as an additional dimension. CAGRs derive from fitted trend extrapolation against capacity expansion announcements and regulatory compliance timelines. Industry-specific forecast inputs include Kroll process electricity intensity curves and chloride-route pigment plant feedstock specification drift.
The analysis sits within stated boundaries; outcomes outside sustained aerospace demand growth or electrochemical reduction technology maturation would require recalibration. Forecasts reflect assumptions on MEE enforcement consistency and EU carbon border adjustment implementation scope. Geopolitical disruption to Ukrainian sponge supply and acid-leaching circuit retrofit delays in China represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Metal and Metal Ores Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Gregoryite Market