
 Recycled Scrap Metal Market | 2026-2036
Recycled Scrap Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Scrap Metal Market Outlook
Scrap metal processing and value-added sorting is reconfiguring profit pools away from raw collection toward refined secondary ingot production. Sims Limited leverages advanced sensor-based separation technology to capture premium non-ferrous fractions. Nucor Corporation anchors its electric arc furnace network with deep scrap sourcing relationships across North America. Aurubis AG competes through copper concentrate substitution with complex multi-metal scrap feeds.
Recycled scrap metal comprises post-consumer and post-industrial metallic discards recovered through mechanical processing, pyrometallurgical refining, or hydrometallurgical extraction to achieve specified purity grades for re-melting. Steel scrap typically contains residual copper below 0.20% and tramp elements controlled to ASTM or EN standards to prevent brittleness in new long products. Aluminum scrap dominates volume flows through shredding and eddy-current separation, though copper recovery from wire and cable commands disproportionate margin capture. Melting-based processing of sorted heavy scrap sustains the highest throughput economics, while baling and shearing serve fragmented construction demolition feeds where scale efficiencies remain limited.
The EPA oversees hazardous waste classifications that determine scrap metal exclusions from RCRASubtitle C, while the EU REACH framework restricts certain alloy additives in recycled feedstocks entering European manufacturing chains. China's SAMR enforces GB standards on imported scrap quality that have reshaped export destinations since policy tightening. Stakeholders must monitor evolving carbon-accounting rules that differentiate secondary metal premiums based on verified emissions reductions rather than traditional assay pricing alone.
Market Dynamics
Carbon-accounting verification is redefining value capture across secondary metal supply chains, with buyers now pricing scrap based on verified emissions reductions rather than traditional assay metrics alone. This shift rewards processors who can document furnace-level carbon intensity through blockchain-tracked chain-of-custody systems.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Import charges on embodied carbon in primary metals redirect automotive and construction procurement toward verified recycled feedstocks from European Electric Arc Furnace networks.
- Automotive lightweighting mandates:Secondary aluminum specifications for body-in-white applications are tightening residual tolerance requirements, pulling high-grade shredded auto scrap into closed-loop foundry relationships.
- Pyrometallurgical sensor integration:Laser-induced breakdown spectroscopy deployed at shredder yards enables real-time alloy sorting that upgrades mixed zorba fractions into furnace-ready specification grades.
Market Restraints
- Copper contamination thresholds:Residual copper above 0.20% in ferrous scrap triggers brittleness penalties in long-product rolling mills, constraining feedstock sourcing from obsolete demolition streams.
- Import quality barriers:China's SAMR enforcement of GB standards on scrap metal shipments has eliminated lower-grade mixed loads from export portfolios, compressing available outlet markets for North American collectors.
- Natural gas price volatility:Electric Arc Furnace operators face margin compression when regional gas benchmarks spike, since melting economics remain tied to energy input costs despite scrap feedstock discounts.
Strategic Opportunities
- India's circular economy infrastructure:BIS standardization of secondary metal grades and PLI scheme support for domestic Electric Arc Furnace capacity creates import substitution potential for shredded auto scrap.
- Building-integrated material passports:Digital twin documentation of structural steel and aluminum installations enables end-of-life recovery planning that secures deconstruction rights decades ahead of demolition.
- Hydrometallurgical copper extraction:Sulfuric acid leaching of complex multi-metal printed circuit board feeds recovers high-purity cathode copper while isolating rare earth elements for battery supply chain integration.
Industry Challenges
- Tramp element chemist scarcity:Specialized metallurgical expertise required to formulate scrap blends that meet ASTM A615 rebar specifications remains concentrated among retiring workforce cohorts in mature recycling markets.
- RCRA hazardous waste determinations:EPA exclusion rulings on spent catalysts and metal-bearing sludges require case-by-case legal review that extends inventory holding periods and complicates just-in-time furnace scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Scrap Metal Market |
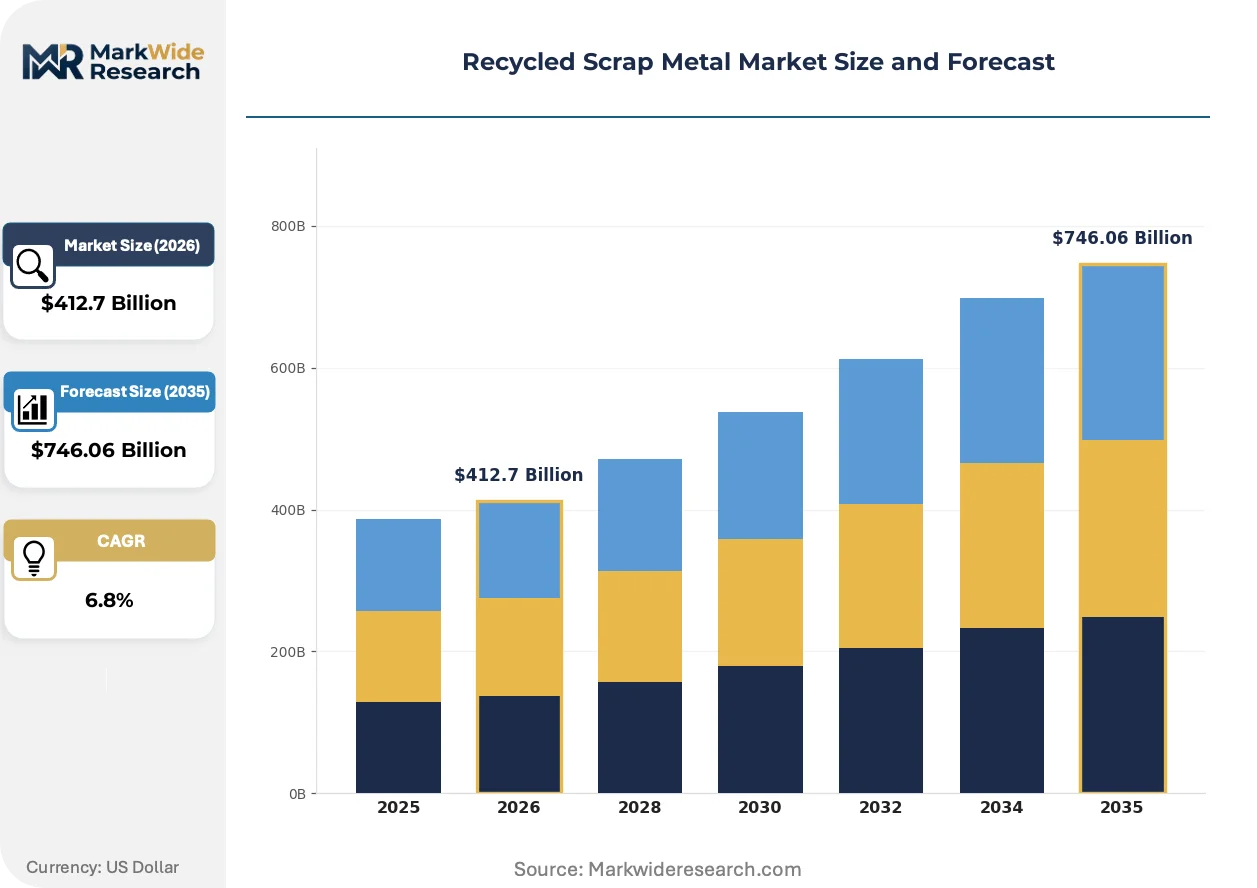
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Copper, Steel, Brass Processing Method: Shredding, Melting, Baling, Shearing End User: Manufacturers, Construction, Automotive, Electronics Market Channel: Direct Sales, Distributors, Auctions, Online Platforms |
| Companies Covered | Sims Limited, Steel Dynamics Inc, Nucor Corporation, Commercial Metals Company, Aurubis AG, European Metal Recycling, Schnitzer Steel Industries Inc, Triple M Metal LP, Tata Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Scrap Metal Market Strategic Shifts
Digital traceability infrastructure and advanced separation physics are converging to transform scrap from a commodity input into a certified, attribute-branded manufacturing feedstock. Processors who master sensor fusion and emissions verification are capturing premium spreads over traditional assay-based competitors.
Sensor-based sorting is hybridizing mechanical processing workflows. X-ray transmission and near-infrared array systems now classify shredded aluminum by alloy series in real time, enabling furnace operators to source 5xxx-series body sheet scrap separately from 3xxx-series brazing stock. Tier-1 automotive suppliers in Germany and the United States are mandating this segregation to maintain crash-performance certification in secondary-content structural components. The technology is compressing blending errors that previously required costly remelt correction.
REACH restrictions on lead and cadmium additives in recycled copper alloys are tightening feedstock acceptance criteria across European manufacturing chains. ECHA substance evaluation dossiers now require smelters to document absence of restricted substances in complex multi-metal scrap feeds, particularly from end-of-life electronics. Copper semis producers in Germany and Italy are responding by screening out cable scrap from unverified demolition sources, redirecting procurement toward construction-site collection with documented installation dates.
Buyer consortiums are consolidating scrap procurement through long-term offtake agreements that embed emissions verification into contract terms. Steel service centers and aluminum rolling mills in the United States are displacing spot-market purchasing with multi-year arrangements tied to specific shredder yard carbon intensity scores. This contractual shift is most visible in automotive supply chains, where OEM sustainability scorecards now weight verified recycled content above price competitiveness in supplier selection algorithms.
Recycled Scrap Metal Market Segmentation
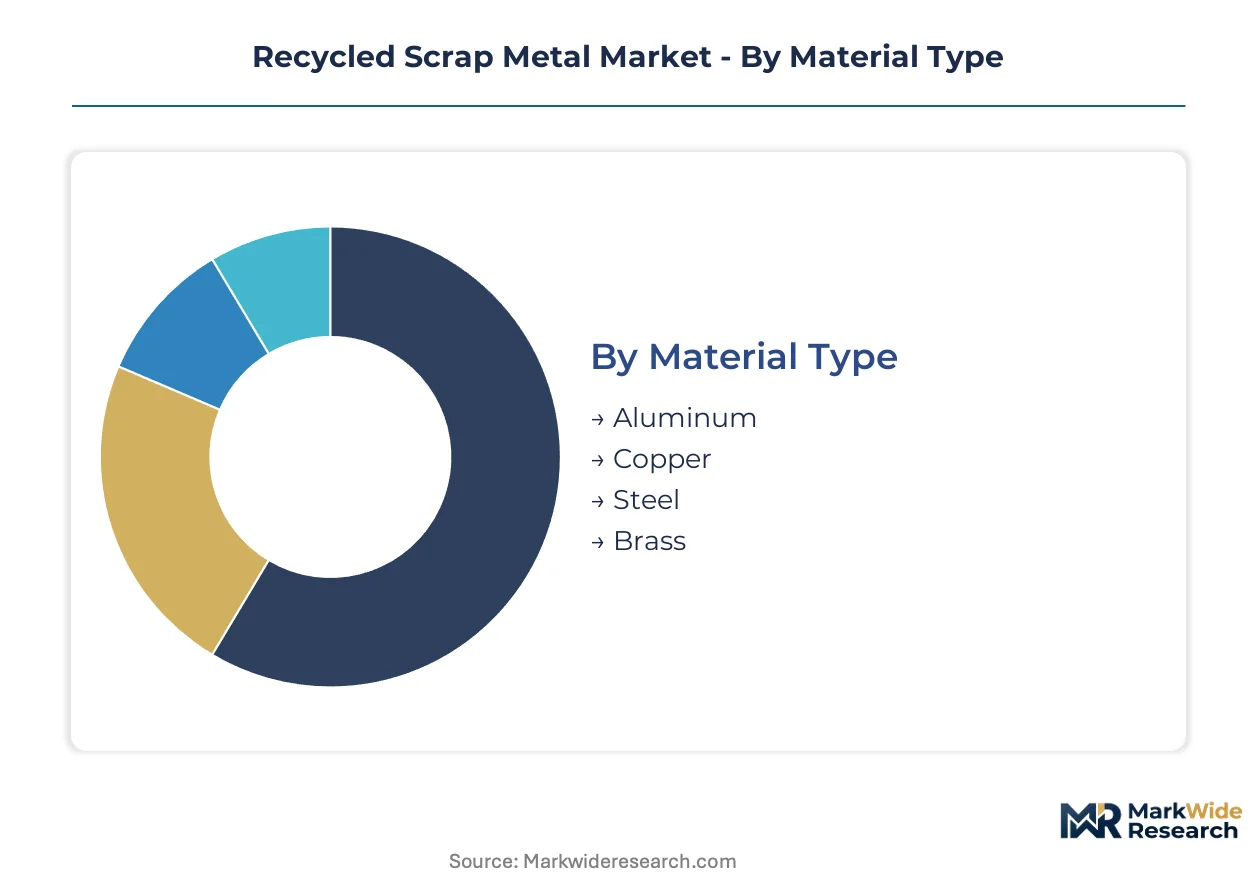
Scrap metal segmentation reveals how material purity, processing intensity, and channel structure determine value capture. Each dimension governs distinct margin pools and competitive requirements for processors and traders.
Material Type:
End-use specifications span crash-rated automotive body sheet to electrical-grade copper cathode, with residual tolerance thresholds dictating sorting investment.
- Steel:Post-industrial and obsolete demolition feeds supply electric arc furnaces with controlled tramp element profiles. Construction rebar and automotive exposed panels concentrate procurement in Germany, China, and the United States as carbon-accounting verification reshapes sourcing criteria.
- Aluminum:Shredded auto scrap and used beverage cans dominate volume flows, with eddy-current separation enabling alloy-series segregation. Body-in-white specifications from Tier-1 automotive suppliers in Germany and the United States mandate closed-loop foundry relationships with documented recycled content.
- Copper:Wire and cable recovery commands premium spreads over mixed non-ferrous fractions, with hydrometallurgical extraction of printed circuit board feeds isolating rare earth elements.
- Brass:Plumbing fixtures and ammunition casings supply lead-free alloy specifications under REACH restrictions, compressing available demolition sources.
The dominant share belongs to Steel, while Aluminum is closing the gap fastest.
Processing Method:
Capital intensity and throughput economics separate commodity preprocessing from value-added refining operations.
- Melting:Electric arc furnace and secondary smelter operations achieve highest throughput economics with sorted heavy scrap, though natural gas price volatility compresses margins during energy benchmark spikes.
- Shredding:Sensor-based separation systems deploy laser-induced breakdown spectroscopy and X-ray transmission for real-time alloy classification, upgrading mixed zorba into furnace-ready grades.
- Baling:Fragmented construction demolition feeds sustain limited scale efficiencies through compression for transport optimization.
- Shearing:Heavy structural scrap from bridge and building demolition requires size reduction for furnace compatibility.
Melting operations capture the dominant value share, though shredding is expanding most quickly through sensor technology deployment.
End User:
Procurement specifications range from commodity-grade construction feedstock to certified automotive structural content with emissions documentation.
- Automotive:OEM sustainability scorecards weight verified recycled content above price in supplier selection, with secondary aluminum body sheet requiring tight residual tolerance control.
- Construction:Structural steel and rebar applications tolerate broader chemistry ranges, though ASTM A615 specifications constrain copper contamination thresholds.
- Manufacturers:General industrial foundries source mixed grades with less stringent segregation requirements than automotive or electronics channels.
- Electronics:Copper semis producers in Germany and Italy screen cable scrap for REACH-restricted substances, redirecting procurement toward construction-site collection with documented installation dates.
Automotive commands premium pricing, while Electronics is gaining share fastest through rare earth recovery integration.
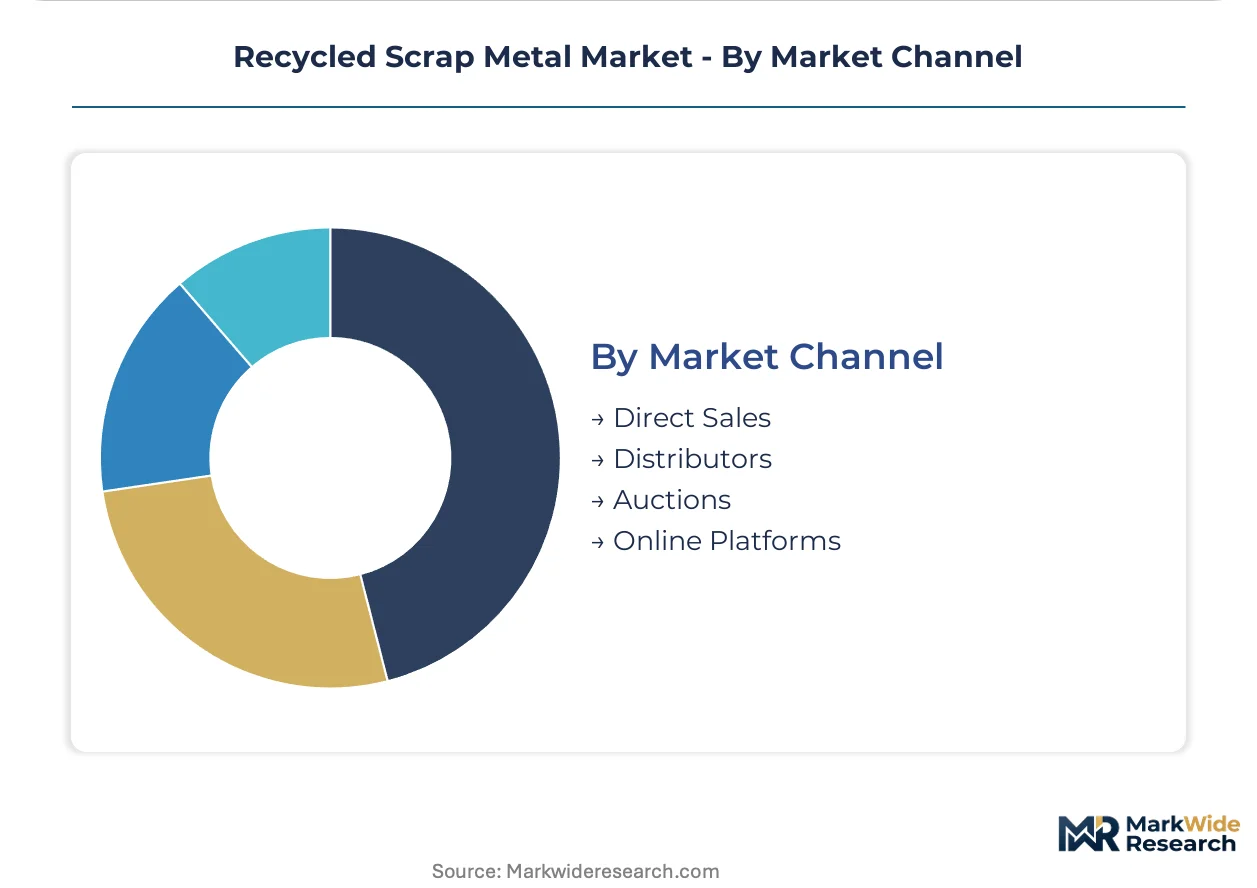
Market Channel:
Relationship structures span spot-market liquidity to multi-year offtake agreements with embedded emissions verification.
- Direct Sales:Long-term contracts between shredder yards and steel service centers or aluminum rolling mills displace spot purchasing, with carbon intensity scores written into pricing terms.
- Distributors:Regional aggregators consolidate fragmented collection volumes for furnace delivery, capturing logistics spreads.
- Auctions:Obsolete industrial equipment and demolition rights trade through competitive bidding for deconstruction timing flexibility.
- Online Platforms:Digital marketplaces for standard grades provide price transparency, though certified automotive feedstock remains relationship-based.
Direct Sales retains the dominant share, while Online Platforms are climbing the fastest through spot-price transparency tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China anchor secondary metal consumption through diverging feedstock strategies. German processors prioritize emissions-verified scrap for automotive closed-loop systems, while Chinese operators concentrate on domestic obsolete stockpiles after import restriction tightening. The United States occupies a middle position, balancing export-oriented collection with growing domestic electric arc furnace demand.
United States
Nucor Corporation and Steel Dynamics anchor electric arc furnace procurement across the Southeast and Midwest. The EPA oversees hazardous waste exclusions under RCRA that determine scrap metal eligibility for furnace feeds. Houston-Galveston and Pittsburgh-Cleveland corridors concentrate shredder yard capacity serving domestic steel service centers.
Germany
Aurubis AG and European Metal Recycling drive copper concentrate substitution through complex multi-metal scrap processing. The EU REACH framework restricts lead and cadmium additives in recycled copper alloys entering manufacturing chains. The Ruhr industrial cluster hosts secondary smelter capacity integrated with automotive OEM sustainability scorecards.
China
Domestic obsolete vehicle and construction demolition feeds replace former import dependence after SAMR enforcement of GB standards. The MIIT dual carbon goals redirect provincial steel capacity toward scrap-based electric arc furnace routes. Yangtze River Delta provinces concentrate shredding and sorting infrastructure for aluminum alloy recovery.
India
Tata Steel scales domestic electric arc furnace capacity under PLI scheme support for import substitution. The BIS standardization of secondary metal grades enables shredded auto scrap acceptance into formal manufacturing channels. Gujarat and Maharashtra industrial corridors attract processing investment for construction rebar and automotive grade production.
Japan
METI circular economy directives mandate end-of-life vehicle recovery rates that sustain domestic shredder feedstock availability. JIS standards on residual element tolerances constrain cross-border scrap trade toward premium-grade segregation. Chubu and Kansai regions concentrate secondary aluminum foundry capacity serving precision automotive components.
Recycled Scrap Metal Market Competitive Environment
Capability concentration sits with sensor-integrated processors who command premium spreads through real-time alloy sorting; scale advantage sits with electric arc furnace operators who anchor procurement through multi-year offtake agreements. The market structures around three tiers: integrated steelmakers with captive scrap networks, independent processors with advanced separation technology, and regional collectors consolidating fragmented demolition feeds. Dominant competitive moves include backward integration into shredding capacity and technology licensing partnerships for emissions verification systems.
Within the integrated processor tier, Sims Limited exemplifies sensor-based separation deployment for non-ferrous fraction capture, while Nucor Corporation anchors North American electric arc furnace networks through deep scrap sourcing relationships. Aurubis AG occupies a position representing copper concentrate substitution through complex multi-metal feed processing. These three entities collectively illustrate the capability-scale tension reshaping procurement contracting toward verified carbon intensity terms.
| Leading Market Players |
|---|
| Sims Limited |
| Steel Dynamics Inc |
| Nucor Corporation |
| Commercial Metals Company |
| Aurubis AG |
| European Metal Recycling |
| Schnitzer Steel Industries Inc |
| Triple M Metal LP |
| Tata Steel |
| Others |
Value Chain & Pricing Dynamics
Electric arc furnace undercapacity in India's western industrial corridors is pulling shredded auto scrap premiums upward while compressing collection margins in saturated North American markets. This utilization divergence rewards processors who can document furnace-ready carbon intensity scores through blockchain-tracked chain-of-custody systems.
Pricing Analysis
Long-term offtake contracts between shredder yards and steel service centers are displacing spot-market liquidity across automotive supply chains. Three-tier pricing structure across emissions-verified premium, assay-standard mid-grade, and unsegregated economy scrap reflects carbon-accounting differentiation. Cost compression in economy-grade demolition feeds is intensifying because China's SAMR enforcement has eliminated lower-grade mixed loads from export portfolios. Tier-1 automotive OEMs exhibit least price sensitivity, while construction rebar mills remain most responsive to spot-market volatility.
Supply Chain Analysis
Contract shredding concentration rests on Sims Limited's sensor-integrated North American network, European Metal Recycling's Ruhr corridor capacity, and Yangtze River Delta provincial operators serving China's domestic obsolete vehicle flows. Raw material dependencies draw from post-consumer auto hulks, construction demolition streams, and industrial manufacturing offcuts. Single-source vulnerability concentrates in hydrometallurgical reagent supply for printed circuit board copper extraction. Distribution runs through direct mill relationships for certified grades, with regional distributors consolidating fragmented construction feeds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-accounting verification is fragmenting procurement into niche certification tiers, creating white-space opportunities for sensor-integrated processors who can document furnace-level emissions intensity.
For Market Incumbents: Harden procurement relationships through backward integration into deconstruction rights for building-integrated material passports. Anchor electric arc furnace offtake with multi-year contracts embedding blockchain-tracked carbon scores to defend against emerging hydrometallurgical copper extraction entrants. For New Entrants and Emerging Players: India's Gujarat and Maharashtra industrial corridors offer underpenetrated shredded auto scrap acceptance into formal BIS-standardized manufacturing channels. Target construction rebar foundries with unverified demolition feeds excluded from automotive closed-loop systems. Pursue technology licensing partnerships for laser-induced breakdown spectroscopy deployment rather than greenfield shredding investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hydrometallurgical copper extraction as sulfuric acid leaching modularizes. Acquisition targets should concentrate on regional collectors with documented installation-date construction scrap and deconstruction rights to structural steel. Watch for SAMR policy relaxation signals as inflection indicators for Chinese import demand recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Based Separation Deployment | Laser-induced breakdown spectroscopy upgrades mixed zorba into furnace-ready specification grades for automotive OEMs. |
| Backward Integration into Deconstruction Rights | Digital twin documentation of structural steel installations secures end-of-life recovery decades ahead of demolition. |
| Blockchain Emissions Verification | Carbon intensity scores written into long-term offtake contracts capture premium spreads over assay-based competitors. |
| Hydrometallurgical Copper Extraction Scale-Up | Sulfuric acid leaching of printed circuit board feeds isolates rare earth elements for battery supply chain integration. |
| Geographic Expansion into India | BIS standardization and PLI scheme support creates import substitution potential for shredded auto scrap processors. |
Study Parameters
Cross-validation between primary interviews with shredder yard operators, electric arc furnace procurement managers, and secondary smelter technical directors anchors the qualitative findings. Secondary validation draws from EPA RCRA exclusion rulings, EU ECHA substance evaluation dossiers, China MIIT dual carbon policy disclosures, and SEC filings from integrated steelmakers. Bottom-up volume modeling triangulates against top-down carbon-accounting premium capture estimates.
Calibration against historical furnace utilization rates and scrap-to-hot-metal yield ratios shapes the projection framework across material type, processing method, and end-user segmentation dimensions. CAGRs derive from regression analysis of carbon border adjustment mechanism implementation timelines and electric arc furnace capacity addition announcements. Forecast inputs incorporate natural gas price volatility scenarios and SAMR import quality enforcement trajectories.
Practitioners should monitor EU Carbon Border Adjustment Mechanism expansion scope, China SAMR GB standard relaxation signals, and electric arc furnace natural gas input cost spikes for early revision triggers. Quarterly review of carbon-accounting premium spreads and shredder yard capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Diamond Market
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Garnet Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Steel Powder Market