
 Zellerite Market | 2026-2036
Zellerite Market Size, Share, and Industry Trends Forecast 2026-2036
Zellerite Market Analysis
REACH compliance is pivoting the cost-of-entry calculus for European suppliers, forcing reformulation investments that smaller producers cannot absorb. Albemarle Corporation leverages its integrated supply chain to sustain compliance without margin erosion. Zeolyst International anchors its position through specialized molecular sieve production for petrochemical clients. Clariant competes by dominating the high-purity pharmaceutical-grade segment across Western European markets.
Zellerite denotes a naturally occurring zeolite mineral composed primarily of hydrated aluminosilicates with a characteristic fibrous morphology and cation-exchange capacity typically exceeding 200 meq per 100 grams. The mineral serves industrial markets as an adsorbent, ion-exchange medium, and catalyst support in processes ranging from water softening to hydrocarbon cracking. Powder formulations command the widest addressable base across chemical manufacturing and agriculture, while crystal grades concentrate margin pools in electronics and pharmaceutical applications where trace-metal specifications are most stringent. Granule demand is accelerating in soil amendment uses where broadcast application equipment requires controlled particle size distribution.
EPA regulations under the Toxic Substances Control Act govern zeolite import and processing thresholds in the United States, while ECHA enforces REACH registration and hazard communication standards across European supply chains. The EU F-Gas Regulation indirectly shapes demand by restricting synthetic refrigerants where natural zeolite adsorbents offer compliant alternatives. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these compound classification shifts could redirect filtration and remediation spending toward certified zellerite grades.
Market Dynamics
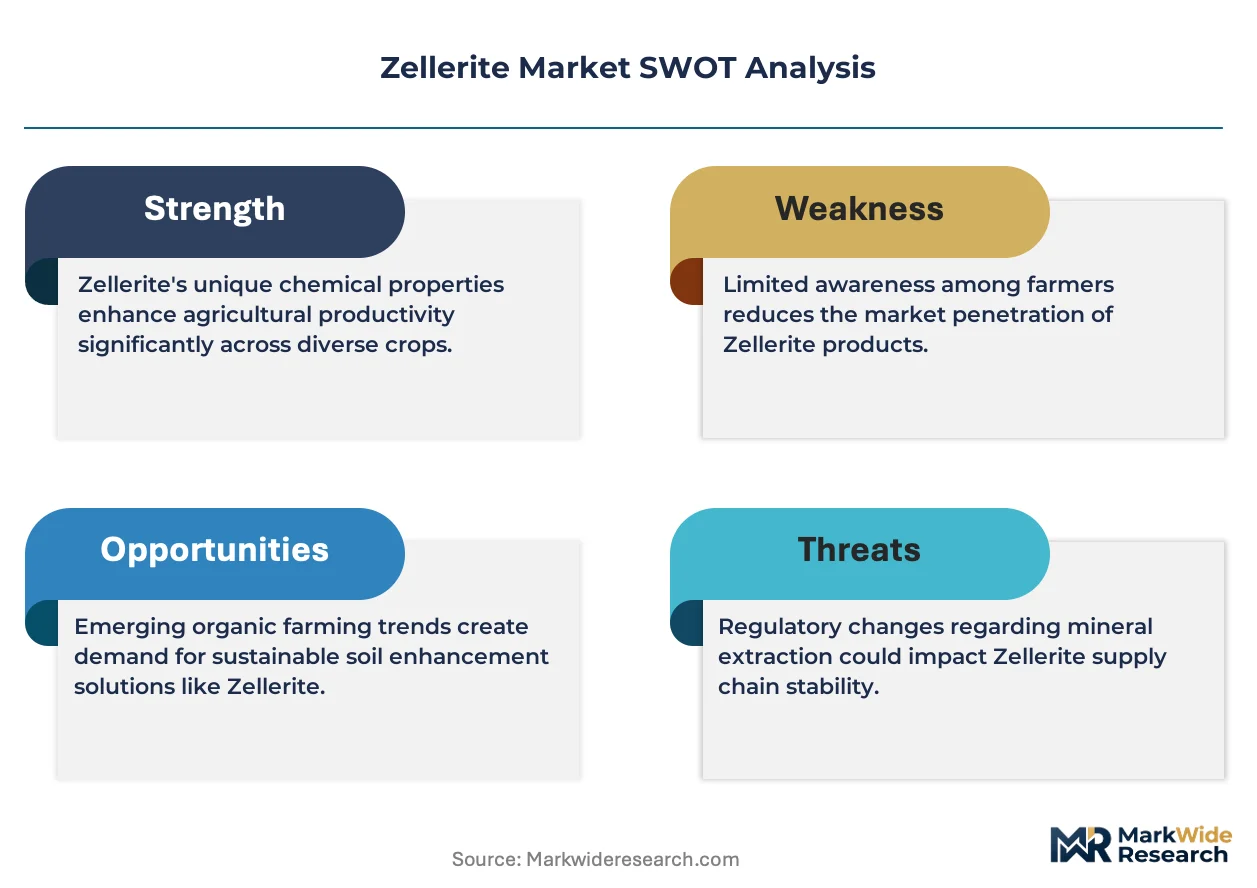
REACH compliance is tightening purity thresholds for zeolite-based inputs across European supply chains, forcing reformulation investments that reshape competitive economics and concentrate market share among integrated producers.
Growth Catalysts
- Agricultural soil amendment substitution:Farmers in Germany seek alternatives to synthetic fertilizers, expanding addressable demand for certified zellerite grades in precision agriculture applications.
- EU F-Gas Regulation:Restrictions on synthetic refrigerants redirect filtration spending toward natural zeolite adsorbents in HVAC and industrial cooling systems.
- Petrochemical catalysis clusters:Industrial concentration in Germany's Rhineland region sustains specialized molecular sieve demand for hydrocarbon cracking processes.
Market Restraints
- Input cost volatility:Energy-intensive calcination processes expose producers to natural gas price swings, compressing margins during supply shocks.
- Supply concentration risk:Premium crystal-grade production concentrates among a limited set of European processors with captive mineral deposits.
- Substitution threat:Synthetic aluminosilicate gels compete in water softening applications where cation-exchange capacity specifications are less stringent.
Strategic Opportunities
- Underpenetrated pharmaceutical-grade segment:Trace-metal specification gaps in Eastern European markets create white space for certified producers meeting EMA standards.
- Remediation application expansion:Per- and polyfluoroalkyl substance restrictions redirect environmental filtration spending toward certified zellerite grades in groundwater treatment.
- Technology convergence:Integration of zeolite adsorbents with membrane separation systems opens hybrid process designs in industrial water recycling.
Industry Challenges
- Certification timeline compression:REACH registration renewal cycles demand accelerated toxicological data generation, straining smaller producers' regulatory affairs capacity.
- Capex intensity for purity upgrades:Crystallization circuit investments required for electronics-grade specifications lock up capital for extended payback periods.
- Skill scarcity in mineral processing:Specialized expertise in cation-exchange optimization and particle size engineering concentrates among aging workforce cohorts in traditional mining regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zellerite Market |
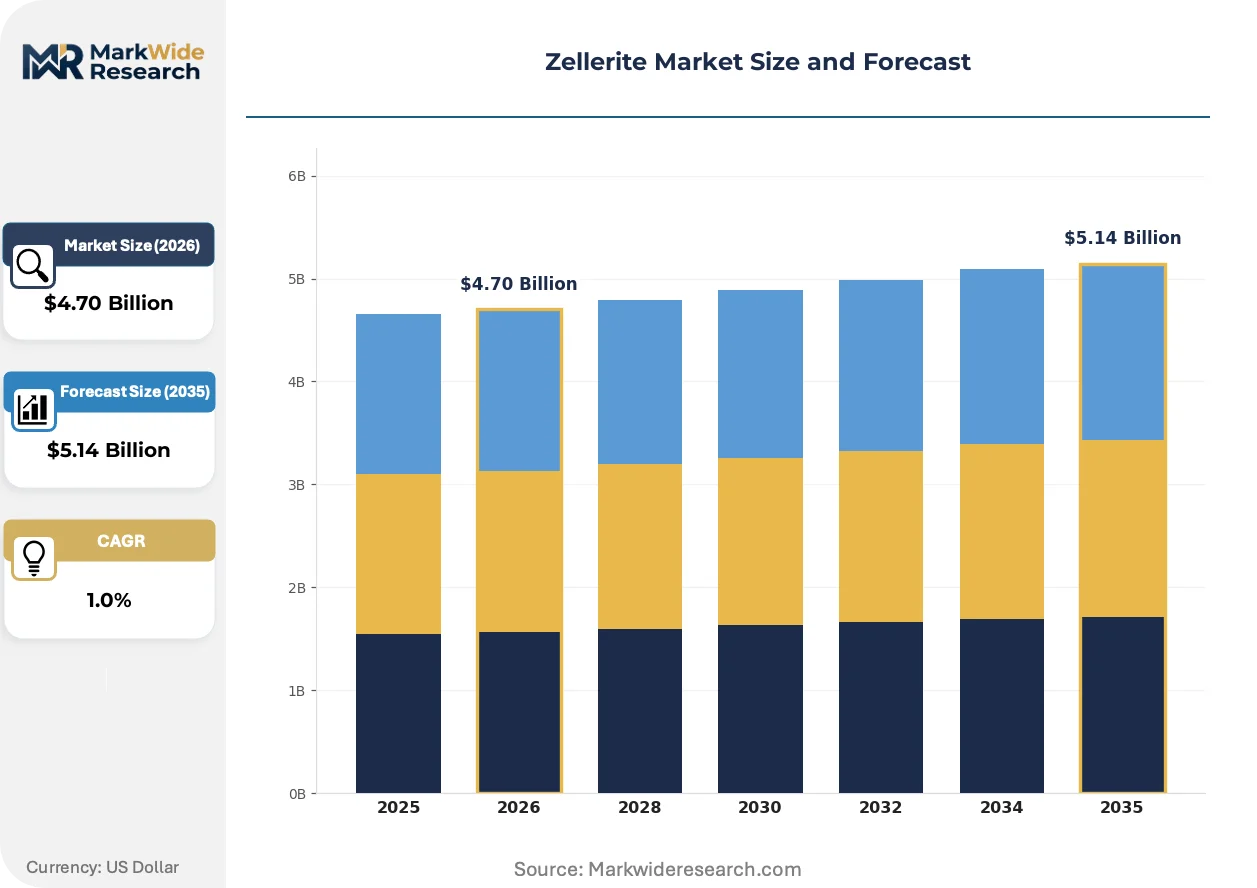
| Market Size in 2026 | $4.70 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Crystals, Tablets Application: Chemical Manufacturing, Agriculture, Pharmaceuticals, Electronics End User: Manufacturers, Distributors, Researchers, Consumers Distribution Channel: Online, Direct Sales, Wholesalers, Retailers |
| Companies Covered | Lenntech BV, Albemarle Corporation, W.R. Grace & Co-Conn, Bear River Zeolite, Clariant, Zeolyst International, Gordes Zeolite, IDA-ORE, Zeocem Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zellerite Market Emerging Trajectories
Zeolite processing is pivoting toward higher-purity fractionation methods as end-use specifications tighten across pharmaceutical and electronics verticals, compressing acceptable impurity thresholds and rewarding technical differentiation.
Surface-modified zellerite variants with enhanced hydrophobicity are overtaking conventional uncoated grades in moisture-sensitive catalytic applications. Petrochemical processors in Germany and the Netherlands adopt these materials at accelerating rates to extend catalyst bed lifetimes. The shift is overtaking legacy ion-exchange resins in selective adsorption processes where thermal regeneration cycles favor mineral stability.
ECHA's 2023 REACH dossier updates for aluminosilicates impose new reproductive toxicity testing obligations on importers and downstream users. Industrial consequences include extended registration timelines and elevated compliance costs for non-EU suppliers seeking European market access. Powder-grade formulations face the most acute pressure, as agricultural and chemical manufacturing applications lack the margin depth to absorb full testing burdens without price restructuring.
Specification-driven procurement is consolidating buyer decision criteria around certified purity tiers rather than commodity pricing. Distributors serving agricultural end-users in France and Spain now bundle application engineering support with material supply, displacing transactional spot purchasing. This pattern is most visible in soil amendment segments where broadcast equipment compatibility and controlled-release performance dominate farmer selection criteria.
Zellerite Market Segmentation
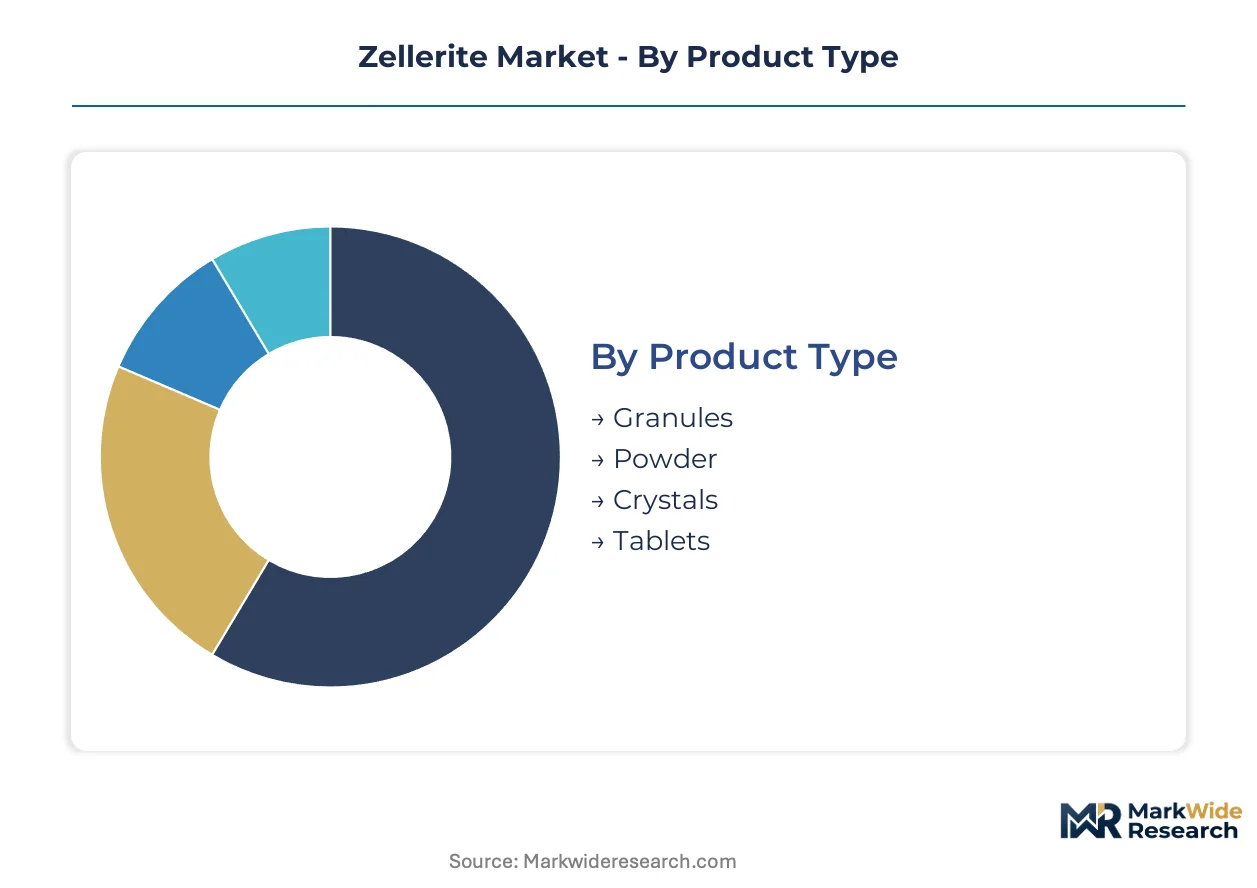
Zellerite grades diverge sharply in margin structure and regulatory burden. Powder formulations serve high-volume commodity applications, while crystal grades extract premiums through trace-metal certification.
Product Type:
Buyers differentiate primarily by particle engineering requirements and downstream processing compatibility.
- Granules:Engineered particle size distribution (1-4mm range) enables mechanical compatibility with broadcast spreaders and fixed-bed reactors. Soil amendment demand concentrates in Germany's precision agriculture clusters, where equipment calibration standards favor uniform granule geometry.
- Powder:Finely milled aluminosilicate with surface area exceeding 300 m²/g serves chemical manufacturing and water treatment. REACH registration costs burden this segment most acutely, as agricultural and industrial buyers lack margin depth to absorb compliance-driven price restructuring.
- Crystals:High-purity fractionation for electronics and pharmaceutical verticals.
- Tablets:Compacted forms for controlled-release soil amendment and specialized catalytic applications.
Volume sits with Powder; growth tilts toward Crystals.
Application:
End-use specifications determine purity thresholds and certification requirements across buyer groups.
- Chemical Manufacturing:Ion-exchange resins and molecular sieves for petrochemical cracking and water softening. Rhineland industrial clusters sustain specialized demand for surface-modified variants with enhanced hydrophobicity.
- Agriculture:Soil amendment substitution for synthetic fertilizers. German farmers drive granule specification tightening as precision agriculture equipment requires calibrated particle distribution.
- Pharmaceuticals:Trace-metal specifications below 10 ppm for excipient and active ingredient applications.
- Electronics:Ultra-high purity for semiconductor manufacturing and battery electrolyte stabilization.
Chemical Manufacturing holds installed base; Agriculture climbs the fastest.
End User:
Procurement sophistication varies by technical capability and volume scale.
- Manufacturers:Integrated chemical and materials producers with captive formulation engineering. These buyers negotiate long-term supply agreements tied to REACH compliance certification and batch consistency guarantees.
- Distributors:Channel intermediaries bundling technical application support with material supply in French and Spanish agricultural markets.
- Researchers:Academic and industrial R&D buyers requiring small-batch specialty grades.
- Consumers:Direct purchasers in home water treatment and garden amendment segments.
Manufacturers dominate volume; Distributors gain share fastest.
Distribution Channel:
Channel selection reflects buyer technical confidence and order fragmentation.
- Online:E-commerce platforms serving small-scale agricultural buyers and consumer segments. Specification transparency limitations restrict penetration in pharmaceutical and electronics grades.
- Direct Sales:Producer-to-manufacturer relationships for high-volume chemical and petrochemical accounts. Technical service integration locks in multi-year contracts.
- Wholesalers:Bulk aggregation for agricultural cooperatives and regional chemical distributors.
- Retailers:Garden center and farm supply channels for consumer soil amendment products.
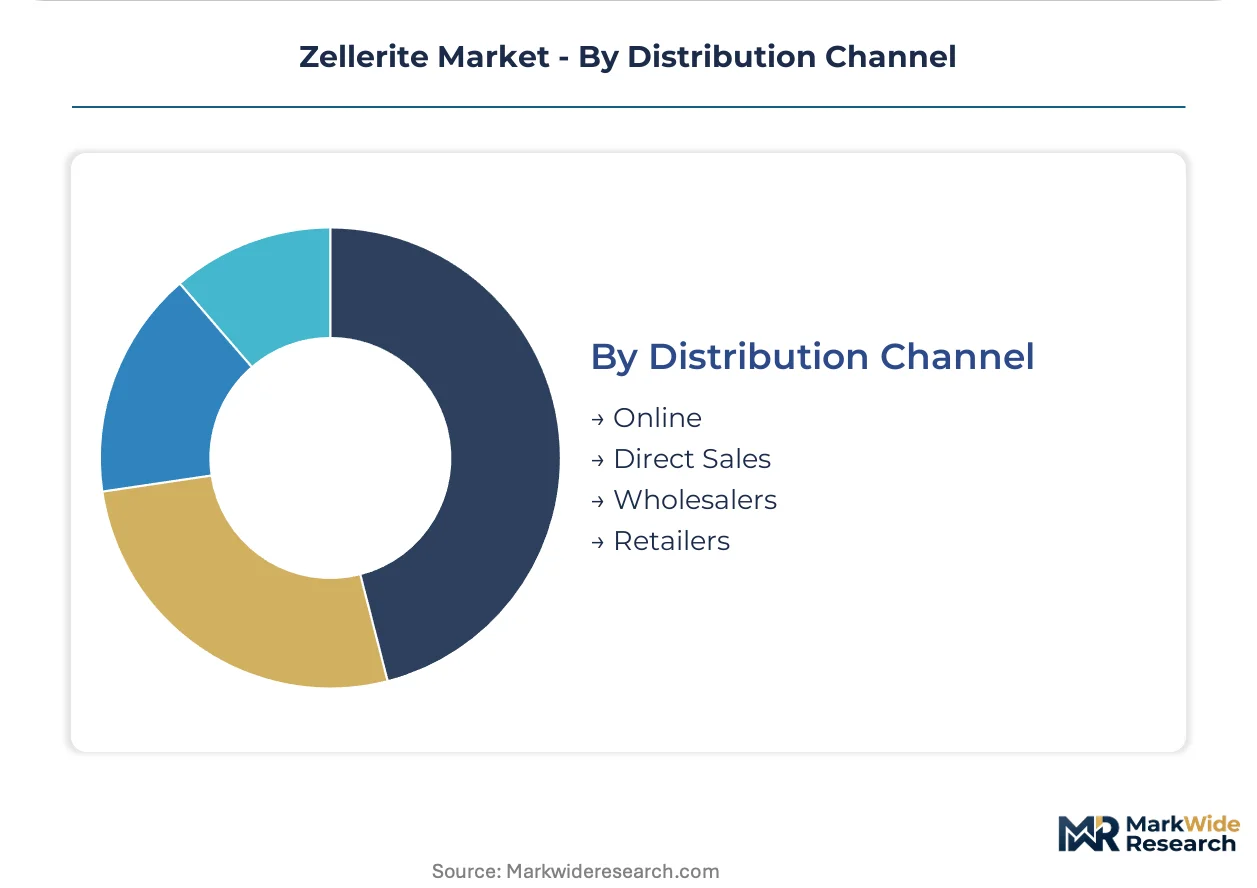
Direct Sales anchor volume; Online expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland chemical corridor operates as the dominant concentration zone for zellerite processing, with precision agriculture clusters in Lower Saxony and industrial catalysis hubs generating specialized demand that shapes European supply chain configuration.
Germany
Agricultural soil amendment demand concentrates in Lower Saxony's precision farming belt, while petrochemical catalysis clusters in North Rhine-Westphalia sustain molecular sieve consumption. ECHA enforces REACH registration renewals with tightened reproductive toxicity testing obligations. The Rhineland industrial corridor anchors specialized production for surface-modified variants with enhanced hydrophobicity.
United States
Water treatment and home soil amendment segments drive powder-grade consumption across Midwest agricultural states. EPA regulations under the Toxic Substances Control Act govern import thresholds and processing facility compliance. Wyoming and Idaho host natural zeolite mining operations supplying domestic calcination facilities.
China
Synthetic aluminosilicate gel producers compete aggressively in water softening applications, pressuring natural zellerite margins in cost-sensitive industrial segments. MIIT oversees industrial mineral processing standards under national GB frameworks. Shandong Province concentrates domestic zeolite mining and primary processing capacity.
France
Distributor-led agricultural markets in the Paris Basin and southwestern grain regions bundle application engineering with material supply. ANSM monitors pharmaceutical-grade excipient specifications for trace-metal thresholds. Lyon and Marseille serve as logistics hubs for Mediterranean-facing export channels.
Japan
Electronics-grade crystal demand concentrates in Kyushu's semiconductor manufacturing corridor and Kanto's battery supply chain. METI administers JIS standards for high-purity mineral inputs in advanced materials. Osaka-based trading houses coordinate procurement for domestic chemical manufacturers.
Zellerite Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with consolidated share among integrated producers coexisting alongside fragmented regional processors. Albemarle Corporation and Clariant anchor the upper tier through compliance-integrated supply chains, while mid-cap specialists concentrate in agricultural-grade segments. Strategic moves center on backward integration into captive mineral deposits and technology licensing partnerships for surface-modified variants.
Among Netherlands-based water technology specialists, Lenntech BV represents the application-engineering archetype, while Zeolyst International exemplifies petrochemical-focused molecular sieve production. Bear River Zeolite and Gordes Zeolite occupy positions within the regional mining-and-processing tier serving agricultural end-users.
| Leading Market Players |
|---|
| Lenntech BV |
| Albemarle Corporation |
| W.R. Grace & Co-Conn |
| Bear River Zeolite |
| Clariant |
| Zeolyst International |
| Gordes Zeolite |
| IDA-ORE |
| Zeocem Ltd |
| Others |
Supply Flow & Price Mechanics
Natural gas price indices cascade through zellerite supply chains, calcination energy costs separating integrated producers with captive mineral deposits from toll-processors exposed to spot fuel markets. Powder-grade agricultural formulations absorb the most acute cost volatility, while crystal-grade electronics and pharmaceutical tiers command pricing premiums through certification-locked supply agreements.
Pricing Analysis
Short lead-time premiums distinguish contract manufacturing arrangements from spot inventory transactions in European chemical manufacturing channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by trace-metal certification thresholds, with EMA-grade pharmaceutical specifications extracting the widest spreads. Cost compression in powder-grade agricultural tiers is intensifying because REACH registration renewal burdens concentrate on lower-margin segments. Small-scale farmers in France and Spain exhibit the highest price sensitivity, while petrochemical processors in Germany's Rhineland negotiate multi-year offtake agreements with batch consistency guarantees.
Supply Chain Analysis
Regenerated catalyst streams and spent molecular sieve returns flow back to specialized reprocessing facilities in Germany and the Netherlands, closing material loops for surface-modified variants. Primary supply concentrates in Germany, the United States, and China, with Wyoming and Idaho deposits feeding domestic calcination capacity while Shandong Province anchors Chinese synthetic aluminosilicate competition. Raw material flows draw from energy-intensive mining operations, natural gas-dependent thermal processing, and specialized crystallization circuit chemicals. Single-source vulnerability concentrates in premium crystal-grade production, where European processors with captive deposits control electronics and pharmaceutical certification pipelines. Distribution runs through direct producer-to-manufacturer relationships for high-volume chemical accounts, supplemented by distributor-led technical bundling in agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive mineral deposits has become the defining competitive race in zellerite processing, with energy cost control and certification pipeline ownership determining margin sustainability across REACH-regulated European markets.
For Market Incumbents: Anticipate synthetic aluminosilicate gel substitution threats in water softening applications by accelerating surface-modified variant development for moisture-sensitive catalytic uses. Secure long-term natural gas supply agreements or renewable thermal energy partnerships to defend calcination cost positions against spot fuel volatility. Prioritize crystallization circuit capacity additions in Germany's Rhineland corridor to lock in electronics-grade certification pipelines before ECHA reproductive toxicity testing timelines compress further. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for natural zeolite adsorbent penetration in HVAC and industrial cooling system retrofits, where synthetic refrigerant restrictions redirect filtration spending. Target underpenetrated pharmaceutical-grade segments in Eastern European markets, where trace-metal specification gaps create white space for EMA-certified producers. Lead with application engineering partnerships rather than commodity supply, bundling broadcast equipment calibration support with granule formulations to displace transactional distributors in French agricultural cooperatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap agricultural-grade processors with established distributor relationships in Spain and Italy, where REACH compliance costs are forcing smaller competitors toward exit. Long-term viability hinges on securing captive mineral deposits or exclusive toll-processing agreements with energy-cost-advantaged facilities. Monitor ECHA registration renewal timelines and natural gas futures curves as early signals of margin compression inflection points that would trigger consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mineral Deposits | Wyoming and Idaho deposit ownership eliminates toll-processing margins and secures supply certainty for calcination facilities. |
| REACH Certification Pipeline Investment | ECHA reproductive toxicity testing completion locks in European market access before smaller competitors face renewal deadlines. |
| Surface-Modified Variant Development | Hydrophobicity-enhanced formulations extend catalyst bed lifetimes for petrochemical processors in Germany's Rhineland. |
| Application Engineering Partnership | Technical bundling with broadcast equipment calibration displaces spot purchasing in French and Spanish agricultural markets. |
| Long-term Supply Agreement Structuring | Multi-year offtake contracts with batch consistency guarantees secure volume commitments from Rhineland chemical manufacturers. |
Methodological Framework
Document review covered ECHA REACH registration dossiers, EPA Toxic Substances Control Act filings, and MIIT GB standard frameworks, complemented by interviews with plant managers at European calcination facilities, procurement leads at German petrochemical clusters, and distribution channel partners in French agricultural markets. Secondary validation drew from customs and trade flow databases, ACC and Cefic industrial mineral reports, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up segment sizing triangulated against top-down market envelope estimates from production capacity and consumption intensity modeling.
Cross-referencing historical price series against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry vertical, particle engineering specification, and regional regulatory cluster. CAGRs derived from intensity-of-use coefficients applied to downstream industry output forecasts, with petrochemical cracking capacity expansion and precision agriculture equipment penetration serving as primary demand drivers.
The model assumes a particular technology adoption path for surface-modified zellerite variants; alternative pathways for synthetic aluminosilicate gel substitution would alter the outlook for natural zeolite demand in cost-sensitive water treatment segments. Forecasts reflect assumptions regarding REACH registration renewal timelines, natural gas price normalization, and EMA pharmaceutical-grade certification adoption rates. Practitioners should monitor ECHA dossier update schedules, F-Gas Regulation enforcement intensity, and per- and polyfluoroalkyl substance restriction expansion for early signals of demand redirection toward certified zellerite grades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Selenium Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Bauxite Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market