
 Moissanite Market | 2026-2036
Moissanite Market Size, Share, and Industry Trends Forecast 2026-2036
Moissanite Market Analysis
The premium moissanite tier is consolidating around colorless DEF-grade stones with certificates, while commodity-grade near-colorless goods face margin compression from Chinese synthetics. Charles & Colvard leverages its patent legacy and North American brand recognition to sustain price premiums in bridal channels. Stars Gem anchors global rough supply through Wuzhou's cutting infrastructure. Harro Gem differentiates via precision-cut specialty shapes that command designer loyalty.
Moissanite is silicon carbide (SiC) crystallized through chemical vapor deposition or high-pressure thermal growth, yielding a gemstone with refractive index 2.65-2.69 and hardness 9.25 on the Mohs scale that serves as a diamond alternative in fine jewelry. Loose stones and finished jewelry represent the dominant product categories, with loose stones capturing manufacturing margin pools in India and Thailand while jewelry commands retail markup in Western markets. Engagement rings and wedding bands anchor application demand, though fashion jewelry shows faster growth as younger consumers prioritize ethical sourcing narratives over traditional gem hierarchies.
The FTC's Jewelry Guides mandate clear disclosure of lab-created origin, while India's BIS certification requirements for precious metals and gemstones shape export compliance costs for domestic manufacturers. China's SAMR enforces GB standards on synthetic gem labeling that affect cross-border e-commerce fulfillment. Stakeholders must monitor evolving disclosure regimes and rough supply concentration in Guangxi province to anticipate margin shifts across the value chain.
Market Dynamics
The FTC's tightened Jewelry Guides disclosure requirements are forcing a structural recalibration of marketing claims across the moissanite value chain, compressing margins for sellers relying on ambiguous terminology while rewarding certified transparent origin documentation.
Growth Catalysts
- Ethical sourcing narratives:Millennial and Gen-Z bridal buyers prioritize lab-created gemstone provenance over mined diamond hierarchies, pulling demand toward documented synthetic supply chains.
- REACH compliance alignment:European jewelry retailers increasingly specify silicon carbide with full material safety documentation, creating procurement preference for certified producers.
- Wuzhou cutting infrastructure:China's concentrated gem processing capacity enables rapid scaling of precision-cut moissanite at competitive unit economics.
Market Restraints
- Silicon carbide feedstock volatility:Semiconductor industry competition for high-purity SiC wafers constrains gem-grade rough availability and elevates input costs.
- Guangxi province concentration:Over 70% of synthetic moissanite rough production clusters in a single Chinese region, creating geopolitical and logistics vulnerability.
- Diamond price compression:Natural and lab-grown diamond price erosion narrows the affordability gap that historically drove moissanite substitution.
Strategic Opportunities
- India domestic bridal expansion:Rising middle-class disposable income and westernized wedding customs create underpenetrated demand for affordable engagement alternatives.
- Men's jewelry line extensions:Cufflinks, tie bars, and signet rings represent emerging application categories with minimal competitive saturation.
- SAMR e-commerce labeling clarity:China's strengthened cross-border synthetic gem disclosure standards reduce consumer confusion and accelerate online conversion rates.
Industry Challenges
- Gemological certification bottlenecks:Third-party laboratory capacity constraints delay DEF-grade documentation timelines, slowing premium inventory velocity.
- CVD reactor capex intensity:High-pressure thermal growth and chemical vapor deposition equipment requires substantial capital deployment with extended depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moissanite Market |
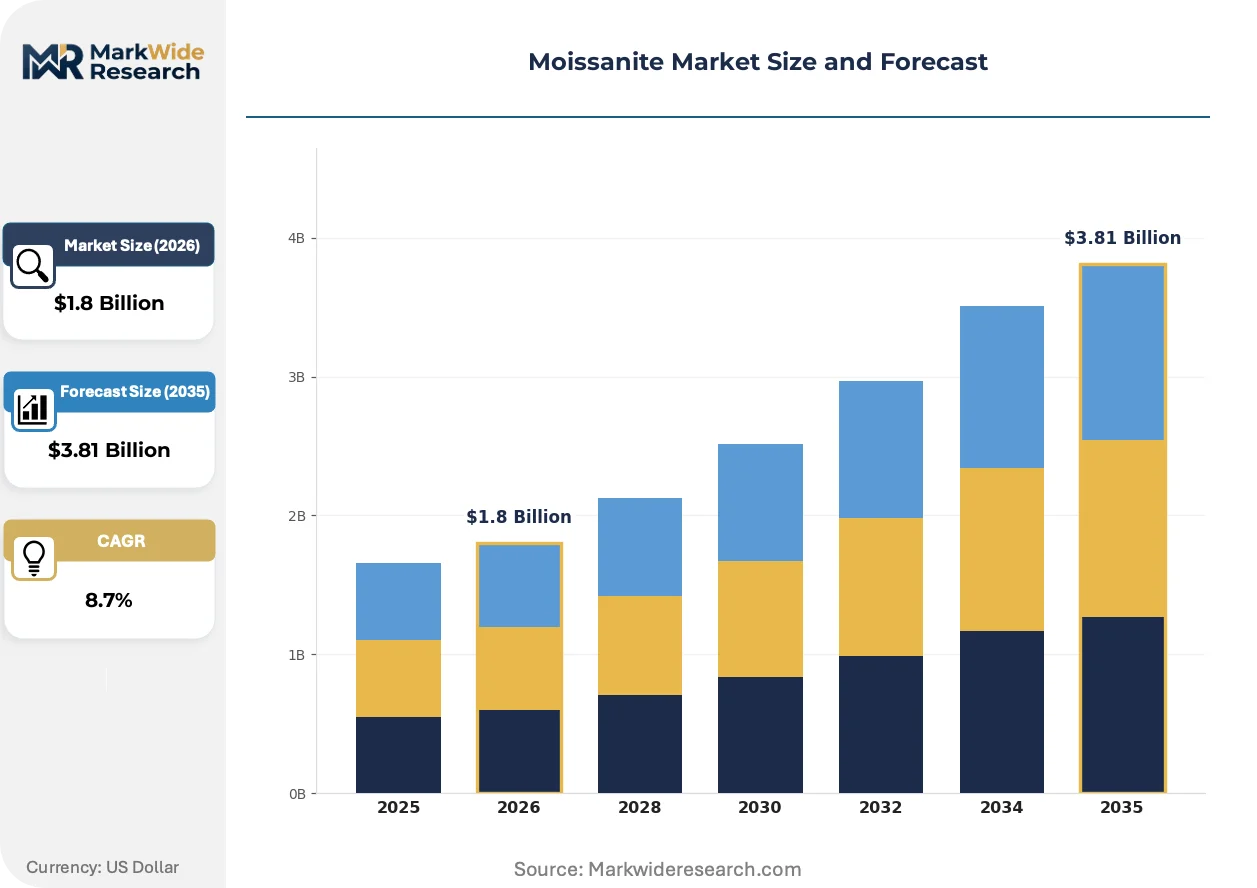
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
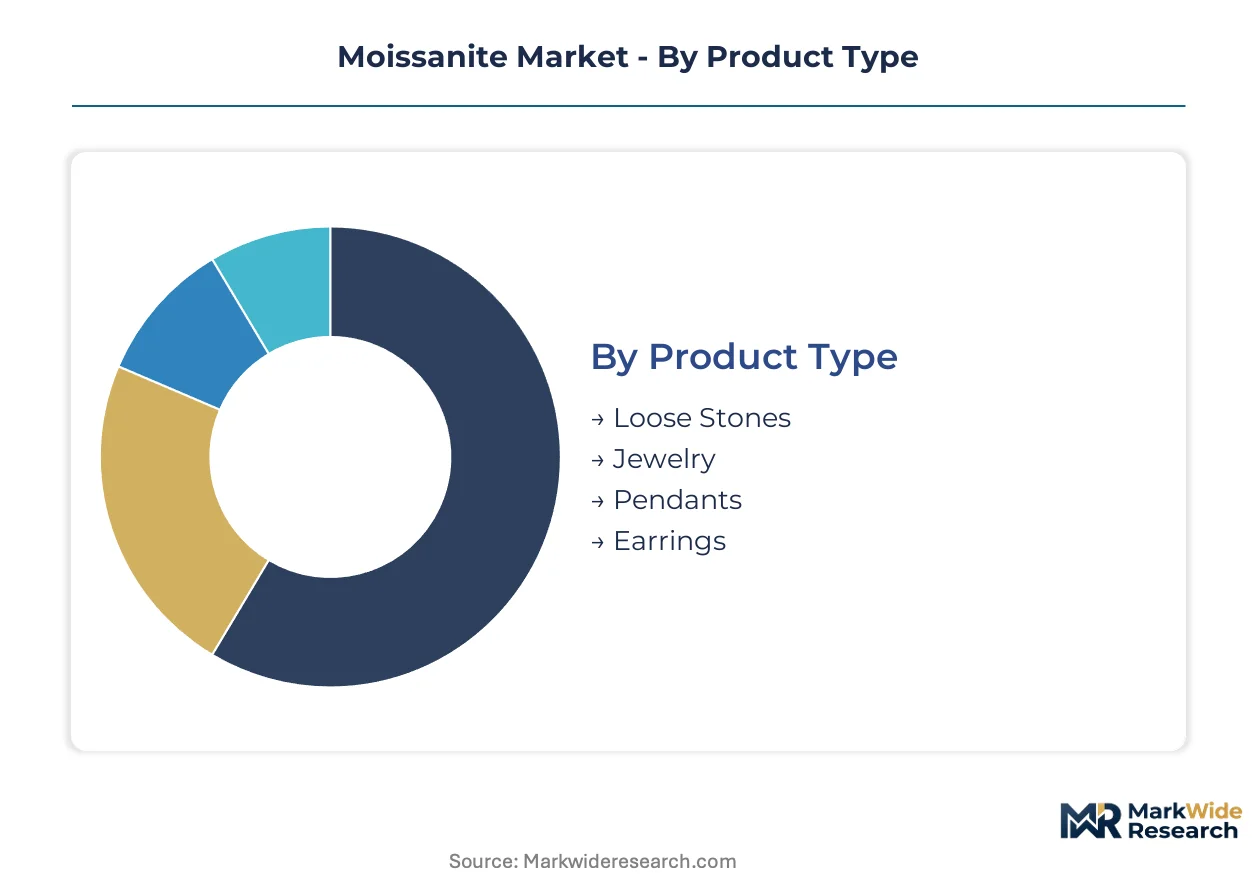
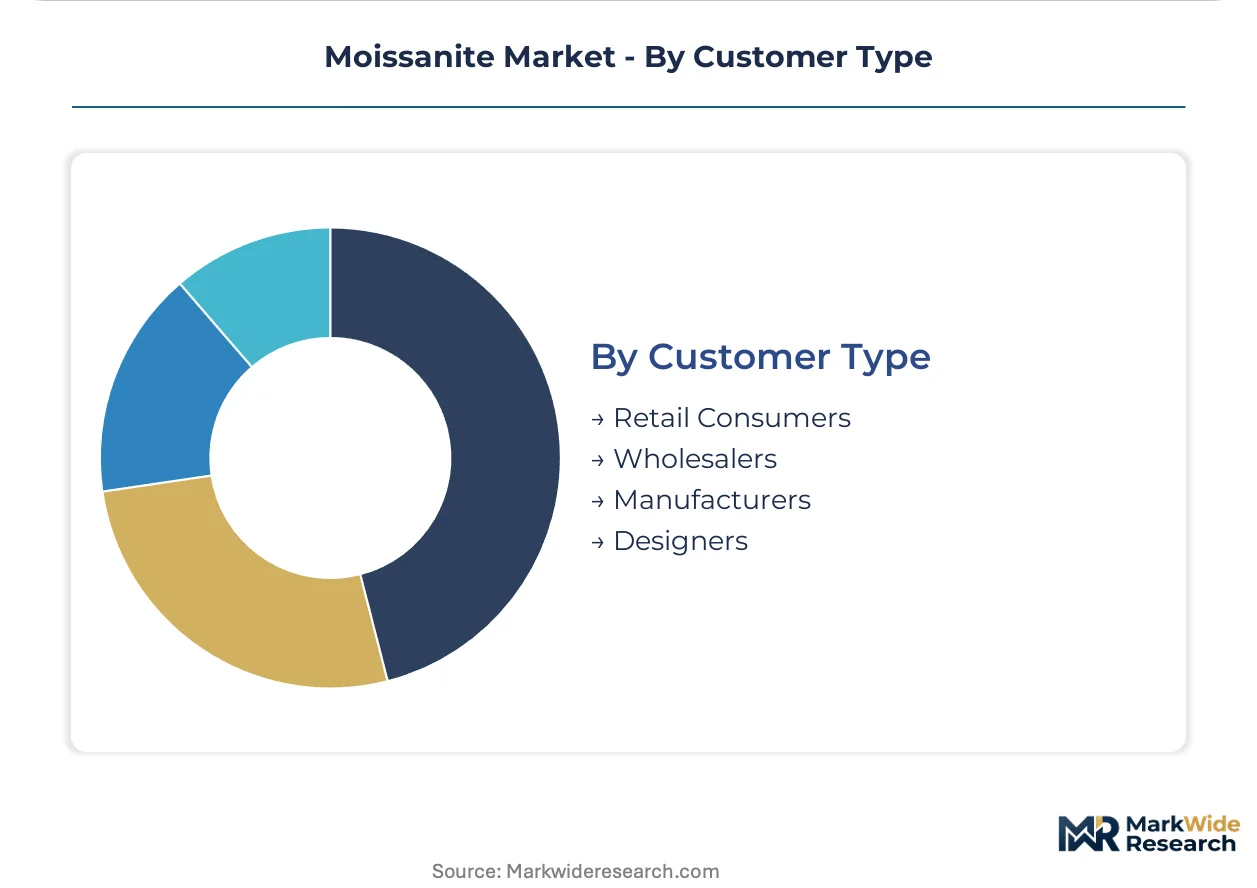
| Segmentation | Product Type: Loose Stones, Jewelry, Pendants, Earrings Application: Engagement Rings, Fashion Jewelry, Wedding Bands, Decorative Use Distribution Channel: Online Retail, Jewelry Stores, Specialty Shops, Auctions Customer Type: Retail Consumers, Wholesalers, Manufacturers, Designers |
| Companies Covered | HRB Exports, Stars Gem, Charles & Colvard, Unimoss, Wuzhou Changsheng Gems, Moissanite International, Viktor Kämmerling, Harro Gem, Amora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moissanite Market Emerging Trajectories
Moissanite production and distribution are undergoing parallel transformation as manufacturing technology matures and retail channels fragment. Three convergent developments are redefining competitive positioning across the value chain.
Chemical vapor deposition is absorbing market share from legacy thermal growth methods by yielding larger, more consistent colorless crystals with fewer inclusions. Bridal manufacturers in the United States and Canada are accelerating CVD procurement to meet certification-grade inventory requirements. This technology transition is compressing margins for producers unable to fund reactor upgrades or secure qualified technical talent.
The FTC's 2023 Jewelry Guides revision mandates explicit lab-created disclosure in all gemstone marketing, eliminating "mined-free" and similar ambiguous terminology. Retailers now face civil penalty exposure for non-compliance, forcing wholesale contract renegotiations with upstream suppliers. Finished jewelry sellers with established transparent sourcing protocols are capturing shelf space from competitors requiring operational overhauls.
Direct-to-consumer digital channels are displacing traditional bridal retail intermediaries as younger buyers complete purchase journeys via Instagram and TikTok discovery. Independent designers and vertically integrated brands are building follower bases that convert without wholesale markup. This channel migration is most visible in United States metropolitan markets where showroom traffic has declined substantially while virtual try-on technology adoption accelerates.
Moissanite Market Segmentation
Moissanite market segmentation reveals divergent margin pools across the value chain, with rough manufacturing concentrated in China's cutting clusters while finished jewelry commands retail premiums in Western bridal channels. Understanding these segment boundaries enables stakeholders to align capital deployment with the highest-return positions.
Product Type:
Volume concentrates in commodity-grade rough and calibrated melee, while premium margin capture depends on certified colorless solitaires with documented provenance.
- Loose Stones:Silicon carbide crystals undergo precision cutting in Wuzhou and Surat facilities to achieve DEF-grade colorless certification. Demand from North American bridal manufacturers drives procurement of 1-carat-plus solitaires with full gemological documentation. Semiconductor industry competition for high-purity SiC feedstock constrains rough availability.
- Jewelry:Finished bridal pieces integrate moissanite into 14K and 18K gold mountings with FTC-compliant lab-created disclosure. United States retailers capture markup multiples through direct-to-consumer digital channels and showroom consultation. Margin compression from lab-grown diamond substitution pressures entry-level price points.
- Pendants:Single-stone and cluster configurations target fashion-oriented buyers seeking ethical gemstone narratives without bridal purchase commitment. China and India manufacturing bases supply silver and gold vermeil mountings at accessible price tiers.
- Earrings:Stud and drop designs utilize matched pairs of calibrated stones for symmetry-dependent visual performance. European REACH compliance requirements shape material safety documentation for base metal and precious metal mountings.
Mature deployment sits with loose stones. Newer deployment is concentrated in finished jewelry with integrated origin storytelling.
Application:
Bridal occasions anchor revenue stability, while fashion-forward positioning enables faster volume expansion among younger demographic cohorts.
- Engagement Rings:Solitaire and halo settings dominate as primary diamond alternatives in United States and Canadian bridal markets. Charles & Colvard's patent-derived brand recognition sustains price premiums against commodity-grade competitors. FTC disclosure mandates eliminate ambiguous marketing terminology.
- Fashion Jewelry:Stackable rings, cocktail pieces, and trend-responsive designs target Gen-Z and millennial buyers prioritizing ethical sourcing over traditional gem hierarchies. Social media discovery via Instagram and TikTok accelerates purchase conversion without wholesale intermediaries.
- Wedding Bands:Eternity and channel-set configurations utilize smaller calibrated stones for continuous sparkle profiles. India and Thailand manufacturing clusters specialize in volume production for Western retail distribution.
- Decorative Use:Non-wearable applications include collectible objets and interior design accents leveraging moissanite's optical properties. Limited commercial scale constrains dedicated supply chain development.
Engagement rings represent the most established revenue base. Fashion jewelry is expanding most quickly as channel migration disrupts traditional bridal retail.
Distribution Channel:
Digital direct-to-consumer platforms are displacing legacy intermediaries, while specialty retail retains relevance for high-consideration bridal purchases.
- Online Retail:Vertically integrated brands and independent designers build follower bases that convert through virtual try-on technology and transparent origin documentation. United States metropolitan markets show substantial showroom traffic decline alongside e-commerce acceleration.
- Jewelry Stores:Brick-and-mortar bridal specialists provide consultation, sizing, and mounting services for high-value transactions. Inventory carrying costs and FTC compliance overhead pressure smaller independent operators.
- Specialty Shops:Gemological retailers and ethical jewelry boutiques curate certified moissanite alongside lab-grown and natural diamonds. European REACH alignment requirements shape procurement specifications.
- Auctions:Estate and secondary market channels facilitate liquidation of vintage pieces and collector-grade specimens. Price discovery remains fragmented without standardized grading consensus.
Established volume flows through jewelry stores. Online retail is capturing incremental growth fastest among digitally native consumer segments.
Customer Type:
Procurement patterns diverge between specification-driven manufacturers and narrative-sensitive end consumers.
- Retail Consumers:Individual buyers complete purchase journeys through direct-to-consumer platforms and bridal showroom consultations. Disclosure clarity and ethical provenance documentation influence brand selection.
- Wholesalers:Volume distributors aggregate calibrated goods from Wuzhou cutting houses for redistribution to jewelry manufacturers and retailers. Margin compression from Chinese synthetic competition pressures trading positions.
- Manufacturers:Finished jewelry producers specify DEF-grade certified rough for bridal inventory while accepting near-colorless goods for fashion-tier production. India's BIS certification requirements shape export compliance costs.
- Designers:Independent creators commission precision-cut specialty shapes and custom dimensions for limited-production collections. Harro Gem's specialty cutting capabilities command loyalty among premium positioning brands.
Wholesalers anchor established supply chain throughput. Designers represent the fastest-expanding customer type as direct-to-consumer brand building accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuzhou anchors global moissanite processing through its concentrated cutting infrastructure, while demand dispersion across bridal and fashion channels creates distinct regional growth profiles. Regulatory disclosure requirements and certification standards are diverging across major consumption markets, reshaping compliance costs and competitive positioning.
United States
Bridal jewelry demand from millennial and Gen-Z buyers prioritizes documented lab-created origin over mined diamond alternatives. The FTC's 2023 Jewelry Guides revision mandates explicit synthetic disclosure, eliminating ambiguous marketing terminology and compressing margins for non-compliant sellers. Los Angeles and New York City host the dominant direct-to-consumer brand headquarters and virtual try-on technology development clusters.
China
Domestic fashion jewelry consumption accelerates through social commerce channels targeting younger demographic cohorts with ethical sourcing narratives. SAMR enforces strengthened GB standards on synthetic gem labeling for cross-border e-commerce fulfillment, reducing consumer confusion. Guangxi province concentrates over 70 percent of global synthetic moissanite rough production, creating concentrated supply vulnerability.
India
Rising middle-class disposable income and westernized wedding customs drive underpenetrated demand for affordable engagement alternatives. BIS certification requirements for precious metals and gemstones shape export compliance costs for domestic jewelry manufacturers. Surat's diamond cutting infrastructure is expanding into calibrated moissanite processing for Western retail distribution.
Germany
European jewelry retailers increasingly specify silicon carbide with full REACH material safety documentation, creating procurement preference for certified producers. The country's national consumer protection regulator enforces strict origin disclosure requirements for synthetic gemstone marketing. Hamburg and Frankfurt concentrate ethical jewelry boutique retail and gemological certification laboratory capacity.
Thailand
Finished jewelry manufacturing clusters in Bangkok supply silver and gold vermeil mountings at accessible price tiers for North American and European markets. The country's national standards body aligns with international gemological disclosure frameworks to maintain export market access. Chanthaburi's colored gemstone trading infrastructure is diversifying into moissanite cutting and jewelry assembly.
Moissanite Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and origin-documentation dimensions, with DEF-grade colorless stones commanding sustained price premiums against near-colorless commodity goods. The vendor base separates into patent-legacy brand holders, precision-cut specialists, and scale-driven rough suppliers. Three archetypes dominate: vertically integrated bridal brands with North American recognition, Wuzhou-anchored cutting houses with global distribution reach, and specialty-shape precision cutters serving designer loyalty. Competitive moves concentrate on FTC-compliant origin documentation investments and direct-to-consumer channel buildout.
Among North American brand holders, Charles & Colvard occupies a position exemplifying patent-derived premium positioning in bridal channels. Within the precision-cut specialist tier, Harro Gem represents designer-focused specialty shape capabilities. At the scale-driven end, Stars Gem anchors global rough supply through Wuzhou's concentrated processing infrastructure. These three entities illustrate the strategic segmentation between brand-premium, craft-specialist, and volume-scale competitive vectors.
| Leading Market Players |
|---|
| HRB Exports |
| Stars Gem |
| Charles & Colvard |
| Unimoss |
| Wuzhou Changsheng Gems |
| Moissanite International |
| Viktor Kämmerling |
| Harro Gem |
| Amora |
| Others |
Supply Flow & Price Mechanics
DEF-grade colorless certification against near-colorless commodity grades bifurcates margin capture across the moissanite value chain, with premium stones commanding sustained price premiums through documented gemological provenance while commodity tiers face compression from Chinese synthetic competition. This tier divergence manifests in supply chain configuration through Wuzhou's concentrated cutting infrastructure serving commodity volume and specialized precision cutters serving premium positioning.
Pricing Analysis
Value-based pricing anchors premium tier positioning to optical performance metrics and certification documentation rather than carat-weight baselines. Three-tier pricing structure across premium, standard, and economy levels separates Charles & Colvard's patent-legacy brand positioning from Wuzhou-anchored commodity suppliers and precision-cut specialists. Cost compression in the commodity tier intensifies because semiconductor industry competition for high-purity silicon carbide feedstock constrains rough availability. Bridal manufacturers show least price sensitivity for certified DEF-grade solitaires, while fashion jewelry distributors exhibit highest sensitivity to per-carat differentials.
Supply Chain Analysis
Single-source vulnerability sits with Guangxi province, where over seventy percent of synthetic moissanite rough production concentrates in a single Chinese region. Manufacturing draws from silicon carbide feedstock, precision cutting equipment, and gemological certification services anchored in China, India, and Thailand. Tariff exposure runs through cross-border e-commerce fulfillment channels serving North American direct-to-consumer brands. Distribution runs through vertically integrated bridal specialists, Wuzhou-based cutting houses, and independent designer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical vapor deposition technology is displacing legacy thermal growth methods across moissanite manufacturing, creating asymmetric investment requirements that favor capitalized incumbents while compressing margins for legacy producers unable to fund reactor upgrades.
For Market Incumbents: Deepen backward integration into high-purity silicon carbide feedstock sourcing to defend against semiconductor industry competition for wafer-grade material. Prioritize FTC-compliant origin documentation investments to capture shelf space from non-compliant competitors facing civil penalty exposure. For New Entrants and Emerging Players: Enter via India's underpenetrated domestic bridal market, where rising middle-class disposable income and westernized wedding customs create white-space demand for affordable engagement alternatives. Target men's jewelry line extensions including cufflinks and signet rings as minimally saturated application categories with direct-to-consumer social commerce positioning. For Investors and Strategic Acquirers: Re-rating potential sits with precision-cut specialty specialists given designer loyalty consolidation and direct-to-consumer channel buildout. Long-term viability favors archetypes with captive CVD reactor capacity and established North American brand recognition. The signal to watch is gemological certification laboratory capacity expansion timelines, which indicate premium inventory velocity acceleration or constraint.| Strategic Initiative | Industry Significance |
|---|---|
| CVD Reactor Capacity Expansion | Enables larger colorless crystal production meeting bridal certification requirements. |
| FTC-Compliant Documentation Investment | Eliminates civil penalty exposure and secures wholesale contract renewals. |
| Direct-to-Consumer Channel Buildout | Captures retail markup multiples via Instagram and TikTok discovery conversion. |
| Backward Integration into Feedstock | Secures silicon carbide supply against semiconductor industry competition. |
| Specialty Shape Precision Cutting | Commands designer loyalty through custom dimension capabilities. |
Methodological Framework
Independent corroboration across bridal jewelry procurement managers, gemological laboratory directors, and CVD reactor equipment suppliers underwrites the qualitative findings. Primary interviews with finished jewelry manufacturers, Wuzhou cutting house operators, and direct-to-consumer brand executives combined with secondary validation from FTC regulatory filings, BIS certification databases, and SAMR cross-border e-commerce standards. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across product type, application, distribution channel, and customer type dimensions structured the analytical framework. CAGRs derived from segment-level growth trajectories normalized against semiconductor industry silicon carbide demand projections and bridal jewelry expenditure patterns. Modeled inputs included CVD technology adoption curves, gemological certification capacity constraints, and social commerce channel penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to Guangxi production or accelerated lab-grown diamond price erosion. Forecasts reflect documented assumptions regarding technology transition timelines and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Metal and Metal Ores Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Manganese Market