
 Beryllium Hydroxide Market | 2026-2036
Beryllium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Hydroxide Market Analysis
Specialty chemical distribution is tilting toward direct mill-to-manufacturer contracts as beryllium hydroxide buyers seek supply security. Materion Corporation leverages captive mining and refining assets in Utah to sustain North American supply continuity. Ulba Metallurgical Plant JSC anchors Central Asian output through state-backed vertical integration into Kazakhstan's beryllium reserves. Stanford Advanced Materials competes on research-grade purity tiers, serving laboratories with customized lot sizes and certification packages.
Beryllium hydroxide functions as an intermediate compound, typically precipitated from beryllium sulfate solutions and calcined to beryllium oxide or reduced to metallic beryllium; its 99.5%+ purity grades enable thermal neutron moderation and high-thermal-conductivity substrate applications. Electronic grade output dominates value generation, driven by semiconductor heat-spreader and microwave component demand, while medical grade commands premium positioning through nuclear imaging equipment supply chains. Aerospace application volumes lead tonnage consumption, though nuclear sector procurement is accelerating as small modular reactor programs advance material qualification timelines.
OSHA enforces permissible exposure limits for beryllium compounds in U.S. fabrication facilities, while REACH classifications in Europe restrict uncontrolled beryllium salt distribution, forcing importers to demonstrate downstream closed-loop handling. China's GB standards and NMPA oversight shape import thresholds for medical-grade material used in domestic imaging equipment manufacturing. Stakeholders must monitor evolving dual-use export control designations, as defense-linked beryllium hydroxide flows face heightened scrutiny under multilateral nonproliferation frameworks.
Market Dynamics
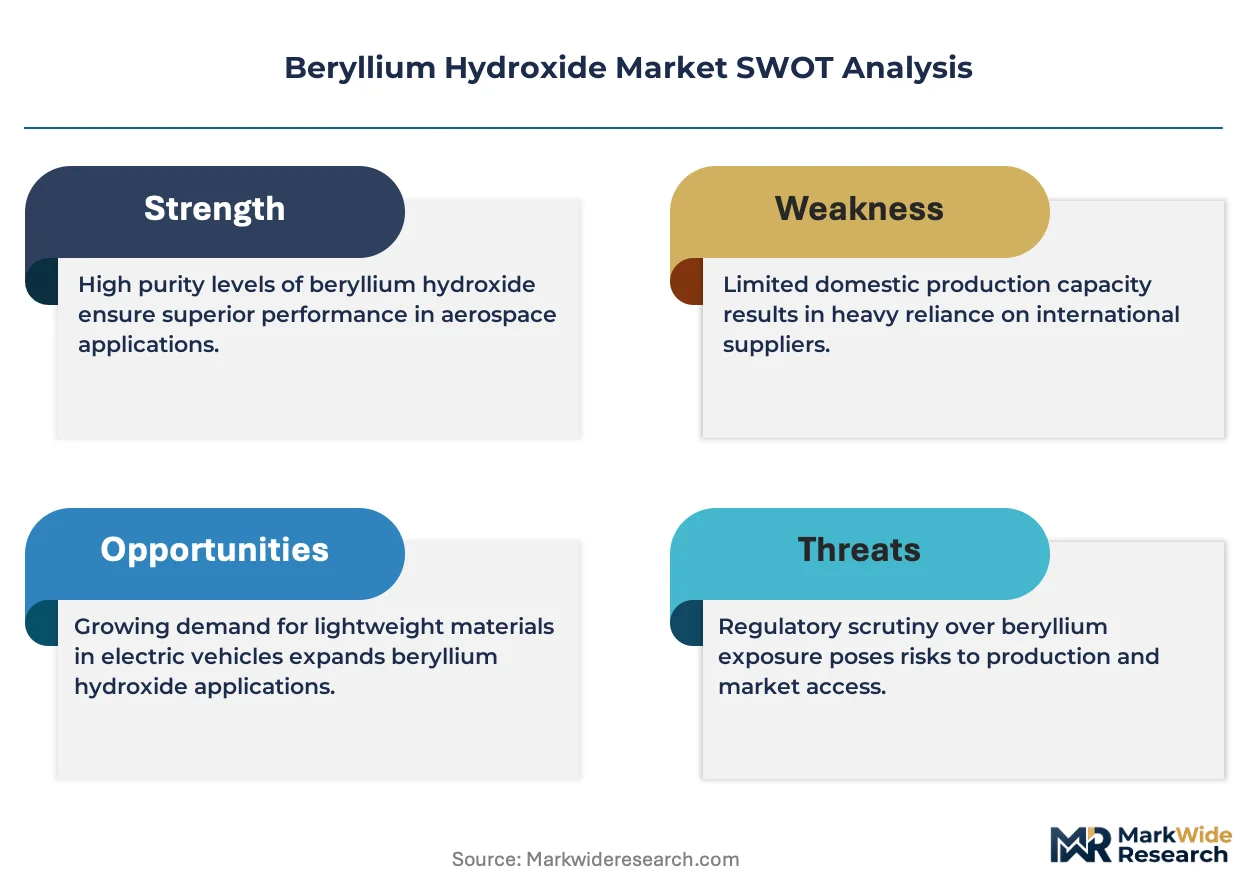
Supply concentration in Kazakhstan and Utah is locking procurement into long-term offtake agreements as aerospace OEMs prioritize thermal management substrate security over spot-market flexibility. This geographic dualism is compressing margin structures for non-integrated distributors.
Growth Catalysts
- Small Modular Reactor Deployment:Nuclear engineering firms are qualifying beryllium hydroxide for neutron moderation in next-generation reactor designs, accelerating procurement timelines for 99.5%+ purity grades.
- OSHA Exposure Limit Tightening:Stricter permissible exposure limits in U.S. fabrication facilities are forcing process upgrades that favor suppliers with closed-loop handling certifications, advantaging integrated producers.
- Semiconductor Heat-Spreader Demand:Advanced packaging architectures in high-performance computing are consuming electronic-grade material at volumes that outpace traditional aerospace applications.
Market Restraints
- Beryllium Ore Concentration:Over 80% of mined feedstock originates from Spor Mountain, Utah and Eastern Kazakhstan deposits, creating single-source vulnerability for non-captive refiners.
- REACH Classification Friction:ECHA restrictions on uncontrolled beryllium salt distribution impose documentation burdens that delay European import clearances by 4-8 weeks.
- Aluminum Nitride Substitution:Ceramic thermal management materials are capturing mid-performance heat-spreader applications where thermal conductivity requirements fall below 200 W/m·K.
Strategic Opportunities
- India Domestic Imaging Equipment:CDSCO regulatory pathways for nuclear medicine device manufacturing are opening import channels for medical-grade material previously blocked by BIS certification gaps.
- Direct Mill-to-Manufacturer Contracting:Bypassing specialty chemical distributors through long-term offtake agreements secures volume commitments and reduces working capital cycles for integrated producers.
- Dual-Use Export Control Arbitrage:Defense-linked beryllium hydroxide flows face heightened multilateral scrutiny, creating compliance service revenue streams for logistics providers with export licensing expertise.
Industry Challenges
- Closed-Loop Handling Certification:Fabricators must demonstrate OSHA-compliant exposure controls across machining, cleaning, and waste disposal operations, requiring capital investment in ventilation and monitoring systems.
- Smelter-Grade to Electronic-Grade Purification:Scaling precipitation and calcination processes from 98% to 99.5%+ purity involves yield losses of 15-20% that compress unit economics for mid-scale refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Hydroxide Market |
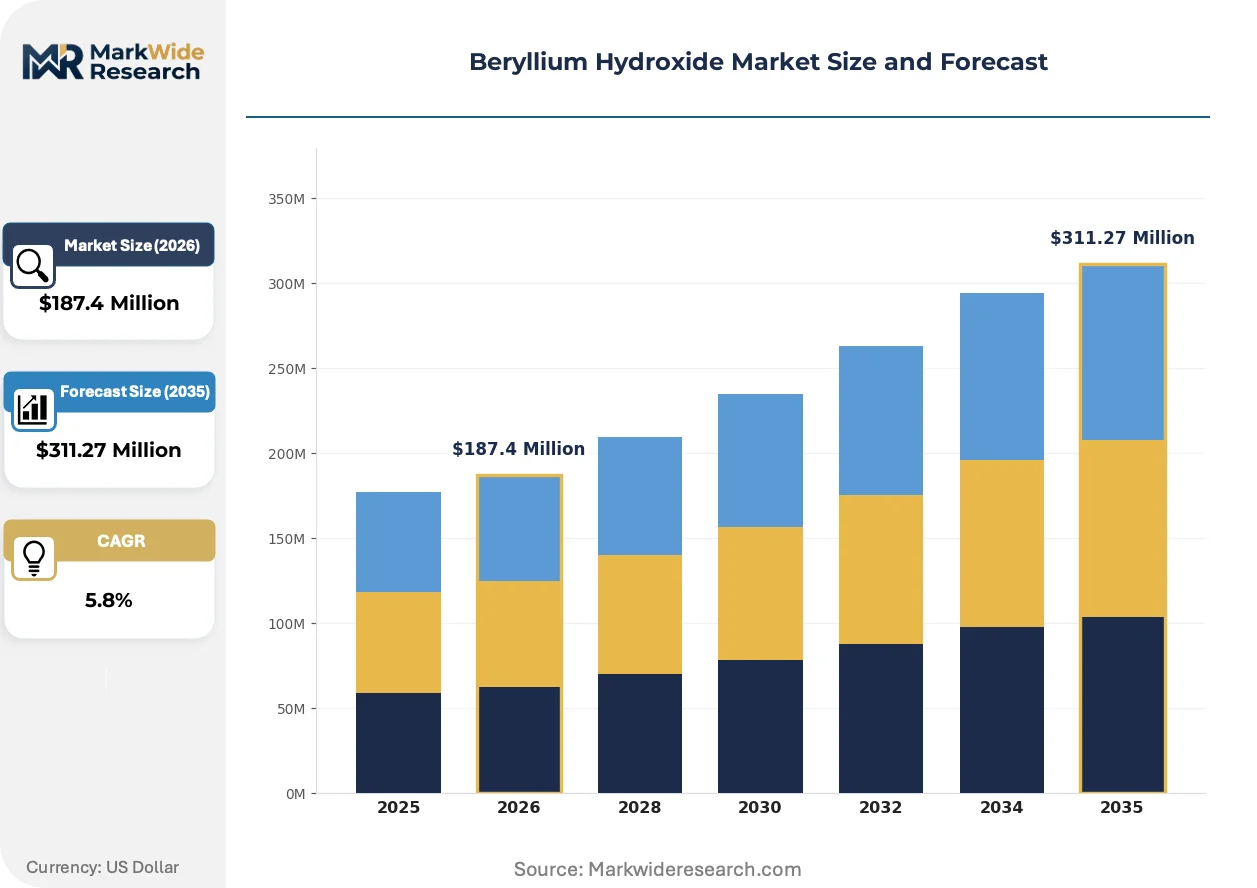
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Electronic Grade, Research Grade, Medical Grade Application: Aerospace, Electronics, Nuclear, Medical Devices End User: Manufacturers, Laboratories, Research Institutes, Defense Sector Form: Powder, Granule, Solution, Paste |
| Companies Covered | Materion Corporation, NGK Metals Corporation, Stanford Advanced Materials, Ulba Metallurgical Plant JSC, IBC Advanced Alloys Corp., American Beryllia Inc., Hunan Nonferrous Beryllium Industry Co. Ltd., Xinjiang Nonferrous Metal Industry Group, Belmont Metals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Hydroxide Market Emerging Trajectories
Thermal management substrate specifications are tightening as power densities in semiconductor and aerospace applications outpace legacy material performance limits. Process innovation and procurement restructuring are converging to reshape competitive positioning.
Sol-gel precipitation techniques for beryllium hydroxide purification are migrating from laboratory-scale demonstration to commercial production lines. Aerospace OEMs in North America are specifying sol-gel-derived material for next-generation heat-spreader assemblies. This migration from conventional sulfate precipitation is enabling 0.3-micron particle size control that legacy methods cannot replicate.
REACH Annex XIV authorization requirements for beryllium compounds are forcing European importers to demonstrate downstream closed-loop handling across their supply chains. Industrial consequence includes mandatory third-party audit costs that add 8-12% to landed material prices. Medical imaging equipment manufacturers in Germany and France are responding by consolidating procurement through distributors with pre-validated handling certifications.
Buyer concentration among tier-one aerospace primes is compressing negotiation cycles from annual to quarterly reviews. Specialty chemical distributors serving second-tier machine shops are losing volume to direct manufacturer contracts. This pattern is most visible in Utah's Wasatch Front cluster, where Materion's captive supply integration has eliminated distributor margins from 60% of regional procurement volume.
Beryllium Hydroxide Market Segmentation
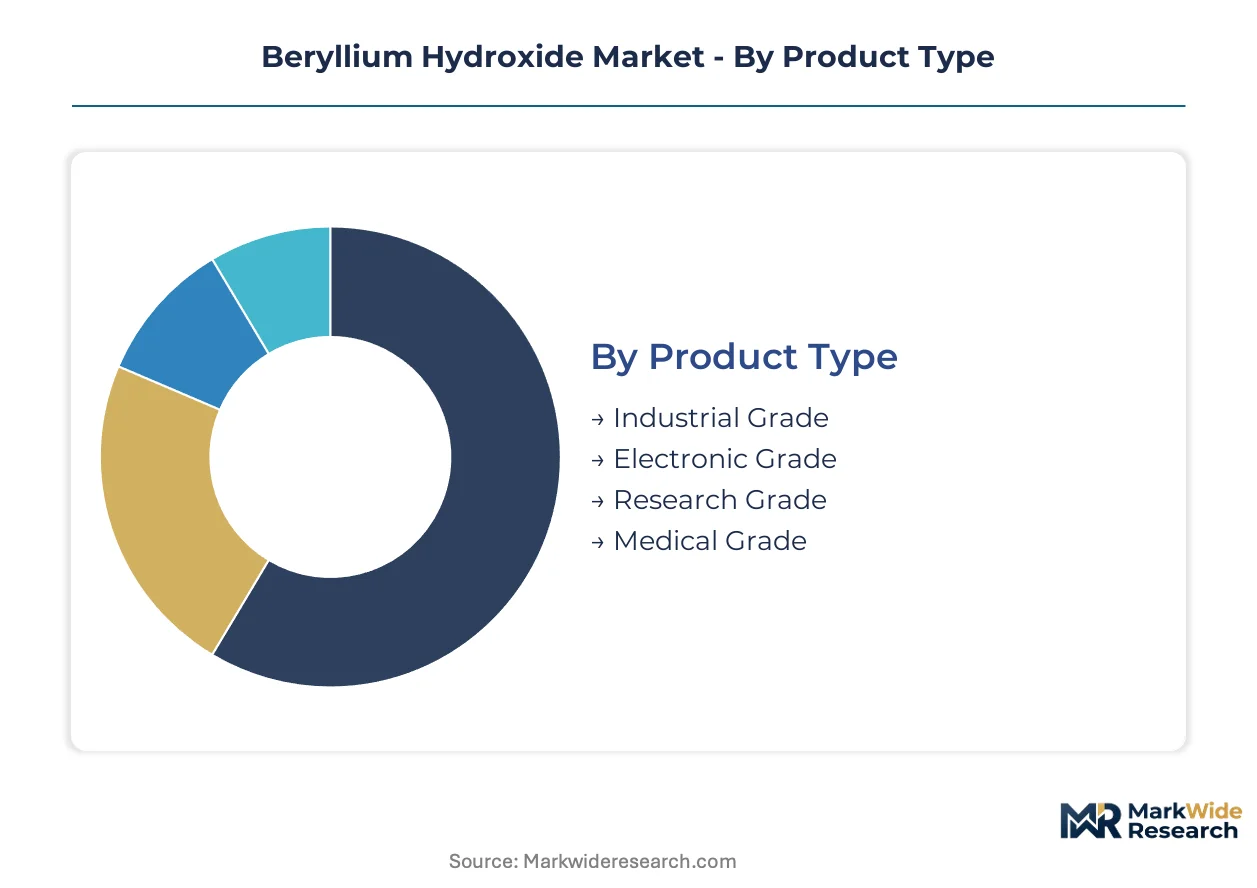
Beryllium hydroxide procurement cycles vary dramatically by purity tier and end-use criticality. Electronic-grade material for semiconductor heat-spreaders turns over on quarterly contracts, while research-grade lots move on project-based timelines measured in years.
Product Type:
Cycle times compress as purity requirements rise, with electronic-grade material refreshing fastest due to semiconductor packaging demand volatility.
- Electronic Grade:Precipitated to 99.5%+ purity specifications with sub-micron particle size control for thermal neutron moderation and high-conductivity substrates. Aerospace OEMs in the United States and Kazakhstan are locking procurement into multi-year offtake agreements as small modular reactor programs accelerate material qualification timelines.
- Medical Grade:Certified for nuclear imaging equipment supply chains with full traceability documentation and closed-loop handling protocols. CDSCO regulatory pathways in India are opening import channels previously blocked by BIS certification gaps, concentrating expansion in domestic imaging device manufacturing.
- Industrial Grade:98% purity baseline material serving ceramic and alloy feedstock applications with lower certification overhead.
- Research Grade:Customized lot sizes with full certification packages for laboratory-scale experimentation and process development.
Electronic grade dominates installed base. Medical grade is where expansion concentrates.
Application:
Cost tier stratification separates mission-critical aerospace procurement from price-sensitive medical device integration.
- Aerospace:Thermal management substrates for satellite and aircraft systems requiring guaranteed supply continuity. Materion Corporation's captive Utah refining operations and Ulba Metallurgical Plant JSC's Kazakhstan integration anchor procurement security for North American and Central Asian primes respectively.
- Electronics:Semiconductor heat-spreader assemblies consuming the highest-purity grades as advanced packaging architectures push power densities beyond legacy material limits. Sol-gel precipitation techniques are displacing conventional sulfate methods for 0.3-micron particle control.
- Nuclear:Neutron moderation applications in small modular reactor designs with 99.5%+ purity mandates and extended qualification cycles.
- Medical Devices:Nuclear imaging equipment integration with premium positioning through regulatory compliance documentation.
Aerospace commands the highest volume throughput. Nuclear is climbing the fastest as reactor deployment accelerates.
End User:
Customer type determines contract structure, with defense-linked procurement facing heightened multilateral export control scrutiny.
- Defense Sector:Dual-use designation requirements under nonproliferation frameworks impose licensing delays that favor suppliers with pre-cleared handling certifications. Logistics providers with export licensing expertise are capturing compliance service revenue streams.
- Manufacturers:Tier-one aerospace primes are compressing negotiation cycles from annual to quarterly reviews, bypassing distributors for direct mill contracts.
- Research Institutes:Project-based procurement with customized lot sizes and extended certification timelines.
- Laboratories:Small-volume, high-frequency orders with premium pricing for research-grade material.
Manufacturers dominate procurement volume. Defense sector is where margin protection concentrates.
Form:
Supply concentration in powder processing favors integrated refiners with in-house precipitation and calcination capabilities.
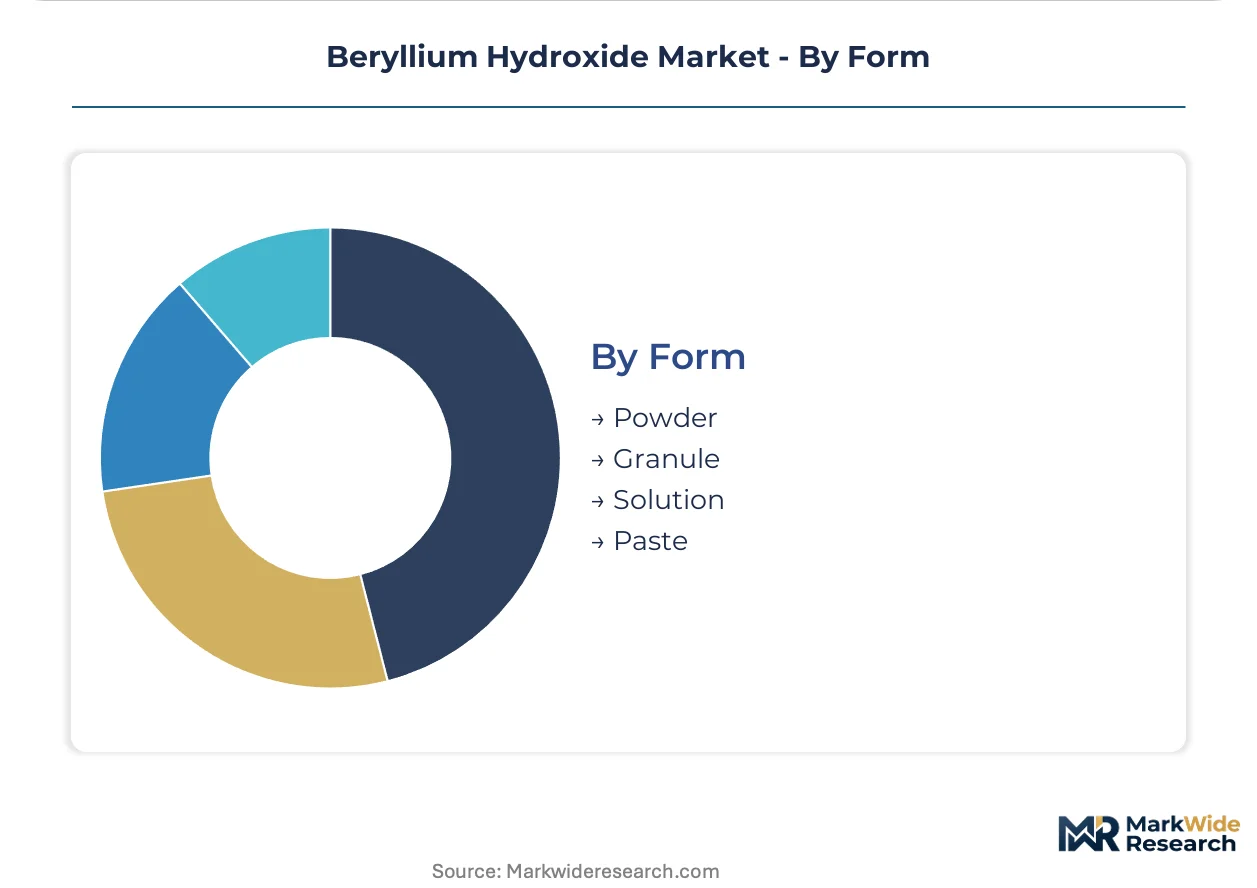
- Powder:Dominant form factor for thermal management substrate manufacturing with established handling protocols and OSHA-compliant exposure control systems.
- Granule:Intermediate processing form for ceramic and alloy feedstock applications with lower purity requirements.
- Solution:Precursor state for specialized coating applications and research-scale experimentation.
- Paste:Niche form for direct deposition processes in prototype and repair operations.
Powder dominates installed base. Solution is where process innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA exposure limits in the United States anchor regulatory stringency for beryllium hydroxide handling, forcing fabrication facilities to upgrade ventilation and monitoring systems. Kazakhstan's state-backed refining complex commands Central Asian output through integrated mining and purification operations.
United States
Aerospace OEMs in Utah's Wasatch Front cluster demand electronic-grade material for thermal management substrates in satellite systems. OSHA enforces permissible exposure limits that favor suppliers with closed-loop handling certifications, advantaging integrated producers with captive refining assets. Materion Corporation's Utah operations sustain North American supply continuity through backward integration into Spor Mountain ore deposits.
Kazakhstan
Ulba Metallurgical Plant JSC anchors Central Asian output through state-backed upstream control over domestic beryllium reserves. The country's national industrial regulator oversees extraction and export licensing for defense-linked material flows. Eastern Kazakhstan's integrated refining corridor concentrates purification capacity for 99.5%+ purity grades serving nuclear and aerospace procurement.
China
Domestic imaging equipment manufacturers consume medical-grade material under NMPA oversight for nuclear medicine device production. GB standards and import thresholds shape procurement channels for foreign-sourced beryllium compounds. Hunan and Xinjiang provinces host nonferrous metal groups with in-house production of ceramic and alloy feedstock grades.
Germany
Medical imaging equipment manufacturers in Bavaria and Baden-Württemberg consolidate procurement through distributors with pre-validated handling certifications. ECHA restrictions on uncontrolled beryllium salt distribution impose documentation burdens that delay import clearances. The Eindhoven Region's semiconductor packaging cluster sources electronic-grade material for advanced heat-spreader assemblies.
India
CDSCO regulatory pathways for nuclear medicine device manufacturing open import channels for medical-grade material previously blocked by BIS certification gaps. Maharashtra and Gujarat host emerging domestic imaging equipment fabrication facilities. The country's national pharmaceutical regulator shapes compliance requirements for traceability documentation in closed-loop handling protocols.
Beryllium Hydroxide Market Vendor Landscape
Vertically integrated miners and specialty chemical distributors split the market into captive supply and merchant resale channels. Concentration remains high due to ore deposit scarcity and purification complexity. Two archetypes dominate: integrated producers with backward control into mining assets, and research-grade specialists competing on certification packages. Competitive moves center on long-term offtake agreements and direct mill-to-manufacturer contracting that eliminates distributor margins.
Among North American fabricators, Materion Corporation exemplifies the integrated producer archetype through captive Utah refining operations. Ulba Metallurgical Plant JSC anchors the state-backed vertical integration model with Kazakhstan's domestic reserve base. Stanford Advanced Materials occupies a position within the research-grade tier, serving laboratory demand with customized lot sizes and extended certification timelines.
| Leading Market Players |
|---|
| Materion Corporation |
| NGK Metals Corporation |
| Stanford Advanced Materials |
| Ulba Metallurgical Plant JSC |
| IBC Advanced Alloys Corp. |
| American Beryllia Inc. |
| Hunan Nonferrous Beryllium Industry Co. Ltd. |
| Xinjiang Nonferrous Metal Industry Group |
| Belmont Metals Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Eastern Kazakhstan's integrated refining corridor is tightening spot-market availability and amplifying long-term offtage premiums. Aerospace OEMs in North America are absorbing cost pass-throughs from captive Utah suppliers as OSHA-compliant handling certifications become non-negotiable procurement filters.
Pricing Analysis
Geographic price spreads between Utah-captive and Kazakhstan-origin material are widening as REACH documentation burdens add landed-cost premiums for European buyers. Contract-based long-term offtake agreements dominate electronic-grade procurement, with price differentiation resting on certification grade and closed-loop handling validation. Cost compression in industrial-grade tiers is intensifying because aluminum nitride substitutes are capturing mid-performance thermal management applications. Medical device manufacturers exhibit lowest price sensitivity due to regulatory compliance requirements and traceability mandates.
Supply Chain Analysis
Tariff exposure between Kazakhstan and European Union member states dominates supply chain risk planning for non-integrated distributors. Production gravity centers on the United States and Kazakhstan, with raw material dependencies drawing from Spor Mountain ore deposits and Eastern Kazakhstan beryllium reserves. Single-source vulnerability in mined feedstock creates procurement insecurity for merchant refiners lacking captive mining assets. Distribution runs through direct mill-to-manufacturer contracts that eliminate specialty chemical distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum nitride substitution in sub-200 W/m·K thermal conductivity applications threatens beryllium hydroxide's installed base in mid-performance electronics. Incumbents must navigate this material displacement while defending premium positioning in neutron moderation and high-reliability aerospace substrates.
For Market Incumbents: Build certification moats around OSHA-compliant closed-loop handling and REACH Annex XIV authorization pre-validation. Materion Corporation's captive Utah refining demonstrates how backward integration into Spor Mountain ore deposits insulates supply continuity. Ulba Metallurgical Plant JSC's state-backed upstream control over Kazakhstan reserves offers a parallel defense against feedstock disruption. Both archetypes compress distributor margins by securing direct aerospace OEM contracts.
For New Entrants and Emerging Players: Establish a beachhead in India's medical-grade segment where CDSCO regulatory pathways are opening import channels previously blocked by BIS certification gaps. Maharashtra and Gujarat host emerging domestic imaging equipment fabrication facilities with unmet demand for traceability-documented material. Research-grade purity tiers offer secondary white-space with customized lot sizes and extended certification timelines that integrated producers disfavor.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive mining and multi-year offtake agreements locking aerospace procurement. Long-term viability hinges on small modular reactor deployment timelines and semiconductor heat-spreader demand durability. Watch qualification progress for 99.5%+ purity grades in next-generation reactor designs as the inflection signal for nuclear sector acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Secures volume commitments from aerospace OEMs facing thermal management substrate shortages. |
| Backward Integration | Captive mining into Spor Mountain or Kazakhstan reserves eliminates single-source feedstock vulnerability. |
| Capacity Expansion | Adds electronic-grade precipitation lines to capture semiconductor heat-spreader demand acceleration. |
| Joint Venture | Combines Kazakhstan state-backed refining with Western handling certification for European market access. |
| Green Manufacturing Transition | Deploys sol-gel precipitation techniques reducing yield losses in 99.5%+ purity production. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed specialty chemical producers, ECHA regulatory submissions, and nuclear engineering qualification databases. Primary interviews engaged plant managers at Utah and Kazakhstan refining facilities, procurement leads at tier-one aerospace OEMs, distribution channel partners in European medical imaging equipment supply chains, and technical R&D directors developing sol-gel precipitation techniques. Bottom-up volume estimates from purity-grade production capacities were triangulated against top-down demand aggregation across aerospace, electronics, nuclear, and medical device end-uses.
Forecast inputs span grade tier stratification, end-use industry demand cycles, regional regulatory cluster adoption timelines, and material qualification progress in small modular reactor programs. CAGRs were derived through regression analysis of historical procurement volumes against projected deployment schedules for semiconductor packaging architectures and next-generation nuclear designs. The modeling period incorporates OSHA exposure limit enforcement trajectories and REACH authorization pathway durations as structural constraints.
Stress conditions across aluminum nitride substitution rates, Kazakhstan export licensing disruptions, and small modular reactor qualification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding purity grade yield curves and aerospace OEM inventory policy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Selenium Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Mexico Mining Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Global Fabricated Metal Products Market