
 Electrolytic Manganese Dioxide Market | 2026-2036
Electrolytic Manganese Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolytic Manganese Dioxide Market Intelligence
The EU Battery Regulation and associated carbon footprint declarations is consolidating procurement criteria across European battery supply chains. Xiangtan Electrochemical Technology Co., Ltd. leverages its integrated manganese ore-to-EMD processing base in Hunan Province to sustain cost advantages in battery-grade output. Tosoh Corporation anchors high-purity synthetic EM production for specialty lithium-ion applications in Japan. Eramet SA competes through its Gabonese ore assets and European refining footprint, navigating divergent regional purity standards.
Electrolytic manganese dioxide is a high-purity manganese oxide produced through electrolysis of manganese sulfate solutions, typically achieving 90-92% MnO₂ content with controlled trace metal profiles for electrochemical performance. The material functions primarily as cathode active material in primary alkaline batteries and as precursor feedstock for lithium-ion battery cathodes. Battery-grade synthetic EM commands premium positioning due to stringent particle size and impurity specifications demanded by lithium-ion cell makers, while natural EM retains volume dominance in alkaline battery applications where cost efficiency outweighs purity thresholds. Chemical-grade product occupies stable industrial niches in fine chemical synthesis with limited growth upside relative to battery-directed grades.
China's SAMR enforces GB standards on battery material purity, while the EU's REACH and Battery Regulation impose disclosure and due diligence obligations on imported manganese products. Japan's METI coordinates domestic stockpiling and supply security frameworks for critical battery minerals including manganese. Stakeholders must monitor evolving carbon-border adjustment mechanisms and country-of-origin traceability mandates that will reshape competitive access across regional battery supply chains.
Market Dynamics
China's dual carbon goals and tightening GB standards on battery material purity are forcing electrolytic manganese dioxide producers to reconfigure energy-intensive electrolysis operations while maintaining cost competitiveness against synthetic alternatives.
Growth Catalysts
- Alkaline battery cathode demand:Primary battery manufacturers in East Asia are scaling procurement of battery-grade EMD for high-drain consumer electronics applications.
- EU Battery Regulation:Carbon footprint declarations and due diligence obligations are consolidating procurement criteria across European battery supply chains toward traceable, low-carbon manganese sources.
- Lithium-ion precursor feedstock:Cathode precursor makers in China's Hunan and Guizhou provinces are expanding offtake agreements for high-purity EMD as synthetic EM substitute.
Market Restraints
- Power cost volatility:Electrolytic production consumes 3,500-4,500 kWh per tonne MnO₂, exposing margins to electricity price swings in China's industrial zones.
- Ore concentration risk:High-grade manganese ore deposits cluster in Gabon, South Africa, and Australia's Groote Eylandt, creating geopolitical chokepoints for sulfate feedstock.
- Synthetic EM substitution:Chemical precipitation methods achieve 99%+ purity for specialty lithium-ion applications, compressing EMD's addressable premium segment.
Strategic Opportunities
- India battery manufacturing:PLI scheme incentives for advanced chemistry cell production are creating first-mover advantage for EMD suppliers establishing local sulfate processing.
- Carbon border adjustment positioning:Producers with captive renewable power and scope 1-2 emissions data can secure preferential access to EU battery supply chains under CBAM phase-in.
- Direct recycling integration:Black mass processors are developing manganese recovery loops that could displace virgin ore demand for secondary EMD feedstock.
Industry Challenges
- Electrochemical engineering talent:Optimizing current efficiency and deposit morphology requires specialized expertise in hydrometallurgical cell design that is scarce outside established Chinese producers.
- Certification timeline compression:Battery maker qualification protocols now demand 12-18 month validation cycles for new EMD sources, locking out speculative entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolytic Manganese Dioxide Market |
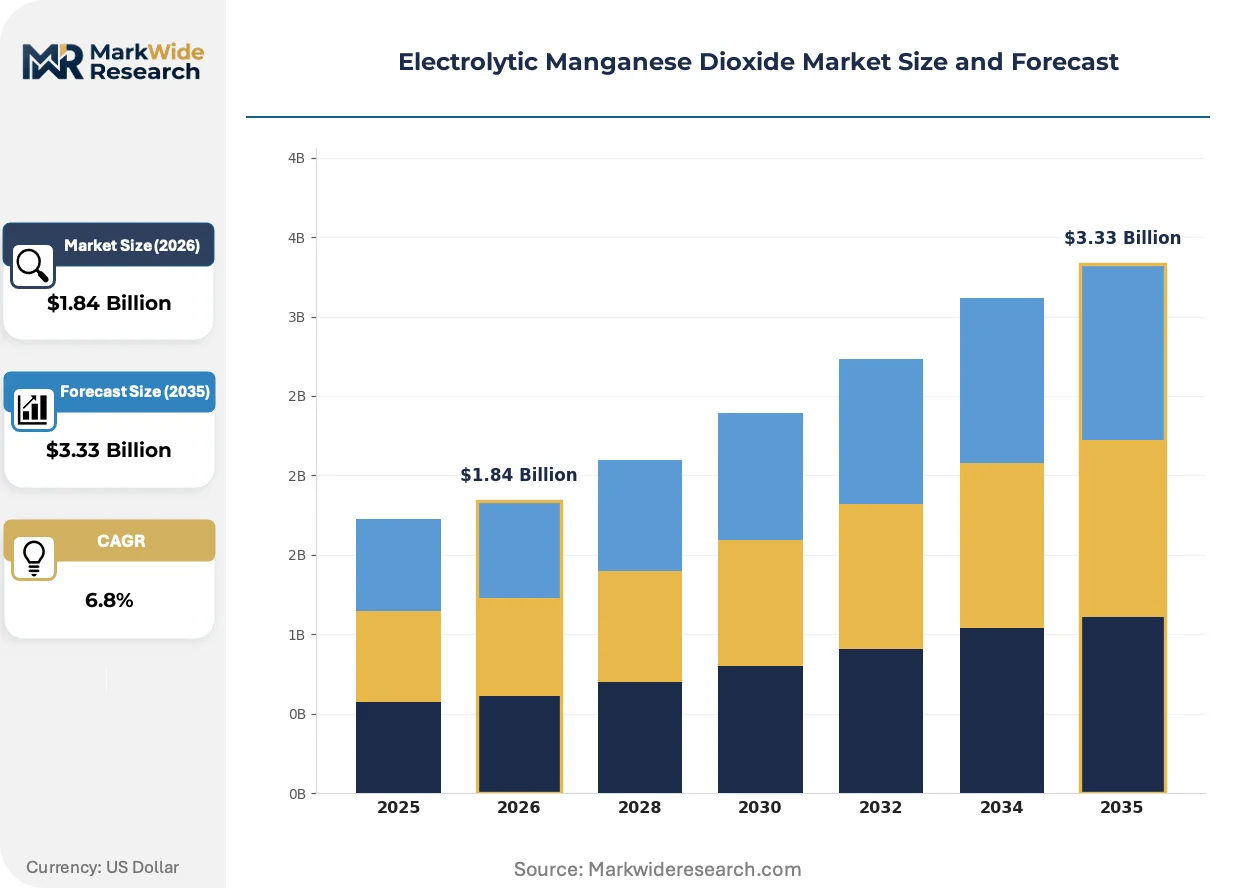
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural EM, Synthetic EM, Battery Grade, Chemical Grade Application: Primary Batteries, Alkaline Batteries, Zinc Manganese Dioxide Cells, Lithium-Ion Cells End User: Battery Manufacturers, Electronic Device Makers, Power Tool Producers, Industrial Equipment Manufacturers Packaging Type: Bulk Bags, Drum Containers, Paper Bags, Plastic Sacks |
| Companies Covered | Vibrantz Technologies, Inc., Tronox Holdings plc, Xiangtan Electrochemical Technology Co., Ltd., Eramet SA, Mesa Minerals Limited, Tosoh Corporation, Guizhou Redstar Developing, MOIL Limited, South Manganese Investment Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolytic Manganese Dioxide Market Strategic Shifts & Innovations
Electrolytic manganese dioxide production is bifurcating between commodity-grade alkaline battery supply and precision-engineered precursor material, with process innovation determining competitive survival across both tracks.
Synthetic electrolytic manganese dioxide with tailored particle morphology is expanding into nickel-manganese-cobalt cathode formulations previously dominated by chemically precipitated alternatives. Korean and Japanese cathode makers are qualifying Hunan-origin EMD for mid-nickel NMC variants. This technology pathway is compressing the purity-premium gap between electrolytic and chemical production methods.
REACH and the EU Battery Regulation are mandating supply chain due diligence and carbon intensity disclosure for imported manganese products entering European battery supply chains. Eramet's Gabonese ore-to-refining integration now competes on traceability metrics against Asian producers. High-purity synthetic EM destined for European automotive cell plants faces the steepest compliance burden.
Long-term offtake contracting is displacing spot market procurement as cathode precursor makers seek supply security for qualified EMD sources. Japanese trading houses are underwriting capacity expansions at integrated Chinese producers in exchange for exclusive volume allocation. This behavioral shift is most visible in South Korea's cathode sector, where POSCO and LG Chem have locked in multi-year sulfate-to-EMD supply corridors.
Electrolytic Manganese Dioxide Market Segmentation
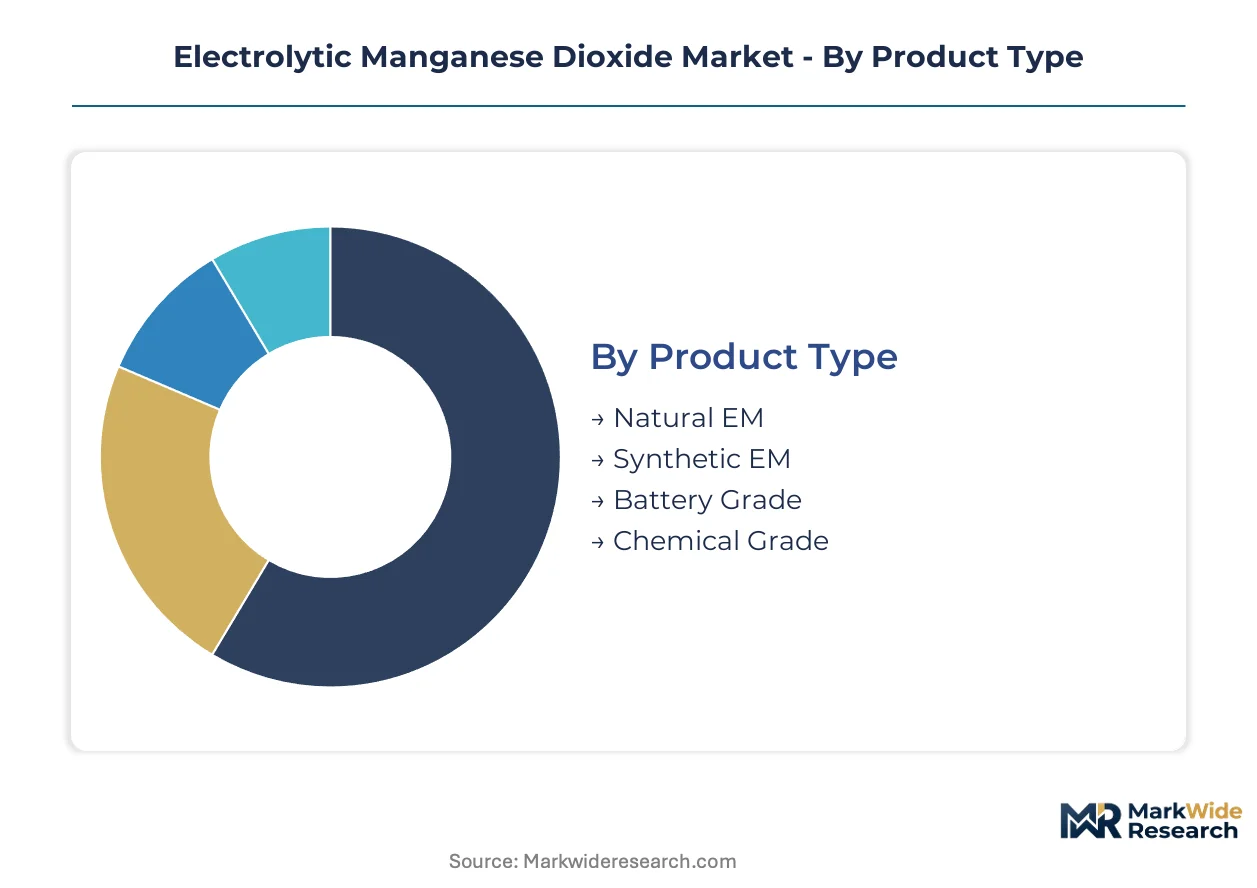
Electrolytic manganese dioxide demand bifurcates sharply between mature alkaline battery applications and emerging lithium-ion precursor markets, with product purity specifications and packaging logistics determining supplier access across divergent end-use channels.
Product Type:
Upgrade cycles from natural to synthetic material are compressing as battery-grade specifications tighten across both primary and secondary cell formats.
- Battery Grade:Achieves 90-92% MnO₂ content with controlled trace metal profiles for electrochemical performance. Demand concentrates in China's Hunan and Guizhou provinces, where cathode precursor makers are locking in multi-year sulfate-to-EMD supply corridors to secure qualified feedstock.
- Synthetic EM:Chemical precipitation methods deliver 99%+ purity for specialty lithium-ion applications. Korean and Japanese cathode makers are qualifying this material for mid-nickel NMC variants, compressing the purity-premium gap with electrolytic alternatives.
- Natural EM:Retains volume dominance in alkaline battery applications where cost efficiency outweighs purity thresholds.
- Chemical Grade:Occupies stable industrial niches in fine chemical synthesis with limited expansion relative to battery-directed grades.
Volume placements concentrate in Battery Grade; the faster expansion belongs to Synthetic EM.
Application:
Cost tier differentiation separates commodity primary cell supply from premium lithium-ion precursor positioning.
- Alkaline Batteries:High-drain consumer electronics applications in East Asia drive procurement scale for battery-grade EMD. Primary battery manufacturers are expanding offtake agreements as disposable battery demand holds steady in emerging markets.
- Lithium-Ion Cells:Cathode precursor feedstock requirements demand stringent particle size and impurity specifications. China's integrated manganese processing clusters supply this segment through captive ore-to-EMD operations.
- Primary Batteries:Standard-duty consumer applications maintain baseline demand for natural EM material.
- Zinc Manganese Dioxide Cells:Specialty primary cell formats require tailored electrochemical performance profiles.
Alkaline Batteries capture the largest volume base; Lithium-Ion Cells are climbing the fastest.
End User:
Customer type stratification reflects divergent qualification timelines and purity requirements across consumer and industrial channels.
- Battery Manufacturers:East Asian cell makers dominate procurement, with 12-18 month validation cycles locking out speculative EMD entrants. Japanese trading houses are underwriting capacity expansions at integrated Chinese producers in exchange for exclusive volume allocation.
- Electronic Device Makers:OEM specifications for high-drain applications are tightening trace metal thresholds beyond standard battery-grade material.
- Power Tool Producers:Cordless equipment battery packs require consistent electrochemical performance across temperature ranges.
- Industrial Equipment Manufacturers:Backup power and specialized industrial applications generate stable but limited demand.
Procurement gravity centers on Battery Manufacturers; Electronic Device Makers are gaining share fastest.
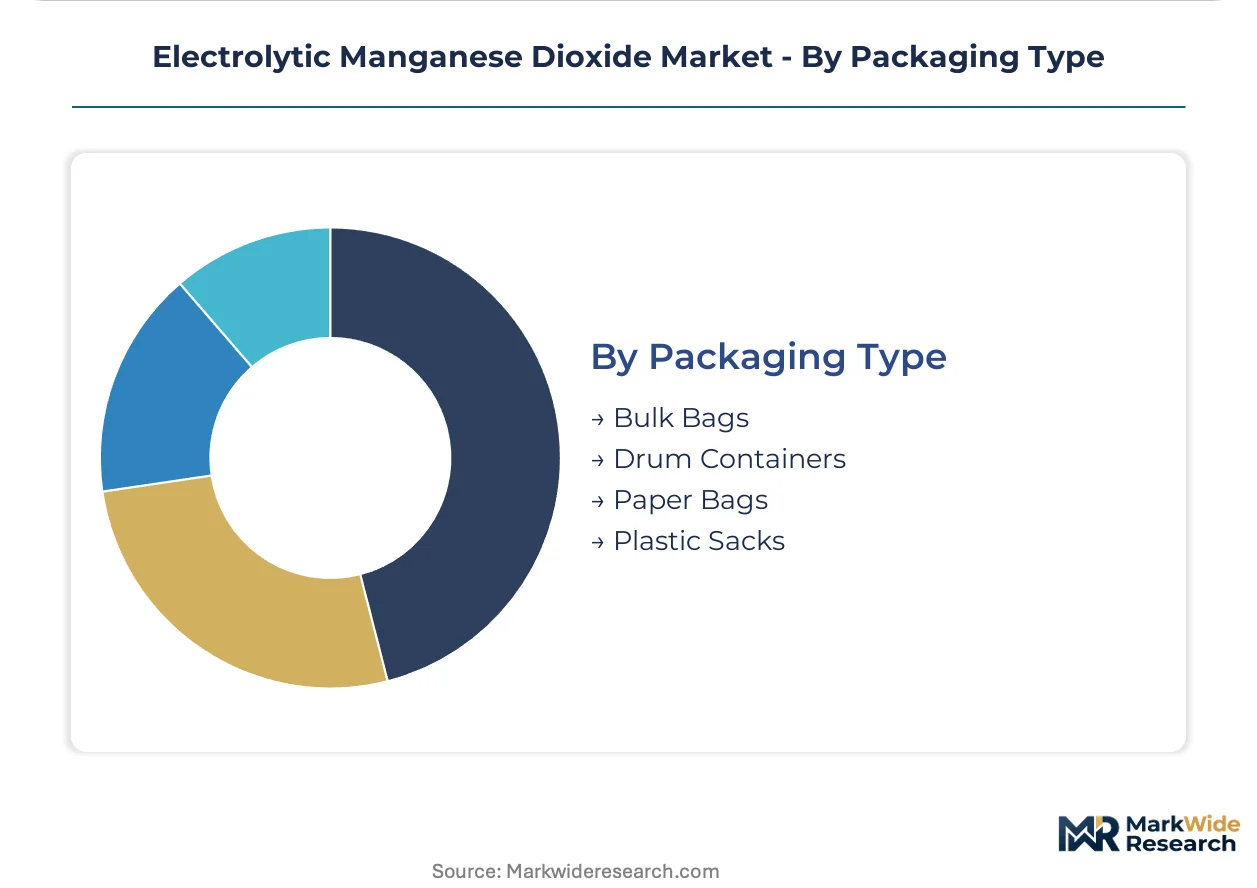
Packaging Type:
Supply chain configuration determines packaging selection, with bulk logistics favoring integrated producers and drum specifications serving qualified specialty volumes.
- Bulk Bags:Integrated manganese processing clusters in Hunan Province deploy bulk logistics for high-volume alkaline battery supply. Rail and riverine freight connections reduce unit logistics costs for captive ore-to-EMD operations.
- Drum Containers:High-purity synthetic EM for lithium-ion precursor applications requires sealed drum specifications to prevent moisture contamination during ocean freight to Korean and Japanese cathode plants.
- Paper Bags:Standard-grade material for chemical synthesis applications uses multi-wall paper packaging.
- Plastic Sacks:Intermediate volume shipments for regional battery assembly operations.
Shipment volumes concentrate in Bulk Bags; Drum Containers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xiangtan anchors the world's densest concentration of electrolytic manganese dioxide capacity, with integrated ore-to-cathode supply corridors radiating from Hunan Province to battery clusters across East Asia.
China
Hunan and Guizhou provinces host captive manganese processing operations supplying cathode precursor makers with battery-grade material. SAMR enforces tightening GB standards on purity and carbon intensity, forcing electrolysis plants to reconfigure energy-intensive operations. Xiangtan Electrochemical Technology leverages its integrated base to sustain cost advantages in qualified battery-grade output.
Japan
Specialty lithium-ion cathode applications drive demand for high-purity synthetic EM in Osaka and Nagoya industrial corridors. METI coordinates domestic stockpiling frameworks for critical battery minerals including manganese. Tosoh Corporation anchors synthetic EM production for premium automotive cell specifications requiring 99%+ purity thresholds.
South Korea
POSCO and LG Chem have locked in multi-year sulfate-to-EMD supply corridors from Chinese integrated producers. The country's cathode sector concentrates procurement through Japanese trading house underwritten capacity expansions. Seoul-based battery makers enforce 12-18 month qualification protocols that exclude speculative EMD entrants.
India
MOIL Limited operates manganese ore mining in Maharashtra and Madhya Pradesh under the PLI scheme for advanced chemistry cell production. The country's battery manufacturing push creates first-mover positioning for suppliers establishing local sulfate processing. Gujarat and Tamil Nadu are emerging as preferred locations for cathode precursor plant investments.
Germany
Eramet SA's European refining footprint navigates divergent regional purity standards through its integrated Gabonese ore assets. The EU Battery Regulation and REACH impose carbon footprint declarations and due diligence obligations on imported manganese products. Bavaria-based automotive cell plants demand traceable, low-carbon manganese sources under CBAM phase-in timelines.
Electrolytic Manganese Dioxide Market Key Industry Players
The competitive structure tilts toward integrated ore-to-EMD operators with captive power and sulfate processing. Market concentration reflects high capital barriers for electrolysis cell infrastructure and extended customer qualification cycles. Three archetypes dominate: Chinese integrated producers with backward ore control, Japanese synthetic EM specialists serving premium lithium-ion tiers, and European-African integrated miners competing on traceability metrics. Capacity expansion and long-term offtake contracting constitute the dominant competitive moves, with carbon-border positioning emerging as a secondary vector.
Among Chinese integrated producers, Xiangtan Electrochemical Technology Co., Ltd. and Guizhou Redstar Developing exemplify the ore-captive archetype with Hunan-Guizhou cluster positioning. Japanese synthetic EM capability is represented by Tosoh Corporation, which occupies the high-purity specialty tier. Eramet SA anchors the European-African integrated model, competing through Gabonese ore assets against Asian cost structures. These three company types illustrate how geographic resource access and process technology specialization segment competitive positioning across alkaline battery and lithium-ion precursor end-uses.
| Leading Market Players |
|---|
| Vibrantz Technologies, Inc. |
| Tronox Holdings plc |
| Xiangtan Electrochemical Technology Co., Ltd. |
| Eramet SA |
| Mesa Minerals Limited |
| Tosoh Corporation |
| Guizhou Redstar Developing |
| MOIL Limited |
| South Manganese Investment Limited |
Cost & Logistics Intelligence
Manganese sulfate spot prices on the Shanghai Metals Market cascade through electrolytic manganese dioxide supply chains into three distinct pricing tiers. Battery-grade material commands premiums tied to cathode precursor yield rates, while commodity alkaline grades track power costs in Hunan Province smelters.
Pricing Analysis
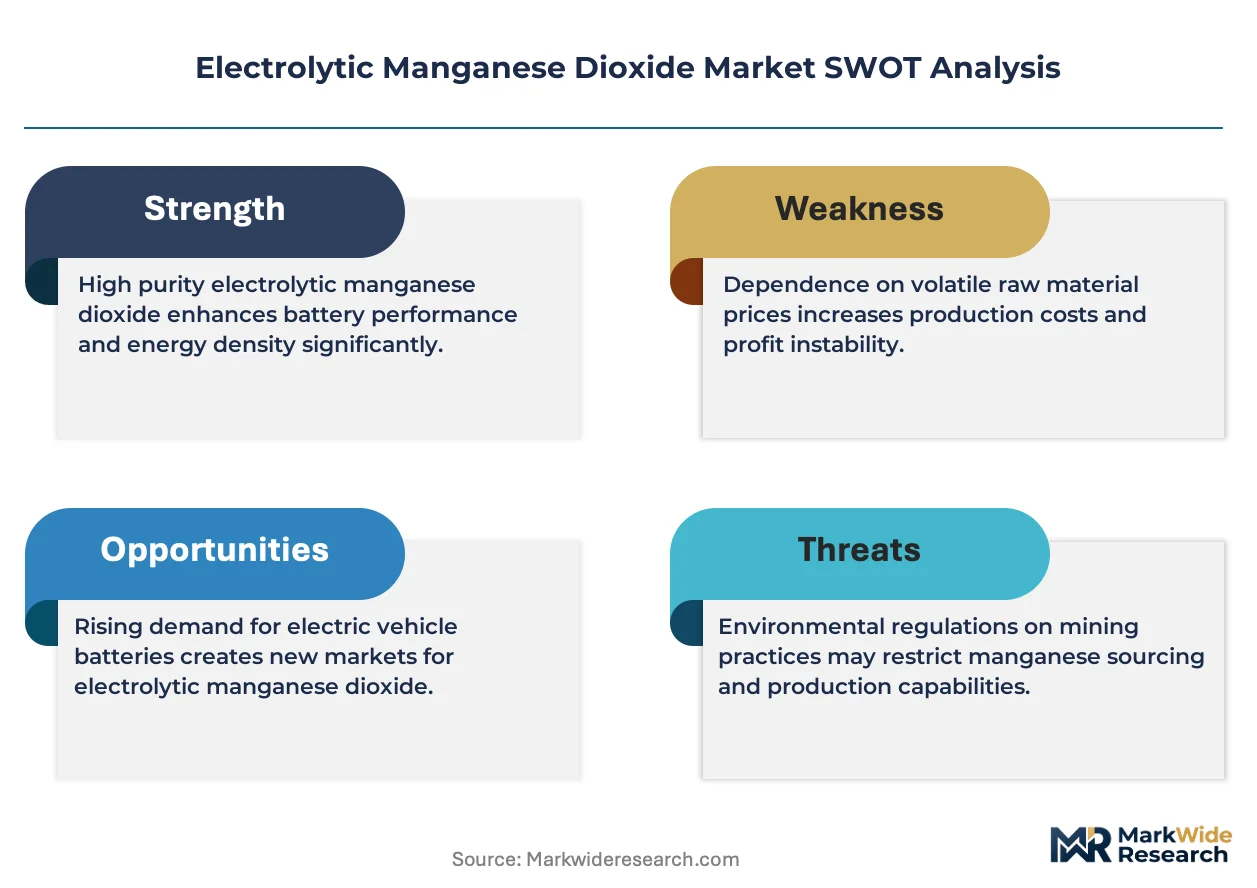
Yield-based pricing anchors battery-grade EMD contracts to lithium-ion cathode performance metrics. Three-tier pricing structure across premium synthetic EM, standard battery-grade EMD, and economy natural EM separates qualified precursor feedstock from alkaline cell commodity supply. Price differentiation rests on SAMR purity certification and carbon intensity disclosure under EU Battery Regulation. Cost compression in standard battery-grade material is intensifying because Hunan power tariffs are squeezing electrolysis margins. Alkaline battery manufacturers exhibit highest price sensitivity; specialty lithium-ion cathode makers accept premium positioning for traceable low-carbon material.
Supply Chain Analysis
Single-source vulnerability sits with high-grade manganese ore deposits clustered in Gabon, South Africa, and Australia's Groote Eylandt. Sulfate feedstock draws from these ore concentrations through seaborne bulk freight to Chinese processing clusters. Supply chain risk centers on geopolitical chokepoints for ore access and maritime logistics disruption through the Strait of Malacca. Distribution runs through long-term offtake contracts from integrated Hunan-Guizhou producers to East Asian cathode plants, displacing spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolytic manganese dioxide supply is tightening around electrolysis cell capacity constraints in China's industrial zones, propping pricing power for qualified producers with captive ore access.
For Market Incumbents: Deepen backward integration into Gabonese or Australian ore assets to secure sulfate feedstock independence from South African supply concentration. Expand electrolysis capacity in Guizhou Province where renewable power purchase agreements meet tightening SAMR carbon intensity benchmarks. Synthetic EM substitution in premium lithium-ion tiers threatens EMD's addressable premium segment; defend through faster qualification cycles with Korean and Japanese cathode makers. For New Entrants and Emerging Players: Direct manganese recovery from black mass recycling offers a technology-first wedge into secondary feedstock supply. Target India's PLI scheme for advanced chemistry cell production, where domestic sulfate processing capacity remains underdeveloped. Establish local EMD qualification with Gujarat and Tamil Nadu cathode precursor investments before 12-18 month validation protocols lock out speculative entrants. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated ore-to-EMD operators with captive power in Hunan Province. Long-term viability over the next decade hinges on carbon-border adjustment positioning for EU battery supply chain access. Watch for CBAM phase-in enforcement as the inflection signal separating traceable low-carbon producers from carbon-intensive competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Assets | Gabonese ore control secures sulfate feedstock against South African supply concentration. |
| Renewable Power Purchase Agreements | Guizhou hydropower contracts satisfy SAMR carbon intensity benchmarks for battery-grade output. |
| Long-term Supply Agreements | Japanese trading house underwritten capacity locks in exclusive volume allocation to Korean cathode makers. |
| Black Mass Recycling Integration | Manganese recovery loops from battery waste displace virgin ore demand for secondary EMD feedstock. |
| Carbon Border Adjustment Positioning | Scope 1-2 emissions data secures preferential EU market access under REACH and Battery Regulation. |
Research Approach
Independent corroboration across primary interviews with electrolysis plant managers, cathode precursor procurement leads, and battery cell technical directors, plus secondary validation through SAMR GB standard filings, EU Battery Regulation documentation, and Shanghai Metals Market price data, underwrites the qualitative findings. Bottom-up capacity modeling across Hunan and Guizhou processing clusters triangulates against top-down demand estimates from East Asian battery production databases.
Comparable-period anchoring to historical electrolysis utilization rates and power cost trajectories shaped the forecast window. The analysis models demand across product grade tiers, application channels from alkaline to lithium-ion, end-user qualification status, and regional production hub carbon intensity. CAGRs derive from segmented volume projections reconciled with cathode precursor capacity buildout announcements. Key inputs include electrolysis energy consumption benchmarks and ore grade degradation curves from major deposit regions.
Several conditions sit outside the modeled scope, including abrupt ore export restrictions from Gabon or South Africa, breakthrough synthetic EM cost reductions, and unanticipated battery chemistry shifts away from manganese-bearing cathodes. Forecasts reflect assumptions about SAMR enforcement continuity and EU CBAM implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Diamond Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Cesium Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Selenium Market