
 Manganese Sulfate Market | 2026-2036
Manganese Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Manganese Sulfate Market Outlook
Specialized chemical engineering talent is rotating toward battery-grade purification, constraining expansion timelines for agricultural and industrial-grade producers. CITIC Dameng leverages captive manganese ore reserves to sustain integrated cost positions across battery-grade output. Prince (ERACHEM Comilog) anchors Atlantic supply routes with European refining assets and long-standing fertilizer sector relationships. Guangxi Yuanchen Manganese Industry competes on volume scale in southern China's processing corridor.
Manganese sulfate is a divalent manganese salt of sulfuric acid, typically produced as the monohydrate (MnSO₄·H₂O) with manganese content ranging from 30–32% by weight via sulfuric acid leaching of manganese dioxide or carbonate ores; its primary purpose is as a micronutrient additive and, increasingly, as a precursor in lithium-ion battery cathode manufacturing. Battery-grade material commands the fastest expansion trajectory within product type segmentation, driven by cathode maker qualification programs and purity thresholds above 99.5% manganese content. Agricultural-grade applications retain volume leadership but face margin compression from commoditization and regional oversupply in fertilizer markets. Powder-form sulfate dominates logistics and dissolution efficiency for battery precursor producers, while dihydrate variants maintain niche positions in specialty chemical synthesis.
China's SAMR enforces evolving GB standards for battery material purity that filter qualified suppliers and redirect investment toward hydrometallurgical upgrading capacity. REACH registration requirements in Europe and EPA hazardous substance reporting in the United States impose divergent compliance burdens on exporters, fragmenting certification costs across destination markets. Stakeholders must monitor cathode chemistry roadmaps from major cell producers, as shifts in manganese-to-nickel ratios will recalibrate grade-specific demand volumes faster than processing capacity can adapt.
Market Dynamics
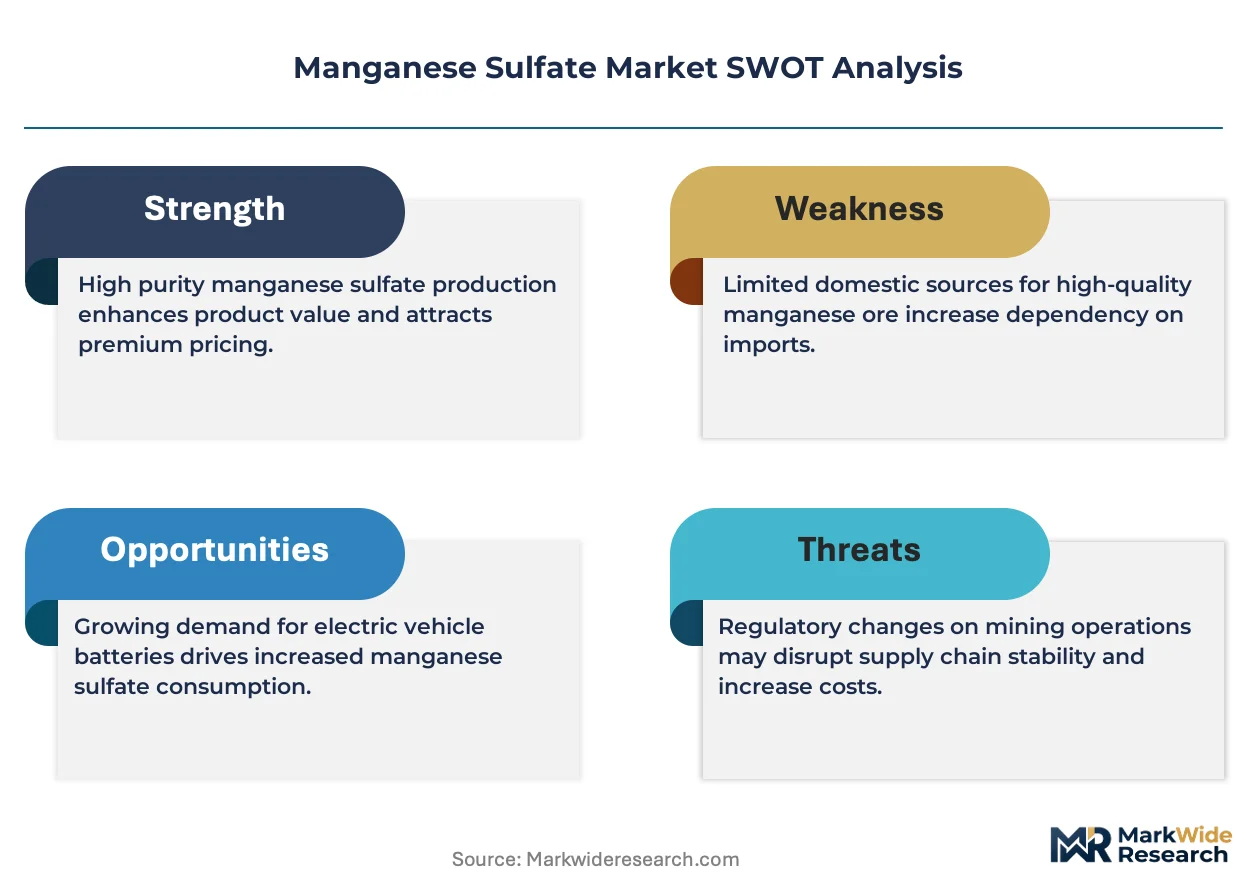
The manganese sulfate market is being fundamentally restructured by the cathode chemistry pivot toward high-manganese formulations, which is concentrating demand qualification around battery-grade purity thresholds and compressing agricultural-grade margins.
Growth Catalysts
- China's dual carbon goals:National emissions targets are accelerating investment in electric vehicle supply chains, directly expanding procurement of battery-grade manganese sulfate for cathode manufacturing.
- High-manganese cathode chemistries:Cell producers are reformulating nickel-manganese-cobalt ratios to reduce cobalt dependence, elevating manganese content requirements in precursor specifications.
- Hunan and Guizhou processing clusters:Integrated mining-to-sulfate infrastructure in these provinces is lowering logistics costs and shortening qualification timelines for battery material buyers.
Market Restraints
- Sulfuric acid cost volatility:Input price swings for the primary leaching reagent compress margins for non-integrated producers lacking captive acid supply.
- Chinese supply concentration:Overreliance on Hunan and Guizhou processing corridors creates geographic risk exposure for qualified suppliers outside these clusters.
- REACH registration friction:European chemical compliance requirements impose divergent certification burdens that fragment market access costs for exporters.
Strategic Opportunities
- Atlantic supply route development:European refining assets can anchor alternative supply chains for battery producers seeking geographic diversification from Chinese dominance.
- Agricultural-grade premiumization:Specialty micronutrient formulations for precision farming applications offer margin recovery paths beyond commodity fertilizer markets.
- GB standards alignment:Early adoption of China's evolving battery material purity regulations positions suppliers for accelerated qualification with domestic cathode makers.
Industry Challenges
- Hydrometallurgical purification expertise:The specialized chemical engineering talent required for battery-grade production is rotating away from agricultural and industrial-grade facilities, constraining their expansion timelines.
- Cathode chemistry roadmap uncertainty:Rapid shifts in manganese-to-nickel ratio specifications are recalibrating grade-specific demand volumes faster than processing capacity can adapt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manganese Sulfate Market |
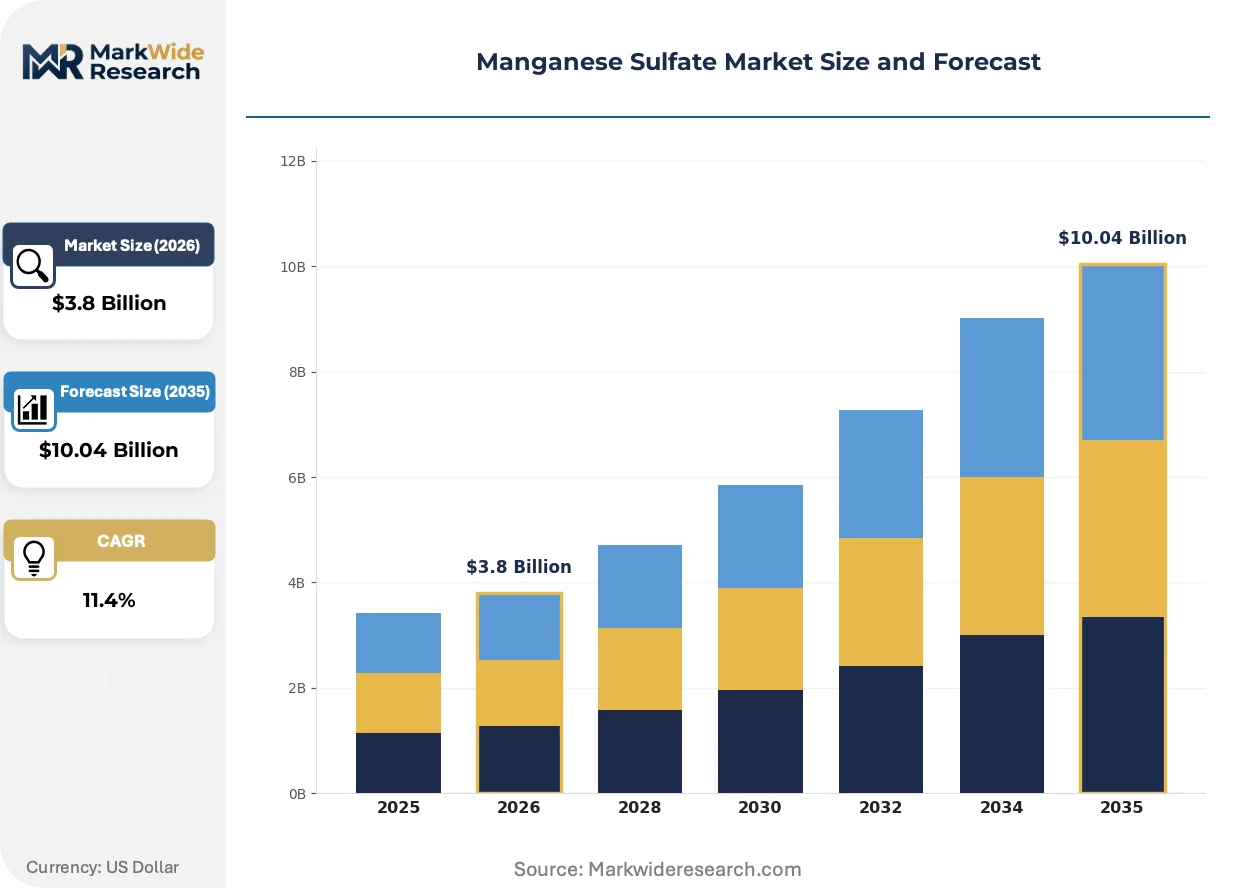
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Battery Grade, Industrial Grade, Agricultural Grade Application: Animal Nutrition, Fertilizers, Electronics, Chemicals End User: Agriculture Sector, Chemical Manufacturers, Battery Producers, Feed Suppliers Form: Sulfate, Monohydrate, Dihydrate, Powder |
| Companies Covered | Paul Lohmann GmbH & Co. KGaA, CITIC Dameng, Prince (ERACHEM Comilog), Guangxi Yuanchen Manganese Industry, Element 25, Guizhou Dalong Huicheng New Material, Xiangtan Electrochemical Technology, ISKY Chemicals, Vibrantz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manganese Sulfate Market Strategic Shifts
Battery-grade purification technology is actively splitting the manganese sulfate market into parallel supply tiers, with diverging equipment, talent, and certification requirements separating qualified from commodity producers.
Solvent extraction and crystallization systems for battery-grade manganese sulfate is bifurcating the competitive landscape. Cathode precursor manufacturers are adopting these hydrometallurgical upgrading methods at accelerating pace to meet purity thresholds above 99.5% manganese content. This technological divide is compressing margins for legacy thermal processing routes while concentrating margin capture among integrated ore-to-sulfate operators with captive feedstock control.
China's SAMR enforcement of evolving GB standards for battery material purity is filtering qualified suppliers and redirecting capital toward purification capacity. The industrial consequence is a widening compliance gap between hydrometallurgical upgraders and conventional producers. Battery-grade product categories face the steepest certification burden, with domestic cathode makers responding by consolidating supplier relationships around pre-qualified integrated processors.
Long-term offtake contracting is displacing spot market procurement for battery-grade material. Tier-one cathode producers are locking in multi-year supply agreements directly with integrated manganese miners, compressing trading house margins and shortening qualification windows for new entrants. This behavioral shift is most visible in China's southern processing corridor, where Hunan and Guizhou-based suppliers are securing priority allocation through direct cell maker relationships.
Manganese Sulfate Market Segmentation
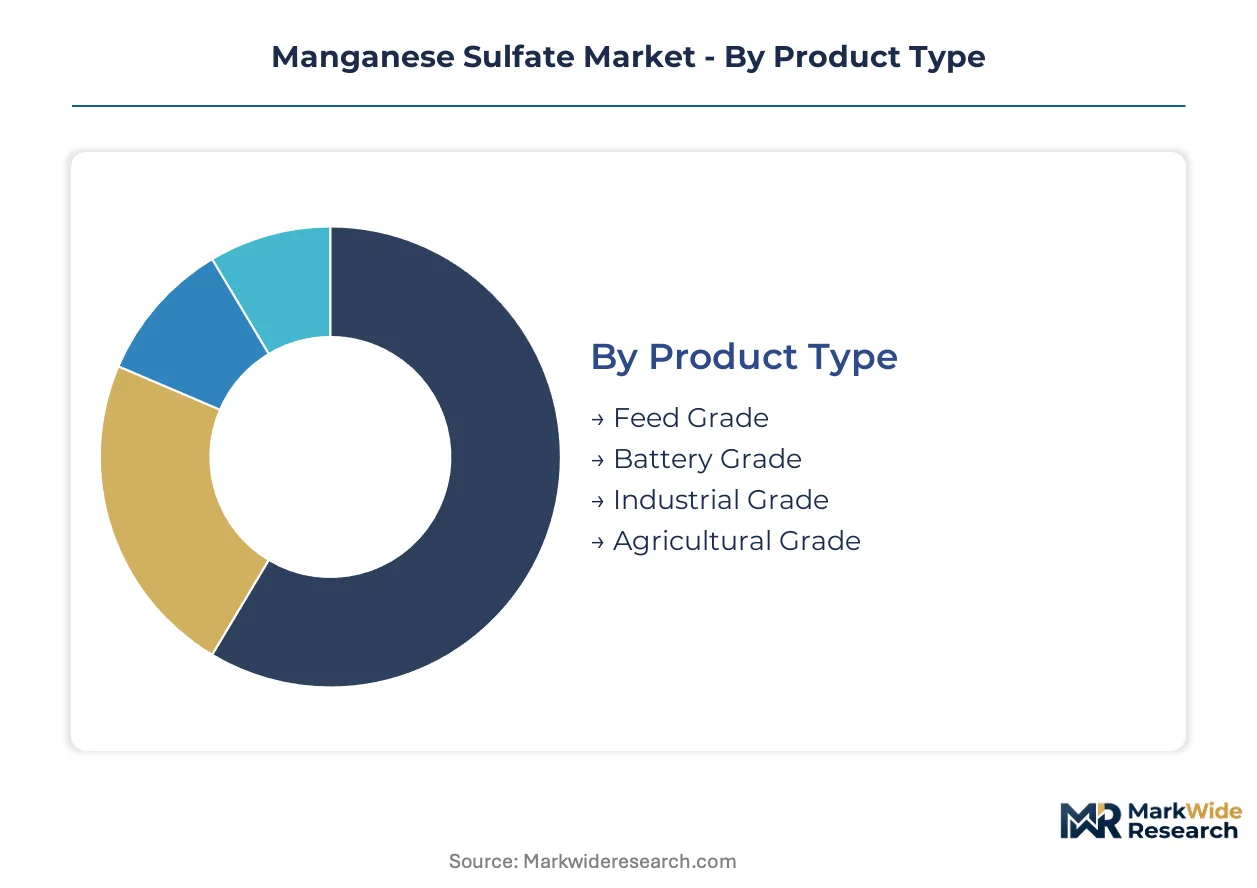
Manganese sulfate demand fragments sharply across purity tiers, with battery-grade specifications diverging from legacy agricultural and industrial applications. Cathode chemistry roadmaps are compressing qualification windows for higher-purity segments while commoditizing lower-grade categories.
Product Type:
Battery-grade material faces the weakest substitution threat due to irreplaceable manganese content in high-nickel cathode formulations, while agricultural and feed grades confront direct competition from alternative micronutrient compounds.
- Battery Grade:Purity thresholds exceed 99.5% manganese content via hydrometallurgical purification, with demand concentrating in China's Hunan and Guizhou processing corridors where integrated ore-to-sulfate infrastructure shortens cathode maker qualification timelines.
- Agricultural Grade:Standard 30–32% manganese content formulations serve bulk fertilizer blending, facing margin compression from regional oversupply in commodity nutrient markets and substitution pressure from chelated micronutrient alternatives.
- Feed Grade:Animal nutrition specifications balance bioavailability with cost, primarily procured by integrated feed compounders in North American and European livestock sectors.
- Industrial Grade:Chemical synthesis and pigment applications require intermediate purity, sourced through spot market procurement with limited long-term contracting.
Agricultural grade anchors the volume base while battery grade gains share at the steepest rate.
Application:
Cost tier differentiation separates high-value electronics precursors from bulk nutrient applications, with purity premiums widening between technical and commodity uses.
- Fertilizers:Bulk blending operations in Brazil, India, and the United States consume the largest volume share, with procurement patterns tied to seasonal planting cycles and phosphate fertilizer pricing correlations.
- Electronics:Cathode precursor manufacturing commands the steepest purity premiums, with manganese sulfate serving as the primary manganese source in nickel-manganese-cobalt and lithium-manganese-oxide cell formulations.
- Animal Nutrition:Swine and poultry feed formulations incorporate manganese sulfate for bone development and enzyme function, with regulatory maximums set by the FDA in the United States and EFSA in Europe.
- Chemicals:Specialty synthesis applications including manganese dioxide production and paint drier manufacturing require consistent grade specifications with moderate volume scale.
Fertilizer applications anchor the volume base while electronics precursors expand most quickly.
End User:
Customer type concentration is accelerating around battery producers, with procurement centralization compressing margins for distributors serving fragmented agricultural and chemical accounts.
- Battery Producers:CATL, BYD, and LG Energy Solution are consolidating supplier relationships around pre-qualified integrated processors, locking in multi-year offtake agreements that displace spot market procurement.
- Agriculture Sector:Regional fertilizer distributors and cooperatives purchase agricultural-grade material with price sensitivity and seasonal demand volatility.
- Chemical Manufacturers:Specialty and commodity chemical producers require consistent industrial-grade supply with moderate purity tolerances.
- Feed Suppliers:Integrated animal nutrition companies procure feed-grade manganese sulfate as part of premix formulations with strict traceability requirements.
Agriculture sector demand anchors the volume base while battery producers drive the steepest share gains.
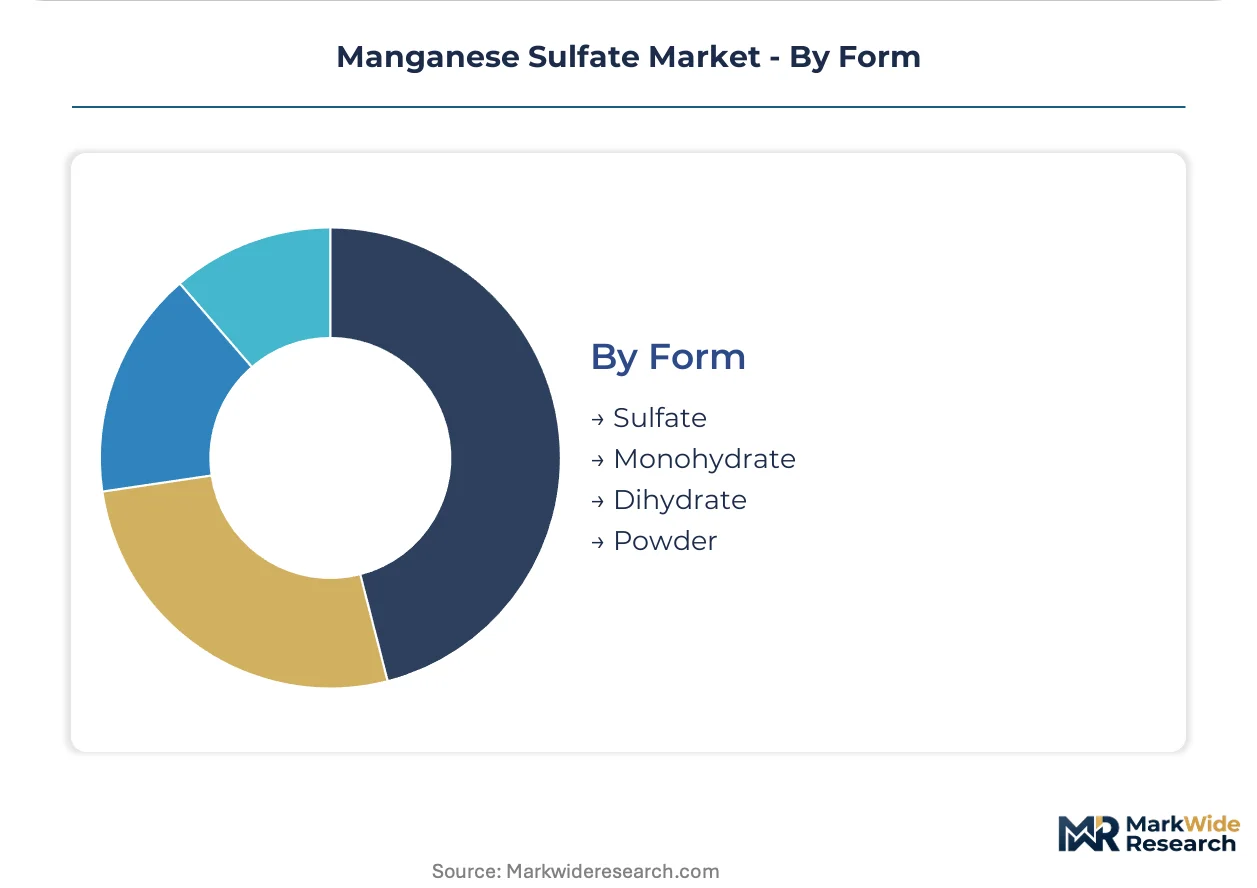
Form:
Logistics efficiency and dissolution rates separate powder and monohydrate specifications from dihydrate and unprocessed sulfate variants.
- Monohydrate:MnSO₄·H₂O with 30–32% manganese content serves battery precursor dissolution with controlled moisture specifications, dominating cathode manufacturer procurement.
- Powder:Fine particle size distribution optimizes dissolution kinetics for battery-grade applications and blending uniformity in fertilizer manufacturing.
- Dihydrate:MnSO₄·2H₂O maintains niche positions in specialty chemical synthesis where crystalline structure affects reaction pathways.
- Sulfate:Unprocessed or partially refined material serves lowest-cost industrial applications with minimal purity requirements.
Monohydrate specifications anchor the volume base while powder form climbs fastest in battery-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese processors command substantial pricing leverage over Atlantic suppliers due to integrated ore-to-sulfate infrastructure and shorter qualification timelines. European refiners absorb compliance premiums from REACH registration while competing for battery maker offtake. Regional supply chains diverge sharply on input cost structures and regulatory burden distribution.
China
Battery-grade demand concentrates in Hunan and Guizhou provinces where mining-to-processing clusters serve domestic cathode makers. SAMR enforcement of evolving GB standards filters qualified suppliers and redirects capital toward hydrometallurgical upgrading capacity. Xiangtan Electrochemical Technology and Guizhou Dalong Huicheng New Material anchor the southern processing corridor with integrated operations.
United States
Domestic battery producers accelerate procurement of qualified sulfate material as IRA domestic content incentives reshape cathode supply chain geography. EPA hazardous substance reporting imposes divergent compliance burdens that fragment certification costs for importers. Midwest and Southeast battery plant investments are pulling qualification timelines forward for potential Atlantic suppliers.
Germany
European cathode manufacturers source through Rotterdam and Antwerp entry points with REACH-registered material commanding logistics premiums. ECHA chemical compliance requirements filter market access for non-EU exporters and consolidate buyer relationships around pre-qualified processors. Bavarian and North Rhine-Westphalian industrial zones host specialty chemical distributors managing sulfate procurement for battery precursor operations.
Australia
High-purity manganese ore exports from Western Australia feed Asian sulfate refineries with concentrate grades supporting battery-grade output specifications. The country's national mining regulator enforces tailings and environmental standards that shape project development timelines for integrated sulfate ventures. Perth-based developers are advancing mine-to-sulfate proposals targeting South Korean and Japanese cathode maker qualification programs.
South Korea
LG Energy Solution and POSCO Chemical anchor sulfate demand through direct offtake contracting with Chinese and Australian suppliers. MFDS industrial chemical standards and METI-aligned battery material specifications create multi-layered compliance requirements for imported material. Gyeonggi-do and Ulsan industrial complexes concentrate precursor manufacturing capacity with just-in-time sulfate logistics requirements.
Manganese Sulfate Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the manganese sulfate market. Integrated ore-to-sulfate operators with captive manganese reserves capture margin through feedstock control, while hydrometallurgical specialists command premium positioning via purification expertise. The competitive structure separates into three strategic archetypes: integrated miners with downstream sulfate assets, standalone refiners serving spot agricultural markets, and battery-grade purification specialists. Dominant competitive moves include backward integration into manganese mining and long-term offtake contracting with tier-one cathode producers.
Among Chinese integrated operators, CITIC Dameng and Guangxi Yuanchen Manganese Industry exemplify the ore-captive archetype with cost positions anchored in southern processing infrastructure. Prince (ERACHEM Comilog) occupies a position representing Atlantic supply route development with European refining assets and established fertilizer sector relationships. Paul Lohmann GmbH & Co. KGaA sits within the specialty chemical tier serving pharmaceutical and high-purity industrial applications with German regulatory compliance credentials.
| Leading Market Players |
|---|
| Paul Lohmann GmbH & Co. KGaA |
| CITIC Dameng |
| Prince (ERACHEM Comilog) |
| Guangxi Yuanchen Manganese Industry |
| Element 25 |
| Guizhou Dalong Huicheng New Material |
| Xiangtan Electrochemical Technology |
| ISKY Chemicals |
| Vibrantz |
| Others |
Value Chain & Pricing Dynamics
China's evolving GB standards for battery material purity operate as a dual gatekeeper, filtering qualified suppliers while simultaneously stratifying price premiums across purity tiers. SAMR enforcement redirects capital toward hydrometallurgical upgrading capacity, compressing margins for legacy thermal processors unable to meet certification thresholds.
Pricing Analysis
The customization-premium spread in manganese sulfate separates battery-grade configured-to-order material from standard agricultural-grade bulk supply. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds, with battery-grade specifications exceeding 99.5% manganese content commanding substantial premiums over 30-32% standard formulations. Cost compression in agricultural-grade tiers is intensifying because regional oversupply in fertilizer markets erodes spot pricing power. Regional fertilizer distributors exhibit the highest price sensitivity, while tier-one cathode producers prioritize qualification security over unit cost.
Supply Chain Analysis
China and Australia anchor manganese sulfate supply chains through divergent production models—integrated ore-to-sulfate clusters in Hunan and Guizhou versus high-purity ore exports from Western Australia. Processing draws from sulfuric acid leaching reagents, manganese dioxide or carbonate ores, and crystallization energy inputs. Single-source vulnerability concentrates in China's southern processing corridor, where Hunan and Guizhou-based integrated operators control qualified battery-grade output. Distribution runs through direct long-term offtake contracting with tier-one cathode makers, displacing spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The manganese sulfate market is entering a cyclical recovery phase as cathode chemistry roadmaps pivot toward high-manganese formulations, with electric vehicle procurement cycles driving demand normalization after agricultural-grade oversupply compression.
For Market Incumbents: Compound defensive positioning through backward integration into captive manganese ore reserves and accelerated GB standards alignment to pre-qualify with domestic cathode makers. CITIC Dameng's integrated cost structure demonstrates how ore control insulates margin from sulfuric acid volatility. Hydrometallurgical purification expertise scarcity threatens expansion timelines for non-integrated competitors. For New Entrants and Emerging Players: Battery-grade tolling services for qualified ore feedstock represent a service-layer gap where incumbents under-serve, creating white-space for purification specialists without mining assets. Atlantic supply route development for European cathode makers offers geographic diversification demand. Agricultural-grade premiumization through precision farming micronutrient formulations provides the most penetrable segment. A go-to-market angle anchored to REACH-registered European refining assets bypasses Chinese supply concentration risks. For Investors and Strategic Acquirers: China's dual carbon goal enforcement reshapes the acquisition landscape by accelerating capital deployment toward battery material supply chains. Long-term viability centers on integrated ore-to-sulfate operators with pre-qualified cathode maker relationships and hydrometallurgical purification capabilities. The signal to watch is cathode chemistry roadmap announcements from major cell producers, as manganese-to-nickel ratio shifts recalibrate grade-specific demand volumes faster than processing capacity adaptation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Mining | CITIC Dameng demonstrates how captive ore reserves sustain integrated cost positions across battery-grade output. |
| Hydrometallurgical Upgrading Capacity Expansion | Guizhou Dalong Huicheng's purification investments align with SAMR's evolving GB standards for battery material purity. |
| Atlantic Supply Route Development | Prince's European refining assets anchor alternative supply chains for battery producers seeking geographic diversification. |
| Long-term Offtake Contracting with Cathode Makers | CATL and BYD procurement centralization compresses trading house margins and shortens qualification windows. |
| Agricultural-grade Premiumization Programs | Specialty micronutrient formulations for precision farming recover margins beyond commodity fertilizer markets. |
Study Parameters
A standing panel of cathode precursor procurement managers, hydrometallurgical plant engineers, fertilizer distribution channel heads, and SAMR regulatory compliance officers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade records, SEC 10-K filings from listed manganese processors, and GB standards documentation from China's Standardization Administration. Bottom-up capacity modeling and top-down demand triangulation from cathode maker expansion announcements ensured cross-verification.
Consistency checks validated volume and value outputs against external benchmarks including EIA mineral commodity summaries and IEA critical minerals tracking data. The analytical framework segmented across grade tier, end-use application, form specification, and regional production hub throughout the projection horizon. CAGRs were derived from segmented demand modeling incorporating cathode chemistry roadmap assumptions and electric vehicle production trajectories. Industry-specific inputs included manganese-to-nickel ratio specifications from tier-one cell producers and sulfuric acid cost volatility indices.
Forecasts assume regulatory continuity in China's SAMR enforcement of GB standards and REACH registration requirements in Europe; material policy shifts would require re-modeling. Specific risks that could revise projections include rapid cathode chemistry pivots away from high-manganese formulations, trade restriction escalation affecting Chinese supply routes, or sustained sulfuric acid price spikes compressing non-integrated processor margins. Recalibration cycles align with material shifts in cathode maker qualification programs and national emissions policy implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Global Sodium Sulfate Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Sodium Ferrocyanide Market