
 Global Chromium Salt Market | 2026-2036
Global Chromium Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chromium Salt Market Foresight
ISO 9001 certification is rotating as a baseline qualification for chromium salt suppliers seeking entry into European leather and metal finishing supply chains. Lanxess AG leverages its backward integration into chromite ore processing to sustain cost advantages across German and Belgian production sites. Vishnu Chemicals anchors its position through captive sodium dichromate capacity serving South Asian tanneries. Elementis plc differentiates via specialized chromium sulfate grades for North American metal finishing applications.
Chromium salts comprise inorganic compounds derived from chromite ore processing, primarily existing in hexavalent and trivalent oxidation states with specifications governing Cr(VI) content below regulatory thresholds for skin-contact applications. These salts function as essential inputs for leather tanning, corrosion-resistant metal coatings, and pigment manufacturing where cross-linking and oxidation properties prove critical. Sodium dichromate dominates volume flows due to its role as an intermediate feedstock for downstream chromium derivatives, while chromium sulfate gains share in leather tanning as tanneries shift toward reduced-toxicity formulations. Pigments and metal finishing applications occupy mature demand positions with stable offtake patterns, whereas catalyst applications in chemical synthesis plants represent an emerging margin pool as refiners seek sulfur-tolerant reforming additives.
REACH regulations in the European Union restrict hexavalent chromium compounds in consumer goods, while EPA oversight in the United States governs discharge limits from electroplating facilities under effluent guidelines. India's Central Pollution Control Board enforces chrome effluent standards for Kanpur tanneries, creating compliance-driven demand for recovery systems and modified salt formulations. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chromium oxidation states and application segments face expanding restrictions versus grandfathered exemptions.
Market Dynamics
The chromium salt market pivots on tightening REACH thresholds for hexavalent chromium in skin-contact applications, forcing tanneries across Germany, Italy, and India to reformulate toward trivalent sulfate alternatives while maintaining leather performance specifications.
Growth Catalysts
- REACH compliance deadlines:European footwear brands are mandating Cr(VI)-free supply chains, accelerating sulfate-based tanning chemical demand from Kanpur-Unnao clusters serving export contracts.
- Chrome recovery systems:India's Central Pollution Control Board enforcement of zero-liquid-discharge norms is driving capital deployment into effluent treatment infrastructure that regenerates chromium for reuse.
- Sodium dichromate intermediates:Pigment manufacturers in China and the United States require consistent dichromate feedstock for chrome oxide green production serving aerospace coatings.
Market Restraints
- Chromite ore supply concentration:South African and Kazakh ore deposits dominate metallurgical-grade feedstock, exposing processors to export duty volatility and logistics bottlenecks.
- Substitution by synthetic tannins:Vegetable and polymer-based tanning agents from specialty chemical suppliers are capturing niche segments in luxury leather where chrome-free labeling commands premium positioning.
- Capital intensity of effluent compliance:Small and mid-scale tanneries in Bangladesh and Pakistan face stranded asset risk as membrane filtration and chemical precipitation systems require seven-figure installation commitments.
Strategic Opportunities
- Underpenetrated African markets:Ethiopian and Nigerian leather sectors lack integrated chromium chemical supply chains, creating first-mover potential for sulfate formulation suppliers establishing local blending facilities.
- Catalyst applications in refining:Sulfur-tolerant reforming additives using chromium-based catalysts are gaining traction among Middle Eastern and U.S. Gulf Coast refiners processing high-sulfur crude slates.
- EU Green Deal chemistry incentives:The European Commission's sustainable chemistry funding windows favor closed-loop chromium recovery processes, rewarding producers with demonstrated circular material flows.
Industry Challenges
- Analytical chemist shortage:Cr(VI) detection at ppb levels requires inductively coupled plasma mass spectrometry expertise that tannery quality control departments struggle to recruit and retain.
- ISO 9001 certification timelines:European supply chain qualification cycles now stretch 18-24 months as brands layer Cr(VI) management system audits atop existing quality protocols.
- Legacy sulfate inventory compatibility:Tanneries switching between hexavalent and trivalent process chemistries face vessel contamination risks requiring complete tank farm reconditioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chromium Salt Market |
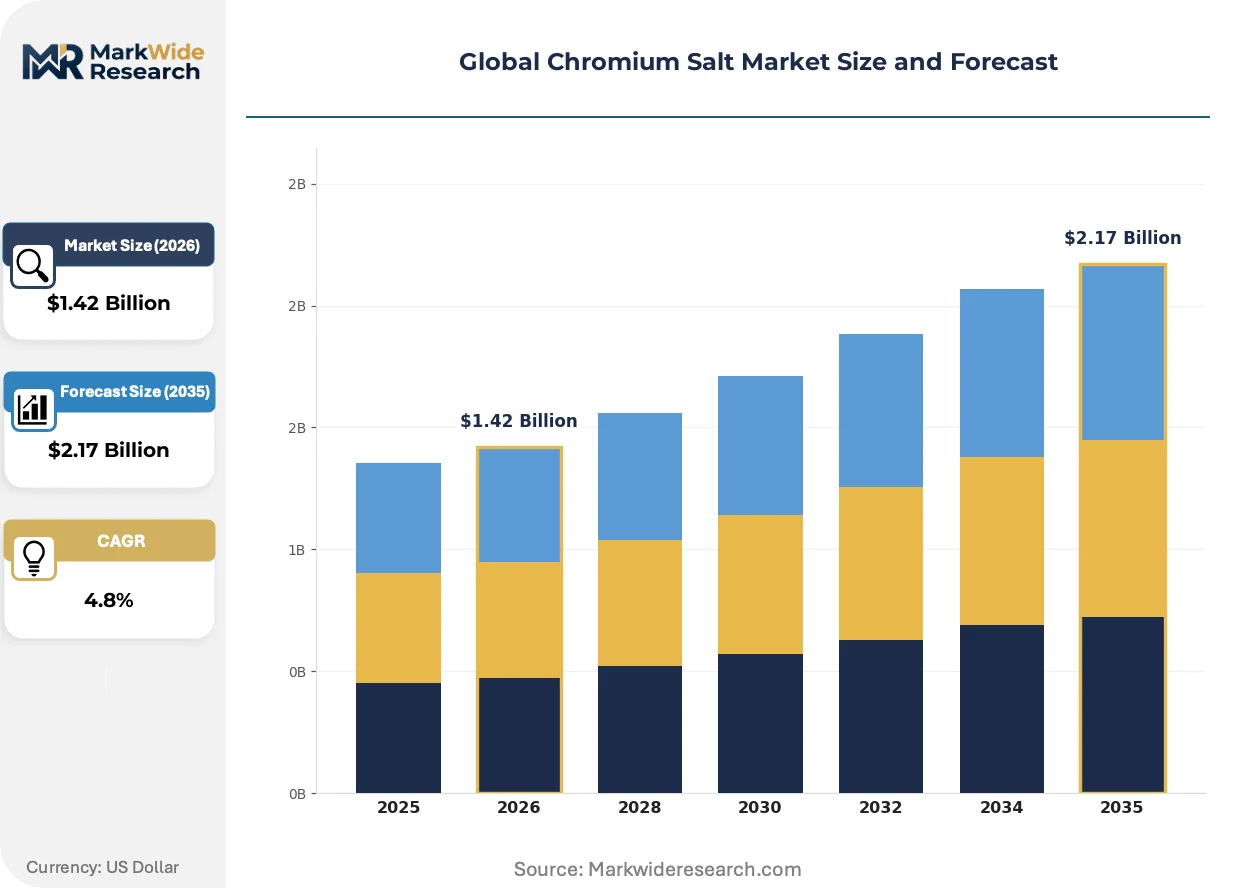
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromium Trioxide, Sodium Dichromate, Chromic Acid, Potassium Dichromate, Chromium Sulfate Application: Leather Tanning, Pigments, Wood Preservation, Metal Finishing, Catalysts, Textile Dyeing End User Industry: Leather Manufacturers, Paint Producers, Timber Treatment Facilities, Electroplating Units, Chemical Synthesis Plants Packaging Type: Drums, Bags, Bulk Containers, Carboys, Fiber Drums |
| Companies Covered | Lanxess AG, Elementis plc, Vishnu Chemicals, Hubei Zhenhua Chemical, Sichuan Yinhe Chemical, American Elements, Nippon Chemical Industrial, Merck KGaA, Soda Sanayii A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chromium Salt Market Shifts & Advancements
Formulation chemistry and regulatory detection protocols are diverging sharply as tanneries pursue simultaneous compliance with diverging Cr(VI) limits across export destinations.
Chromium sulfate complexes with masked basicity are bifurcating the leather chemical market between high-performance automotive upholstery specifications and cost-optimized footwear applications. German and Italian tanneries serving BMW and Ferrari seating contracts are adopting polymer-stabilized sulfate grades that maintain shrinkage resistance above 100°C, while Indian bulk producers for mass-market shoes prioritize standard sulfate with reduced masking agent loadings. This technical divergence is compressing mid-tier formulation suppliers unable to serve both performance tiers.
ECHA's 2023 update to REACH Annex XVII restricted hexavalent chromium in leather articles to 3 mg/kg, down from previous 10 mg/kg thresholds. The regulation forces testing laboratories to deploy ion chromatography post-column derivatization methods with detection limits below 0.5 mg/kg. Italian testing houses in Arzignano and Santa Croce sull'Arno are investing in automated sample preparation robotics to handle volume surges from brand-mandated batch testing.
Brand-led supply chain auditing is displacing transactional spot purchasing in European leather procurement. Kering and LVMH now require quarterly Cr(VI) test reports from direct chemical suppliers rather than relying on tannery certificates, shifting verification costs upstream. This behavioral change concentrates contract volumes with sulfate producers maintaining in-house ISO 17025 analytical capabilities, visible most acutely in chemical supply agreements for Portuguese and Spanish tanneries serving luxury goods houses.
Global Chromium Salt Market Segmentation
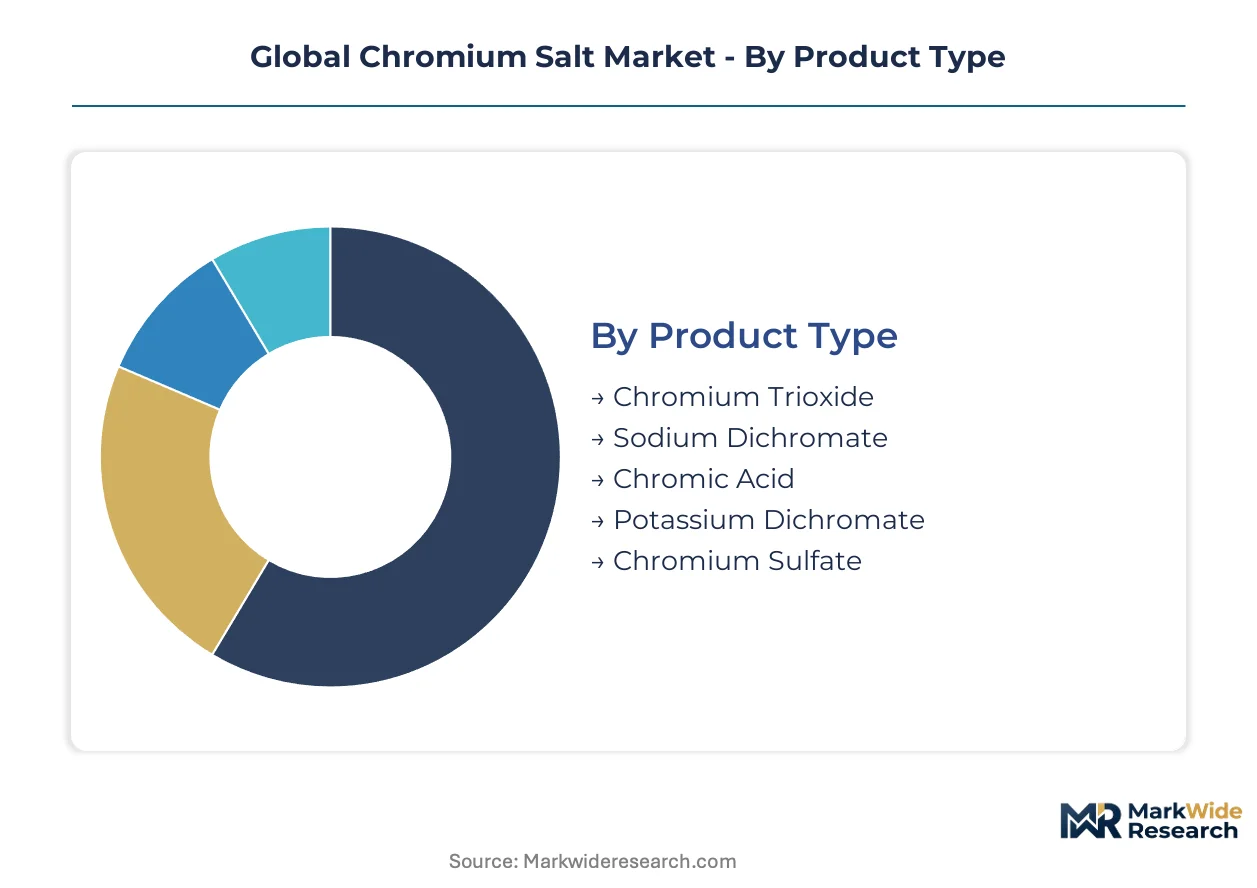
Chromium salt procurement patterns diverge sharply between domestic bulk consumers and export-oriented processors. Segmentation reveals how REACH compliance in Germany and Italy is restructuring product mixes, while Kanpur-Unnao tanneries drive volume concentration for specific salt grades.
Product Type:
Sodium dichromate and chromium sulfate anchor domestic consumption in India and China, while chromium trioxide and chromic acid flow predominantly toward export destinations with stringent purity specifications.
- Sodium Dichromate:An orange crystalline intermediate serving as the primary feedstock for downstream chromium derivatives manufacturing. Kanpur-Unnao leather clusters and Chinese pigment producers absorb the heaviest volumes, though REACH Cr(VI) restrictions are compressing growth in skin-contact applications.
- Chromium Sulfate:A trivalent salt complex employed in reduced-toxicity tanning formulations. German and Italian tanneries serving BMW and Ferrari contracts are migrating toward polymer-stabilized sulfate grades, while Indian bulk footwear producers prioritize standard formulations with lower masking agent loadings.
- Chromium Trioxide:A hexavalent oxide deployed in electroplating baths and metal finishing applications requiring hard chrome deposition.
- Chromic Acid:A strong oxidizing agent utilized in anodizing aluminum and specialized etching processes.
- Potassium Dichromate:A laboratory and photographic chemical with declining industrial relevance outside niche analytical applications.
Sodium dichromate commands the established base. The steepest expansion runs through chromium sulfate.
Application:
Leather tanning absorbs the dominant share of trivalent sulfate flows, while pigments and metal finishing maintain steady offtake for hexavalent intermediates in non-contact industrial uses.
- Leather Tanning:Cross-linking collagen fibers to produce shrinkage-resistant hides. Italian Arzignano and Santa Croce sull'Arno tanneries are qualifying sulfate suppliers through 18-24 month ISO 9001 plus Cr(VI) management audits, concentrating contract volumes with analytically capable producers.
- Pigments:Chrome oxide green synthesis for aerospace and industrial coatings. Chinese and U.S. manufacturers require consistent dichromate feedstock quality, with EPA discharge limits governing electroplating effluent from pigment precursor production.
- Wood Preservation:Chromated copper arsenate formulations for timber treatment, facing substitution pressure from copper-based alternatives.
- Metal Finishing:Decorative and hard chrome plating applications governed by EPA effluent guidelines in the United States.
- Catalysts:Sulfur-tolerant reforming additives for petroleum refining, gaining traction among Middle Eastern and U.S. Gulf Coast processors handling high-sulfur crude slates.
- Textile Dyeing:Mordant applications for color fixation, largely displaced by synthetic alternatives in mainstream apparel.
Leather tanning retains the volume anchor position. Catalyst applications are climbing the fastest as refiners seek sulfur-tolerant process chemistry.
End User Industry:
Leather manufacturers and electroplating units operate under the tightest regulatory scrutiny, while chemical synthesis plants represent an emerging demand pocket with less mature compliance frameworks.
- Leather Manufacturers:Kanpur-Unnao clusters serving Italian and German footwear brands. India's Central Pollution Control Board zero-liquid-discharge enforcement is mandating chrome recovery system investments that regenerate chromium for reuse.
- Paint Producers:Chrome oxide green consumers in aerospace and protective coatings, requiring batch consistency for high-temperature performance specifications.
- Timber Treatment Facilities:Preservative chemical applicators facing regulatory phase-out of chromated arsenical formulations in residential construction.
- Electroplating Units:Decorative and functional chrome platers governed by EPA discharge limits in the United States and REACH authorization requirements in the European Union.
- Chemical Synthesis Plants:Refinery and petrochemical operators deploying chromium-based catalysts for reforming and oxidation reactions.
Leather manufacturers anchor current demand. Chemical synthesis plants are gaining share fastest as sulfur-tolerant refining applications commercialize.
Packaging Type:
Bulk containers dominate high-volume flows to integrated tanneries and pigment plants, while drums and bags serve fragmented downstream processors with smaller batch requirements.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for Kanpur-Unnao tanneries and Chinese pigment manufacturers with direct rail or pipeline feedstock connections.
- Drums:Steel and plastic drum shipments for electroplating units and mid-scale leather processors requiring controlled moisture protection.
- Bags:Multi-wall paper and woven polypropylene packaging for wood treatment facilities and textile dyers with lower volume requirements.
- Carboys:Glass and plastic carboy deliveries for laboratory and analytical-grade potassium dichromate.
- Fiber Drums:Lightweight cylindrical packaging for specialty chromium sulfate grades with modified basicity specifications.
Bulk containers dominate volume throughput. Fiber drums are expanding most quickly as customized formulation shipments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented tanneries in India, Germany, Italy, China, and the United States absorb the dominant share of chromium salt procurement, with each market exhibiting distinct regulatory pressures and buyer qualification protocols.
India
Kanpur-Unnao leather clusters supply Italian and German footwear brands with chrome-tanned hides. India's Central Pollution Control Board enforces zero-liquid-discharge norms that mandate chrome recovery system investments. Tanneries in Uttar Pradesh are deploying membrane filtration infrastructure to regenerate chromium for reuse while meeting export contract specifications.
Germany
Automotive upholstery tanneries serving BMW and Porsche contracts drive sulfate-grade demand with polymer-stabilized formulations. ECHA's REACH Annex XVII restricts hexavalent chromium in leather articles to 3 mg/kg. Lanxess AG maintains chromite ore processing integration across Belgian and German sites to sustain cost positions.
Italy
Arzignano and Santa Croce sull'Arno tanneries qualify chemical suppliers through 18-24 month ISO 9001 plus Cr(VI) management audits. Kering and LVMH now require quarterly test reports from direct chemical suppliers rather than tannery certificates. This verification shift concentrates contract volumes with sulfate producers maintaining in-house ISO 17025 analytical capabilities.
China
Pigment manufacturers in the Yangtze River Delta require consistent sodium dichromate feedstock for chrome oxide green production serving aerospace coatings. EPA discharge limits on electroplating effluent govern export-oriented pigment precursor operations. Hubei and Sichuan-based chemical producers serve domestic leather processing hubs in Guangdong and Zhejiang.
United States
Metal finishing applications in Michigan and Ohio electroplating corridors sustain chromic acid demand for hard chrome deposition. EPA effluent guidelines restrict discharge from electroplating facilities. American Elements and specialty chemical distributors serve aerospace coating specifications requiring batch consistency for high-temperature performance.
Global Chromium Salt Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive chromite processing, regional sulfate specialists serving tannery clusters, and diversified materials suppliers with metal finishing expertise. The vendor base separates into three archetypes: backward-integrated ore processors, formulation specialists with analytical certification capabilities, and trading houses with regional distribution density. Competitive moves center on portfolio diversification into trivalent sulfate grades and geographic expansion toward underpenetrated African leather sectors.
Within the integrated processor tier, Lanxess AG exemplifies backward integration into chromite ore processing, while Elementis plc occupies a position emphasizing specialized chromium sulfate grades for North American metal finishing. Vishnu Chemicals anchors the regional specialist archetype through captive sodium dichromate capacity serving South Asian tanneries. These three companies represent the dominant competitive configurations: ore-integrated multinational, application-focused specialty supplier, and regionally concentrated integrated producer.
| Leading Market Players |
|---|
| Lanxess AG |
| Elementis plc |
| Vishnu Chemicals |
| Hubei Zhenhua Chemical |
| Sichuan Yinhe Chemical |
| American Elements |
| Nippon Chemical Industrial |
| Merck KGaA |
| Soda Sanayii A.S. |
| Others |
Supply & Pricing Matrix
Vegetable tanning agent substitution in luxury leather segments is simultaneously redrawing supply geography toward Brazilian and Argentine quebracho extract processors and compressing pricing power for standard chromium sulfate grades in mass-market footwear supply chains.
Pricing Analysis
Cost-plus contracts indexed to South African chromite ore benchmarks dominate long-term supply agreements between integrated processors and European automotive tanneries. Pricing stratifies across polymer-stabilized premium grades for BMW and Ferrari seating contracts, standard sulfate formulations for Indian bulk footwear producers, and economy basicity variants for domestic Chinese leather processing. Cost compression in standard sulfate tiers is intensifying as Kanpur-Unnao tanneries consolidate procurement volumes through cooperative purchasing arrangements. Indian bulk footwear producers exhibit the highest price sensitivity due to thin export margins, while German automotive upholstery tanneries prioritize batch consistency over unit cost.
Supply Chain Analysis
Durban port congestion and Richards Bay chromite export bottlenecks expose global processors to inventory volatility and forced spot market exposure. Metallurgical-grade chromite ore draws from South African Bushveld Complex deposits and Kazakh Donskoy ore bodies, with sodium sulfate and sulfuric acid as critical chemical reagents for dichromate conversion. Single-source vulnerability concentrates in South African ore supply, where export duty volatility and Transnet logistics disruptions propagate through derivative chemical pricing. Distribution runs through integrated chemical conglomerates with captive ore processing for large tannery and pigment contracts, while regional distributors serve fragmented electroplating and wood treatment accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chrome recovery system services and effluent compliance consulting are expanding faster than commodity salt sales as India's Central Pollution Control Board enforcement creates recurring revenue streams for technology-anchored suppliers.
For Market Incumbents: Shield sulfate formulation margins by deepening captive chromite ore processing integration at South African and Kazakh feedstock sources. Prioritize ISO 17025 analytical certification investments to capture Kering and LVMH supplier qualification cycles, defending against emerging Indian and Chinese competitors lacking in-house testing capabilities. For New Entrants and Emerging Players: Lead with chrome recovery system deployment and operation contracts for Kanpur-Unnao tanneries facing zero-liquid-discharge mandates. Target Ethiopian and Nigerian leather sectors lacking integrated chemical supply chains, positioning sulfate blending facilities adjacent to emerging tannery clusters with technical service attach as the primary go-to-market mechanism. For Investors and Strategic Acquirers: ECHA's 2023 REACH Annex XVII threshold reduction to 3 mg/kg Cr(VI) reshapes the acquisition landscape toward trivalent sulfate specialists with demonstrated brand supply chain qualification. Five-to-ten-year viability favors producers with backward integration into chromite processing and established circular material flows qualifying for EU Green Deal chemistry incentives. Monitor Italian and German tannery supplier consolidation as the signal indicating which chemical producers have secured durable contract positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Ore Processing | Lanxess AG's Bushveld feedstock control insulates margin positions from export duty volatility. |
| ISO 17025 Analytical Certification Investment | In-house testing capabilities satisfy Kering and LVMH direct supplier verification requirements. |
| Chrome Recovery System Deployment | Membrane filtration infrastructure captures India's Central Pollution Control Board compliance-driven capital deployment. |
| Polymer-Stabilized Sulfate Grade Development | High-temperature shrinkage resistance specifications secure BMW and Ferrari seating contract volumes. |
| African Leather Sector Geographic Expansion | First-mover blending facilities in Ethiopia and Nigeria exploit underpenetrated chromium chemical supply chains. |
Research Methodology
Initial hypotheses were tested against primary input from tannery plant managers, leather chemical procurement leads, chromite ore traders, effluent treatment system engineers, and REACH compliance consultants, then refined against customs trade data, ECHA regulatory filings, SEC 10-K disclosures from listed chemical producers, Indian Central Pollution Control Board enforcement records, and industry association reports from Cefic and the American Leather Chemists Association. Bottom-up volume estimates from individual tannery and pigment plant consumption patterns were triangulated against top-down chromite ore trade flow analysis.
Variance decomposition across product grade tier, end-use application, packaging format, and regional production hub drove the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling with cross-validation against historical dichromate and sulfate volume trends. Chrome recovery system penetration rates and REACH compliance cost pass-through assumptions served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained ECHA enforcement intensity, stable South African ore export flows, or continued Italian and German automotive upholstery demand would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and tannery capital expenditure cycles. Practitioners should keep alternative scenarios live as Indian zero-liquid-discharge enforcement patterns and synthetic tanning agent substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Diamond Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Sodium Tungstate Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market