
 Hot Briquetted Iron (HBI) Market | 2026-2036
Hot Briquetted Iron (HBI) Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Briquetted Iron (HBI) Market Foresight
The EU Carbon Border Adjustment Mechanism is repositioning the cost-of-entry calculus for steelmakers sourcing metallics from carbon-intensive blast furnace routes. ArcelorMittal leverages its integrated mining-to-steel footprint to secure low-emission HBI feedstock across European and North American mills. Cleveland-Cliffs anchors its Great Lakes steelmaking complex with captive HBI supply from its Toledo direct reduction facility. Voestalpine sustains its Austrian electric steel operations through dedicated offtake from its Texas HBI plant, navigating trans-Atlantic freight economics against carbon-adjusted import costs.
Hot Briquetted Iron consists of direct reduced iron compressed into dense, pillow-shaped briquettes with metallization exceeding 91 percent and carbon content typically ranging from 1.5 to 3.5 percent, engineered for safe ocean transport and efficient melting in electric arc furnaces. The briquettes segment dominates premium seaborne trade due to superior handling characteristics and reduced reoxidation risk versus standard DRI. Steel Mills represent the largest end-user category, though Metal Fabricators are expanding HBI blending ratios as quality consistency improves and scrap price volatility widens.
The EPA enforces emissions standards that favor direct reduction pathways over traditional coke-based ironmaking, while the EU Green Deal and associated CBAM framework impose carbon cost differentials on imported steel and metallics. ISO standards governing DRI/HBI shipping safety and product specifications shape vessel certification requirements and terminal handling protocols. Stakeholders must monitor regulatory calibration on carbon border mechanisms and corresponding green hydrogen subsidies that could redraw the geographic cost map for HBI production.
Market Dynamics
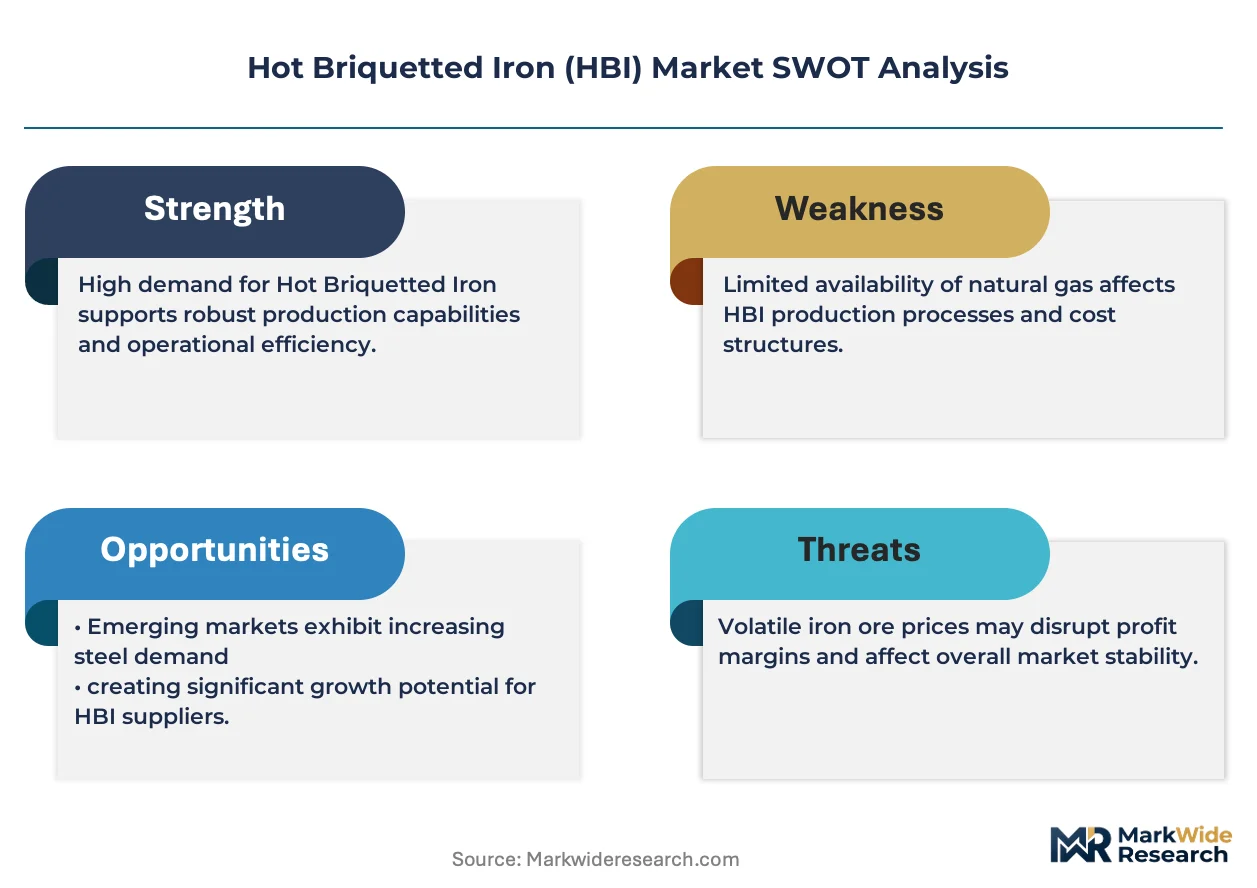
The EU Carbon Border Adjustment Mechanism is compressing the cost advantage of carbon-intensive blast furnace iron, redirecting electric arc furnace steelmakers toward low-emission metallics procurement. This regulatory pressure is accelerating investment in direct reduction capacity and reshaping Atlantic basin trade flows.
Growth Catalysts
- EU Green Deal framework:The CBAM imposes carbon cost differentials on imported steel and metallics, incentivizing EAF operators to source HBI over higher-emission alternatives. Compliance deadlines are tightening procurement specifications across European mills.
- Green hydrogen subsidies:Government incentive programs in multiple jurisdictions are de-risking capital deployment for hydrogen-based direct reduction plants. These subsidies are compressing the green premium for zero-carbon HBI production.
- Gulf Coast production clusters:Concentrated natural gas supply and deepwater port infrastructure in Texas and Louisiana are attracting integrated steel investments. Proximity to shale gas fields delivers feedstock cost advantages for DRI-HBI operations.
Market Restraints
- Natural gas price volatility:Feedstock cost swings in North American and Middle Eastern production hubs compress margin predictability for merchant HBI suppliers. Price spikes directly transfer to briquette production economics.
- Ocean freight rate instability:Trans-Atlantic and Asia-Europe shipping cost fluctuations distort landed cost comparisons between regional HBI sources. Vessel availability constraints at specialized DRI-handling terminals compound exposure.
- Scrap price arbitrage:Ferrous scrap remains the dominant EAF metallic input in price-sensitive markets. HBI must compete against established scrap collection and processing infrastructure with lower capital intensity.
Strategic Opportunities
- US Inflation Reduction Act credits:Clean hydrogen production tax credits are enabling first-mover economics for green HBI facilities. IRA provisions reduce the cost gap between natural gas and electrolytic hydrogen reduction pathways.
- India's PLI scheme for specialty steel:Domestic production incentives are stimulating direct reduction investments to reduce import dependence on metallics. Policy support targets capacity buildout for high-grade automotive and electrical steel inputs.
- ISO 10882 shipping standard adoption:Updated safety protocols for DRI/HBI vessel certification are expanding eligible carrier pools. Terminal handling protocol harmonization reduces port congestion risks for seaborne trade.
Industry Challenges
- Metallurgical technician scarcity:Direct reduction plant operations require specialized expertise in gas chemistry and briquetting process control. Workforce development lags capacity expansion timelines in emerging production regions.
- Legacy EAF integration complexity:Existing electric arc furnace configurations optimized for scrap charging require feedstock system modifications to handle HBI blends. Retrofit capital and operational learning curves delay adoption at smaller mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Briquetted Iron (HBI) Market |
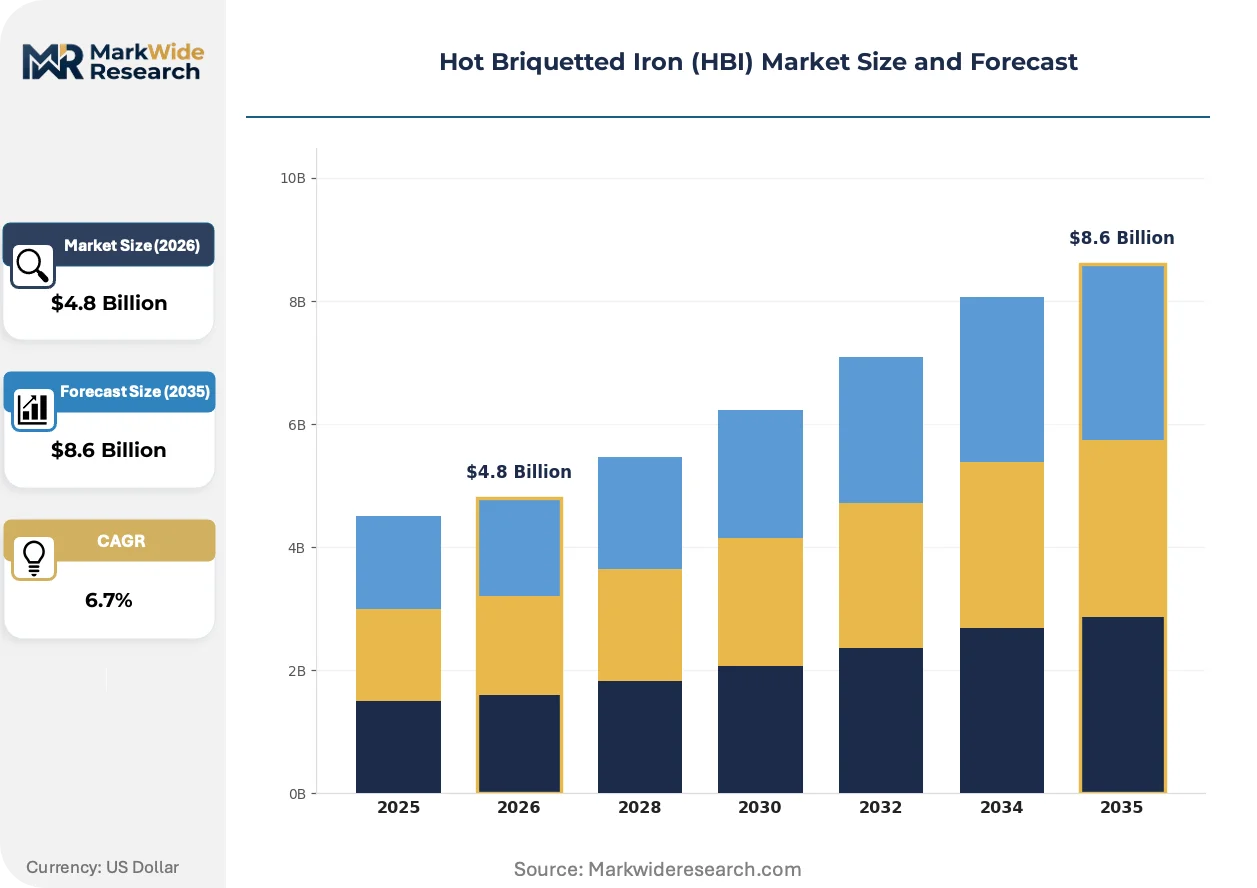
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Briquettes, Fines, DRI End User: Steel Mills, Foundries, Metal Fabricators, OEMs Application: Steelmaking, Ironmaking, Metal Recycling, Alloy Production Pricing Model: Spot Market, Contract Pricing, Index-Based Pricing, Auction |
| Companies Covered | NUCOR, JSW Steel, ArcelorMittal, Jindal Shadeed Iron & Steel, Cleveland-Cliffs, Metalloinvest, Kobe Steel, Midrex Technologies, Voestalpine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Briquetted Iron (HBI) Market Shifts & Advancements
Hydrogen-based direct reduction technology is consolidating technical pathways for near-zero emission iron production. Equipment suppliers and steelmakers are converging on standardized reactor designs that de-risk capital deployment.
Fluidized bed reduction technology paired with hydrogen injection is consolidating the technology stack for commercial-scale green HBI production. Midrex and Energiron licensors are scaling reactor modules to match gigawatt-scale electrolyzer deployments. Equipment standardization is compressing engineering timelines and enabling project finance at utility-scale renewable energy sites.
The EU Carbon Border Adjustment Mechanism is restructuring import duty calculations for steel and embedded metallics from January 2026. European steelmakers are securing long-term HBI offtake to demonstrate compliance with embodied carbon thresholds. North American and Middle Eastern suppliers are certifying product carbon footprints to maintain market access under the phased implementation.
Steel mill procurement departments are consolidating metallic input purchasing under centralized category management functions. EAF operators are negotiating multi-year HBI supply agreements to hedge against scrap price volatility and secure emissions accounting transparency. This organizational shift is most advanced among European and North American integrated steel producers with disclosed net-zero commitments.
Hot Briquetted Iron (HBI) Market Segmentation
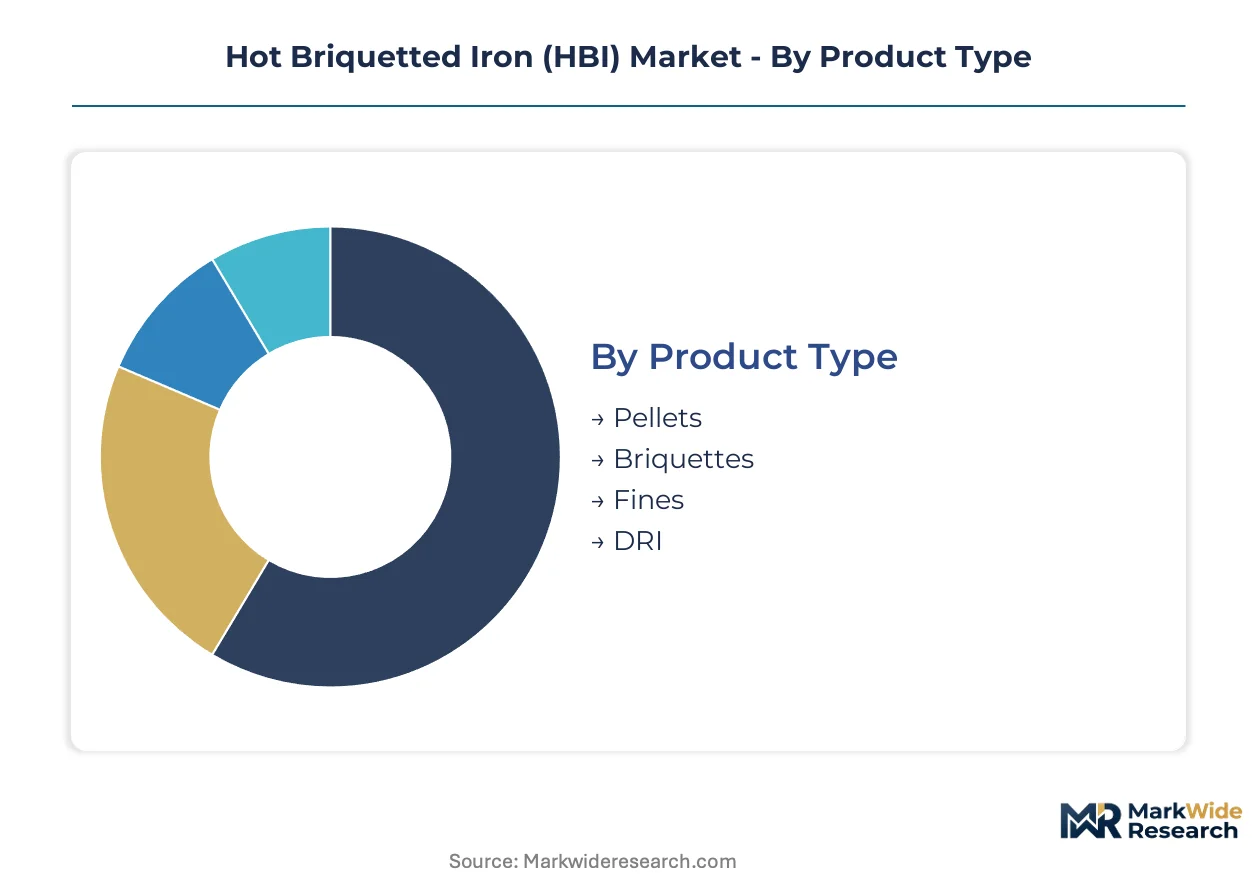
HBI market segmentation reflects divergent technical specifications, procurement strategies, and metallurgical requirements across steelmaking value chains. Understanding these divisions enables suppliers to align product forms with specific melting operations and emissions compliance frameworks.
Product Type:
Material density and reoxidation resistance drive buyer selection between competing direct reduced iron formats.
- Briquettes:Compressed pillow-shaped forms with metallization exceeding 91 percent and carbon content of 1.5 to 3.5 percent, engineered for safe ocean transport. Gulf Coast production clusters in Texas and Louisiana concentrate supply for Atlantic basin electric arc furnace steelmakers seeking low-emission feedstock alternatives under EU Carbon Border Adjustment Mechanism compliance requirements.
- Pellets:Spherical direct reduced iron with lower bulk density than briquetted forms, typically consumed at integrated facilities with captive direct reduction shaft furnaces. Merchant pellet demand concentrates in Middle Eastern production hubs where natural gas feedstock costs support continuous reduction economics.
- Fines:Unbriquetted particulate material requiring pneumatic handling systems and immediate consumption to prevent reoxidation. Limited seaborne trade due to ISO 10882 shipping safety constraints and terminal handling restrictions.
- DRI:Generic direct reduced iron category encompassing non-briquetted forms with variable metallization grades, primarily consumed in captive steelmaking configurations or regional land-based trade.
Briquettes leads on scale; pellets leads on momentum in merchant trade expansion.
End User:
Procurement sophistication and feedstock blending capabilities distinguish customer tiers in metallic sourcing.
- Steel Mills:Electric arc furnace operators represent the dominant consumption category, integrating HBI at 15 to 30 percent charge ratios to dilute scrap contaminants and stabilize melt chemistry. European mills under EU Green Deal compliance deadlines are expanding offtake to demonstrate embodied carbon thresholds for CBAM reporting.
- Metal Fabricators:Secondary steel producers and re-rollers are increasing HBI blending ratios as quality consistency improves and scrap price volatility widens procurement risk exposure.
- Foundries:Gray and ductile iron producers utilize HBI as a metallurgical corrective in cupola and induction furnace operations, with demand concentrated in automotive component supply chains.
- OEMs:Original equipment manufacturers with captive steelmaking operations, including automotive and heavy machinery producers, source certified low-carbon metallics for scope 3 emissions accounting.
Steel Mills leads on scale; Metal Fabricators leads on momentum in adoption velocity.
Application:
Metallurgical process requirements determine specification stringency and carbon footprint certification needs.
- Steelmaking:Electric arc furnace charge material representing the primary application, where HBI substitutes for prime scrap in flat-rolled and long-product production. Demand concentrates around coastal mill complexes with deepwater HBI receiving terminals.
- Ironmaking:Blast furnace burden supplementation and hot metal production in hybrid configurations, with limited adoption due to coke-based route dominance in integrated steelmaking.
- Metal Recycling:Contaminant dilution in scrap-based melting operations, improving final product quality consistency for construction and automotive grade steels.
- Alloy Production:Specialty steel and ferroalloy manufacturing requiring precise chemistry control, with premium pricing for high-metallization low-residue material.
Steelmaking leads on scale; Metal Recycling leads on momentum in circular economy integration.
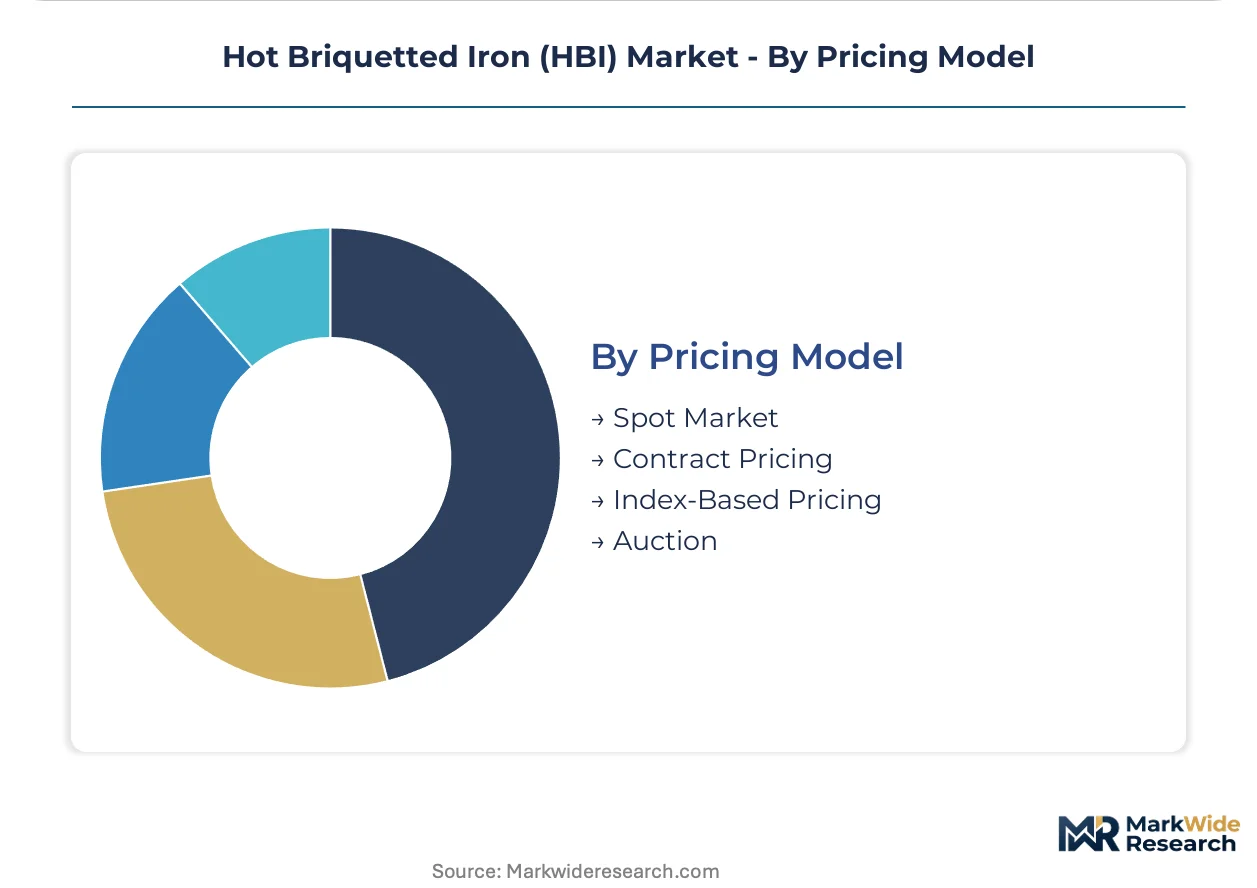
Pricing Model:
Risk allocation preferences and procurement organization maturity shape contracting structure selection.
- Contract Pricing:Multi-year offtake agreements with fixed or escalated pricing, preferred by integrated steel producers with disclosed net-zero commitments seeking emissions accounting transparency and supply security.
- Index-Based Pricing:Formulas tied to iron ore, scrap, or natural gas benchmarks, transferring feedstock cost volatility while preserving margin predictability for merchant HBI suppliers.
- Spot Market:Transactional purchases for volume flexibility and opportunistic procurement, dominant in price-sensitive markets with established scrap collection infrastructure.
- Auction:Competitive bidding for cargo lots, employed for distressed inventory disposition and regional supply-demand rebalancing.
Contract Pricing leads on scale; Index-Based Pricing leads on momentum in risk management adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical technicians concentrate around direct reduction plant clusters in Texas, Louisiana, and the Arabian Gulf, anchoring regional production capacity. These workforce pools support the specialized gas chemistry and briquetting process control expertise that direct reduction operations demand.
United States
Gulf Coast electric arc furnace steelmakers are expanding HBI offtake to meet emissions disclosure requirements from automotive OEM customers. The EPA enforces emissions standards that favor direct reduction pathways over coke-based ironmaking. Production clusters in Texas and Louisiana leverage concentrated natural gas supply and deepwater port infrastructure for Atlantic basin export.
Germany
Steel mills under EU Green Deal compliance deadlines are securing long-term HBI supply to demonstrate embodied carbon thresholds for CBAM reporting. The EU Carbon Border Adjustment Mechanism imposes carbon cost differentials on imported metallics from January 2026. The Ruhr industrial region hosts EAF operators integrating HBI at 15 to 30 percent charge ratios to stabilize melt chemistry.
India
Domestic steel producers are increasing direct reduction investments to reduce import dependence on metallics for high-grade automotive and electrical steel inputs. The PLI scheme for specialty steel stimulates capacity buildout with production incentives. Gujarat and Odisha host emerging DRI-HBI facilities targeting merchant supply to coastal mill complexes.
United Arab Emirates
Merchant HBI suppliers in the Arabian Gulf are certifying product carbon footprints to maintain European market access under phased CBAM implementation. The country's national industrial regulator aligns with ISO standards governing DRI/HBI shipping safety and vessel certification. Jebel Ali and Ruwais industrial zones concentrate export-oriented direct reduction capacity with access to specialized DRI-handling terminals.
Japan
Electric steel operators are evaluating HBI blending ratios as scrap price volatility widens procurement risk exposure for construction and automotive grade steels. METI oversees industrial emissions frameworks that incentivize low-carbon metallics procurement. The Chubu region around Nagoya hosts EAF complexes exploring feedstock diversification to improve final product quality consistency.
Hot Briquetted Iron (HBI) Market Competitive Landscape
The competitive structure tilts toward integrated mining-to-steel conglomerates with captive direct reduction capacity. Merchant suppliers concentrate in natural gas-rich production hubs where feedstock cost advantages support continuous operations. Two strategic archetypes dominate: integrated steel producers with backward integration into HBI supply, and technology licensors enabling third-party direct reduction deployments. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing long-term offtake agreements to hedge against scrap price volatility.
Within the integrated producer tier, ArcelorMittal and Cleveland-Cliffs exemplify the mining-to-steel model, while Voestalpine occupies a position bridging European steelmaking with trans-Atlantic HBI supply. Among technology-focused entities, Midrex Technologies represents the equipment licensing archetype that enables project finance at utility-scale renewable energy sites. These named players anchor the competitive landscape without exhausting its structure.
| Leading Market Players |
|---|
| NUCOR |
| JSW Steel |
| ArcelorMittal |
| Jindal Shadeed Iron & Steel |
| Cleveland-Cliffs |
| Metalloinvest |
| Kobe Steel |
| Midrex Technologies |
| Voestalpine |
| Others |
Supply & Pricing Matrix
Carbon certification divergence between EU CBAM-compliant and conventional HBI streams bifurcates both pricing premiums and supply chain sourcing strategies. Buyers seeking embodied carbon transparency pay structural premiums for certified low-emission briquettes, while procurement teams optimize landed costs against regulatory compliance deadlines across Atlantic basin trade lanes.
Pricing Analysis
Carbon-unbundled versus carbon-bundled HBI sales splits the market into distinct contracting archetypes. Three-tier pricing structure across premium low-carbon, standard merchant, and economy spot tiers reflects certification grade and volume commitment differentiation. Pricing pressure stems from natural gas feedstock volatility compressing margin predictability at Gulf Coast production clusters. Scrap-dependent EAF operators in price-sensitive markets exhibit highest price sensitivity, while automotive OEMs with scope 3 disclosure mandates show lowest sensitivity to carbon-certified premiums.
Supply Chain Analysis
Dual-sourcing requirements from European steelmakers mandate qualification of at least two Atlantic basin HBI suppliers to mitigate CBAM compliance risk. Supply concentrates in the United States, United Arab Emirates, and India, with each hub drawing from distinct natural gas, iron ore pellet, and hydrogen feedstock configurations. Logistics chokepoints at specialized DRI-handling terminals in Rotterdam and Houston create single-point vulnerability for seaborne trade. Distribution runs through long-term offtake contracts with integrated steel producers and merchant spot sales to independent EAF operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hot Briquetted Iron market compounds steadily as regulatory carbon accounting hardens demand for traceable low-emission metallics across electric steelmaking value chains.
For Market Incumbents: Acquire hydrogen reduction technology licenses to secure first-mover positioning as green HBI production scales. Cleveland-Cliffs and ArcelorMittal anchor defensive moats through captive natural gas supply and backward integration into direct reduction capacity. Counter emerging merchant entrants from Middle Eastern production hubs by locking multi-year automotive OEM offtake with certified carbon footprint disclosure. For New Entrants and Emerging Players: Capture stranded renewable hydrogen assets in Texas and Louisiana where IRA production tax credits compress green premium economics. India's PLI-stimulated specialty steel sector offers penetrable white-space for domestic HBI supply reducing import dependence. Establish tolling partnerships with existing direct reduction shaft furnace operators to bypass capital-intensive greenfield development timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with technology licensors enabling utility-scale renewable hydrogen integration at greenfield HBI sites. Five-to-ten year viability hinges on CBAM enforcement stringency and green hydrogen cost convergence. Monitor EU carbon border certificate pricing as the inflection signal determining Atlantic basin trade flow reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Supply Agreement | Locks electrolyzer capacity for zero-carbon HBI production under IRA tax credit frameworks. |
| CBAM Certification Program | Enables European market access through verified embodied carbon disclosure per EU Green Deal requirements. |
| Long-term Automotive Offtake | Secures scope 3 emissions accounting transparency for OEM steel procurement committees. |
| Specialized Terminal Partnership | Expands vessel eligibility through ISO 10882-compliant handling infrastructure at Gulf Coast ports. |
| Metallurgical Workforce Development | Addresses technician scarcity through accredited training programs at Texas and Louisiana plant clusters. |
Research Methodology
Coverage spans North America, Europe, Middle East, and South Asia, with primary inputs from each region's steelmaking corridor. Direct reduction plant managers, EAF procurement directors, automotive OEM sustainability officers, and merchant HBI traders provided operational data. Secondary validation drew from EPA emissions filings, EU CBAM regulatory texts, SEC 10-K disclosures from integrated steel producers, and IEA hydrogen deployment trackers. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Granularity-level modeling segmented the market by briquette/pellet/fines product forms, steel mill/fabricator/foundry end users, and contract/index/spot pricing structures. CAGRs derived from production capacity buildout timelines, scrap price correlation analysis, and carbon cost pass-through elasticity across the projection horizon. Hydrogen reduction technology maturation curves and EU CBAM phase-in schedules constituted industry-specific forecast inputs.
Natural gas price volatility, ocean freight rate instability, and scrap market arbitrage are the dominant revision risks to HBI demand projections. Deviation in EU carbon border enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Cesium Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Chromite Market