
 Gemstones Market | 2026-2036
Gemstones Market Size, Share, and Industry Trends Forecast 2026-2036
Gemstones Market Analysis
Asset-light leasing models for rough gemstone inventory are narrowing the capital barrier for mid-tier cutters and polishers entering the market. De Beers Group leverages its Sight holder system to control rough diamond distribution across key cutting centers. PJSC ALROSA anchors supply security through direct state-backed mining operations in Yakutia. Chow Tai Fook Jewellery Group Limited dominates retail channel access across Greater China with vertically integrated sourcing.
Gemstones are naturally occurring mineral crystals valued for beauty, rarity, and durability, with hardness ratings on the Mohs scale and optical properties such as refractive index determining cut quality and commercial grading. These materials serve primarily as store-of-value assets, luxury adornment, and industrial abrasives depending on clarity and structural integrity. Diamonds in gem quality grade sustain the largest value pool due to established bridal market demand and investment liquidity, while collector quality sapphires and untreated rubies represent the fastest appreciation segment driven by auction scarcity and provenance premiums. Rough form stones retain higher margin capture for mining houses, whereas faceted finished goods concentrate value addition with specialist cutters in traditional hubs.
The Kimberley Process Certification Scheme governs rough diamond trade documentation, while the EU Conflict Minerals Regulation extends due diligence to gold and colored gemstone supply chains entering European markets. The UAE's Ministry of Economy and Dubai Multi Commodities Centre enforce local anti-money laundering protocols for precious stone trading, reshaping hub logistics and documentation burdens. Stakeholders must monitor evolving mandatory disclosure requirements across multiple jurisdictions to preserve market access and brand positioning.
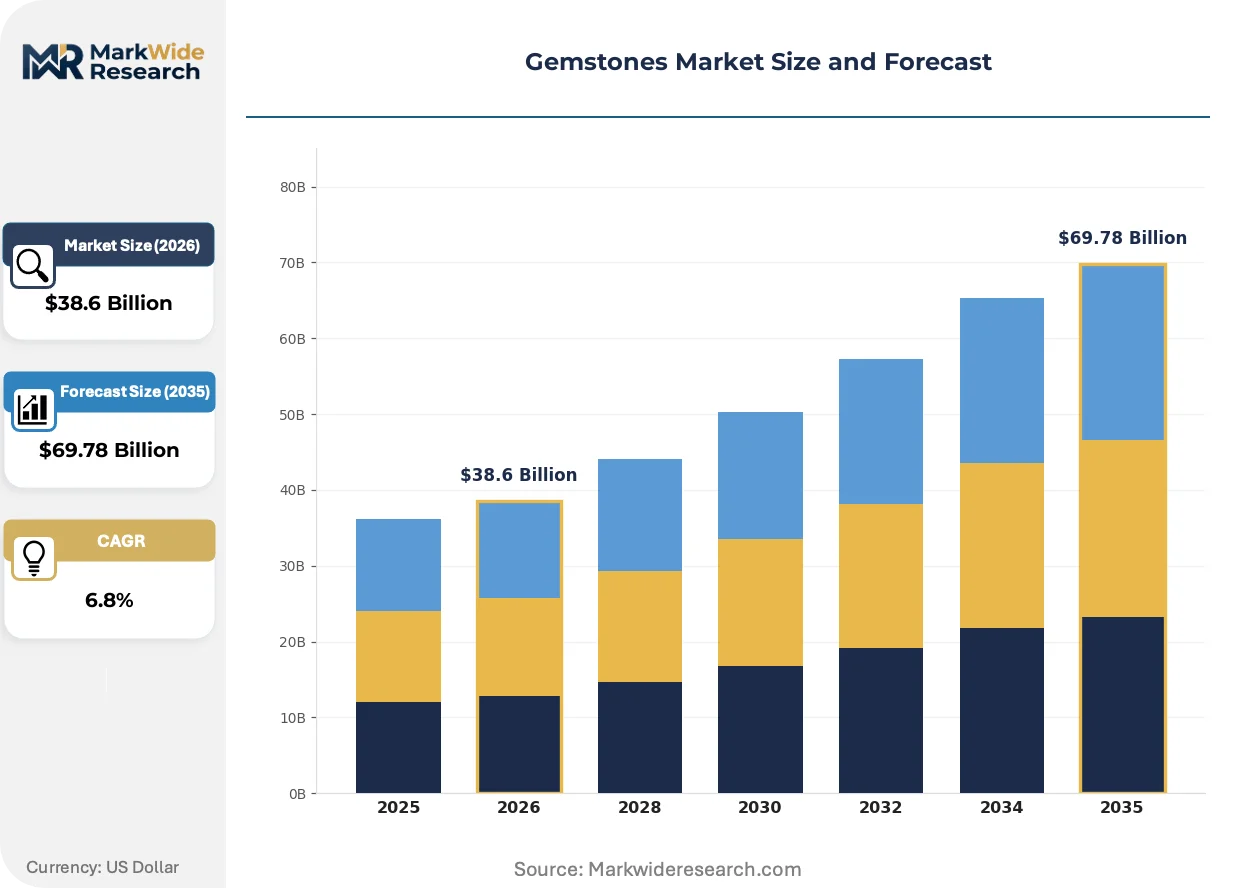
Market Dynamics
Traceability mandates from the Kimberley Process Certification Scheme and EU due diligence rules are compressing margins for rough stone traders while concentrating procurement power with vertically integrated houses that control documentation from mine to retail.
Growth Catalysts
- EU Conflict Minerals Regulation:Mandatory supply chain disclosure for gold and colored gemstones entering European markets is accelerating investment in blockchain-based provenance systems by mid-tier traders seeking compliance advantage.
- Bridal market liquidity:Established certification standards for gem-quality diamonds sustain institutional investment demand, particularly in Swiss and UAE private banking channels seeking portable store-of-value assets.
- Myanmar ruby scarcity:Collector-grade untreated stones from Mogok command auction premiums that pull capital into specialized sourcing operations across Southeast Asian trading hubs.
Market Restraints
- Input cost volatility:Rough sapphire and emerald prices fluctuate with artisanal mining output disruptions in Colombia and Madagascar, squeezing cutter margins on fixed-price retail contracts.
- Supply concentration risk:State-controlled mining operations in Russia's Yakutia region dominate rough diamond feedstock, creating single-source dependency for polishers without Sight holder status.
- Technical limitation:Laboratory-grown diamond detection requires spectroscopic equipment beyond the capital reach of small-scale dealers, limiting their participation in certified resale channels.
Strategic Opportunities
- Underpenetrated secondary markets:India's gem and jewelry export processing zones offer tariff-advantaged cutting operations for rough stones destined to Middle Eastern retail networks.
- Regulatory tailwind:Dubai Multi Commodities Centre anti-money laundering protocols are positioning the emirate as a compliant alternative to traditional European trading centers for high-value stone transfers.
- Technology convergence:Integration of photoluminescence spectroscopy with distributed ledger systems enables real-time authentication for online auction platforms serving ultra-high-net-worth collectors.
Industry Challenges
- Skill pipeline collapse:Master faceting craftsmanship in traditional centers like Jaipur and Surat faces generational attrition as younger workers migrate to technology services sectors.
- Certification timeline compression:Multi-jurisdictional documentation requirements for rough imports now extend customs clearance periods beyond the working capital cycles of independent traders.
- Legacy system integration:Family-owned cutting houses struggle to reconcile handwritten provenance records with automated compliance reporting demanded by EU and UAE regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gemstones Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamonds, Rubies, Sapphires, Emeralds Form: Rough, Cut, Cabochon, Faceted End User: Retail Consumers, Jewelers, Collectors, Manufacturers Quality Grade: Gem Quality, Industrial Quality, Commercial Quality, Collector Quality |
| Companies Covered | PJSC ALROSA, De Beers Group, Anglo American plc, Rio Tinto Group, Gemfields Group Limited, Chow Tai Fook Jewellery Group Limited, Tiffany & Co., Blue Nile, Inc., Gem Diamonds Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gemstones Market Emerging Trajectories
Digital authentication and provenance tracking are displacing paper-based certification, while auction platforms and direct-to-collector channels compress traditional dealer hierarchies in high-value gemstone trading.
Photoluminescence spectroscopy combined with Raman analysis is digitizing the detection of treatment history in sapphires and rubies. Major auction houses and investment-grade collectors now mandate these scans prior to acquisition, compressing the market for undocumented stones. The technology is digitizing trust mechanisms that previously required physical inspection by a handful of recognized experts, enabling remote transaction execution across international borders.
REACH regulation amendments extending substance restrictions to jewelry alloys are forcing reformulation of mountings and settings across European manufacturing. The industrial consequence is accelerated substitution of nickel-based white gold with palladium alloys, raising material costs for mass-market producers. Swiss and Italian luxury houses are responding by emphasizing platinum settings in premium lines to preempt compliance disruption.
Collector behavior now favors direct sourcing from mining jurisdictions over traditional dealer intermediation, particularly for untreated Burmese rubies and Kashmir sapphires. Ultra-high-net-worth buyers in Switzerland and the UAE are establishing private offices in Yangon and Srinagar to secure first refusal on rough production. This channel disintermediation is most visible in Geneva and Dubai auction results, where stones with documented direct-provenance narratives achieve 15-40% premiums over dealer-sourced equivalents.
Gemstones Market Segmentation
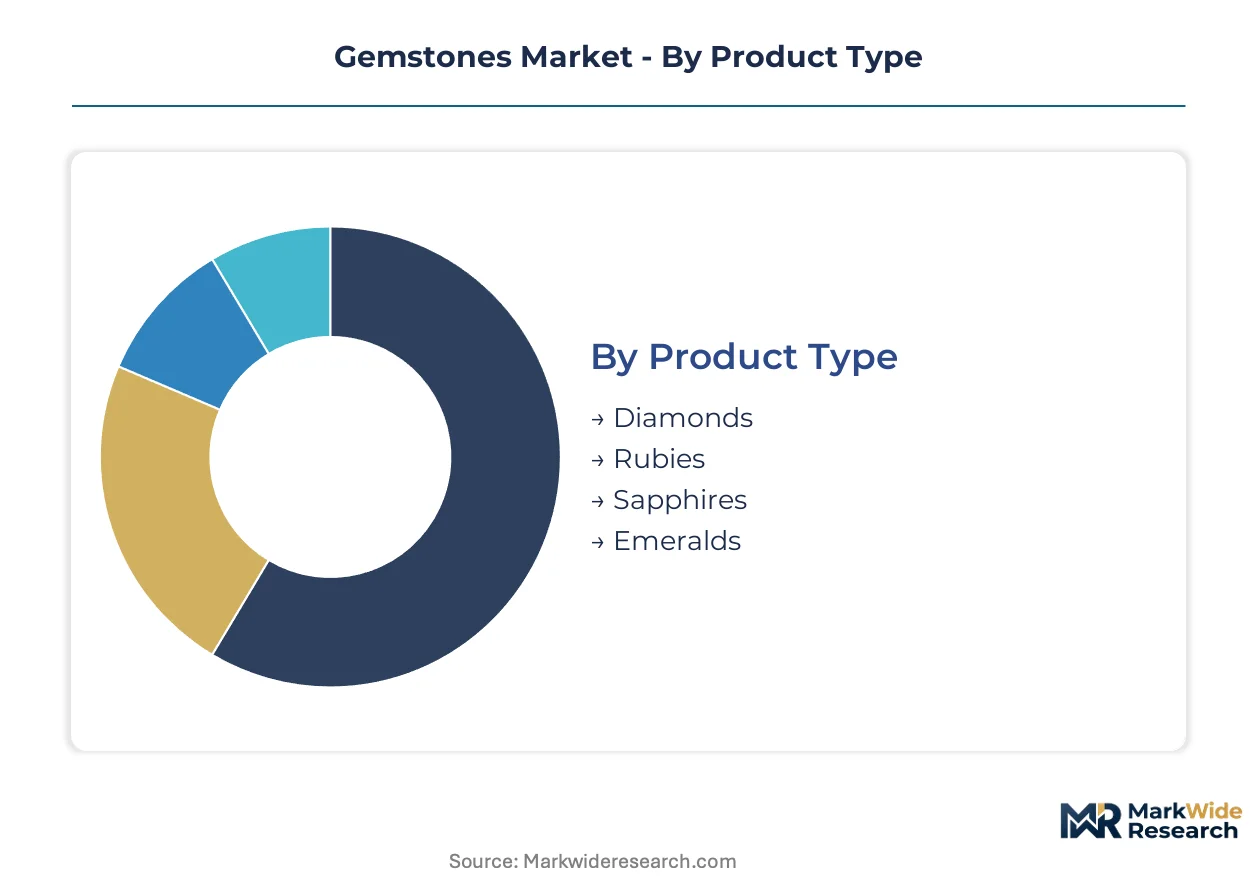
Gemstone segmentation separates inventory velocity from margin capture. Cycle times vary dramatically between bridal-grade diamonds and collector-grade untreated rubies, dictating working capital requirements and authentication protocols across trading tiers.
Product Type:
Diamonds turn inventory fastest through established certification pipelines, while collector-grade colored stones sit longest awaiting provenance verification and auction timing.
- Diamonds:Gem-quality stones with established 4C grading standards sustain the deepest liquidity pools through bridal market demand. Swiss private banking channels and UAE family offices treat certified diamonds as portable collateral assets, compressing resale friction relative to colored stones.
- Rubies:Untreated Burmese specimens from Mogok command the steepest provenance premiums among all colored gemstones. Collector demand concentrates in Geneva and Dubai auction circuits where documented mine-to-market narratives achieve 15-40% price elevation over dealer-sourced equivalents.
- Sapphires:Kashmir-origin stones and Ceylon blues retain distinct geographic branding, though Madagascar and Sri Lanka now dominate rough supply volume.
- Emeralds:Colombian Muzo and Chivor deposits anchor investment-grade supply, with Zambian material filling commercial-grade fabrication channels.
Diamonds dominate installed base. Collector-grade rubies are where expansion concentrates.
Form:
Cost tier separation is pronounced: rough stones demand geological expertise and state-backed mining access, while finished goods concentrate value-add with specialist cutters.
- Rough:Unprocessed crystals retain highest margin capture for mining houses in Yakutia and Yakutsk-controlled operations. De Beers Sight holder system and ALROSA direct state contracts create tiered procurement access that excludes non-vertically integrated polishers.
- Faceted:Precision-cut stones with optimized refractive index command retail premiums in bridal and investment channels. Antwerp, Surat, and Tel Aviv cutting houses specialize in round-brilliant and fancy-shape production for certified resale markets.
- Cut:Generic pre-formed material serves mid-tier jewelry manufacturers with standardized sizing for mass-market mountings.
- Cabochon:Domed unfaceted cuts suit opaque or heavily included material, particularly star sapphires and cat's-eye chrysoberyl, where asterism drives value rather than clarity.
Rough dominates mining house revenue. Faceted stones are where downstream margin expansion concentrates.
End User:
Customer type determines authentication burden and transaction velocity, with retail consumers demanding standardized certification while collectors accept extended due diligence timelines.
- Retail Consumers:Bridal market purchasers prioritize GIA or IGI certification for diamonds, driving volume through Chow Tai Fook and comparable vertically integrated retail networks across Greater China.
- Collectors:Ultra-high-net-worth buyers in Switzerland and the UAE establish direct sourcing offices in Yangon and Srinagar, bypassing traditional dealer hierarchies for untreated Burmese rubies and Kashmir sapphires.
- Jewelers:Independent fabricators and luxury houses source calibrated melee and center stones through Antwerp and Mumbai trading floors, with EU REACH compliance now filtering alloy and mounting specifications.
- Manufacturers:Industrial abrasive producers consume bort and carbonado grades for cutting and grinding applications, with price sensitivity favoring synthetic diamond substitution where structural tolerance permits.
Retail consumers dominate transaction volume. Collectors are where price-per-carat expansion concentrates.
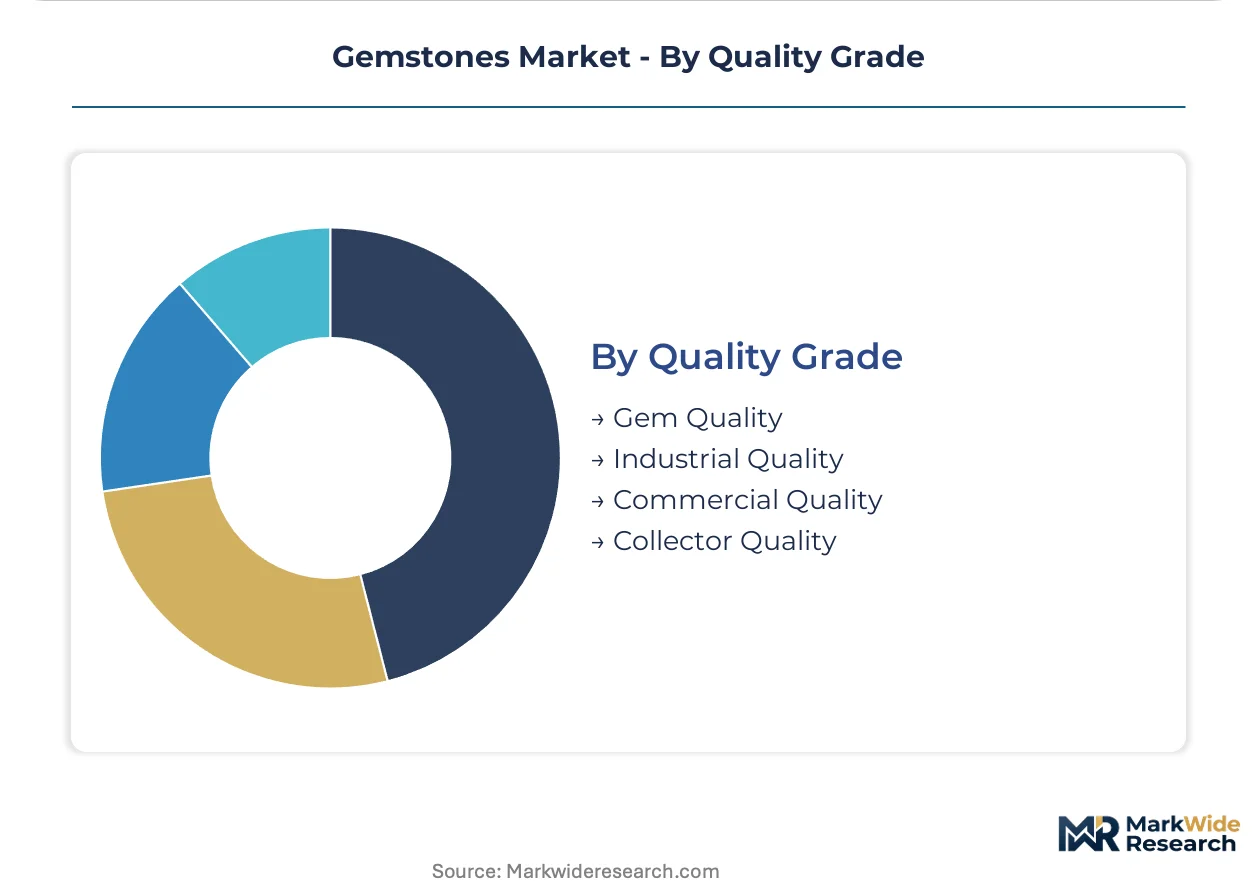
Quality Grade:
Margin stratification follows clarity and treatment history, with untreated material achieving scarcity premiums that laboratory-grown alternatives cannot replicate.
- Gem Quality:Flawless to slightly included stones with optimal color saturation sustain auction liquidity and private banking collateral acceptance. GIA grading reports and blockchain-linked provenance documentation now standard for stones above one carat.
- Collector Quality:Museum-grade specimens with documented geological origin and no thermal or fracture-filling treatment history. Photoluminescence spectroscopy and Raman analysis digitize authentication, enabling remote transaction execution across international borders.
- Commercial Quality:Moderately included material with acceptable color for mass-market jewelry fabrication, typically heat-treated to enhance saturation.
- Industrial Quality:Included, off-color, or fractured crystals directed toward abrasive, cutting, and drilling applications where hardness outweighs optical properties.
Commercial quality dominates carat volume. Collector quality is where appreciation velocity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate rough stone procurement in mining jurisdictions and polished distribution in consumer markets, with regulatory divergence across customs regimes fragmenting traditional trading corridors.
United States
Bridal market demand drives certified diamond imports through New York and Los Angeles customs districts, with GIA-graded stones commanding liquidity premiums in private banking collateral pools. The FTC Jewelry Guides mandate disclosure of gemstone treatments and laboratory-grown origins, reshaping retail documentation standards. Manhattan's Diamond District remains the primary trading floor for investment-grade stones destined to family offices and auction houses.
Switzerland
Geneva anchors collector-grade colored stone auctions, with untreated Burmese rubies and Kashmir sapphires achieving provenance premiums through documented mine-to-market narratives. Swissmedic and FINMA protocols govern anti-money laundering compliance for high-value transfers, compressing transaction timelines for documented inventory. The canton of Geneva hosts specialized vaulting and authentication facilities serving ultra-high-net-worth buyers from the Middle East and Asia.
United Arab Emirates
Dubai Multi Commodities Centre positioning attracts rough stone traders seeking compliant alternatives to European documentation burdens, with the Ministry of Economy enforcing local AML protocols for precious stone transfers. The emirate's free zone infrastructure enables tariff-advantaged re-export to South Asian and African markets. Jebel Ali logistics corridors now rival Antwerp for throughput of certified diamonds destined to Indian cutting centers.
India
Surat and Mumbai processing zones dominate faceted diamond output, with gem and jewelry export processing zones offering duty-drawback advantages for rough imports re-exported as finished goods. The Gem and Jewellery Export Promotion Council coordinates with customs authorities to streamline Kimberley Process documentation. Gujarat's diamond cutting clusters face generational skill attrition as younger workers migrate to technology services sectors.
Myanmar
Mogok ruby deposits sustain concentrated supply of collector-grade untreated material, though US Treasury sanctions restrict direct procurement by American entities. Artisanal mining output fluctuates with seasonal access and informal taxation regimes, creating price volatility for specialized traders. Yangon now hosts private buying offices established by Swiss and UAE collectors seeking first refusal on rough production.
Gemstones Market Vendor Landscape
On the supply side, the industry is bifurcated between state-controlled mining operations and vertically integrated luxury houses, with mid-tier traders facing margin compression from traceability documentation burdens. De Beers and ALROSA anchor rough diamond supply through sight holder systems and direct state contracts respectively. Strategic archetypes include mining houses with captive geological assets, luxury retailers with backward-integrated sourcing, and specialized auction platforms with authentication technology. Dominant competitive moves center on blockchain-based provenance systems and direct-to-collector channel development.
Among mining-dominated entities, PJSC ALROSA exemplifies state-backed supply security through Yakutia operations, while De Beers Group occupies a position defining rough distribution protocols across Antwerp, Surat, and Tel Aviv cutting centers. Within retail-integrated specialists, Chow Tai Fook Jewellery Group Limited represents Greater China channel dominance through vertically controlled sourcing, and Tiffany & Co. anchors American luxury positioning with heritage authentication standards.
| Leading Market Players |
|---|
| PJSC ALROSA |
| De Beers Group |
| Anglo American plc |
| Rio Tinto Group |
| Gemfields Group Limited |
| Chow Tai Fook Jewellery Group Limited |
| Tiffany & Co. |
| Blue Nile, Inc. |
| Gem Diamonds Limited |
| Others |
Supply Flow & Price Mechanics
Jebel Ali logistics corridors connecting Dubai to Indian cutting centers transmit freight cost volatility directly into rough stone procurement economics, amplifying price spreads between documented Kimberley Process-certified inventory and undocumented material while compressing cutter margins on fixed-price retail contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for bort and carbonado abrasive grades, while gem-quality segments stratify across collector, bridal, and commercial tiers. Price differentiation rests on certification pedigree and documented provenance, with GIA-graded stones commanding liquidity premiums. Cost compression in mid-tier colored stones is intensifying because artisanal mining disruptions in Madagascar and Colombia squeeze cutter margins. Retail consumers exhibit highest price sensitivity for commercial-grade material, whereas ultra-high-net-worth collectors demonstrate inelastic demand for untreated Burmese rubies with mine-to-market documentation.
Supply Chain Analysis
Tariff exposure between Myanmar and United States markets dominates supply chain risk calculus for collector-grade ruby traders navigating Treasury sanctions. Geographic supply concentrates in Russia's Yakutia region, Myanmar's Mogok tract, and Colombia's Muzo mines. Raw material dependencies encompass rough diamond feedstock, untreated colored stone crystals, and palladium alloy for REACH-compliant mountings. Single-source vulnerability pervades state-controlled mining operations. Distribution runs through Antwerp's trading floors, Dubai's free zones, and Surat's cutting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gemstone authentication services and blockchain provenance verification represent the fastest-expanding recurring-revenue layer, outpacing rough stone trading margins as regulatory disclosure mandates proliferate across EU and UAE jurisdictions.
For Market Incumbents: Insulate Sight holder status and direct mining contracts against mid-tier trader encroachment by accelerating blockchain provenance integration. De Beers and ALROSA should deepen upstream control over Yakutia feedstock. Investment in photoluminescence spectroscopy capabilities defends against laboratory-grown diamond substitution threats in certified resale channels.
For New Entrants and Emerging Players: Establish a beachhead in India's gem and jewelry export processing zones, where tariff-drawback advantages enable competitive rough-to-finished operations. Target collector-grade untreated sapphire niches in Kashmir and Ceylon origins where established houses maintain lighter coverage. Pursue direct-to-collector auction platform development as the go-to-market angle, leveraging spectroscopic authentication to bypass traditional dealer hierarchies.
For Investors and Strategic Acquirers: Specialized authentication technology providers with integrated distributed ledger capabilities offer the strongest acquisition target archetype for exposure to compliance-driven spending. Long-term viability hinges on regulatory trajectory rather than commodity price cycles. Watch for EU Conflict Minerals Regulation enforcement escalation as the inflection signal indicating accelerated provenance technology adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Kimberley Process and EU due diligence compliance now mandate documented chain-of-custody for rough imports. |
| Photoluminescence Spectroscopy Deployment | Raman analysis digitizes treatment detection in sapphires and rubies, enabling remote collector transactions. |
| Direct Sourcing Office Establishment | Swiss and UAE collectors now maintain Yangon and Srinagar presences for first refusal on rough production. |
| REACH-Compliant Alloy Reformulation | Swiss and Italian luxury houses emphasize platinum settings to preempt nickel-based white gold restrictions. |
| Secondary Market Platform Development | Online auction infrastructure with real-time authentication compresses traditional dealer hierarchies in Geneva and Dubai. |
Methodological Framework
A standing panel of rough stone procurement directors, master faceting craftsmen, luxury house sourcing executives, and Dubai Multi Commodities Centre compliance officers provided ongoing calibration against operating conditions. Primary interviews with these stakeholders combined with secondary validation from Kimberley Process annual reports, UAE Ministry of Economy trade statistics, Swissmedic AML filings, and Antwerp trading floor customs data. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation dimensions spanning product type, quality grade, form, and end-user archetype. CAGRs derived from fitted growth curves incorporating bridal market liquidity indices, collector auction velocity, and industrial abrasive substitution rates. Modeled inputs included artisanal mining output fluctuations in Myanmar and Colombia, plus REACH amendment implementation timelines.
Sensitivities concentrate around Treasury sanctions enforcement on Burmese rubies, EU due diligence rule expansion, and generational attrition in Jaipur and Surat craftsmanship pools. Forecasts reflect documented assumptions subject to revision from these factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Garnet Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Cesium Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Sodium Tungstate Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Zinc Sulfate Market