
 Middle East and Africa Bone Glue Market | 2026-2036
Middle East and Africa Bone Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Bone Glue Market Foresight
Polymethyl methacrylate-based bone cement is expanding its share as hospitals across the Middle East and Africa substitute traditional mechanical fixation with adhesive-based solutions in hip and knee arthroplasty. Stryker leverages its orthopedic implant ecosystem to bundle bone glue with joint replacement systems across Gulf Cooperation Council markets. Zimmer Biomet anchors its regional presence through distributor partnerships that reach secondary hospitals in Nigeria and Kenya. Medtronic competes by integrating bone adhesive platforms with its broader surgical navigation portfolio.
Bone glue comprises biocompatible adhesives formulated from synthetic polymers, natural proteins, or bioactive ceramics that polymerize in situ to bond bone fragments or secure implants to osseous tissue; these materials typically achieve compressive strengths of 50-90 MPa and cure within 8-15 minutes under physiological conditions. Synthetic polymers command the largest volume share due to their predictable setting kinetics and shelf stability in climates with variable cold-chain reliability. Bioadhesives represent the fastest-expanding category as research institutions in the region validate marine-derived and plant-based formulations for reduced inflammatory response. Orthopedic surgery absorbs the majority of current demand, though trauma surgery applications are widening as emergency medicine capabilities improve across North African markets.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce biocompatibility testing aligned with ISO 10993 standards, while the UAE's MOHAP requires registration documentation that slows market entry for unvalidated suppliers. These frameworks elevate compliance costs but protect incumbent manufacturers with established quality management systems. Stakeholders must monitor how Egypt's drug authority harmonizes with Gulf regulatory standards as the country expands its medical device manufacturing zone near Suez.
Market Dynamics
Biocompatibility certification requirements from Saudi Arabia's SFDA and South Africa's SAHPRA are compressing the supplier base while elevating synthetic polymer formulations over traditional mechanical fixation in orthopedic departments across tertiary hospitals.
Growth Catalysts
- SFDA biocompatibility alignment with ISO 10993:Saudi Arabia's tightened implantable material standards accelerate hospital procurement of certified synthetic bone adhesives for arthroplasty procedures.
- Medical city construction:Government healthcare privatization in Saudi Arabia creates concentrated demand for advanced surgical consumables in newly commissioned orthopedic centers.
- Marine-derived bioadhesive research:Regional research institutions validate plant-based and marine-sourced formulations, expanding clinical options for trauma fixation with reduced inflammatory profiles.
Market Restraints
- Cold-chain reliability gaps:Variable refrigeration infrastructure across secondary hospitals in Nigeria and Kenya limits shelf-stable natural protein adhesive distribution.
- Registration documentation burdens:UAE's MOHAP requires extensive validation paperwork that extends market entry timelines for emerging suppliers without established quality systems.
- Mechanical fixation substitution resistance:Traditional plate-and-screw systems retain preference in cost-constrained public hospital procurement committees.
Strategic Opportunities
- Egypt's Suez manufacturing zone expansion:Harmonization of Egyptian drug authority standards with Gulf regulatory frameworks positions local production for regional export.
- Emergency medicine capability building:North African trauma surgery applications widen as Morocco and Algeria invest in ambulance-based fracture stabilization protocols.
- Digital surgical navigation integration:Convergence of bone adhesive platforms with intraoperative imaging systems creates bundled procurement opportunities in South African academic medical centers.
Industry Challenges
- Polymer chemistry specialization scarcity:Formulation scientists with orthopedic biomaterials expertise remain concentrated in Johannesburg and Riyadh, constraining regional technical support capacity.
- Multi-jurisdiction certification complexity:Separate SAHPRA and SFDA approval pathways force duplicate clinical testing investments for products targeting both South African and Gulf markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Bone Glue Market |
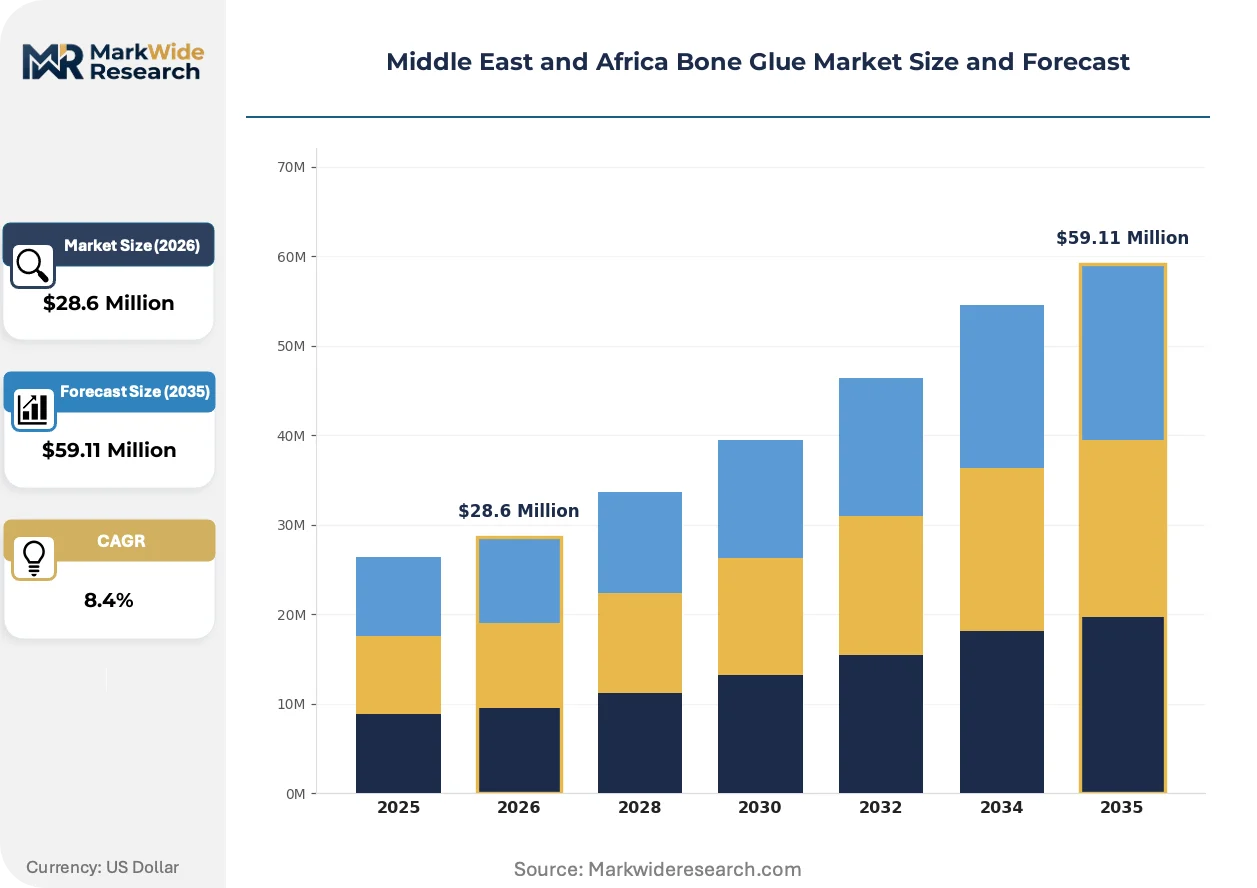
| Market Size in 2026 | $28.6 Million |
| Market Size in 2035 | $59.11 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellular Adhesives, Synthetic Polymers, Natural Adhesives, Bioadhesives Application: Orthopedic Surgery, Dental Procedures, Trauma Surgery, Surgical Fixation End User: Hospitals, Clinics, Outpatient Facilities, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | Stryker, Zimmer Biomet, Medtronic, B. Braun Melsungen AG, DePuy Synthes, Smith & Nephew, Arthrex, DJO Global, Heraeus Medical, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Bone Glue Market Shifts & Advancements
Synthetic polymer curing kinetics and bioadhesive sourcing strategies are reshaping competitive positioning in Middle East and Africa orthopedic supply chains, with regulatory compliance emerging as the primary differentiation mechanism.
Photocurable cyanoacrylate formulations with tunable viscosity profiles are penetrating trauma surgery suites in South African tertiary hospitals. Emergency medicine departments in Cape Town and Durban are adopting these adhesives for rapid wound closure and temporary fracture stabilization. This technology is converging with point-of-care ultrasound imaging to enable adhesive application under real-time bone visualization, compressing the timeline between injury presentation and definitive fixation.
SAHPRA's phased implementation of medical device registration requirements aligned with ISO 10993 biocompatibility testing is elevating compliance costs for imported bone cements. South African orthopedic distributors are consolidating supplier relationships toward manufacturers with pre-existing European CE marking or US FDA clearance. Synthetic polymer categories with established international regulatory histories capture disproportionate procurement share in Johannesburg's private hospital networks.
Hospital purchasing committees in Saudi Arabia are unbundling bone adhesive procurement from implant manufacturer bundles, creating direct sourcing relationships with specialized consumables distributors. This disintermediation pressures traditional orthopedic device vendors who previously captured adhesive sales through joint replacement system contracts. The shift is most visible in Riyadh's medical cities, where procurement autonomy allows materials managers to optimize adhesive selection independent of implant vendor preferences.
Middle East and Africa Bone Glue Market Segmentation
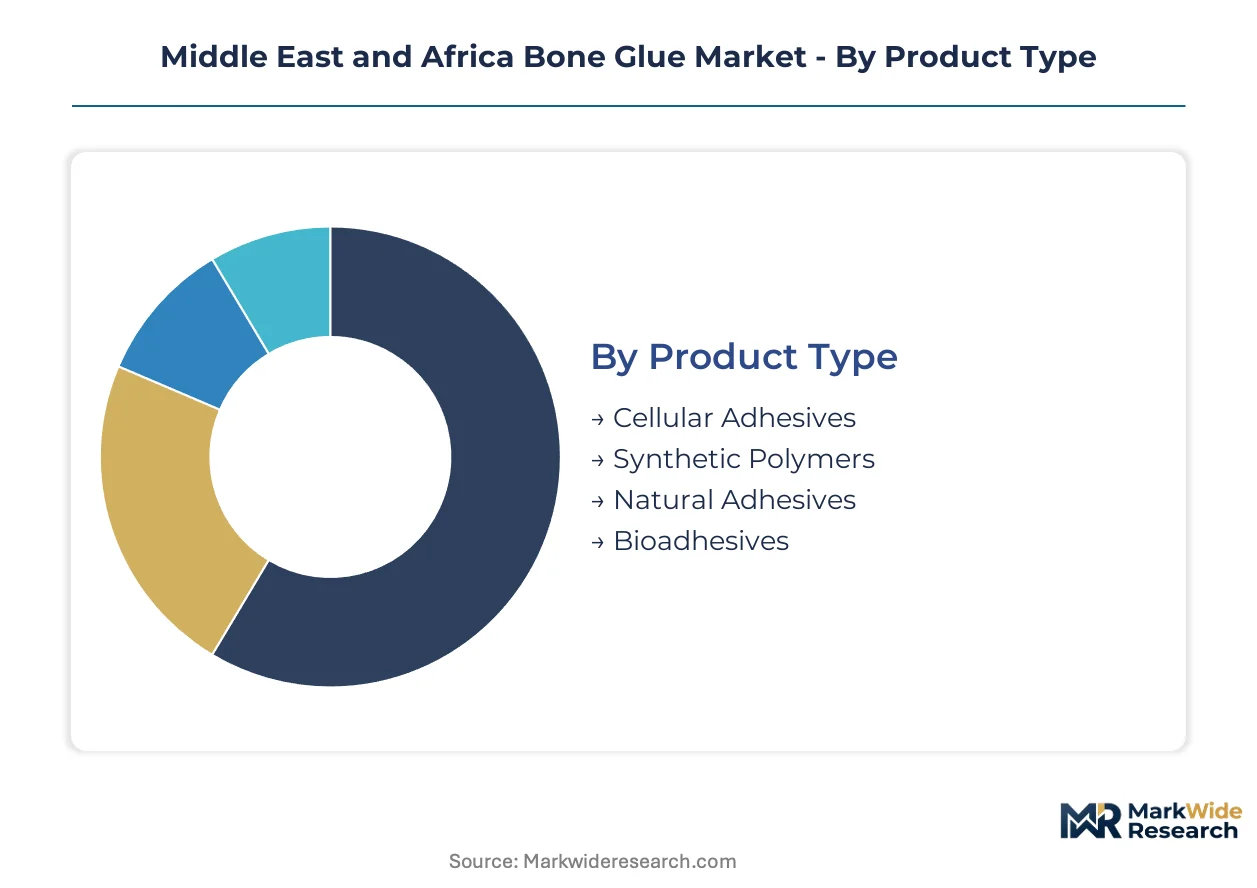
Segmentation in the Middle East and Africa bone glue market reveals how procurement patterns diverge across regulatory environments, climate constraints, and surgical capability tiers. Understanding these divisions exposes where formulation investments concentrate and which customer types drive technology transitions.
Product Type:
Replacement cycles for bone adhesives accelerate as hospitals retire mechanical fixation systems and adopt polymer-based alternatives with validated biocompatibility certifications.
- Synthetic Polymers:Formulations based on polymethyl methacrylate and related acrylic compounds deliver compressive strengths of 50-90 MPa with predictable 8-15 minute cure times. Tertiary hospitals in Saudi Arabia's medical cities prioritize these materials for hip and knee arthroplasty, where SFDA biocompatibility alignment with ISO 10993 has compressed supplier qualification timelines.
- Bioadhesives:Marine-derived and plant-based formulations polymerize through enzymatic or pH-triggered mechanisms rather than exothermic reactions. Research institutions in South Africa and the UAE are validating these materials for reduced inflammatory response in trauma applications, though cold-chain requirements constrain distribution to secondary hospitals in Nigeria and Kenya.
- Natural Adhesives:Protein-based formulations derived from collagen and fibrinogen require refrigeration infrastructure that remains inconsistent across North African emergency medicine networks.
- Cellular Adhesives:Experimental formulations incorporating osteogenic cells remain confined to academic medical centers in Johannesburg and Riyadh with active tissue engineering programs.
Synthetic Polymers sit at the top of the volume ranking, with Bioadhesives climbing the fastest as regional research validates alternative sourcing strategies.
Application:
Cost tier differentiation separates high-complexity arthroplasty centers from resource-constrained trauma units, with adhesive selection tracking surgical volume and reimbursement levels.
- Orthopedic Surgery:Joint reconstruction and elective arthroplasty procedures consume the majority of certified bone cement volumes. Saudi Arabian medical cities and South African private hospital networks concentrate demand here, where procurement committees unbundle adhesive selection from implant manufacturer contracts.
- Trauma Surgery:Emergency fracture stabilization drives adoption of rapid-cure cyanoacrylate formulations in Cape Town and Durban, where ambulance-based protocols and point-of-care ultrasound enable adhesive application under real-time visualization.
- Dental Procedures:Maxillofacial reconstruction applications in UAE and Lebanese private clinics utilize smaller-format adhesive delivery systems with specialized viscosity profiles.
- Surgical Fixation:General operative applications including sternal closure and cranial flap reattachment absorb residual volumes through distributor networks reaching secondary hospitals.
Orthopedic Surgery commands procurement priority in Gulf markets, while Trauma Surgery gains share fastest as North African emergency medicine capabilities expand.
End User:
Customer type determines whether adhesives enter through bundled implant contracts or direct materials management relationships, with implications for pricing transparency and formulation choice.
- Hospitals:Tertiary institutions with orthopedic surgery departments drive specification-setting for the broader market. Saudi Arabia's government healthcare privatization and medical city construction are concentrating procurement authority in materials management offices with autonomous adhesive selection.
- Clinics:Ambulatory surgical centers in South African urban corridors and UAE free zones handle lower-complexity procedures with simplified adhesive requirements.
- Outpatient Facilities:Day-surgery units in Moroccan and Algerian cities are expanding fracture stabilization capabilities, creating incremental demand for rapid-cure formulations.
- Research Institutions:Universities in Johannesburg, Riyadh, and Cape Town validate novel bioadhesive chemistries, though clinical translation timelines extend commercial relevance.
Hospitals anchor absolute volume, with Outpatient Facilities expanding most quickly as ambulatory surgery infrastructure proliferates.
Distribution Channel:
Supply concentration among established distributors with multi-jurisdiction regulatory expertise creates barriers for direct manufacturer engagement with smaller hospital accounts.
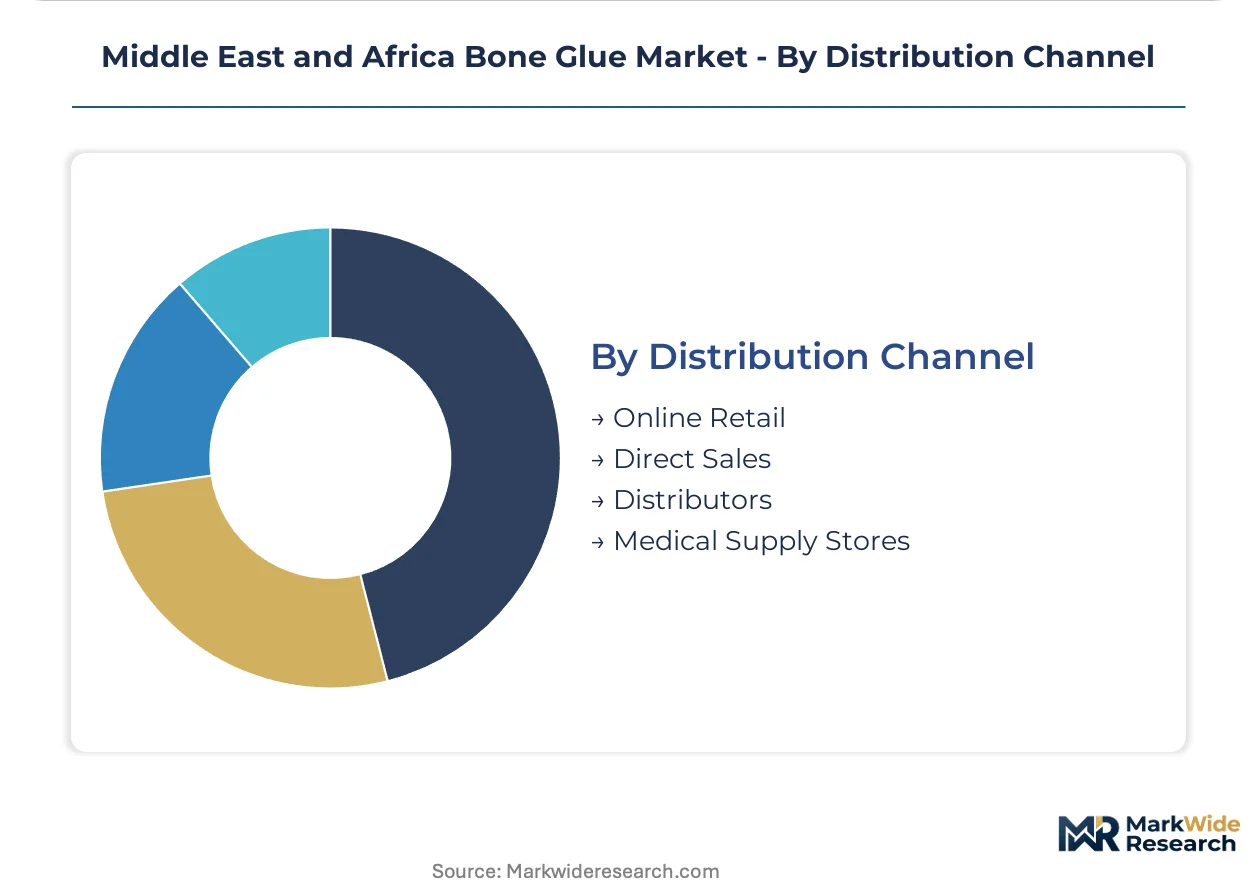
- Distributors:Specialized surgical consumables distributors with SAHPRA and SFDA compliance capabilities dominate procurement channels. Zimmer Biomet and Stryker leverage these relationships to reach secondary hospitals in Nigeria and Kenya beyond their direct sales footprints.
- Direct Sales:Implant manufacturers bundle bone adhesives with joint replacement systems in Gulf Cooperation Council markets, though Saudi medical city procurement autonomy is eroding this channel.
- Medical Supply Stores:Regional wholesalers serve dental and small-clinic accounts with lower regulatory validation requirements.
- Online Retail:E-procurement platforms remain marginal due to cold-chain and documentation requirements that favor established distributor relationships.
Distributors maintain channel leadership, with Direct Sales facing pressure as hospital procurement autonomy expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's medical cities concentrate procurement authority for bone adhesives, with tertiary hospital construction driving specification-setting across the Gulf. Regulatory harmonization between Gulf Cooperation Council states is compressing supplier qualification timelines for certified synthetic polymers.
Saudi Arabia
Government healthcare privatization and medical city construction in Riyadh and Jeddah generate concentrated demand for SFDA-certified bone cements. The Saudi Food and Drug Administration enforces ISO 10993-aligned biocompatibility testing that elevates synthetic polymer formulations over traditional mechanical fixation. Procurement autonomy in King Faisal Specialist Hospital and other tertiary centers enables direct adhesive sourcing independent of implant vendor bundles.
South Africa
Private hospital networks in Johannesburg and Cape Town drive specification-setting for arthroplasty adhesives with validated regulatory histories. The South African Health Products Regulatory Authority's phased medical device registration requirements favor suppliers with pre-existing CE marking or FDA clearance. Academic medical centers in Gauteng province validate photocurable cyanoacrylate formulations for trauma applications converging with point-of-care ultrasound.
United Arab Emirates
MOHAP registration documentation requirements extend market entry timelines for emerging bone adhesive suppliers without established quality systems. Dubai's private clinic networks and ambulatory surgical centers in healthcare free zones handle maxillofacial reconstruction with specialized viscosity profiles. Secondary hospital procurement in Northern Emirates remains constrained by distributor concentration among established surgical consumables channels.
Egypt
Medical device manufacturing zone expansion near Suez positions local production for regional export as the Egyptian drug authority harmonizes with Gulf regulatory frameworks. Public hospital procurement committees retain preference for traditional plate-and-screw systems in cost-constrained environments. Alexandria and Cairo tertiary centers represent incremental demand for rapid-cure formulations as emergency medicine capabilities expand.
Nigeria
Secondary hospital networks in Lagos and Abuja absorb bone adhesive volumes through distributor partnerships reaching beyond direct manufacturer footprints. Variable cold-chain reliability limits shelf-stable natural protein adhesive distribution to facilities with consistent refrigeration infrastructure. Trauma surgery applications widen as emergency medicine investment concentrates in federal teaching hospitals.
Middle East and Africa Bone Glue Market Competitive Landscape
Strategic partnerships dominate the current landscape as orthopedic implant manufacturers bundle bone adhesives with joint replacement systems. The supplier base compresses toward incumbents with multi-jurisdiction regulatory expertise spanning SAHPRA and SFDA requirements. Three archetypes define positioning: diversified medical device conglomerates with orthopedic ecosystems, specialized surgical consumables distributors with regional compliance capabilities, and research-oriented institutions validating novel bioadhesive chemistries. Competitive moves center on procurement autonomy erosion through direct hospital relationships and technology convergence with intraoperative imaging platforms.
Among diversified medical device conglomerates, Stryker, Zimmer Biomet, and Medtronic exemplify distinct strategic positions. Stryker leverages its orthopedic implant ecosystem to bundle bone glue with joint replacement systems across Gulf Cooperation Council markets. Zimmer Biomet anchors its regional presence through distributor partnerships that reach secondary hospitals in Nigeria and Kenya. Medtronic occupies a position integrating bone adhesive platforms with its broader surgical navigation portfolio, particularly in South African academic medical centers where digital convergence creates bundled procurement opportunities.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Medtronic |
| B. Braun Melsungen AG |
| DePuy Synthes |
| Smith & Nephew |
| Arthrex |
| DJO Global |
| Heraeus Medical |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility alignment gates both qualified supply and premium-tier pricing access, as Saudi Arabia's SFDA and South Africa's SAHPRA enforce testing standards that compress the supplier base toward certified synthetic polymer formulations with validated regulatory histories.
Pricing Analysis
Raw material cost pass-through from methyl methacrylate monomer suppliers concentrates in synthetic polymer formulations, with acrylic compound price volatility compressing margins for distributors serving secondary hospitals. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified medical city procurements from MOHAP-registered UAE deliveries and unvalidated economy-tier imports. Pricing pressure stems from procurement autonomy in Riyadh's tertiary centers unbundling adhesives from implant contracts. Public hospital committees in Egypt and Nigeria exhibit highest price sensitivity, while Saudi medical cities prioritize certification grade over unit cost.
Supply Chain Analysis
Polymer chemist and biomedical formulation scientist scarcity in Johannesburg and Riyadh constrains technical support capacity for regional manufacturing scale-up. Supply concentrates in Germany, Switzerland, and the United States for PMMA precursor chemicals, while cold-chain infrastructure gaps in Nigeria and Kenya limit natural protein adhesive distribution. Raw material dependencies on petroleum-derived acrylic monomers, ceramic filler compounds, and marine-derived bioadhesive feedstocks expose the chain to commodity price volatility. Distribution runs through specialized surgical consumables distributors with multi-jurisdiction SAHPRA and SFDA compliance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement committees in Saudi medical cities shifting specification authority toward materials managers prioritizing ISO 10993-certified synthetic polymers over bundled implant-adhesive contracts.
For Market Incumbents: Extend regulatory certification moats by accelerating SAHPRA and SFDA alignment for next-generation photocurable cyanoacrylate formulations, defending against emerging bioadhesive specialists with marine-derived alternatives. Deepen distributor partnerships in Nigeria and Kenya to offset procurement autonomy erosion in Gulf medical cities. Prioritize backward integration into PMMA precursor supply to buffer acrylic monomer cost volatility. For New Entrants and Emerging Players: E-procurement platform specialization offers a lower-friction entry path for validated synthetic polymer formulations targeting Egyptian and Algerian outpatient facilities with simplified documentation requirements. White-space concentrates in trauma surgery rapid-cure applications across North African emergency medicine networks and dental maxillofacial reconstruction in UAE free zone clinics. Pursue research institution co-development partnerships in Cape Town and Riyadh to accelerate bioadhesive clinical validation. For Investors and Strategic Acquirers: Roll-up economics work for specialized surgical consumables distributors with multi-jurisdiction compliance capabilities because SAHPRA and SFDA approval pathway fragmentation forces duplicate testing investments that favor consolidated regulatory expertise. Long-term viability centers on platform convergence with intraoperative imaging and surgical navigation systems. Monitor Egypt's Suez manufacturing zone regulatory harmonization progress as the inflection signal for regional production repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Biocompatibility Certification Investment | Accelerates hospital procurement qualification timelines in Saudi medical cities. |
| Distributor Partnership Consolidation | Extends reach to secondary hospitals in Nigeria and Kenya beyond direct sales footprints. |
| Marine-Derived Bioadhesive R&D Collaboration | Validates reduced inflammatory response formulations with Cape Town research institutions. |
| Photocurable Cyanoacrylate Platform Launch | Captures trauma surgery demand in South African emergency medicine departments. |
| Surgical Navigation Integration Development | Creates bundled procurement opportunities in Johannesburg academic medical centers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining orthopedic surgeon and hospital purchasing committee discussions with biomedical engineer and distributor compliance officer perspectives. Secondary validation drew from SFDA medical device registration databases, SAHPRA submission records, hospital procurement contract repositories, and GCC customs trade data. Bottom-up adhesive volume modeling triangulated against top-down surgical procedure forecasts.
Historical reference periods anchored the projection framework to pre-pandemic arthroplasty volumes and post-privatization Saudi medical city commissioning timelines. Segmentation dimensions spanned product type, application, end user, and distribution channel, with regional regulatory cluster and cold-chain infrastructure tier as cross-cutting variables. CAGRs derived from procedure volume elasticities and adhesive consumption per surgery ratios, incorporating PMMA price index trajectories and bioadhesive clinical trial enrollment curves.
The model assumes a particular technology adoption path; alternative pathways for marine-derived bioadhesive polymerization mechanisms would alter the outlook if enzymatic trigger systems demonstrate superior inflammatory profiles in head-to-head trials. Forecasts reflect assumptions regarding SFDA-Egyptian drug authority harmonization velocity and Gulf medical city procurement autonomy expansion. Material deviation in Saudi healthcare privatization timelines or SAHPRA registration requirement implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Plastic Adhesives Market