
 Global Soft Magnetic Materials Market | 2026-2036
Global Soft Magnetic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soft Magnetic Materials Market Intelligence
High-performance nanocrystalline alloy development is tilting the industry's profit focus away from commoditized silicon steel production. Vacuumschmelze GmbH & Co. KG specializes in these advanced materials for demanding applications in the automotive and industrial sectors. Meanwhile, steel giants like JFE Steel Corporation leverage massive scale in electrical steel production for transformers. Hitachi Metals, Ltd. competes through its strong portfolio in both amorphous and nanocrystalline products.
Soft magnetic materials are substances characterized by low coercivity, allowing for easy magnetization and demagnetization with minimal energy loss. Their primary function is to concentrate and direct magnetic flux within components used in electrical power conversion and distribution. While silicon steel continues to dominate high-volume applications like transformers and electric motors, advanced nanocrystalline alloys are gaining traction. These materials are critical for high-frequency inductors and magnetic sensors where superior performance justifies a higher cost.
Regulatory frameworks directly influence material selection and product design. The EU's RoHS directive governs material composition in electronics, while its Ecodesign requirements push for higher efficiency in transformers and motors. In parallel, Japan's JIS standards and China's GB standards set stringent performance benchmarks for electrical steels. End-users must continually balance the upfront cost of advanced materials against the long-term operational savings from superior energy efficiency.
Market Dynamics
The market's structural dynamics are defined by the global push for higher energy efficiency in power conversion and electric mobility. This pressure forces a material-level trade-off between the high-volume affordability of silicon steel and the superior performance of advanced alloys for specialized applications.
Growth Catalysts
- EU Ecodesign Directive:Mandates for higher energy efficiency in electric motors and transformers are compelling manufacturers to adopt higher-grade soft magnetic materials, including advanced electrical steels and amorphous alloys.
- Electric Vehicle Production:The expansion of EV manufacturing, particularly in China and Germany, creates sustained demand for high-performance materials like nanocrystalline alloys for traction motors and onboard chargers.
- High-Frequency Power Electronics:The shift towards higher switching frequencies in power supplies and inverters for industrial automation requires materials with lower core losses, favoring amorphous and nanocrystalline types.
Market Restraints
- Raw Material Volatility:The pricing and availability of critical raw materials, such as cobalt and rare earth elements used in some high-performance alloys, introduce significant cost uncertainty for specialty producers.
- Silicon Steel Production Scale:The massive capital investment required for electrical steel production concentrates supply among a few large mills in Asia, creating potential bottlenecks and price leverage.
- Ferrite Material Competition:In certain low-power, high-frequency applications, cost-effective ferrite cores present a viable alternative to metallic soft magnetic materials, capping price ceilings for some amorphous products.
Strategic Opportunities
- Wireless Power Transfer:The development of high-power wireless charging systems for EVs and industrial equipment creates a new market for materials optimized for high-frequency magnetic field shielding and flux guidance.
- Indian Industrial Modernization:India's focus on upgrading its power grid and expanding domestic electronics manufacturing under national initiatives offers significant growth potential for electrical steel and amorphous materials.
- Grid-Scale Energy Storage:Government incentives for battery energy storage systems in the US and Europe are driving demand for large, efficient transformers and inductors, creating opportunities for advanced electrical steels.
Industry Challenges
- Nanocrystalline Annealing Complexity:Achieving consistent material properties in nanocrystalline ribbon production requires precise control over annealing processes, a significant operational challenge that limits yield and scalability for many manufacturers.
- Global Standards Harmonization:Navigating divergent performance standards for electrical steels, such as Japan's JIS and China's GB standards, complicates product development and inventory management for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soft Magnetic Materials Market |
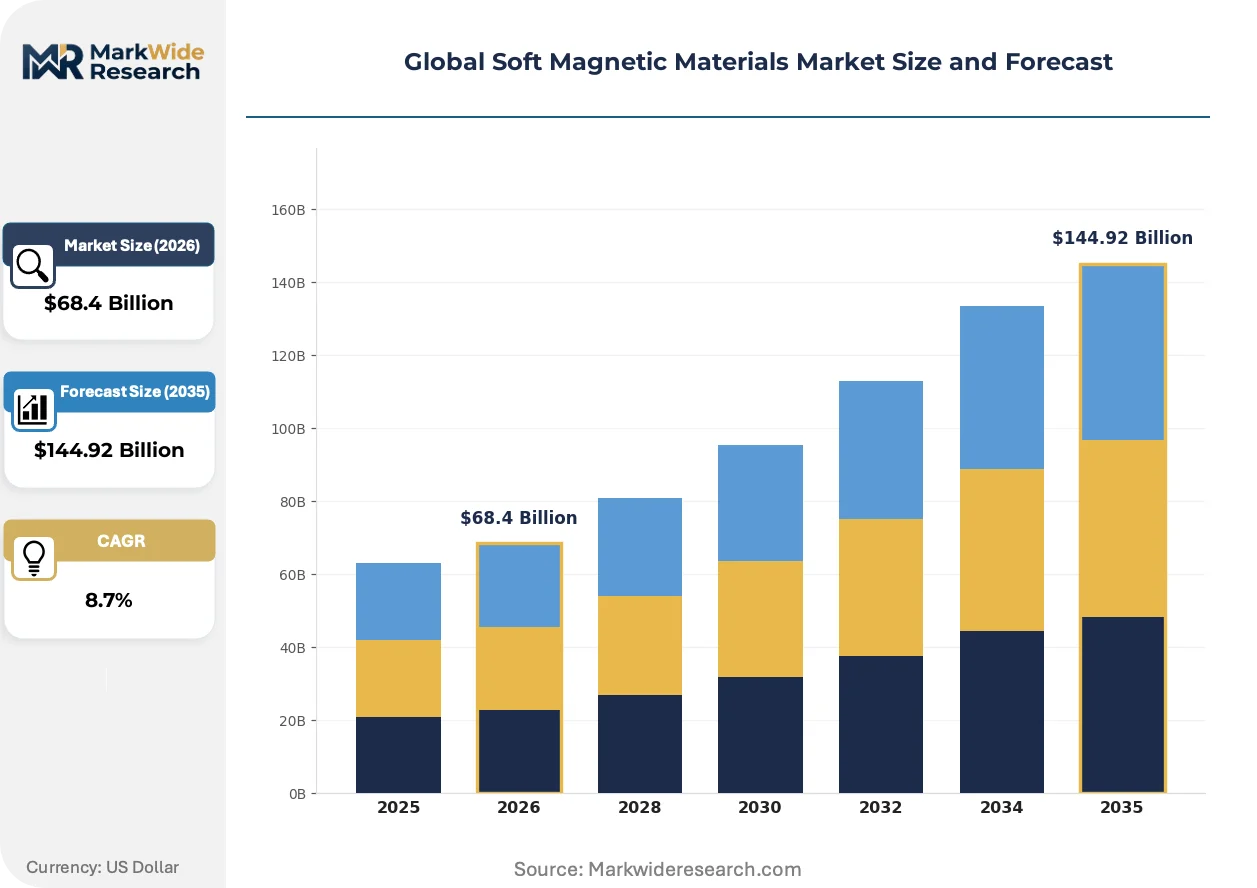
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Steel, Amorphous Metal, Nanocrystalline Alloy, Ferrite, Alnico Technology: Electrical Steel, Powder Metallurgy, Vacuum Casting, Sputtering, Laser Annealing Application: Transformers, Inductors, Magnetic Sensors, Electric Motors, Generators End User: Consumer Electronics Manufacturers, Renewable Energy Firms, Aerospace Suppliers, Telecommunications Providers |
| Companies Covered | Nippon Steel Corporation, Sumitomo Metal Mining Co., Ltd., Hitachi Metals, Ltd. (Proterial, Ltd.), Arnold Magnetic Technologies, Daido Steel Co., Ltd., TDK Corporation, JFE Steel Corporation, Toshiba Materials Co., Ltd., Vacuumschmelze GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soft Magnetic Materials Market Strategic Shifts & Innovations
A fundamental shift is underway as material selection moves from a component choice to an integrated part of system-level engineering. This change prioritizes co-design between material scientists and component engineers to optimize for specific performance outcomes like thermal management.
Advanced magnetic modeling software allows engineers to simulate the performance of materials like nanocrystalline alloys under complex thermal and electrical loads. Automotive and aerospace design teams are adopting these tools to shorten development cycles. This software-led approach is virtualizing the material selection and prototyping process, reducing reliance on costly physical testing.
China's dual carbon policy framework is driving updates to its GB standards, mandating higher efficiency for industrial electric motors. These requirements force a transition from lower-grade silicon steels toward higher-permeability electrical steels and amorphous metals. Domestic motor manufacturers must upgrade material inputs to comply with new energy efficiency labels.
Buyers in high-performance sectors are moving from transactional, catalog-based procurement of standard magnetic materials. They are forming long-term partnerships with material specialists to co-create custom alloy compositions for specific applications. This collaborative model is most prominent in the EV and high-frequency power electronics segments.
Global Soft Magnetic Materials Market Segmentation
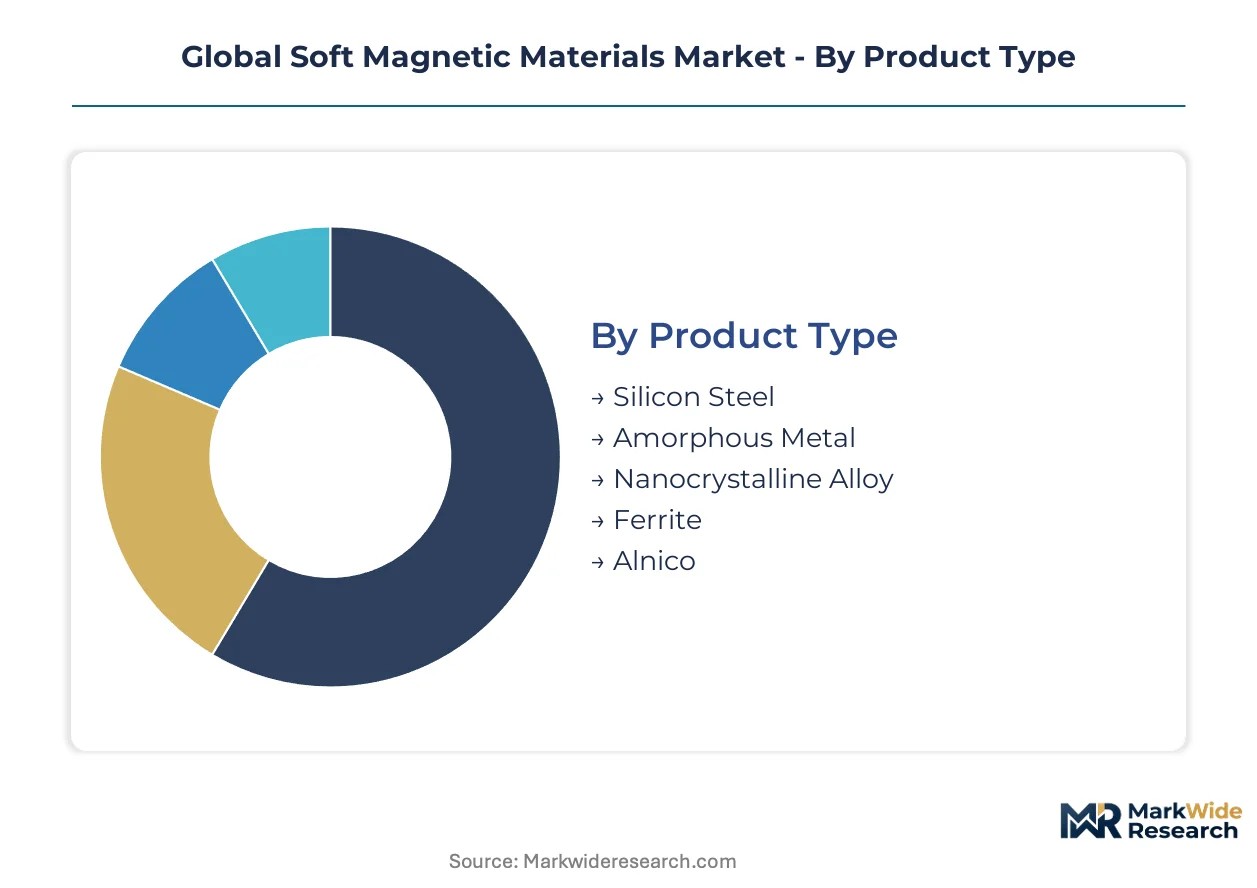
The structural composition of the global soft magnetic materials market reflects diverse performance requirements across various industrial and consumer applications. Understanding these segments is essential for producers to align material development with specific end-use demands. This analysis delineates the market by product type, underlying technology, primary application, and key end-user industries.
Product Type:
The market for soft magnetic materials exhibits varying innovation cycles, with some product types evolving rapidly to meet new performance benchmarks while others maintain established production rhythms.
- Silicon Steel:This iron-silicon alloy offers high saturation magnetization and low core losses at power frequencies for transformers and motors. Demand concentrates in China and India due to its cost-effectiveness and mature production.
- Nanocrystalline Alloy:These advanced iron-based materials provide superior magnetic permeability and extremely low core losses at high frequencies. Electric vehicle powertrains and onboard chargers in Germany and Japan drive significant demand.
- Amorphous Metal:This non-crystalline alloy offers lower core losses, finding use in energy-efficient distribution transformers.
- Ferrite:Ferrites are cost-effective ceramic compounds for high-frequency, low-power applications in consumer electronics.
- Alnico:Alnico, an alloy of aluminum, nickel, and cobalt, provides high magnetic strength for specialized sensors.
Silicon Steel dominates the installed base for power distribution. Nanocrystalline Alloy is where expansion concentrates for high-performance applications.
Technology:
Different manufacturing technologies enable the production of soft magnetic materials tailored for distinct performance envelopes, from bulk power handling to precision sensing.
- Electrical Steel:This technology involves precise alloying, rolling, and annealing to produce iron-silicon sheets with controlled grain orientation. It is critical for transformers and motors, with production scale concentrated in China and South Korea.
- Powder Metallurgy:This process forms complex magnetic components by compacting metal powders, offering design flexibility and reduced eddy current losses. Applications in automotive sensors and high-density inductors are expanding across Europe and North America.
- Vacuum Casting:Vacuum casting produces amorphous and nanocrystalline ribbons by rapidly solidifying molten metal.
- Sputtering:Sputtering creates nanoscale magnetic layers via thin-film deposition for advanced sensors and micro-inductors.
- Laser Annealing:Laser annealing refines magnetic domains within electrical steel, enhancing permeability and reducing core losses.
Electrical Steel technology underpins most high-volume production. Powder Metallurgy is gaining share fastest for customized, high-frequency components.
Application:
The scale and specific requirements of end-use applications dictate the selection and consumption patterns of soft magnetic materials across the market.
- Electric Motors:Soft magnetic materials are essential for efficient energy conversion in motors, forming the core of stators and rotors. Rapid EV manufacturing expansion in China and the European Union drives significant demand.
- Transformers:These devices rely on soft magnetic cores for efficient energy transfer between circuits, minimizing loss. Grid modernization efforts and renewable energy integration in the United States and India increase demand.
- Inductors:Inductors require materials with low core losses for energy storage and filtering in high-frequency power electronics.
- Magnetic Sensors:Magnetic sensors utilize soft magnetic materials for high sensitivity in automotive and industrial control systems.
- Generators:Generators use soft magnetic materials as core components for efficient conversion of mechanical energy into electrical power.
Electric Motors represent the largest volume application, particularly with EV growth. Magnetic Sensors show significant innovation and future demand.
End User:
Different end-user industries hold distinct positions within the value chain, driving material innovation and procurement strategies based on their product lifecycles and performance needs.
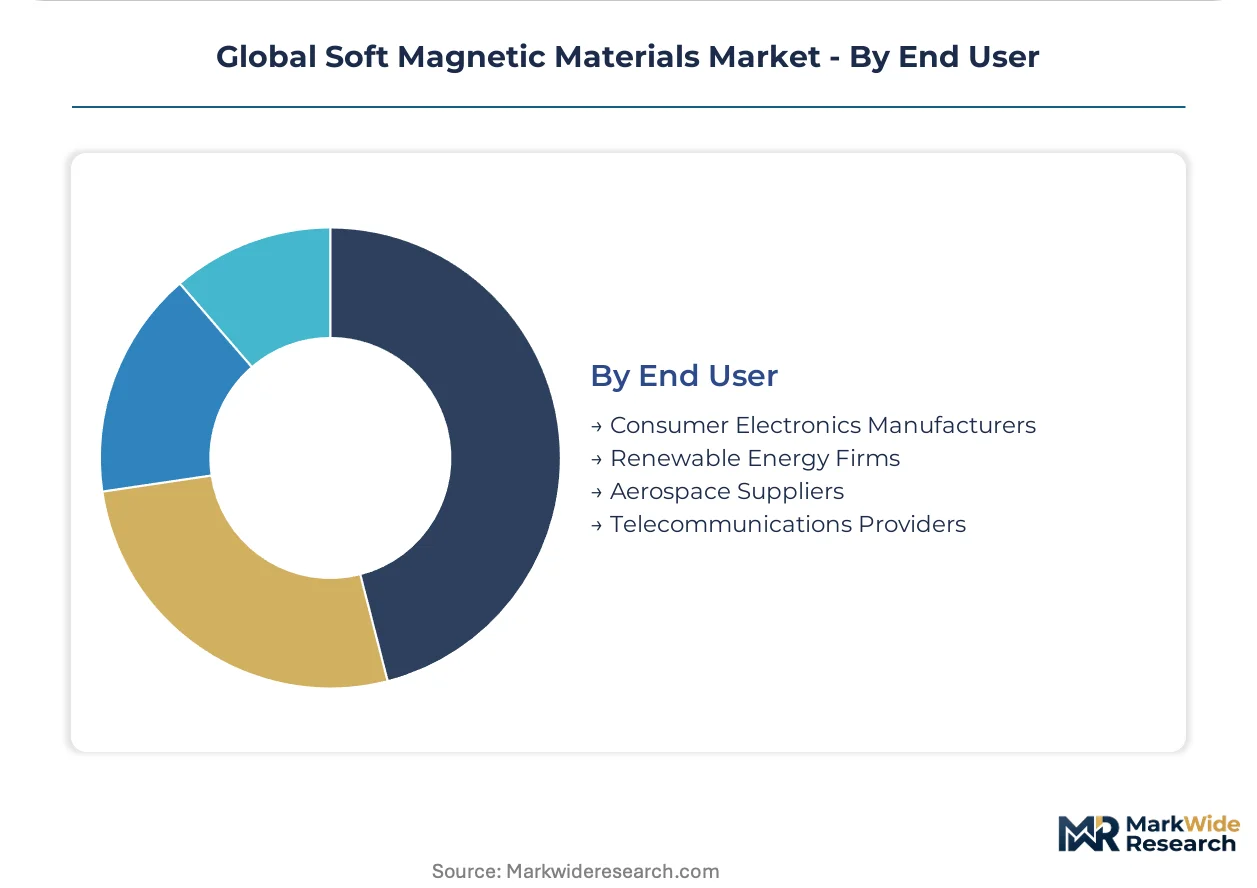
- Consumer Electronics Manufacturers:These firms integrate soft magnetic materials into devices like smartphones, laptops, and chargers for power conversion and EMI suppression. Miniaturization and EU energy efficiency mandates influence material selection.
- Renewable Energy Firms:Companies in solar and wind power generation utilize soft magnetic materials in inverters, converters, and transformers for efficient grid integration. US and European incentives spur demand for high-efficiency components.
- Aerospace Suppliers:Aerospace suppliers require high-reliability, lightweight soft magnetic materials for critical power systems and sensors.
- Telecommunications Providers:Telecommunications providers use soft magnetic materials in network infrastructure for signal processing and power management.
Consumer Electronics Manufacturers drive high-volume material procurement. Renewable Energy Firms are pushing for advanced material adoption due to efficiency targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for soft magnetic materials varies significantly by geography, reflecting regional industrial strengths and regulatory priorities. While some regions prioritize high-volume, cost-effective silicon steel, others drive demand for advanced, high-performance alloys. This differentiation shapes material development and supply chain dynamics across the global market.
China
Rapid expansion in electric vehicle manufacturing and electronics production fuels substantial demand for soft magnetic materials. China's GB standards, increasingly aligned with its dual carbon policy, mandate higher efficiency for industrial electric motors. Major automotive and electronics manufacturing hubs in the Yangtze River Delta are upgrading material inputs to comply with these new energy efficiency labels.
Germany
Germany's robust automotive and industrial sectors drive significant demand for high-performance nanocrystalline alloys. The EU's Ecodesign Directive compels manufacturers to adopt higher-grade soft magnetic materials for energy-efficient motors and transformers. Key industrial clusters in Bavaria and Baden-Württemberg are at the forefront of developing advanced magnetic components for demanding applications.
Japan
Japan's market focuses on high-frequency inductors and magnetic sensors, leveraging its strong portfolio in amorphous and nanocrystalline products. The country's JIS standards set stringent performance benchmarks for electrical steels, influencing material innovation. Major electronics and automotive R&D centers in the Kanto region are pushing the boundaries of magnetic material performance.
United States
Grid modernization efforts and renewable energy integration are increasing demand for efficient transformers and inductors in the United States. Government incentives for battery energy storage systems under the IRA further drive the adoption of advanced electrical steels. Innovation hubs in California and the Northeast corridor are developing next-generation power electronics and energy storage solutions.
India
India's industrial modernization initiatives, particularly in power grid upgrades and domestic electronics manufacturing, create growth potential for electrical steel and amorphous materials. The country's national regulators are emphasizing energy efficiency in industrial equipment. Manufacturing zones in Maharashtra and Gujarat are expanding their capacity for electrical steel production and transformer assembly.
Global Soft Magnetic Materials Market Key Industry Players
Capability concentration sits with one tier of specialized material scientists, while scale advantage sits with another tier of integrated steel producers. The market structure is tiered, separating high-volume, commoditized products from niche, high-performance alloys. Strategic archetypes include large-scale steel producers, advanced materials specialists, and component manufacturers. Dominant competitive moves involve both capacity expansion in traditional materials and targeted technology licensing for advanced alloys.
At the scale-driven end, JFE Steel Corporation exemplifies the massive capital investment required for electrical steel production, serving high-volume applications like transformers. Hitachi Metals, Ltd. (Proterial, Ltd.) occupies a position across both traditional and advanced segments, with a strong portfolio in amorphous and nanocrystalline products. Vacuumschmelze GmbH & Co. KG represents the advanced materials specialists, focusing on high-performance nanocrystalline alloys for demanding automotive and industrial applications.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Sumitomo Metal Mining Co., Ltd. |
| Hitachi Metals, Ltd. (Proterial, Ltd.) |
| Arnold Magnetic Technologies |
| Daido Steel Co., Ltd. |
| TDK Corporation |
| JFE Steel Corporation |
| Toshiba Materials Co., Ltd. |
| Vacuumschmelze GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
China's overcapacity in silicon steel production drives aggressive pricing strategies and forces smaller regional players to consolidate or specialize. This utilization pressure shapes global commodity pricing and influences investment in advanced materials.
Pricing Analysis
Long-term offtake agreements dominate pricing for high-volume silicon steel, providing stability for large-scale producers like JFE Steel Corporation. Conversely, advanced nanocrystalline alloys command value-based pricing driven by customization level and superior performance characteristics. Pricing softness for commoditized silicon steel stems from intense competition among Asian mills. Consumer electronics manufacturers exhibit high price sensitivity for ferrite cores, while automotive OEMs prioritize performance over cost for EV traction motors.
Supply Chain Analysis
Extended payment terms are common practice in the electrical steel supply chain, supporting the massive capital expenditures required for mill operations. Supply concentration for silicon steel centers in China and South Korea, while advanced alloys are sourced from Germany and Japan. The industry relies on critical raw materials like iron ore, silicon, cobalt, and rare earth elements, making commodity price volatility a significant structural risk. Distribution runs directly to large original equipment manufacturers and Tier 1 component suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft magnetic materials market faces a talent shortage in advanced alloy design and processing. This expertise gap limits innovation and scalability, creating strategic opportunities for focused investment.
For Market Incumbents: Harden core silicon steel operations by investing in advanced laser annealing technologies to counter efficiency demands from China's GB standards. Pursue targeted R&D in higher-grade electrical steels to mitigate potential displacement by amorphous metals in transformer applications. Strategic acquisitions of smaller nanocrystalline alloy specialists can expand product portfolios. This approach defends against margin pressure from commoditization and emerging material competition.
For New Entrants and Emerging Players: India's underpenetrated industrial modernization sector offers significant white-space opportunities for advanced electrical steels and amorphous materials. Focus on supplying high-frequency inductors for industrial automation, where performance justifies higher material costs. Target the growing market for battery energy storage systems in the United States, leveraging government incentives. A collaborative co-development model with local component manufacturers provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among advanced materials specialists providing custom alloys for long-lifecycle automotive and industrial applications. The long-term viability of this market is secured by the global push for electrification and energy efficiency. Acquisition targets should include niche players with proprietary nanocrystalline or amorphous metal production expertise, particularly those serving the EV sector. Monitor patent filings for novel alloy compositions as an inflection indicator for future market leadership.
| Strategic Initiative | Industry Significance |
|---|---|
| Nanocrystalline Capacity Expansion | Expanding production capacity for nanocrystalline alloys supports electric vehicle manufacturing in Germany and China. |
| Advanced Electrical Steel R&D | Research into higher-grade electrical steels enhances transformer efficiency, aligning with the EU's Ecodesign Directive. |
| Powder Metallurgy Technology Licensing | Licensing powder metallurgy techniques accelerates the development of complex magnetic components for automotive sensors. |
| Supply Chain Resilience Partnerships | Forming long-term partnerships with rare earth element suppliers mitigates raw material volatility for specialty producers. |
| Digital Modeling Software Adoption | Implementing advanced magnetic modeling software shortens development cycles for aerospace power systems. |
Research Approach
Operator-level perspectives from material scientists, automotive engineers, and procurement leads anchored the qualitative base. Primary interviews with these stakeholders were rigorously validated against secondary sources, including company SEC filings, national energy efficiency standards like China's GB standards, and academic research. A comprehensive bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
Scenario-bracketing analysis modeled market evolution across the analysis window, accounting for various technological adoption rates. The analytical framework integrated market segmentation by product type, technology, application, end-user, and regional energy efficiency mandates. Compound annual growth rates were derived from historical trends and projected growth drivers, such as electric vehicle production forecasts and global energy efficiency targets.
Practitioners should monitor shifts in raw material availability and regulatory enforcement for early signals impacting market dynamics. Forecasts reflect current market assumptions, acknowledging raw material volatility and evolving energy efficiency mandates as risks. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Magnet Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market