
 Superconducting Magnets Market | 2026-2036
Superconducting Magnets Market Size, Share, and Industry Trends Forecast 2026-2036
Superconducting Magnets Market Outlook
The EU Green Deal is pivoting procurement standards for energy infrastructure, compelling utilities to evaluate superconducting solutions for grid efficiency. Bruker Corporation leverages its cryogen-free magnet architecture to sustain leadership in analytical instrumentation. Sumitomo Electric Industries Ltd. anchors the high-current cable segment through its niobium-titanium manufacturing scale. Siemens AG competes in medical imaging systems by integrating superconducting coils across its MRI platform.
Superconducting magnets are electromagnets wound from materials that exhibit zero electrical resistance below a critical temperature, typically requiring liquid helium cooling at 4.2 Kelvin or nitrogen-based systems at 77 Kelvin for high-temperature variants, and they generate persistent magnetic fields for particle beam steering, diagnostic imaging, and plasma confinement. Niobium-titanium alloys dominate installed volume due to decades of proven performance in clinical MRI systems, while rare-earth barium copper oxide captures R&D investment as engineers push operating temperatures higher and reduce cryogenic dependency. The energy end-user segment attracts capital as fusion reactor projects in France and South Korea validate large-bore magnet designs for toroidal field coils.
The International Electrotechnical Commission sets performance benchmarks for superconducting device safety, while the FDA governs magnetic field exposure limits for clinical MRI systems in the United States and the EU AI Act imposes documentation requirements on automated diagnostic platforms that integrate these magnets. These frameworks elevate compliance costs for new entrants but protect incumbent manufacturers with established certification pathways. Stakeholders must track which regulatory bodies adopt harmonized standards versus jurisdiction-specific testing regimes, as divergence determines where capital deployment for new production capacity carries lower market-access risk.
Market Dynamics
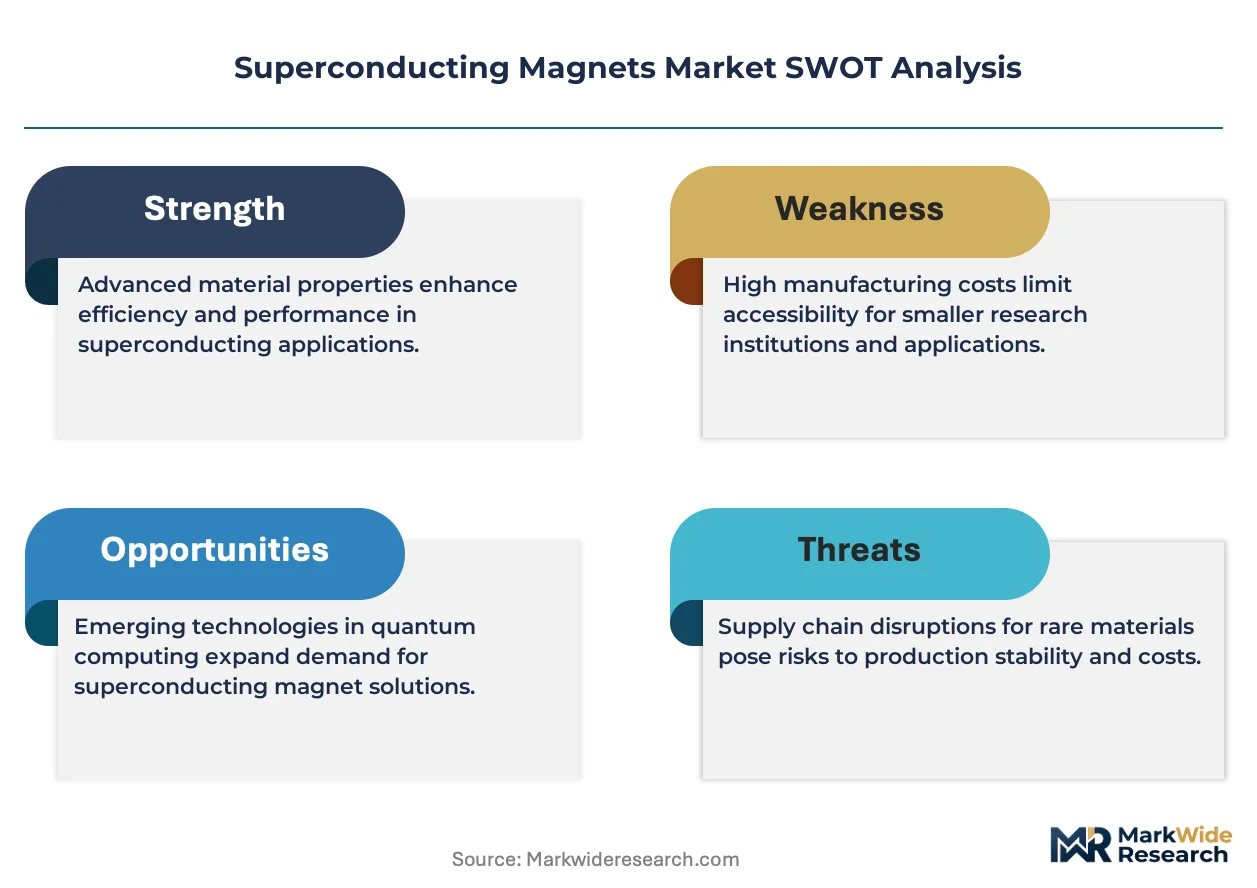
The transition from low-temperature superconductors to high-temperature variants using rare-earth barium copper oxide tape is compressing cryogenic infrastructure requirements and redrawing competitive boundaries across medical imaging and energy applications.
Growth Catalysts
- EU Green Deal procurement mandates:Utilities in France and Germany must evaluate superconducting grid solutions for efficiency gains, accelerating utility-scale demonstrations.
- Fusion energy programs:Toroidal field coil deployments in France, South Korea, and the United States validate large-bore magnet architectures and sustain R&D funding pipelines.
- Healthcare diagnostic mandates:Japan and Germany are scaling MRI deployments under stricter imaging standards, expanding installed base for niobium-titanium systems.
Market Restraints
- Liquid helium supply concentration:Qatar and the United States control over 75% of global helium production, exposing magnet operators to price volatility and export restriction risks.
- Cryogenic cooling burden:Conventional niobium-titanium systems require 4.2 Kelvin operation, demanding complex refrigeration infrastructure that elevates total cost of ownership.
- REACH substance restrictions:European chemical regulations on rare-earth processing complicate REBCO tape manufacturing and lengthen qualification timelines.
Strategic Opportunities
- Grid-scale superconducting cable deployment:Urban congestion in Seoul and Tokyo creates demand for compact, high-capacity transmission corridors using niobium-tin conductors.
- India's PLI scheme for medical devices:Domestic manufacturing incentives could localize MRI magnet assembly and reduce import dependency for healthcare infrastructure.
- AI-integrated diagnostic platforms:The EU AI Act creates compliance requirements that favor established magnet suppliers with documentation capabilities, consolidating vendor relationships.
Industry Challenges
- Superconducting wire fabrication expertise:The specialized metallurgy and precision winding skills required for consistent critical current density exceed available training pipeline capacity in most manufacturing regions.
- IEC 60601-2-33 certification timelines:Clinical MRI magnet approval processes span 18-24 months, compressing product refresh cycles and elevating pre-market capital commitment.
- Legacy helium infrastructure lock-in:Hospitals with existing liquid helium supply contracts face switching costs that delay adoption of cryogen-free magnet architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superconducting Magnets Market |
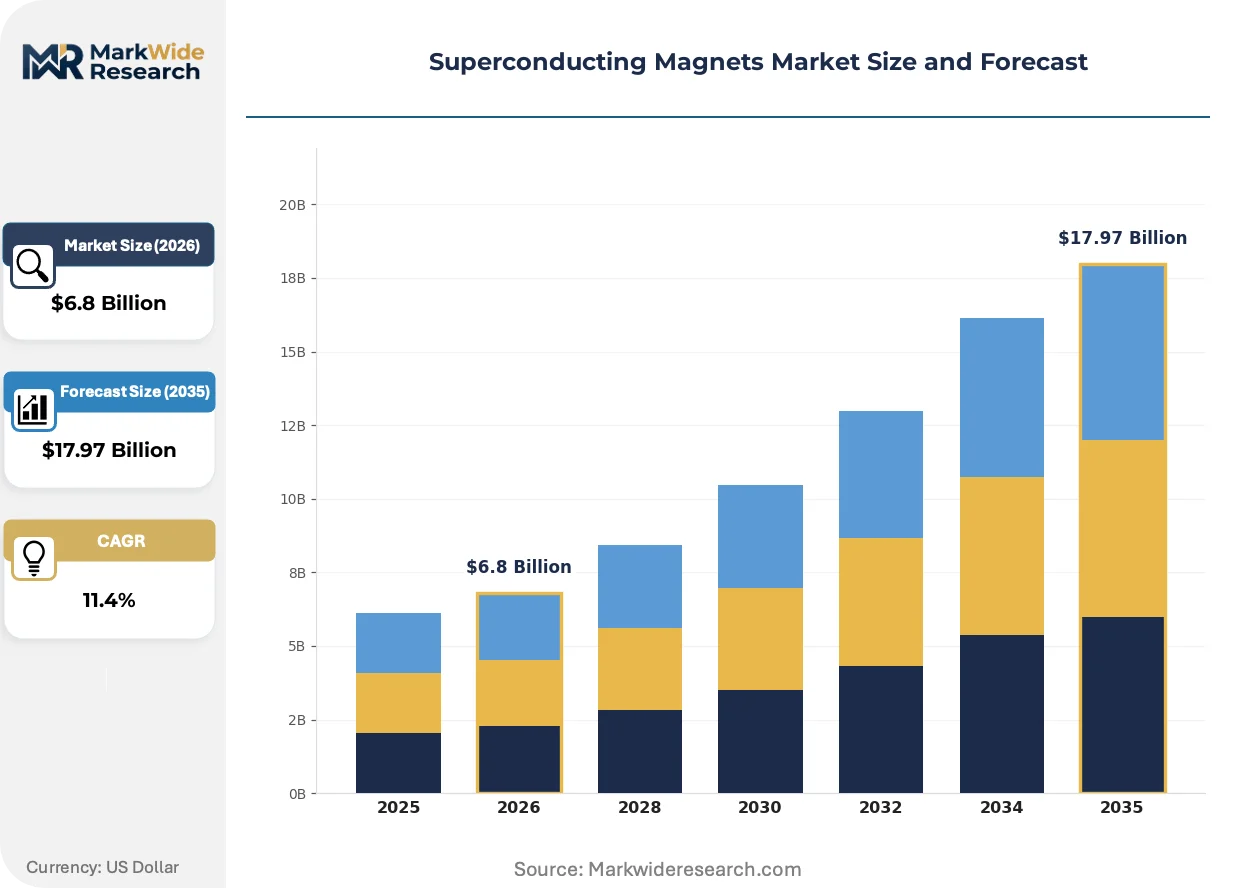
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Niobium-Titanium, Niobium-Tin, High-Temperature Superconductors, Rare-Earth Barium Copper Oxide End User: Healthcare, Research Institutions, Industrial Applications, Energy Technology: Magnetic Resonance Imaging, Particle Accelerators, Magnetic Levitation, Fusion Reactors Application: Medical Imaging, Quantum Computing, Magnetic Energy Storage, Scientific Research |
| Companies Covered | Bruker Corporation, Sumitomo Electric Industries Ltd., American Superconductor Co., Agilent Technologies Inc., American Magnetics Inc., Siemens AG, Fujikura Ltd., ASG Superconductors S.p.A, Furukawa Electric Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superconducting Magnets Market Strategic Shifts
Material science breakthroughs and regulatory recalibration are converging to reshape how superconducting systems are designed, cooled, and deployed across energy and healthcare infrastructure.
REBCO tape manufacturing is decentralizing cryogenic infrastructure requirements by enabling 77 Kelvin operation with liquid nitrogen rather than helium. Fusion reactor projects in France and South Korea are adopting these tapes for toroidal field coils, reducing plant complexity. This temperature elevation is compressing the total addressable market for conventional helium liquefaction equipment while expanding geographic feasibility for superconducting applications.
The EU AI Act imposes documentation and risk-classification requirements on automated diagnostic platforms integrating superconducting MRI systems. Medical device manufacturers must now maintain algorithmic transparency records alongside magnetic field safety certifications. European healthcare procurement is responding by consolidating vendor relationships toward suppliers with established compliance architectures.
Service unbundling is fragmenting traditional magnet supply contracts across university research facilities. Buyers are separating hardware acquisition from cryogenic maintenance and field mapping calibration, creating specialized service intermediaries. This pattern is most visible in United States national laboratory procurement, where multi-vendor integration contracts now outnumber single-source agreements.
Superconducting Magnets Market Segmentation
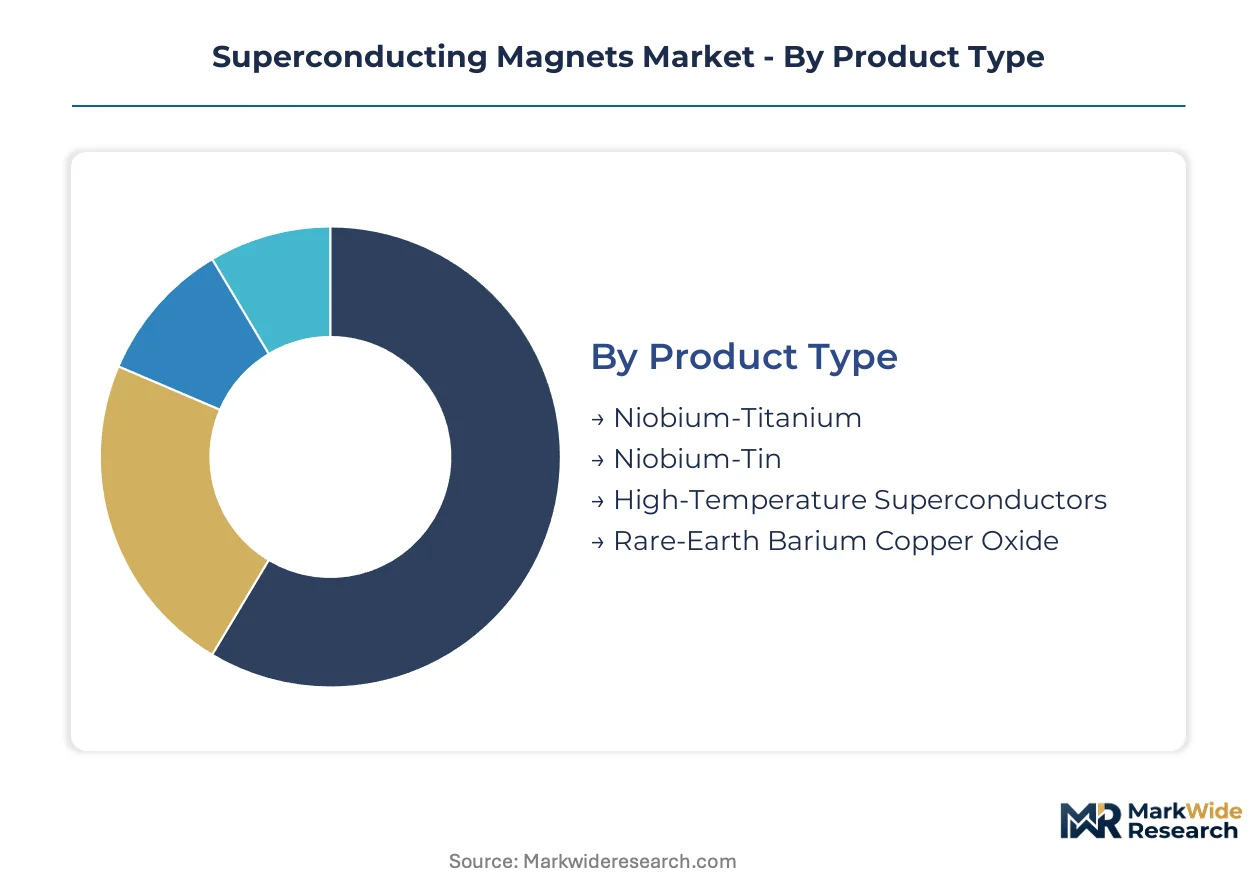
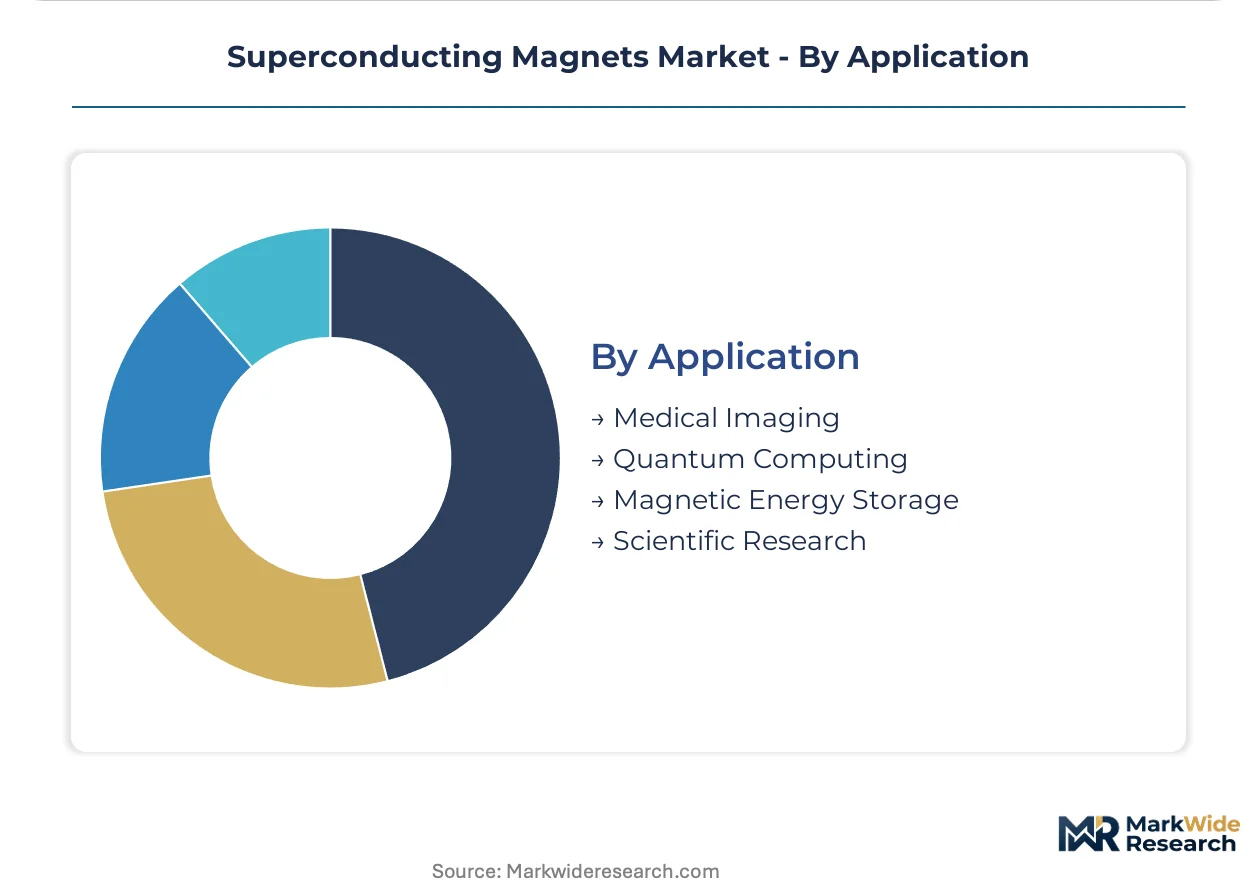
Segmentation in superconducting magnets reveals how capital allocation, cooling infrastructure, and regulatory compliance cluster around distinct material systems and end-use requirements. Procurement patterns diverge sharply between clinical MRI operators seeking proven niobium-titanium reliability and fusion energy developers betting on rare-earth barium copper oxide temperature advantages.
Product Type:
Capital intensity varies dramatically across material platforms, with cryogenic infrastructure requirements driving total project economics more than raw wire costs.
- Niobium-Titanium:Aluminum-stabilized composite conductors operate at 4.2 Kelvin with decades of clinical validation. Hospital procurement in Japan and Germany concentrates demand here due to established helium supply chains and FDA-cooled installation protocols.
- Rare-Earth Barium Copper Oxide:Layered ceramic tapes enable 77 Kelvin operation with liquid nitrogen cooling, slashing refrigeration capital expenditure. Fusion reactor projects in France and South Korea validate these conductors for toroidal field coils where magnetic field strength requirements exceed niobium-titanium limits.
- Niobium-Tin:Intermetallic compound achieves higher critical field than niobium-titanium but demands precise heat treatment during winding.
- High-Temperature Superconductors:Bismuth-based and iron-based variants occupy niche R&D positions pending manufacturing scale-up.
Niobium-titanium absorbs the bulk of installed capacity; rare-earth barium copper oxide is expanding most quickly.
End User:
Customer sophistication around cryogenic operations determines contract structures and service bundling preferences.
- Healthcare:Hospital systems and imaging centers prioritize magnet uptime guarantees and helium supply security over unit economics. Japan's diagnostic imaging mandates and Germany's stricter MRI referral standards are accelerating replacement cycles for clinical systems.
- Energy:Grid operators and fusion developers accept higher technical risk for step-change efficiency gains. EU Green Deal procurement standards in France and Germany now require utilities to evaluate superconducting cable demonstrations for urban transmission corridors.
- Research Institutions:National laboratories and university facilities separate hardware acquisition from cryogenic maintenance contracts.
- Industrial Applications:Semiconductor fabrication and magnetic separation operations demand standardized magnet configurations with rapid field ramping capability.
Healthcare commands the deepest installed base; energy applications show the steepest expansion trajectory.
Technology:
Magnetic field specifications and duty cycle requirements fragment the supplier landscape across deployment scenarios.
- Magnetic Resonance Imaging:Clinical systems require 1.5 to 7 Tesla fields with extreme temporal stability for diagnostic precision. FDA magnetic field exposure limits and IEC 60601-2-33 safety standards govern procurement specifications in the United States and European markets.
- Fusion Reactors:Tokamak and stellarator designs demand 12+ Tesla fields sustained for plasma confinement durations. ITER construction in France and KSTAR operations in South Korea validate large-bore magnet architectures for commercial reactor designs.
- Particle Accelerators:Synchrotron and collider facilities require precision field mapping for beam steering accuracy.
- Magnetic Levitation:Urban transit systems in Japan and South Korea deploy superconducting coils for frictionless propulsion.
Magnetic resonance imaging dominates current revenue; fusion reactor technology is climbing the fastest.
Application:
End-use performance requirements determine whether buyers prioritize field strength, temporal stability, or operational temperature flexibility.
- Medical Imaging:Diagnostic MRI systems require homogeneous fields across large patient bore diameters with sub-part-per-million stability. India's PLI scheme for medical devices is creating localized assembly opportunities for magnet subsystems.
- Scientific Research:National laboratory facilities in the United States unbundle magnet procurement from cryogenic service contracts, fragmenting traditional supply relationships.
- Quantum Computing:Superconducting qubit architectures demand dilution refrigeration integration with specialized magnetic shielding.
- Magnetic Energy Storage:Grid-scale systems remain pre-commercial with demonstration projects concentrated in South Korea and Japan.
Medical imaging anchors current deployment volumes; quantum computing applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors superconducting magnet deployment through its dense concentration of MRI systems and fusion research facilities. Japan's metropolitan corridor generates sustained procurement volume for niobium-titanium clinical systems and high-temperature superconductor R&D.
United States
Fusion energy programs at Princeton Plasma Physics Laboratory and MIT Plasma Science drive demand for large-bore toroidal field coils. The FDA governs magnetic field exposure limits for clinical MRI systems under 21 CFR 892.1000. Boston's medical technology cluster sustains magnet assembly operations serving diagnostic imaging networks.
Germany
Stricter MRI referral standards under the German Social Code Book V expand replacement cycles for clinical superconducting systems. The EU Green Deal procurement mandates compel utilities to evaluate superconducting grid solutions. Munich's industrial corridor hosts concentrated magnet manufacturing serving both healthcare and energy applications.
France
ITER construction in Cadarache validates rare-earth barium copper oxide tape architectures for commercial fusion reactor designs. ANSM oversees medical device safety alongside EU MDR harmonized standards. The Provence-Alpes-Côte d'Azur region concentrates cryogenic engineering expertise for next-generation magnet qualification.
South Korea
KSTAR operations at the National Fusion Research Institute sustain toroidal field coil procurement for tokamak plasma confinement. MFDS regulates medical imaging equipment under harmonized Asian standards. Seoul's urban congestion creates demand for compact superconducting transmission corridors using niobium-tin conductors.
India
The PLI scheme for medical devices incentivizes localized MRI magnet assembly to reduce import dependency. BIS certification requirements govern superconducting equipment safety standards. Maharashtra's industrial belt hosts emerging magnet fabrication capacity serving domestic healthcare infrastructure expansion.
Superconducting Magnets Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive cryogenic capabilities. Market concentration remains moderate with established players holding certification advantages under IEC and FDA pathways. Three archetypes dominate: integrated medical imaging system suppliers, specialized superconducting wire fabricators, and energy infrastructure contractors. Capacity expansion and strategic technology licensing represent the primary competitive vectors as manufacturers position for fusion reactor procurement cycles.
Among diversified technology conglomerates, Siemens AG and Bruker Corporation exemplify the integrated-systems archetype spanning medical imaging and analytical instrumentation. Sumitomo Electric Industries Ltd. anchors the specialized conductor segment through its niobium-titanium manufacturing scale. These three entities occupy positions reflecting distinct strategic postures: Siemens AG represents hospital-system integration depth, Bruker Corporation exemplifies cryogen-free magnet architecture specialization, and Sumitomo Electric Industries Ltd. sits within the high-current cable supply tier serving grid and fusion applications.
| Leading Market Players |
|---|
| Bruker Corporation |
| Sumitomo Electric Industries Ltd. |
| American Superconductor Co. |
| Agilent Technologies Inc. |
| American Magnetics Inc. |
| Siemens AG |
| Fujikura Ltd. |
| ASG Superconductors S.p.A |
| Furukawa Electric Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Liquid helium procurement costs cascade through superconducting magnet pricing tiers, compressing margins for niobium-titanium system operators while rewarding REBCO tape manufacturers with nitrogen-cooling economics. The path from Qatar and United States extraction through hospital GPO contracts and fusion reactor procurement creates divergent cost structures across buyer archetypes.
Pricing Analysis
Uptime guarantees anchor value-based pricing for clinical MRI installations, with magnet availability commitments commanding premium positioning against hardware-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cooled installation protocols from cryogen-free architectures and refurbished helium-dependent systems. Cost compression in standard-tier niobium-titanium contracts is intensifying because REACH substance restrictions lengthen European qualification timelines. Hospital systems with captive helium infrastructure exhibit lowest price sensitivity; research institutions unbundling service contracts show highest.
Supply Chain Analysis
Single-source vulnerability sits with Qatar and United States helium production, exposing magnet operators to export restriction risks and price volatility. Niobium-titanium wire fabrication draws from Japanese and German metallurgical expertise, while rare-earth barium copper oxide tape manufacturing rests on South Korean and United States ceramic deposition capabilities. Tariff exposure runs through rare-earth concentrate processing concentrated in China. Distribution runs through integrated medical imaging OEMs for healthcare, specialized cable fabricators for grid and fusion applications, and unbundled procurement channels for national laboratory research facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Superconducting magnet manufacturing is becoming a vertical-integration race, with captive cryogenic capabilities and in-house wire fabrication determining cost position across healthcare and energy verticals.
For Market Incumbents: Anticipate REBCO tape substitution eroding niobium-titanium volume in fusion applications by securing rare-earth barium copper oxide manufacturing licenses or joint ventures. Reinforce hospital system relationships through helium supply security guarantees and extended uptime service contracts that emerging cryogen-free competitors cannot match. Certification investment in EU AI Act documentation capabilities creates vendor consolidation pressure favoring established compliance architectures. For New Entrants and Emerging Players: Research institution procurement officers represent the most penetrable channel, as unbundled hardware acquisition and multi-vendor integration contracts fragment traditional single-source relationships. Target India's PLI scheme for medical devices to localize MRI magnet assembly and capture domestic healthcare infrastructure expansion. A go-to-market angle emphasizing liquid nitrogen cooling economics against incumbent helium dependency unlocks geographic markets with constrained cryogenic infrastructure. For Investors and Strategic Acquirers: ITER toroidal field coil qualification milestones are the leading indicator that REBCO tape manufacturing scale will command scarcity premiums in fusion reactor procurement cycles. Acquisition candidates with demonstrated 77 Kelvin conductor performance and existing IEC certification pathways offer strongest positioning across the projection horizon. Watch for KSTAR operational duration records as signals of commercial tokamak magnet readiness.| Strategic Initiative | Industry Significance |
|---|---|
| REBCO Tape Manufacturing Scale-Up | Enables 77 Kelvin fusion reactor deployment while displacing helium-dependent niobium-titanium architectures. |
| Cryogen-Free Magnet Architecture Development | Bruker Corporation's approach eliminates liquid helium burden for analytical instrumentation and research applications. |
| EU AI Act Compliance Architecture Investment | Documentation capabilities consolidate vendor relationships toward established medical device suppliers under automated diagnostic platform mandates. |
| India PLI Scheme Localization | Domestic MRI magnet assembly reduces import dependency while capturing Maharashtra industrial belt capacity expansion. |
| Fusion Reactor Toroidal Field Coil Partnership | ITER and KSTAR validation programs secure long-term procurement pipelines for large-bore superconducting systems. |
Study Parameters
Independent corroboration across magnet procurement officers at hospital systems, cryogenic engineering directors at national laboratories, and fusion project developers at ITER and KSTAR underwrites the qualitative findings. Primary interviews with biomedical equipment GPO contract managers, superconducting wire fabrication plant managers, and utility grid planning officers combined with secondary validation from IEC standards documentation, FDA 510(k) filings, EU MDR harmonized standards, and national fusion program budget disclosures. Bottom-up installation tracking and top-down materials demand modeling triangulate volume estimates.
Comparable-period anchoring to historical niobium-titanium MRI deployment cycles and rare-earth barium copper oxide R&D expenditure patterns structured the forecast window. Segmentation dimensions modeled include material system, cooling technology, end-user vertical, and regional regulatory cluster. CAGRs were derived from installed base replacement velocity and greenfield fusion reactor procurement pipelines. Industry-specific inputs incorporated helium supply contract durations and EU Green Deal procurement mandate implementation timelines.
Caveats apply where liquid helium export restrictions, REACH substance regulation expansion, or fusion reactor construction delays could materially shift the outlook. Forecasts reflect assumptions about cryogenic infrastructure deployment rates and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market