
 Global 3D Printing Ceramics Market | 2026-2036
Global 3D Printing Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Printing Ceramics Market Foresight
European powder synthesis specialists is restructuring supply chains for high-purity alumina and zirconia feedstocks used in additive manufacturing. EOS GmbH leverages its laser sintering heritage to dominate industrial metal-to-ceramic hybrid systems. Lithoz GmbH anchors Central European precision with its lithography-based ceramic manufacturing platform optimized for dental and aerospace tolerances. 3D Ceram competes through specialized silicon carbide formulations serving French aerospace foundries.
3D printing ceramics refers to additive fabrication of inorganic, non-metallic materials—typically oxides, carbides, or nitrides—layer-by-layer from digital models, with fired densities exceeding 95% theoretical and tolerances reaching ±25 micrometers. These components serve extreme thermal, wear, and dielectric applications unreachable by polymers or metals. Alumina and zirconia product types capture the dominant margin pools due to established medical and electronics certification pathways. Binder jetting and stereolithography technologies lead installed capacity, though selective laser sintering of silicon carbide represents the fastest-growing process segment for aerospace heat exchangers.
FDA biocompatibility protocols and EU MDR Class IIa/III device standards shape dental implant and surgical tool qualification timelines, while REACH and RoHS frameworks govern powder chemistry disclosures across European electronics supply chains. China's GB standards and NMPA medical device registrations create parallel compliance tracks for market access. Stakeholders must monitor divergence between FDA 510(k) ceramic device pathways and emerging EU AI Act implications for automated print qualification systems.
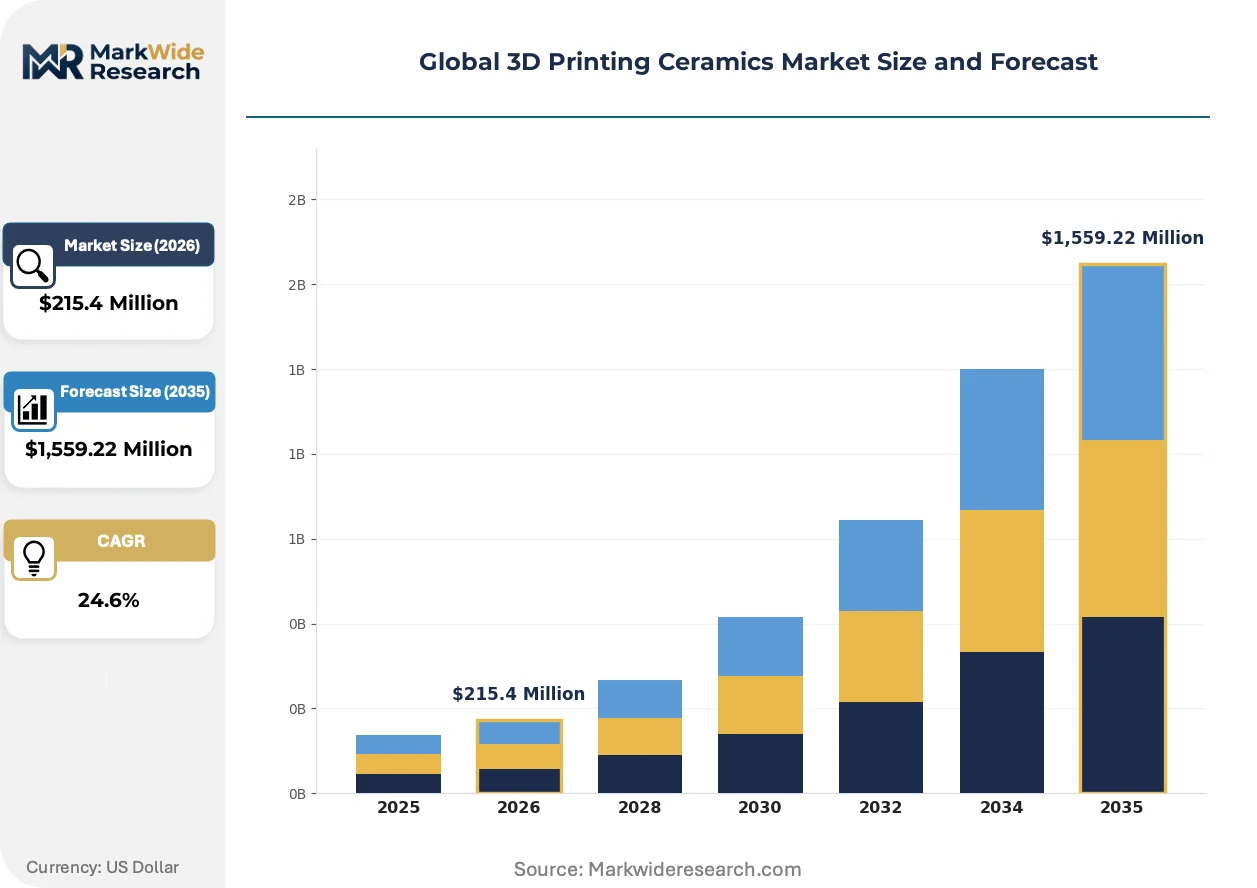
Market Dynamics
Hybrid laser sintering systems are collapsing the traditional boundary between metal and ceramic additive manufacturing, forcing powder suppliers to reformulate feedstocks for dual-material compatibility while aerospace buyers consolidate vendor lists.
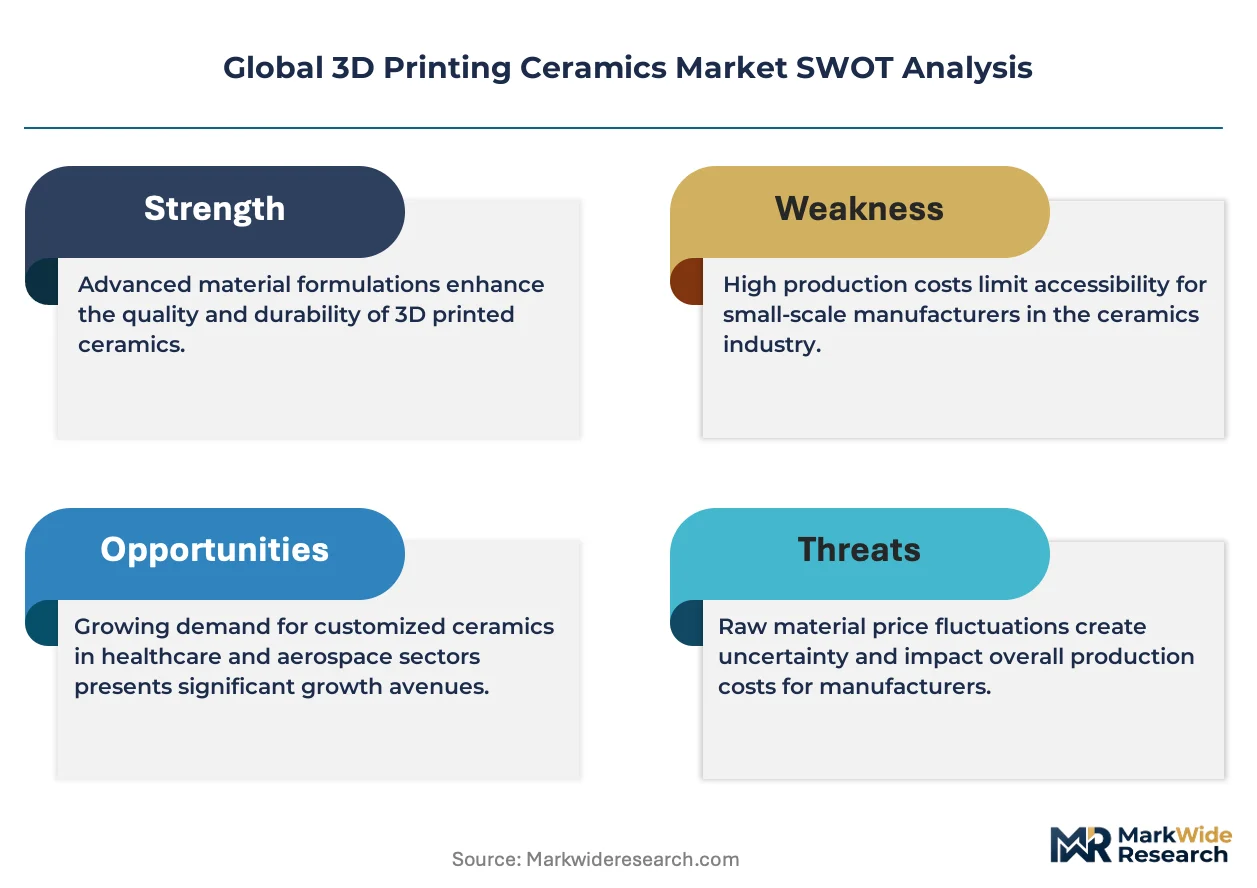
Growth Catalysts
- EU MDR Class IIa/III device standards:Stricter biocompatibility documentation requirements for dental implants are accelerating laboratory migration toward certified alumina and zirconia workflows with full traceability.
- 5G infrastructure deployment:Electronics manufacturers in China's Yangtze River Delta are integrating ceramic printed circuit substrates into base station architectures, creating sustained demand for low-loss dielectric components.
- Selective laser sintering of silicon carbide:Aerospace heat exchanger programs in Germany and the United States are validating this process for turbine blade applications above 1,200°C operating temperatures.
Market Restraints
- High-purity alumina powder concentration:European synthesis specialists control critical feedstock supply chains, exposing buyers to single-source risk and extended lead times for aerospace-qualified batches.
- Post-processing bottleneck:Thermal debinding and sintering cycles for complex geometries require 48-72 hour furnace occupancy, constraining throughput scaling regardless of print speed improvements.
- Polymer and metal substitution:PEEK composites and Inconel superalloys compete for thermal management applications below 800°C, compressing addressable ceramic volume in automotive and industrial segments.
Strategic Opportunities
- India's medical device PLI scheme:Domestic manufacturing incentives for Class C implants create localized production pathways for zirconia dental components previously imported from European suppliers.
- Photopolymer-nanoparticle convergence:Lithography-based ceramic manufacturing platforms are merging with semiconductor-scale precision optics, enabling microfluidic device architectures below 50 micrometer feature resolution.
- Direct-to-laboratory distribution:Dental CAD/CAM software integration allows ceramic printer OEMs to bypass traditional dental distributor networks, capturing margin and reducing equipment procurement cycles.
Industry Challenges
- Materials science talent scarcity:The intersection of ceramic engineering and additive process control requires hybrid expertise rarely available in single academic programs, extending hiring timelines for R&D functions.
- FDA 510(k) ceramic device pathway variability:Evolving biocompatibility testing protocols for patient-specific surgical guides create unpredictable qualification timelines and retrospective documentation burdens.
- Legacy ERP integration:Aerospace tier-one suppliers struggle to incorporate ceramic additive work orders into SAP systems designed for subtractive manufacturing cost accounting and lot traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printing Ceramics Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $1,559.22 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Zirconia, Silicon Carbide, Mullite, Steatite, Cordierite Technology: Stereolithography, Binder Jetting, Material Extrusion, Selective Laser Sintering, Digital Light Processing, Material Jetting Application: Electronics Components, Aerospace Parts, Dental Implants, Automotive Components, Defense Equipment, Consumer Goods End User: Research Institutions, Dental Laboratories, Electronics Manufacturers, Aerospace Manufacturers, Defense Contractors, Consumer Electronics Firms |
| Companies Covered | 3D Systems Corporation, Stratasys Ltd., Materialise NV, EOS GmbH, Lithoz GmbH, 3D Ceram, Renishaw plc, The ExOne Company, Tethon 3D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printing Ceramics Market Shifts & Advancements
Process-parameter artificial intelligence and real-time thermal monitoring are compressing the iteration cycles for dense ceramic qualification, while regulatory frameworks in multiple jurisdictions harden documentation requirements simultaneously.
Multi-material laser sintering platforms with in-situ alloy gradient control are expanding into aerospace turbine component repair applications. Maintenance divisions at German and US engine OEMs are adopting these systems for blade tip restoration rather than full replacement. This capability is expanding into service revenue models that compete directly with traditional spare parts supply chains.
REACH Article 33 disclosure obligations and RoHS restricted substance lists are tightening powder chemistry documentation requirements across European electronics supply chains. Component suppliers must now declare trace heavy metal content below 0.1% threshold for all ceramic feedstocks used in 5G infrastructure. Medical device manufacturers in Germany and France are responding by demanding full material passports from alumina and zirconia powder sources.
Certification-driven vendor consolidation is restructuring procurement patterns in dental laboratory networks. Small laboratories are abandoning in-house milling of zirconia blanks in favor of centralized additive manufacturing service bureaus holding FDA 510(k) clearances and ISO 13485 certifications. This pattern is most visible in the United States, where dental group practice chains are negotiating volume commitments with certified ceramic printing providers.
Global 3D Printing Ceramics Market Segmentation
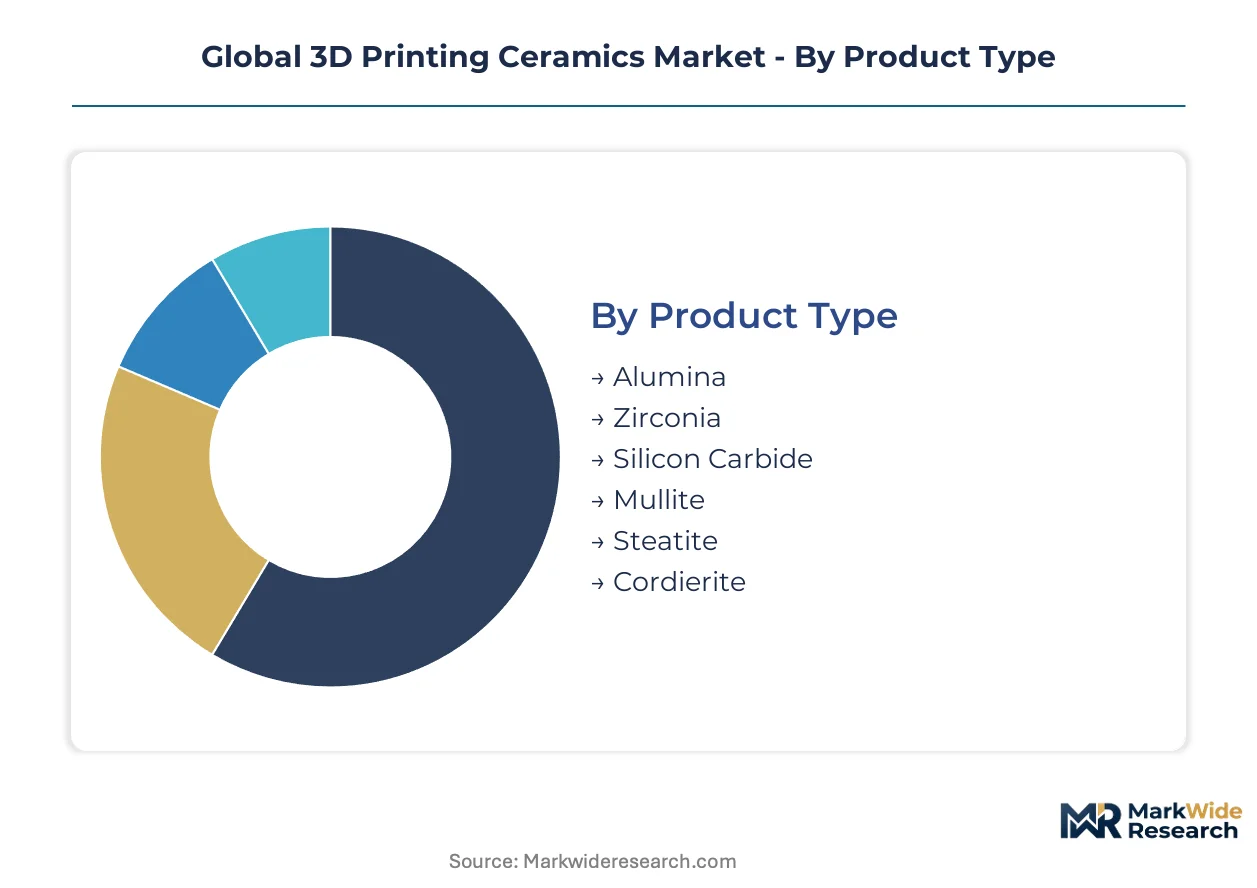
Segmentation in 3D printing ceramics reveals how certification pathways fragment commercial opportunity. Material choices determine regulatory burden, while technology selection constrains achievable tolerances and throughput economics for specific end-use verticals.
Product Type:
FDA 510(k) clearance requirements and EU MDR Class IIa/III standards concentrate most heavily on implant-grade formulations, while aerospace heat management applications demand NADCAP-accredited batch traceability.
- Alumina:High-purity alpha-alumina formulations achieve fired densities exceeding 99% theoretical with dielectric strength above 15 kV/mm. Dental laboratories in the United States and Germany specify this grade for crown and bridge frameworks requiring ISO 6872 certification. Demand concentrates in China's Yangtze River Delta for 5G substrate applications where low dielectric loss is critical.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal delivers fracture toughness exceeding 10 MPa·m½ for load-bearing implant indications. European dental networks are consolidating procurement around certified zirconia workflows to satisfy EU MDR biocompatibility documentation requirements.
- Silicon Carbide:Sintered SiC serves turbine blade and heat exchanger applications above 1,200°C operating temperatures.
- Mullite:Low thermal expansion coefficient suits kiln furniture and investment casting cores for aerospace foundries.
- Steatite:Cost-effective electrical insulation for high-frequency industrial equipment and automotive sensors.
- Cordierite:Exceptional thermal shock resistance supports catalytic converter substrates and diesel particulate filters.
Leading the category by volume: Alumina. Growing fastest: Silicon Carbide.
Technology:
Process selection determines capital intensity, geometric complexity limits, and post-processing burden across medical, aerospace, and electronics applications.
- Stereolithography:Lithography-based ceramic manufacturing achieves ±25 micrometer tolerances through photopolymer-nanoparticle suspension curing. Lithoz GmbH dominates this segment for dental and aerospace precision components in Central Europe.
- Binder Jetting:High-throughput powder bed process enables complex geometries without support structures, though thermal debinding extends total cycle time. Electronics manufacturers in China's Yangtze River Delta favor this route for ceramic printed circuit substrate production at scale.
- Material Extrusion:Filament-based deposition suits prototyping and educational markets with lower capital barriers.
- Selective Laser Sintering:Direct laser fusion of ceramic powders enables silicon carbide heat exchangers without organic binder phases.
- Digital Light Processing:Mask-based projection curing accelerates layer throughput for small-batch dental restorations.
- Material Jetting:Drop-on-demand deposition enables multi-material gradients for functional grading in aerospace components.
Widest installed base: Binder Jetting. Steepest expansion trajectory: Selective Laser Sintering.
Application:
End-use verticals diverge sharply in qualification timelines, with medical and aerospace segments requiring multi-year certification investments that consumer applications avoid entirely.
- Electronics Components:Low-loss dielectric substrates for 5G base stations and high-frequency radar modules. China's electronics manufacturers integrate alumina and cordierite printed circuit substrates into Yangtze River Delta infrastructure deployment.
- Aerospace Parts:Silicon carbide turbine blades and thermal protection systems operate above 1,200°C in German and US engine programs. FAA and EASA airworthiness certification drives NADCAP-accredited process validation.
- Dental Implants:Zirconia and alumina restorations require FDA 510(k) or EU MDR Class IIa/III clearance with full biocompatibility traceability.
- Automotive Components:Sensor housings and catalytic substrates compete with pressed ceramic alternatives on cost.
- Defense Equipment:Armor tiles and RF-transparent radomes demand ITAR-controlled supply chains in US programs.
- Consumer Goods:Decorative and functional ceramics face price pressure from traditional manufacturing.
Highest margin pool: Aerospace Parts. Volume leader: Electronics Components.
End User:
Customer type determines purchasing authority, with consolidated aerospace OEMs negotiating enterprise contracts while fragmented dental laboratories migrate toward centralized service bureaus.
- Research Institutions:Universities and national laboratories advance process-parameter development for next-generation ceramic formulations. German Fraunhofer institutes and US national laboratories drive selective laser sintering of silicon carbide innovation.
- Dental Laboratories:Small laboratories are abandoning in-house milling for certified additive service bureaus holding FDA 510(k) clearances. US dental group practice chains negotiate volume commitments with centralized providers.
- Electronics Manufacturers:5G infrastructure suppliers in China specify ceramic substrates for base station deployment.
- Aerospace Manufacturers:German and US engine OEMs adopt hybrid laser sintering for blade tip restoration programs.
- Defense Contractors:ITAR and EAR compliance requirements constrain supplier qualification.
- Consumer Electronics Firms:Wearable device housings and premium audio components represent emerging volume.
Procurement consolidation: Dental Laboratories. Fastest capability buildout: Aerospace Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity alumina synthesis in Germany's Rhineland and zirconia powder production in Japan's Kansai region anchor feedstock supply chains for additive manufacturing. These localities feed precision ceramic fabrication clusters across three continents.
Germany
Aerospace turbine blade programs and dental implant certification drive alumina and zirconia consumption. REACH Article 33 disclosure obligations and EU MDR Class IIa/III standards govern powder chemistry documentation. Fraunhofer institutes in Bavaria and North Rhine-Westphalia advance selective laser sintering of silicon carbide for heat exchanger applications above 1,200°C.
United States
Engine OEM maintenance divisions adopt hybrid laser sintering for blade tip restoration rather than full replacement. FDA 510(k) clearance pathways and FAA airworthiness certification shape qualification timelines for medical and aerospace components. Greater Boston and Pacific Northwest research corridors concentrate process-parameter development for next-generation ceramic formulations.
China
Electronics manufacturers in the Yangtze River Delta integrate ceramic printed circuit substrates into 5G base station architectures. NMPA medical device registrations and GB standards create parallel compliance tracks for market access. Shanghai and Suzhou industrial zones sustain demand for low-loss dielectric alumina and cordierite components.
Japan
Precision ceramics heritage supports lithography-based manufacturing platforms optimized for dental and aerospace tolerances. METI industrial policy and JIS standards framework govern materials qualification. Osaka-Kobe manufacturing belt supplies yttria-stabilized zirconia feedstocks for load-bearing implant indications requiring fracture toughness above 10 MPa·m½.
India
Domestic manufacturing incentives for Class C implants under the PLI scheme create localized production pathways for zirconia dental components. CDSCO medical device regulations and BIS standards guide import substitution strategies. Maharashtra and Gujarat pharmaceutical corridors attract contract manufacturers seeking to bypass European supply chains.
Global 3D Printing Ceramics Market Competitive Landscape
Global majors compete with regional champions across technology platforms and certification depth, creating a tiered structure where scale-driven system integrators coexist with specialized powder formulators. Laser sintering heritage and lithography-based platforms represent distinct capability anchors. Three archetypes dominate: European precision equipment builders, Asian electronics-integrated fabricators, and North American dental-aerospace hybrid specialists. Competitive moves center on M&A for feedstock security and strategic partnerships for regulatory certification acceleration.
Among German-based equipment builders, EOS GmbH and Lithoz GmbH exemplify the precision-platform archetype, anchoring industrial metal-to-ceramic hybrid systems and lithography-based manufacturing respectively. 3D Systems Corporation represents North American diversification across dental CAD/CAM integration and aerospace service bureau networks. These three occupy positions spanning equipment supply, materials qualification, and regulatory-cleared production workflows.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| Stratasys Ltd. |
| Materialise NV |
| EOS GmbH |
| Lithoz GmbH |
| 3D Ceram |
| Renishaw plc |
| The ExOne Company |
| Tethon 3D |
| Others |
Supply & Pricing Matrix
Backward integration into high-purity alumina synthesis anchors both supply security and pricing power for European equipment builders serving aerospace and dental certification tracks. This captive feedstock control allows Lithoz GmbH and EOS GmbH to bundle multi-year service contracts with hardware sales, compressing total cost of ownership for buyers locked into FDA 510(k) qualification timelines.
Pricing Analysis
Equipment-plus-consumables bundling dominates, with stereolithography platforms commanding premium positioning through embedded regulatory consulting and ISO 13485 certification support. Price differentiation separates NADCAP-accredited aerospace systems from standard dental laboratory configurations. Cost compression in entry-level binder jetting systems is intensifying as Chinese electronics manufacturers scale procurement for 5G substrate production. Dental service bureaus show highest price sensitivity, while German engine OEMs prioritize qualification speed over capital expenditure.
Supply Chain Analysis
FDA 510(k) and EU MDR Class IIa/III documentation requirements gate supplier qualification, elongating onboarding for powder feedstock vendors. High-purity alumina concentrates in Germany's Rhineland and yttria-stabilized zirconia draws from Japan's Kansai region. Single-source vulnerability pervades aerospace-qualified silicon carbide batches, where NADCAP accreditation limits viable suppliers. Distribution runs through authorized equipment distributors in Europe and direct-to-laboratory digital channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selective laser sintering of silicon carbide is displacing conventional investment casting for turbine blades above 1,200°C, compressing the window for legacy process incumbents to capture service revenue from maintenance divisions.
For Market Incumbents: Lock in multi-year powder supply agreements with Rhineland synthesis specialists before EU MDR documentation requirements tighten further. Prioritize in-house production of yttria-stabilized zirconia to offset Japanese feedstock concentration risk. Hybrid laser sintering platforms threaten equipment-only revenue models; bundle predictive maintenance software to defend service attach rates. For New Entrants and Emerging Players: Launch via certified service bureau partnerships targeting India's PLI-subsidized Class C implant manufacturing corridors. Dental laboratories in Maharashtra and Gujarat offer lowest competitive density for zirconia restoration workflows. Photopolymer-nanoparticle convergence for microfluidic devices below 50 micrometer resolution represents the most penetrable white-space for lithography-based platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated equipment builders with captive regulatory consulting capabilities. Five-to-ten year viability hinges on FDA 510(k) clearance velocity versus EU AI Act automated qualification implications. Watch for divergence between FAA and EASA airworthiness certification timelines as inflection signal for aerospace segment capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Acceleration | Compresses FDA 510(k) timelines for dental implant workflows through pre-submission consulting. |
| Feedstock Backward Integration | Captures high-purity alumina margin pools controlled by Rhineland synthesis specialists. |
| Hybrid Platform Development | Enables blade tip restoration revenue at German and US engine OEM maintenance divisions. |
| Direct-to-Laboratory Distribution | Bypasses dental distributor networks through CAD/CAM software integration. |
| Microfluidic Precision Expansion | Merges lithography platforms with semiconductor-scale optics for sub-50 micrometer architectures. |
Research Methodology
Document review covered SEC filings, EASA airworthiness directives, and NMPA registration databases, complemented by interviews with additive manufacturing equipment executives, dental laboratory procurement managers, aerospace tier-one supplier quality directors, and high-purity powder synthesis specialists. Secondary validation drew from FDA 510(k) clearance records, EU MDR technical documentation, and Fraunhofer institute process-parameter publications. Bottom-up segmentation modeling triangulated against top-down industry aggregation.
Installed base projections by technology platform and certified application vertical were generated across the analysis window, with segmentation spanning material formulation, process technology, end-use application, and customer archetype. CAGRs were derived from elasticity-adjusted adoption curves incorporating REACH Article 33 disclosure trajectories and China's 5G infrastructure deployment cadence. Forecast inputs included NADCAP-accredited batch qualification rates and dental service bureau consolidation velocity.
Regulatory pathway divergence, feedstock supply disruption, and substitution by PEEK composites or Inconel superalloys are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in FDA ceramic device biocompatibility testing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Thermoformed Plastics for Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
3D Printing Materials Market