
 Europe Feed Minerals Market | 2026-2036
Europe Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Minerals Market Foresight
Aftermarket technical service revenue is reshaping competitive economics in Europe feed minerals, as formulation advice and on-farm mineral auditing now generate margins that rival base product sales. Cargill leverages its pan-European nutrition consulting network to lock in long-term supply contracts with integrated livestock groups. BASF SE anchors its position through backward integration into methionine and trace mineral precursor production. Adisseo competes by specializing in rumen-protected mineral technologies for high-performance dairy herds.
Feed minerals are inorganic compounds—primarily calcium, phosphorus, magnesium, zinc, copper, manganese, and selenium—delivered as premixes, trace mineral complexes, or macro mineral supplements to correct dietary deficiencies and optimize metabolic function in livestock. Chelated and organically bound forms improve bioavailability compared to inorganic oxide and sulfate sources, particularly in monogastric species with less efficient mineral absorption. Trace minerals command premium pricing due to lower inclusion rates and higher formulation complexity, while macro minerals generate volume through bulk phosphate and limestone sales to compound feed mills. Powder and liquid forms dominate ruminant applications, whereas pelleted delivery is gaining share in automated poultry and aquaculture feeding systems where uniform dispersion prevents segregation.
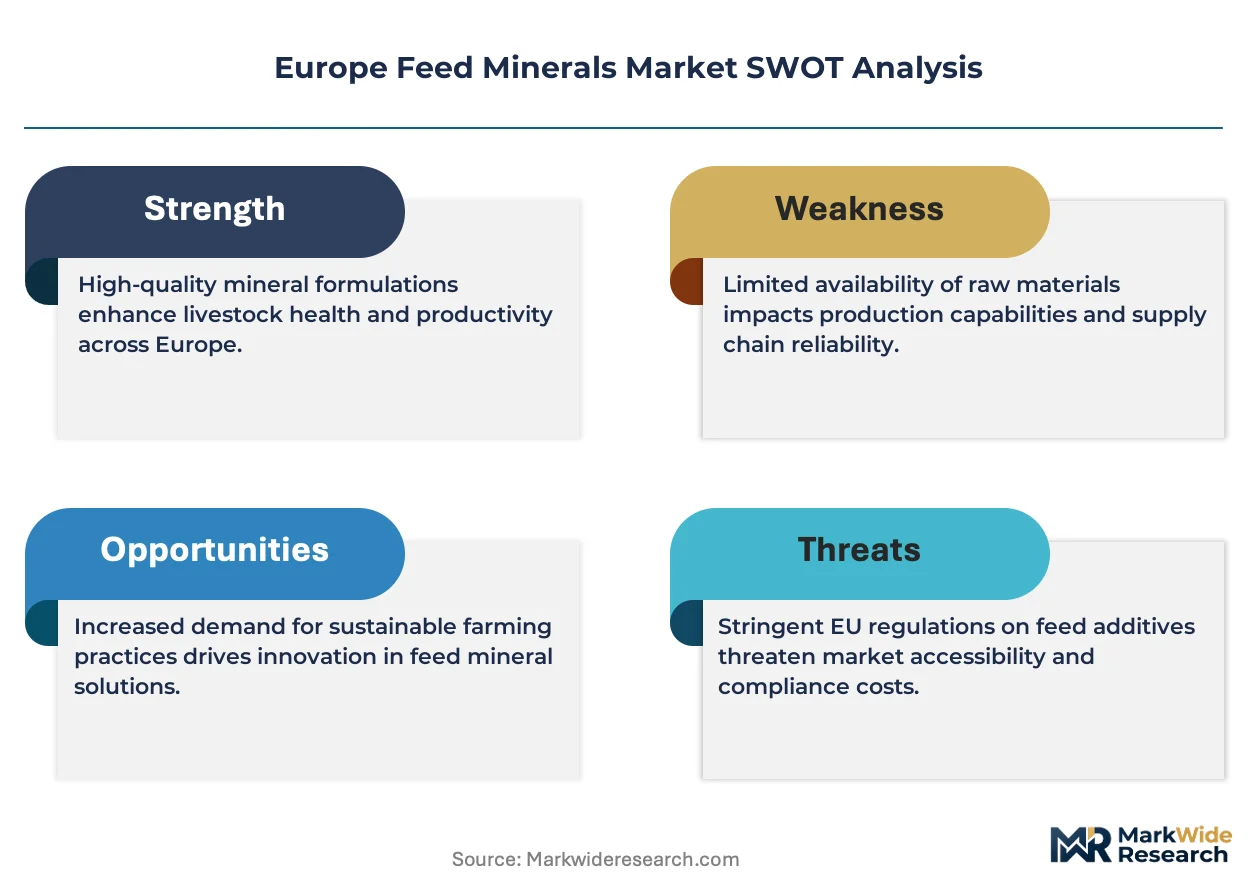
EMA feed additive re-evaluation procedures, REACH chemical registration requirements, and EU Green Deal sustainability disclosures are collectively elevating compliance costs and favoring suppliers with dedicated regulatory affairs teams and transparent supply chain documentation. The F-Gas Regulation indirectly pressures mineral processing energy intensity, accelerating plant upgrades in Belgium and the Netherlands. Stakeholders must monitor pending revisions to maximum permitted levels of copper and zinc in pig and poultry diets, as stricter limits would force rapid reformulation across premix portfolios.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing mineral processing margins while simultaneously accelerating capital deployment into lower-carbon sourcing infrastructure across Belgium and the Netherlands.
Growth Catalysts
- Chelated Trace Mineral Adoption:Large-scale poultry and swine operations in France and Spain are upgrading from basic salt-based supplements to bioavailable organic forms, driving formulation complexity premiums.
- REACH Registration Compliance:Transparent supply chain documentation requirements favor established suppliers with dedicated regulatory affairs teams, consolidating market access for compliant producers.
- Dairy Herd Performance Demands:German and Dutch dairy farms are expanding mineral premix usage to optimize milk yield and metabolic health in high-production herds.
Market Restraints
- Phosphate Input Volatility:Bulk phosphate and limestone price swings squeeze compound feed mill margins, forcing volume-driven macro mineral suppliers into defensive pricing postures.
- Energy-Intensive Processing:F-Gas Regulation pressures mineral calcination and drying operations in Belgium and the Netherlands, requiring costly plant retrofits or capacity rationalization.
- Maximum Level Uncertainty:Pending EFSA revisions to copper and zinc limits in pig and poultry diets create reformulation risk across premix portfolios before scientific consensus solidifies.
Strategic Opportunities
- Poland and Romania Livestock Modernization:Underpenetrated dairy and poultry sectors in Eastern Europe present first-mover advantages for technical service bundled with mineral premix supply.
- Rumen-Protected Mineral Platforms:Convergence of lipid encapsulation and precision release technologies enables bypass delivery for high-performance ruminant nutrition.
- CSRD Sustainability Disclosures:Mandatory environmental reporting creates competitive differentiation for suppliers with verified lower-carbon mineral sourcing and processing methods.
Industry Challenges
- Formulation Chemistry Expertise Gap:Shortage of mineral nutritionists capable of balancing bioavailability, cost, and regulatory compliance slows product development cycles.
- EMA Re-Evaluation Timelines:Extended feed additive re-approval procedures delay market entry for novel mineral complexes, trapping R&D investment in regulatory limbo.
- Legacy System Integration:Automated poultry and aquaculture feeding systems require pelleted mineral forms incompatible with existing powder-handling infrastructure at smaller compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Minerals Market |
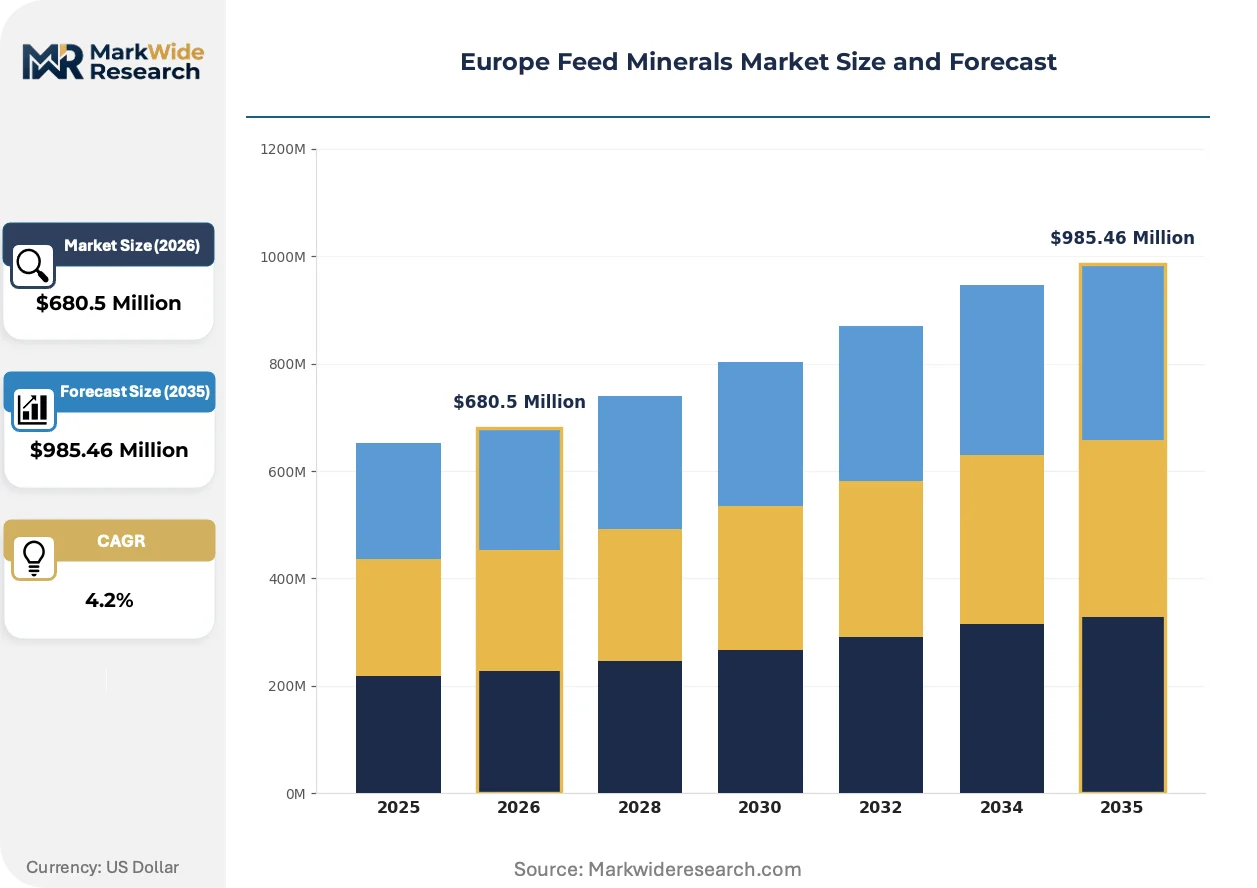
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $985.46 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premixes, Trace Minerals, Macro Minerals, Mineral Supplements End User: Dairy Farms, Poultry Farms, Aquaculture, Pet Food Manufacturers Form: Powder, Liquid, Granule, Pelleted Application: Animal Nutrition, Feed Additives, Veterinary Medicine, Health Supplements |
| Companies Covered | Cargill, BASF SE, Archer Daniels Midland, Alltech, Adisseo, Kemin Industries, Novus International, Nutreco NV, Zinpro, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Minerals Market Shifts & Advancements
Digital mineral auditing platforms and precision livestock monitoring are converging to reshape how feed minerals are specified, dosed, and validated on-farm across European integrated livestock groups.
Near-infrared spectroscopy coupled with cloud-based formulation software is virtualizing traditional laboratory mineral analysis. Integrated pork and poultry producers in Denmark and the Netherlands are deploying these systems at line speed for real-time premix verification. The technology is virtualizing quality control labor while compressing the specification window between compound feed mills and their livestock customers.
EMA feed additive re-evaluation procedures are tightening evidentiary standards for mineral bioavailability claims. Manufacturers must now submit species-specific absorption data, elevating R&D costs and extending time-to-market for novel organic trace mineral forms. High-specification dairy nutrition segments in Germany and Ireland are absorbing these compliance premiums through long-term supply contracts.
Livestock procurement teams are consolidating mineral premix suppliers to capture technical service economies. Integrated poultry groups in Spain and France are unbundling traditional distributor relationships to contract directly with formulation specialists offering on-farm mineral auditing. This channel compression is most visible in automated layer and broiler operations where uniform mineral dispersion directly impacts feed conversion metrics.
Europe Feed Minerals Market Segmentation
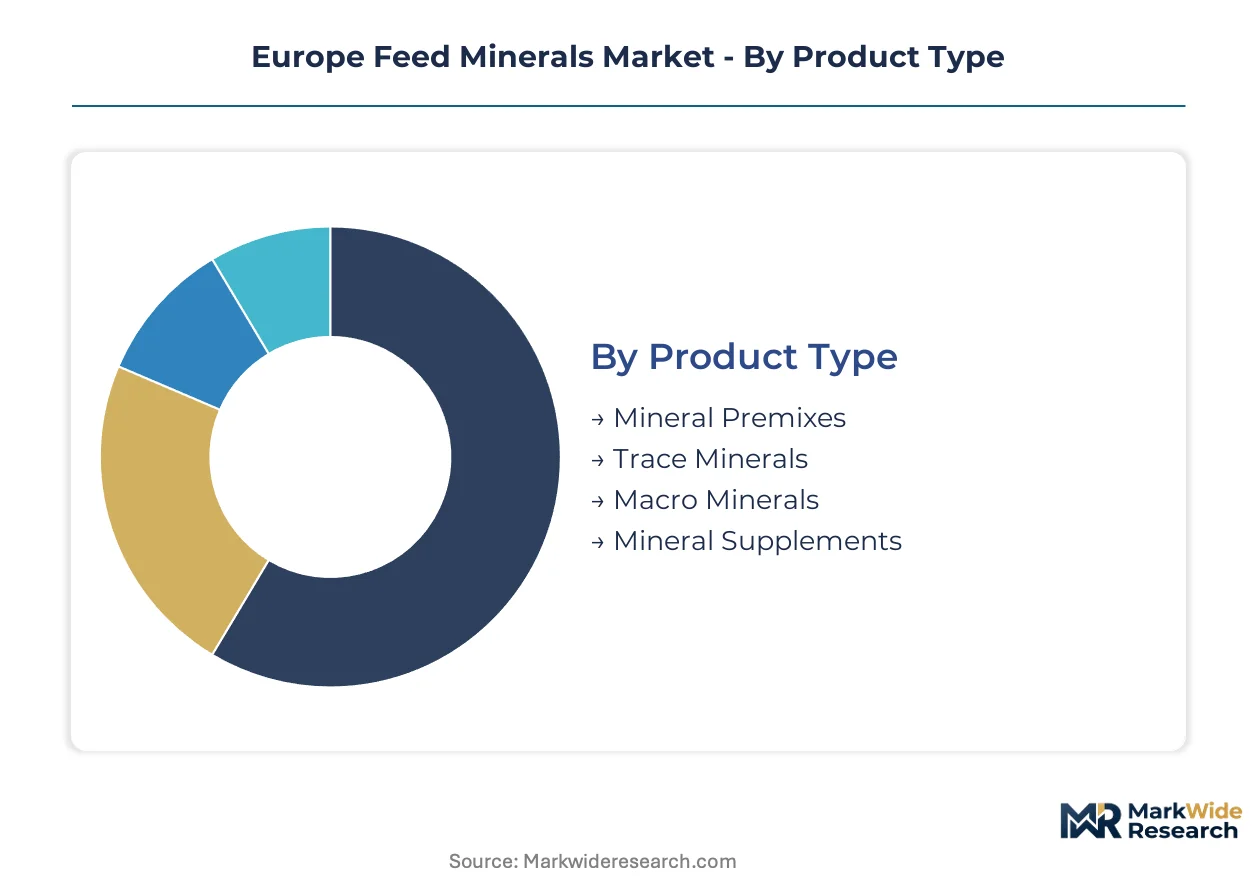
Feed mineral suppliers structure their portfolios around four distinct segmentation axes, each demanding different technical service intensity and formulation expertise. Product type and end-user concentration determine margin architecture, while form and application specifications dictate manufacturing asset allocation and regulatory compliance pathways.
Product Type:
Technical service bundling intensity varies sharply across product categories, with trace minerals commanding premium advisory support while macro minerals compete on volume logistics.
- Mineral Premixes:Complex blends of macro and trace minerals combined with carriers and processing aids, formulated to precise inclusion rates for species-specific diets. German and Dutch dairy farms drive demand for customized premixes with on-farm mineral auditing services bundled into supply contracts.
- Trace Minerals:Chelated and organically bound forms of zinc, copper, manganese, and selenium delivering superior bioavailability in monogastric species. Large-scale poultry operations in France and Spain absorb premium pricing for these formulations to optimize feed conversion metrics.
- Macro Minerals:Bulk calcium, phosphorus, and magnesium sources including limestone, dicalcium phosphate, and magnesium oxide supplied to compound feed mills. Phosphate input volatility squeezes margins for volume-driven suppliers serving integrated livestock groups.
- Mineral Supplements:Standalone mineral products for targeted deficiency correction or therapeutic intervention in veterinary protocols. Pet food manufacturers in Italy and Poland source specialized supplements for premium companion animal nutrition lines.
Mineral Premixes holds the largest share; momentum sits with Trace Minerals.
End User:
Customer procurement sophistication spans from automated purchasing systems at integrated poultry groups to relationship-driven mineral auditing contracts at family-owned dairy operations.
- Dairy Farms:High-performance herds in Germany, the Netherlands, and Ireland require precision mineral balancing for metabolic health and milk yield optimization. Rumen-protected mineral technologies capture premium positioning in this segment.
- Poultry Farms:Automated layer and broiler operations in France and Spain demand pelleted mineral forms with uniform dispersion characteristics to prevent feed segregation and maintain conversion efficiency.
- Aquaculture:Salmon and trout producers in Norway and Scotland source specialized mineral premixes addressing osmoregulation and immune function in intensive marine farming systems.
- Pet Food Manufacturers:Premium companion animal nutrition brands in Italy and the UK formulate chelated trace minerals for bioavailability claims on high-margin product lines.
Dairy Farms commands the deepest technical service penetration; Aquaculture represents the steepest expansion trajectory.
Form:
Physical delivery specifications directly determine equipment compatibility and handling economics across compound feed mill infrastructure.
- Powder:Fine-ground mineral products dominating ruminant applications where mechanical mixing achieves adequate dispersion in total mixed rations. Legacy infrastructure at smaller compounders retains powder handling systems.
- Liquid:Suspended or dissolved mineral solutions enabling precise dosing through automated drinking water systems in poultry and swine operations. Danish integrated pork producers deploy liquid minerals for real-time adjustment capabilities.
- Granule:Intermediate particle size offering flowability advantages in specific handling systems. Niche positioning in aquaculture feed production where water stability requirements constrain form selection.
- Pelleted:Compressed mineral forms gaining share in automated poultry and aquaculture feeding systems where segregation prevention directly impacts feed conversion ratios. Spanish layer operations drive adoption.
Powder retains volume leadership; Pelleted forms are climbing the fastest.
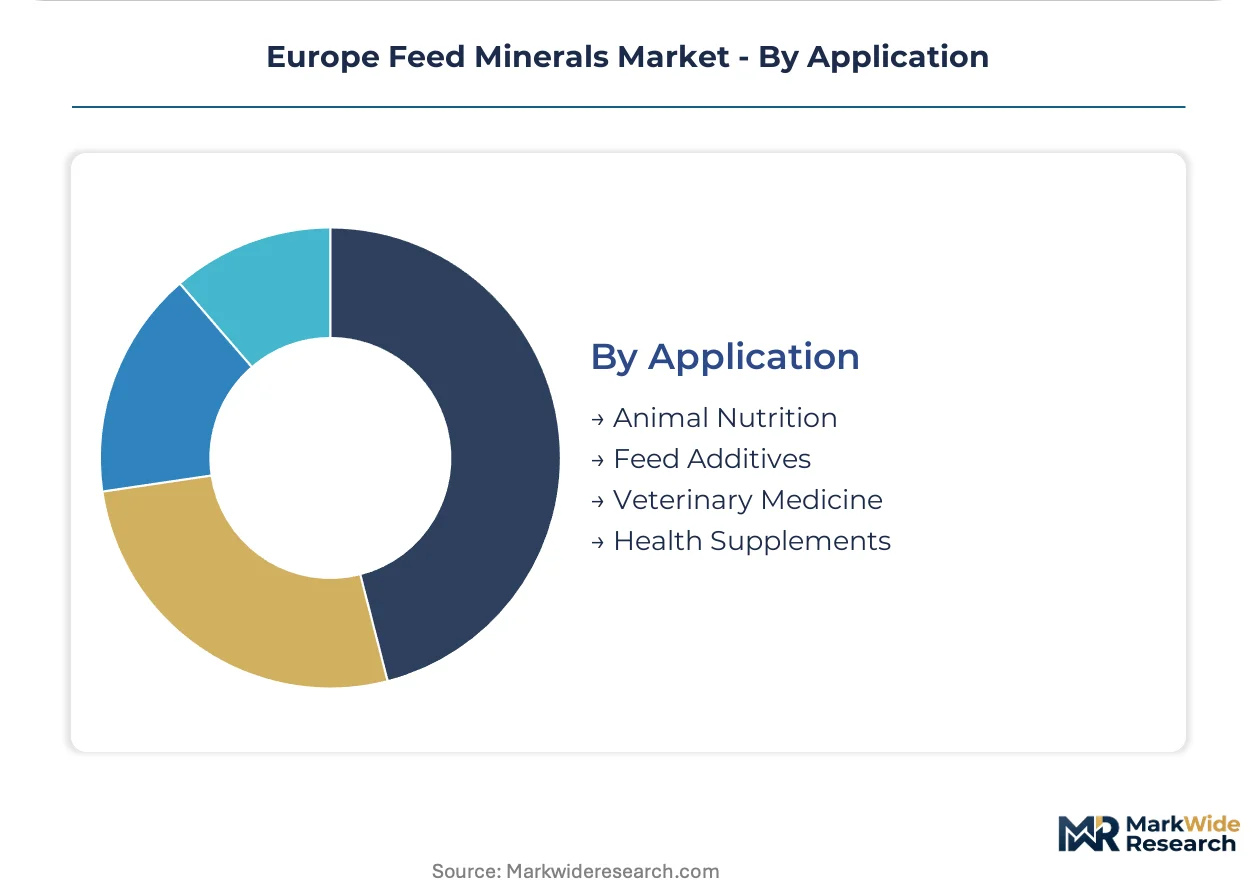
Application:
Regulatory pathway complexity fragments this axis, with feed additive registration timelines diverging sharply from veterinary medicine approval procedures.
- Animal Nutrition:Core mineral supplementation for growth, reproduction, and maintenance in commercial livestock production. REACH registration requirements and EFSA maximum level determinations govern formulation parameters.
- Feed Additives:Mineral products claiming specific zootechnical benefits requiring EMA feed additive re-evaluation and species-specific bioavailability documentation. Extended approval timelines trap R&D investment.
- Veterinary Medicine:Therapeutic mineral interventions for deficiency diseases and metabolic disorders regulated under veterinary medicinal product frameworks. Prescription pathways limit market access to qualified practitioners.
- Health Supplements:Wellness-oriented mineral products for companion animals and specialty livestock segments. Pet food manufacturers in premium tiers absorb compliance premiums for differentiated positioning.
Animal Nutrition captures the broadest volume base; Feed Additives faces the steepest regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral consumption patterns across Europe diverge sharply between northwestern dairy-intensive regions and southwestern monogastric belts, with Germany and the Netherlands prioritizing rumen-protected formulations while France and Spain concentrate pelleted trace mineral demand in automated poultry systems.
Germany
High-performance dairy herds in Lower Saxony and Bavaria drive demand for customized mineral premixes with bundled technical auditing services. EFSA maximum level consultations for copper and zinc are forcing rapid reformulation across pig and poultry portfolios. The Münsterland dairy cluster anchors rumen-protected mineral adoption for metabolic health optimization.
Netherlands
Intensive livestock operations in Gelderland and North Brabant deploy liquid mineral dosing systems for real-time dietary adjustment capabilities. F-Gas Regulation pressures are accelerating calcination plant retrofits in the Rotterdam port industrial zone. Dutch integrated pork producers are consolidating premix suppliers to capture formulation advisory economies.
France
Large-scale layer and broiler operations in Brittany and Pays de la Loire are upgrading to chelated trace minerals for feed conversion efficiency gains. REACH registration documentation requirements favor established suppliers with dedicated regulatory affairs teams. The Rennes agri-nutrition cluster concentrates pelleted mineral production for automated feeding systems.
Spain
Integrated poultry groups in Catalonia and Aragon are bypassing distributors to contract directly with formulation specialists offering on-farm mineral auditing. CSRD sustainability disclosure mandates are creating competitive differentiation for lower-carbon mineral sourcing. The Lleida corridor drives adoption of water-stable mineral forms in high-density layer operations.
Poland
Underpenetrated dairy and poultry sectors in Greater Poland and Lower Silesia present first-mover advantages for technical service bundled with premix supply. EU Green Deal agricultural transition funds are accelerating livestock modernization in former state farm territories. The Poznań feed industry hub is attracting mineral suppliers targeting eastern European expansion.
Europe Feed Minerals Market Competitive Landscape
Capability concentration sits with formulation specialists commanding premium advisory relationships; scale advantage sits with integrated chemical conglomerates controlling mineral precursor production. The market structures around three tiers: global nutrition platforms with pan-European consulting networks, backward-integrated chemical producers with captive mineral supply, and regional premix specialists with deep livestock segment expertise. Dominant competitive moves include technical service bundling to lock in long-term supply contracts and regulatory compliance investments to consolidate market access under tightening EMA and REACH requirements.
Within the global nutrition platform tier, Cargill anchors its position through pan-European consulting infrastructure, while BASF SE exemplifies chemical-backed mineral production with upstream integration into methionine and trace mineral precursors. Adisseo occupies a specialist position focused on rumen-protected delivery technologies for high-performance dairy applications.
| Leading Market Players |
|---|
| Cargill |
| BASF SE |
| Archer Daniels Midland |
| Alltech |
| Adisseo |
| Kemin Industries |
| Novus International |
| Nutreco NV |
| Zinpro |
| Others |
Supply & Pricing Matrix
Phosphate rock concentration in Morocco and Western Sahara feeds directly into margin capture at European compound feed mills, where bulk mineral sourcing contracts determine competitive positioning across northwestern dairy belts and southwestern poultry corridors. Long-term offtake agreements with North African suppliers anchor cost predictability for macro mineral volumes, while trace mineral premiums flow to formulation specialists commanding bioavailability verification.
Pricing Analysis
Contract structures bifurcate between multi-year mineral supply agreements with integrated livestock groups and spot-market transactions serving smaller compounders. Price differentiation hinges on chelation certification tier and bundled technical service intensity, with EFSA-compliant organic trace minerals commanding substantial premia over inorganic sulfates. Cost compression in bulk phosphate and limestone tiers is intensifying because of energy-intensive processing retrofits mandated by the F-Gas Regulation. Integrated poultry operations in France and Spain exhibit lowest price sensitivity due to feed conversion economics, while family-owned dairy farms in Poland and Romania remain most responsive to per-kilogram mineral costs.
Supply Chain Analysis
Upstream feedstock sourcing draws from phosphate deposits in Morocco, sulfur processing in Germany and Poland, and selenium refining in Belgium and Finland. Critical dependencies include phosphate rock quality grades, methionine precursor availability, and chelating agent chemical feedstocks. Single-source vulnerability concentrates in rumen-protected lipid encapsulation technologies controlled by a limited supplier base. Distribution runs through pan-European nutrition consulting networks for premium premix tiers, with bulk macro minerals flowing via Rotterdam and Antwerp port logistics to compound feed mill clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe feed minerals sit in early-cycle expansion as dairy herd modernization across Eastern Europe and precision livestock monitoring adoption create penetration headroom previously unavailable in saturated western markets.
For Market Incumbents: Insulate formulation advisory relationships through multi-year mineral auditing contracts that embed switching costs before REACH registration compliance investments mature into market access barriers. Prioritize backward integration into methionine and trace mineral precursor production to defend margin pools against phosphate input volatility and energy cost escalation at calcination facilities. For New Entrants and Emerging Players: Poland and Romania dairy sector underpenetration offers first-mover positioning where technical service bundling can displace unbranded commodity mineral suppliers before consolidated premix networks establish presence. Target automated poultry operations in Spain with pelleted mineral forms compatible with existing feeding infrastructure, leveraging CSRD sustainability disclosure mandates to differentiate lower-carbon sourcing credentials against established competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional premix specialists possessing deep livestock segment expertise but lacking regulatory affairs scale to navigate EMA re-evaluation timelines independently. Five-to-ten year viability favors targets with verified supply chain documentation and captive mineral precursor relationships. The signal to watch is pending EFSA copper and zinc limit revisions, which would force rapid portfolio reformulation and consolidate market access around compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | BASF SE's captive methionine supply anchors margin control against phosphate volatility. |
| Rumen-Protected Mineral Platform Development | Adisseo's lipid encapsulation specialization captures premium positioning in German dairy clusters. |
| Pan-European Technical Service Network Expansion | Cargill's nutrition consulting infrastructure locks in long-term supply contracts with integrated livestock groups. |
| CSRD-Verified Lower-Carbon Sourcing Certification | Spanish layer operations differentiate procurement through sustainability disclosure compliance. |
| EMA Regulatory Affairs Team Buildout | Transparent supply chain documentation consolidates market access under tightening REACH requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across mineral nutritionists at integrated livestock groups, procurement leads at compound feed mills, regulatory affairs directors at premix manufacturers, and plant managers at phosphate processing facilities. Secondary validation drew from EMA feed additive re-evaluation filings, EFSA maximum level consultation documents, EU Green Deal implementation trackers, and customs trade data for phosphate and limestone imports. Bottom-up mineral consumption modeling triangulated against top-down feed production statistics from national agricultural ministries.
Calibration approached volume and value outputs across the projection horizon through segmented modeling of product type, end-user concentration, physical form specifications, and application regulatory pathways. CAGRs were derived from mineral inclusion rate trends, livestock herd expansion projections, and premix adoption penetration curves. Industry-specific forecast inputs included dairy cow productivity benchmarks from the Münsterland cluster and poultry feed conversion metrics from Brittany layer operations.
Practitioners should monitor EFSA copper and zinc limit revision timelines, F-Gas Regulation enforcement intensity at Belgian and Dutch calcination plants, and EU Green Deal agricultural transition fund disbursement patterns for early signals of forecast deviation. Cross-checking against national feed industry association production statistics and Cefic chemical output disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Perlite Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Fluorspar Market