
 Cobalt Oxide Market | 2026-2036
Cobalt Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Oxide Market Analysis
Modular cathode precursor sourcing is expanding as battery makers unbundle traditional bundled cobalt oxide supply contracts to secure direct offtake from specific refiners. Huayou Cobalt leverages its integrated DRC-to-China refining corridor to control feedstock quality. Freeport-McMoRan anchors North American supply through its Indonesian cobalt by-product streams. Glencore dominates merchant trading volumes, giving it pricing leverage across multiple battery tier customers.
Cobalt oxide is a black crystalline powder with the chemical formula CoO or Co₃O₄, typically produced through thermal decomposition of cobalt salts at temperatures exceeding 900°C, serving primarily as a cathode precursor material in lithium-ion batteries and as a colorant in ceramic glazes. The cobalt(II) oxide product category leads volume shipments due to its direct use in lithium cobalt oxide cathode formulations, while cobalt hydroxide occupies the fastest-growing position as an intermediate feedstock for battery-grade refining. High purity grades command concentrated margin pools as cathode makers tighten specification tolerances for nickel-cobalt-manganese formulations.
The EU Battery Regulation mandates supply chain due diligence and recycled content thresholds, while China's MIIT enforces GB standards for battery-grade cobalt oxide purity and the DRC's national mining code revises royalty structures on strategic minerals. These frameworks collectively raise compliance costs for unintegrated traders while advantaging producers with verified mine-to-refiner traceability. Stakeholders must monitor evolving cobalt classification under EU critical raw materials lists and corresponding stockpiling obligations.
Market Dynamics
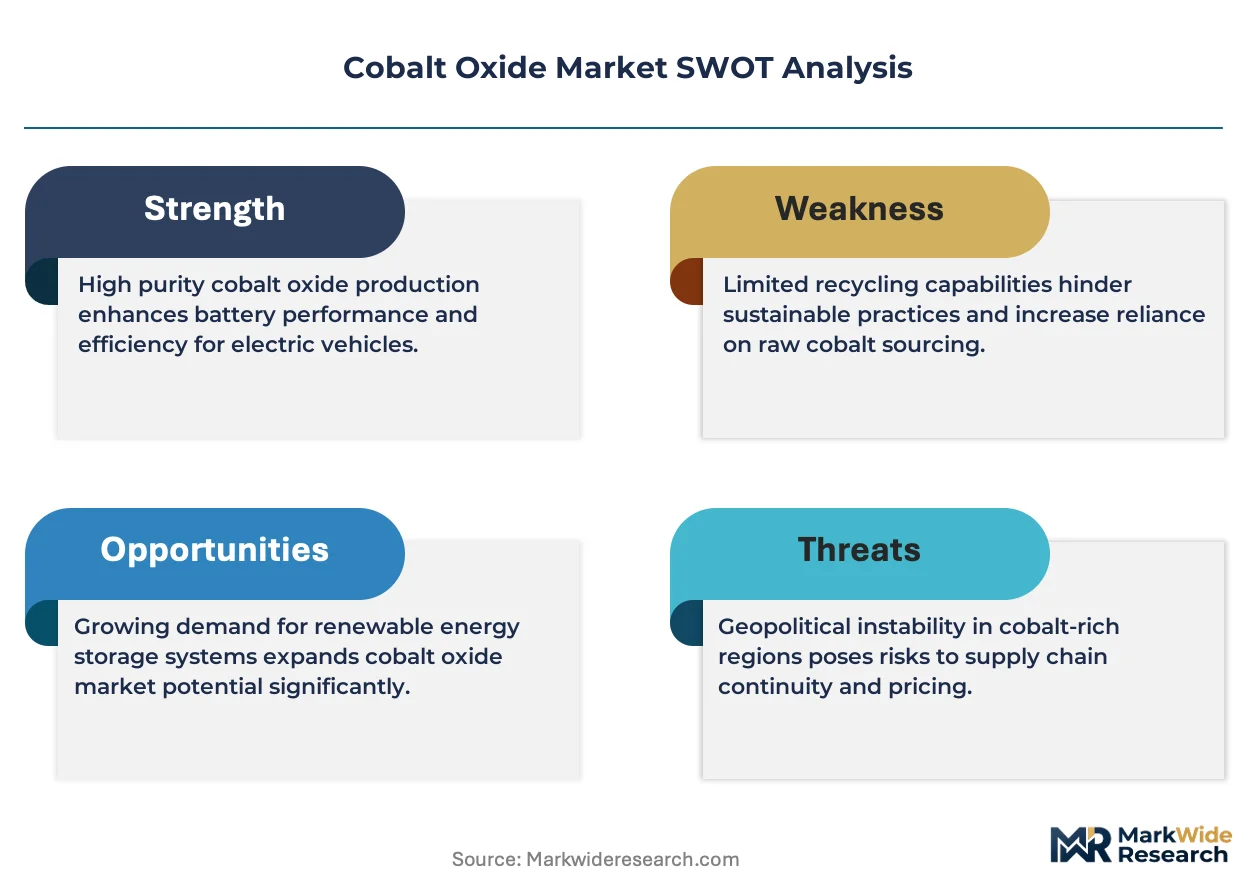
Upstream concentration in the Democratic Republic of Congo is forcing battery manufacturers to restructure their cobalt oxide procurement strategies around traceability verification and direct refiner relationships rather than merchant trading channels.
Growth Catalysts
- EU Battery Regulation:Mandatory due diligence and recycled content thresholds are compelling cathode makers to source certified cobalt oxide with verified mine-to-refiner documentation, tightening supplier qualification criteria.
- Electric vehicle cathode expansion:NCM 811 and 9.5.5 formulations are consuming higher-purity cobalt oxide feedstock as automakers prioritize energy density in premium battery packs.
- Artisanal mining formalization:DRC government licensing reforms are channeling previously informal cobalt feedstock into traceable supply chains, expanding auditable upstream capacity.
Market Restraints
- Geographic supply concentration:Over 70% of mined cobalt originates from the DRC, exposing downstream consumers to regional instability, export duty revisions, and infrastructure bottlenecks.
- Cobalt-free cathode substitution:Lithium iron phosphate and high-nickel low-cobalt chemistries are displacing cobalt oxide in cost-sensitive and high-volume battery applications.
- Input cost volatility:Sulfuric acid and energy prices for hydrometallurgical refining fluctuate with natural gas and electricity markets, compressing margin predictability for unintegrated producers.
Strategic Opportunities
- Indonesian nickel-cobalt integration:HPAL projects extracting cobalt as a nickel by-product are creating new Southeast Asian feedstock corridors outside African supply chains.
- Battery recycling mandates:EU and Chinese regulations requiring minimum recycled content in new batteries are stimulating investment in black mass processing and cobalt oxide recovery from end-of-life cells.
- Solid-state battery cathodes:Next-generation solid electrolyte interfaces demand ultra-high-purity cobalt oxide with sub-50ppm metallic impurities, opening premium specification tiers.
Industry Challenges
- Geochemical assay standardization:Discrepancies between ISO-certified laboratories and mine-site testing facilities create disputes over cobalt content and penalty element thresholds in concentrate offtake contracts.
- Carbon accounting complexity:Scope 3 emissions verification for cobalt oxide requires tracing energy sources across DRC mining, South African logistics, and Chinese refining, straining sustainability reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Oxide Market |
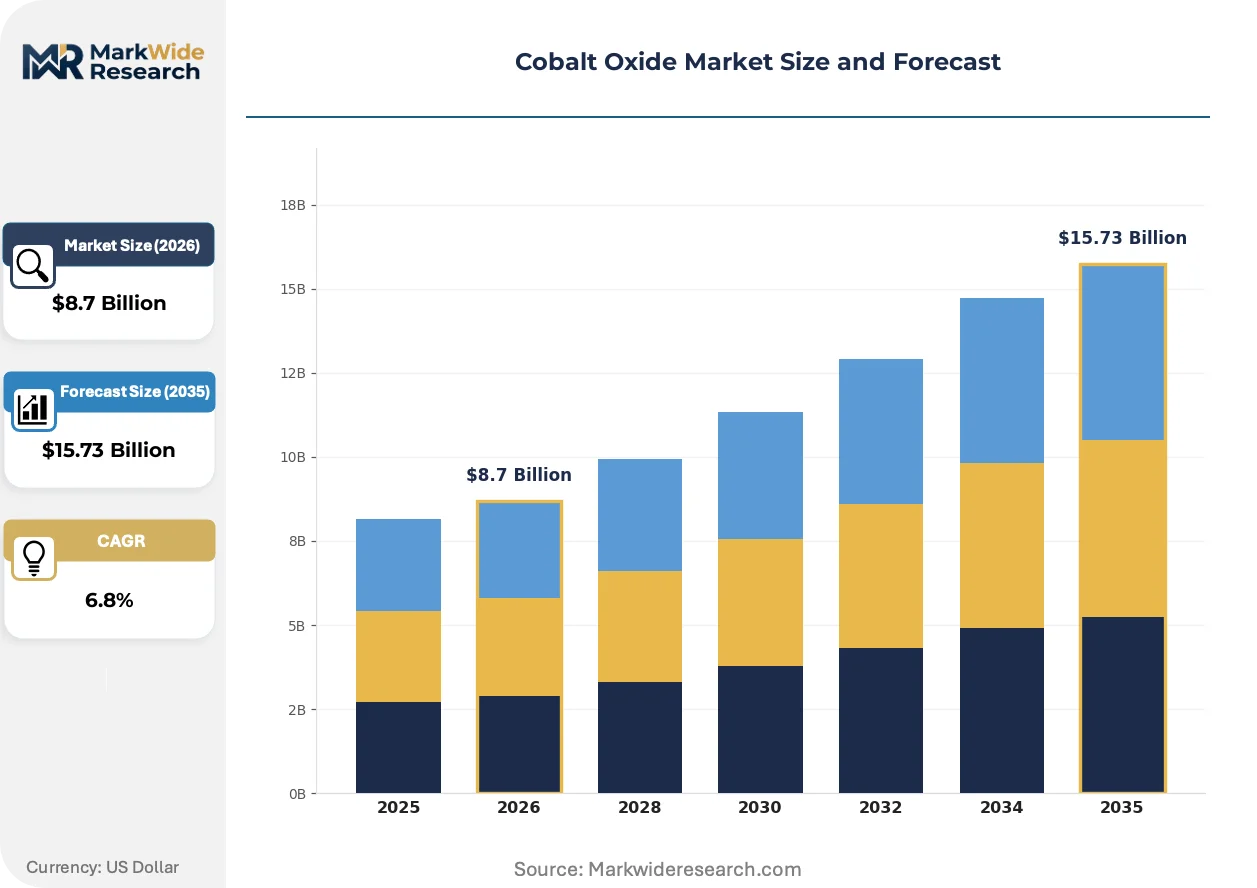
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cobalt(II) Oxide, Cobalt(III) Oxide, Cobalt Hydroxide, Cobalt Carbonate End Use Industry: Battery Manufacturing, Ceramics, Pigments, Catalyst Production Form: Powder, Granules, Pellets, Tablets Purity Grade: High Purity, Technical Grade, Ultra High Purity, Others |
| Companies Covered | Huayou Cobalt, Freeport-McMoRan, Glencore, GEM, Sherritt International Corporation, CMOC Group Limited, Eurasian Resources Group, Jinchuan International, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Oxide Market Emerging Trajectories
Cathode precursor supply chains are fragmenting from bundled merchant contracts toward direct refiner relationships, driven by traceability mandates and purity specification tightening. Three developments are restructuring competitive positioning.
Direct precursor synthesis is modularizing traditional cobalt oxide supply arrangements. Battery manufacturers are unbundling chemical conversion steps to source cobalt hydroxide intermediates directly from DRC-linked refiners, then completing final calcination in-house or at captive facilities. This architecture compresses margin capture by merchant traders while enabling lot-level chemical fingerprinting for regulatory compliance.
REACH authorization requirements for cobalt compounds are tightening industrial access across the European Economic Area. ECHA's 2023 inclusion of cobalt salts on the candidate list is forcing battery material importers to submit substitution analysis and exposure scenario documentation. Cathode producers with pre-registered supply chains are accelerating GB standard alignment with China's MIIT to maintain dual-market access.
Long-term offtake contracting is displacing spot market purchasing for battery-grade cobalt oxide. Tier 1 cathode makers in South Korea and Japan are locking five to seven-year supply commitments with integrated DRC-China refiners, securing volume priority ahead of second-tier competitors. This behavior concentrates procurement leverage among vertically integrated battery groups and marginalizes merchant-dependent mid-tier players.
Cobalt Oxide Market Segmentation
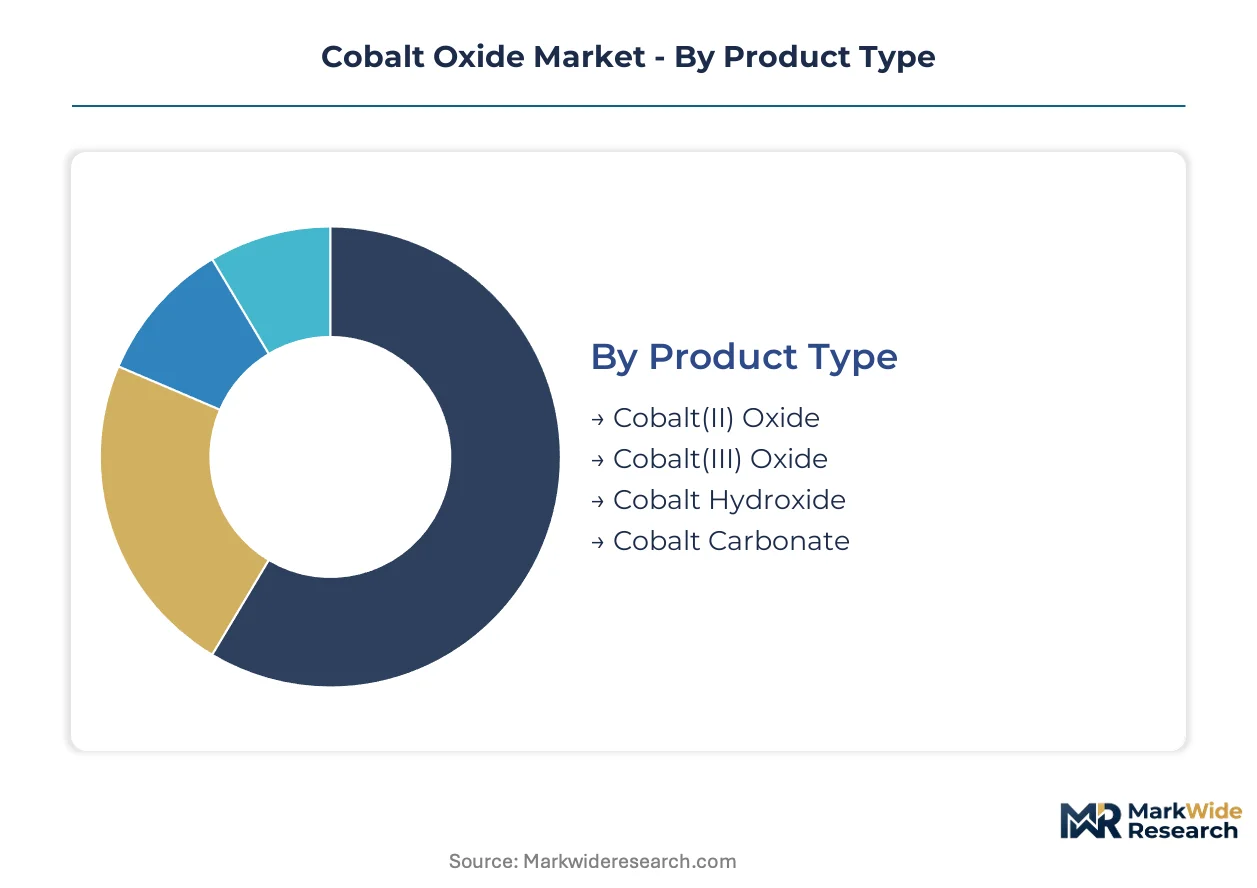
Cobalt oxide procurement patterns diverge sharply across product specifications and end-use requirements. Battery-grade cathode precursors command distinct qualification protocols compared to industrial ceramic applications, creating tiered sourcing strategies among buyers.
Product Type:
Buyers differentiate primarily by chemical oxidation state and downstream process compatibility rather than price alone.
- Cobalt(II) Oxide:Black crystalline powder with CoO stoichiometry, produced through controlled thermal decomposition of cobalt carbonate at 900-950°C. Demand concentrates in lithium cobalt oxide cathode formulations for premium consumer electronics, where Samsung SDI and LG Energy Solution enforce tight particle size distributions. China's MIIT GB/T standards for battery-grade CoO tighten impurity tolerances below 100ppm for nickel, copper, and iron.
- Cobalt Hydroxide:Intermediate feedstock with Co(OH)₂ composition serving hydrometallurgical refining circuits. Indonesian HPAL projects and DRC concentrate exporters ship hydroxide to Chinese refiners for final calcination to battery-grade oxide. The material's lower thermal processing burden appeals to cathode makers completing conversion in-house.
- Cobalt(III) Oxide:Higher oxidation state compound with Co₂O₃ stoichiometry, deployed in specialized ceramic magnet formulations and certain catalyst applications where trivalent cobalt reactivity proves advantageous.
- Cobalt Carbonate:Precursor salt CoCO₃ used primarily in pigment manufacturing and as a calcination feedstock for oxide production, with pigment makers in Italy and Spain representing concentrated demand pockets.
Cobalt(II) oxide leads volumes today; cobalt hydroxide is gaining share fastest.
End Use Industry:
Application-specific purity mandates and certification requirements separate procurement tiers.
- Battery Manufacturing:Cathode precursor consumption dominates value capture, with NCM 811 and 9.5.5 formulations requiring sub-50ppm metallic impurities. South Korean and Japanese cathode makers enforce lot-level chemical fingerprinting for EU Battery Regulation compliance.
- Ceramics:Glaze colorant applications tolerate higher iron and nickel content, sourcing technical-grade material through merchant trading channels rather than direct refiner relationships.
- Pigments:Cobalt blue and violet ceramic pigments utilize carbonate and lower-purity oxide grades, with Italian manufacturers representing legacy demand concentration.
- Catalyst Production:Petrochemical and emission control catalysts demand controlled surface area and porosity specifications, sourcing through specialty chemical distributors rather than mining-integrated suppliers.
Battery manufacturing commands margin concentration; catalyst production shows steepest specification tightening.
Form:
Physical morphology determines handling economics and reactor compatibility across conversion processes.
- Powder:Dominant shipment format for cathode precursor integration, with particle size distributions calibrated to dry mixing and calcination equipment at LG Chem and POSCO Chemical facilities.
- Granules:Intermediate agglomeration state reducing dust exposure during handling, preferred by ceramic glaze manufacturers in Spain and Italy with manual batching operations.
- Pellets:Compacted cylindrical form enabling precise volumetric feeding in continuous catalyst production lines.
- Tablets:High-density pressed form for specialized metallurgical and chemical synthesis applications requiring minimal surface oxidation during storage.
Powder dominates shipment volumes; granules are expanding most quickly in ceramic applications.
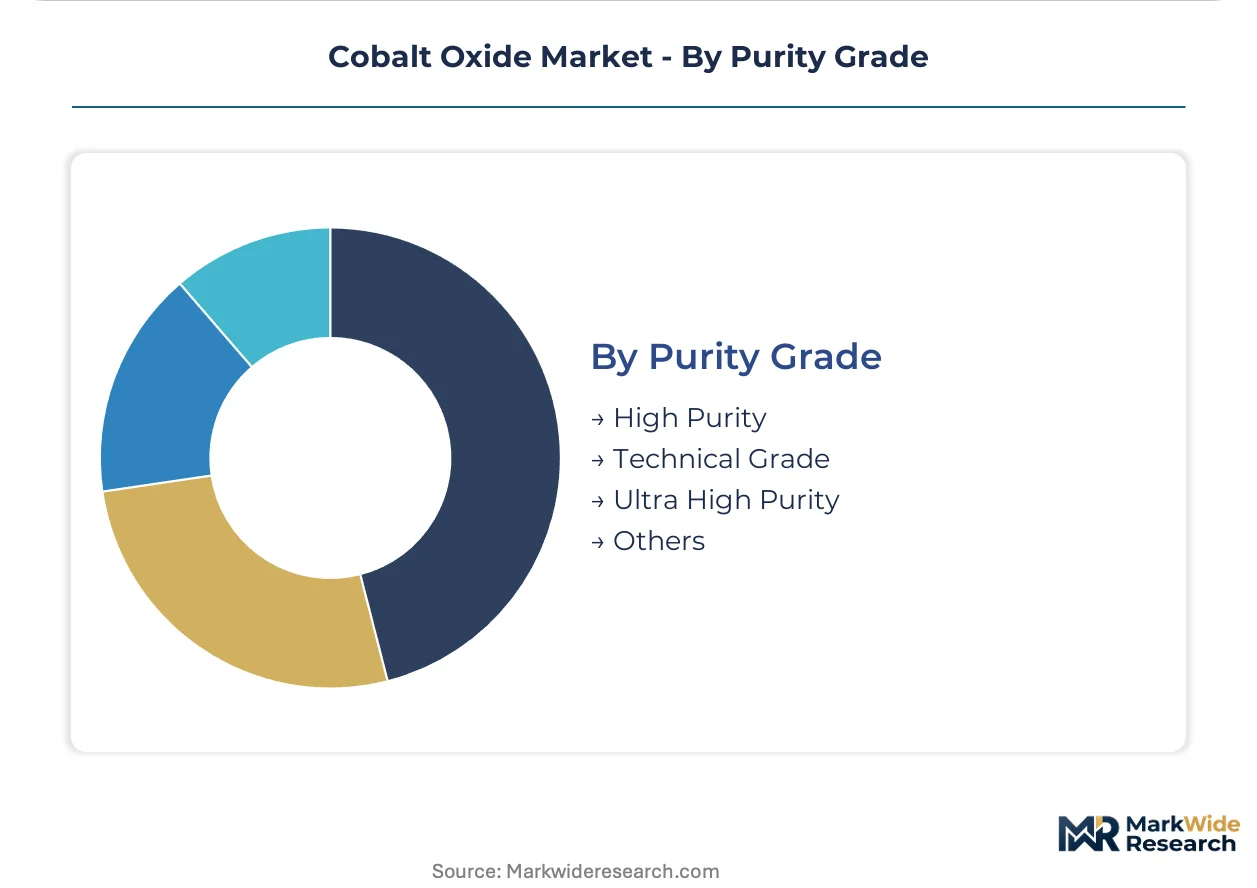
Purity Grade:
Specification tolerance bands separate pricing tiers by an order of magnitude.
- High Purity:99.5-99.9% cobalt content with controlled alkali and alkaline earth metals, serving NCM 622 and 811 cathode formulations where residual sodium and calcium degrade cycle life.
- Ultra High Purity:Sub-50ppm total metallic impurities and sub-10ppm individual element limits, required for solid-state battery cathode interfaces and premium automotive cell qualifications.
- Technical Grade:98-99% cobalt content with relaxed transition metal tolerances, sufficient for ceramic pigments and industrial catalysts where cost minimization dominates.
- Others:Custom specification blends including battery-grade intermediates and metallurgical feedstock categories outside standard classification schemes.
High purity leads volumes today; ultra high purity is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cobalt oxide processing scaled through Chinese hydrometallurgical corridors during the 2000s, establishing the foundational geography for battery-grade refining capacity.
China
Huayou Cobalt and GEM anchor cathode precursor production in Zhejiang and Guangdong provinces, feeding South Korean and Japanese battery makers. MIIT enforces GB/T standards for battery-grade purity. The Yangtze River Delta corridor concentrates calcination and chemical conversion facilities serving NCM 811 formulations.
Democratic Republic of Congo
Artisanal and industrial mining operations in Lualaba and Haut-Katanga provinces supply over seventy percent of global cobalt feedstock. The national mining code revises royalty structures on strategic minerals. Kolwezi and Lubumbashi serve as logistics hubs for concentrate export to Chinese refiners.
Indonesia
High-pressure acid leach projects in Sulawesi and Halmahera extract cobalt as a nickel by-product, diversifying supply outside African corridors. The Ministry of Energy and Mineral Resources regulates downstream processing incentives. Morowali Industrial Park hosts integrated HPAL-to-precursor facilities supplying battery manufacturers.
South Korea
LG Energy Solution and POSCO Chemical enforce lot-level chemical fingerprinting for EU Battery Regulation compliance. The Ministry of Trade, Industry and Energy supports cathode material R&D through national technology programs. Gyeonggi Province hosts qualification laboratories for ultra-high-purity cobalt oxide testing.
Belgium
Umicore operates refining and recycling capabilities in Hoboken, processing black mass from end-of-life batteries. ECHA REACH authorization requirements tighten industrial access for cobalt compounds. The Port of Antwerp handles intermediate feedstock flows between DRC concentrate exporters and European cathode makers.
Cobalt Oxide Market Vendor Landscape
The competitive structure tilts toward integrated mining-to-refining conglomerates with captive DRC feedstock access. Merchant traders and independent refiners occupy secondary positions as traceability mandates concentrate procurement leverage among verified supply chain operators. Two strategic archetypes dominate: vertically integrated Chinese refiners controlling DRC-to-Asia corridors, and diversified mining majors extracting cobalt as a by-product of nickel or copper operations. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, with five-to-seven-year supply commitments displacing spot market purchasing.
Among DRC-integrated Chinese refiners, Huayou Cobalt and GEM exemplify the vertically integrated archetype with controlled feedstock corridors. Freeport-McMoRan represents the diversified mining-major model, extracting cobalt through Indonesian nickel operations. These three occupy distinct competitive positions: Huayou and GEM anchor the integrated refining tier, while Freeport-McMoRan sits within the by-product extraction segment. Each exemplifies how geographic and structural positioning shapes margin capture in an environment tightening around traceability verification.
| Leading Market Players |
|---|
| Huayou Cobalt |
| Freeport-McMoRan |
| Glencore |
| GEM |
| Sherritt International Corporation |
| CMOC Group Limited |
| Eurasian Resources Group |
| Jinchuan International |
| Umicore |
| Others |
Supply Flow & Price Mechanics
Captive DRC-to-China refining corridors anchor both supply security and margin capture for integrated producers, while merchant-dependent operators face pricing power erosion as traceability mandates concentrate procurement leverage among verified supply chain operators.
Pricing Analysis
Long-term offtake contracting dominates battery-grade cobalt oxide procurement, with five-to-seven-year supply commitments displacing spot market purchasing. Price differentiation hinges on purity certification tier and verified mine-to-refiner documentation under EU Battery Regulation compliance. Cost compression in technical-grade material intensifies as Indonesian HPAL by-product streams expand feedstock availability. Ceramic pigment buyers exhibit highest price sensitivity; solid-state battery cathode makers show lowest sensitivity due to ultra-high-purity specification requirements.
Supply Chain Analysis
Direct-to-cathode-maker channels handle tier 1 battery manufacturer demand, while merchant trading networks serve ceramic and pigment applications. Supply concentrates in the Democratic Republic of Congo for mined feedstock, China for hydrometallurgical refining, and Indonesia for nickel-cobalt by-product extraction. The corridor draws from sulfuric acid, energy inputs, and cobalt concentrate as critical dependencies. Single-source vulnerability in DRC concentrate supply exposes downstream consumers to export duty revisions and infrastructure bottlenecks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cobalt oxide market functions as a geographic-arbitrage play between African mining economics and Asian refining scale, with EU regulatory compliance costs creating divergent margin structures across supply chain positions.
For Market Incumbents: Deepen upstream control over DRC concentrate corridors to defend against Indonesian HPAL displacement, while accelerating GB standard alignment with China's MIIT to maintain dual-market access amid REACH authorization tightening for cobalt compounds. For New Entrants and Emerging Players: Launch via black mass processing partnerships to capture EU Battery Regulation recycled content mandates, targeting battery recycling hubs in Belgium and South Korea as the most penetrable entry points. For Investors and Strategic Acquirers: Roll-up economics work for integrated DRC-China refiners because traceability verification concentrates procurement leverage among verified supply chain operators. Long-term viability favors assets with captive mine-to-refiner documentation and HPAL by-product diversification. Watch Indonesian nickel-cobalt integration rates as the inflection signal for African supply chain displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DRC Mining | Huayou Cobalt and GEM secure captive concentrate supply ahead of royalty code revisions. |
| HPAL Capacity Expansion | Indonesian projects extract cobalt as nickel by-product, diversifying feedstock outside African corridors. |
| Long-term Supply Agreement | LG Energy Solution and POSCO Chemical lock five-to-seven-year commitments with integrated refiners. |
| Black Mass Processing Investment | Umicore's Hoboken facility processes end-of-life batteries for EU recycled content compliance. |
| Ultra-high-purity Certification | Solid-state battery cathode specifications open premium pricing tiers above standard battery-grade material. |
Methodological Framework
Coverage spans China, the Democratic Republic of Congo, Indonesia, South Korea, and Belgium, with primary inputs from each market cluster combining interviews with cathode material procurement directors, hydrometallurgical plant managers, DRC concentrate exporters, and EU regulatory affairs specialists. Secondary validation draws from Chinese customs data, SEC filings by integrated producers, ECHA REACH documentation, and MIIT GB standard publications. Bottom-up demand modeling triangulates against top-down supply capacity assessments.
Segmentation granularity extends to oxidation state chemistry, purity grade tier, end-use industry application, and physical form morphology across the projection horizon. CAGRs derive from weighted average growth assumptions across battery manufacturing, ceramics, pigments, and catalyst consumption endpoints. Modeling incorporates NCM cathode chemistry evolution, solid-state battery commercialization timelines, and DRC artisanal mining formalization progress as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DRC export policy shifts, cobalt-free cathode substitution acceleration, or EU recycled content threshold revisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Ferrofluid Market