
 Steel Bar Magnet Market | 2026-2036
Steel Bar Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Bar Magnet Market Analytics
Neodymium is consolidating its position as the dominant rare-earth composition in premium steel bar magnet formulations, though ferrite gains ground in cost-sensitive industrial tiers. Hitachi Metals Ltd. leverages integrated rare-earth sourcing from its upstream mining partnerships to secure alloy consistency. Shin-Etsu Chemical Co., Ltd. anchors its competitive stance through proprietary sintering technologies that yield higher coercivity grades. Arnold Magnetic Technologies differentiates via custom magnetic circuit design services bundled with bar magnet supply.
A steel bar magnet is a ferromagnetic alloy formed into elongated rectangular or cylindrical geometry, typically exhibiting remanence values from 1.0 to 1.4 tesla depending on composition, and serves to generate static magnetic fields for electromechanical force translation. Neodymium segments command premium positioning due to maximum energy product superiority in servo motor miniaturization, while ferrite occupies volume leadership across conveyor and separation equipment where field strength requirements moderate. Alnico retains niche durability advantages in high-temperature automotive sensor applications where thermal demagnetization resistance proves critical.
The EPA governs hazardous substance reporting for magnet manufacturing facilities under TSCA mandates, while REACH compliance in Europe restricts hexavalent chromium coatings traditionally applied to steel bar magnets for corrosion protection. China's MIIT enforces dual carbon goals that elevate energy efficiency standards for magnetic materials used in industrial motor applications. Stakeholders must monitor evolving coating chemistry substitutions and certify supply chain documentation ahead of tightening substance restrictions across multiple jurisdictions.
Market Dynamics
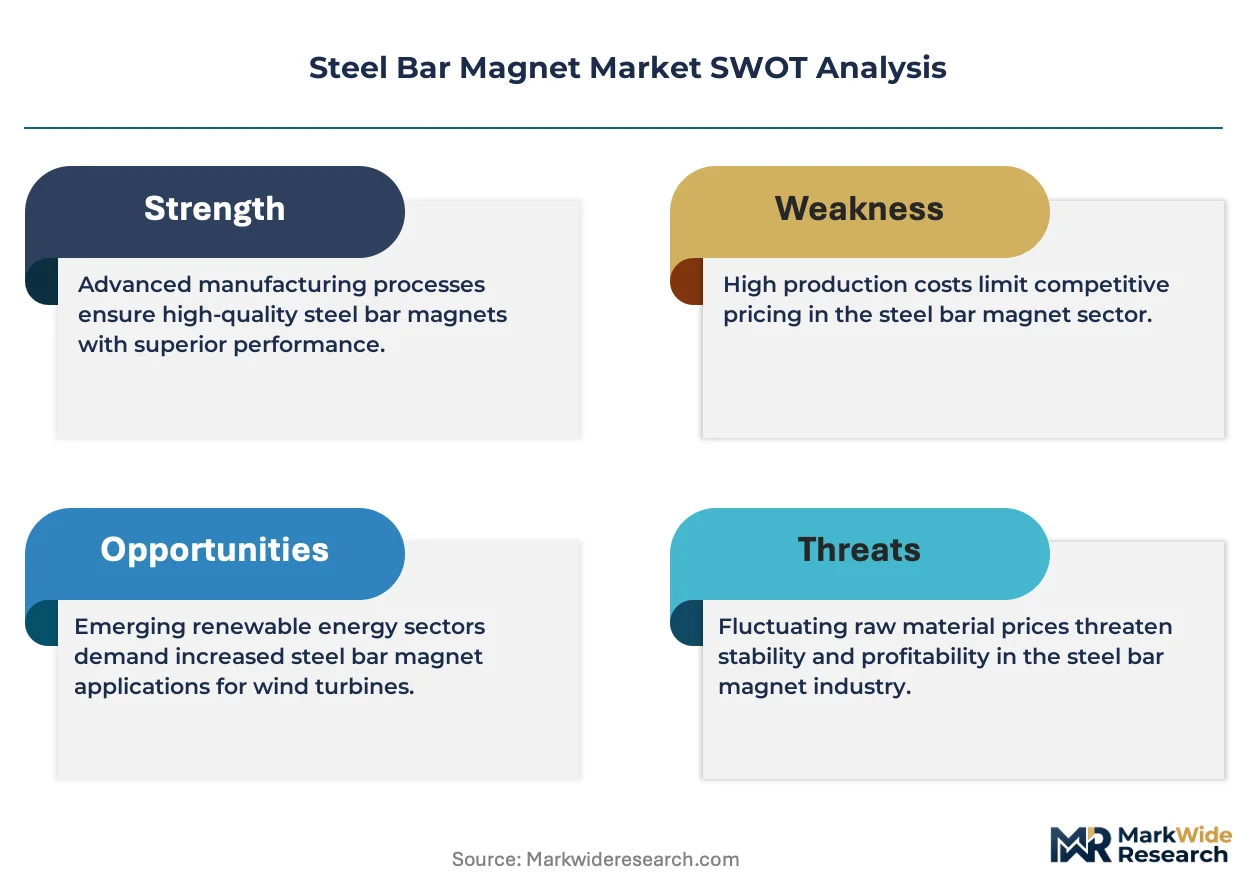
Rare earth supply concentration in China and tightening environmental mandates across industrialized economies are forcing steel bar magnet buyers toward ferrite and alnico alternatives while reshaping long-term procurement contracts.
Growth Catalysts
- Industrial Automation Intensification:Servo motor manufacturers in Germany's precision manufacturing corridor specify certified magnetic assemblies for motion control systems.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases redirect investment toward magnetic refrigeration systems using permanent magnet assemblies.
- Neodymium Alloy Advances:Sintering technology improvements yield higher coercivity grades that enable motor miniaturization in robotics applications.
Market Restraints
- Rare Earth Concentration Risk:China's MIIT export licensing and dual carbon goals create supply vulnerability for neodymium-dependent formulations.
- Hexavalent Chromium Phase-Out:REACH compliance deadlines in Europe eliminate traditional corrosion coatings, forcing costly chemistry substitutions.
- Ferrite Performance Ceiling:Maximum energy product limitations prevent substitution in high-torque servo applications requiring miniaturization.
Strategic Opportunities
- Alnico Thermal Durability:High-temperature automotive sensor applications where thermal demagnetization resistance proves critical remain underexploited.
- Magnetic Circuit Design Services:Bundled engineering consultation creates differentiation beyond commodity bar magnet supply.
- India PLI Scheme:Production-linked incentives for advanced cell manufacturing could stimulate domestic magnet assembly demand.
Industry Challenges
- Rare Earth Metallurgy Expertise Gap:Alloy consistency engineering requires specialized knowledge concentrated in Japanese and Chinese technical institutes.
- Multi-Jurisdiction Certification Timelines:TSCA reporting, REACH documentation, and MIIT carbon audits create overlapping compliance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Bar Magnet Market |
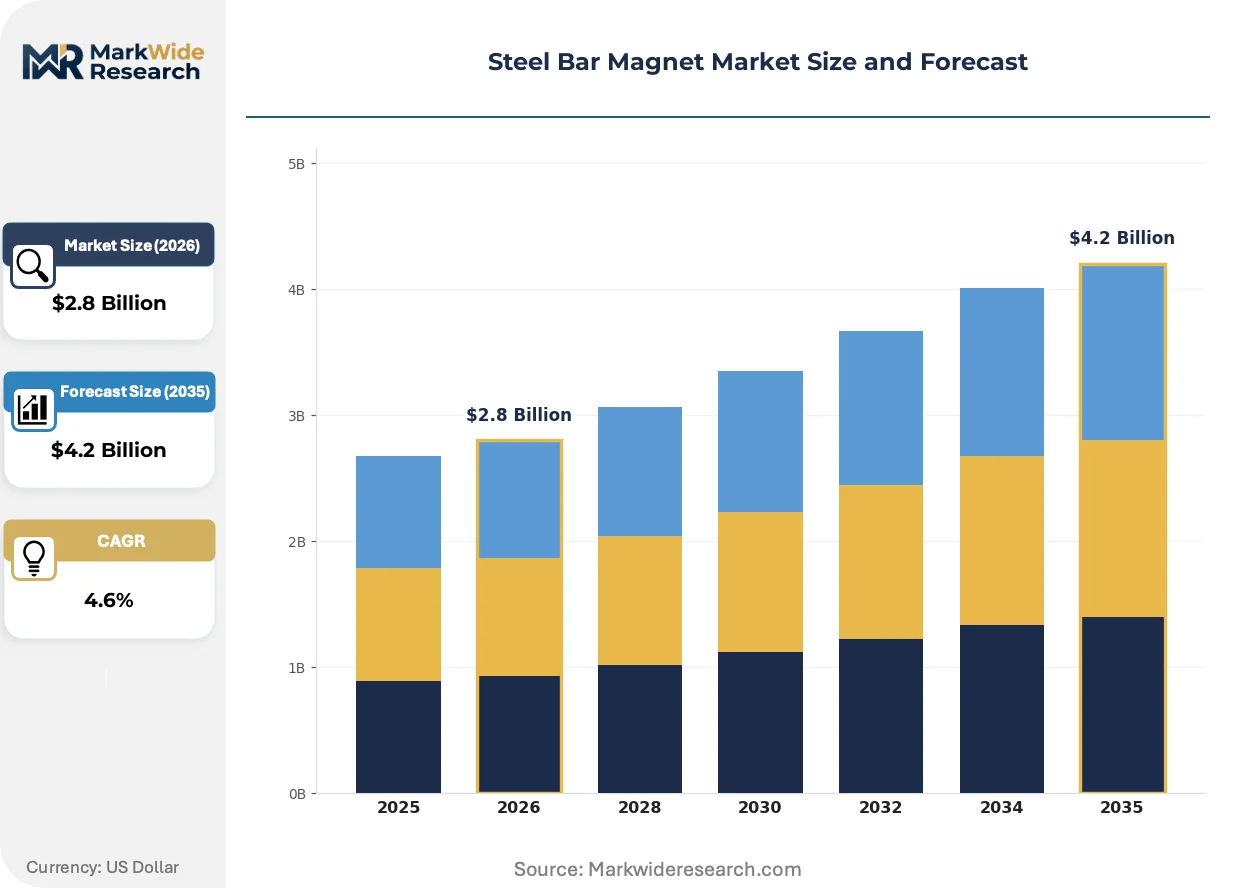
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neodymium, Samarium Cobalt, Ferrite, Alnico Application: Industrial Automation, Automotive, Consumer Electronics, Renewable Energy End User: Manufacturers, Distributors, Retailers, Research Institutions Technology: 3D Printing, Magnetic Assembly, Coating, Recycling |
| Companies Covered | Hitachi Metals Ltd., Shin-Etsu Chemical Co., Ltd., Arnold Magnetic Technologies, Adams Magnetic Products Co., Hangzhou Permanent Magnet Group, Daido Steel Co., Ltd., TDK Corporation, Vacuumschmelze GmbH & Co. KG, Electron Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Bar Magnet Market Evolving Landscape
Magnetic material engineering is pivoting toward sustainability-aligned formulations and service-integrated supply models that embed technical consultation into core offerings.
Grain boundary diffusion technology is integrating dysprosium and terbium into neodymium magnet surfaces rather than bulk alloying. Automotive tier-1 suppliers in Stuttgart and Nagoya are specifying these grades for traction motor applications. This diffusion approach is integrating heavy rare earth conservation with performance maintenance, compressing material cost structures for high-volume electric powertrain programs.
REACH substance restrictions are eliminating hexavalent chromium passivation layers from corrosion protection protocols. Magnet finishers must certify trivalent chromium or nickel-copper-nickel alternatives through ECHA notification procedures. German automotive OEMs are accelerating coating chemistry validation to maintain component qualification status ahead of 2026 restriction enforcement.
Certification-driven supplier consolidation is compressing approved vendor lists across European industrial automation channels. Buyers now require ISO 9001 and IATF 16949 documentation bundled with magnetic property test reports. This qualification burden favors integrated manufacturers with captive metrology laboratories over trading intermediaries.
Steel Bar Magnet Market Segmentation
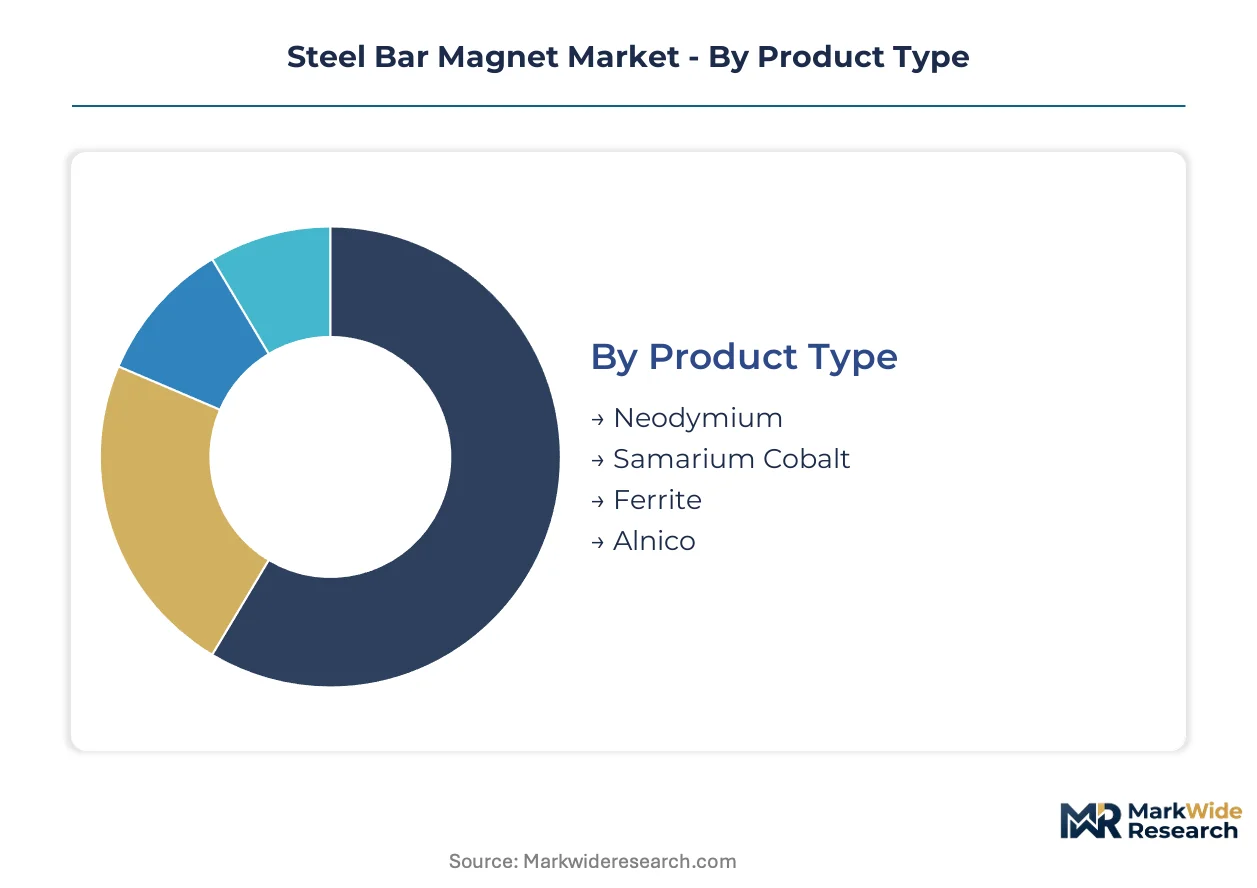
Steel bar magnet procurement hinges on magnetic performance requirements, thermal operating conditions, and regulatory compliance burdens that vary sharply across end-use environments. Buyers segment formulations by energy product specifications and corrosion resistance needs rather than commodity-grade purchasing.
Product Type:
Cost tier and magnetic energy density drive formulation selection in servo motor and sensor applications.
- Neodymium:Sintered NdFeB alloys deliver maximum energy products exceeding 400 kJ/m³, enabling motor miniaturization in Stuttgart robotics clusters where space constraints dominate design. Rare earth supply licensing under China's MIIT creates procurement volatility for German automotive tier-1 suppliers.
- Ferrite:Ceramic ferrite formulations offer moderate coercivity at substantially lower material cost, absorbing volume demand across conveyor separation equipment in India's industrial corridors where field strength requirements remain modest. BIS certification requirements are tightening for imported magnetic assemblies.
- Samarium Cobalt:SmCo alloys retain magnetic properties above 300°C, serving aerospace actuator applications where thermal demagnetization resistance commands premium positioning.
- Alnico:Cast alnico grades withstand continuous 450°C operation, maintaining niche positioning in automotive exhaust sensors across Nagoya manufacturing networks.
Ferrite leads on scale; neodymium leads on momentum.
Application:
End-use environment dictates certification depth and magnetic circuit complexity requirements.
- Industrial Automation:Servo motor manufacturers in Germany's precision manufacturing corridor specify certified magnetic assemblies with IATF 16949 documentation. REACH substance restrictions on hexavalent chromium coatings are forcing chemistry substitutions ahead of enforcement deadlines.
- Automotive:Traction motor applications specify grain boundary diffusion grades to conserve dysprosium while maintaining coercivity. ECHA notification procedures for trivalent chromium alternatives are compressing supplier qualification timelines.
- Consumer Electronics:Miniature actuator demand concentrates in Shenzhen and Seoul manufacturing hubs where magnetic assembly precision tolerances tighten annually.
- Renewable Energy:Direct-drive wind turbine generators specify large-block neodymium assemblies with specialized corrosion protection for offshore environments.
Automotive commands premium positioning; industrial automation expands most quickly.
End User:
Procurement sophistication varies by technical integration depth and volume scale.
- Manufacturers:OEMs with captive magnetic circuit design capabilities specify alloy grades directly, bypassing distributor markup. German robotics OEMs require bundled engineering consultation with bar magnet supply.
- Distributors:Channel intermediaries face compression as certification-driven supplier consolidation favors direct manufacturer relationships with integrated metrology laboratories.
- Retailers:Hobbyist and educational magnet sales concentrate through e-commerce platforms with minimal technical specification requirements.
- Research Institutions:National laboratories access specialized high-temperature grades through government procurement frameworks with extended qualification protocols.
Manufacturers dominate volume capture; research institutions show steepest specification escalation.
Technology:
Process innovation is reshaping cost structures and environmental compliance pathways.
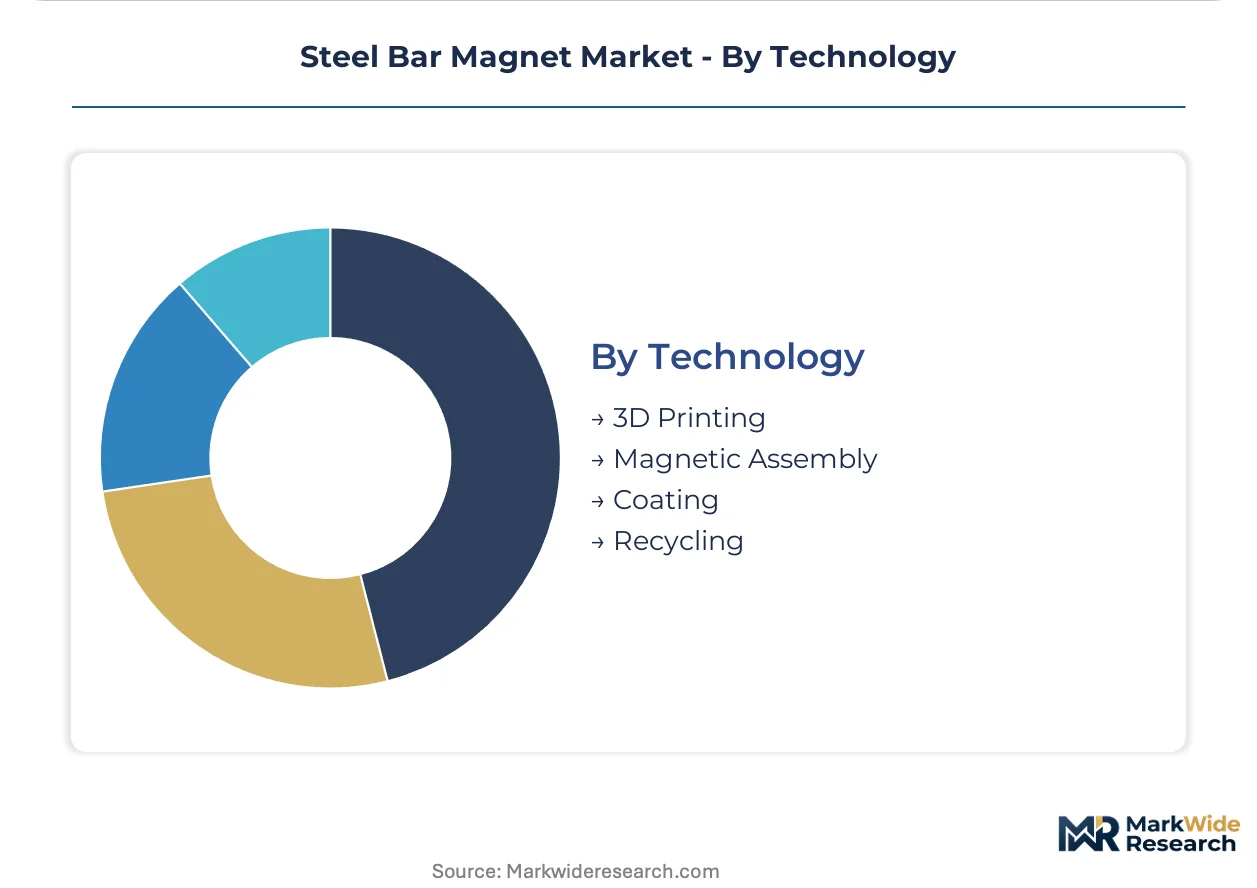
- 3D Printing:Additive manufacturing of magnetic alloys enables complex pole geometries for custom actuator designs, with METI-funded development programs accelerating in Osaka technical institutes.
- Magnetic Assembly:Automated magnetization and pole orientation systems reduce labor content in high-volume automotive programs. ISO 9001 documentation requirements favor integrated manufacturers over trading intermediaries.
- Coating:Trivalent chromium and nickel-copper-nickel passivation layers are displacing hexavalent chromium under REACH mandates, with ECHA notification procedures adding certification burden.
- Recycling:Hydrometallurgical recovery of rare earth content from end-of-life magnets is scaling in response to China's dual carbon goals and export licensing constraints.
Magnetic assembly leads on deployment scale; recycling gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor concentrates the highest specification demand for certified magnetic assemblies in servo motor and robotics applications. Regional procurement patterns diverge sharply between premium neodymium formulations for miniaturization and ferrite alternatives for cost-sensitive industrial tiers.
Germany
Automotive tier-1 suppliers in Stuttgart specify grain boundary diffusion grades for traction motor applications. The EU's F-Gas Regulation redirects investment toward magnetic refrigeration systems using permanent magnet assemblies. Bavaria's robotics OEMs require IATF 16949 documentation bundled with magnetic circuit design services from integrated manufacturers.
China
MIIT export licensing and dual carbon goals constrain neodymium supply availability for international buyers. The country's rare earth metallurgy expertise concentrates alloy consistency engineering within technical institutes in Beijing and Shanghai. Shenzhen manufacturing hubs drive miniature actuator demand for consumer electronics with tightening precision tolerances.
Japan
METI-funded development programs in Osaka accelerate additive manufacturing of magnetic alloys for custom actuator designs. JIS standards govern sintering technology improvements yielding higher coercivity grades. Nagoya manufacturing networks maintain niche alnico demand for high-temperature automotive exhaust sensors.
United States
EPA TSCA mandates govern hazardous substance reporting for magnet manufacturing facilities. The IRA creates production-linked incentives for domestic magnet assembly capacity expansion. Midwest industrial automation corridors absorb larger volumes of high-performance steel bar magnets as servo motor requirements intensify.
India
BIS certification requirements tighten for imported magnetic assemblies across conveyor separation equipment. The PLI scheme for advanced cell manufacturing stimulates domestic magnet assembly demand in Gujarat and Maharashtra. India's industrial corridors favor ferrite formulations where field strength requirements remain modest and cost sensitivity dominates procurement.
Steel Bar Magnet Market Competitive Landscape
Global majors compete with regional champions across rare earth sourcing integration and proprietary sintering capabilities. The vendor base stratifies into three tiers: integrated miners with captive alloy production, specialized magnetic material engineers with proprietary process IP, and assembly-focused fabricators serving cost-sensitive volume segments. Dominant competitive moves include backward integration into rare earth mining partnerships and certification-driven supplier consolidation compressing approved vendor lists.
Among Japanese material science conglomerates, Hitachi Metals Ltd. and Shin-Etsu Chemical Co., Ltd. occupy positions exemplifying upstream integration and proprietary sintering technology archetypes respectively. Arnold Magnetic Technologies represents the engineering-services bundling model, anchoring differentiation through custom magnetic circuit consultation rather than commodity supply alone.
| Leading Market Players |
|---|
| Hitachi Metals Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Arnold Magnetic Technologies |
| Adams Magnetic Products Co. |
| Hangzhou Permanent Magnet Group |
| Daido Steel Co., Ltd. |
| TDK Corporation |
| Vacuumschmelze GmbH & Co. KG |
| Electron Energy Corporation |
| Others |
Value Network & Pricing Analysis
Captive rare-earth mining partnerships anchor supply position and pricing power for integrated Japanese and Chinese producers, while non-integrated fabricators absorb margin compression from alloy cost volatility and coating chemistry substitutions under tightening substance restrictions.
Pricing Analysis
Input-cost pass-through from dysprosium and terbium spot markets drives pricing volatility for grain boundary diffusion grades. Three-tier pricing structure across certified automotive, standard industrial, and uncertified commodity tiers reflects IATF 16949 documentation burdens. Cost compression in ferrite segments intensifies because Indian and Southeast Asian buyers prioritize volume scale over coercivity specifications. Distributors serving hobbyist and educational channels exhibit highest price sensitivity; German automotive tier-1 suppliers show lowest sensitivity due to embedded magnetic circuit design services.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart robotics clusters and Nagoya automotive networks, bypassing distributor markup. Raw material sourcing concentrates in China's Jiangxi and Inner Mongolia rare-earth mining zones, with secondary metallurgy expertise in Japan's Chubu region. The chain draws from neodymium-iron-boron alloy feedstock, trivalent chromium coating precursors, and automated magnetization equipment. Single-source vulnerability from MIIT export licensing creates procurement risk for international buyers. Distribution runs through certified manufacturer-direct relationships with captive metrology laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as German robotics OEMs mandate bundled engineering consultation with magnetic property certification, elevating late-cycle margin capture for integrated suppliers.
For Market Incumbents: Anchor market position through backward integration into rare-earth mining partnerships and captive sintering capacity expansion in Japan or China. Certification investment in ISO 9001 and IATF 16949 documentation compresses approved vendor lists against trading intermediaries. Defend against ferrite substitution in cost-sensitive tiers by emphasizing coercivity grade differentiation for servo motor miniaturization. For New Entrants and Emerging Players: Specialized magnetic circuit design boutiques can penetrate the Stuttgart precision manufacturing corridor where German automotive tier-1 suppliers require custom actuator engineering. White-space exists in alnico formulations for high-temperature automotive exhaust sensors across Nagoya manufacturing networks. Go-to-market should leverage METI-funded technical partnerships for alloy process validation. For Investors and Strategic Acquirers: Roll-up economics work for regional magnetic assembly fabricators because certification-driven supplier consolidation compresses approved vendor lists and creates scale advantages in metrology investment. Long-term viability centers on five-to-ten year windows for rare-earth recycling infrastructure as China's dual carbon goals constrain primary supply. Watch MIIT export licensing intensity as inflection indicator for Western supply chain restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Mining | Secures alloy consistency for Hitachi Metals and Shin-Etsu against MIIT licensing volatility. |
| Grain Boundary Diffusion Scale-Up | Conserves dysprosium content while meeting Stuttgart traction motor coercivity specifications. |
| Trivalent Chromium Coating Certification | Maintains ECHA compliance for German automotive OEMs ahead of hexavalent chromium phase-out. |
| Magnetic Circuit Design Service Bundling | Differentiates Arnold Magnetic Technologies from commodity bar magnet suppliers in robotics channels. |
| Hydrometallurgical Recycling Capacity | Addresses China's dual carbon goals while securing rare-earth feedstock for Western magnet assemblers. |
Research Methodology
Direct dialogue with magnet manufacturing plant managers, procurement leads at German automotive tier-1 suppliers, technical R&D directors at Japanese material science conglomerates, and channel partners in Indian industrial corridors grounded qualitative findings. Secondary validation drew from MIIT export licensing disclosures, ECHA REACH substance restriction updates, SEC 10-K filings of listed magnetic material producers, and BIS certification requirement notifications. Bottom-up alloy grade demand modeling triangulated against top-down regional industrial automation investment forecasts.
Segment-level value outputs across the projection horizon reflect neodymium, ferrite, samarium cobalt, and alnico formulation tiers crossed with servo motor, automotive traction, consumer electronics, and renewable energy applications. CAGRs derived from regression against industrial automation capital expenditure indices and electric powertrain production trajectories. Forecast inputs incorporated MIIT dual carbon policy stringency scenarios and REACH coating chemistry substitution timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth export licensing volatility, trivalent chromium coating validation delays, and servo motor miniaturization technology shifts. Outputs reflect documented assumptions on alloy substitution elasticity and regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Catalyst Bins Market
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Portable Magnetizer Market