
 Ferric Fluoride Market | 2026-2036
Ferric Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Ferric Fluoride Market Analysis
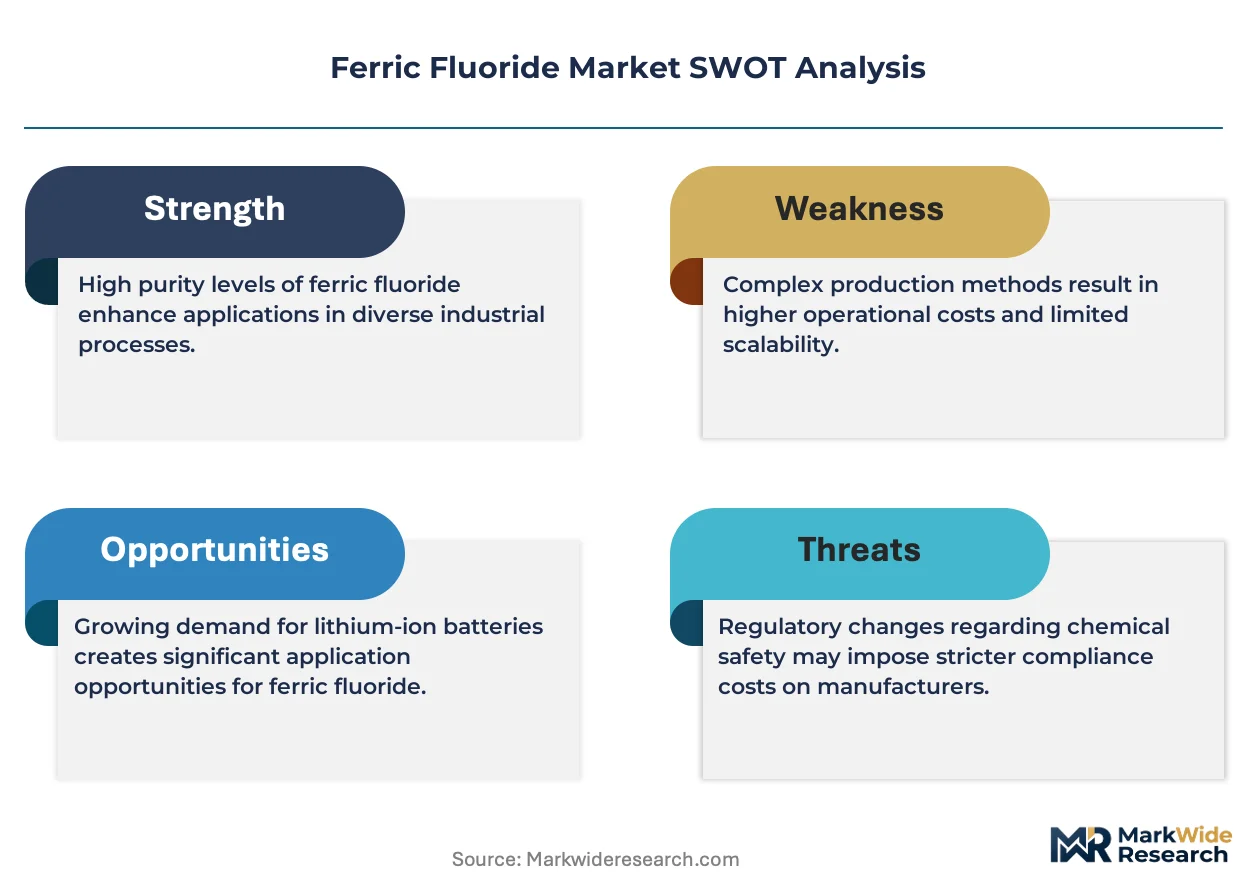
Battery-grade purity specifications are redrawing supplier hierarchies in the ferric fluoride value chain. Sigma-Aldrich (Merck) leverages its analytical standards heritage to command premium positioning in laboratory and R&D channels. XI'AN FUNCTION MATERIAL GROUP CO., LTD anchors Chinese domestic supply through integrated fluoride processing capabilities and direct industrial offtake relationships. American Elements specializes in custom synthesis for aerospace and defense applications where trace metal tolerances sit below 10 ppm.
Ferric fluoride denotes an inorganic compound with the formula FeF3, existing in anhydrous, hydrated, and aqueous solution forms with melting points varying by hydration state from approximately 1000°C for the anhydrous salt to decomposition thresholds near 100°C for hexahydrate variants; manufacturers deploy hydrofluoric acid leaching or direct fluorination routes to achieve target purity tiers for catalytic and electronic applications. Anhydrous grades dominate margin pools due to energy-intensive dehydration requirements and stringent moisture specifications for lithium-ion battery electrolyte additives. Hexahydrate and solution formats compete on volume in water treatment and metal surface preparation where technical specifications permit higher hydration levels.
EPA standards under the Toxic Substances Control Act and REACH registration mandates through ECHA impose graduated compliance burdens based on purity tier and end-use exposure pathways. China's MIIT and NMPA coordinate GB standard revisions that increasingly reference battery material specifications, narrowing the window for non-conforming imports. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Battery-grade ferric fluoride specifications are compressing supplier margins while redrawing qualification hierarchies, as cathode material producers enforce sub-10 ppm trace metal tolerances that disqualify legacy hydrofluoric acid leaching operations.
Growth Catalysts
- Semiconductor Etching Demand:Advanced node fabrication below 7 nm requires ultra-high-purity FeF3 for plasma etching of tungsten interconnects, with foundries in Taiwan and South Korea expanding capacity.
- EU Battery Regulation:Mandatory recycled content thresholds and carbon footprint declarations for lithium-ion cells are accelerating qualification of European-sourced battery-grade fluoride salts.
- Direct Fluorination Advances:Gas-phase fluorination of iron oxide precursors is displacing aqueous routes for anhydrous grades, enabling moisture specifications below 50 ppm for solid-state electrolyte research.
Market Restraints
- Hydrofluoric Acid Feedstock Volatility:HF pricing ties to fluorspar concentrate from Mexico and China, with export quota fluctuations transmitting directly to FeF3 production economics.
- Chinese Supply Concentration:Integrated fluoride processing clusters in Hunan and Zhejiang provinces control an estimated majority of technical-grade hexahydrate output, creating single-source vulnerability for non-battery applications.
- Hexafluorosilicic Acid Substitution:Water treatment municipalities in North America are pivoting to fluorosilicate salts for cost reasons, eroding volume demand for ferric fluoride solutions.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting battery material investments in Gujarat and Tamil Nadu, creating first-mover advantage for qualified FeF3 suppliers.
- Solid-State Battery Electrolytes:FeF3 as a lithium-ion conductive additive in sulfide and oxide solid electrolytes represents an unqualified application segment with pre-commercial offtake discussions active in Japan.
- Digital Chemical Marketplaces:B2B platforms specializing in specialty inorganics are disintermediating traditional distributor networks for R&D-scale orders, compressing customer acquisition costs for analytical-grade producers.
Industry Challenges
- Analytical Talent Scarcity:ICP-MS and ion chromatography specialists capable of certifying sub-ppm impurity profiles command premium compensation, constraining quality control expansion at mid-scale producers.
- REACH Registration Timelines:ECHA substance evaluation windows extending 18-24 months for fluoride salts are delaying market access for new entrants targeting European battery supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferric Fluoride Market |
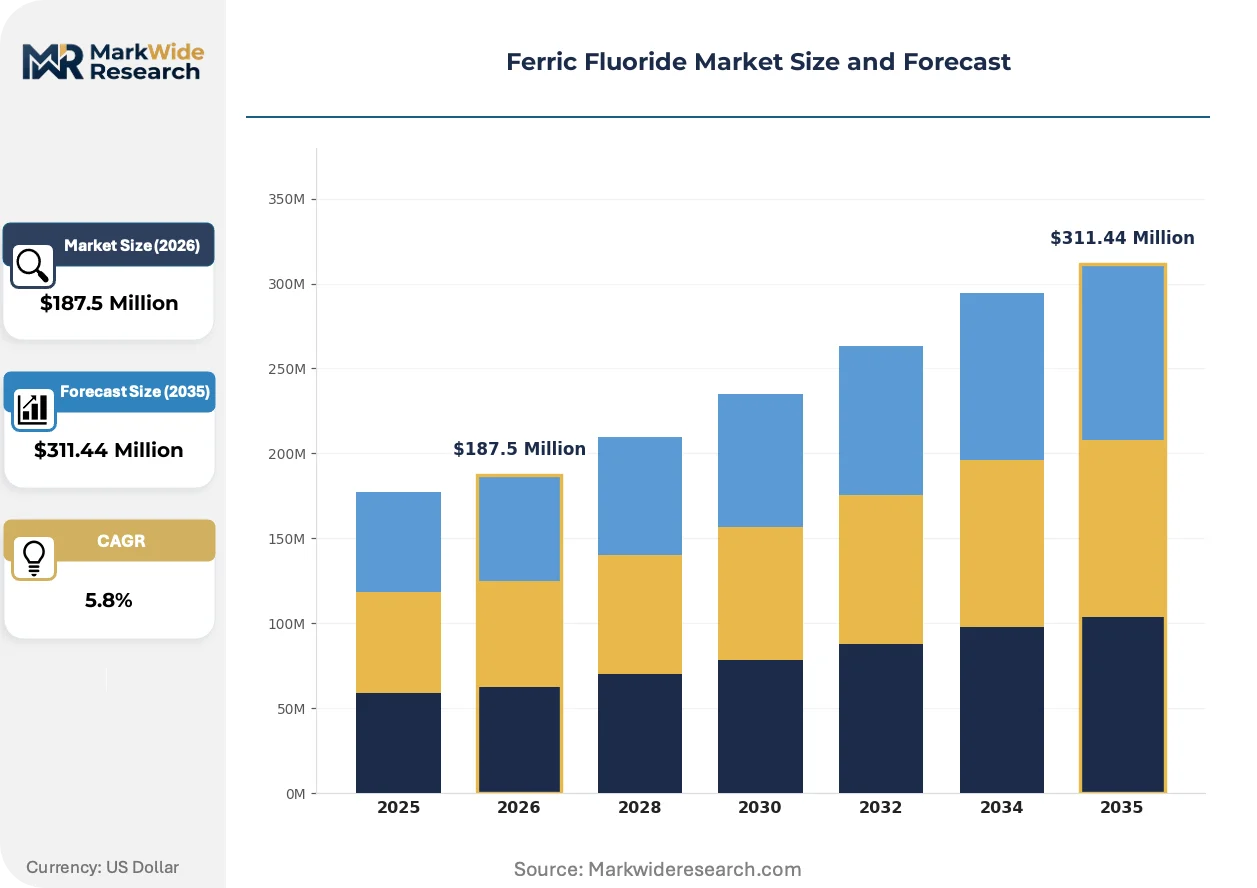
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $311.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Hexahydrate, Tetrahydrate, Solution End Use Industry: Electronics, Chemical Manufacturing, Metal Treatment, Water Treatment Application: Etching Agent, Catalyst, Flux, Corrosion Inhibitor Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Sigma-Aldrich (Merck), XI'AN FUNCTION MATERIAL GROUP CO., LTD, Advance Research Chemicals, Inc., Strem Chemicals, ESPI Metals, Alfa Aesar, American Elements, Intelligent Materials Pvt. Ltd., ThermoFisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferric Fluoride Market Emerging Trajectories
Process intensification and purity verification technologies are converging to reshape competitive differentiation, with automation and inline analytics displacing batch-wise quality control.
Gas-phase fluorination reactors utilizing elemental fluorine rather than HF are miniaturizing from pilot-scale to modular production units. Japanese specialty chemical producers are deploying these systems for aerospace-grade anhydrous FeF3, enabling lot-to-lot consistency that satisfies MIL-SPEC requirements. The technology is compressing qualification timelines for defense contractors while raising capital barriers for conventional aqueous processors.
REACH Annex XIV authorization requirements for persistent organic pollutants are tightening impurity thresholds for fluorinated process chemicals. The regulation forces FeF3 producers to certify absence of perfluorinated byproducts across the supply chain, with battery material applications facing the most stringent documentation burdens. German chemical distributors are responding by consolidating supplier panels to those with full ECHA registration dossiers.
Long-term offtake contracting is displacing spot purchasing for battery-grade material. Cathode producers in South Korea and Sweden are locking in three-to-five-year supply agreements with fixed pricing and volume flex provisions, replacing the quarterly tender processes that dominated technical-grade procurement. This shift concentrates purchasing power among cell manufacturers with gigafactory scale, squeezing margin for non-integrated FeF3 suppliers.
Ferric Fluoride Market Segmentation
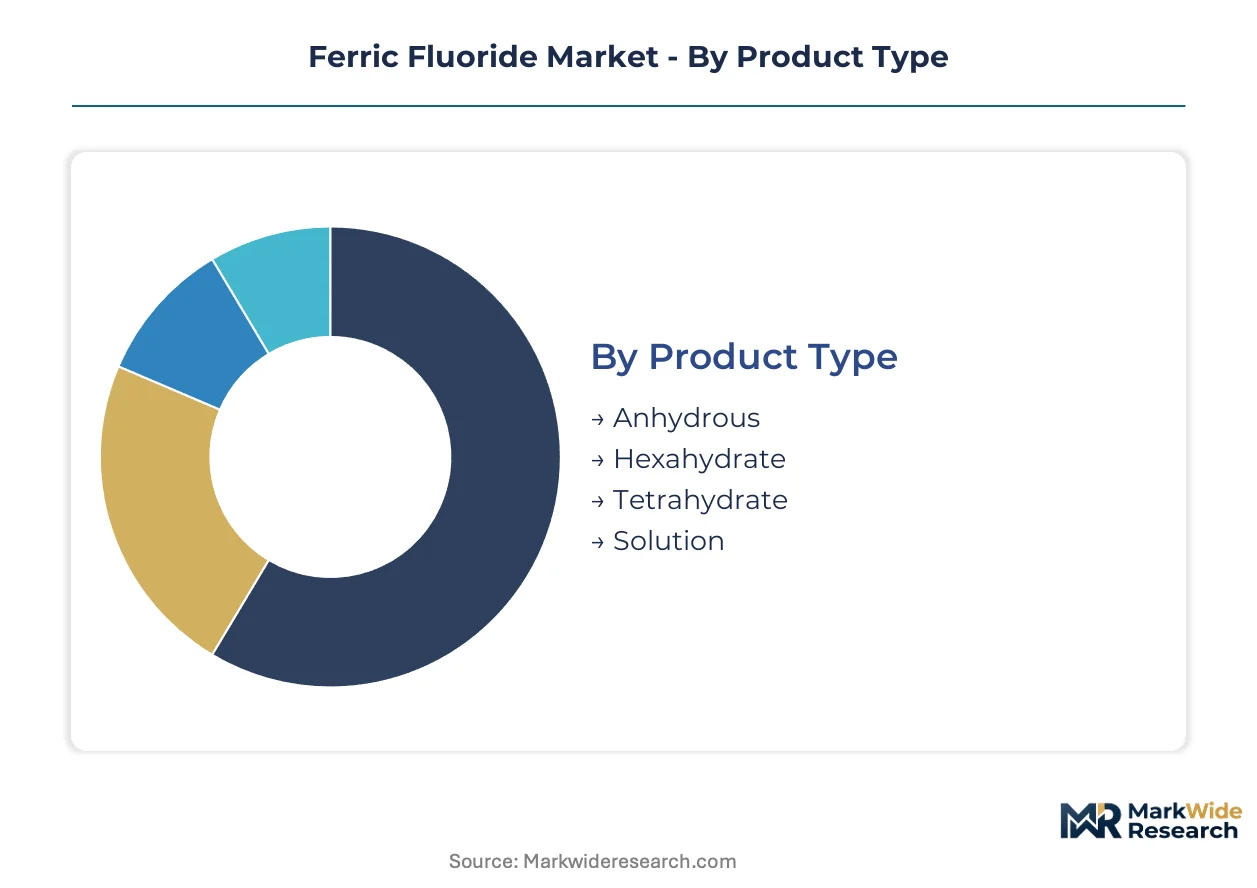
Segmentation in ferric fluoride reflects divergent purity requirements across battery materials, semiconductor fabrication, and industrial processing. Margin capture varies sharply between dehydration-intensive anhydrous grades and commodity hydrates.
Product Type:
Anhydrous formats command premium pricing due to energy-intensive production and stringent moisture thresholds for solid-state battery research.
- Anhydrous:Iron(III) fluoride in water-free crystalline form requires temperatures exceeding 300°C for dehydration and maintains sub-50 ppm moisture specifications. South Korean cathode producers specify this grade for lithium-ion conductive additives in sulfide electrolyte development. Direct fluorination routes are displacing aqueous processing to meet trace metal tolerances below 10 ppm.
- Hexahydrate:The hexahydrate variant (FeF3·6H2O) decomposes near 100°C and serves water treatment and metal surface preparation where technical specifications permit higher hydration. Chinese integrated processors in Hunan province dominate volume output for this grade, creating single-source vulnerability for non-battery applications.
- Tetrahydrate:Intermediate hydration state with niche demand in laboratory reagents and specialty catalyst preparation.
- Solution:Aqueous formulations compete on convenience for etching baths and wastewater treatment, though hexafluorosilicic acid substitution is eroding North American municipal demand.
The dominant share belongs to Anhydrous, while Hexahydrate is closing the gap fastest.
End Use Industry:
Application-specific purity tiers create distinct customer qualification barriers and contract structures across industrial segments.
- Electronics:Semiconductor foundries in Taiwan and South Korea deploy ultra-high-purity FeF3 for plasma etching of tungsten interconnects below 7 nm nodes. Advanced node fabrication requires sub-ppm metallic impurity profiles certified through ICP-MS protocols.
- Chemical Manufacturing:Catalytic applications in fluorination reactions and polymerization processes utilize technical-grade material with relaxed trace metal specifications.
- Metal Treatment:Surface preparation and flux applications in aerospace and automotive sectors demand consistent lot-to-lot chemistry for MIL-SPEC compliance.
- Water Treatment:Municipal fluoridation programs historically consumed solution-grade ferric fluoride, though cost-driven substitution toward fluorosilicate salts is compressing volume in North American markets.
Electronics captures the steepest expansion trajectory, while Water Treatment faces structural headwinds from alternative chemistries.
Application:
Functional performance requirements determine specification intensity and supplier qualification depth.
- Etching Agent:Plasma etching of tungsten and silicon nitride layers in semiconductor fabrication demands anhydrous grades with particle size control below 10 microns. Taiwan-based foundries are expanding capacity for sub-7 nm production, intensifying demand for certified high-purity material.
- Catalyst:Fluorination catalysts and Lewis acid applications in fine chemical synthesis tolerate broader hydration ranges and trace metal windows.
- Flux:Brazing and soldering flux formulations require controlled fluoride activity without aggressive hygroscopic behavior.
- Corrosion Inhibitor:Protective coatings and pickling inhibitors utilize solution and hydrate forms where film-forming properties outweigh purity metrics.
Etching Agent holds the largest revenue concentration, while Catalyst applications are expanding most quickly in pharmaceutical intermediate production.
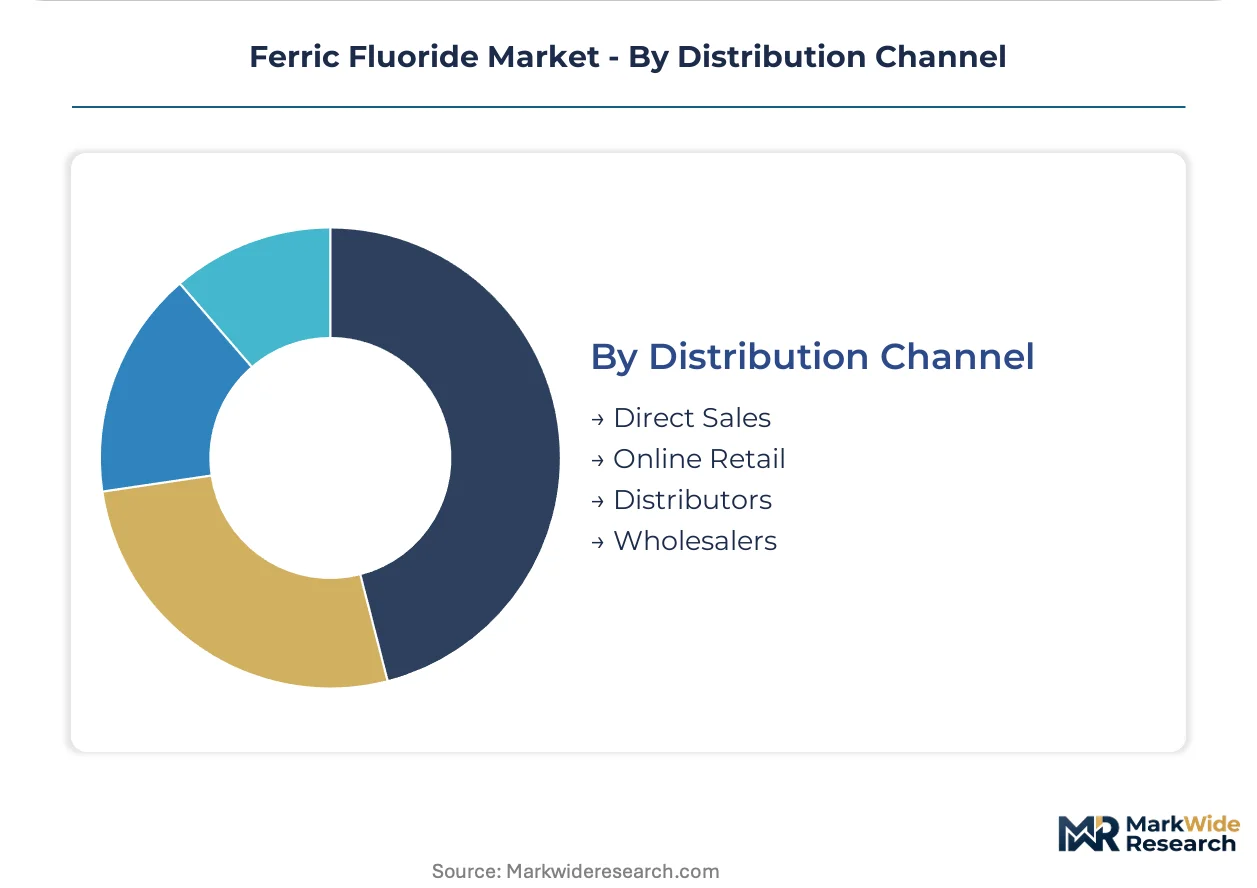
Distribution Channel:
Procurement patterns are shifting from spot purchasing toward structured contracting as battery material qualification timelines extend.
- Direct Sales:Cathode producers and semiconductor foundries negotiate multi-year offtake agreements with fixed pricing and volume flex provisions. South Korean and Swedish cell manufacturers concentrate purchasing power through gigafactory-scale procurement.
- Distributors:German chemical distributors are consolidating supplier panels to ECHA-registered producers to satisfy REACH Annex XIV documentation burdens for battery supply chains.
- Online Retail:B2B platforms specializing in specialty inorganics are disintermediating traditional networks for R&D-scale orders, compressing customer acquisition costs for analytical-grade producers.
- Wholesalers:Technical-grade hexahydrate moves through regional wholesalers serving water treatment and metal finishing SMEs.
Direct Sales dominates value capture, while Online Retail is gaining share fastest in laboratory and pilot-scale segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Battery-grade buyers in South Korea and Taiwan absorb premiums for sub-10 ppm purity, while water treatment operators in North America switch to fluorosilicate alternatives on marginal cost shifts.
China
Hunan and Zhejiang provinces house integrated fluoride processing clusters supplying hexahydrate for industrial applications. MIIT coordinates GB standard revisions that increasingly reference battery material specifications, tightening import windows for non-conforming material. Xiangtan city in Hunan province anchors technical-grade output, with local processors expanding direct fluorination capacity to qualify for cathode supply chains.
South Korea
Semiconductor foundries in Pyeongtaek and Yongin drive ultra-high-purity demand for sub-7 nm tungsten etching. The national semiconductor regulator enforces trace metal documentation aligned with advanced node roadmaps. Gwangju cluster cathode producers are locking in three-to-five-year offtake agreements with fixed pricing, replacing quarterly tender processes.
United States
EPA standards under the Toxic Substances Control Act impose graduated compliance burdens based on purity tier and exposure pathway. Aerospace and defense contractors in California and Texas specify MIL-SPEC anhydrous grades with lot-to-lot consistency below 10 ppm trace metals. Houston-area chemical processors face feedstock volatility from Mexican fluorspar concentrate fluctuations.
Germany
ECHA REACH registration mandates and Annex XIV authorization requirements tighten impurity thresholds for fluorinated process chemicals. Düsseldorf-based chemical distributors consolidate supplier panels to ECHA-registered producers to satisfy documentation burdens for battery supply chains. Bavarian specialty chemical producers deploy gas-phase fluorination systems for aerospace-grade material.
India
The PLI scheme for advanced chemistry cell manufacturing attracts battery material investments in Gujarat and Tamil Nadu. BIS certification requirements for specialty fluoride salts are converging with battery-grade specifications. Hazira industrial zone in Gujarat is emerging as a qualification site for first-mover FeF3 suppliers targeting gigafactory offtake.
Ferric Fluoride Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with analytical-grade specialists commanding premium positioning while integrated Chinese processors dominate volume tiers. The market structure concentrates around three strategic archetypes: laboratory and R&D channel suppliers leveraging certification heritage, domestic integrated processors with direct industrial offtake relationships, and custom synthesis specialists serving aerospace and defense tolerances. Dominant competitive moves include long-term offtake contracting with volume flex provisions and gas-phase fluorination technology licensing for anhydrous grade expansion.
Among laboratory and R&D channel suppliers, Sigma-Aldrich (Merck) and Strem Chemicals exemplify the premium archetype through analytical standards positioning. XI'AN FUNCTION MATERIAL GROUP CO., LTD anchors the integrated domestic processor tier with direct industrial relationships. American Elements occupies a position within the custom synthesis specialist segment where trace metal tolerances sit below 10 ppm for defense applications.
| Leading Market Players |
|---|
| Sigma-Aldrich (Merck) |
| XI'AN FUNCTION MATERIAL GROUP CO., LTD |
| Advance Research Chemicals, Inc. |
| Strem Chemicals |
| ESPI Metals |
| Alfa Aesar |
| American Elements |
| Intelligent Materials Pvt. Ltd. |
| ThermoFisher Scientific |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracting with volume flex provisions locks in supply access for South Korean cathode producers while anchoring price visibility against Mexican fluorspar concentrate volatility. This contract structure concentrates purchasing power among gigafactory-scale cell manufacturers and squeezes margin for non-integrated ferric fluoride suppliers serving spot markets.
Pricing Analysis
REACH registration mandates through ECHA dictate the pricing tier structure across European battery supply chains, forcing documentation investments that stratify pricing across certification-grade boundaries. Anhydrous grades command three-tier pricing structure across premium, standard, and economy levels based on moisture specifications and trace metal tolerances certified through ICP-MS protocols. Cost compression in technical-grade hexahydrate is intensifying because Chinese integrated processors in Hunan province dominate volume output. Water treatment municipalities in North America exhibit highest price sensitivity and pivot to fluorosilicate alternatives on marginal cost shifts, while semiconductor foundries in Taiwan absorb premiums for sub-10 ppm purity without volume elasticity.
Supply Chain Analysis
Mexican fluorspar concentrate export quotas underwrite feedstock volatility that transmits directly to ferric fluoride production economics in Houston-area chemical processors. Supply concentrates in China through integrated fluoride processing clusters in Hunan and Zhejiang provinces, with South Korean cathode producers and German specialty chemical firms drawing from Japanese gas-phase fluorination systems for aerospace-grade material. Hydrofluoric acid leaching routes and direct fluorination equipment constitute critical input dependencies. Single-source vulnerability runs through Chinese technical-grade hexahydrate dominance for non-battery applications. Distribution runs through German chemical distributors consolidating supplier panels to ECHA-registered producers and B2B platforms disintermediating traditional networks for R&D-scale orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification and analytical services attach to ferric fluoride supply at expanding margins, as ICP-MS and ion chromatography specialists capable of certifying sub-ppm impurity profiles command premium compensation that outpaces hardware margin growth.
For Market Incumbents: Secure multi-year offtake agreements with South Korean and Swedish cell manufacturers before REACH Annex XIV authorization timelines extend qualification windows for new entrants. Invest in gas-phase fluorination capacity to defend against aqueous route displacement, as direct fluorination advances are compressing qualification timelines for defense contractors. Backward integration into fluorspar concentrate sourcing mitigates Mexican export quota volatility that threatens Houston-area processor economics. For New Entrants and Emerging Players: Anchor in India's PLI scheme for advanced chemistry cell manufacturing, where BIS certification requirements are converging with battery-grade specifications and first-mover advantage remains open in Gujarat and Tamil Nadu. Target solid-state battery electrolyte research segments in Japan where FeF3 as lithium-ion conductive additive represents unqualified application space with pre-commercial offtake discussions active. Deploy digital chemical marketplace presence to compress customer acquisition costs for analytical-grade R&D orders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among analytical-grade producers serving laboratory and R&D channels through certification heritage and repeat purchase patterns. Over a multi-year window, gas-phase fluorination technology holders with ECHA registration dossiers present superior acquisition profiles than aqueous processors facing margin compression. Watch for Indian gigafactory qualification announcements as inflection indicators for regional supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Concentrate | Mexican export quota volatility threatens Houston-area processor feedstock security. |
| Gas-Phase Fluorination Capacity Expansion | Japanese specialty chemical producers deploy modular systems for MIL-SPEC anhydrous grades. |
| ECHA REACH Registration Dossier Completion | German distributors consolidate supplier panels to registered producers for battery supply chains. |
| Long-Term Offtake Agreement Structuring | South Korean cathode producers lock in three-to-five-year contracts replacing quarterly tenders. |
| Digital Marketplace Channel Development | B2B platforms disintermediate traditional distributor networks for R&D-scale ferric fluoride orders. |
Methodological Framework
A spread of perspectives from plant managers at fluoride processing facilities, procurement leads at cathode material producers, distribution channel partners in specialty inorganics, and technical R&D directors at semiconductor foundries converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, SEC filings, chemical industry association reports, and ECHA registration databases. Bottom-up volume modeling triangulated against top-down value estimates across grade tier, end-use industry, and regional production hub segmentation.
Product type, end-use industry, application function, and distribution channel dimensions structured the analytical framework across the projection horizon. CAGRs derived from regression analysis of historical price-volume relationships and forward qualification timeline assumptions. Forecast inputs incorporated solid-state battery electrolyte research progression, Indian PLI scheme implementation pace, and REACH Annex XIV authorization window extensions.
Decision-makers should treat outputs as directional under assumptions of stable fluorspar concentrate trade flows and continued semiconductor node advancement; material deviation in Mexican export policy or battery chemistry substitution would warrant model refresh. Practitioners should keep alternative scenarios live as solid-state electrolyte commercialization timelines and EU Battery Regulation recycled content thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Acid Anhydrides Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
Global Fluorosilicic Acid Market
Chemicals
Methanol Market
Chemicals
Global N-Butanol Market
Chemicals
1-Methylimidazole Market
Chemicals
Hexamine Market
Chemicals
Japan Methanol Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Flatting Agents Market
Chemicals
Catechol Market
Chemicals
Para Cresol Market
Chemicals
Triethylaluminum Market