

ePTFE Electronic Film Market Size, Share, and Industry Trends Forecast 2026-2036
ePTFE Electronic Film Market Insights
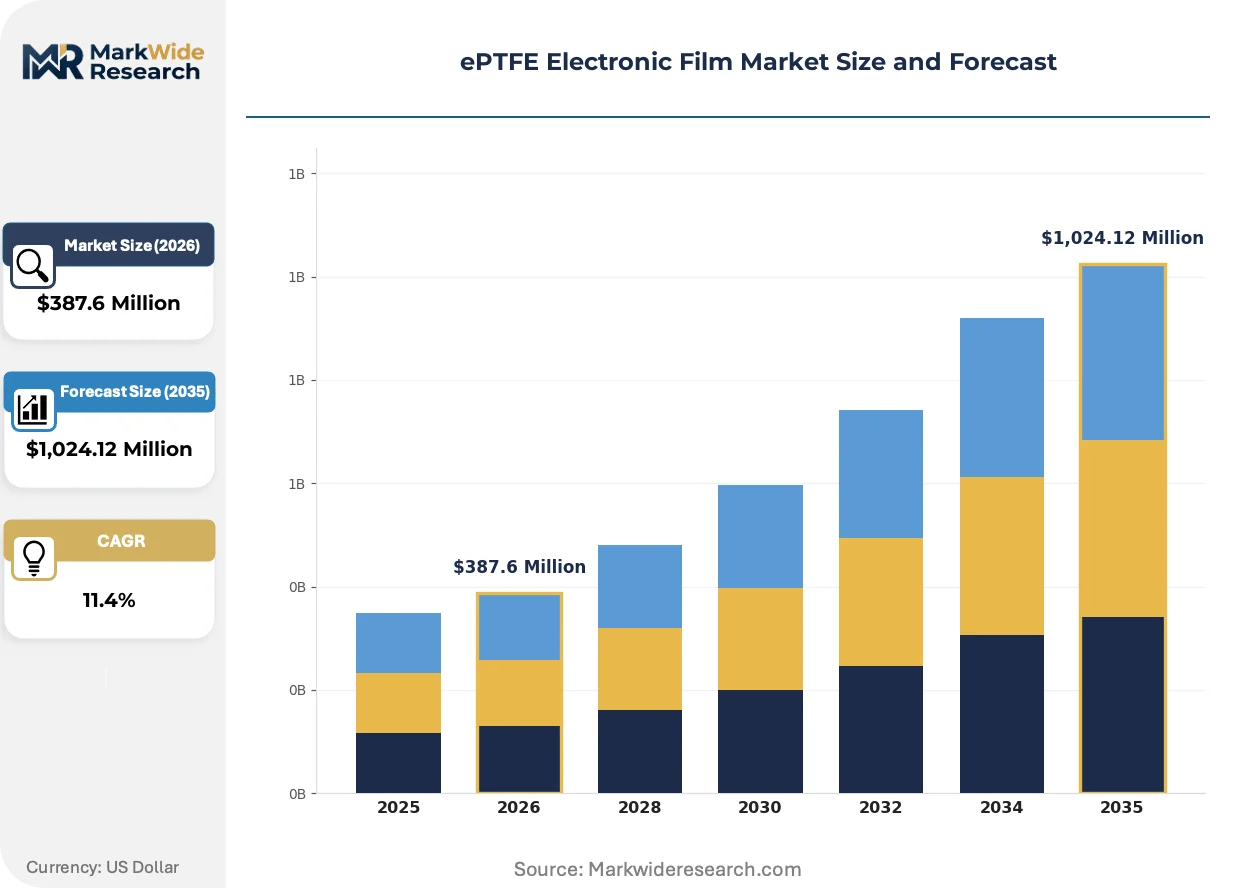
The ePTFE electronic film market is decoupling into two distinct tiers: aerospace-grade specifications commanding premium positioning versus commodity-grade supply for mass-market consumer electronics. W. L. Gore & Associates leverages its vertically integrated fluoropolymer operations to sustain dominance in high-reliability defense and aerospace applications. Saint-Gobain anchors its competitive stance through specialized coating capabilities that differentiate performance in harsh-environment sensor deployments.
Expanded polytetrafluoroethylene electronic film consists of a microporous membrane structure manufactured through mechanical stretching of PTFE resin, yielding pore sizes ranging from 0.1 to 10 micrometers while maintaining dielectric constants below 2.0 for high-frequency signal integrity. This material serves primarily as a substrate and protective barrier in flexible printed circuit boards, display assemblies, and electromagnetic shielding applications where thermal stability and chemical resistance prove critical. Conductive films and functional films represent the most dynamic product categories, with functional films capturing expanding margin pools as surface modification techniques enable multi-layer lamination for advanced sensor architectures. Flexible circuits applications lead volume uptake, though printed electronics emerges as the fastest-growing application segment as micro-patterning technologies mature.
EPA regulations in the United States restrict per- and polyfluoroalkyl substance emissions from fluoropolymer manufacturing, compelling producers to invest in abatement systems or alternative chemistries. REACH and RoHS frameworks in Europe mandate material traceability and restrict hazardous substances in electronic components, directly influencing formulation choices and supplier qualification protocols. The EU AI Act and emerging CSRD disclosure requirements will further tighten supply chain documentation standards for electronics materials. Stakeholders must monitor regulatory divergence between jurisdictions while evaluating captive production versus outsourced supply strategies for critical film grades.
Market Dynamics
Fluoropolymer purity mandates from REACH and EPA are bifurcating supplier qualification tiers, forcing film producers to choose between premium aerospace certification or commodity consumer electronics supply chains. This regulatory wedge is accelerating capital flight from mid-tier producers unable to fund dual-track compliance infrastructure.
Growth Catalysts
- Flexible Circuit Substrate Demand:Consumer electronics manufacturers in Taiwan and South Korea are expanding procurement of microporous membranes for foldable display interconnects, driven by device miniaturization requirements.
- REACH Compliance Deadlines:The EU Green Deal's material traceability mandates are disqualifying uncertified suppliers from automotive sensor supply chains, concentrating volume among qualified producers.
- Electromagnetic Shielding Specifications:5G base station deployments are specifying ePTFE dielectric barriers for signal integrity in high-frequency transmission assemblies.
Market Restraints
- PTFE Resin Supply Concentration:Virgin resin production clusters in China and Japan create input cost volatility when export licensing tightens.
- EPA Emission Abatement Costs:Per- and polyfluoroalkyl substance capture systems add capital intensity to US-based manufacturing without offsetting revenue premiums.
- Alternative Dielectric Substitution:Liquid crystal polymer films are displacing ePTFE in cost-sensitive flexible circuit applications below 6 GHz operating frequencies.
Strategic Opportunities
- Printed Electronics Micro-Patterning:Advanced sensor architectures in medical diagnostics are creating specification pull for multi-layer functional film laminations.
- South Korean Defense Procurement:Indigenous aerospace programs are qualifying domestic ePTFE sources for satellite and UAV applications previously supplied by US producers.
- CSRD Supply Chain Disclosure:The EU's Corporate Sustainability Reporting Directive is creating first-mover advantage for producers with documented fluoropolymer provenance systems.
Industry Challenges
- Cleanroom Fabrication Skill Scarcity:Micropore uniformity control requires specialized technicians trained in mechanical stretching process optimization.
- Aerospace Certification Timelines:FAA and EASA qualification cycles for defense-grade films extend 18-24 months, locking working capital in inventory.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ePTFE Electronic Film Market Trends and Innovations
Laser-assisted surface modification and AI-driven pore structure modeling are compressing development cycles for application-specific film grades. These capabilities are redrawing competitive boundaries between integrated resin-to-film producers and specialty coating houses.
Plasma-enhanced chemical vapor deposition is automating the functionalization of ePTFE membranes with conductive or hydrophilic surface layers. Sensor manufacturers in Germany and Japan are adopting these treated films for harsh-environment deployments at triple the pace of standard grades. The technology is automating what previously required batch chemical baths, collapsing coating cycle times from hours to minutes.
The EU AI Act's risk classification framework is extending to electronic component supply chains, mandating algorithmic traceability for materials used in high-risk AI hardware. European automotive OEMs are now requiring ePTFE suppliers to document machine-learning-assisted quality control parameters. This regulatory layer is compressing supplier qualification windows while favoring producers with digitized manufacturing execution systems.
Defense contractors are consolidating vendor bases around single-source agreements with qualification heritage, displacing the multi-source procurement norms of consumer electronics. This concentration is visible in Taiwan's printed circuit board clusters, where military-specification films now command dedicated production lines separate from commercial output. The shift is forcing mid-tier producers to choose certification investments or exit the premium tier entirely.
ePTFE Electronic Film Market Segmentation
ePTFE electronic film specifications diverge sharply across end-use environments, from aerospace-grade dielectric stability to commodity substrates for foldable smartphones. Understanding these segment boundaries reveals where margin pools concentrate and where qualification barriers protect incumbent positions.
Product Type:
Technical specifications around conductivity, transparency, and surface functionality define the primary product architecture in this market.
- Conductive Films:Metalized or intrinsically conductive surface layers enable electromagnetic interference shielding in 5G base station assemblies. South Korean telecommunications infrastructure deployments specify these grades for signal integrity at millimeter-wave frequencies.
- Functional Films:Multi-layer surface modifications—hydrophilic, oleophobic, or piezoelectric—support advanced sensor architectures in medical diagnostics. German automotive OEMs are qualifying these for battery management system membranes under ECHA substance restrictions.
- Insulative Films:Pure dielectric barriers with dielectric constants below 2.0 isolate high-voltage traces in aerospace power distribution systems.
- Protective Films:Abrasion-resistant microporous layers shield flexible circuit traces from mechanical damage during device assembly.
- Transparent Films:Optical-grade ePTFE with controlled haze values serves display stack bonding in foldable device prototypes.
Functional films lead on scale; conductive films lead on momentum.
Application:
End-use environments impose distinct thermal, mechanical, and chemical performance requirements that filter supplier eligibility.
- Flexible Circuits:Substrate membranes for dynamic bending applications in foldable smartphones and wearable devices. Taiwan's printed circuit board clusters consume the majority volume, with procurement expanding for next-generation display interconnects.
- Printed Electronics:Micro-patterned ePTFE enables roll-to-roll manufacturing of disposable biosensors and RFID antennas. Japanese pharmaceutical packaging firms are piloting these for intelligent drug delivery tracking systems.
- Display Panels:Optical bonding layers and moisture barriers for OLED and micro-LED assemblies.
- Sensors:Harsh-environment membranes for automotive exhaust gas and industrial process monitoring.
- Solar Panels:Backsheet substrates with UV stability for concentrated photovoltaic installations.
Flexible circuits dominate absolute volume; printed electronics shows the steepest expansion trajectory.
Technology:
Process capabilities separate integrated producers from coating specialists, with automation investments compressing cycle times for functionalized grades.
- Surface Modification:Plasma-enhanced chemical vapor deposition functionalizes membranes with conductive or hydrophilic layers in minutes rather than hours. German sensor manufacturers are adopting these treated films at triple the pace of standard grades.
- Micro-Patterning:Laser-assisted and photolithographic techniques create sub-micron feature resolution for antenna and electrode geometries. South Korean research institutes are advancing these methods for satellite communication hardware.
- Manufacturing Processes:Mechanical stretching protocols control pore size distribution from 0.1 to 10 micrometers.
- Coating Techniques:Roll-to-roll sputtering and solution deposition apply functional surface layers.
- Lamination Methods:Adhesive-free thermal bonding creates multi-layer stacks for complex device architectures.
Surface modification commands premium pricing; micro-patterning is gaining share fastest.
End User:
Procurement sophistication varies from commodity spot purchasing to multi-year qualification programs with dedicated production lines.
- Consumer Electronics Manufacturers:High-volume, price-sensitive procurement for smartphones, tablets, and wearables. South Korean and Taiwanese device assemblers dominate this tier, with specifications tightening around foldable display reliability.
- Defense Contractors:Single-source agreements with 18-24 month FAA and EASA qualification cycles lock working capital in inventory. US prime contractors are consolidating vendor bases around heritage suppliers with aerospace certification.
- Aerospace Suppliers:Satellite and UAV applications require outgassing-tested films for vacuum environments.
- Telecommunications Firms:5G infrastructure deployments specify dielectric barriers for base station signal integrity.
- Research Institutes:Small-lot procurement for prototype validation and process development.
Consumer electronics manufacturers drive aggregate volume; defense contractors anchor margin stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's defense procurement outpaces Taiwan's commercial expansion, yet both East Asian electronics clusters drive contrasting demand profiles for ePTFE specifications. Regulatory divergence between EPA emission mandates and REACH substance restrictions fragments supplier qualification pathways across major manufacturing jurisdictions.
United States
Defense contractors consolidate vendor bases around single-source agreements with FAA qualification heritage, locking working capital in 18-24 month certification cycles. EPA regulations restrict per- and polyfluoroalkyl substance emissions from fluoropolymer manufacturing, compelling producers to invest in abatement systems. Aerospace manufacturing concentrates in California and Texas corridors, where satellite and UAV programs specify outgassing-tested films for vacuum environments.
Germany
Automotive OEMs qualify functional films for battery management system membranes under ECHA substance restrictions. The EU AI Act and CSRD disclosure requirements tighten supply chain documentation standards for electronics materials. Sensor manufacturers in Bavaria and Baden-Württemberg adopt plasma-enhanced surface modification films at triple the pace of standard grades for harsh-environment deployments.
South Korea
Indigenous aerospace programs qualify domestic ePTFE sources for satellite and UAV applications previously supplied by US producers. MFDS and national defense procurement standards accelerate localization timelines. Seoul Capital Area electronics clusters expand procurement of microporous membranes for foldable display interconnects, driven by device miniaturization requirements.
Japan
Pharmaceutical packaging firms pilot micro-patterned ePTFE for intelligent drug delivery tracking systems under METI advanced manufacturing initiatives. JIS standards and material traceability protocols align with REACH-equivalent substance restrictions. Chubu and Kansai industrial corridors host roll-to-roll manufacturing pilots for disposable biosensors and RFID antennas.
Taiwan
Printed circuit board clusters consume majority volume for flexible circuit substrates, with military-specification films commanding dedicated production lines separate from commercial output. Device assemblers tighten specifications around foldable display reliability for next-generation smartphones. Hsinchu Science Park anchors procurement concentration for high-frequency dielectric barriers in 5G base station assemblies.
ePTFE Electronic Film Market Competitive Landscape
Top-tier vendors anchor aerospace-grade specifications with premium positioning, while commodity-grade producers serve mass-market consumer electronics with price-sensitive supply chains. The vendor base stratifies across three archetypes: integrated resin-to-film producers controlling upstream fluoropolymer supply, specialty coating houses leveraging surface modification capabilities, and regional fabricators capturing localized defense procurement. Competitive moves concentrate on strategic partnerships for technology licensing and capacity expansion for functional film grades.
Among integrated fluoropolymer operators, W. L. Gore & Associates exemplifies the heritage-anchored archetype with vertically controlled resin operations, while Saint-Gobain S.A. occupies a position within specialized coating capabilities for harsh-environment sensor deployments. Nitto Denko Corporation represents the Asia-Pacific fabrication tier with Japanese Co., Ltd. structure serving regional electronics clusters.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| 3M |
| Saint-Gobain |
| Nitto Denko Corporation |
| Rogers Corporation |
| AGC |
| Daikin Industries |
| The Chemours Company |
| Chukoh Chemical Industries |
| Others |
Pricing and Supply Chain Analysis
Cleanroom fabrication technicians concentrated in Taiwan's Hsinchu Science Park and South Korea's Seoul Capital Area command wage premiums that widen spreads between aerospace-grade and commodity-grade ePTFE film pricing tiers. Labor-cost differentials between these specialized workforce pools and general manufacturing regions amplify margin compression in standard consumer electronics supply chains while insulating premium defense-grade producers.
Pricing Analysis
Coating service unbundling from base film supply separates integrated producers from specialty houses. Three-tier pricing structure across aerospace-certified, automotive-qualified, and consumer-grade levels reflects FAA/EASA certification investment recovery timelines. Price differentiation centers on surface modification complexity and dielectric performance guarantees. Cost compression in consumer electronics tiers intensifies as liquid crystal polymer films gain share below 6 GHz applications. Defense contractors exhibit lowest price sensitivity due to single-source qualification lock-in.
Supply Chain Analysis
Freight cost volatility for fluoropolymer resin shipments between China, Japan, and processing facilities in Taiwan and South Korea amplifies input cost uncertainty. Virgin PTFE resin production clusters in China and Japan feed mechanical stretching operations across East Asian electronics manufacturing corridors. Supply chain risk concentrates in export licensing volatility for fluoropolymer precursors. Distribution runs through qualified supplier programs at tier-one flexible circuit board assemblers with dedicated line segregation for military-specification films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in functional film grades where surface modification capabilities command premium positioning. Plasma-enhanced chemical vapor deposition automation compresses coating cycle economics while medical diagnostics and automotive sensor demand accelerates.
For Market Incumbents: Anticipate displacement pressure from South Korean domestic qualification programs for satellite and UAV applications. Lock in aerospace certification heritage through accelerated FAA/EASA renewal investments. Secure captive resin supply through backward integration into fluoropolymer precursor operations or long-term offtake agreements with Japanese and Chinese virgin resin producers. For New Entrants and Emerging Players: Printed electronics micro-patterning partnerships with Japanese pharmaceutical packaging firms and German sensor manufacturers offer white-space entry points. Target medical diagnostics functional film laminations where qualification timelines remain shorter than defense-grade cycles. Pursue technology licensing arrangements with plasma-enhanced chemical vapor deposition equipment suppliers to bypass multi-year process development. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing fluoropolymer operations are the most active acquirer in this space, seeking coating capability bolt-ons. Five-to-ten year viability hinges on REACH and EPA compliance infrastructure amortization across dual certification tracks. Monitor EU AI Act supply chain disclosure mandates as inflection signal for first-mover advantage in documented provenance systems.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Enhanced CVD Capacity Expansion | Automates functionalization for German automotive sensor manufacturers, collapsing cycle times from hours to minutes. |
| Backward Integration into Virgin Resin | Secures fluoropolymer precursor supply against Chinese and Japanese export licensing volatility. |
| Aerospace Certification Renewal Investment | Preserves defense contractor single-source agreements with 18-24 month FAA/EASA qualification heritage. |
| Medical Diagnostics Partnership Program | Captures functional film margin pools in multi-layer laminations for disposable biosensor architectures. |
| CSRD-Compliant Provenance System | Creates first-mover advantage under EU Corporate Sustainability Reporting Directive disclosure requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from flexible circuit board procurement managers at Taiwanese device assemblers, cleanroom fabrication technicians in South Korean electronics clusters, fluoropolymer resin procurement leads at Japanese chemical producers, and regulatory affairs specialists navigating REACH and EPA compliance frameworks. Secondary validation drew from customs trade data for ePTFE film shipments, SEC filings of listed fluoropolymer producers, ECHA substance restriction updates, and FAA/EASA certification databases. Bottom-up volume builds across product grades reconciled against top-down market sizing through iterative triangulation.
Segment-weighting approaches applied differential growth assumptions across conductive, functional, insulative, protective, and transparent film categories. Application-level modeling incorporated flexible circuit, printed electronics, display panel, sensor, and solar panel end-use trajectories. Technology dimensions captured surface modification, micro-patterning, manufacturing process, coating technique, and lamination method penetration rates. CAGRs derived from regression analysis against electronics manufacturing capex cycles and defense procurement authorization patterns. Forecast inputs included foldable smartphone display adoption curves and 5G base station deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluoropolymer resin supply disruptions, alternative dielectric substitution rates, and regulatory divergence between EPA emission mandates and REACH substance restrictions. Forecasts reflect documented assumptions about qualification timeline stability and workforce availability in specialized cleanroom fabrication. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.