
 Apple Powder Market | 2026-2036
Apple Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Powder Market Analysis
Functional beverage developers is redrawing procurement patterns in the apple powder space, displacing traditional bakery buyers as the primary volume anchor. Tree Top leverages its Pacific Northwest apple supply base to sustain year-round powder production. FutureCeuticals Inc differentiates through polyphenol-standardized extracts for nutraceutical clients. HERBAFOOD INGREDIENTS GmbH anchors European supply with spray-drying capacity near German orchard clusters.
Apple powder consists of dehydrated apple solids, typically produced through spray-drying or freeze-drying to achieve moisture levels below five percent and preserve native fiber, pectin, and antioxidant compounds. The material functions as a natural flavoring, colorant, and functional ingredient across formulated foods, supplements, and cosmetic applications. Organic apple powder commands premium positioning as clean-label formulations displace conventional alternatives in European and North American retail channels. Spray-dried apple powder dominates manufacturing scale due to lower unit costs, though freeze-dried variants capture margin pools in high-end nutraceutical and cosmetic segments where volatile retention justifies price premiums.
FDA food additive regulations and USDA organic certification requirements shape product standards and market access for U.S.-origin apple powder, while EFSA novel food assessments and EU organic labeling rules govern European commercialization pathways. The EU Green Deal agricultural sustainability targets are pressuring processors to document carbon footprint across drying operations and orchard sourcing. Stakeholders must monitor evolving polyphenol health claim substantiation requirements, as EFSA and FDA divergence on bioactive ingredient marketing will determine which product grades retain pricing power in premium channels.
Market Dynamics
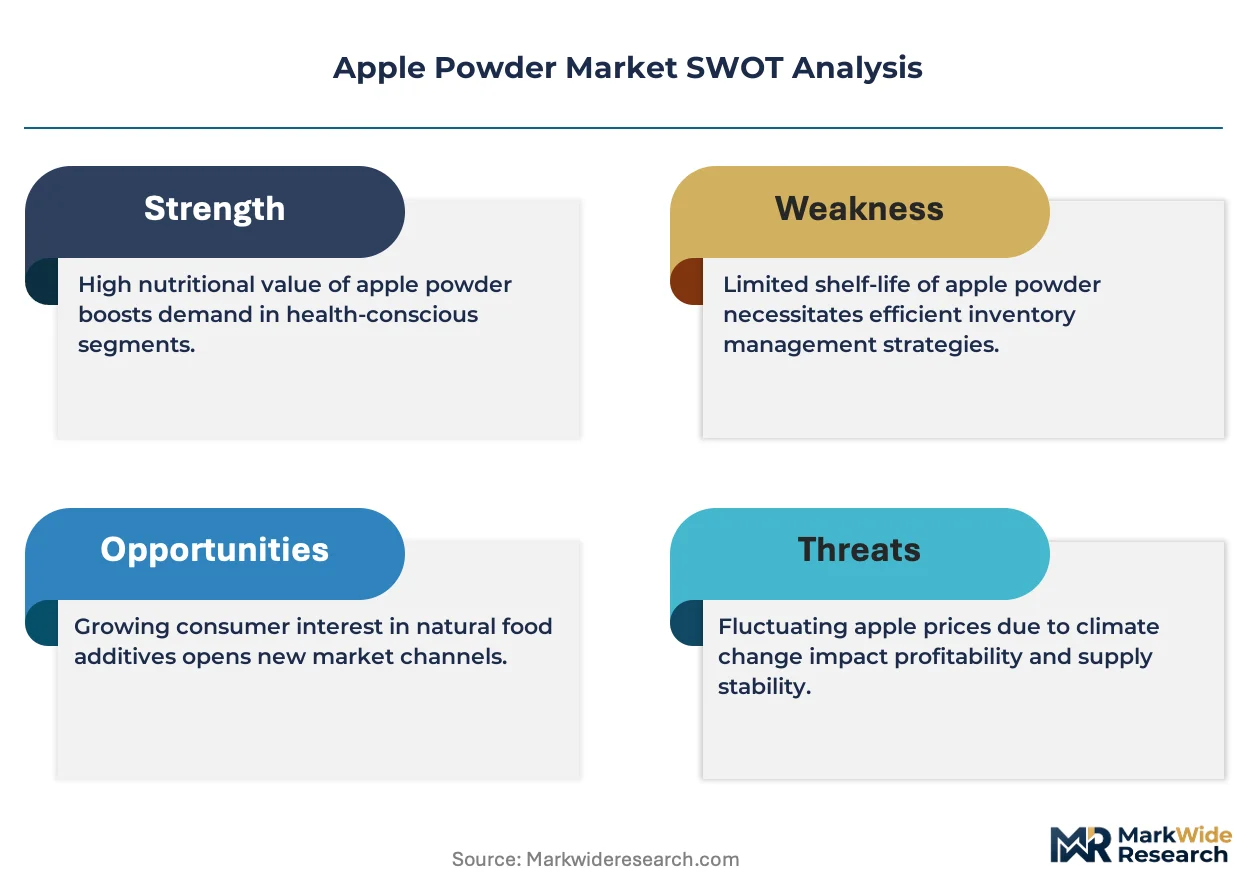
Clean-label mandates from EFSA and FDA are compressing additive-tolerant supply chains while concentrating procurement around single-ingredient, polyphenol-standardized apple powders for nutraceutical and functional food formulators.
Growth Catalysts
- EU Green Deal agricultural sustainability targets:Orchard processors documenting carbon footprints across drying operations unlock preferential access to German and French bakery chains seeking Scope 3 reductions.
- Functional beverage formulators:Sports and wellness drink developers in the United States are displacing traditional bakery buyers as the primary volume anchor for high-solids apple powder.
- Freeze-drying technology maturation:Volatile retention capabilities in pectin and antioxidant compounds justify price premiums in cosmetic and premium nutraceutical segments.
Market Restraints
- Pacific Northwest supply concentration:Year-round powder production depends on a narrow orchard belt vulnerable to climate volatility and labor availability constraints.
- Input cost volatility in natural gas:Spray-drying operations face margin compression when energy prices spike, disproportionately affecting standard-grade powder economics.
- Substitution threat from pomegranate and acerola powders:Competing polyphenol sources capture clean-label positioning with higher antioxidant density per serving.
Strategic Opportunities
- Underpenetrated Indian functional food sector:FSSAI clean-label guidelines are creating first-mover advantages for certified organic apple powder entrants before local supply chains mature.
- Regulatory tailwind from USDA organic certification expansion:Streamlined approval pathways for imported organic powders reduce time-to-shelf for Central European processors.
- Cosmetic application convergence:Anti-aging serum formulators combining apple-derived polyphenols with hyaluronic acid delivery systems open margin pools above food-grade pricing.
Industry Challenges
- Polyphenol standardization skill gap:Analytical chemists capable of validating batch-to-batch bioactive consistency command salaries that mid-tier processors struggle to match.
- Dual certification timeline friction:Simultaneous USDA organic and EU organic label acquisition requires 18-24 month documentation cycles that freeze working capital.
- Legacy spray-drying asset retrofit complexity:Existing facilities face technical barriers integrating carbon capture documentation systems demanded by EFSA supply chain audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Powder Market |
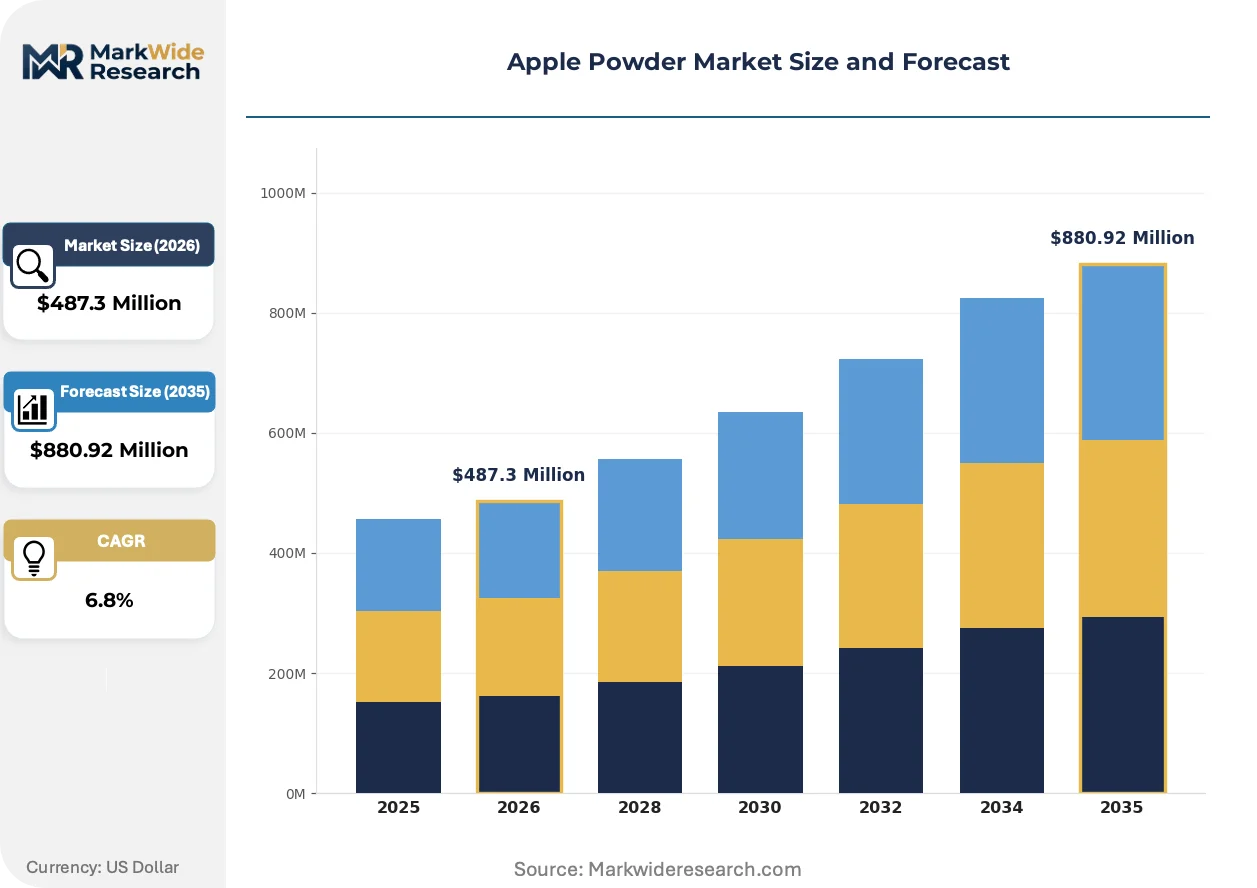
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Apple Powder, Conventional Apple Powder, Freeze-Dried Apple Powder, Spray-Dried Apple Powder Packaging Type: Bulk Packaging, Retail Packaging, Sachets, Jars End Use: Food & Beverages, Nutraceuticals, Bakery Products, Cosmetics Sales Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Naturex, Mayer Brothers, Tree Top, FutureCeuticals Inc, New Directions Aromatics Inc, Instantia, Z Natural Foods LLC, Kerry Group, HERBAFOOD INGREDIENTS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Powder Market Emerging Trajectories
Processing technology and procurement logic are diverging sharply between mass-market spray-dried supply and precision freeze-dried segments serving bioactive-conscious buyers.
Spray-drying equipment with integrated real-time moisture sensors is miniaturizing quality control infrastructure for mid-tier processors. German ingredient technology vendors are deploying these systems to orchard-adjacent facilities in Baden-Württemberg. The capital compression is enabling regional processors to challenge centralized drying conglomerates on lead time and custom specification flexibility.
EFSA novel food assessments are tightening substantiation requirements for polyphenol health claims in dietary supplements. Manufacturers must now submit clinical trial data linking specific apple powder grades to measurable antioxidant biomarkers. Premium nutraceutical suppliers with existing bioactive libraries are accelerating dossier preparation while commodity-grade producers retreat to food-flavoring positioning.
Buyer concentration among functional beverage developers is shortening contract cycles from annual to quarterly terms. Direct procurement relationships between CPG brand innovation teams and orchard processors are displacing traditional ingredient distributor networks. The disintermediation is most visible in California and Oregon, where beverage startups source traceable Pacific Northwest apple powder through vertically integrated supplier portals.
Apple Powder Market Segmentation
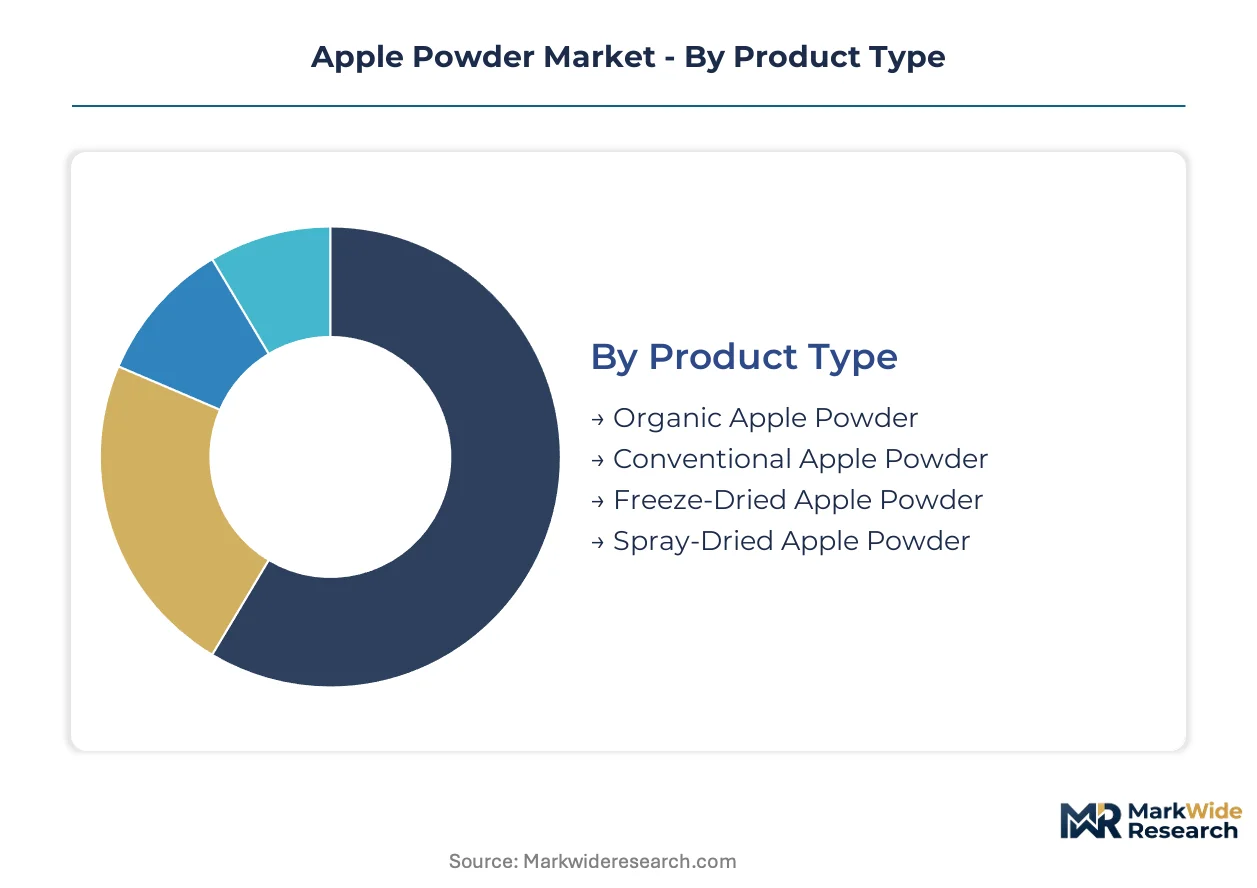
Apple powder segmentation reveals divergent supply chain configurations across product grades and procurement channels. Clean-label mandates compress conventional segments while polyphenol-standardized grades capture premium positioning in nutraceutical formulations.
Product Type:
Domestic consumption concentrates on spray-dried and conventional grades in Germany and the United States, while freeze-dried and organic variants flow disproportionately toward export-led nutraceutical and cosmetic channels serving Japanese and South Korean formulators.
- Spray-Dried Apple Powder:Produced through atomization and hot-air dehydration to achieve sub-five percent moisture with preserved pectin and fiber matrices. German bakery chains and U.S. functional beverage developers anchor procurement volumes, though EFSA carbon-footprint documentation requirements now filter supplier qualification.
- Freeze-Dried Apple Powder:Sublimation-based dehydration retains volatile antioxidant compounds and native flavor profiles. Cosmetic serum formulators in Japan and premium nutraceutical buyers in Switzerland absorb output at price multiples above food-grade alternatives, with batch-to-batch polyphenol validation now mandatory for health claim substantiation.
- Organic Apple Powder:Orchard sourcing meets USDA and EU organic certification with eighteen-to-twenty-four-month documentation cycles. Demand clusters in North American clean-label retail and European functional food channels.
- Conventional Apple Powder:Standard orchard sourcing without organic certification. Price-sensitive bakery and confectionery applications in Central Europe absorb the majority of volume.
Spray-dried apple powder commands the established base. The steepest expansion runs through freeze-dried apple powder.
Packaging Type:
Volume scale and margin structure diverge sharply: bulk formats serve industrial procurement with quarterly contract cycles, while retail-facing formats capture shelf-price multiples through supermarket and direct-to-consumer channels.
- Bulk Packaging:Industrial totes and drums exceeding twenty-kilogram net weight serve bakery and beverage manufacturing facilities. German ingredient processors and Pacific Northwest suppliers dominate this channel with integrated logistics.
- Retail Packaging:Consumer-facing pouches and canisters positioned in supermarket health food aisles. Clean-label branding and organic certification badges drive shelf placement in U.S. and French retail.
- Sachets:Single-serve units targeting on-the-go functional beverage preparation. Wellness-focused direct-to-consumer brands in California and New York deploy subscription models around this format.
- Jars:Reusable containers for home baking and smoothie additive use. European specialty stores and online retail channels concentrate distribution.
Bulk packaging commands the established base. The steepest expansion runs through sachets.
End Use:
Application-driven procurement logic separates commodity-grade flavoring demand from bioactive-conscious formulation requirements, with regulatory divergence between EFSA and FDA shaping grade specifications.
- Nutraceuticals:Polyphenol-standardized extracts for dietary supplement capsules and tablets. EFSA novel food assessments and FDA substantiation requirements govern health claim permissibility, with clinical trial dossiers now required for antioxidant positioning.
- Food & Beverages:Natural flavoring and colorant deployment across formulated drinks, confectionery, and prepared foods. Functional beverage developers in the United States displace traditional bakery buyers as volume anchors.
- Bakery Products:Moisture retention and natural sweetening in bread, pastry, and snack formulations. German and French industrial bakeries sustain demand through clean-label reformulation mandates.
- Cosmetics:Anti-aging serum and mask applications combining apple-derived polyphenols with hyaluronic acid delivery systems. Japanese and South Korean formulators drive premium pricing above food-grade alternatives.
Food & beverages commands the established base. The steepest expansion runs through nutraceuticals.
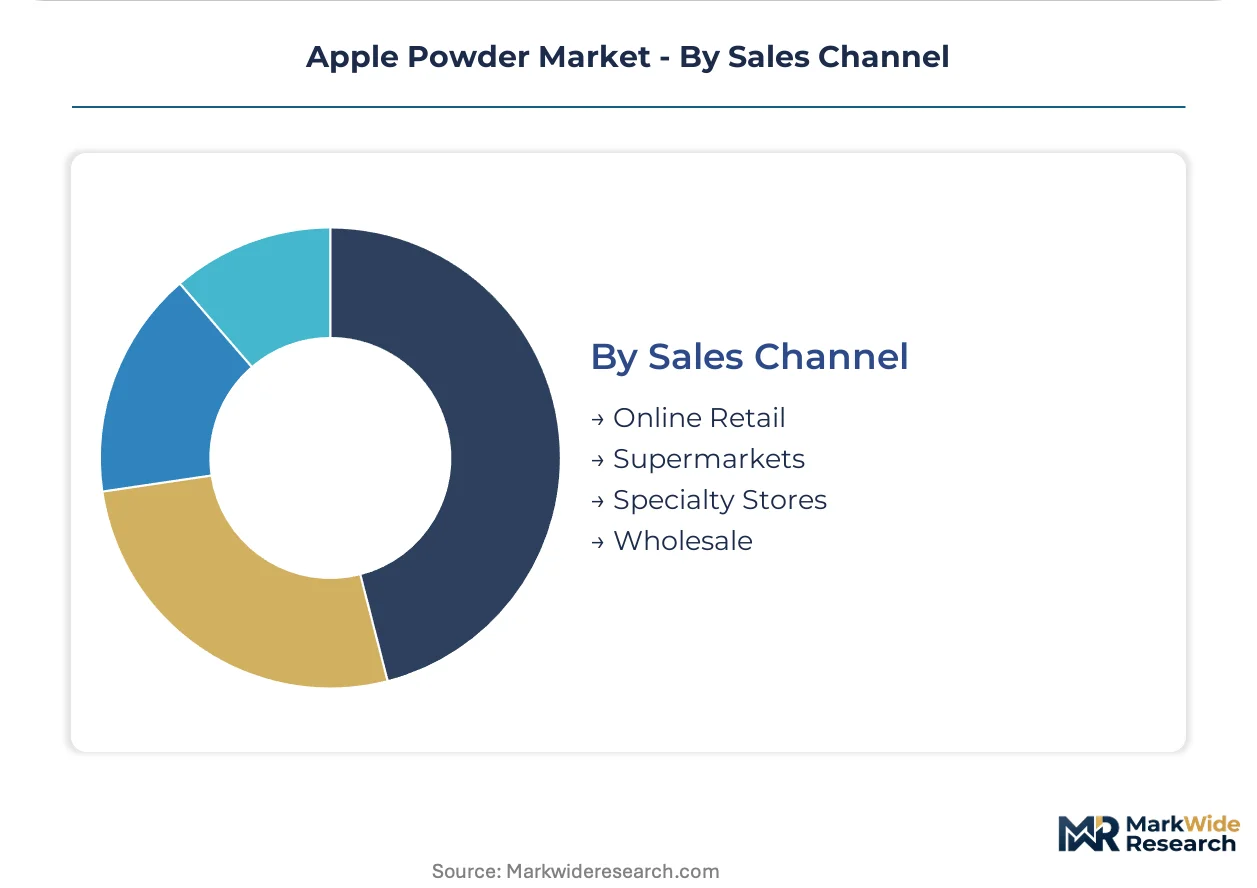
Sales Channel:
Disintermediation pressures reshape channel economics: direct procurement portals between orchard processors and CPG innovation teams shorten contract cycles, while traditional distributor networks retreat to smaller account servicing.
- Wholesale:Industrial ingredient distributors serving mid-tier processors and regional bakery chains. German and U.S. distributors consolidate around polyphenol-certified inventory pools.
- Online Retail:Direct-to-consumer and B2B platform sales enabling traceability documentation and subscription logistics. California beverage startups source Pacific Northwest supply through vertically integrated portals.
- Supermarkets:Mass retail placement for consumer-packaged organic and conventional grades. Clean-label positioning determines shelf allocation in French and U.S. chains.
- Specialty Stores:Health food and cosmetic ingredient boutiques serving formulators and enthusiasts. Swiss and Japanese markets sustain premium pricing through this channel.
Wholesale commands the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Central Europe's ingredient distribution hub status for apple powder shipments. German rail freight corridors connect this maritime gateway to spray-drying clusters in Baden-Württemberg. Pacific Northwest port infrastructure at Seattle-Tacoma anchors trans-Pacific supply chains for U.S.-origin powder.
Germany
Functional food formulators in Baden-Württemberg and Bavaria drive procurement of polyphenol-standardized grades. EU Green Deal agricultural sustainability targets pressure processors to document carbon footprints across orchard sourcing and drying operations. HERBAFOOD INGREDIENTS GmbH anchors European spray-drying capacity near orchard clusters in the Lake Constance region.
United States
California beverage startups and Oregon functional food developers displace traditional bakery buyers as volume anchors. FDA food additive regulations and USDA organic certification requirements shape product standards for domestic and export-bound powder. Tree Top leverages Pacific Northwest apple supply bases near Wenatchee and Yakima to sustain year-round production.
India
FSSAI clean-label guidelines are creating first-mover advantages for certified organic apple powder entrants before local supply chains mature. The country's national food safety regulator tightens additive restrictions in parallel with European precedents. Maharashtra and Gujarat ingredient distributors are building import logistics for spray-dried grades serving bakery reformulation.
Japan
Cosmetic serum formulators in Tokyo and Osaka absorb freeze-dried apple powder at price multiples above food-grade alternatives. METI standards for natural cosmetic ingredients drive batch-to-batch polyphenol validation requirements. Kanto region anti-aging product developers combine apple-derived polyphenols with hyaluronic acid delivery systems.
Switzerland
Premium nutraceutical buyers in Basel and Zurich sustain demand for organic-certified grades with eighteen-to-twenty-four-month documentation cycles. Swissmedic guidance on bioactive ingredient marketing influences health claim substantiation protocols across European suppliers. Alpine region specialty stores and direct-to-consumer channels concentrate distribution of high-margin variants.
Apple Powder Market Vendor Landscape
Concentration sits with orchard-integrated processors and polyphenol-standardization specialists rather than commodity traders. The vendor base spans Pacific Northwest fruit cooperatives, German spray-drying conglomerates, and freeze-drying boutiques serving cosmetic channels. Two strategic archetypes dominate: vertically integrated orchard-to-powder operators and bioactive-focused extraction specialists. Competitive moves center on dual certification acquisition timelines and carbon capture documentation retrofits for EFSA supply chain audits.
Within the orchard-integrated tier, Tree Top and HERBAFOOD INGREDIENTS GmbH exemplify geographic anchoring strategies. FutureCeuticals Inc occupies a position among polyphenol-standardization specialists. These three represent divergent capability investments: Pacific Northwest fruit supply base control, European spray-drying infrastructure proximity to orchard belts, and nutraceutical-grade bioactive libraries for health claim substantiation.
| Leading Market Players |
|---|
| Naturex |
| Mayer Brothers |
| Tree Top |
| FutureCeuticals Inc |
| New Directions Aromatics Inc |
| Instantia |
| Z Natural Foods LLC |
| Kerry Group |
| HERBAFOOD INGREDIENTS GmbH |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for Pacific Northwest apple powder concentrate procurement power in the hands of orchard-integrated processors who control drying capacity scheduling. German buyers face extended lead times from Baden-Württemberg spray-drying clusters, compressing their margin to negotiate spot purchases against contract holders.
Pricing Analysis
Volume-discount tiering separates freeze-dried cosmetic grades from spray-dried food-grade alternatives, with polyphenol standardization commanding the widest spreads. Certification grade and volume scale drive price differentiation, with dual USDA-EU organic labels capturing premiums above conventional alternatives. Cost compression in standard-grade spray-dried powder intensifies because natural gas input volatility erodes processor margins. Bakery chains in Central Europe exhibit the highest price sensitivity, while Japanese cosmetic formulators absorb premiums with minimal volume elasticity.
Supply Chain Analysis
Wenatchee-Yakima orchard belt transit through Seattle-Tacoma port infrastructure anchors trans-Pacific supply chains for U.S.-origin powder. Production draws from the United States, Germany, and India, with spray-drying equipment, natural gas feedstock, and organic certification documentation forming critical input dependencies. Single-source vulnerability concentrates in Pacific Northwest climate exposure and labor availability constraints. Distribution runs through direct procurement portals between orchard processors and CPG innovation teams, displacing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-procurement portal adoption is transforming apple powder sourcing into a platform-economics inflection, with traceability APIs and carbon-footprint dashboards now mandatory for EFSA supply chain audit compliance.
For Market Incumbents: Shield polyphenol-standardized grade positioning by accelerating dual certification timelines before mid-tier processors close the documentation gap. Captive control over Pacific Northwest orchard supply bases and retrofitting legacy spray-drying assets with real-time moisture sensors defend against price erosion in commodity segments. For New Entrants and Emerging Players: USDA organic certification fast-track for imported powders unlocks first-mover positioning in India's FSSAI-compliant functional food sector before local supply chains mature. White-space concentration sits with certified organic sachet formats for California wellness beverage subscription models, with traceability storytelling as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from European fruit cooperative parent organizations seeking to monetize non-core spray-drying infrastructure near German orchard clusters. Long-term viability hinges on bioactive extraction capabilities and carbon-capture documentation systems. The signal to watch is EFSA novel food assessment timeline compression for polyphenol health claim substantiation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Fast-Track | USDA-EU organic label acquisition reduces time-to-shelf for Central European processors serving clean-label retail. |
| Carbon Capture Retrofit | Spray-drying facility upgrades satisfy EFSA supply chain audit demands from German bakery chain procurement teams. |
| Polyphenol Standardization Investment | Analytical chemistry capabilities enable batch-to-batch bioactive consistency for nutraceutical health claim dossiers. |
| Direct Procurement Portal Launch | Vertical integration between Pacific Northwest orchard processors and California beverage startups disintermediates distributor networks. |
| Freeze-Drying Capacity Addition | Sublimation-based dehydration assets capture cosmetic-grade margin pools in Japanese anti-aging serum formulations. |
Methodological Framework
A standing panel of spray-drying plant managers, nutraceutical procurement leads, functional beverage formulators, and EU organic certification auditors provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA food additive filings, EFSA novel food assessment databases, USDA organic certification records, and German customs trade data. Bottom-up orchard processor capacity assessments triangulated against top-down bakery and beverage manufacturer demand forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including dehydration technology type, certification tier, end-use application, packaging format, and regional production hub. CAGRs were derived from trend extrapolation of procurement pattern shifts and input cost trajectories, with polyphenol health claim substantiation timelines and EU Green Deal carbon documentation requirements serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained clean-label regulatory tightening and Pacific Northwest supply concentration assumptions; material deviation in climate volatility or natural gas pricing would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA-FDA divergence on bioactive ingredient marketing and FSSAI guideline evolution in India reshape grade-specific demand patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Natural Rosemarine Extract Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Medicinal Plant Extracts Market
Extracts
Pullulan Market
Extracts
Passion Flower Extracts Market
Extracts
White Willow Bark Extract Market
Extracts
Black Fungus Extract Market
Extracts
Organic Extracts Market
Extracts
Gum Turpentine Oil Market
Extracts
Peru Balsam Extract Market
Extracts
Algae Extracts Market
Extracts
Eucommia Extract Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Nootkatone Market
Extracts
Belladonna Market
Extracts
Herba Houttuyniae Extract Market