
 Epoxy Encapsulation Material Market | 2026-2036
Epoxy Encapsulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Encapsulation Material Market Foresight
The EU Green Deal is restructuring procurement criteria for electronic component protection across European automotive supply chains. Henkel AG & Co. KGaA leverages its adhesive heritage to dominate thermal conductive formulations for power modules. Sumitomo Bakelite anchors legacy supply relationships with Japanese semiconductor fabricators through high-purity resin consistency. Shin-Etsu Chemical competes on silicone-epoxy hybrid architectures that sustain dielectric performance at elevated temperatures.
Epoxy encapsulation materials are thermosetting polymer systems, typically formulated from bisphenol-A or bisphenol-F resins cured with anhydrides or amines, that provide environmental protection and mechanical support for sensitive electronic components. These materials must maintain glass transition temperatures above 150°C and thermal conductivity thresholds exceeding 1.5 W/m·K for power electronics applications. Thermal conductive grades command premium positioning as electric vehicle inverters and charging infrastructure multiply heat dissipation requirements. Electrical insulating formulations retain stable margin pools in mature consumer electronics circuit board applications where reliability standards have long been codified. UV curing segments are accelerating fastest in sensor packaging for industrial automation, where throughput speed determines line economics.
EPA standards on volatile organic compound emissions constrain formulation chemistry for US-based electronics manufacturing, while REACH registration requirements in Europe enforce full material disclosure across epoxy hardener supply chains. China's MEE enforces dual carbon goals that pressure domestic encapsulant producers toward bio-based feedstock substitution. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional product variants offer superior compliance economics.
Market Dynamics
Semiconductor packaging densification in East Asia is compressing thermal management tolerances, forcing formulators to balance dielectric stability against conductivity thresholds in sub-10nm node applications.
Growth Catalysts
- Power module thermal loads:Electric vehicle inverters from BYD and Tesla's supply chains demand encapsulants exceeding 2.0 W/m·K thermal conductivity. Korean and Chinese battery pack integrators are qualifying new grades quarterly.
- REACH SVHC disclosure:ECHA's expanding candidate list forces hardener suppliers to document full substance flow. European automotive tier-1s now require third-party verified material passports for epoxy sourcing.
- Industrial sensor throughput:UV-curable formulations are automating line speeds for photodiode packaging in German and Japanese factory automation deployments.
Market Restraints
- Bisphenol-A feedstock volatility:Crude-linked benzene and propylene costs transmit directly to resin pricing. Chinese petrochemical capacity additions have not stabilized spot market swings.
- High-purity resin concentration:Japanese specialty chemical producers control 70% of semiconductor-grade bisphenol-F supply. Geographic single-sourcing creates allocation risk during fab capacity ramps.
- Silicone-epoxy hybrid substitution:Shin-Etsu's silicone-modified platforms sustain flexibility above 180°C. Power electronics designers are migrating away from pure epoxy for junction temperatures exceeding Tg limits.
Strategic Opportunities
- India semiconductor packaging:Micron's Gujarat assembly and test facility creates first-mover positioning for encapsulant qualification. Domestic PLI scheme incentives cover 30% of capital expenditure for materials localization.
- Optoelectronic co-packaging:Silicon photonics transceivers require low-stress encapsulation for fiber alignment retention. CPO switch deployments by cloud hyperscalers will scale this application through 2028.
- China dual carbon compliance:MEE enforcement of bio-based content mandates opens formulation slots for lignin-derived epichlorohydrin routes. State-backed research institutes are piloting epoxidized vegetable oil curing systems.
Industry Challenges
- Formulation chemist scarcity:Thermoset rheology and filler dispersion expertise concentrates among retiring Japanese and German specialists. University polymer programs have shifted toward thermoplastics and composites.
- Cleanroom qualification timelines:Semiconductor fab material approval cycles extend 18-24 months for new encapsulant grades. Particle count and outgassing protocols from SEMI standards block fast market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Encapsulation Material Market |
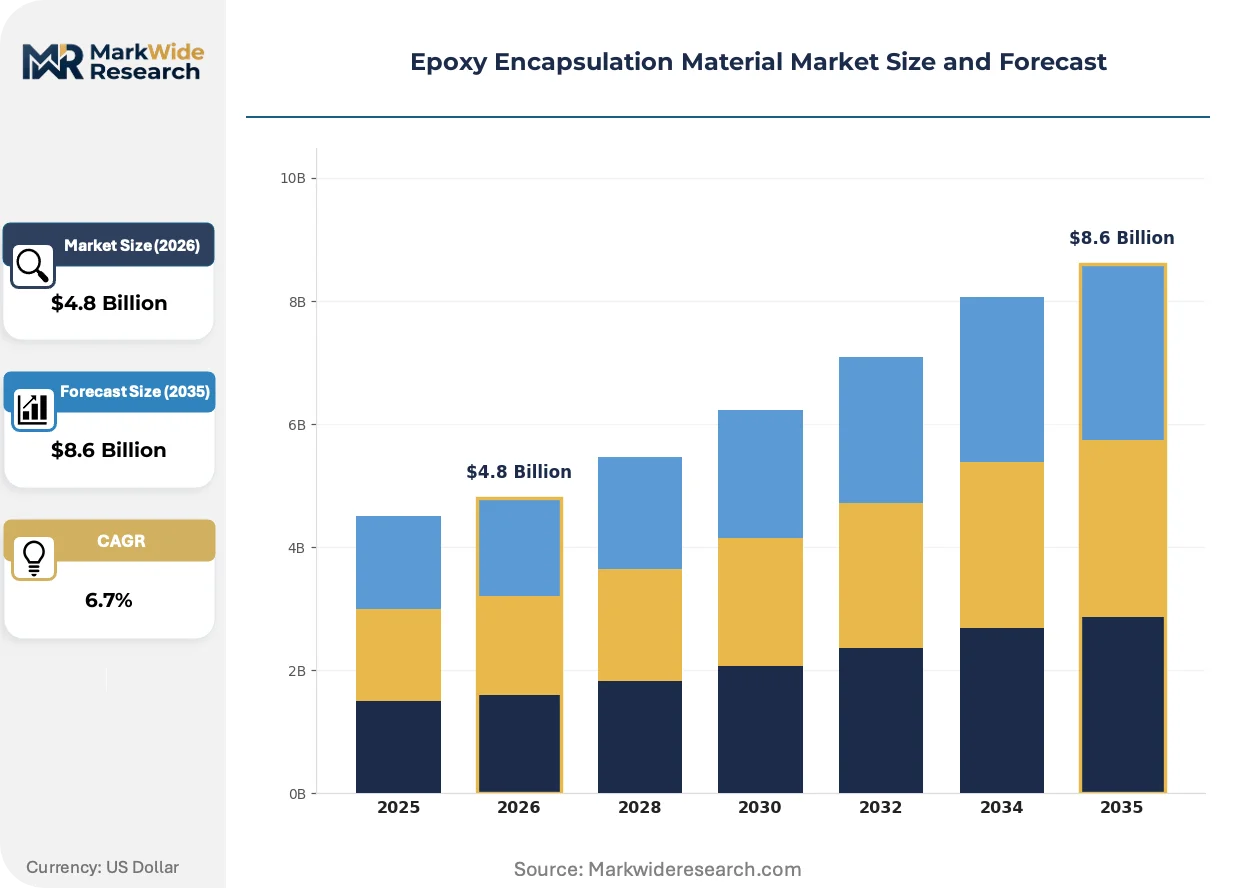
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Conductive, Electrical Insulating, UV Curing, Flexible End User: Electronics, Automotive, Aerospace, Industrial Application: Consumer Electronics, Circuit Boards, Sensors, Industrial Equipment Grade: High Purity, Low Viscosity, High Temperature, Standard |
| Companies Covered | Henkel AG & Co. KGaA, Sumitomo Bakelite, Shin-Etsu Chemical, Hitachi Chemical, Huntsman Corporation, Panasonic Corporation, Samsung SDI, Showa Denko Materials, Chang Chun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Encapsulation Material Market Shifts & Advancements
Epoxy encapsulation chemistry is pivoting from generic electrical insulation toward thermal-functional specialization, with formulation automation and regulatory material disclosure as concurrent transformation vectors.
AI-driven formulation platforms are automating filler loading optimization and cure kinetics prediction. Henkel and Sumitomo Bakelite have deployed machine learning models that compress experimental design cycles from months to weeks. These systems are automating the translation of thermal simulation outputs into validated material specifications for customer-specific power module geometries.
China's MEE dual carbon enforcement is tightening disclosure requirements for hardener supply chains. Domestic encapsulant producers must now document carbon intensity per kilogram and submit to provincial environmental audits. Export-oriented formulators in Jiangsu and Guangdong are accelerating bio-based feedstock substitution to maintain EU market access under CBAM border adjustments.
Automotive tier-1s are consolidating qualified supplier lists to single-source encapsulants per inverter platform. Bosch and Continental have reduced their active formulation approvals from twelve suppliers to four per thermal class. This concentration is compressing pricing leverage for mid-tier formulators and elevating technical service intensity as the primary retention mechanism in European and North American procurement.
Epoxy Encapsulation Material Market Segmentation
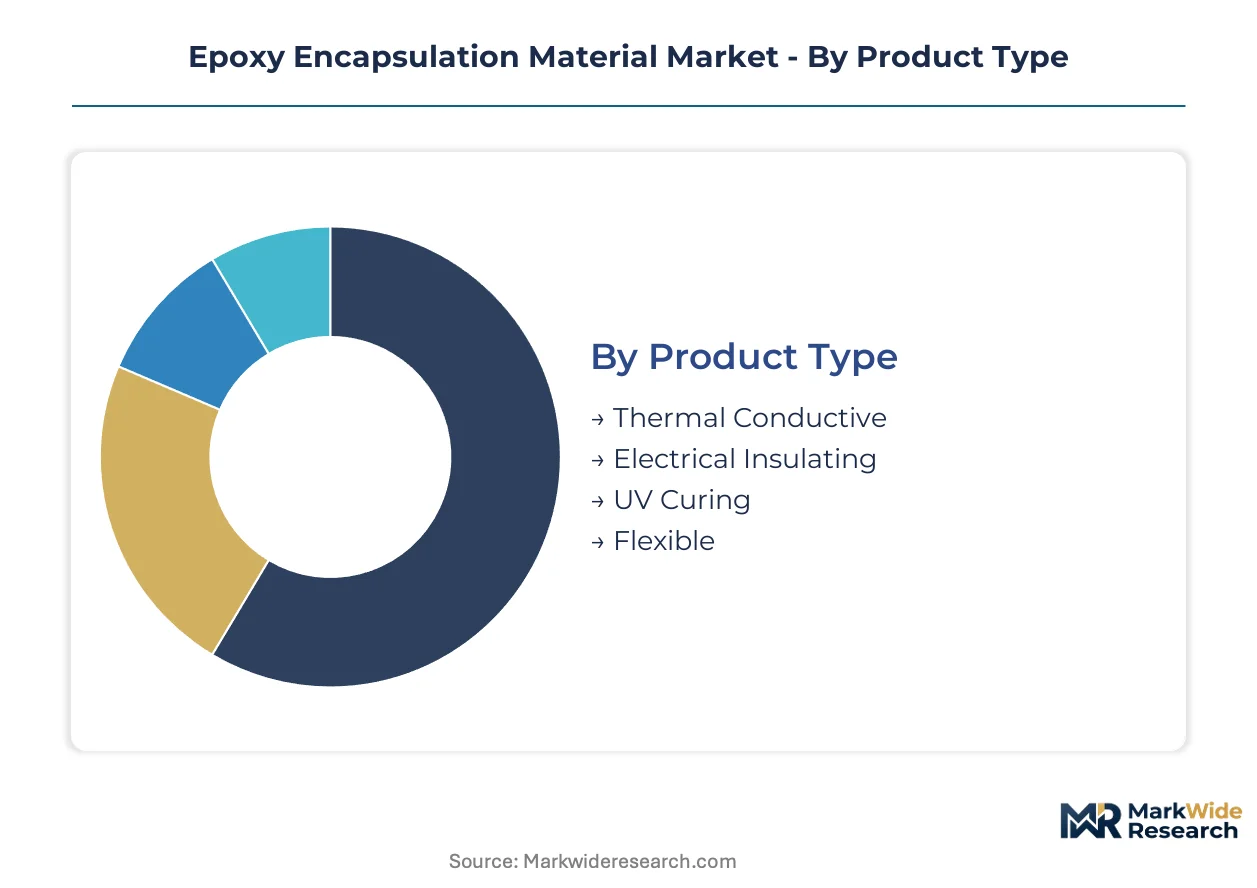
Epoxy encapsulation materials segment across performance specifications, thermal demands, and regulatory compliance tiers. Formulators must match resin chemistry to substrate sensitivity, operating temperature, and cure speed requirements.
Product Type:
Customization intensity spans from commodity electrical insulation to engineered thermal management solutions requiring filler loading optimization and cure profile tuning.
- Thermal Conductive:Boron nitride or aluminum oxide-filled formulations achieve thermal conductivity above 1.5 W/m·K. BYD and Tesla inverter suppliers in South Korea and China are qualifying grades exceeding 2.0 W/m·K quarterly. Premium positioning reflects electric vehicle power module heat dissipation requirements.
- Electrical Insulating:Unfilled bisphenol-A or bisphenol-F systems prioritize dielectric strength and moisture resistance. Circuit board protection in mature consumer electronics retains stable margin pools where reliability standards have long been codified.
- UV Curing:Photoinitiated acrylate-modified epoxies enable line speeds under 30 seconds. German and Japanese factory automation deployments for photodiode packaging drive sensor segment automation.
- Flexible:Silicone-epoxy hybrid architectures sustain elongation above 5% post-cure. Shin-Etsu Chemical platforms compete for junction temperatures exceeding 180°C in power electronics migration.
Leading the category by volume: Electrical Insulating. Growing fastest: UV Curing.
End User:
Application severity divides segments by thermal cycling tolerance, flame retardancy requirements, and qualification timeline intensity.
- Electronics:Semiconductor packaging densification in East Asia compresses thermal management tolerances for sub-10nm node applications. Memory chip clusters around Pyeongtaek and Yongin pull demand upward.
- Automotive:Inverter and onboard charger modules require encapsulants sustaining 150°C continuous operation. EU Green Deal procurement criteria restructure European automotive supply chain specifications.
- Aerospace:Outgassing compliance to NASA or ESA standards constrains resin selection. Satellite electronics qualification cycles extend 24-36 months.
- Industrial:Motor drive and power supply applications balance cost against thermal performance. REACH SVHC disclosure requirements from ECHA now mandate third-party verified material passports.
Electronics commands the largest volume share. Automotive presents the steepest expansion trajectory as electric vehicle production scales.
Application:
Device miniaturization and assembly automation dictate formulation viscosity, filler particle size distribution, and cure mechanism selection.
- Consumer Electronics:Smartphone and wearable protection demands low-stress curing to prevent warpage of thin substrates. High-volume Asian contract manufacturers prioritize potting speed and material cost.
- Circuit Boards:Conformal coating and potting applications require moisture resistance and solder mask compatibility. Mature specifications limit formulation differentiation to logistics and technical service.
- Sensors:Photodiode and MEMS packaging requires optical clarity or low-alpha particle emission. UV curing segments accelerate where throughput speed determines line economics.
- Industrial Equipment:Harsh environment protection for motor controllers and power supplies emphasizes chemical resistance and thermal cycling durability. China's MEE dual carbon enforcement pressures bio-based feedstock substitution.
Circuit Boards retains the highest volume base. Sensors are climbing the fastest on silicon photonics and industrial automation demand.
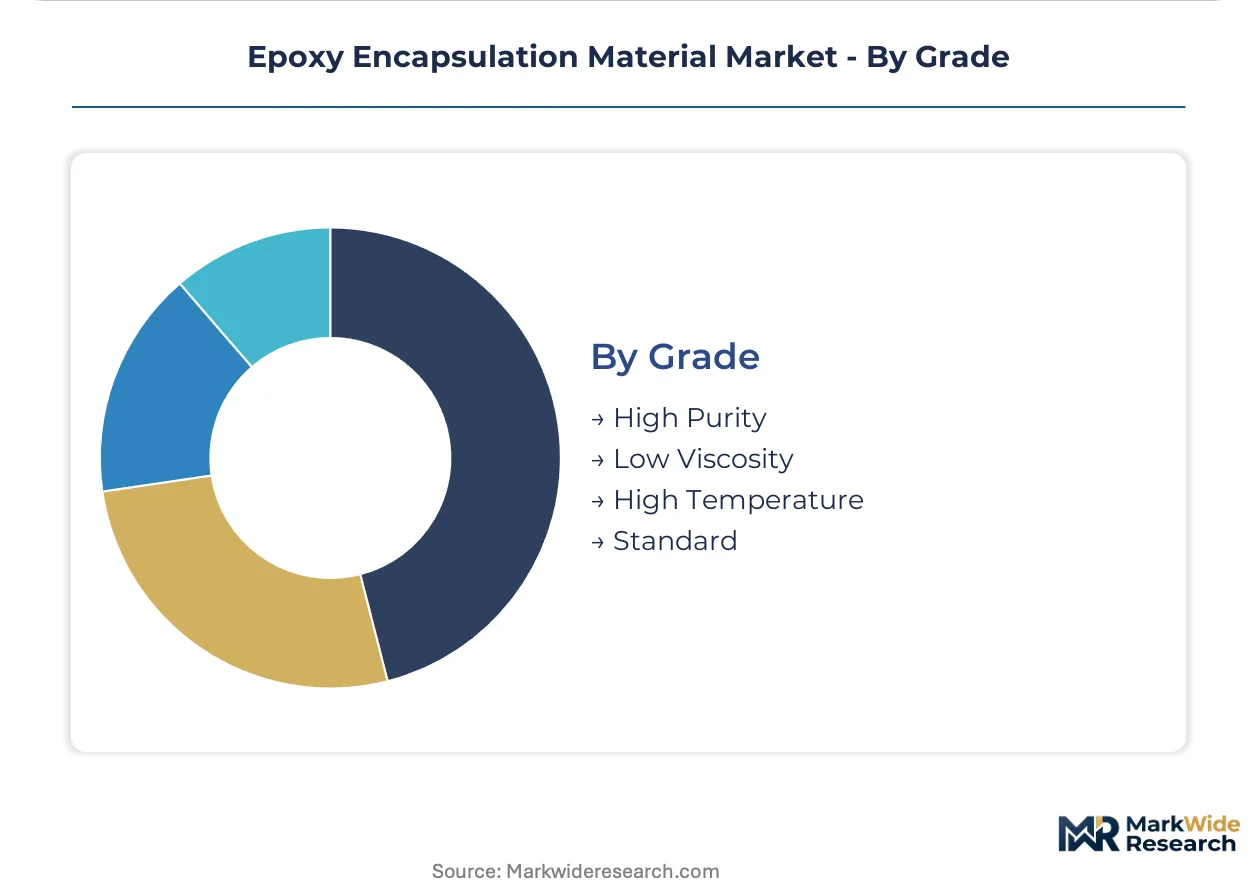
Grade:
Purity and processing characteristics stratify pricing across semiconductor-grade precision and general industrial suitability.
- High Purity:Ionically-cleaned resins with chloride content below 10ppm prevent corrosion of aluminum bond pads. Japanese specialty chemical producers control 70% of semiconductor-grade bisphenol-F supply, creating geographic single-sourcing risk.
- Low Viscosity:Capillary flow formulations penetrate underfill gaps below 50 microns. Flip-chip and chip-scale package applications in Taiwan and South Korea drive qualification.
- High Temperature:Anhydride-cured systems achieve glass transition temperatures above 180°C. Automotive underhood and power electronics applications require sustained performance at elevated junction temperatures.
- Standard:General-purpose bisphenol-A formulations serve cost-sensitive potting and casting. Bisphenol-A feedstock volatility from crude-linked benzene and propylene costs transmits directly to resin pricing.
Standard grade leads by shipment volume. High Purity commands the fastest share gain on advanced packaging expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and South Korea concentrate production of semiconductor-grade resins while China and the United States consume the majority of thermal conductive formulations for electric vehicle power electronics. East Asian fabrication clusters drive specification intensity as packaging densities compress thermal tolerances.
China
MEE dual carbon enforcement pressures domestic formulators toward bio-based feedstock substitution and full carbon intensity disclosure per kilogram. Jiangsu and Guangdong export-oriented producers accelerate lignin-derived epichlorohydrin pilot programs to maintain EU market access under CBAM border adjustments. The Yangtze River Delta encapsulant manufacturing corridor faces provincial environmental audit tightening.
South Korea
Memory chip packaging around Pyeongtaek and Yongin pulls demand for high-purity bisphenol-F resins and low-viscosity underfill formulations. Korean battery pack integrators qualify thermal conductive grades exceeding 2.0 W/m·K quarterly for BYD and Tesla supply chains. Seoul Capital Area formulators concentrate technical service resources on automotive inverter platform approvals.
Japan
Japanese specialty chemical producers control approximately 70 percent of semiconductor-grade bisphenol-F supply, creating geographic single-sourcing concentration risk during fab capacity ramps. METI industrial policy supports high-purity resin consistency standards for domestic semiconductor fabricator relationships. Kanto and Kansai chemical corridors anchor legacy supply relationships with advanced packaging houses.
United States
EPA volatile organic compound emission standards constrain formulation chemistry for domestic electronics manufacturing, particularly in automotive and industrial equipment applications. Texas and Arizona semiconductor packaging expansions drive qualification timelines for new encapsulant grades. Midwest power electronics manufacturing clusters demand thermal conductive formulations sustaining 150°C continuous operation.
Germany
ECHA REACH SVHC disclosure requirements and EU Green Deal procurement criteria restructure automotive supply chain specifications for electronic component protection. Bavaria and Baden-Württemberg automotive tier-1s consolidate qualified supplier lists to single-source encapsulants per inverter platform. German factory automation deployments accelerate UV-curable formulation adoption for photodiode packaging throughput.
Epoxy Encapsulation Material Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with adhesive or resin heritage rather than pure-play encapsulant specialists. Japanese and German producers anchor premium positioning through high-purity consistency and thermal-functional specialization, while Korean and Chinese suppliers compete on scale and regional qualification speed. Three archetypes dominate: diversified materials conglomerates with semiconductor customer intimacy, thermal management specialists leveraging power electronics demand, and regional formulators capturing domestic electric vehicle supply chain slots. Capacity expansion and portfolio diversification toward silicone-epoxy hybrid architectures constitute the dominant competitive moves.
Within the diversified conglomerate tier, Henkel AG & Co. KGaA and Sumitomo Bakelite occupy positions defined by adhesive heritage and resin consistency expertise respectively. Shin-Etsu Chemical exemplifies the thermal-functional specialization archetype through silicone-epoxy hybrid platforms. These three anchors represent distinct competitive vectors: European automotive supply chain consolidation, Japanese semiconductor fabricator legacy relationships, and high-temperature material architecture innovation.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sumitomo Bakelite |
| Shin-Etsu Chemical |
| Hitachi Chemical |
| Huntsman Corporation |
| Panasonic Corporation |
| Samsung SDI |
| Showa Denko Materials |
| Chang Chun Group |
| Others |
Supply & Pricing Matrix
Automotive tier-1 inverter platform consolidation concentrates procurement leverage among Bosch, Continental, and BYD supply chain managers, compressing pricing power toward contract-based long-term offtake structures with volume-scaled rebates.
Pricing Analysis
Margin tightening in thermal conductive grades reflects bisphenol-A feedstock volatility from crude-linked benzene and propylene costs. Three-tier pricing structure across high-purity semiconductor, automotive thermal, and standard industrial grades differentiates by certification level and filler loading optimization. Cost-down pressure on mid-tier formulators accelerates because Korean and Chinese battery pack integrators qualify new suppliers quarterly. Circuit board protection segments exhibit highest price sensitivity; high-purity resin grades for sub-10nm packaging show least sensitivity due to Japanese supply concentration.
Supply Chain Analysis
Dual-sourcing mandates from European automotive OEMs now require qualified backup suppliers for all thermal conductive formulations. Raw material supply concentrates in Japan, South Korea, and China, with Japanese specialty chemical producers controlling semiconductor-grade bisphenol-F supply. Formulation chemistry draws from epichlorohydrin, anhydride hardeners, and boron nitride fillers. Single-source vulnerability in high-purity resin channels creates allocation risk during fab capacity ramps. Distribution runs through regional chemical distributors and direct technical service teams to semiconductor fabricators and automotive tier-1s.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
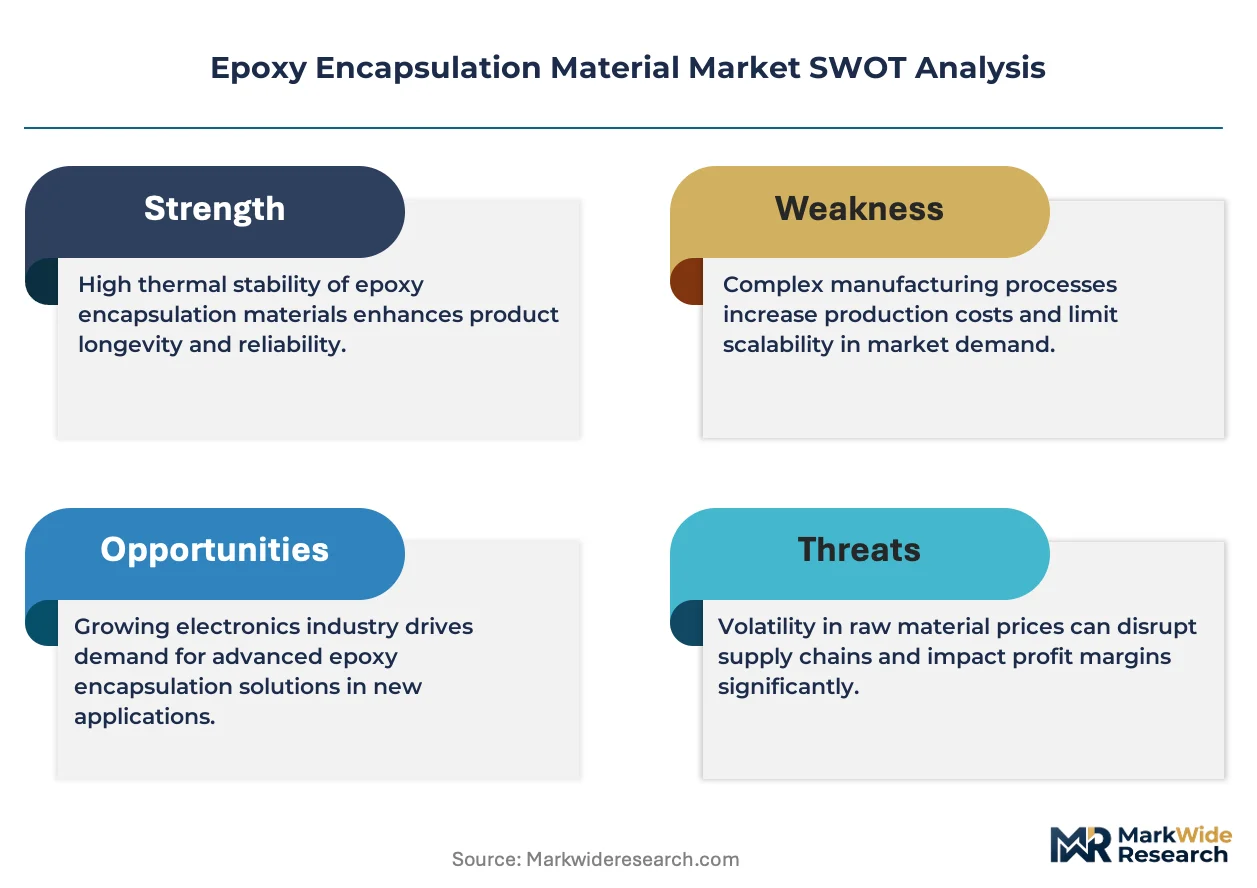
This market functions as a vertical-integration race where backward integration into high-purity resin production determines margin defense against Japanese supply concentration.
For Market Incumbents: Anchor semiconductor fabricator relationships through dedicated cleanroom qualification teams and 18-24 month co-development programs. Defend against silicone-epoxy hybrid substitution by accelerating anhydride-cured high-temperature grade R&D. Prioritize capacity addition in South Korea's Pyeongtaek corridor to match memory chip packaging densification timelines. For New Entrants and Emerging Players: The price-point gap between Shin-Etsu's silicone-epoxy hybrids and standard bisphenol-A formulations opens white-space in flexible encapsulation for industrial motor drives. Target India's Gujarat semiconductor packaging cluster through Micron qualification partnerships. Pursue bio-based feedstock routes under China's MEE dual carbon enforcement as differentiated go-to-market positioning against incumbent petrochemical supply chains. For Investors and Strategic Acquirers: The window for entry favors formulators with captive high-purity resin supply or established automotive inverter platform approvals. Long-term viability hinges on qualification speed compression and thermal conductivity threshold advancement. Acquisition target archetype: regional specialists with automotive tier-1 technical service depth. Watch ECHA REACH SVHC list expansion as inflection indicator for hardener supply chain restructuring costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Resin | Captive bisphenol-F supply reduces allocation risk from Japanese concentration during fab ramps. |
| Silicone-Epoxy Hybrid Platform Launch | Shin-Etsu's architecture sustains flexibility above 180°C for power electronics junction temperature migration. |
| India Semiconductor Packaging Qualification | Micron's Gujarat facility creates first-mover positioning under PLI scheme capital expenditure incentives. |
| Bio-Based Feedstock Substitution | Lignin-derived epichlorohydrin routes secure EU market access under CBAM border adjustments. |
| AI-Driven Formulation Automation | Henkel and Sumitomo Bakelite deploy machine learning to compress experimental design from months to weeks. |
Research Methodology
Independent corroboration across formulation chemist interviews, automotive tier-1 procurement leads, and semiconductor fab material engineers underwrites the qualitative findings. Primary fieldwork engaged plant managers at Jiangsu and Guangdong encapsulant facilities, distribution channel partners serving East Asian packaging houses, and technical R&D directors at thermal management specialists. Secondary validation drew from customs trade data, SEMI standards documentation, EPA emission filings, and ECHA REACH registration databases. Bottom-up resin grade shipment estimates and top-down electric vehicle inverter content assumptions were triangulated.
Rate-of-change decomposition across product type, end user, application, and grade dimensions structured the analytical framework. Thermal conductivity threshold advancement, semiconductor node shrinkage timelines, and automotive inverter production scaling served as industry-specific forecast inputs. CAGRs were derived from segment-level volume trajectories cross-referenced against electric vehicle battery pack integration rates and memory chip packaging expansion schedules throughout the forecast period.
Inputs from ECHA regulatory filings and MEE provincial audit disclosures were available through the study window; gaps in real-time semiconductor fab material qualification timelines introduce uncertainty bands around adoption rate assumptions. Deviation in REACH SVHC list expansion timing or CBAM border adjustment enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Open Cell Foam Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Global PE Films Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Polyimide Films Market