
 Europe Solar Control Window Films Market | 2026-2036
Europe Solar Control Window Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Control Window Films Market Analysis
A capital-intensity divergence between integrated resin producers and regional installers is redrawing competitive boundaries in the European market. Saint-Gobain Performance Plastics Corporation leverages its float glass heritage to anchor premium architectural specifications across France and neighboring markets. Eastman Chemical Company sustains polymer innovation pipelines that differentiate its ceramic and spectrally selective portfolios. Purlfrost Ltd competes through specialized UK distribution networks serving retrofit commercial segments.
Europe solar control window films comprise multi-layer polymer laminates, typically polyester substrates with metallized, dyed, or nano-ceramic coatings, engineered to attenuate solar infrared and ultraviolet transmission while preserving visible light transmission for glazing assemblies. These films reduce cooling loads, limit interior fading, and improve occupant thermal comfort in buildings and vehicles. Ceramic films command expanding share as their non-metallic composition eliminates signal interference and satisfies electromagnetic transparency requirements for connected commercial spaces. Professional installation dominates value capture given warranty validity and precision demands on large-format glazing, though DIY channels extend reach in residential renovation cycles across Southern Europe.
The EU Green Deal and Energy Performance of Buildings Directive, enforced by national regulators including BREEAM assessors and country-level energy agencies, mandate progressive thermal efficiency upgrades that directly expand retrofit film specifications. REACH compliance and CE marking requirements govern chemical composition and optical safety thresholds, filtering non-conforming imports from Asian supply bases. Stakeholders must monitor upcoming revisions to the F-Gas Regulation and national building renovation passports, as these frameworks will determine whether solar control films qualify as primary or supplementary efficiency measures in public incentive schemes.
Market Dynamics
The EU Green Deal's retrofit mandates are compressing installation timelines across Europe's aging commercial building stock, forcing rapid specification shifts toward high-performance ceramic and spectrally selective films that satisfy tightening national energy codes.
Growth Catalysts
- Energy Performance of Buildings Directive:National regulators in Germany and France enforce progressive thermal efficiency upgrades that directly expand retrofit film specifications in commercial structures.
- Ceramic coating advances:Non-metallic nano-ceramic films eliminate electromagnetic interference, satisfying connectivity requirements for smart commercial buildings and connected vehicle fleets.
- Southern Europe renovation cycles:Spain and Italy's residential retrofit activity accelerates DIY channel penetration for residential solar control applications.
Market Restraints
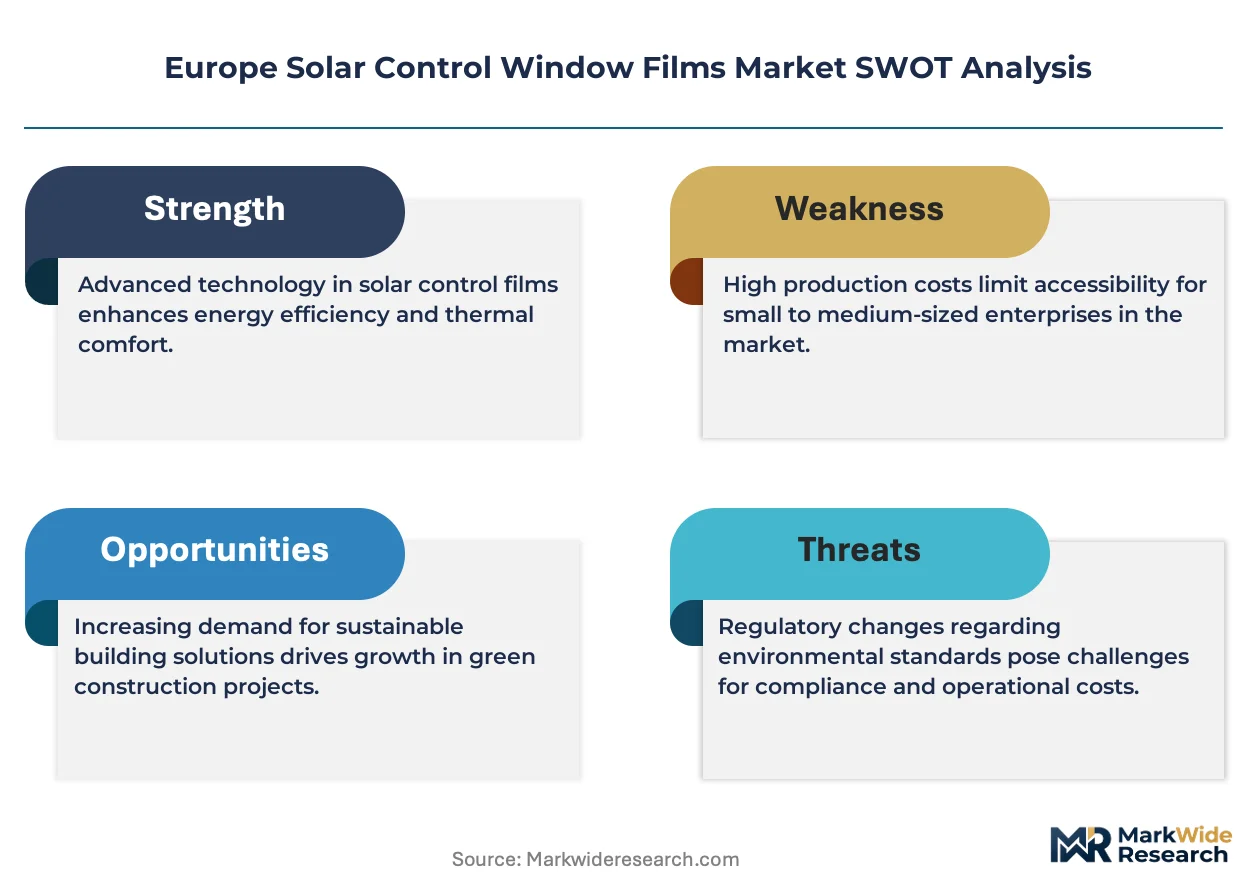
- Polyester resin cost volatility:Petrochemical feedstock fluctuations squeeze margin structures for film laminators dependent on virgin polyester substrates.
- Asian import concentration:Non-conforming supply from unverified Asian manufacturers creates quality inconsistency and warranty claim exposure for European distributors.
- Window replacement substitution:Triple-glazing and electrochromic smart glass advances threaten film retrofit economics in premium new-build segments.
Strategic Opportunities
- Poland and Eastern Europe building stock:Underpenetrated markets present first-mover advantages as EU cohesion funds channel toward energy efficiency upgrades.
- Building renovation passports:France's national renovation passport scheme positions solar control films as qualifying efficiency measures for public incentive schemes.
- Automotive OEM integration:Electric vehicle manufacturers specify factory-applied ceramic films to manage thermal loads without compromising 5G connectivity.
Industry Challenges
- Skilled installer scarcity:Large-format commercial glazing demands precision application expertise that outpaces vocational training pipeline output.
- REACH compliance timelines:Chemical composition verification and CE marking documentation create extended product launch cycles for reformulated coatings.
- Legacy HVAC integration:Film specification conflicts with existing building management system setpoints complicate energy savings verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Control Window Films Market |
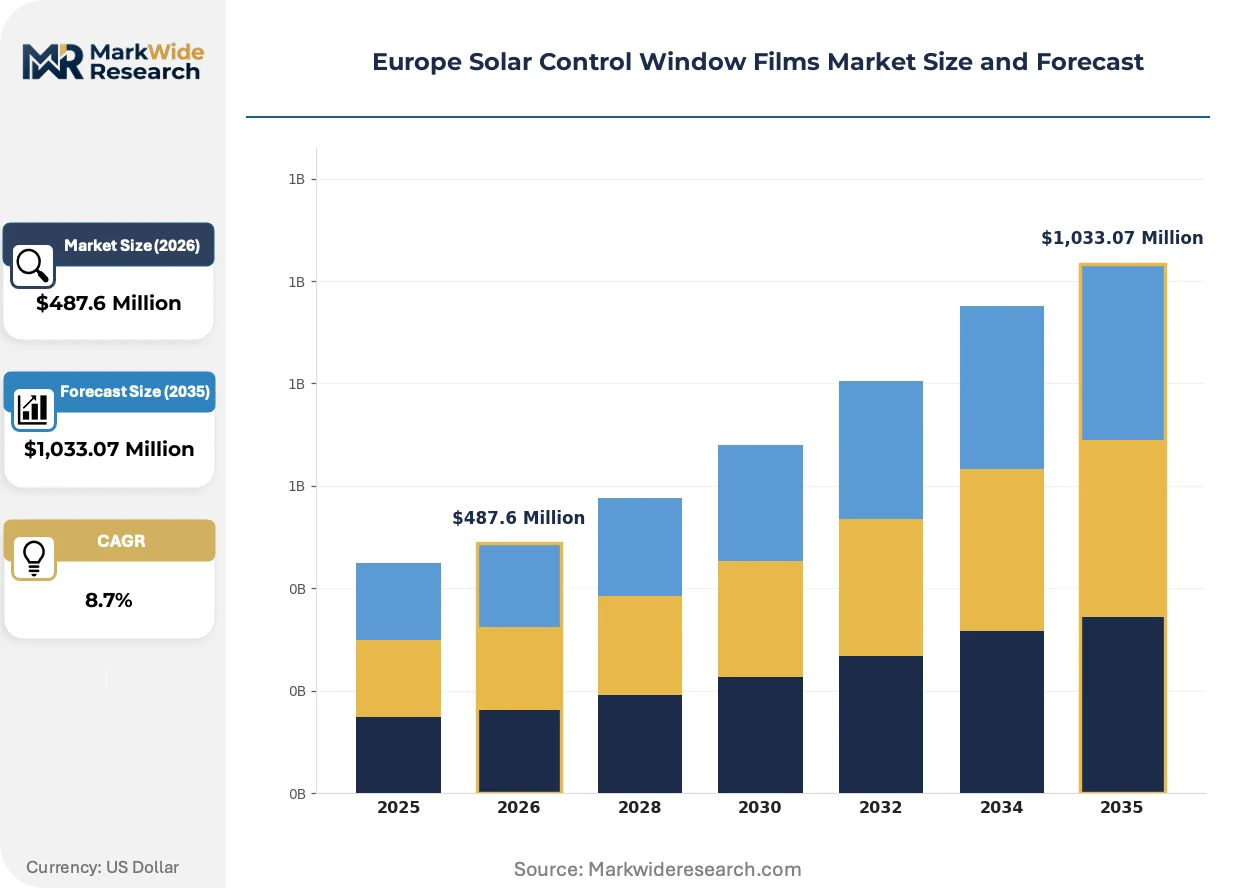
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyed Films, Metalized Films, Ceramic Films, Spectrally Selective Films Application: Residential, Commercial, Automotive, Marine Installation Type: DIY, Professional, Retro-fit, New Construction Technology: Reflective, Absorptive, Nano-coating, Hybrid |
| Companies Covered | 3M, Saint-Gobain Performance Plastics Corporation, Eastman Chemical Company, Purlfrost Ltd, Avery Dennison Israel Ltd, Johnson Window Films Inc., Madico Inc, The Window Film Company, Solar Screen International S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Control Window Films Market Emerging Trajectories
Material science convergence with digital building infrastructure is redefining performance benchmarks across European specification channels. Three developments dominate current R&D allocation and buyer evaluation criteria.
Nano-ceramic interference coatings are miniaturizing thermal rejection architectures while preserving optical clarity. German automotive OEMs now specify these layers for electric vehicle panoramic roofs. The technology is miniaturizing equipment footprints for on-site application, reducing logistics costs for retrofit contractors.
REACH chemical safety revisions and impending F-Gas Regulation updates are tightening permissible coating chemistries. Film formulators accelerate fluorine-free adhesive development to preempt compliance cliffs. Southern European distributors stockpile qualifying inventory ahead of enforcement windows.
Professional certification is displacing price-only evaluation in commercial procurement. BREEAM assessors and national energy agencies validate installation quality for warranty eligibility. France and the Netherlands lead this behavioral shift, with specification committees mandating certified installer networks for public building tenders.
Europe Solar Control Window Films Market Segmentation
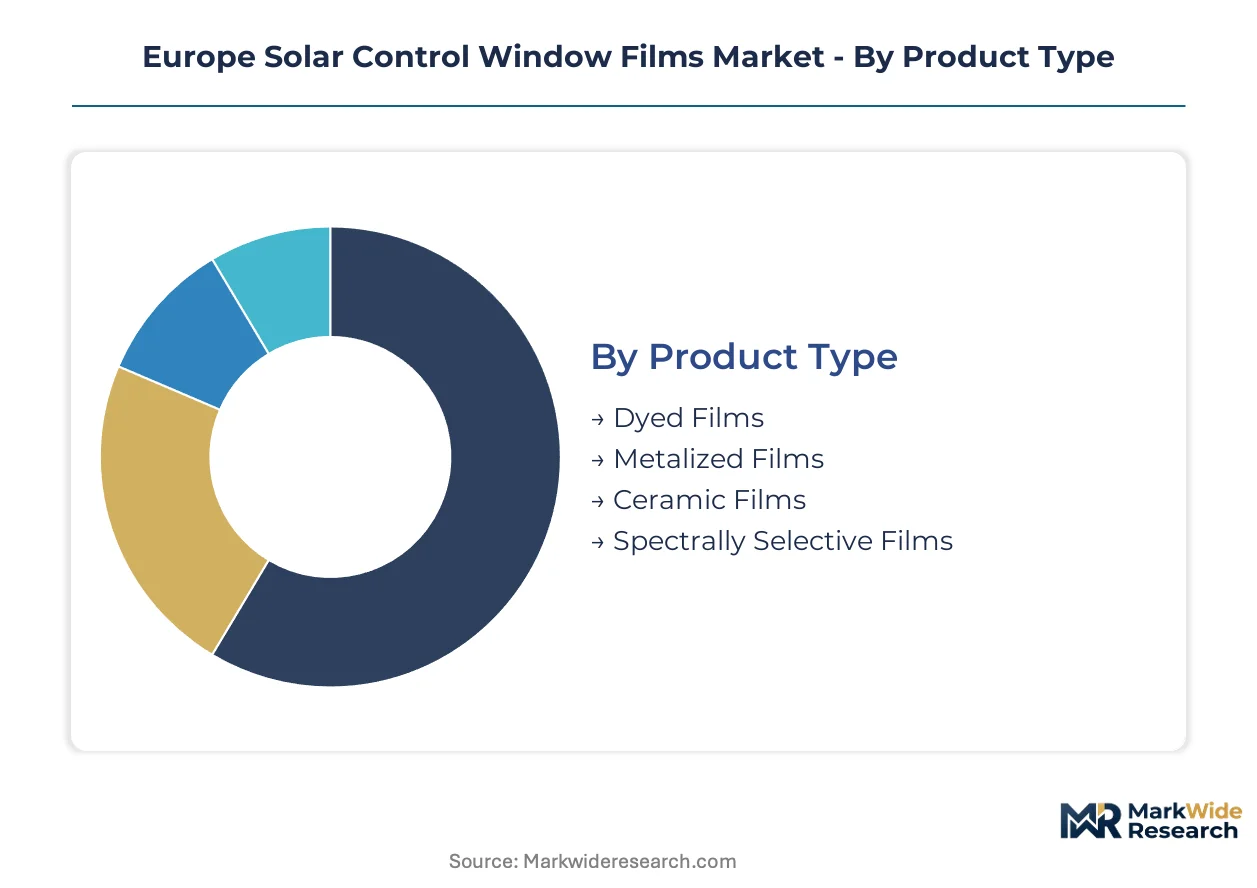
Segmentation in the Europe solar control window films market reveals how regulatory pressure and installation economics split demand across performance tiers and application contexts. Understanding these divides helps stakeholders align product development with the EU Green Deal's retrofit mandates and emerging connectivity requirements.
Product Type:
Geographic demand concentration varies sharply across product categories, with spectrally selective and ceramic formulations tracking toward export-intensive Northern European markets while dyed films serve price-sensitive domestic renovation cycles in Southern Europe.
- Dyed Films:Polyester substrates infused with organic colorants absorb solar energy rather than reflect it, producing moderate heat rejection at lower cost points. Spanish and Italian residential retrofits absorb the bulk of regional volume as DIY channels prioritize affordability over peak thermal performance.
- Metalized Films:Vacuum-deposited aluminum or nickel layers deliver high infrared rejection through reflective interference. German and French commercial specifications dominate demand, though electromagnetic opacity limits deployment in connected building zones and electric vehicle glazing.
- Ceramic Films:Non-metallic nano-ceramic oxides attenuate infrared transmission without signal degradation. Electric vehicle manufacturers and smart commercial buildings in the Netherlands and Scandinavia specify these layers for electromagnetic transparency compliance.
- Spectrally Selective Films:Multi-layer optical stacks target specific wavelength bands, maximizing visible light transmission while blocking thermal infrared. BREEAM-assessed office retrofits in London and Paris specify these for daylighting optimization under tightening energy codes.
Ceramic films command the established base. The steepest expansion runs through spectrally selective formulations.
Application:
Cost tier stratification separates premium architectural specifications from mass-market residential adoption, with automotive emerging as a volume bridge between the two.
- Residential:Single-family and multi-unit housing retrofits concentrate in Mediterranean climates where cooling load reduction drives purchase decisions. Southern European distributors stock DIY-oriented dyed and metalized inventories for renovation seasonality.
- Commercial:Office, retail, and hospitality glazing retrofits dominate value capture. German Energy Agency enforcement of the Energy Performance of Buildings Directive compels building owners toward ceramic and spectrally selective specifications with verified savings documentation.
- Automotive:Factory-applied and aftermarket glazing treatments for passenger and commercial vehicles. Electric vehicle OEMs specify ceramic films for thermal management without 5G signal interference, with German and Swedish manufacturers leading integration.
- Marine:Yacht and commercial vessel glazing applications demanding salt corrosion resistance and optical clarity. Mediterranean shipyards in Italy and France specify professional-grade ceramic installations for superyacht segments.
Commercial applications anchor revenue concentration. Automotive integration is expanding most quickly.
Installation Type:
Volume concentration sits with professional and retrofit channels, while new construction penetration depends on specification timing relative to glazing procurement cycles.
- DIY:Consumer-applied film kits distributed through hardware retailers and e-commerce. Spanish and Italian residential markets sustain this channel through summer renovation peaks, though warranty limitations constrain commercial uptake.
- Professional:Certified installer networks delivering precision application on large-format glazing. BREEAM assessors and French national energy agencies validate these installations for warranty eligibility and public incentive qualification.
- Retro-fit:Post-construction film application to existing glazing assemblies. The EU Green Deal's building renovation mandates compress timelines across Germany and France, accelerating specification of high-performance ceramic and spectrally selective layers.
- New Construction:Factory or site-integrated film application during initial glazing installation. Triple-glazing and electrochromic smart glass competition limits film penetration in premium new-build segments.
Retro-fit channels dominate current volume. New construction represents the most contested battleground.
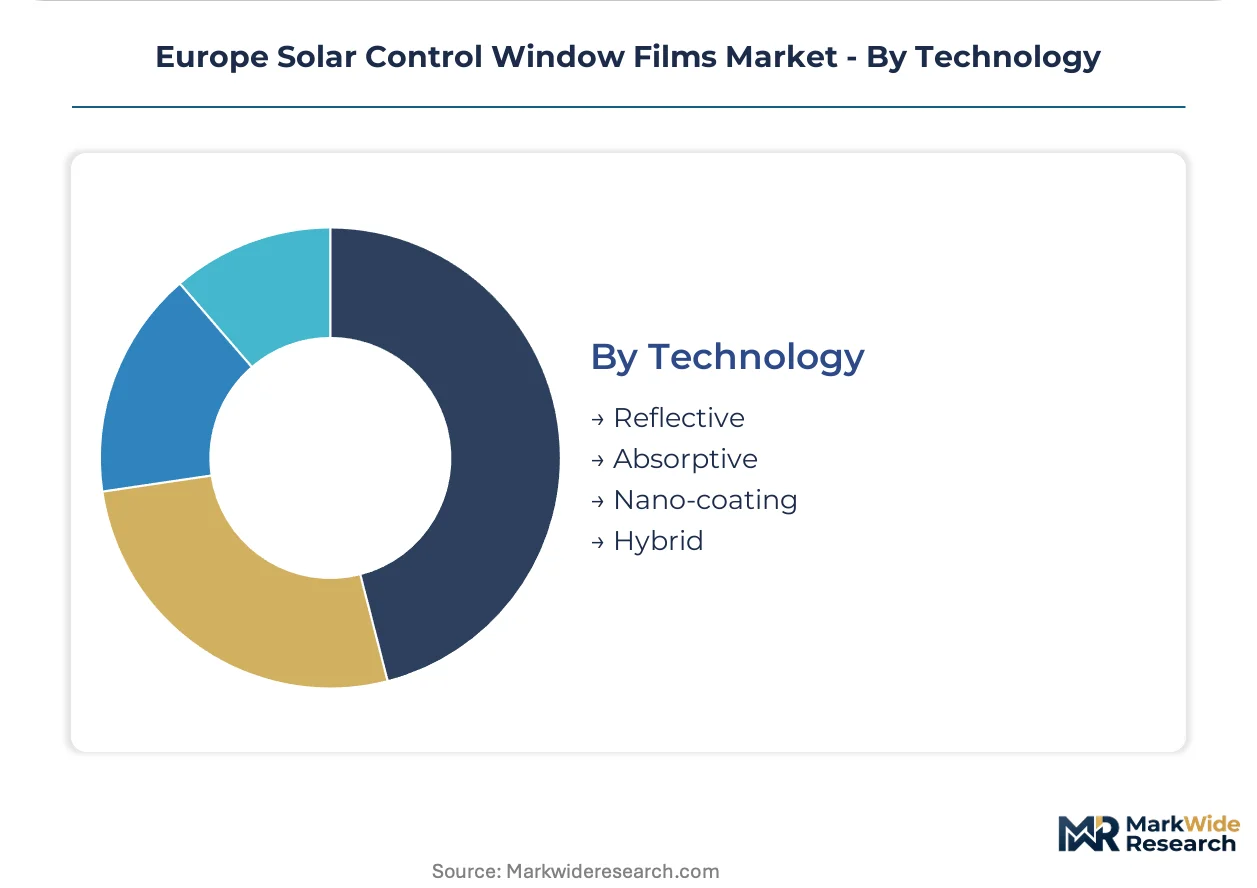
Technology:
Customer procurement patterns favor nano-coating and hybrid architectures where performance verification supports energy savings claims, while reflective technologies face substitution pressure from non-metallic alternatives.
- Reflective:Metallized interference coatings that reject solar energy through mirror-like surface reflection. Electromagnetic interference and aesthetic restrictions limit specification in connected commercial spaces and historic building renovations.
- Absorptive:Dyed or pigmented layers that convert solar energy to heat within the film substrate. Moderate performance and lower cost sustain demand in residential DIY segments despite higher thermal stress on glazing edges.
- Nano-coating:Molecular-scale ceramic or metallic oxide deposition enabling precise optical tuning. German automotive OEMs and Dutch commercial developers specify these for electric vehicle and smart building applications requiring signal transparency.
- Hybrid:Combined absorptive and reflective mechanisms within multi-layer laminates. REACH-compliant adhesive development and fluorine-free formulation advances position these for upcoming F-Gas Regulation enforcement windows.
Nano-coating architectures lead technology investment. Hybrid systems are gaining share fastest as formulators preempt regulatory compliance cliffs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commercial retrofits command pricing premiums that Italian residential channels cannot match, creating a two-tier value capture structure across the region. This asymmetry concentrates margin-rich specification work in Northern European markets while Southern Europe absorbs volume through cost-sensitive renovation cycles.
Germany
Energy Agency enforcement of the Energy Performance of Buildings Directive compels commercial building owners toward ceramic and spectrally selective specifications. The national building renovation passport scheme positions solar control films as qualifying efficiency measures for public incentive qualification. Industrial concentration clusters around the Rhine-Ruhr metropolitan region where glazing contractors serve retrofit mandates across aging office stock.
France
BREEAM assessors validate installation quality for warranty eligibility in Parisian commercial developments. The country's national energy agency tightens thermal efficiency standards through progressive regulatory enforcement. The Île-de-France region anchors specification activity where Saint-Gobain leverages float glass heritage for premium architectural contracts.
United Kingdom
London office retrofits drive spectrally selective film demand for daylighting optimization under tightening energy codes. Purlfrost Ltd operates specialized distribution networks serving commercial segments with certified installer requirements. Greater Manchester and Birmingham secondary markets expand as regional energy efficiency programs channel retrofit investment.
Netherlands
Smart commercial buildings in Amsterdam and Rotterdam specify ceramic films for electromagnetic transparency compliance. The national building code mandates progressive thermal performance upgrades that expand high-performance film specifications. Eindhoven's technology corridor generates connected building demand that eliminates metalized film deployment.
Spain
Residential renovation cycles in Madrid and Barcelona accelerate DIY channel penetration for cost-sensitive solar control applications. Mediterranean cooling load reduction drives purchase decisions without stringent regulatory enforcement. Valencia and Andalusian markets absorb dyed film inventories through seasonal hardware retail distribution.
Europe Solar Control Window Films Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers commanding premium specifications while regional installers capture retrofit volume through service proximity. The vendor base splits between multinational chemical conglomerates with polymer innovation pipelines and specialized distributors with certified installation networks. Two strategic archetypes dominate: capital-intensive integrated manufacturers leveraging float glass or chemical heritage, and agile regional specialists with vocational training pipelines. Competitive moves concentrate on REACH-compliant formulation development and professional certification program expansion.
Within the integrated manufacturer tier, Saint-Gobain Performance Plastics Corporation and Eastman Chemical Company exemplify divergent heritage advantages. The French multinational anchors premium architectural specifications through float glass lineage, while the US-based chemical conglomerate sustains polymer innovation pipelines. Purlfrost Ltd occupies a position among UK-based distribution specialists serving retrofit commercial segments through proximity-driven service models.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain Performance Plastics Corporation |
| Eastman Chemical Company |
| Purlfrost Ltd |
| Avery Dennison Israel Ltd |
| Johnson Window Films Inc. |
| Madico Inc |
| The Window Film Company |
| Solar Screen International S.A. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German glazing contractors and polyester resin suppliers lock in feedstock access while anchoring price visibility through volatile petrochemical cycles. These contracts insulate regional laminators from spot market swings that otherwise compress margins on ceramic and spectrally selective film production.
Pricing Analysis
The customization-premium spread separates configured-to-order architectural specifications from standard DIY inventories. Project-based pricing dominates commercial retrofits where BREEAM assessors validate performance claims, while transactional per-unit pricing serves Southern European residential channels. Price differentiation hinges on CE marking tier and installation certification level. Cost compression in dyed film tiers is intensifying because Asian import concentration floods price-sensitive segments. Residential DIY buyers in Spain and Italy exhibit highest price sensitivity; premium commercial specifiers in Germany and France show lowest.
Supply Chain Analysis
Rotterdam port customs clearance underwrites just-in-time delivery schedules for Continental European distributors dependent on Asian polyester substrate imports. Virgin polyester resin supply concentrates in China, South Korea, and Germany. Nano-ceramic oxide feedstock draws from Japanese and American specialty chemical producers. Single-source vulnerability in metallized coating equipment creates bottlenecks for European film laminators expanding capacity. Distribution runs through certified installer networks for commercial specifications and hardware retail channels for residential DIY.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against electrochromic smart glass substitution that threatens film retrofit economics in premium new-build segments. The window of opportunity narrows as triple-glazing advances compress addressable glazing surface area.
For Market Incumbents: Consolidate backward integration into polyester resin production to capture margin from petrochemical volatility. Acquire certified installer networks in Poland and Eastern Europe before EU cohesion funds accelerate retrofit demand. Vertical control over coating formulation protects against REACH compliance cliffs that disqualify reformulated competitors from public incentive schemes.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or France accelerates qualification for public building tenders. Target underpenetrated Polish commercial retrofits where Energy Performance of Buildings Directive enforcement lags Western markets by several retrofit cycles. Lead with ceramic film portfolios that satisfy electromagnetic transparency requirements for Amsterdam and Rotterdam smart building specifications.
For Investors and Strategic Acquirers: The market sits at a regulatory enforcement acceleration phase that favors integrated manufacturers with polymer innovation pipelines. Five-to-ten year viability rests on REACH-compliant formulation moats rather than distribution scale. Acquisition targets should demonstrate fluorine-free adhesive development progress. Monitor F-Gas Regulation revision timelines as the critical inflection signal for portfolio rebalancing between hybrid and nano-coating technology bets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captures margin from petrochemical volatility that squeezes laminator profitability. |
| Certified Installer Network Expansion | Secures warranty eligibility under BREEAM assessor validation requirements in France and Netherlands. |
| Fluorine-Free Adhesive Development | Preempts REACH compliance cliffs that threaten coating formulation continuity. |
| Poland and Eastern Europe Market Entry | Captures first-mover positioning before EU cohesion funds channel retrofit investment. |
| Automotive OEM Partnership Program | Locks in electric vehicle thermal management specifications with German and Swedish manufacturers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from chemical conglomerates, and EU regulatory enforcement records. Primary interviews engaged plant managers at film laminators, procurement leads at German glazing contractors, distribution channel partners serving Southern European hardware retail, and technical R&D directors at resin producers. Secondary validation drew from ECHA REACH registration databases, national energy agency retrofit incentive records, and BREEAM assessor certification directories. Bottom-up volume estimates triangulated against top-down addressable glazing surface calculations.
Segmentation dimensions modeled include product type hierarchy, application context, installation channel, and technology architecture across the projection horizon. CAGRs derived from regression analysis of historical retrofit penetration rates against regulatory enforcement intensity indices. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and electric vehicle production forecasts from German and Swedish OEMs.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and stable petrochemical feedstock availability; material deviation in F-Gas Regulation stringency or polyester resin supply disruption would warrant model refresh. Practitioners should keep alternative scenarios live as national building renovation passport scheme eligibility criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Global PE Films Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
United States Neoprene Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Global Cellulose Esters Market