
 Machine Automation Controllers Market | 2026-2036
Machine Automation Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Automation Controllers Market Intelligence
Certification under the IEC 61131-3 standard for programmable controllers is collapsing the distinction between high-end and mid-range suppliers. Siemens AG leverages its extensive portfolio in industrial automation to dominate complex system integrations. Rockwell Automation differentiates through its focus on connected enterprise solutions for North American manufacturers. Schneider Electric competes with its EcoStruxure platform, targeting energy efficiency in industrial processes.
Machine automation controllers are specialized digital systems designed to execute control logic for industrial machinery and processes. These units operate on real-time operating systems to manage high-speed input/output signals, ensuring precise and repeatable actions. Programmable Logic Controllers (PLCs) form the mature core of the market, while the adoption of cloud-based control technologies represents the fastest-growing segment. Demand from the manufacturing and automotive OEM end-user segments continues to command the largest share of deployments.
Compliance with standards like Europe's CE marking and safety integrity levels (SIL) dictates product design and market access. In the United States, regulations from OSHA influence the implementation of safety controllers within automated systems, while China's GB standards impose specific requirements for domestic market entry. Vendor selection will increasingly hinge on the ability to provide secure, interoperable controllers that can function seamlessly between on-premises and cloud environments.
Market Dynamics
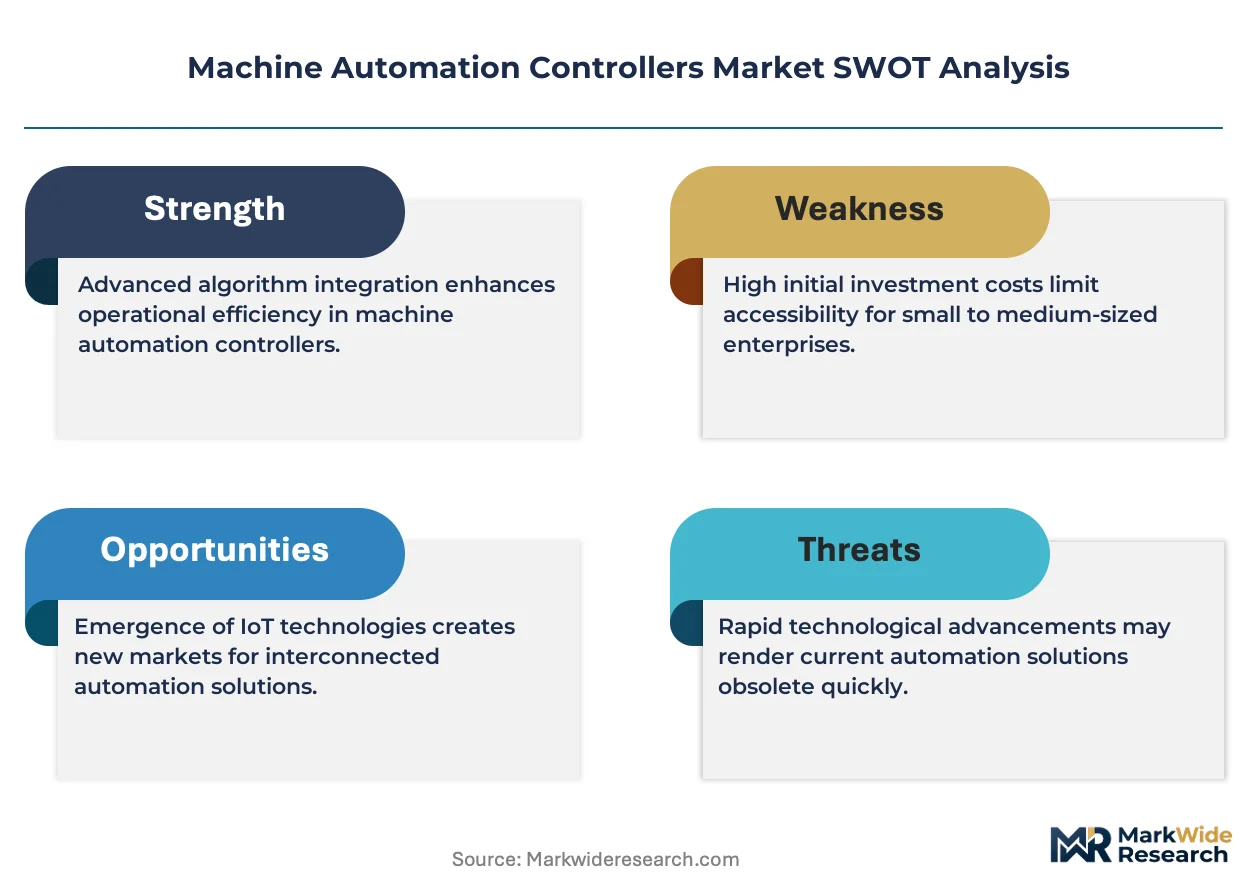
The convergence of operational technology and information technology, driven by demands for data analytics and cloud connectivity, is the central force shaping the market. This shift prioritizes software, interoperability, and security over standalone hardware performance, creating a new competitive axis.
Growth Catalysts
- Automotive Sector Demand:Precision requirements in robotics and assembly lines from automotive OEMs, especially within Germany’s advanced manufacturing clusters, necessitate adoption of high-performance motion controllers.
- Regulatory Mandates:The EU's Machinery Directive imposes stringent safety and performance standards, compelling manufacturers to upgrade to newer, compliant controllers to maintain market access.
- IIoT Proliferation:The expansion of Industrial Internet of Things platforms relies on modern controllers to collect, process, and transmit real-time operational data for enterprise-level analytics and optimization.
Market Restraints
- High Initial Cost:The significant capital expenditure required for advanced programmable automation controllers and the associated system integration services acts as a barrier for many small and medium-sized enterprises.
- Legacy System Integration:Integrating new, open-architecture controllers with existing proprietary and legacy automation systems presents substantial technical challenges, operational risks, and costs for industrial operators.
- Component Supply Concentration:A high concentration of semiconductor and specialized electronic component manufacturing in a few Asian countries creates supply chain vulnerabilities for controller hardware producers globally.
Strategic Opportunities
- Renewable Energy Sector:Developing controllers specifically for renewable energy applications, such as wind turbine pitch control and solar panel tracking systems, opens a significant new industrial vertical.
- Edge Computing Integration:Embedding edge computing capabilities directly within machine controllers enables real-time data processing and decision-making on the factory floor, creating a new premium product category.
- Geographic Expansion:India's expanding manufacturing base, stimulated by its Production Linked Incentive (PLI) scheme, offers a major growth market for mid-range and value-segment automation controllers.
Industry Challenges
- Skilled Labor Shortage:A deficit of automation engineers and technicians with combined expertise in OT programming standards like IEC 61131-3 and modern IT cybersecurity practices complicates system deployment and maintenance.
- Cybersecurity Vulnerability:Increased connectivity of controllers to enterprise networks and the cloud exposes critical industrial assets to a wider range of cyber threats, demanding more sophisticated security protocols.
- Interoperability Hurdles:Achieving seamless plug-and-play functionality between controllers from different vendors remains a persistent challenge, despite standardization efforts with protocols like OPC UA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Automation Controllers Market |
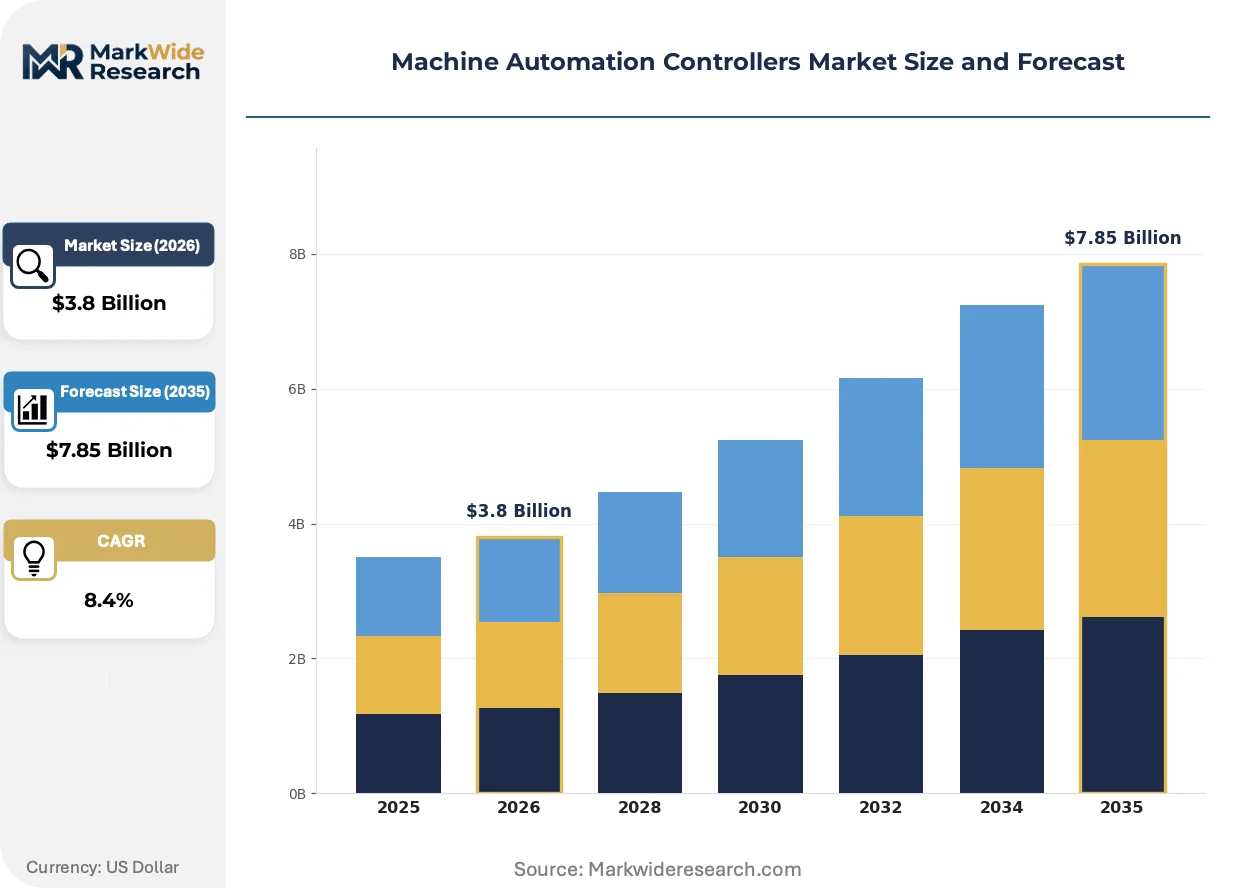
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Motion Controllers, Safety Controllers, Supervisory Controllers Technology: Distributed Control Systems, Embedded Control, Cloud-Based Control, Hybrid Control End User: Manufacturing, Oil & Gas, Automotive OEMs, Pharmaceuticals Installation: On-Premises, Remote, Integrated, Standalone |
| Companies Covered | Rockwell Automation, Siemens AG, Schneider Electric, ABB Ltd., Emerson Electric, Honeywell International Inc., Mitsubishi Electric Corporation, Yokogawa Electric Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Automation Controllers Market Strategic Shifts & Innovations
Software-defined functionality is fundamentally altering the market's value proposition. The emphasis is shifting from the physical controller to the intelligence, connectivity, and data services it enables, which is reshaping vendor business models and the expectations of industrial end-users.
Cloud-based control technology, which hosts logic execution in remote data centers, is seeing initial adoption. Industrial operators are using this for non-critical supervisory and monitoring tasks before committing to real-time process control. This adoption pattern is fragmenting the traditional control hierarchy, creating a hybrid architecture where on-premise controllers work alongside cloud services.
Europe's proposed AI Act is introducing risk-based requirements for artificial intelligence systems. This legislation directly impacts the development of AI-enabled controllers used in adaptive manufacturing and predictive maintenance applications. Controller vendors targeting the EU market must now build robust compliance frameworks addressing algorithmic transparency, data governance, and risk mitigation.
A pivot away from single-vendor proprietary ecosystems towards open-architecture systems is gaining momentum. End-users increasingly specify controllers that support standards like OPC UA to avoid vendor lock-in and enable flexible, best-of-breed system integration. This shift is most visible in the consumer packaged goods and food and beverage sectors where production agility is critical.
Machine Automation Controllers Market Segmentation
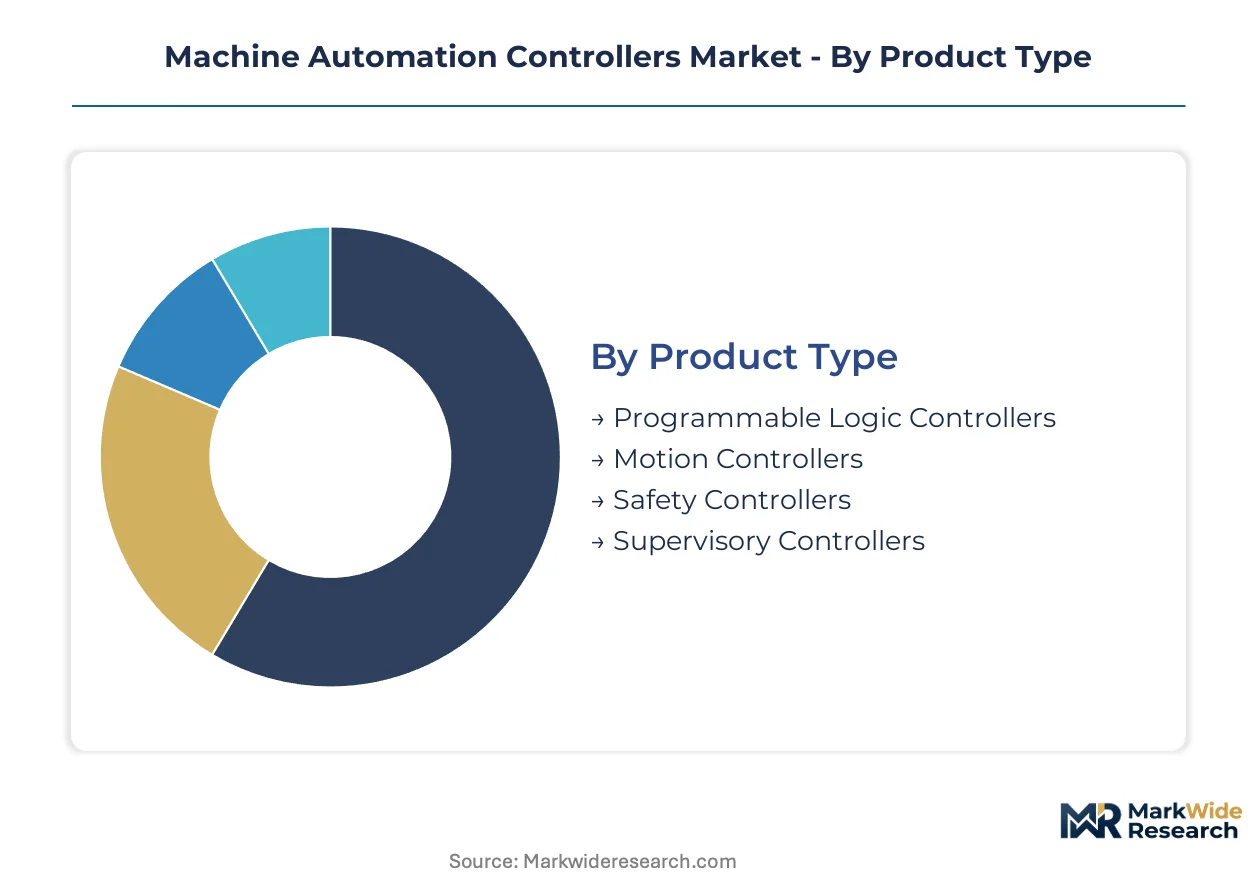
Segmentation of the machine automation controllers market provides a granular view of diverse product applications and technological adaptations. This detailed breakdown helps identify specific growth vectors and areas requiring specialized solutions. Understanding these distinct segments is crucial for manufacturers to tailor offerings and for end-users to optimize system procurement.
Product Type:
The channel mix for machine automation controllers varies significantly by product type, reflecting specialized distribution networks and direct sales strategies.
- Programmable Logic Controllers:These controllers execute control logic for industrial machinery using ladder logic or structured text programming. Manufacturing operations in Germany use PLCs extensively for process automation and discrete control.
- Motion Controllers:Motion controllers manage precise movements of robotic arms and other mechanical components in automated systems. Automotive OEMs in the United States demand these for high-speed assembly line robotics and synchronized production.
- Safety Controllers:Safety controllers implement critical safety functions, adhering to standards like Europe's CE marking and Safety Integrity Levels.
- Supervisory Controllers:Supervisory controllers coordinate multiple lower-level devices, often integrating with SCADA systems for plant-wide oversight and data aggregation.
By volume, Programmable Logic Controllers lead. By growth pace, Motion Controllers are expanding most quickly due to robotics advancements.
Technology:
Different technology approaches dictate the complexity and deployment models available for industrial automation, influencing system architecture and scalability.
- Cloud-Based Control:Cloud-based control hosts logic execution and data processing in remote data centers, leveraging internet connectivity for distributed operations. Manufacturing enterprises in China are exploring this for non-critical supervisory tasks and data analytics to optimize operations.
- Hybrid Control:Hybrid control combines on-premises hardware with cloud services, balancing real-time needs with scalability and data analytics capabilities. North American manufacturers adopt hybrid models to integrate legacy systems with modern IIoT platforms for enterprise-level analytics.
- Distributed Control Systems:Distributed Control Systems manage large-scale industrial processes across multiple interconnected control loops, ensuring robust and redundant operation.
- Embedded Control:Embedded control integrates processing capabilities directly into machinery, enabling localized decision-making and rapid response for specific functions.
Profitability varies significantly among these technologies, with Cloud-Based Control offering new revenue streams through subscription models and data services.
End User:
Customer types vary widely, influencing procurement cycles and technical specifications for machine automation controllers across different industrial applications.
- Automotive OEMs:Automotive OEMs require high-performance controllers for precision robotics, assembly line synchronization, and stringent quality control systems. Germany's automotive clusters drive demand for advanced motion controllers to maintain high production standards and comply with EU regulations.
- Manufacturing:The broader manufacturing sector uses controllers for diverse applications, including material handling, packaging, and general process automation. India's expanding manufacturing base, stimulated by its Production Linked Incentive (PLI) scheme, represents a significant growth market for mid-range automation controllers.
- Oil & Gas:The Oil & Gas sector utilizes robust controllers for process optimization, safety monitoring, and remote asset management in harsh and geographically dispersed environments.
- Pharmaceuticals:Pharmaceutical companies deploy controllers for precise batch processing, regulatory compliance, and validation in sterile production facilities, ensuring product integrity.
Supply concentration for end-user specific solutions is often driven by specialized technical requirements and rigorous regulatory compliance demands.
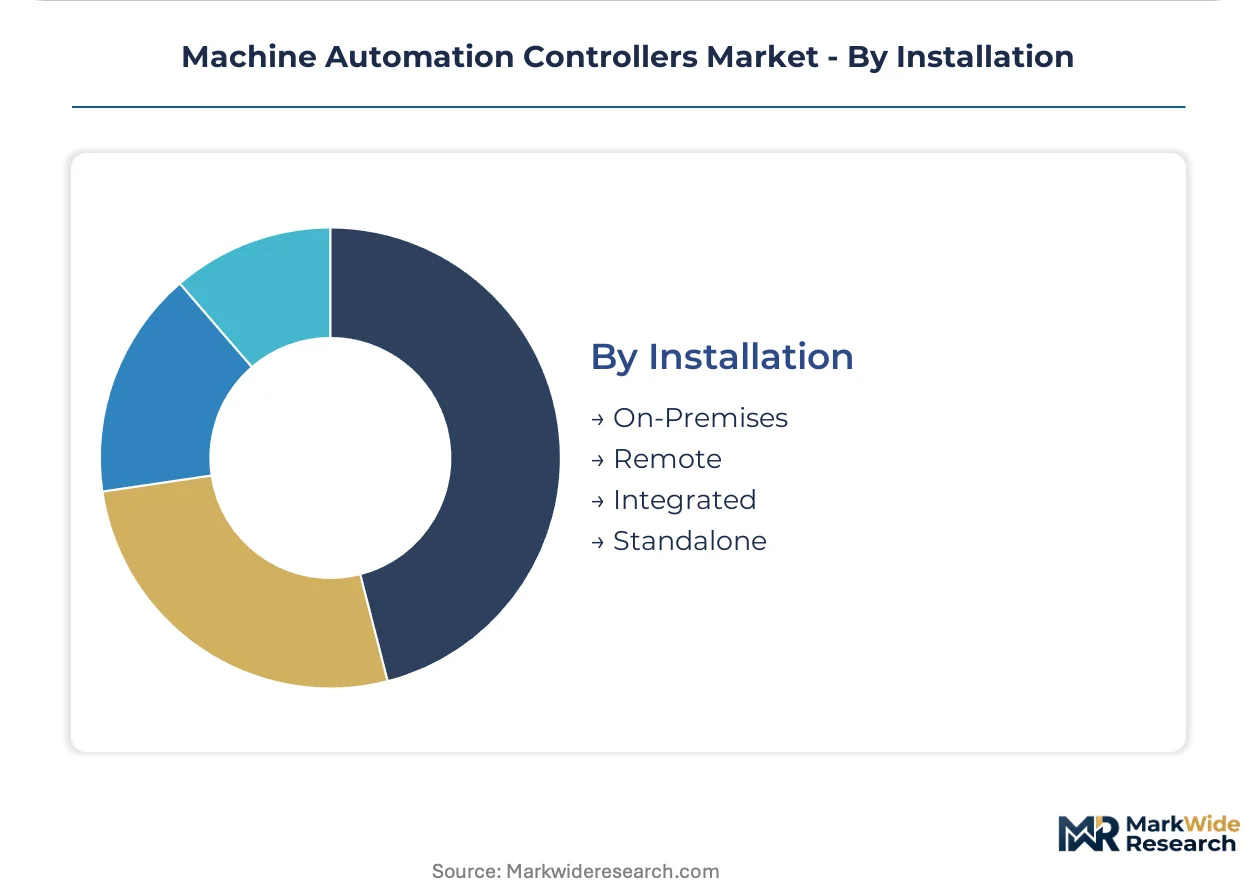
Installation:
The maturity of installation approaches dictates the infrastructure requirements and scalability for automation controller deployments, from localized to globally distributed systems.
- On-Premises:On-premises installations involve physical controllers deployed directly within the factory or plant, managed locally by dedicated IT/OT teams. Traditional manufacturing facilities in the United States continue to rely on on-premises systems for critical real-time control and data sovereignty.
- Integrated:Integrated installations embed controllers directly into machinery or larger control systems, providing seamless functionality and reducing external wiring. Advanced manufacturing in Japan frequently employs integrated controllers for compact, high-performance machine designs and complex automation cells.
- Remote:Remote installations allow control and monitoring of machinery from a distant location, often leveraging cloud or edge computing infrastructure for operational flexibility.
- Standalone:Standalone controllers operate independently for specific tasks, offering flexibility for smaller applications or discrete machine control where integration is not a primary concern.
Cost efficiency per installation type varies, with standalone solutions offering lower initial investment compared to complex integrated systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's robust industrial infrastructure underwrites Europe's strong position in machine automation controllers. This market sees significant adoption driven by precision manufacturing demands and evolving regulatory landscapes. Key countries leverage specific policies and industrial clusters to propel controller deployment.
Germany
Germany's advanced manufacturing clusters demand high-performance motion controllers for precision robotics and assembly line control. The EU's Machinery Directive compels manufacturers to upgrade to compliant systems, ensuring market access. Bavaria's industrial heartland, for example, consistently drives innovation in automated production processes.
United States
North American manufacturers require advanced controllers for connected enterprise solutions and real-time control in traditional facilities. OSHA regulations significantly influence the implementation of safety controllers within automated systems. The automotive manufacturing hubs in Michigan continue to drive demand for integrated and high-performance control units.
China
China's expansive manufacturing base explores cloud-based control for non-critical supervisory tasks and operational data analytics. Compliance with China's GB standards imposes specific requirements for domestic market entry and product design. Industrial zones in the Yangtze River Delta actively adopt modern controllers to enhance production efficiency.
India
India's expanding manufacturing base drives demand for mid-range and value-segment automation controllers. The Production Linked Incentive (PLI) scheme stimulates domestic production, creating a significant market for these systems. Industrial corridors in Maharashtra are witnessing substantial deployments of controllers for diverse manufacturing applications.
Japan
Japan's advanced manufacturing sector frequently employs integrated controllers for compact, high-performance machine designs and complex automation cells. Adherence to JIS standards ensures quality and interoperability across various industrial applications. The Kanto region's technology clusters are at the forefront of developing sophisticated embedded control solutions.
Machine Automation Controllers Market Key Industry Players
Listed leaders compete with private specialists across the machine automation controllers market, which exhibits a tiered structure. The landscape is characterized by a few major global players dominating complex system integrations and numerous niche providers serving specialized applications. Strategic archetypes include integrated automation providers, software-centric innovators, and hardware specialists. Companies pursue strategic partnerships and portfolio diversification to enhance their market reach and solution offerings.
Integrated automation providers like Siemens AG exemplify a broad portfolio approach, anchoring complex system integrations across diverse industries. Rockwell Automation, a North American-based corporation, occupies a position focused on connected enterprise solutions for regional manufacturers. Schneider Electric, a global energy management and automation specialist, represents a strong emphasis on energy efficiency platforms for industrial processes. These entities leverage their established market presence to influence technology standards and adoption patterns.
| Leading Market Players |
|---|
| Rockwell Automation |
| Siemens AG |
| Schneider Electric |
| ABB Ltd. |
| Emerson Electric |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Yokogawa Electric Corporation |
| Omron Corporation |
| Others |
Cost & Logistics Intelligence
Cloud-based control replacing traditional hardware components simultaneously reshapes supply geography towards software development hubs and alters pricing economics from upfront capital expenditure to recurring subscription models. This transformation redefines value capture and distribution across the ecosystem.
Pricing Analysis
Certification level, particularly adherence to Safety Integrity Levels (SIL) and CE marking, creates the primary spread in machine automation controller pricing. The dominant pricing structure combines per-unit transactional sales for hardware with subscription-based models for associated software services and cloud connectivity. Price differentiation stems from advanced software features, the level of integration services offered, and brand reputation. Pricing pressure intensifies on basic PLC hardware due to commoditization and increased competition from software-defined functionalities. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity, while large automotive OEMs prioritize performance and compliance over cost.
Supply Chain Analysis
Just-in-time manufacturing principles guide component procurement for machine automation controllers, balancing cost efficiency with responsiveness. Geographic supply concentration for critical components centers on East Asia, with Taiwan and China dominating semiconductor and specialized electronic component manufacturing. Key raw material dependencies include rare earth elements for motion controller magnets and various semiconductors for processing units. A structural supply chain risk involves the high concentration of component manufacturing, creating vulnerability to geopolitical events or natural disasters. Distribution runs primarily through direct sales channels for complex integrated systems, supplemented by a network of specialized channel partners for mid-range and standalone controllers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase, primarily driven by renewed industrial capital expenditure following global economic stabilization. Manufacturers are upgrading legacy systems, fostering demand for advanced automation solutions.
For Market Incumbents:
Compound existing market leadership by aggressively investing in secure, interoperable cloud-edge architectures that bridge operational technology and information technology. Acquire specialized software-centric innovators to integrate advanced analytics and AI capabilities, mitigating the threat from open-architecture systems and cloud-native solutions. Reinforce compliance expertise for evolving regulatory landscapes like Europe's AI Act, ensuring market access. Develop robust cybersecurity protocols to protect connected industrial assets from escalating cyber threats.
For New Entrants and Emerging Players:
Anchor in niche applications with high growth potential, such as renewable energy sector controllers for wind turbine pitch control or specialized solutions for India's expanding manufacturing base. Target the mid-range and value-segment automation controllers by offering flexible, subscription-based cloud control solutions for non-critical supervisory tasks. Focus on interoperability standards like OPC UA to reduce integration hurdles for end-users. Provide strong technical support and localized services to build trust in new markets.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors software-centric innovators and providers of integrated cloud-edge solutions. Long-term viability remains strong, driven by the persistent demand for manufacturing efficiency and digital transformation over the next decade. Identify acquisition targets specializing in embedded edge computing capabilities, AI-enabled control software, or cybersecurity for industrial control systems. The signal to watch for inflection is the widespread adoption of cloud-based control for real-time process management beyond monitoring tasks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate control systems, enhancing operational efficiency and data visibility for end-users. |
| Software-Defined Functionality | Shifts value from hardware to flexible, upgradeable software, enabling adaptive manufacturing processes. |
| Edge Computing Investment | Embeds real-time data processing closer to machines, reducing latency for critical control decisions. |
| Geographic Expansion (India) | Captures demand from India's growing manufacturing sector, leveraging its Production Linked Incentive scheme. |
| Cybersecurity Enhancement | Protects critical industrial assets from cyber threats, ensuring operational continuity and data integrity. |
Research Approach
The analysis maps key sub-sectors including Programmable Logic Controllers, Motion Controllers, and Safety Controllers, each validated through extensive primary interviews with industry experts and automation engineers. This process combines insights from OEMs, system integrators, and plant managers with secondary data from regulatory bodies like OSHA and the EU's Machinery Directive. Bottom-up data from end-user segments is triangulated with top-down market sizing for comprehensive validation.
Outputs were validated for consistency against macroeconomic indicators and industrial production indices across the analysis window. The analytical framework integrated historical data with forward-looking projections, segmenting the market by product type, technology, end-user, installation type, and regional manufacturing output. Compound annual growth rates were derived from a detailed assessment of market drivers, restraints, and competitive intensity. Industrial capital expenditure trends and IIoT adoption rates served as critical forecast inputs.
Material uncertainties — geopolitical shifts, semiconductor supply disruptions, and rapid regulatory changes — sit outside the modeled envelope, reflecting forecasts based on current market conditions. Global economic downturns or unforeseen supply chain shocks represent significant risk factors. Revision becomes warranted when significant shifts in manufacturing investment or regulatory frameworks cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
North America Process Automation Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Asia Pacific Industrial Communication Market