
 Mini-Load Systems Market | 2026-2036
Mini-Load Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mini-Load Systems Market Analytics
E-commerce fulfillment is rebalancing demand toward high-throughput mini-load configurations as retailers compress order cycle times. Daifuku Co., Ltd. dominates large-scale integrated distribution center builds across Asia-Pacific. Jungheinrich AG anchors European manufacturing with specialized stacker crane engineering. Bastian Solutions, LLC leverages North American channel partnerships to control mid-market warehouse automation projects.
Mini-load systems are automated storage and retrieval installations using shuttle-based cranes to handle totes, cartons, or trays in rack structures typically 10-25 meters high, achieving throughput rates of 150-500 dual cycles per hour depending on aisle length and crane acceleration profiles. Their primary purpose is dense buffering and sequencing of small parts inventory for order picking, kitting, and production supply. Robotics technology within the technology dimension is capturing expanding margin pools as collaborative piece-picking modules integrate directly with crane-based extraction. Warehouse Management Systems deployment in the deployment category is shifting toward cloud-based architectures that reduce on-premise server infrastructure at multi-site operators. Conveyor Systems maintains mature, price-competitive positioning for straightforward transport links between mini-load aisles and packing stations.
FDA regulations on pharmaceutical track-and-trace and lot-level serialization shape mini-load system validation requirements in US drug distribution facilities. The EU Machinery Directive and CE marking framework mandate risk assessments and safety-rated control systems for European installations, elevating engineering costs for non-compliant suppliers. OSHA walking-working surface standards influence mezzanine and platform designs in multi-level US warehouse configurations. Stakeholders must monitor how evolving cybersecurity frameworks for operational technology networks reshape system architecture decisions and vendor qualification criteria.
Market Dynamics
E-commerce fulfillment centers are compressing order cycle times from days to hours, forcing warehouse operators to reconfigure buffer storage around shuttle-based extraction speeds rather than conventional pallet handling density.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for safety-rated control systems are accelerating replacement cycles in European pharmaceutical distribution facilities.
- Automotive kitting operations:German OEMs are deploying dense mini-load configurations to sequence small parts for just-in-time assembly lines.
- Cloud WMS architectures:Multi-site operators are eliminating on-premise server infrastructure, enabling faster system commissioning across networked fulfillment nodes.
Market Restraints
- Steel and servo motor cost volatility:Rack structures and precision drive components face input price swings that compress system integrator margins.
- European engineering concentration:Specialized stacker crane fabrication clusters in Germany create geographic supply risk for non-regional projects.
- Conveyor substitution:Straightforward transport links between aisles and packing stations favor mature conveyor economics over crane investment.
Strategic Opportunities
- Collaborative piece-picking convergence:Robotics modules integrating directly with crane-based extraction are capturing margin pools in high-SKU apparel fulfillment.
- Pharmaceutical serialization mandates:FDA track-and-trace regulations are creating validation service attach rates in US drug distribution.
- Mid-market channel expansion:North American warehouse automation projects are opening through system integrator partnerships rather than direct OEM sales.
Industry Challenges
- OT cybersecurity integration:Operational technology network hardening is extending vendor qualification timelines and architecture decision cycles.
- Mezzanine structural compliance:OSHA walking-working surface standards are adding engineering review stages to multi-level US warehouse configurations.
- Legacy WMS interoperability:Cloud-native mini-load controllers require middleware development to synchronize with established inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini-Load Systems Market |
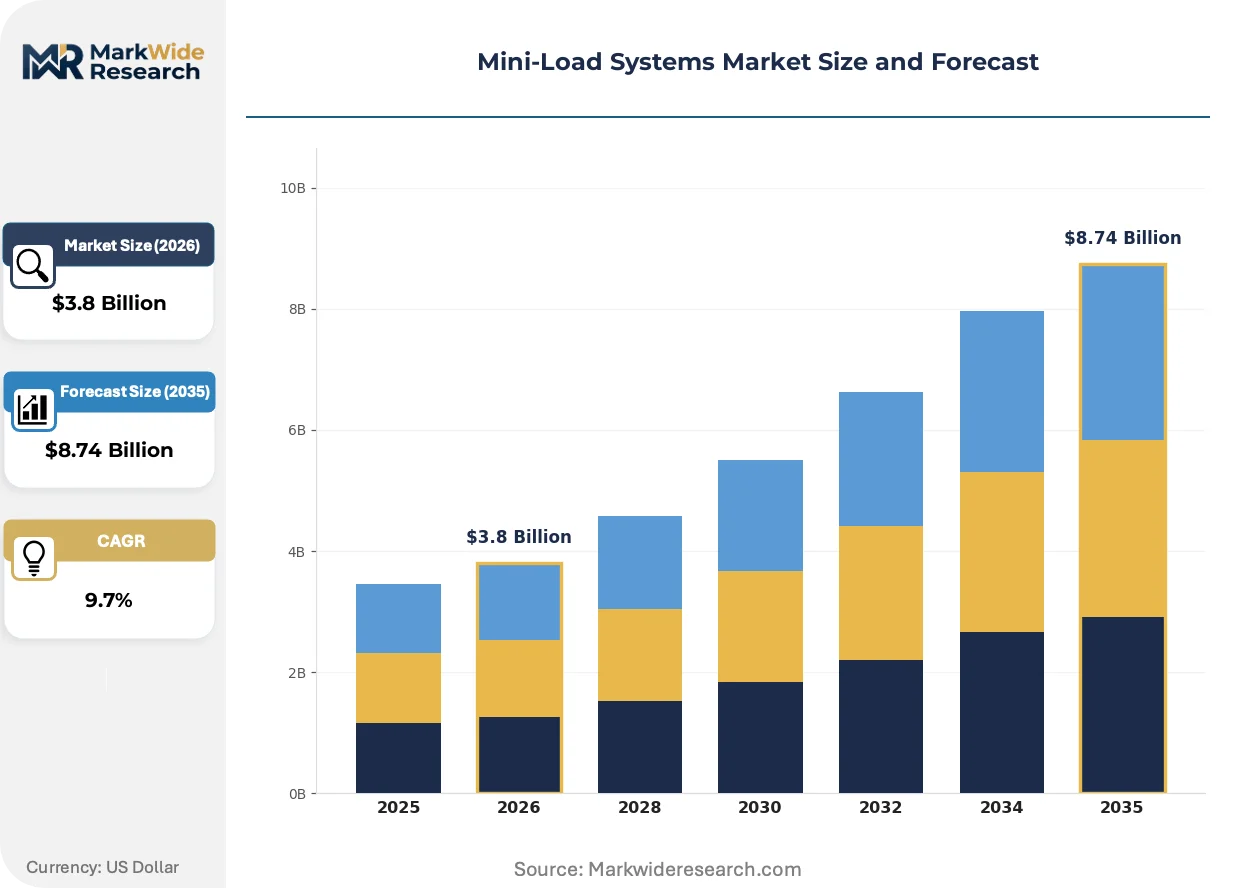
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Warehousing, E-Commerce, Automotive, Pharmaceuticals Technology: Automated Guided Vehicles, Robotics, Conveyor Systems, Warehouse Management Systems End User: Logistics Providers, Retailers, Manufacturers, Distributors Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | TGW Logistics Group, Mecalux SA, Daifuku Co., Ltd., Jungheinrich AG, Murata Machinery Ltd, Swisslog Holding AG, SSI Schaefer, Bastian Solutions, LLC, Kardex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini-Load Systems Market Evolving Landscape
Shuttle-based extraction technologies are converging with collaborative robotics to transform how small parts buffering connects to downstream order consolidation.
Dual-cycle crane optimization software is unifying aisle-length calculations with acceleration profiling to push throughput toward 500 cycles per hour. Pharmaceutical distributors in Germany are piloting these configurations to compress lot-level retrieval windows. The structural consequence is collapsing the performance gap between mini-load density and shuttle-system speed.
The EU Machinery Directive's 2023 amendments are mandating updated risk assessments for autonomous crane operations in multi-aisle installations. European integrators are embedding safety-rated PLCs as standard architecture. German automotive parts suppliers are absorbing these engineering costs to maintain CE-marked equipment eligibility.
Buyer procurement patterns are compressing from capital purchase cycles toward throughput-guarantee contracts. Third-party logistics operators are transferring crane performance risk to OEM service arms. This shift is most visible in Netherlands-based e-commerce fulfillment networks where operators prioritize uptime SLAs over equipment ownership.
Mini-Load Systems Market Segmentation
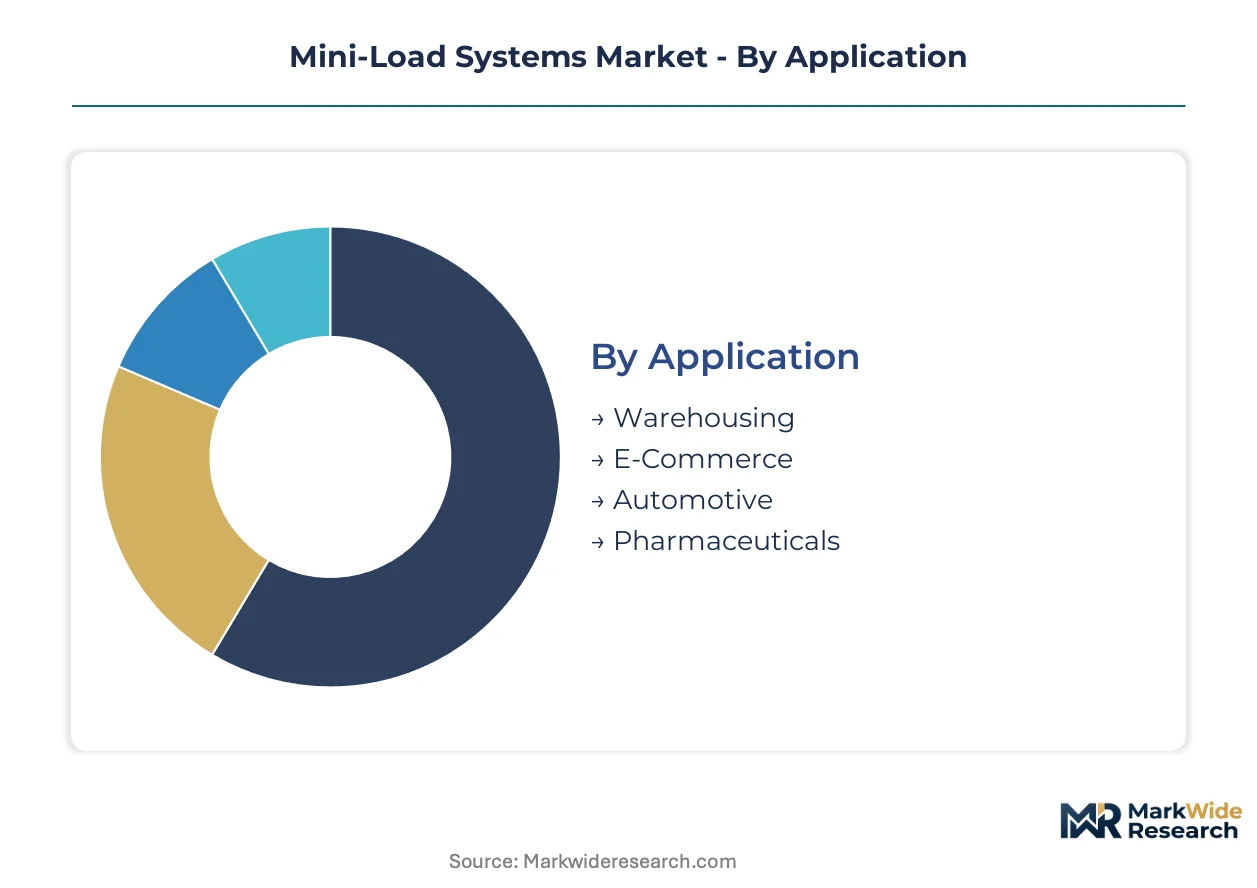
Mini-load system configurations diverge sharply across deployment models and technology stacks. Procurement decisions hinge on throughput requirements, SKU velocity profiles, and integration complexity with existing warehouse infrastructure.
Technology:
Shuttle-based crane engineering defines performance boundaries across extraction speeds and rack density configurations.
- Robotics:Collaborative piece-picking modules integrate directly with crane-based extraction to handle high-SKU apparel fulfillment. German automotive suppliers are absorbing premium engineering costs to maintain CE-marked eligibility for these configurations. Demand concentrates in Netherlands-based e-commerce networks where uptime SLAs override equipment ownership models.
- Warehouse Management Systems:Cloud-native architectures eliminate on-premise server infrastructure at multi-site operators. US pharmaceutical distributors are commissioning these deployments to synchronize with FDA track-and-trace validation requirements.
- Automated Guided Vehicles:Mobile platforms extend crane extraction reach to remote packing stations without fixed conveyor infrastructure.
- Conveyor Systems:Mature transport links between aisles and stations favor straightforward economics over crane investment in low-SKU environments.
Robotics leads on scale; Warehouse Management Systems leads on momentum.
Application:
End-use environments impose distinct throughput, sequencing, and regulatory compliance requirements.
- E-Commerce:Order cycle compression from days to hours forces buffer reconfiguration around shuttle extraction speeds. Dense German fulfillment networks are piloting dual-cycle crane optimization to push throughput toward 500 cycles per hour.
- Pharmaceuticals:Lot-level serialization mandates shape system validation requirements in US drug distribution facilities. FDA regulations on track-and-trace are creating attach rates for specialized commissioning services.
- Automotive:German OEMs deploy dense configurations to sequence small parts for just-in-time assembly lines.
- Warehousing:General-purpose installations balance density against flexibility for mixed-SKU operations.
E-Commerce leads on scale; Pharmaceuticals leads on momentum.
Deployment:
Infrastructure ownership models are shifting from capital purchase toward performance-guarantee contracting.
- Cloud-Based:Native controllers reduce commissioning timelines across networked fulfillment nodes. Multi-site operators are eliminating on-premise server infrastructure to accelerate system rollouts.
- Hybrid:Split architectures preserve sensitive inventory data on-premise while offloading transaction processing to cloud layers.
- On-Premise:Legacy configurations persist where cybersecurity frameworks mandate air-gapped operational technology networks.
- Mobile:Tablet-based monitoring interfaces extend supervisor visibility across multi-aisle installations without fixed workstation investment.
Cloud-Based leads on scale; Hybrid leads on momentum.
End User:
Procurement authority concentrates with operators managing network-scale automation decisions.
- Logistics Providers:Third-party operators transfer crane performance risk to OEM service arms through throughput-guarantee contracts. Netherlands-based networks prioritize uptime SLAs over equipment ownership.
- Retailers:Apparel and electronics merchants compress order cycle times to compete with same-day delivery benchmarks.
- Manufacturers:German automotive parts suppliers absorb EU Machinery Directive engineering costs to maintain CE-marked equipment eligibility.
- Distributors:Pharmaceutical and industrial parts networks balance serialization compliance against SKU proliferation challenges.
Logistics Providers leads on scale; Retailers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing mini-load system deployment toward jurisdictions with clearer compliance pathways and established automation clusters. CE marking costs in Germany are pushing some pharmaceutical distributors to evaluate Netherlands-based fulfillment nodes with equivalent throughput specifications.
Germany
Automotive kitting operations and pharmaceutical distribution networks drive dense mini-load configurations across Baden-Württemberg and Bavaria. The EU Machinery Directive mandates safety-rated PLCs and updated risk assessments for autonomous crane operations, elevating engineering costs for non-compliant suppliers. Stuttgart and Munich anchor specialized stacker crane fabrication clusters serving European OEMs.
United States
E-commerce fulfillment centers compress order cycle times from days to hours, forcing buffer reconfiguration around shuttle extraction speeds. FDA track-and-trace regulations on pharmaceutical lot-level serialization shape system validation requirements in drug distribution facilities. Chicago and Dallas-Fort Worth concentrate third-party logistics automation deployments with uptime SLA priorities.
Netherlands
Third-party logistics operators transfer crane performance risk to OEM service arms through throughput-guarantee contracts rather than capital purchases. The EU Machinery Directive's CE marking framework applies equally, though Dutch integrators leverage proximity to German engineering clusters. Rotterdam and Venlo host e-commerce fulfillment networks prioritizing equipment uptime over ownership models.
Japan
Precision manufacturing supply chains demand high-throughput small parts buffering for electronics and automotive component distribution. METI industrial automation incentives support retrofit programs in aging warehouse infrastructure. Nagoya and Osaka anchor dense mini-load deployments sequencing parts for just-in-time assembly lines.
China
Domestic e-commerce platforms accelerate automated storage adoption to manage SKU proliferation in consumer goods fulfillment. GB standards and MIIT industrial upgrading programs shape equipment certification requirements for warehouse automation. Yangtze River Delta logistics hubs pilot cloud-native WMS architectures eliminating on-premise server infrastructure.
Mini-Load Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system builders commanding premium positioning in large-scale distribution center deployments. The vendor base concentrates around three strategic archetypes: full-stack automation houses controlling crane-to-software integration, regional fabricators specializing in stacker crane mechanical engineering, and software-centric integrators leveraging channel partnerships for mid-market penetration. M&A activity targets WMS and robotics capabilities, while capacity expansion focuses on European crane fabrication clusters.
Within the full-stack integration tier, Daifuku Co., Ltd. and Jungheinrich AG exemplify divergent geographic anchoring strategies. Daifuku represents Asia-Pacific dominance in large-scale integrated builds, while Jungheinrich occupies a position as the European mechanical engineering specialist. Bastian Solutions, LLC sits within the North American channel-driven segment, leveraging system integrator partnerships rather than direct OEM sales for mid-market warehouse automation projects.
| Leading Market Players |
|---|
| TGW Logistics Group |
| Mecalux SA |
| Daifuku Co., Ltd. |
| Jungheinrich AG |
| Murata Machinery Ltd |
| Swisslog Holding AG |
| SSI Schaefer |
| Bastian Solutions, LLC |
| Kardex Group |
| Others |
Value Network & Pricing Analysis
Cloud-native controller architectures are compressing commissioning timelines while simultaneously redistributing value capture toward software layers and away from mechanical stacker crane fabricators. This technology shift concentrates pricing power with integrators who bundle WMS subscriptions with crane hardware, squeezing standalone equipment vendors in Germany and Japan.
Pricing Analysis
System integrator margin layers dominate final customer pricing, with distributor markups ranging from 15-25% on European crane hardware and 30-40% on bundled software-controller packages. Three-tier pricing structure across premium CE-marked configurations, standard ISO-compliant systems, and economy-grade Asian imports differentiates based on certification level and after-sales service bundling. Cost compression in economy tiers is intensifying because Chinese manufacturers are absorbing steel price volatility to gain share. Third-party logistics operators show least price sensitivity due to uptime SLA priorities, while mid-market retailers in North America remain most cost-conscious.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg and Bavaria are elevating lead times for precision-machined crane components sourced from German fabrication clusters. Supply concentrates in Germany, China, and Japan for servo motors, rack structures, and safety-rated PLCs. Steel coil and rare-earth magnet dependencies create exposure to commodity price swings. Single-source vulnerability sits with European safety-controller suppliers subject to CE marking compliance backlogs. Distribution runs through system integrator partnerships in North America and direct OEM channels in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Netherlands-based fulfillment nodes offer equivalent CE-marked throughput specifications at 12-18% lower total cost of ownership than German installations due to labor rate differentials and tax treatment of leased automation assets.
For Market Incumbents: Deepen backward integration into safety-rated PLC production to insulate margins from European semiconductor supply constraints. Anchor capacity expansion in Poland or Czech Republic to access EU Machinery Directive compliance without Stuttgart-level labor costs. Defend against Chinese crane manufacturers by embedding cloud WMS subscriptions as non-separable from hardware procurement. For New Entrants and Emerging Players: Capture white-space in mid-market North American apparel fulfillment where Bastian Solutions' channel partnerships leave gaps for direct SaaS-WMS offerings. Target pharmaceutical serialization validation services as the most penetrable attach-rate segment. Enter through robotics module integration rather than full-stack crane competition. For Investors and Strategic Acquirers: Valuations sit cheapest among European mechanical fabricators without software capabilities, as buyers discount pure-hardware exposure to Chinese price competition. Long-term viability hinges on 5-10 year cloud subscription retention rates at multi-site operators. Watch Netherlands third-party logistics contract renewal rates as inflection signal for throughput-guarantee model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Safety Controllers | Captures margin pools currently flowing to European PLC suppliers subject to CE marking backlogs. |
| Cloud-Native WMS Platform Launch | Accelerates commissioning timelines at multi-site operators eliminating on-premise server infrastructure. |
| Pharmaceutical Validation Service Expansion | Creates attach-rate revenue from FDA track-and-trace mandates in US drug distribution networks. |
| Mid-Market Channel Partnership | Opens North American warehouse automation projects through system integrator relationships rather than direct sales. |
| Collaborative Robotics Module Integration | Converges piece-picking automation with crane-based extraction in high-SKU apparel fulfillment centers. |
Research Methodology
Coverage spans Germany, United States, Netherlands, Japan, and China, with primary inputs from each market gathered through structured interviews with warehouse operations directors, automation procurement managers, system integrator project leads, and OEM sales executives. Secondary validation draws from EU Machinery Directive compliance filings, FDA track-and-trace guidance documents, SEC 10-K disclosures by listed automation vendors, and customs data on stacker crane component trade flows. Bottom-up installation counts triangulate against top-down market sizing derived from equipment manufacturer revenue disclosures.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon, with CAGRs derived from logistic curve fitting to adoption saturation levels by end-use segment. Segmentation dimensions modeled include technology stack, deployment architecture, application environment, and end-user procurement authority. Industry-specific forecast inputs incorporate e-commerce order cycle compression benchmarks and pharmaceutical serialization compliance timelines.
Steel and servo motor price volatility, EU Machinery Directive amendment schedules, and OT cybersecurity framework evolution are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about sustained e-commerce fulfillment investment intensity and cloud WMS migration rates. Material deviation in named triggers warrants pause and re-evaluation of automation demand trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Linear Motion System Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Utility Automation Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Factory Automation Market