
 North America Process Automation Market | 2026-2036
North America Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Process Automation Market Analytics
Mexico's manufacturing corridor is narrowing the automation deployment gap with U.S. and Canadian peers as nearshoring accelerates capital expenditure. Emerson Electric Co. sustains deep relationships with Gulf Coast petrochemical operators through its DeltaV platform specialization. Rockwell Automation, Inc. dominates discrete-to-process hybrid applications in food and beverage packaging lines. Honeywell International Inc. controls the largest installed base of legacy DCS migrations across North American refineries.
Process automation encompasses the integrated hardware, software, and instrumentation systems that monitor, control, and optimize continuous and batch manufacturing operations, typically achieving response times under 100 milliseconds for critical loop control. These systems execute regulatory control, advanced process control, and safety instrumented functions to maximize throughput while enforcing operational constraints. Distributed Control Systems retain the largest revenue share among product types due to decades-long replacement cycles in oil and gas infrastructure. Edge Computing deployment models are expanding fastest as latency-sensitive applications bypass cloud round-trips for local inference. Manufacturing Execution Systems capture disproportionate margin pools in pharmaceuticals, where FDA validation requirements create switching costs.
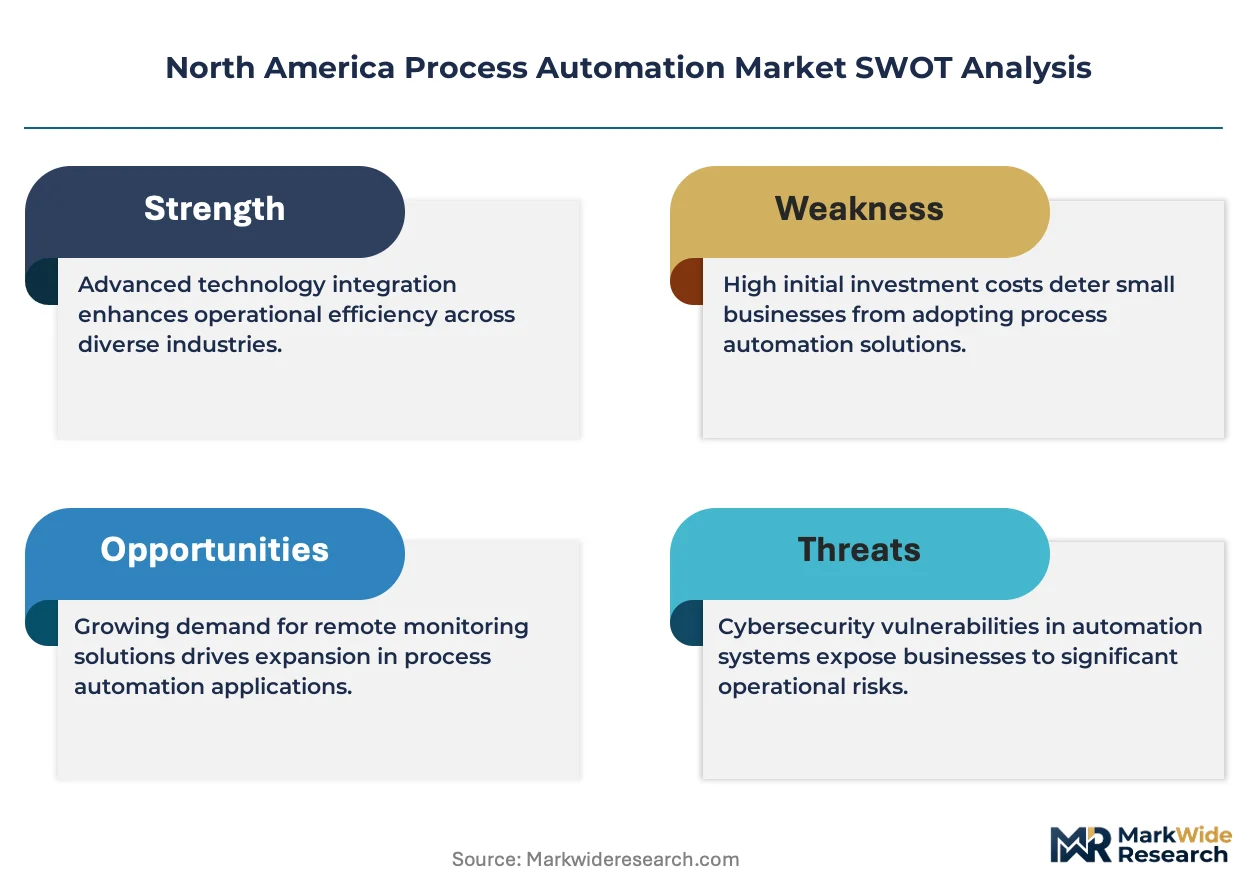
The EPA enforces Mandatory Greenhouse Gas Reporting rules that compel process industries to install continuous emissions monitoring systems with automated data acquisition. OSHA's Process Safety Management standard mandates functional safety architectures that drive demand for safety instrumented systems in chemical facilities. The Cybersecurity and Infrastructure Security Agency issues binding operational directives for critical infrastructure control systems. Stakeholders must weigh cloud-versus-edge deployment trade-offs against evolving NERC CIP reliability standards and state-level carbon accounting requirements.
Market Dynamics
EPA emissions tracking mandates are forcing Gulf Coast petrochemical operators to retrofit continuous monitoring infrastructure, compressing replacement cycles for legacy distributed control systems and accelerating edge computing deployments for real-time compliance verification.
Growth Catalysts
- EPA Mandatory Greenhouse Gas Reporting:Process industries across Texas and Louisiana must install automated data acquisition systems for continuous emissions monitoring, creating immediate hardware demand.
- Edge Computing Architectures:Refinery operators are deploying localized inference nodes to bypass cloud latency for sub-100 millisecond loop control in critical safety applications.
- Nearshoring Acceleration:Mexico's manufacturing corridor is expanding capital expenditure on automation systems to match U.S. and Canadian throughput standards.
Market Restraints
- Semiconductor Component Volatility:Supply constraints for industrial-grade processors and analog chips extend lead times for DCS hardware deliveries.
- Legacy System Interoperability:Decades-old proprietary protocols in Gulf Coast refineries create technical debt that slows cloud-native platform adoption.
- NERC CIP Compliance Burden:Electric utility automation buyers face escalating cybersecurity audit costs that divert budget from modernization programs.
Strategic Opportunities
- Pharmaceutical MES Expansion:FDA validation requirements for electronic batch records create high-switching-cost environments for manufacturing execution system vendors.
- Hybrid Discrete-Process Applications:Food and beverage packaging lines require integrated control platforms that bridge batch processing with high-speed discrete motion.
- State-Level Carbon Accounting:California and Washington are implementing emissions disclosure rules that extend monitoring requirements beyond federal minimums.
Industry Challenges
- Cybersecurity Workforce Gap:CISA binding operational directives for critical infrastructure require specialized OT security expertise that remains scarce across the region.
- Functional Safety Certification Timelines:OSHA Process Safety Management mandates drive demand for safety instrumented systems, but TÜV and exida certification cycles stretch 18-24 months.
- Multi-Vendor Integration Complexity:Refinery operators struggle to harmonize Emerson DeltaV, Honeywell Experion, and Yokogawa CENTUM platforms within unified digital twin architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Process Automation Market |
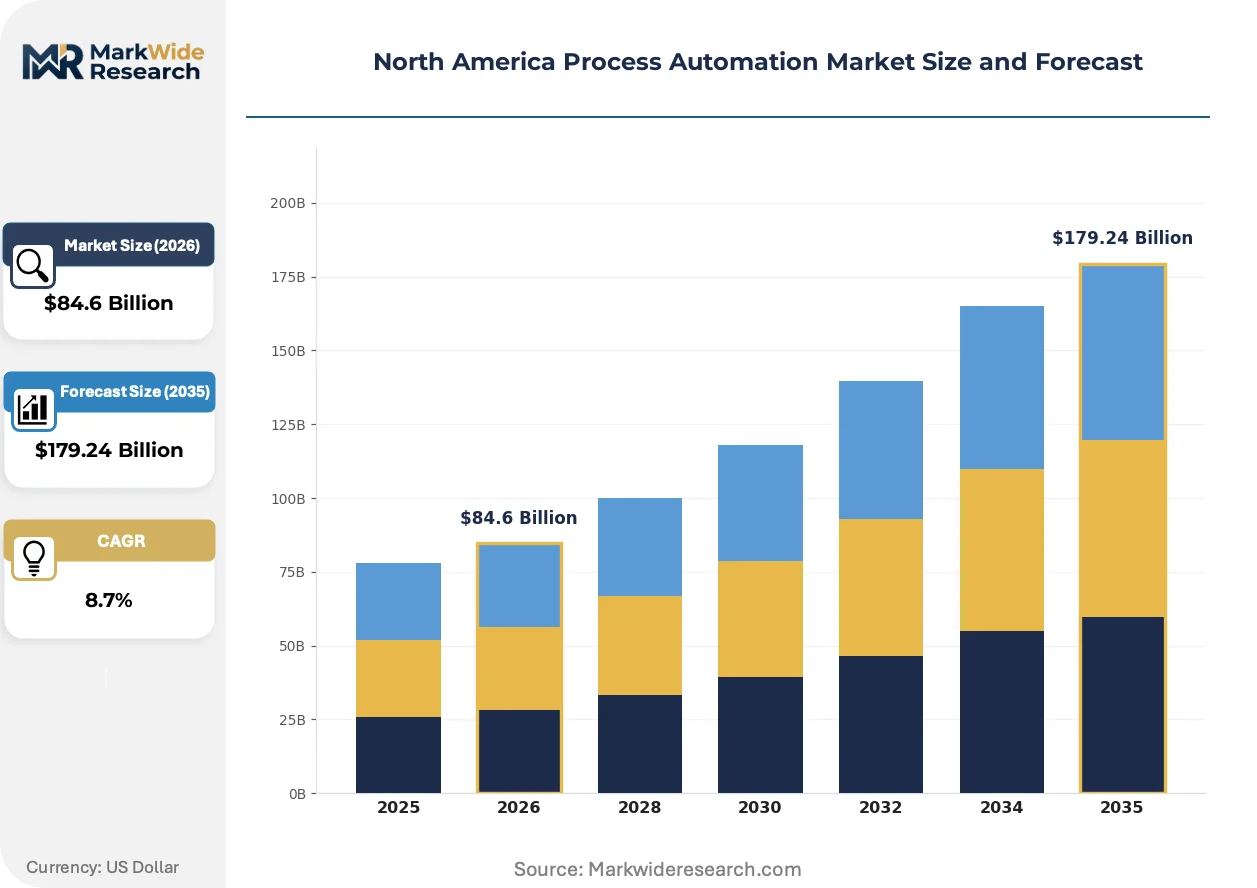
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $179.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distributed Control Systems, Supervisory Control and Data Acquisition, Manufacturing Execution Systems, Programmable Logic Controllers Industry Vertical: Oil & Gas, Chemicals, Food & Beverage, Pharmaceuticals Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Manufacturers, Process Industries, Utilities, System Integrators |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric SE, Rockwell Automation, Inc., Emerson Electric Co., General Electric Company, Honeywell International Inc., Mitsubishi Electric Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Process Automation Market Evolving Landscape
Software-defined automation architectures are displacing hardware-centric control paradigms, while regulatory pressure and buyer behavior shifts reshape deployment priorities across the continent.
Digital twin platforms are virtualizing physical process assets into real-time simulation environments that mirror refinery and chemical plant operations. Operators in Texas and Louisiana are piloting these systems for predictive maintenance and scenario planning. This technology is virtualizing traditional engineering workflows, compressing commissioning timelines from months to weeks.
OSHA's Process Safety Management standard is tightening enforcement of functional safety architectures in chemical facilities, mandating independent safety instrumented systems for high-hazard processes. The rule is compelling operators to segregate safety-critical loops from basic process control. Chemical manufacturers in the Gulf Coast corridor are responding with dedicated SIS upgrade programs separate from general automation modernization.
Service unbundling is fragmenting traditional automation vendor relationships as end-users separate hardware procurement from software licensing and ongoing support. Large petrochemical operators are negotiating direct platform subscriptions while sourcing implementation through systems integrators. This pattern is most pronounced among multinational operators with centralized engineering standards.
North America Process Automation Market Segmentation
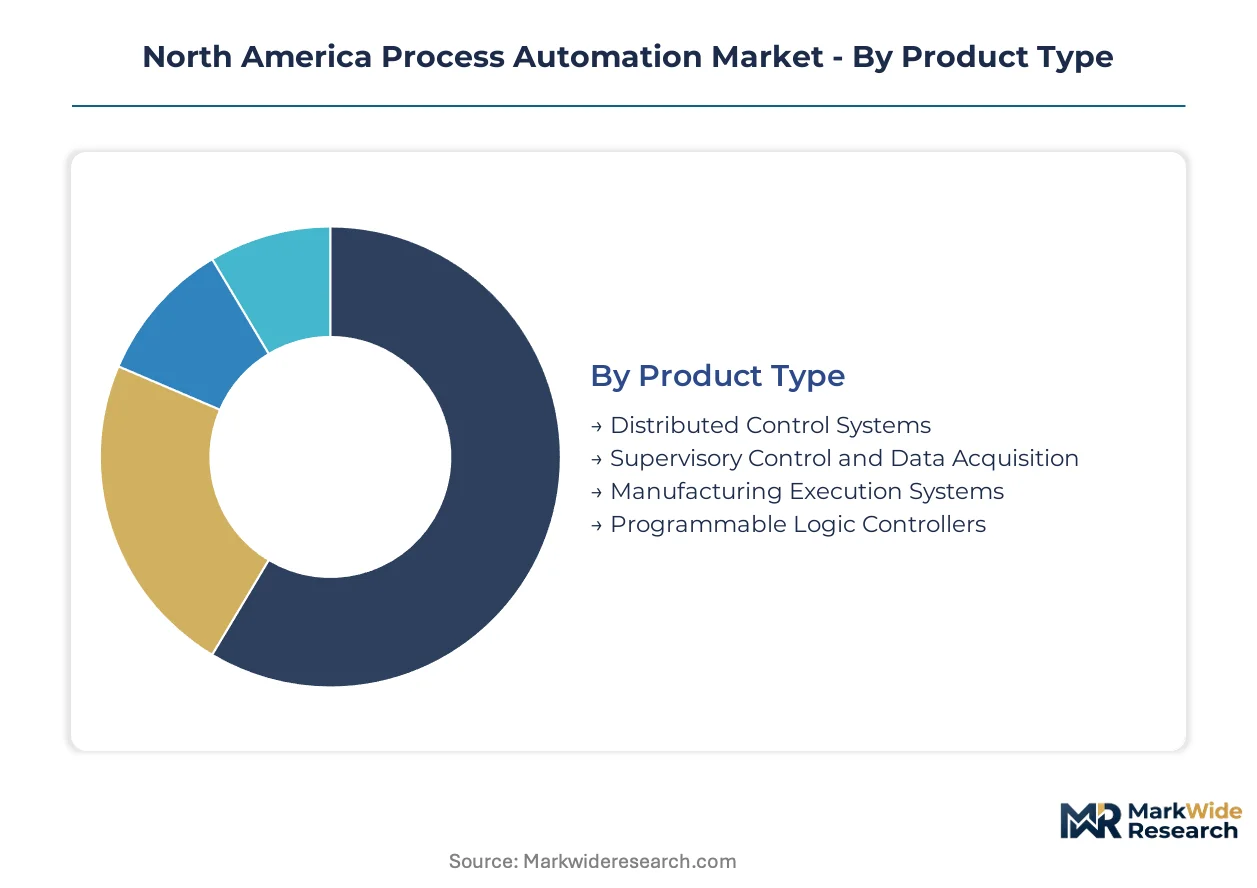
Segmentation in process automation reveals divergent replacement cycles and margin structures across hardware, software, and service layers. Gulf Coast petrochemical operators prioritize DCS lifecycle extensions while pharmaceutical manufacturers drive MES premiumization through FDA validation requirements.
Product Type:
Replacement cycles span decades for hardware-centric systems versus months for software modules, creating stark revenue recognition patterns across the installed base.
- Distributed Control Systems:These integrated platforms coordinate thousands of I/O points across refinery units through redundant controller architectures. Demand concentrates in Texas and Louisiana where EPA emissions mandates are compressing replacement timelines for 1990s-era Honeywell TDC and Yokogawa CENTUM installations.
- Manufacturing Execution Systems:Software platforms that enforce electronic batch records and material genealogy for FDA-regulated production. Pharmaceutical manufacturers in Puerto Rico and Massachusetts pay switching-cost premiums for validated MES deployments that lock out competitive displacement.
- Supervisory Control and Data Acquisition:Wide-area telemetry systems monitoring pipeline networks and remote wellheads across Permian Basin infrastructure.
- Programmable Logic Controllers:Ruggedized controllers executing discrete logic in packaging lines and material handling systems throughout Mexico's nearshored manufacturing corridor.
Distributed Control Systems dominate installed base. Manufacturing Execution Systems is where expansion concentrates.
Industry Vertical:
Capital intensity and regulatory exposure split demand between hydrocarbon processing and life sciences manufacturing.
- Oil & Gas:Upstream, midstream, and downstream automation spanning drilling controls through refinery optimization. Gulf Coast operators in Texas and Louisiana anchor the largest safety instrumented system deployments driven by OSHA Process Safety Management enforcement.
- Chemicals:Continuous and batch processing for petrochemical intermediates and specialty chemicals. EPA Mandatory Greenhouse Gas Reporting rules are forcing continuous emissions monitoring retrofits at Gulf Coast ethylene crackers and methanol plants.
- Pharmaceuticals:Sterile manufacturing and active pharmaceutical ingredient synthesis requiring 21 CFR Part 11 compliant data integrity architectures.
- Food & Beverage:Hybrid discrete-process applications integrating batch recipe management with high-speed packaging motion control.
Oil & Gas dominates installed base. Pharmaceuticals is where expansion concentrates.
Deployment Model:
Latency requirements and cybersecurity postures determine cloud-versus-local processing trade-offs across critical infrastructure.
- Edge Computing:Localized inference nodes executing sub-100 millisecond loop control without cloud round-trip dependency. Refinery operators in Texas deploy edge architectures for real-time emissions compliance verification and safety-critical burner management.
- Hybrid:Architectures partitioning regulatory control on-premises while pushing optimization workloads to cloud analytics. Chemical manufacturers favor this model for balancing OSHA safety segregation with supply chain visibility.
- On-Premises:Fully air-gapped control systems meeting NERC CIP reliability standards for electric utility automation buyers.
- Cloud-Based:SaaS manufacturing execution and predictive analytics platforms serving mid-market food and beverage processors.
On-Premises dominates installed base. Edge Computing is where expansion concentrates.
End User:
Procurement authority fragmentation separates capital project owners from ongoing operational technology management.
- Process Industries:Owner-operators of refineries, chemical plants, and primary metals facilities with centralized engineering standards. These buyers negotiate direct platform subscriptions while unbundling implementation through systems integrators.
- System Integrators:Engineering firms delivering turnkey automation projects and lifecycle support services. Gulf Coast petrochemical operators increasingly source DCS commissioning through specialized integrators rather than vendor direct.
- Manufacturers:Discrete and hybrid producers integrating process automation with enterprise resource planning systems.
- Utilities:Electric power and water treatment operators facing NERC CIP cybersecurity audit cost escalation.
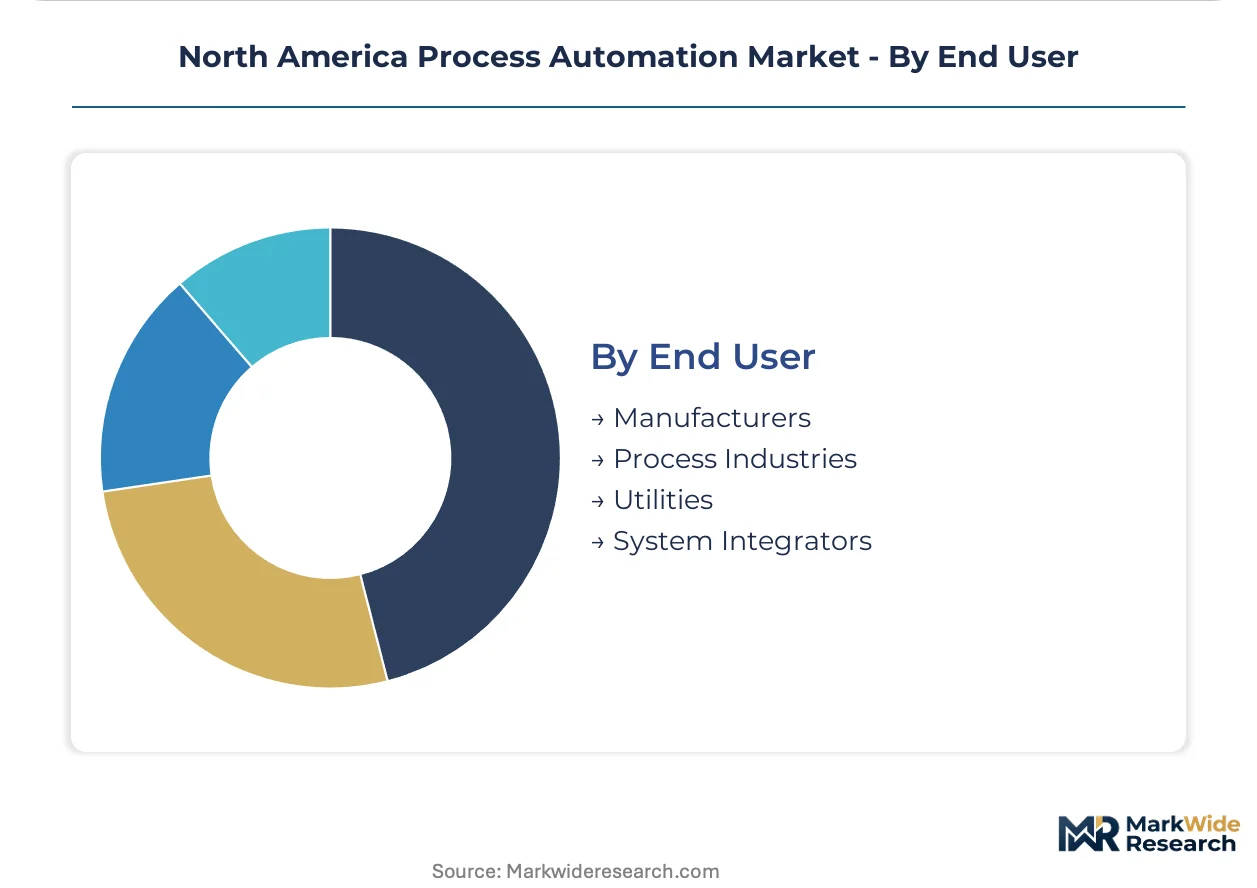
Process Industries dominate installed base. System Integrators is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process automation hardware concentrates along the Gulf Coast petrochemical corridor, with Texas and Louisiana anchoring the largest installed base of distributed control systems. Mexico's manufacturing belt is narrowing the deployment gap through accelerated capital expenditure. Canadian oil sands operators maintain distinct procurement patterns tied to provincial environmental compliance frameworks.
United States
EPA Mandatory Greenhouse Gas Reporting rules compel Texas and Louisiana refineries to retrofit continuous emissions monitoring infrastructure. OSHA Process Safety Management enforcement drives safety instrumented system upgrades across Gulf Coast chemical facilities. Houston anchors the largest concentration of DCS migration projects as operators replace 1990s-era Honeywell and Yokogawa installations.
Canada
Alberta oil sands producers deploy wide-area SCADA architectures for remote extraction monitoring across vast geographical footprints. Health Canada and provincial regulators enforce functional safety standards that align with OSHA frameworks but incorporate cold-climate reliability requirements. Calgary and Edmonton host engineering centers specializing in arctic-rated automation hardware specification.
Mexico
Nearshoring acceleration pushes Nuevo León and Bajío Region manufacturers to match U.S. throughput standards through expanded automation deployment. The country's federal environmental regulator mandates emissions tracking for major industrial facilities, creating compliance hardware demand. Querétaro and Guanajuato automotive suppliers integrate Rockwell PLC architectures with process control layers for hybrid manufacturing.
Pacific Northwest
Washington state carbon accounting rules extend monitoring requirements beyond federal EPA minimums for process industries. The region's clean energy transition drives automation investment in biofuel refineries and green hydrogen pilot plants. Seattle-Tacoma industrial corridor hosts specialized system integrators serving carbon-intensive facility retrofits.
North America Process Automation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, actuators, and edge devices. The vendor base organizes around three archetypes: full-stack DCS providers, hybrid discrete-process platform vendors, and safety instrumented system specialists. Consolidation pressure favors scale players with installed base migration capabilities. Competitive moves center on unbundling service relationships and expanding edge computing portfolios.
Within the full-stack platform tier, Emerson Electric Co., Honeywell International Inc., and Rockwell Automation, Inc. exemplify divergent strategic positioning. Emerson occupies a position anchored in Gulf Coast petrochemical relationships through specialized DCS platforms. Honeywell represents the legacy migration opportunity across North American refineries with decades-old installed bases. Rockwell sits within the hybrid application space bridging batch processing with discrete motion control for food and beverage packaging integrators.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Rockwell Automation, Inc. |
| Emerson Electric Co. |
| General Electric Company |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| Yokogawa Electric Corporation |
| Others |
Value Network & Pricing Analysis
Houston Ship Channel freight corridors transmit semiconductor logistics cost volatility directly into DCS hardware pricing, compressing margins for Gulf Coast system integrators while amplifying price differentiation between EPA-compliant certified tiers and uncertified alternatives. Texas and Louisiana petrochemical operators absorb these cost escalations unevenly, with large owner-operators leveraging volume scale against mid-tier buyers facing steeper procurement penalties.
Pricing Analysis
EPA Mandatory Greenhouse Gas Reporting dictates the pricing tier structure across the North American process automation landscape. Three-tier pricing structure across premium, standard, and economy levels segments buyers by validation depth: FDA-certified MES deployments command substantial switching-cost premiums in Puerto Rico pharmaceuticals, while uncertified edge nodes serve price-sensitive Mexican packaging integrators. Cost compression in mid-tier DCS hardware is intensifying because semiconductor lead time volatility forces vendors to pre-purchase industrial-grade processors at inflated spot rates. Small-to-mid chemical manufacturers in the Gulf Coast corridor exhibit highest price sensitivity, whereas multinational refineries with centralized engineering standards demonstrate lowest sensitivity due to lifecycle cost optimization frameworks.
Supply Chain Analysis
Industrial-grade processor fabrication draws from Taiwan, South Korea, and the United States, with analog chip production concentrated in Japan and Germany. Raw material dependencies span silicon wafers, rare-earth magnets for precision actuators, and specialty alloys for arctic-rated instrumentation specified by Canadian oil sands operators. Single-source vulnerability permeates the controller hardware tier where Yokogawa and Honeywell maintain captive fabrication relationships. Distribution runs through authorized systems integrator networks across Texas, Louisiana, and Nuevo León, with direct OEM procurement reserved for multinational operators with unbundled service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American process automation functions as a regulatory-moat market where EPA emissions mandates and FDA validation requirements erect structural barriers that entrench incumbent positions through customer switching costs. This defensive architecture favors platform specialists with installed base migration capabilities over pure-play component vendors.
For Market Incumbents: Pre-empt edge computing commoditization by embedding proprietary inference accelerators into DeltaV and Experion controller architectures before cloud-native competitors achieve latency parity. Consolidate systems integrator relationships across the Gulf Coast corridor to block emerging entrants from securing DCS commissioning footholds at Texas and Louisiana refineries. Prioritize TÜV functional safety certification acceleration to compress 18-24 month timelines and capture OSHA-mandated SIS upgrade cycles ahead of Yokogawa.
For New Entrants and Emerging Players: Mexico's Bajío Region presents the most penetrable automation deployment corridor, where nearshoring manufacturers seek hybrid discrete-process platforms without legacy protocol baggage. Target pharmaceutical MES white space in Puerto Rico and Massachusetts where FDA validation requirements have locked out non-specialized competitors. Pursue cloud-native SaaS manufacturing execution positioning to bypass on-premises hardware margin compression and capture mid-market food and beverage processors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors safety instrumented system specialists with TÜV/exida certification pipelines and Gulf Coast operator relationships. Long-term viability across the analysis window rests on regulatory entrenchment depth rather than hardware innovation velocity. Acquisition screening should prioritize vendors with EPA emissions monitoring integration capabilities and established OSHA Process Safety Management compliance track records. The signal to monitor is CISA binding operational directive expansion beyond electric utilities into chemical facility cybersecurity mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Portfolio Expansion | Localized inference nodes bypass cloud latency for sub-100 millisecond refinery safety loops. |
| FDA Validation Acceleration Program | Compressed electronic batch record certification timelines lock out MES competitors in Puerto Rico pharmaceuticals. |
| Systems Integrator Channel Consolidation | Exclusive commissioning partnerships block emerging entrants from Gulf Coast DCS migration projects. |
| Hybrid Discrete-Process Platform Development | Unified control architectures capture food and beverage packaging automation in Mexico's nearshoring corridor. |
| Carbon Accounting Software Integration | State-level emissions disclosure compliance extends vendor relevance beyond federal EPA minimums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA enforcement databases, and OSHA compliance records. Plant managers at Texas and Louisiana refineries, procurement leads at Gulf Coast petrochemical operators, systems integrator principals, and FDA regulatory affairs specialists contributed structured interviews. Bottom-up installed base enumeration triangulates against top-down capital expenditure tracking across the North American hydrocarbon processing and life sciences manufacturing sectors.
Forecast inputs span product type replacement cycles, deployment model adoption curves, and vertical regulatory exposure intensity across the projection horizon. Segmentation dimensions include hardware-software-service layering, edge-hybrid-cloud architecture partitioning, and EPA-OSHA-FDA compliance tier stratification. CAGRs derive from regression against historical DCS migration patterns and nearshoring capital expenditure acceleration in Mexican manufacturing corridors. Industry-specific inputs incorporate semiconductor lead time volatility and TÜV certification queue depth.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native automation platforms or Chinese DCS vendors would shift outcomes substantially. Cross-checking against FERC infrastructure investment filings and CISA critical infrastructure directive implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Motion Control Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Safety Programmable Controller Market