
 Asia Pacific Factory Automation and Industrial Controls Market | 2026-2036
Asia Pacific Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Factory Automation and Industrial Controls Market Outlook
Automotive production lines is broadening as the dominant demand source across the Asia Pacific Factory Automation and Industrial Controls Market, displacing traditional process industries in annual equipment procurement volumes. Siemens AG leverages its digital twin portfolio to anchor automation contracts with German-Japanese automotive joint ventures in Thailand. Mitsubishi Electric Corporation dominates servo motor and CNC controller supply to precision machining facilities across Taiwan and South Korea. Yokogawa Electric Corporation specializes in distributed control systems for petrochemical complexes along Singapore's Jurong Island, competing with Emerson Electric Co's process automation division.
Asia Pacific factory automation and industrial controls encompass programmable logic controllers, supervisory control and data acquisition systems, human-machine interfaces, industrial robotics, and their associated networking infrastructure, typically operating across voltage classes from 24V DC control circuits to 690V AC power distribution with communication protocols including EtherCAT, Profinet, and OPC UA. These systems execute real-time process monitoring, motion control, and safety interlocking to minimize unplanned downtime in continuous and discrete manufacturing environments. PLC and robotics hardware commands the largest installed base across the product type dimension, while cloud computing and edge computing deployments within the technology category are expanding fastest as manufacturers seek to reduce latency for predictive maintenance algorithms. The industry vertical segmentation shows manufacturing and automotive applications generating the most concentrated margin pools, whereas oil and gas automation spending remains structurally mature with replacement-driven rather than expansionary demand.
China's MIIT enforces GB standards for industrial cybersecurity and equipment interoperability, compelling foreign suppliers to localize firmware and certification documentation. Japan's METI coordinates JIS standards alignment with IEC 61131 programming environments for programmable controllers, while India's BIS mandates electromagnetic compatibility testing for imported automation hardware under the Compulsory Registration Order. South Korea's MFDS and KOSHA frameworks additionally shape safety controller specifications for pharmaceutical and heavy machinery applications. Stakeholders must monitor divergence between national standards bodies and the IEC's harmonization timeline to determine whether to pursue unified product architectures or region-specific certification tracks.
Market Dynamics
Automotive assembly plants across China, Japan, and South Korea are accelerating capital deployment into robotic welding cells and smart conveyor networks, compressing replacement cycles from seven years to four years as just-in-sequence manufacturing mandates intensify.
Growth Catalysts
- China's dual carbon goals:Binding emissions targets under MIIT's GB standards are forcing steel and cement plants to retrofit with energy-efficient servo drives and regenerative power modules.
- Precision machining clusters:Taiwan's semiconductor equipment fabricators are scaling orders for multi-axis CNC controllers and linear motor stages to support advanced packaging lines.
- India's PLI scheme:Production-linked incentives for electronics manufacturing are triggering greenfield automation investments in Noida and Sri City industrial corridors.
Market Restraints
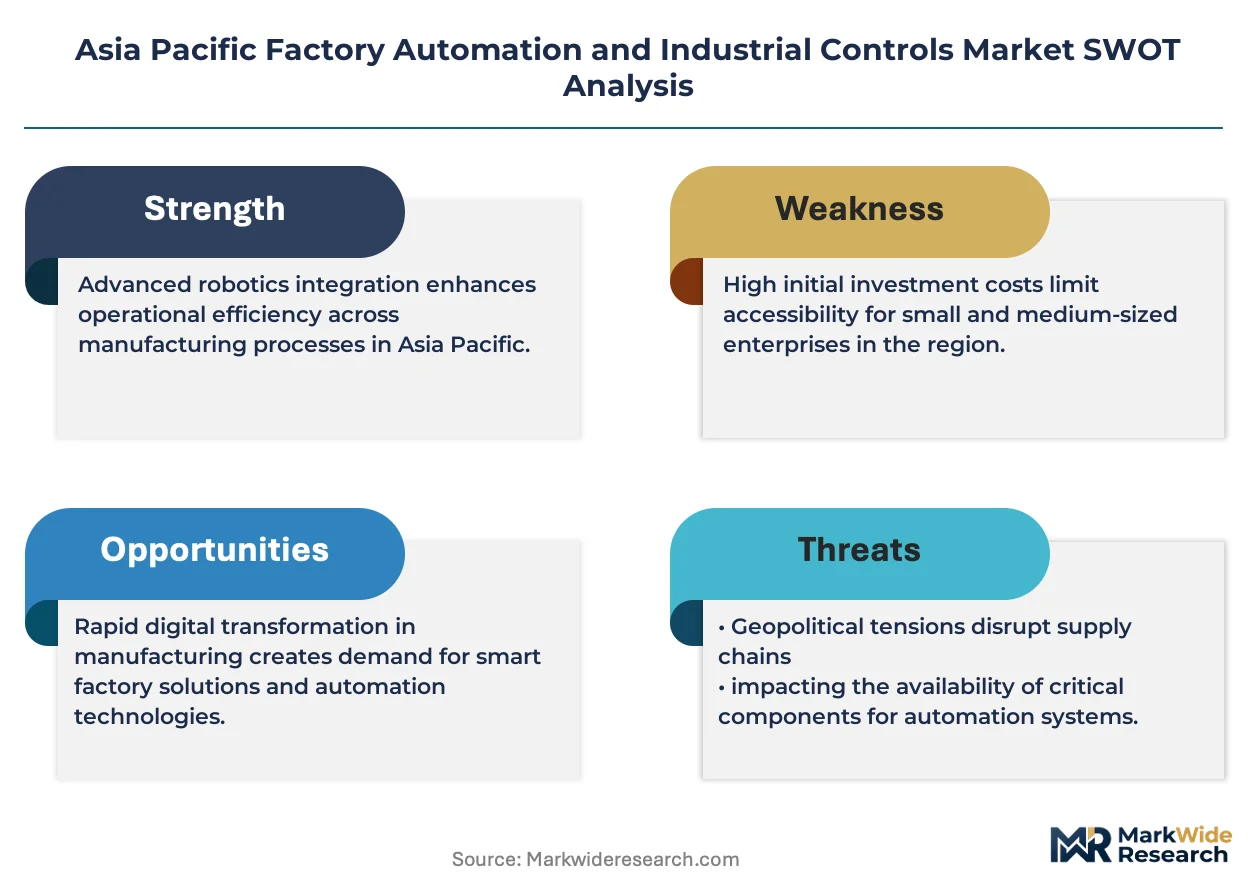
- Semiconductor component concentration:Power chip and FPGA supply remains concentrated among Taiwanese foundries, exposing lead times to geopolitical friction.
- Copper and rare earth price volatility:Permanent magnet costs for servo motors fluctuate with Chinese export quota adjustments, squeezing margin predictability.
- Legacy protocol fragmentation:Proprietary fieldbus architectures in installed Japanese and Korean machine bases resist seamless OPC UA migration.
Strategic Opportunities
- Vietnam's electronics assembly expansion:Samsung and Foxconn supplier parks near Bac Ninh lack mature system integrators, creating first-mover openings for turnkey robotic workcell providers.
- Edge-to-cloud convergence:Manufacturers are bundling predictive maintenance algorithms with hardware sales, shifting revenue toward recurring software subscriptions.
- Thailand's Eastern Economic Corridor:Board of Investment tax holidays for smart factory investments are attracting German-Japanese joint ventures seeking regional export hubs.
Industry Challenges
- Multi-protocol integration complexity:Engineers must bridge EtherCAT, Profinet, and proprietary legacy networks within single production lines, extending commissioning timelines.
- Functional safety certification backlog:TÜV and KOSHA SIL-3 validation queues for safety PLCs stretch to fourteen months, delaying pharmaceutical and heavy machinery deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Factory Automation and Industrial Controls Market |
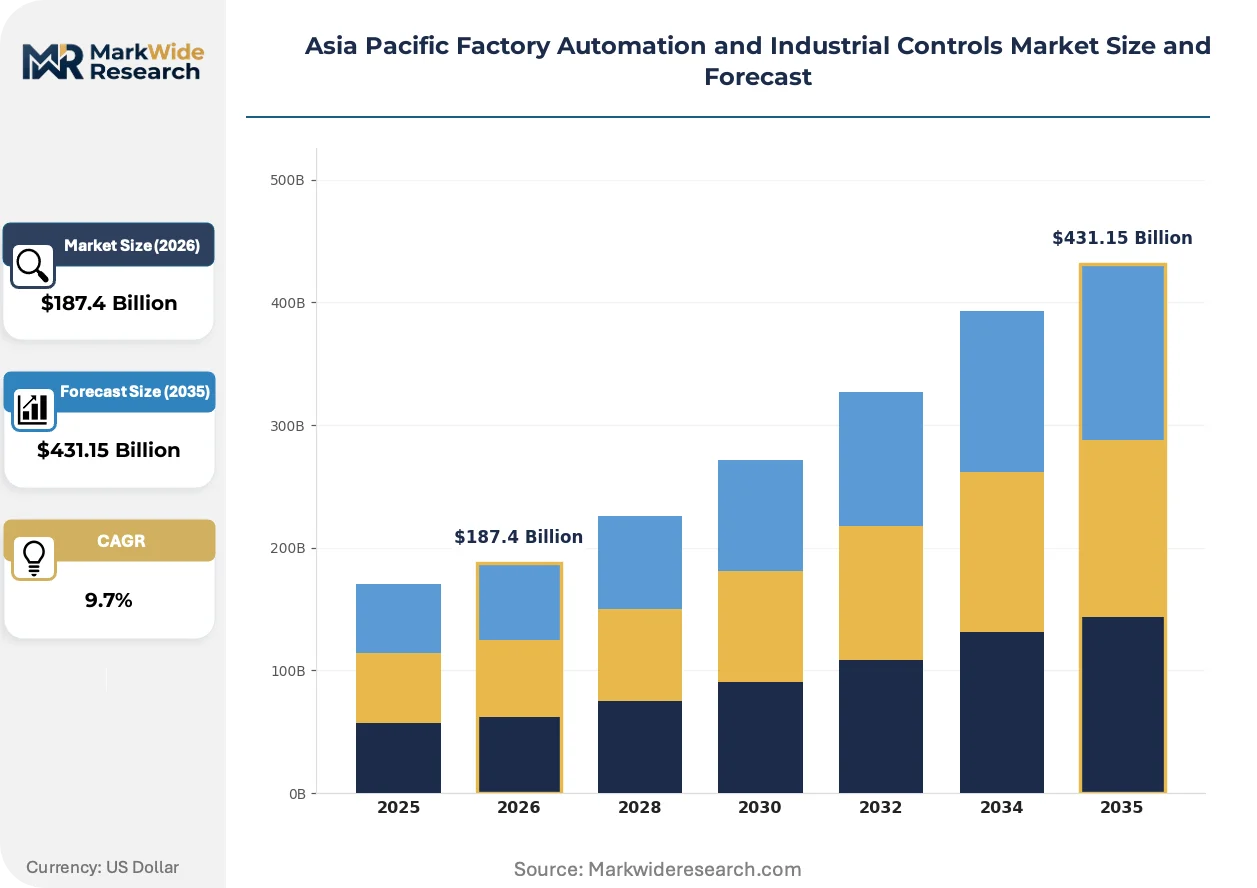
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, SCADA, HMI, Robotics Technology: IoT, Machine Learning, Cloud Computing, Edge Computing Industry Vertical: Manufacturing, Oil & Gas, Automotive, Food & Beverage End User: OEMs, System Integrators, Distributors, End Customers |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Yokogawa Electric Corporation, Rockwell Automation Inc, Mitsubishi Electric Corporation, Omron Corporation, Emerson Electric Co, Honeywell International Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Factory Automation and Industrial Controls Market Strategic Shifts
Real-time data processing architectures are migrating from centralized servers toward production-floor nodes, slashing latency for closed-loop control applications while complicating cybersecurity perimeter design.
Digital twin software is expanding into automotive stamping and body-in-white operations, enabling virtual commissioning of robotic cells before physical installation. German-Japanese joint ventures in Thailand are deploying these tools to compress factory startup schedules by forty percent. The technology is expanding into supplier quality management, allowing tier-one component makers to simulate tolerance stack-ups across multi-site production.
Japan's METI has mandated JIS-IEC 61131 alignment for all government-procured programmable controllers, forcing domestic suppliers to abandon proprietary programming environments. This industrial consequence is accelerating code portability between Mitsubishi, Omron, and Keyence platforms. Small and mid-sized automotive parts manufacturers in Aichi Prefecture are responding by consolidating supplier relationships around vendors with certified interoperability.
Buying committees at Chinese state-owned enterprises now require five-year total cost of ownership analyses rather than upfront capital expenditure comparisons, elevating energy efficiency and maintenance predictability in vendor selection. System integrators are responding with performance-guarantee contracts that bundle hardware, software, and remote monitoring services. This behavioral shift is most visible in Yangtze River Delta chemical and textile conglomerates executing MIIT-mandated smart factory upgrades.
Asia Pacific Factory Automation and Industrial Controls Market Segmentation
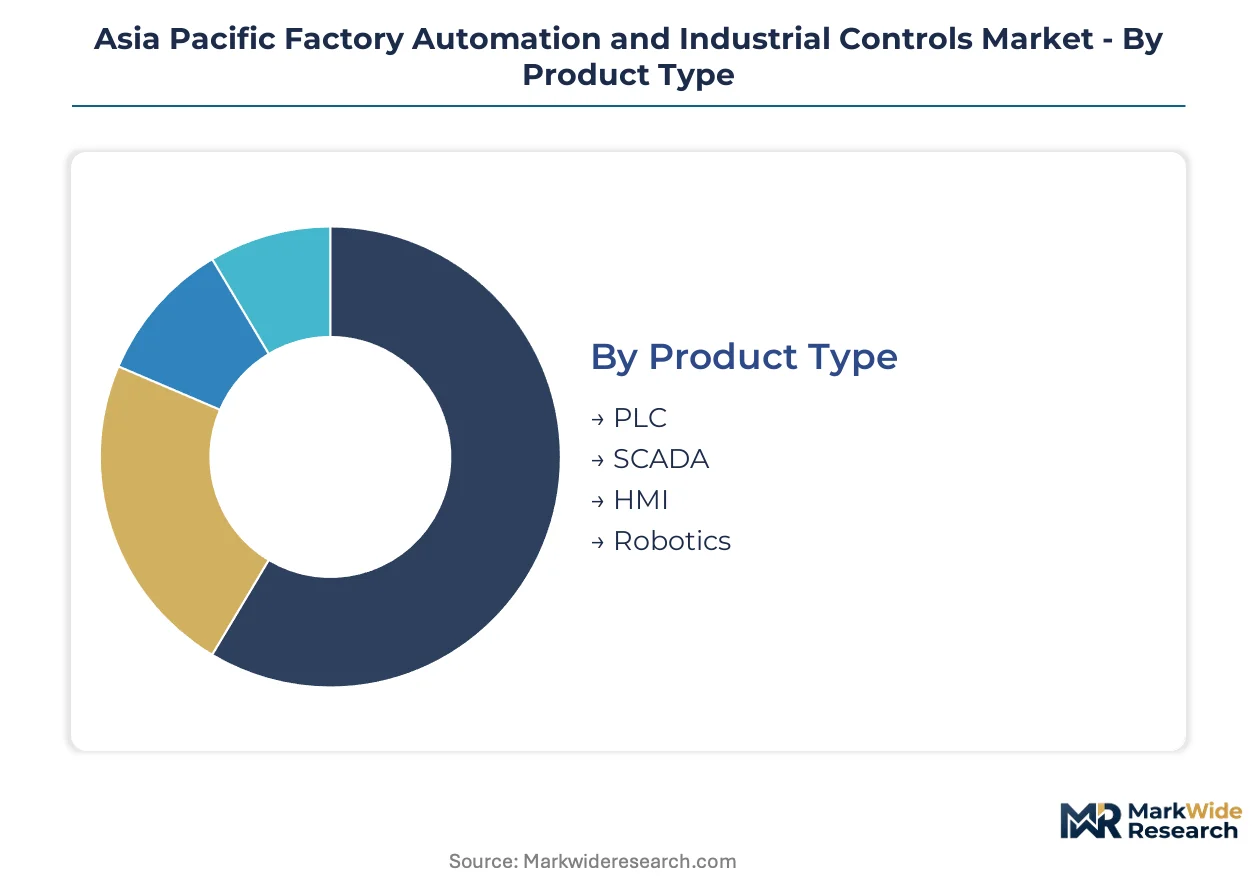
Segmentation reveals how automation procurement patterns diverge across hardware categories, digital architectures, and buyer types. Equipment specifications and technology readiness vary sharply between established automotive assembly hubs and emerging electronics manufacturing corridors.
Product Type:
Volume deployment dominates PLC and robotics hardware, while premium pricing concentrates in integrated SCADA-HMI bundles for complex process environments.
- PLC:Programmable logic controllers execute discrete control sequences across voltage classes from 24V DC to 690V AC. Demand concentrates in China's Yangtze River Delta steel and cement plants executing MIIT-mandated energy efficiency retrofits under dual carbon goals.
- Robotics:Industrial robotic systems encompass articulated arms, SCARA units, and Cartesian coordinate machines with payload ranges from 3kg to 2,300kg. Automotive assembly plants across Japan's Aichi Prefecture and South Korea's Ulsan cluster are compressing replacement cycles from seven years to four years for welding and material handling cells.
- SCADA:Supervisory control and data acquisition platforms aggregate sensor telemetry across distributed assets. Petrochemical complexes along Singapore's Jurong Island deploy these for centralized monitoring of cracking and distillation units.
- HMI:Human-machine interfaces provide operator visualization and alarm management for production floors. Taiwan's semiconductor equipment fabricators specify multi-touch panels with IP65 ingress protection for cleanroom environments.
Mature deployment sits with PLC hardware in basic manufacturing cells. Newer deployment is concentrated in robotics with integrated vision systems for quality inspection.
Technology:
Edge architectures command premium pricing for latency-sensitive motion control, while cloud subscriptions expand fastest for predictive maintenance analytics.
- Edge Computing:Distributed processing nodes execute real-time control loops and anomaly detection algorithms at production-floor locations. Thailand's Eastern Economic Corridor smart factories deploy these to reduce latency for closed-loop robotic welding applications.
- IoT:Industrial internet-of-things platforms connect sensors, actuators, and controllers through standardized communication protocols. India's PLI scheme beneficiaries in Noida electronics corridors are mandating IoT-enabled energy monitoring for incentive compliance.
- Machine Learning:Algorithmic models trained on operational data predict equipment failures and optimize process parameters. South Korean automotive tier-one suppliers in Gyeonggi Province apply these for stamping press maintenance scheduling.
- Cloud Computing:Centralized data storage and compute resources support long-term trend analysis and remote diagnostics. System integrators across Vietnam's Bac Ninh electronics parks bundle cloud subscriptions with hardware sales to shift revenue toward recurring models.
Established implementation sits with cloud-based remote monitoring platforms. Accelerating adoption is visible in edge computing for safety-critical motion control loops.
Industry Vertical:
Automotive applications generate concentrated margin pools through high-specification robotics, while oil and gas spending remains replacement-driven with mature technology requirements.
- Automotive:Body-in-white welding, paint shop automation, and final assembly sequencing demand multi-axis coordination and functional safety certification. German-Japanese joint ventures in Thailand deploy digital twin software to compress factory startup schedules.
- Manufacturing:Discrete production spanning electronics assembly, metal fabrication, and packaging equipment requires flexible reprogramming and rapid changeover capabilities. China's MIIT smart factory upgrade mandates are reshaping procurement standards for textile and machinery producers.
- Oil & Gas:Upstream drilling automation and downstream refining control prioritize intrinsic safety and explosion-proof enclosures. Singapore's Jurong Island petrochemical complex operators specify Yokogawa distributed control systems for cracking unit reliability.
- Food & Beverage:Hygienic design standards and washdown-rated components dominate equipment specifications. Australia's dairy processing cooperatives specify stainless steel servo motors with IP69K protection for CIP/SIP compatibility.
Replacement-driven demand sits with oil and gas automation. Expansionary investment is concentrated in automotive electrification transitions and battery manufacturing lines.
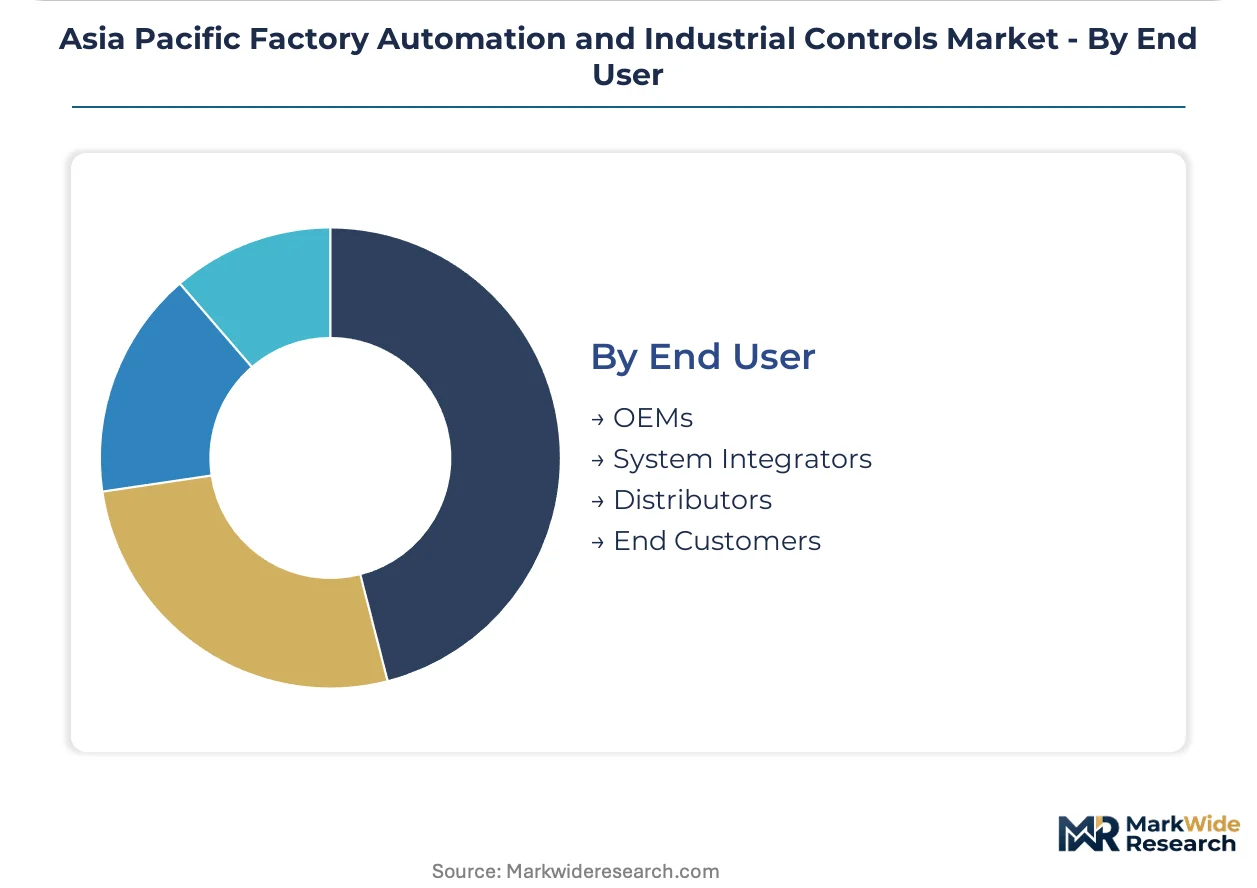
End User:
OEMs capture volume through standardized machine platforms, while system integrators extract premium value from complex multi-vendor integration projects.
- System Integrators:Engineering firms design, commission, and maintain integrated automation solutions across heterogeneous equipment bases. Vietnam's electronics assembly expansion lacks mature integrators, creating first-mover openings for turnkey robotic workcell providers near Samsung and Foxconn supplier parks.
- OEMs:Original equipment manufacturers embed automation components into machines for resale to end customers. Taiwan's semiconductor equipment fabricators specify Mitsubishi servo motors and CNC controllers for precision stages.
- Distributors:Channel partners stock standard components and provide logistics, technical support, and localized service. India's BIS Compulsory Registration Order for electromagnetic compatibility testing shapes import channel strategies.
- End Customers:Manufacturing enterprises procure automation directly for brownfield upgrades and greenfield facilities. Chinese state-owned enterprises now require five-year total cost of ownership analyses rather than upfront capital expenditure comparisons.
Long-established relationships sit with OEM specification channels. Emerging procurement influence is visible among end customers bundling performance-guarantee contracts with remote monitoring services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax holidays for smart factory investments are drawing German-Japanese automotive joint ventures seeking regional export hubs. This incentive architecture is redistributing automation procurement patterns across Southeast Asia.
China
Steel and cement plants in the Yangtze River Delta are retrofitting with energy-efficient servo drives under MIIT's GB standards for dual carbon compliance. The country's national industrial regulator enforces cybersecurity and equipment interoperability mandates that compel foreign suppliers to localize firmware. Shanghai and Suzhou manufacturing clusters now dominate procurement volumes for robotic welding and smart conveyor systems.
Japan
Automotive assembly plants in Aichi Prefecture are compressing equipment replacement cycles from seven years to four years for robotic welding cells. METI coordinates JIS standards alignment with IEC 61131 programming environments for programmable controllers. Nagoya's precision machining facilities anchor servo motor and CNC controller demand from domestic suppliers.
South Korea
Automotive tier-one suppliers in Gyeonggi Province deploy machine learning algorithms for stamping press maintenance scheduling. The country's pharmaceutical and heavy machinery safety frameworks shape safety controller specifications through MFDS and KOSHA requirements. Ulsan's industrial cluster drives concentrated demand for multi-axis coordination systems in body-in-white operations.
India
Electronics manufacturing beneficiaries of the PLI scheme in Noida and Sri City industrial corridors are triggering greenfield automation investments. BIS mandates electromagnetic compatibility testing for imported automation hardware under the Compulsory Registration Order. These procurement patterns concentrate most visibly in the Delhi-NCR and Andhra Pradesh manufacturing belts.
Vietnam
Samsung and Foxconn supplier parks near Bac Ninh lack mature system integrators, creating first-mover openings for turnkey robotic workcell providers. The country's national standards body shapes import certification timelines for industrial equipment. Electronics assembly expansion in northern provinces is outpacing local automation service capacity.
Asia Pacific Factory Automation and Industrial Controls Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with discrete manufacturing favoring integrated solution providers while process industries tolerate multi-vendor environments. The vendor base concentrates around three strategic archetypes: diversified electrical conglomerates with full-stack automation portfolios, precision motion control specialists, and process automation pure-plays. Competitive moves center on bundling predictive maintenance software with hardware sales and pursuing performance-guarantee contracts that shift revenue toward recurring subscriptions.
Among diversified electrical conglomerates, Siemens AG and Mitsubishi Electric Corporation exemplify the full-stack archetype, anchoring automation contracts through digital twin portfolios and servo motor supply respectively. Yokogawa Electric Corporation occupies a position within the process automation tier, specializing in distributed control systems for petrochemical applications. These three entities represent distinct competitive vectors: European-Japanese joint venture capture in Thailand, precision machining cluster dominance in Taiwan and South Korea, and island-based petrochemical complex penetration.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| Rockwell Automation Inc |
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Emerson Electric Co |
| Honeywell International Inc |
| Others |
Value Chain & Pricing Dynamics
Captive integration into Taiwanese power semiconductor foundries anchors supply security for servo drive manufacturers serving China's Yangtze River Delta steel retrofits. This vertical control over IGBT and MOSFET sourcing simultaneously buffers margin pressure from copper and rare earth volatility while enabling premium positioning for energy-efficient regenerative modules under MIIT's dual carbon procurement mandates.
Pricing Analysis
Premium pricing for four-week lead times on safety-certified PLCs separates automotive tier-one suppliers from spot-market buyers accepting eight-month delivery windows for standard controllers. Three-tier pricing structure across SIL-3 certified, IEC-compliant, and economy-grade hardware reflects TÜV validation costs and firmware localization requirements under China's GB cybersecurity standards. Cost compression in economy servo motors is intensifying because Chinese export quota adjustments on neodymium permanent magnets squeeze margin predictability. System integrators exhibit the sharpest price sensitivity, while state-owned enterprises prioritize five-year total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Container freight cost spikes from Shanghai to Bangkok and Ho Chi Minh City are forcing German-Japanese joint ventures in Thailand's Eastern Economic Corridor to regionalize component warehousing. Geographic supply concentration centers on Taiwan for power chips and FPGAs, China for rare earth magnets and copper windings, and Japan for precision encoders and motion controllers. Raw material dependencies rest on neodymium-iron-boron magnets, electrolytic copper for motor windings, and silicon carbide substrates for next-generation servo drives. Single-source vulnerability around Taiwanese foundry capacity exposes lead times to geopolitical friction. Distribution runs through authorized distributors stocking standard PLCs and robotics, with system integrators handling complex multi-vendor project fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific factory automation is consolidating around vendors with captive semiconductor supply and certified interoperability stacks, squeezing mid-tier players lacking firmware localization capabilities or safety validation depth.
For Market Incumbents: Cement dominance in Thailand's Eastern Economic Corridor by bundling digital twin software with hardware sales to compress joint venture startup schedules. Deepen backward integration into Taiwanese foundry capacity to secure power chip allocation ahead of automotive electrification ramps. Lock in Chinese state-owned enterprise accounts through performance-guarantee contracts spanning energy efficiency retrofits and remote monitoring subscriptions.
For New Entrants and Emerging Players: Edge-native predictive maintenance algorithms offer the most penetrable wedge for Vietnam's Bac Ninh electronics parks lacking mature system integrators. Target turnkey robotic workcell deployment for Samsung and Foxconn supplier ecosystems requiring rapid commissioning without established local service infrastructure. Lead with subscription-based remote diagnostics to shift revenue toward recurring models and bypass capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified electrical conglomerates seeking digital twin capabilities or edge computing software stacks. Long-term viability favors vendors with certified interoperability across Mitsubishi, Omron, and Keyence platforms under METI's JIS-IEC 61131 alignment mandates. Monitor divergence between national standards bodies and IEC harmonization timelines as the critical inflection signal determining whether unified or region-specific certification tracks prevail.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Taiwanese foundry partnerships secure IGBT allocation for servo drive manufacturers serving MIIT-mandated retrofits. |
| Digital Twin Platform Deployment | German-Japanese joint ventures in Thailand compress factory startup schedules by forty percent through virtual commissioning. |
| Safety Certification Acceleration | TÜV and KOSHA SIL-3 validation investment clears fourteen-month queues blocking pharmaceutical automation deployments. |
| Edge Computing Node Expansion | Thailand's Eastern Economic Corridor smart factories reduce robotic welding latency through distributed processing architectures. |
| Performance Guarantee Contracting | Chinese state-owned enterprises in the Yangtze River Delta bundle hardware, software, and remote monitoring under five-year TCO frameworks. |
Study Parameters
Multi-period observation of capital expenditure flows, equipment replacement cycles, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with plant engineers at automotive assembly facilities, procurement leads at Chinese state-owned steel enterprises, system integrators in Vietnam's Bac Ninh corridor, and aftermarket service heads at Japanese precision machining clusters. Secondary validation drew from MIIT GB standard filings, METI JIS alignment documentation, BIS Compulsory Registration Order records, and customs trade data on industrial automation imports. Bottom-up equipment shipment tracking and top-down manufacturing value-added estimates were triangulated to cross-verify market sizing.
Segment-weighting across product type, technology architecture, industry vertical, and end-user channel shaped the analytical framework over the projection horizon. Hardware volume forecasts for PLCs and robotics were modeled separately from software subscription growth in edge and cloud deployments. CAGRs were derived from regression analysis against industrial production indices and automation intensity ratios by country. Industry-specific inputs included MIIT smart factory upgrade mandates, India's PLI scheme disbursement schedules, and automotive electrification capital commitment announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged semiconductor supply constraints or abrupt shifts in Chinese rare earth export policy. Forecasts reflect assumptions about regulatory harmonization timelines, joint venture formation velocity in Thailand, and the pace of OPC UA migration away from legacy Japanese and Korean fieldbus architectures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Smart Industries Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Factory Automation Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
North America and Europe Retail Automation Market