
 Business to Business E Commerce Market | 2026-2036
Business to Business E Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Business to Business E Commerce Market Intelligence
China is rewriting the competitive map for B2B digital trade infrastructure through state-backed industrial marketplace expansion and cross-border payment corridor development. Shopify leverages its merchant ecosystem to extend into wholesale tooling, while SAP Commerce Cloud anchors enterprise procurement digitization across European manufacturing bases. Salesforce Commerce Cloud competes on AI-driven contract analytics, and commercetools differentiates through API-first architecture that decouples frontend experience from backend commerce logic.
Business to business e commerce denotes digitally intermediated transactions between commercial entities, typically executed through proprietary platforms, electronic data interchange protocols, or API-connected procurement systems that automate requisition-to-payment workflows. Cloud-based deployment models lead transaction volume as enterprises abandon on-premise licensing for elastic infrastructure, while subscription services within transaction types capture expanding software and industrial consumables revenue. Order management solutions dominate solution spending as buyers prioritize real-time inventory visibility across multi-tier supply networks.
FDA guidelines on electronic record integrity, EU GDPR data residency rules, and China's SAMR platform governance standards collectively elevate compliance costs for cross-border B2B operators. ISO 27001 certification and SOC 2 attestation now function as market access prerequisites for platform vendors serving regulated industries. Stakeholders must weigh sovereign data requirements against the operational complexity of fragmented national compliance regimes when architecting multi-territory commerce infrastructure.
Market Dynamics
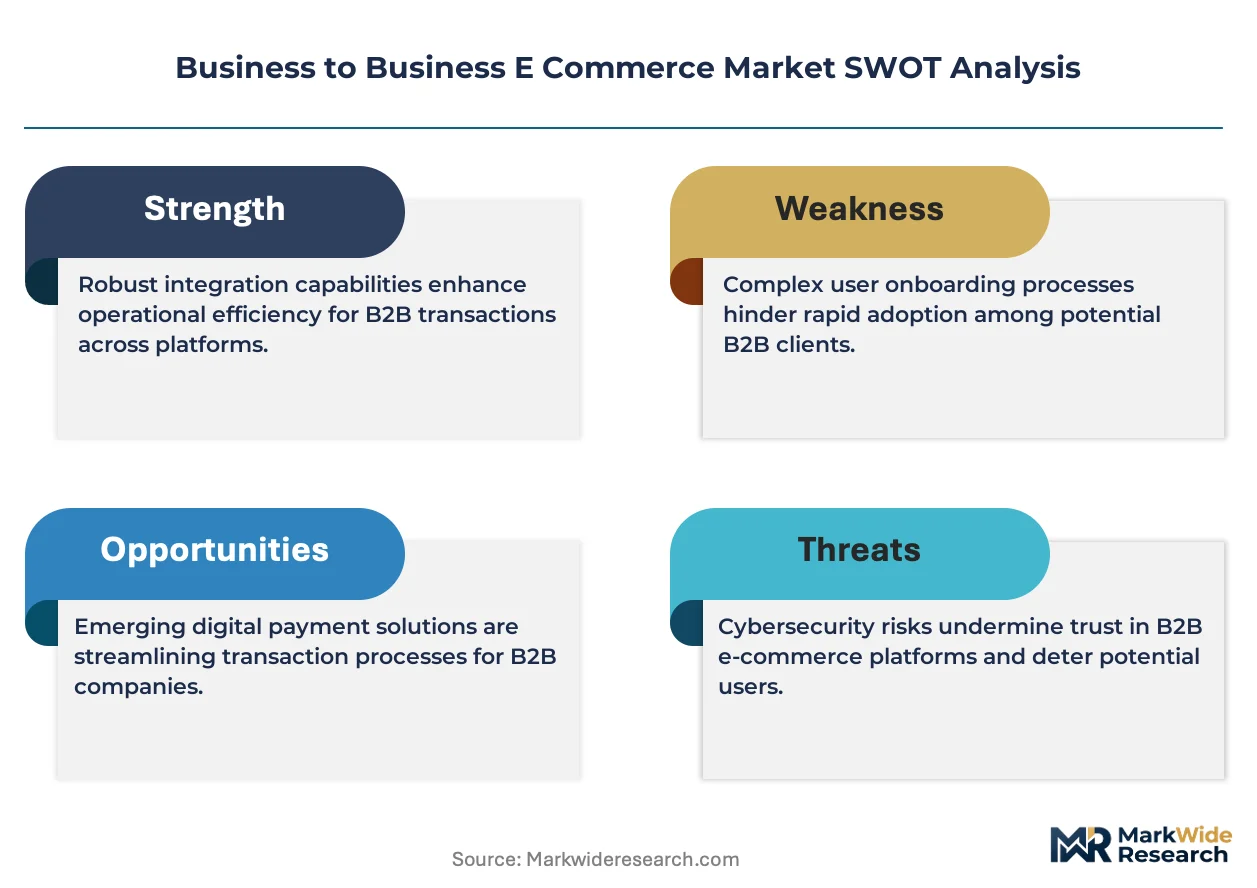
Manufacturing procurement teams now mandate API-first platform architectures that collapse traditional requisition-to-payment cycles from weeks to hours, forcing incumbent vendors to rebuild core infrastructure or cede enterprise accounts to cloud-native competitors.
Growth Catalysts
- ISO 27001 Certification Mandates:Regulated industries in Germany and the United States now require attestation for supplier onboarding, accelerating platform consolidation around compliant vendors.
- Cross-Border Payment Corridor Development:China's state-backed digital currency infrastructure reduces settlement friction for industrial importers sourcing from Asian manufacturing clusters.
- Cloud Infrastructure Elasticity:Enterprises abandon fixed-capacity licensing for consumption-based models, expanding addressable spend for platform providers serving seasonal production cycles.
Market Restraints
- Fragmented National Compliance Regimes:EU GDPR data residency rules, China's SAMR platform governance standards, and FDA electronic record guidelines create architectural complexity for multi-territory operators.
- Supplier Concentration Risk:Critical cloud infrastructure components concentrate among three hyperscale providers, exposing buyers to single-point-of-failure vulnerabilities during regional outages.
- Legacy EDI Protocol Persistence:AS2 and EDIFACT standards remain entrenched in automotive and aerospace supply chains, delaying API migration timelines.
Strategic Opportunities
- Industrial Marketplace Infrastructure:Germany's Mittelstand manufacturing base lacks dedicated B2B procurement platforms, creating whitespace for vertical-specific entrants.
- AI-Driven Contract Analytics:Natural language processing convergence with procurement workflows enables automated clause extraction and risk scoring for enterprise legal teams.
- Carbon Accounting Integration:EU CSRD scope 3 disclosure requirements create demand for embedded emissions tracking across multi-tier supplier networks.
Industry Challenges
- API Integration Talent Scarcity:Enterprise IT departments lack sufficient staff fluent in GraphQL and event-driven architecture patterns required for modern platform deployment.
- Multi-Year Certification Timelines:SOC 2 Type II attestation processes extend 12-18 months, delaying market entry for infrastructure startups targeting financial services buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business to Business E Commerce Market |
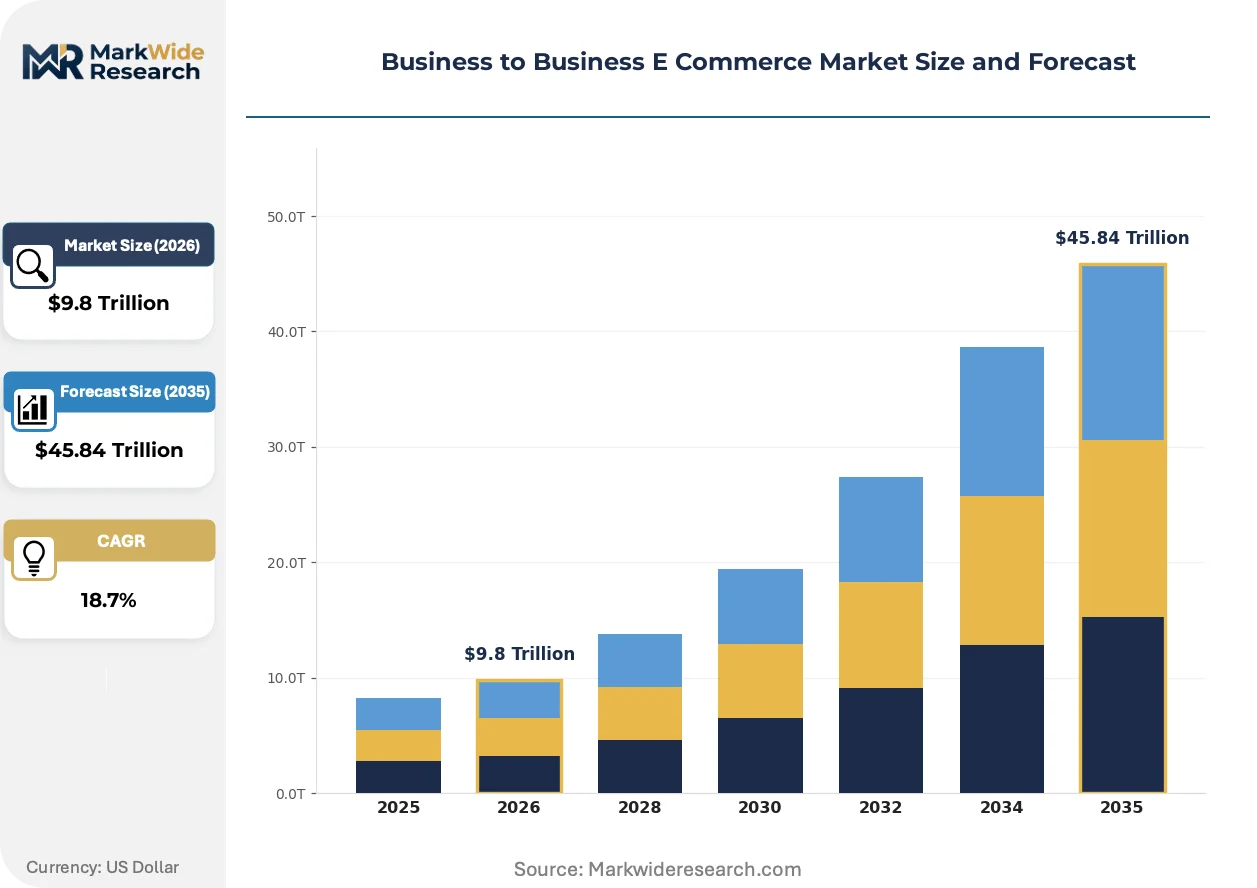
| Market Size in 2026 | $9.8 Trillion |
| Market Size in 2035 | $45.84 Trillion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Order Management, Inventory Management, Payment Processing, Supplier Relationship Management, Customer Analytics, Contract Management Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS, API Integration End User Industry: Manufacturing, Wholesale Distributors, Logistics Providers, Technology Firms, Professional Services Transaction Type: Bulk Purchase, Just-in-Time, Subscription Services, Spot Buying, Consignment Sales |
| Companies Covered | Shopify, Adobe Commerce, BigCommerce, OroCommerce, Salesforce Commerce Cloud, SAP Commerce Cloud, Virto Commerce, Intershop, commercetools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business to Business E Commerce Market Strategic Shifts & Innovations
Headless commerce architectures are fragmenting traditional platform monoliths, enabling manufacturers to compose best-of-breed capabilities rather than accepting bundled functional trade-offs from single vendors.
Composable commerce stacks built on microservices are collapsing the distinction between procurement and customer-facing commerce systems. Industrial buyers in the United States now expect consumer-grade search and recommendation engines within supplier portals. This convergence pressures legacy ERP vendors to unbundle monolithic suites or lose direct material spend visibility.
REACH substance-of-very-high-concern restrictions are forcing chemical and materials suppliers to restructure product data hierarchies for downstream disclosure. European manufacturers must now transmit compliance certificates through API-connected procurement channels rather than document repositories. German automotive suppliers report 40% faster supplier qualification cycles where compliance data flows through integrated platforms.
Self-service procurement portals are displacing traditional sales representative relationships for standardized industrial consumables. Maintenance, repair, and operations buyers in China now complete 60% of spot purchases without supplier contact. This behavior compresses price discovery cycles and rewards platforms with real-time inventory transparency across distributor networks.
Business to Business E Commerce Market Segmentation
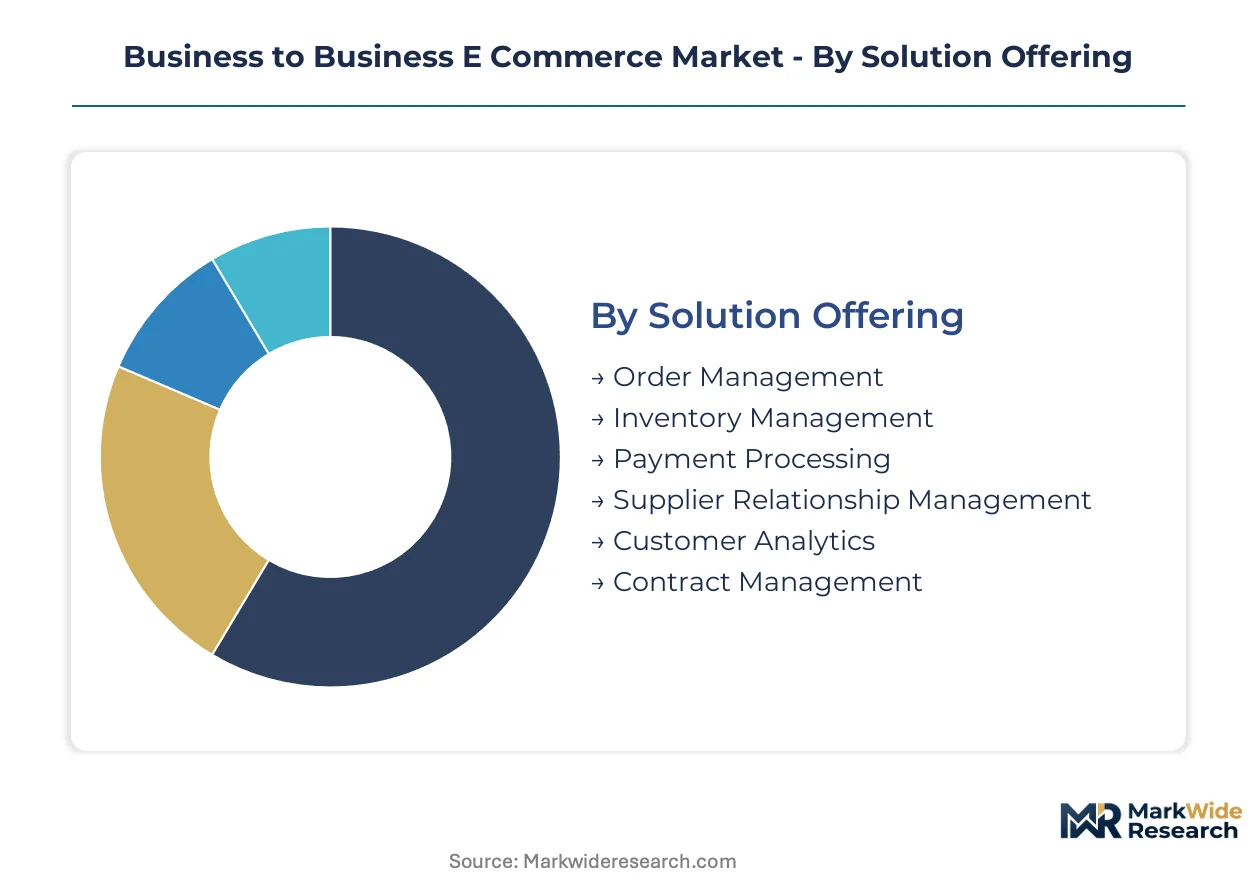
Segmentation in B2B e-commerce reveals divergent technology maturity across buyer workflows. Procurement velocity varies dramatically by solution type and deployment architecture, creating distinct vendor competitive sets.
Solution Offering:
Order Management systems turn over fastest as manufacturers demand real-time inventory visibility, while Contract Management cycles extend longest due to legal review protocols.
- Order Management:Orchestrates requisition-to-fulfillment workflows with multi-warehouse allocation logic. German automotive suppliers prioritize these systems to collapse procurement cycles from weeks to hours under ISO 9001 quality mandates.
- Inventory Management:Synchronizes stock levels across distributor networks through API-connected warehouse management systems. United States industrial distributors deploy these solutions to prevent production line stoppages at Midwest manufacturing plants.
- Payment Processing:Automates invoice matching and multi-currency settlement for cross-border transactions.
- Supplier Relationship Management:Centralizes vendor qualification, performance scoring, and risk monitoring dashboards.
- Customer Analytics:Applies predictive models to procurement patterns for demand forecasting and churn prevention.
- Contract Management:Version-controls pricing agreements and automates renewal workflows with clause extraction.
Order Management dominates installed base. Contract Management is where expansion concentrates as legal teams digitize supplier agreements.
Deployment Model:
Cost tier separation shapes vendor selection, with hyperscale cloud providers commanding premium pricing against self-hosted alternatives.
- Cloud-Based:Delivers elastic compute for seasonal demand spikes without capital expenditure. Chinese state-backed industrial marketplaces mandate cloud infrastructure to comply with SAMR data sovereignty requirements.
- SaaS:Bundles software licensing with managed infrastructure under per-seat or transaction-based pricing. United States mid-market manufacturers favor SaaS procurement portals to bypass internal IT hiring constraints.
- On-Premise:Retains data within corporate firewalls for defense and aerospace supply chains.
- Hybrid:Combines cloud frontends with on-premise ERP connectors for phased migration paths.
- API Integration:Enables composable commerce stacks through microservices architecture.
Cloud-Based deployments capture the majority of new implementations. API Integration is climbing the fastest as enterprises unbundle monolithic suites.
End User Industry:
Application complexity varies by sector, with discrete manufacturing demanding deeper supplier network orchestration than professional services.
- Manufacturing:Integrates CAD data, quality certificates, and production schedules into procurement workflows. German Mittelstand firms deploy these platforms to automate REACH compliance documentation across chemical supplier tiers.
- Wholesale Distributors:Manages price books, volume tiers, and territory restrictions for downstream resellers. United States electrical and HVAC distributors prioritize real-time availability feeds to prevent contractor project delays.
- Logistics Providers:Coordinates freight procurement, carrier selection, and customs documentation.
- Technology Firms:Sources cloud infrastructure, software licenses, and professional services through self-service portals.
- Professional Services:Automates vendor onboarding for contingent workforce and consulting engagements.
Manufacturing holds the deepest installed base. Wholesale Distributors are gaining share fastest as distributor networks consolidate.
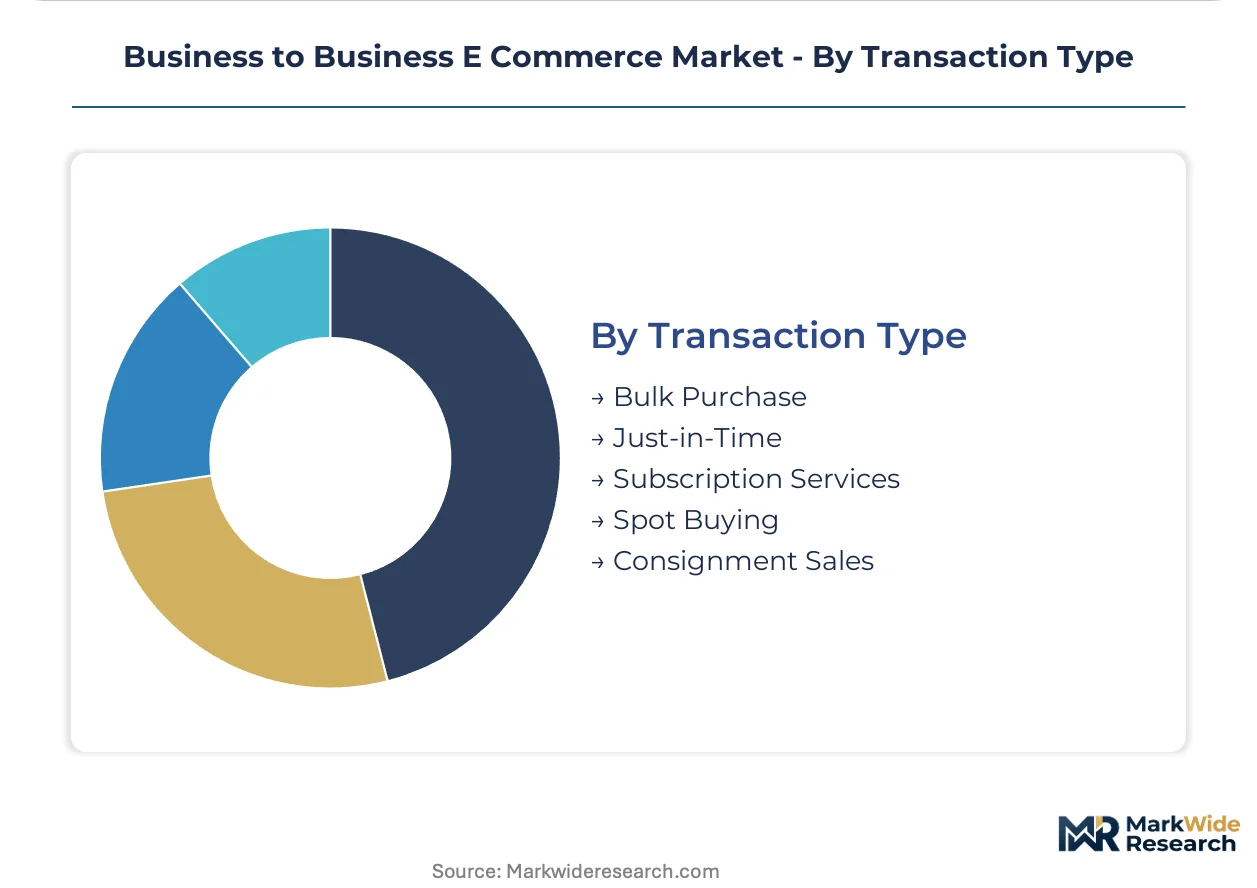
Transaction Type:
Volume concentration separates recurring revenue streams from opportunistic spot purchasing behaviors.
- Subscription Services:Locks in recurring revenue for software, industrial consumables, and maintenance parts through auto-renewal terms. United States MRO buyers favor subscription models for critical spare parts to ensure availability without safety stock.
- Just-in-Time:Synchronizes delivery schedules with production line consumption rates through EDI or API triggers. Japanese automotive assemblers mandate JIT protocols to minimize working capital tied in inventory.
- Bulk Purchase:Negotiates volume discounts for raw materials with extended payment terms.
- Spot Buying:Executes ad-hoc purchases for emergency requirements through marketplace interfaces.
- Consignment Sales:Transfers ownership only upon consumption, shifting inventory risk to suppliers.
Bulk Purchase retains the largest transaction value. Subscription Services show the steepest expansion trajectory as vendors pursue recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud infrastructure concentrates in the United States, China, and Germany, where procurement digitization mandates and supplier onboarding protocols create divergent platform requirements across national compliance regimes.
United States
FDA electronic record integrity guidelines and ISO 27001 certification mandates reshape pharmaceutical and defense procurement workflows. Midwest manufacturing clusters around Detroit and Chicago deploy cloud-based order management systems to prevent automotive production line stoppages. Maintenance, repair, and operations buyers now complete the majority of spot purchases through self-service portals without supplier contact.
China
State-backed industrial marketplace expansion and cross-border payment corridor development accelerate procurement digitization for manufacturing importers. SAMR platform governance standards mandate cloud infrastructure compliance for data sovereignty. Yangtze River Delta manufacturing bases integrate digital currency settlement infrastructure to reduce friction for industrial sourcing from Asian supplier clusters.
Germany
Mittelstand manufacturing firms automate REACH compliance documentation across chemical supplier tiers through API-connected procurement channels. EU GDPR data residency rules elevate architectural complexity for multi-territory platform operators. Bavarian automotive suppliers report accelerated supplier qualification cycles where compliance data flows through integrated platforms rather than document repositories.
United Kingdom
Professional services firms digitize contingent workforce vendor onboarding through self-service procurement portals. Post-Brexit customs documentation requirements reshape logistics provider platform specifications. London-based technology firms source cloud infrastructure and software licenses through automated requisition-to-payment workflows.
Japan
Automotive assemblers mandate just-in-time procurement protocols synchronized with production line consumption rates through EDI triggers. METI industrial digitization programs support SME marketplace infrastructure development. Kansai manufacturing clusters deploy inventory management systems to minimize working capital tied in safety stock for critical spare parts.
Business to Business E Commerce Market Key Industry Players
Enterprise suite vendors and API-native specialists split the market between bundled functional depth and composable architecture flexibility. The competitive structure tiers around three strategic archetypes: cloud-native platform builders, legacy ERP extenders, and vertical-specific marketplace operators. Consolidation pressures intensify as manufacturing procurement teams mandate API-first architectures. Incumbent vendors face rebuild-or-lose decisions while cloud-native competitors capture enterprise accounts.
Within the enterprise suite tier, SAP Commerce Cloud and Salesforce Commerce Cloud anchor procurement digitization across European and North American manufacturing bases. Shopify exemplifies the merchant-ecosystem extension model, leveraging retail infrastructure into wholesale tooling. Commercetools occupies a position representing API-first architecture that decouples frontend experience from backend commerce logic.
| Leading Market Players |
|---|
| Shopify |
| Adobe Commerce |
| BigCommerce |
| OroCommerce |
| Salesforce Commerce Cloud |
| SAP Commerce Cloud |
| Virto Commerce |
| Intershop |
| commercetools |
| Others |
Cost & Logistics Intelligence
Single-source dependency on hyperscale cloud infrastructure concentrates pricing power among three dominant providers and forces tiered spreads between certified and uncertified platform offerings. Tariff exposure on cross-border data transmission costs amplifies this concentration, compressing margins for multi-territory operators while rewarding vendors with sovereign cloud deployments in Germany, China, and the United States.
Pricing Analysis
ISO 27001 certification dictates the pricing tier structure across the B2B e-commerce landscape, separating SOC 2-attested platforms from uncertified alternatives by substantial premiums. Three-tier pricing stratifies across enterprise-grade, mid-market SaaS, and self-hosted open-source solutions, with quality grade and geographic data residency as primary differentiation drivers. Pricing pressure stems from cloud infrastructure commoditization as hyperscalers compete on consumption-based compute rates. Mid-market manufacturers exhibit highest price sensitivity, while defense and pharmaceutical buyers prioritize certification compliance over cost.
Supply Chain Analysis
Extended payment terms now function as competitive weapons, with supply-chain finance facilities embedded within platform offerings to lock in supplier loyalty. Cloud infrastructure concentrates in the United States, China, and Germany, while semiconductor components and specialized API middleware draw from Taiwan, South Korea, and Japan. Single-source vulnerability haunts the sector through hyperscale provider concentration. Distribution runs through direct enterprise sales, systems integrator channels, and self-service marketplace onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face acute substitution risk from API-native specialists unbundling monolithic suites, demanding defensive repositioning around compliance depth and vertical integration.
For Market Incumbents: Harden market position through backward integration into sovereign cloud infrastructure and accelerated SOC 2 Type II certification pipelines. SAP Commerce Cloud and Salesforce Commerce Cloud must absorb API-first architecture capabilities before commercetools and Shopify capture manufacturing procurement accounts. Channel control through systems integrator exclusivity represents a secondary defensive lever. For New Entrants and Emerging Players: Build out vertical-specific marketplace infrastructure targeting Germany's Mittelstand manufacturing base, where REACH compliance automation remains underserved. AI-driven contract analytics and carbon accounting integration offer the most penetrable solution segments. A channel partnership strategy with European systems integrators accelerates enterprise access without direct sales infrastructure. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors API-native specialists with ISO 27001 certification and vertical workflow depth. Long-term viability across the projection horizon rests on compliance automation capabilities rather than transaction volume scale. Watch API integration talent scarcity as the inflection signal—platforms with captive engineering pipelines command premium valuations.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | Decouples frontend experience from backend commerce logic for manufacturing buyers. |
| ISO 27001 Certification Investment | Unlocks regulated industry procurement mandates in Germany and United States. |
| Vertical Marketplace Development | Captures Mittelstand chemical supplier tiers through REACH compliance automation. |
| Carbon Accounting Integration | Addresses EU CSRD scope 3 disclosure requirements for industrial buyers. |
| Strategic Partnership with Hyperscalers | Secures elastic infrastructure for seasonal manufacturing demand spikes. |
Research Approach
A spread of perspectives from procurement directors, platform engineering leads, systems integrator partners, and compliance officers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, customs trade data, and ISO certification registries. Bottom-up transaction volume estimates triangulated against top-down cloud infrastructure spending allocations.
Demand-supply balance across deployment models, solution types, and end-user industries anchored the analytical framework. Segmentation dimensions modeled include cloud versus on-premise architecture, order management versus contract management solutions, and manufacturing versus wholesale distribution verticals. CAGRs derived from elasticity-adjusted adoption curves and infrastructure capacity buildouts. Cross-border payment corridor development and SAMR compliance timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by API-native entrants or state-backed industrial marketplace operators would shift outcomes. Macroeconomic contraction in manufacturing capital expenditure, regulatory fragmentation escalation, or breakthroughs in quantum-secure data transmission would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Saudi Arabia Delivery Apps Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
E-Commerce Market