
 Global Assembly Line Solutions Market | 2026-2036
Global Assembly Line Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Assembly Line Solutions Market Foresight
ISO 10218 robot safety certification is unwinding competitive barriers for new entrants in collaborative automation. ABB Ltd. leverages its European installed base to anchor premium retrofit contracts. Fanuc Corporation dominates precision servo applications through captive supply of motion controllers. Siemens AG competes on digital twin integration, bundling hardware with edge analytics software.
Assembly line solutions comprise integrated material handling, robotic manipulation, and process control architectures designed to synchronize discrete manufacturing workflows. Conveyor systems coordinate work-in-progress movement across stations, while robotic arms execute programmed pick-place-sequence operations with repeatability tolerances below 0.1 millimeter. Robotic arms command the largest margin pool due to aftermarket service attach rates, yet automated guided vehicles represent the fastest-expanding category as warehouse-to-factory logistics blur. Control units remain the most mature segment, with pricing pressure from open-source PLC alternatives eroding proprietary stack value.
FDA quality system regulations shape pharmaceutical processing line design, mandating 21 CFR Part 11 electronic record compliance for traceability. The EU AI Act imposes conformity assessment burdens on machine vision systems deployed in European automotive plants. OSHA lockout-tagout standards govern US conveyor maintenance protocols, extending equipment procurement cycles. Stakeholders must weigh regulatory certification timelines against modular upgrade paths when allocating capital across brownfield and greenfield installations.
Market Dynamics
The convergence of EU Green Deal manufacturing mandates with China's dual carbon goals is forcing automotive and electronics OEMs to retrofit legacy plants with cyber-physical systems, compressing equipment replacement cycles and elevating demand for modular, energy-efficient assembly architectures.
Growth Catalysts
- EU AI Act conformity pathways:Machine vision systems deployed in European automotive plants now require documented risk assessments, creating certified supplier preference and locking in upgrade budgets for compliant integrators.
- Yangtze River Delta electronics corridor:Contract manufacturers in this cluster are retrofitting legacy semiconductor packaging lines with collaborative robots to meet Apple and Tesla supplier qualification thresholds.
- Battery gigafactory buildouts:Cell assembly lines for electric vehicles require precision stacking and welding stations, pulling high-repeatability servo systems into automotive supplier toolkits.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnets for precision servo motors source predominantly from Chinese processing facilities, exposing motion control OEMs to export quota volatility and price spikes.
- ISO 10218 certification timelines:Collaborative robot safety validation requires 14-18 month third-party testing cycles, delaying product launches and freezing R&D amortization schedules.
- Open-source PLC erosion:Codesys and similar platforms are commoditizing proprietary control stack value, compressing margins on hardware-centric vendors.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Smartphone and component assembly incentives are attracting Foxconn and Dixon Technologies to establish greenfield facilities requiring full-line automation deployment.
- Digital twin-physical system convergence:Siemens and ABB are bundling edge analytics with hardware, creating sticky subscription revenue streams that extend beyond equipment installation.
- FDA 21 CFR Part 11 compliance gaps:Pharmaceutical contract manufacturers in North America and Europe need electronic batch record systems, opening retrofit contracts for validated assembly line integrators.
Industry Challenges
- Mechatronics technician scarcity:Germany's KBA and industrial associations report 45,000 unfilled positions for robot maintenance and PLC programming, extending commissioning timelines.
- Brownfield integration complexity:Retrofitting 1990s-era conveyor systems with AGV handoff stations requires custom mechanical interfaces and disrupts production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Assembly Line Solutions Market |
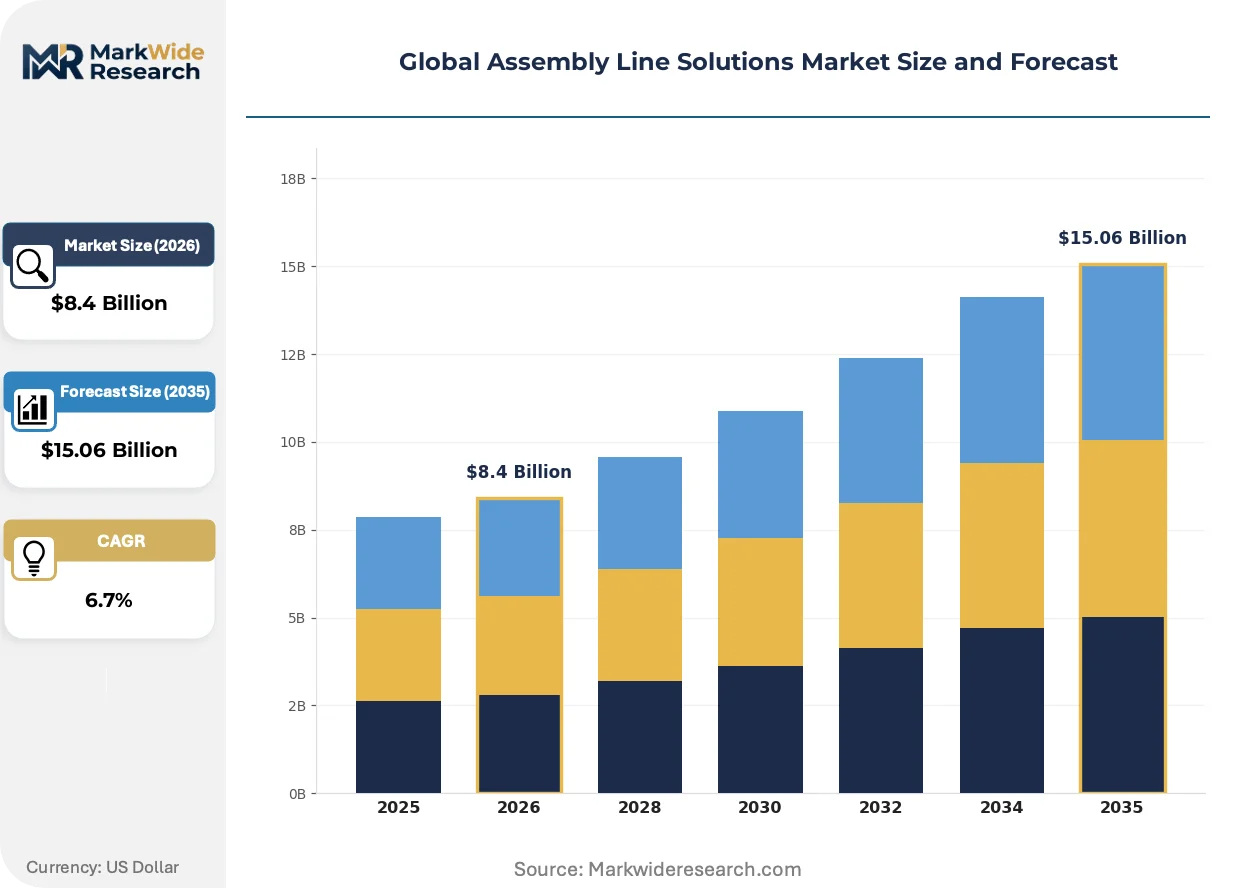
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Robotic Arms, Automated Guided Vehicles, Inspection Systems, Control Units Technology: Machine Vision, Programmable Logic Controllers, IoT Integration, Artificial Intelligence, Cyber-Physical Systems Application: Electronics Manufacturing, Aerospace Fabrication, Food Packaging, Consumer Goods Assembly, Pharmaceutical Processing End User Industry: Original Equipment Manufacturers, Contract Manufacturing Firms, Aftermarket Suppliers, Assembly Line Integrators |
| Companies Covered | Rockwell Automation, JR Automation, ABB Ltd., Yaskawa Electric Corporation, Fanuc Corporation, Siemens AG, Bosch Rexroth AG, BBS Automation, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Assembly Line Solutions Market Shifts & Advancements
Active inference and edge-deployed AI are compressing the gap between sensing and actuation, enabling assembly lines to self-optimize without cloud latency. This shift is redrawing competitive boundaries between hardware OEMs and software-native entrants.
Collaborative robots with force-torque sensing and adaptive trajectory planning are supplanting traditional caged industrial arms in small-batch automotive and electronics assembly. Tier-2 suppliers in Germany and South Korea are adopting these systems at 18-month replacement cycles versus 7-year norms for conventional robots. The technology is supplanting fixed automation investments and enabling mixed-model production with sub-15-minute changeovers.
REACH substance restrictions and F-Gas Regulation phase-downs are banning hydrofluorocarbon-based cooling in precision servo drives across European installations. Manufacturers must redesign thermal management architectures using water-glycol loops or dielectric fluids. Automotive stamping and body-in-white lines in Germany, Czech Republic, and Slovakia face 2027 compliance deadlines, accelerating procurement of next-generation motion controllers.
Pharmaceutical and medical device buyers are unbundling aftermarket service contracts from initial equipment purchases, forcing automation vendors to compete on transparent hourly rates and remote diagnostic capabilities. This procurement evolution is most visible in North American biologics manufacturing, where Amgen and Moderna facilities now specify API-based predictive maintenance platforms as contract prerequisites. Equipment suppliers must restructure revenue recognition and field service organizations to capture recurring revenue without captive service lock-in.
Global Assembly Line Solutions Market Segmentation
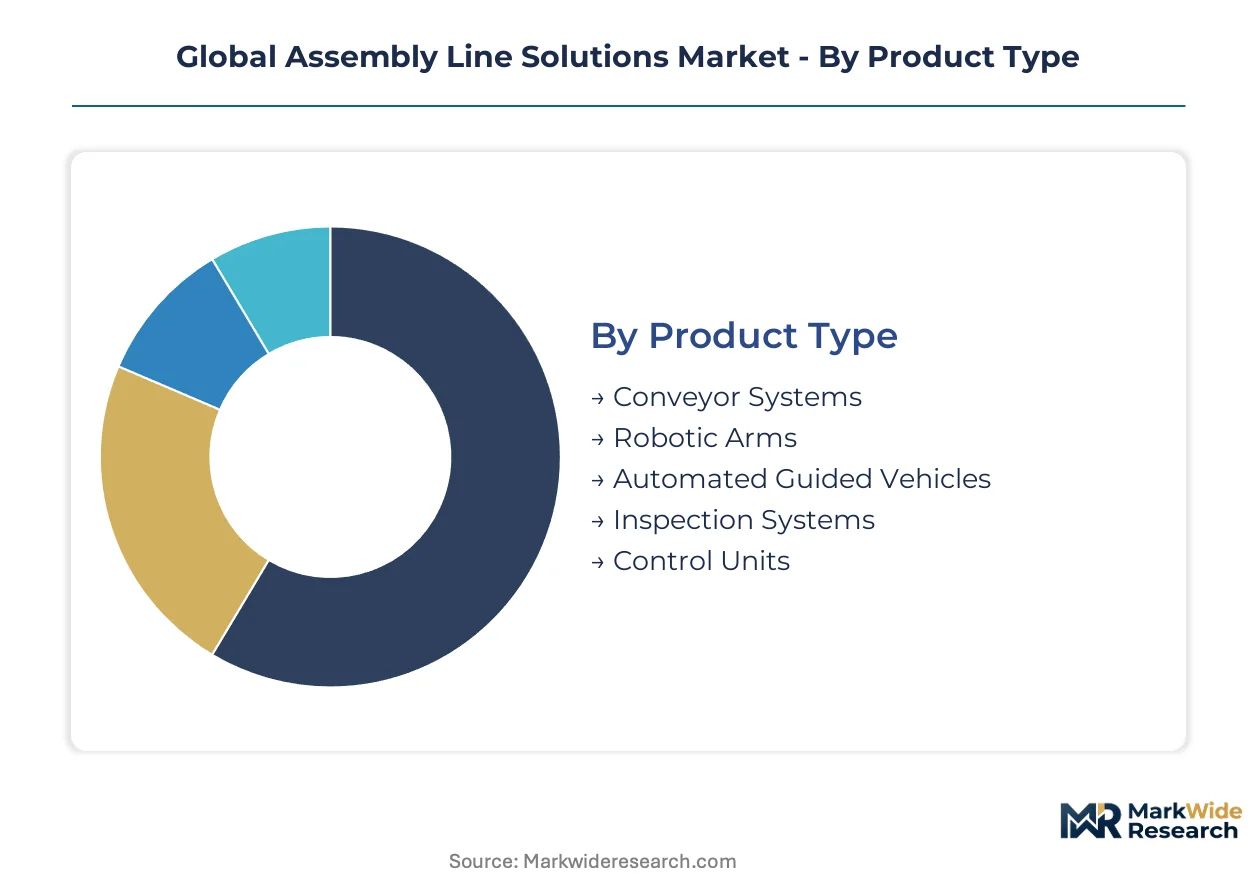
Segmentation in assembly line solutions reveals divergent margin profiles across hardware, software, and integration layers. Technology choices determine recurring revenue potential, while application verticals dictate regulatory complexity and contract duration.
Product Type:
Margin pools concentrate in robotic manipulation hardware and aftermarket service attach rates, with conveyor systems facing commoditization pressure from modular open-source alternatives.
- Conveyor Systems:Belt and roller architectures coordinate work-in-progress movement across stations with throughput rates exceeding 10,000 units per hour. Demand concentrates in China's Yangtze River Delta electronics corridor, where Foxconn and Luxshare retrofit legacy plants with magnetic levitation conveyors to reduce energy draw under dual carbon mandates.
- Robotic Arms:Six-axis and SCARA configurations execute pick-place-sequence operations with repeatability tolerances below 0.1 millimeter. Automotive OEMs in Germany anchor premium retrofit contracts, driven by EU Green Deal manufacturing standards requiring collaborative robot integration for mixed-model flexibility.
- Automated Guided Vehicles:Warehouse-to-factory logistics blur is pulling AGV deployments into brownfield automotive and electronics facilities.
- Inspection Systems:Machine vision and coordinate measuring machines enforce quality gates at line speed.
- Control Units:Proprietary PLC stacks face erosion from Codesys and open-source alternatives, compressing hardware-centric vendor margins.
The dominant share belongs to Robotic Arms, while Automated Guided Vehicles is closing the gap fastest.
Technology:
Adoption velocity varies sharply by deployment complexity, with edge-deployed architectures commanding implementation premiums over centralized control systems.
- Machine Vision:Camera arrays and deep learning inference engines perform defect detection at sub-millimeter resolution. European automotive plants now require documented risk assessments under EU AI Act conformity pathways, locking in upgrade budgets for certified integrators.
- Programmable Logic Controllers:Industrial controllers execute ladder logic with deterministic cycle times. Open-source alternatives are commoditizing proprietary stack value, forcing Siemens and Rockwell to bundle edge analytics subscriptions.
- IoT Integration:Sensor networks and OPC-UA protocols enable real-time production monitoring.
- Artificial Intelligence:Active inference algorithms compress sensing-to-actuation latency for self-optimizing lines.
- Cyber-Physical Systems:Digital twin-physical convergence creates sticky recurring revenue streams extending beyond installation.
Cyber-Physical Systems capture the highest implementation premiums, though Artificial Intelligence is expanding most quickly as edge deployment costs decline.
Application:
Regulatory burden intensity separates pharmaceutical and aerospace contracts from consumer-facing verticals, with validation timelines extending procurement cycles.
- Electronics Manufacturing:Surface-mount technology lines and semiconductor packaging require precision placement at micron tolerances. Contract manufacturers in South Korea and Taiwan retrofit legacy facilities with collaborative robots to meet Apple and Tesla supplier qualification thresholds.
- Pharmaceutical Processing:Aseptic filling and packaging lines enforce FDA 21 CFR Part 11 electronic record compliance. North American biologics manufacturers at Amgen and Moderna facilities now specify API-based predictive maintenance platforms as contract prerequisites.
- Aerospace Fabrication:Composite layup and riveting stations demand force-controlled manipulation.
- Food Packaging:Washdown-rated automation handles high-speed primary and secondary packaging.
- Consumer Goods Assembly:High-volume, low-mix lines prioritize throughput over flexibility.
Electronics Manufacturing holds the largest installed base, while Pharmaceutical Processing is gaining share fastest on compliance-driven retrofit demand.
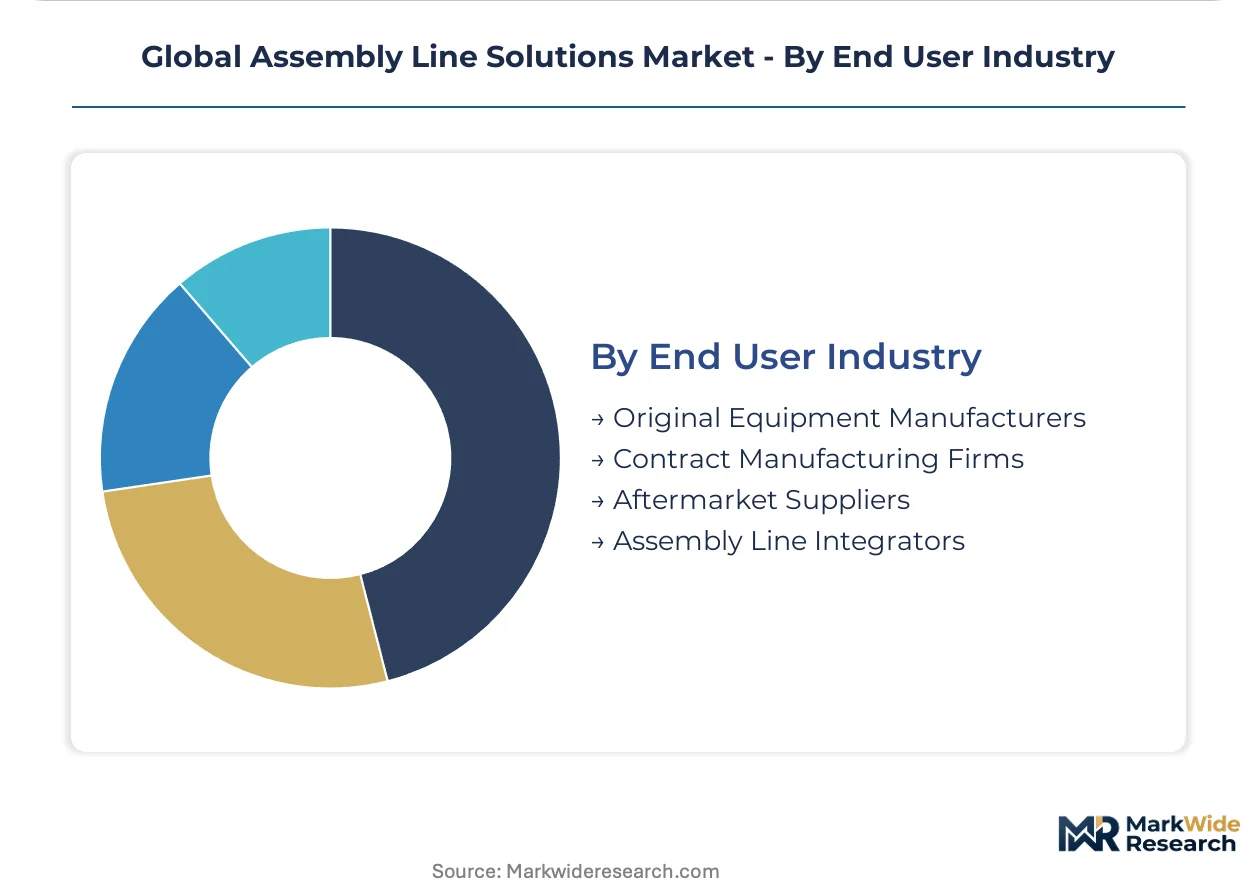
End User Industry:
Procurement authority concentration shapes sales cycle dynamics, with OEMs driving standardization and integrators capturing implementation margins.
- Original Equipment Manufacturers:Automotive and electronics OEMs specify equipment architectures across supplier networks. Germany's KBA reports 45,000 unfilled mechatronics technician positions, extending commissioning timelines for BMW and Volkswagen brownfield retrofits.
- Contract Manufacturing Firms:Foxconn, Jabil, and Flex operate build-to-print assembly at massive scale. India's PLI scheme for electronics manufacturing is attracting greenfield facility establishment by Foxconn and Dixon Technologies, requiring full-line automation deployment.
- Aftermarket Suppliers:Spare parts and refurbishment services extend equipment lifecycle value.
- Assembly Line Integrators:System houses bundle hardware, software, and commissioning for turnkey delivery.
Original Equipment Manufacturers command the largest contract values, while Contract Manufacturing Firms are expanding most aggressively on reshoring incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is attracting Foxconn and Dixon Technologies to establish greenfield facilities requiring full-line automation deployment. Germany's KBA reports 45,000 unfilled mechatronics technician positions, extending commissioning timelines for automotive brownfield retrofits. China's dual carbon goals are compressing equipment replacement cycles across the Yangtze River Delta electronics corridor.
United States
OSHA lockout-tagout standards govern conveyor maintenance protocols, extending equipment procurement cycles for automotive and aerospace fabricators. FDA 21 CFR Part 11 electronic record compliance mandates shape pharmaceutical processing line design in North American biologics manufacturing. Amgen and Moderna facilities in Massachusetts and California now specify API-based predictive maintenance platforms as contract prerequisites.
Germany
EU Green Deal manufacturing standards require automotive OEMs to expand robotic integration for mixed-model flexibility. REACH substance restrictions and F-Gas Regulation phase-downs are banning hydrofluorocarbon-based cooling in precision servo drives, forcing thermal management redesigns by 2027. Automotive stamping and body-in-white lines in Bavaria, Baden-Württemberg, and North Rhine-Westphalia face accelerated procurement of next-generation motion controllers.
China
Dual carbon mandates are forcing contract manufacturers in the Yangtze River Delta electronics corridor to retrofit legacy plants with cyber-physical systems. MIIT standards govern industrial robot safety certification, creating compliance timelines for collaborative automation deployment. Foxconn and Luxshare facilities in Jiangsu and Zhejiang provinces are installing magnetic levitation conveyors to reduce energy draw.
India
The PLI scheme for electronics manufacturing is attracting Foxconn and Dixon Technologies to establish greenfield smartphone assembly facilities. BIS certification requirements shape equipment procurement specifications for contract manufacturers. Tamil Nadu and Karnataka industrial corridors are seeing full-line automation deployment to meet Apple and Tesla supplier qualification thresholds.
South Korea
MFDS pharmaceutical quality regulations enforce electronic batch record systems for aseptic processing lines. Tier-2 automotive suppliers are adopting collaborative robots with force-torque sensing at 18-month replacement cycles versus 7-year norms. Electronics contract manufacturers in Gyeonggi Province retrofit legacy semiconductor packaging lines to meet global OEM qualification standards.
Global Assembly Line Solutions Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive motion control supply, creating tiered competition between hardware-centric vendors and software-native integrators. The vendor base clusters around three strategic archetypes: European engineering houses bundling digital twin platforms, Japanese precision servo specialists with vertical component control, and North American automation integrators targeting pharmaceutical validation workflows. Dominant competitive moves include strategic partnerships for edge analytics bundling and geographic expansion into India's PLI-subsidized electronics manufacturing corridors.
Among diversified European engineering houses, ABB Ltd., Siemens AG, and Bosch Rexroth AG exemplify the convergence of hardware manufacturing with software subscription models. These Zurich-based, Munich-based, and Lohr am Main-based entities occupy positions where digital twin-physical system convergence creates sticky recurring revenue streams extending beyond equipment installation. Japanese specialists Fanuc Corporation and Yaskawa Electric Corporation represent the precision servo archetype, with their Oshino and Kitakyushu origins reflecting geographic concentration in motion controller captive supply. North American integrators Rockwell Automation and JR Automation anchor the pharmaceutical and automotive validation tier, with their Milwaukee and Holland, Michigan bases situating them near FDA-regulated biologics manufacturing clusters and Detroit-area automotive stamping operations.
| Leading Market Players |
|---|
| Rockwell Automation |
| JR Automation |
| ABB Ltd. |
| Yaskawa Electric Corporation |
| Fanuc Corporation |
| Siemens AG |
| Bosch Rexroth AG |
| BBS Automation |
| KUKA AG |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for rare earth magnets lock in both supply access and price visibility for motion control OEMs, insulating tier-1 integrators from export quota volatility while exposing spot-market buyers to Chinese processing facility pricing swings.
Pricing Analysis
Certification level (ISO 10218/FDA-grade) creates the primary spread between premium retrofit integrators and commodity hardware vendors. Three-tier pricing structure across premium, standard, and economy levels bundles edge analytics subscriptions at the top tier while bare-bone PLC configurations compete on unit economics. Price compression runs through the control unit segment as Codesys alternatives commoditize proprietary stack value. Contract manufacturers in India's PLI corridors show highest price sensitivity, whereas German automotive OEMs prioritize compliance-grade certification over procurement cost.
Supply Chain Analysis
Rare earth magnet processing concentration in Chinese facilities anchors the chokepoint for precision servo motor supply chains. Permanent magnet sourcing draws from Jiangxi and Inner Mongolia refining complexes, while motion controller semiconductors rest on Taiwanese foundry output. Single-source vulnerability in neodymium-dysprosium processing exposes ABB and Fanuc to export quota disruptions. Distribution runs through regional integrator networks with captive service arms, bypassing direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service attach rates for robotic arms are expanding faster than hardware shipments, converting one-time equipment sales into recurring predictive maintenance subscriptions across pharmaceutical and automotive installed bases.
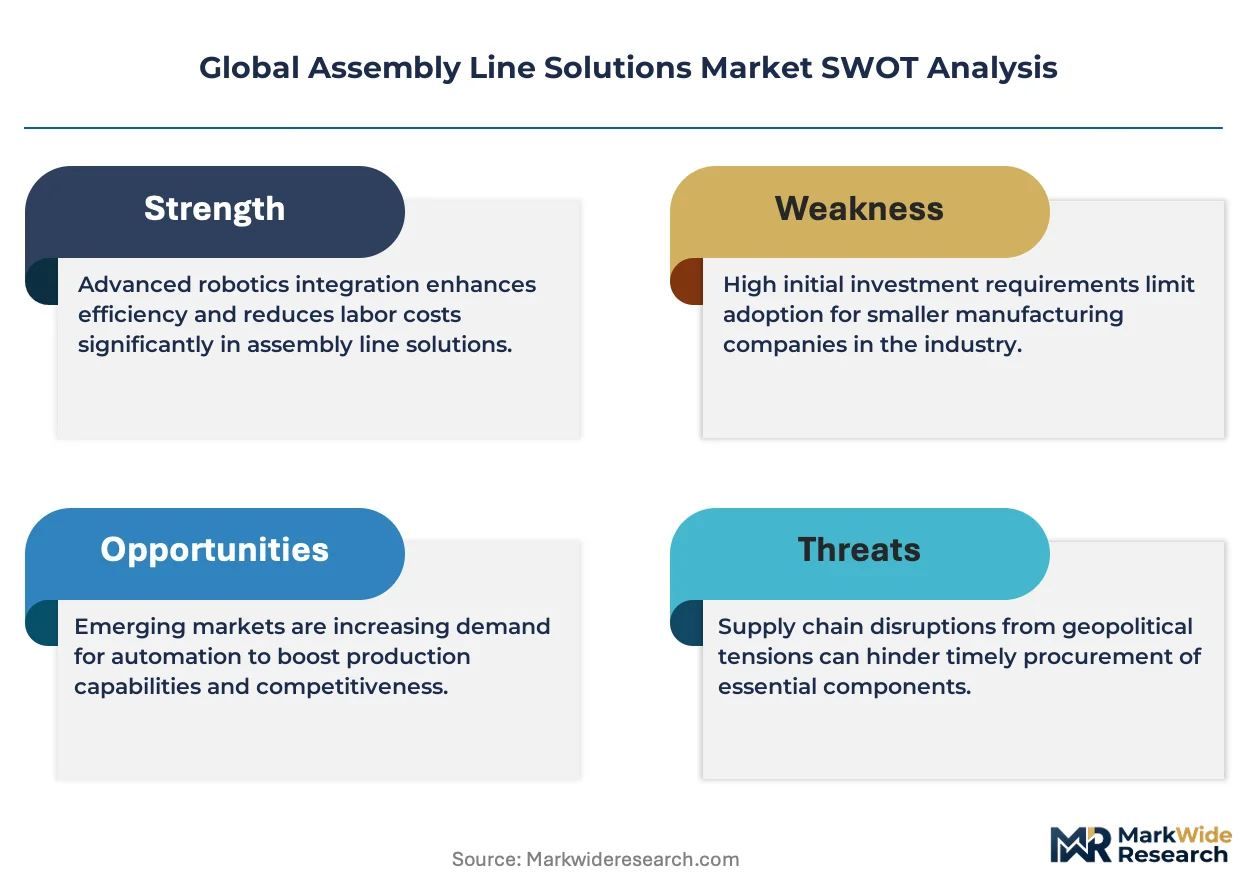
For Market Incumbents: Compound defensive moats by deepening captive supply of motion controllers and securing ISO 10218 certification ahead of collaborative robot safety mandates. Siemens and ABB must accelerate digital twin bundling to offset open-source PLC erosion in control unit pricing. Priority investment targets brownfield retrofit integration capabilities where technician scarcity extends commissioning timelines. For New Entrants and Emerging Players: Differentiate on FDA 21 CFR Part 11 validation workflows for North American pharmaceutical contract manufacturers, where incumbent service unbundling creates white-space for API-based predictive maintenance platforms. India's PLI-subsidized electronics corridors offer the most penetrable geography for greenfield full-line automation deployment. Go-to-market motion should anchor on transparent hourly service rates rather than captive lock-in contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European engineering houses bundling cyber-physical system subscriptions with hardware installation. Long-term viability favors targets with validated pharmaceutical processing line credentials and edge analytics software stacks. Watch collaborative robot safety certification timelines as inflection indicator for competitive barrier erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens and ABB bundle edge analytics with hardware to create sticky subscription revenue streams beyond installation. |
| Backward Integration into Motion Controllers | Fanuc and Yaskawa secure captive servo supply to shield margins from rare earth magnet price volatility. |
| Pharmaceutical Validation Workflow Investment | Rockwell Automation targets FDA 21 CFR Part 11 compliance gaps in North American biologics manufacturing clusters. |
| Geographic Expansion into India PLI Corridors | Foxconn and Dixon Technologies greenfield facilities in Tamil Nadu require full-line automation deployment partners. |
| Collaborative Robot Safety Certification | ISO 10218 compliance timelines create certified supplier preference for European automotive brownfield retrofits. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and assembly line integrators; and secondary validation through SEC filings, customs/trade data, MIIT robot safety certifications, and EU AI Act conformity documentation. Bottom-up equipment shipment triangulation against top-down manufacturing capex disclosures anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation by product type (conveyor systems, robotic arms, AGVs, control units), technology layer (machine vision, PLCs, cyber-physical systems), and application vertical (electronics manufacturing, pharmaceutical processing, automotive fabrication). CAGRs derived from equipment replacement cycle compression under EU Green Deal and China dual carbon mandates, cross-referenced with technician scarcity constraints in Germany.
Material uncertainties — rare earth export quota disruptions, ISO 10218 certification timeline extensions, open-source PLC commoditization acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance pacing and reshoring incentive durability. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and India PLI scheme renewal negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Linear Motion System Market
Industrial Automation
North America and Europe Retail Automation Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Modular Automation and Services Market
Industrial Automation
UV Curing System Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Europe Retail Automation Market