
 North America Machine Control System Market | 2026-2036
North America Machine Control System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Machine Control System Market Analytics
Canadian sensor module producers are repositioning their assembly lines toward tighter integration with OEM hydraulic platforms. Trimble Inc. leverages its dominance in GNSS correction services to anchor pricing power across the Great Plains contractor base. Hexagon AB sustains R&D intensity in laser scanning fusion algorithms that differentiate its offerings from commodity guidance packages. Topcon Corporation competes aggressively on total cost of ownership for mid-tier earthmoving fleets in the southeastern United States.
A machine control system integrates real-time kinematic positioning, inertial measurement units, and electro-hydraulic valve actuators to automate blade, bucket, and boom movements within three-dimensional design surfaces, typically achieving horizontal accuracies of one to three centimeters. These systems eliminate manual grade staking, reduce material overruns, and compress project schedules in heavy civil and residential construction. Hardware components including GNSS receivers, machine-mounted tablets, and angle sensors currently command the largest revenue share, while cloud-based installation types are expanding fastest as fleet managers prioritize over-the-air configuration updates and remote diagnostics across dispersed job sites. PID control technology retains broad applicability in repetitive earthworks, though PLC-based architectures are gaining traction in integrated plant environments where machine control must synchronize with batch processing and material handling systems.
The Federal Aviation Administration's evolving Part 107 framework for commercial drone operations directly shapes how contractors deploy aerial photogrammetry to generate machine-guidance terrain models, while EPA Tier 4 Final compliance costs are accelerating replacement of older unguided fleets with precision-equipped machines. OSHA excavation safety standards create additional pull for automated depth and slope limiting functions that reduce operator error in trenching applications. Stakeholders must monitor how NHTSA autonomous vehicle research programs cross-pollinate with off-road machine autonomy standards, as this regulatory convergence will determine which control architectures achieve long-term platform status.
Market Dynamics
Contractor procurement patterns across the United States and Canada are forcing control system vendors to decouple hardware from software subscriptions, reshaping how fleet operators budget for precision guidance capabilities over multi-year equipment lifecycles.
Growth Catalysts
- FAA Part 107 Evolution:The Federal Aviation Administration's expanding commercial drone framework permits faster aerial terrain survey turnaround, accelerating photogrammetry-to-machine-guidance workflows for earthmoving contractors.
- Texas-Oklahoma Energy Corridor:Pipeline and pad construction in this concentrated geography demands millimeter-grade elevation control, pulling advanced 3D machine control into mid-tier fleet specifications.
- OSHA Excavation Standards:Automated depth and slope limiting functions reduce trenching liability exposure, creating specification pull from safety-conscious municipal and utility contractors.
Market Restraints
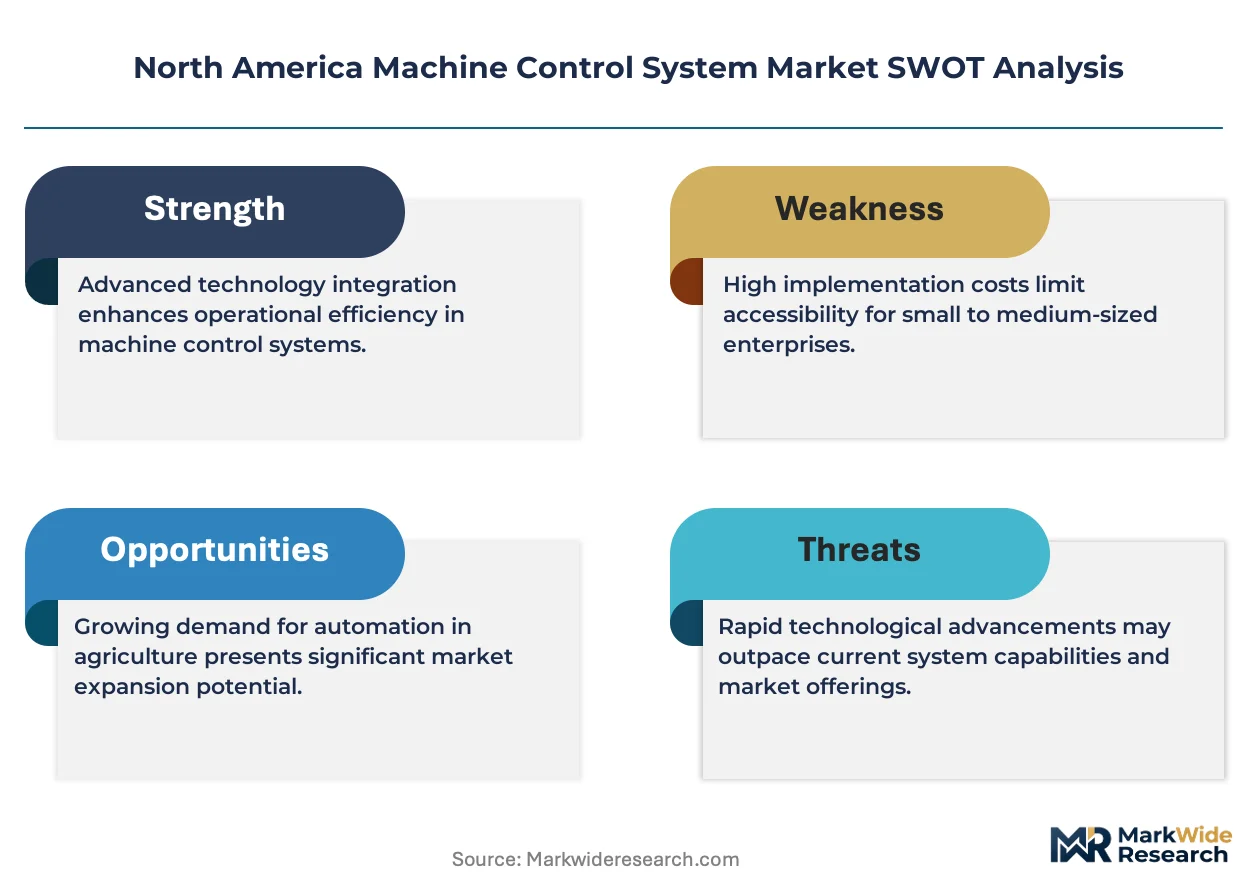
- GNSS Correction Service Concentration:Real-time kinematic subscription pricing remains controlled by a narrow supplier base, limiting contractor negotiating leverage on recurring costs.
- EPA Tier 4 Final Compliance:Emissions hardware costs on new machine purchases compress capital budgets available for precision control retrofits on existing iron.
- Electro-Hydraulic Valve Integration:OEM hydraulic platform fragmentation forces control vendors to maintain multiple actuator calibrations, elevating engineering overhead.
Strategic Opportunities
- Canadian Prairie Provinces:Agricultural drainage and resource road construction in Manitoba and Saskatchewan remain underpenetrated relative to US adoption rates.
- Cloud-Based Configuration:Over-the-air firmware updates and remote diagnostic portals enable vendors to capture recurring revenue from dispersed fleet operators.
- Laser-GNSS Sensor Fusion:Converging optical and satellite positioning architectures open specification opportunities in canopy-covered forestry and urban canyon environments.
Industry Challenges
- RTK Network Technician Scarcity:Field calibration of base station infrastructure requires specialized competency that contractor training programs have not scaled to match fleet growth.
- Legacy CAN Bus Integration:Older earthmoving equipment lacks standardized diagnostic ports, forcing custom harness fabrication that extends installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Machine Control System Market |
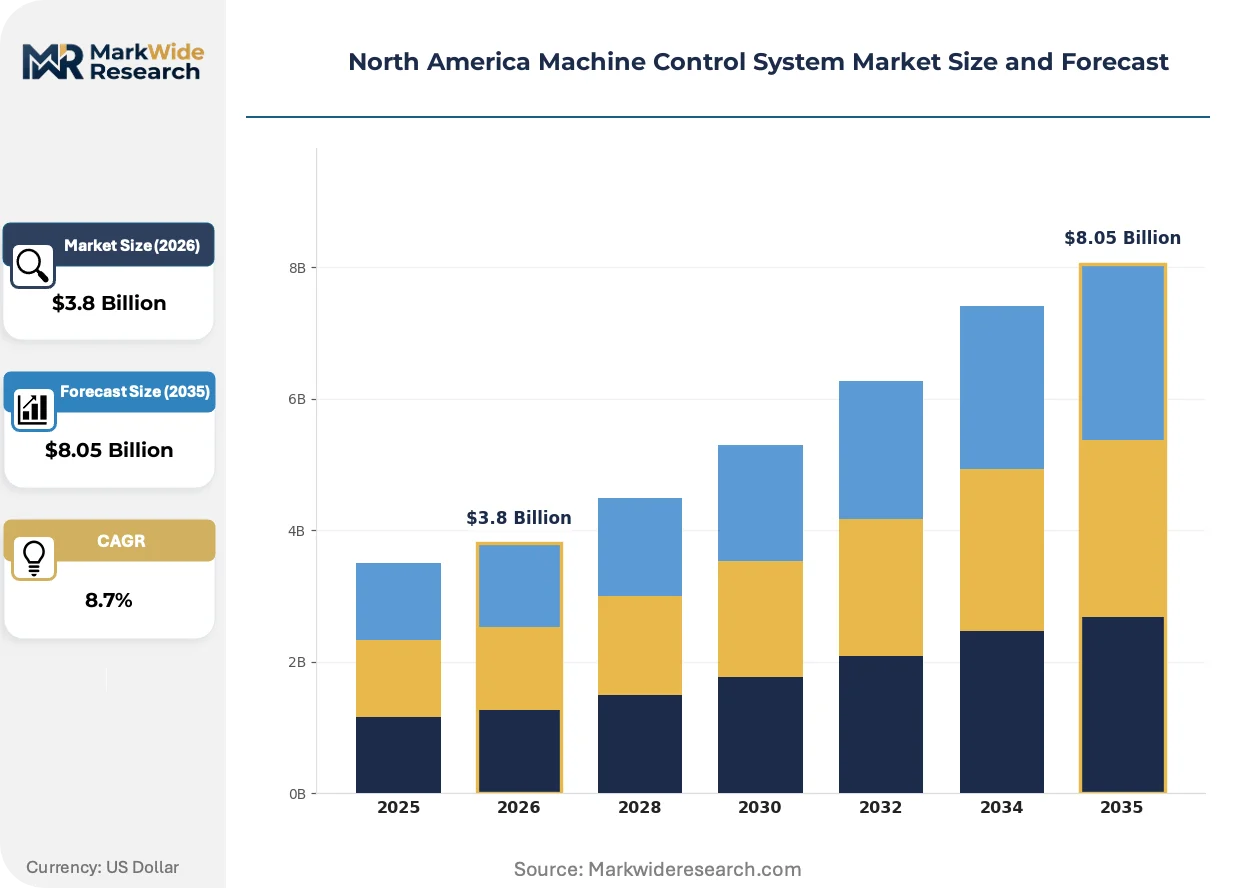
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Control Units, Sensors Technology: PID Control, PLC, SCADA, HMI End User: Manufacturing, Construction, Automotive, Aerospace Installation Type: On-premises, Cloud-based, Hybrid, Remote |
| Companies Covered | Trimble Inc., Topcon Corporation, Hexagon AB, MOBA Mobile Automation AG, Hemisphere GNSS Inc., ABB, Schneider Electric SE, Komatsu Ltd., Leica Geosystems AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Machine Control System Market Evolving Landscape
Control architectures are migrating from standalone guidance packages toward embedded autonomy stacks, compressing the boundary between operator-assist functions and semi-autonomous earthmoving.
Real-time kinematic positioning paired with inertial measurement units is expanding into mid-tier dozer and motor grader fleets previously served by laser-only or unguided operation. Regional contractors in the southeastern United States now specify these fused systems for subdivision grading and commercial site work. The technology is expanding into rental fleet channels, forcing OEMs to standardize hydraulic valve interfaces across model years.
The Federal Aviation Administration's Part 107 waiver processing for beyond-visual-line-of-sight drone operations directly shapes how contractors generate machine-guidance terrain models. Faster waiver turnaround compresses survey-to-cut cycles from weeks to days. Earthmoving fleets in the Great Lakes manufacturing belt now integrate aerial photogrammetry into weekly production scheduling.
Equipment-as-a-service arrangements are displacing outright purchase for precision control systems among municipal and utility contractors with constrained capital budgets. Rental houses in Texas and Oklahoma now bundle GNSS-equipped excavators with operator training and correction service subscriptions. This shift concentrates specification influence with fleet procurement officers rather than individual machine owners.
North America Machine Control System Market Segmentation
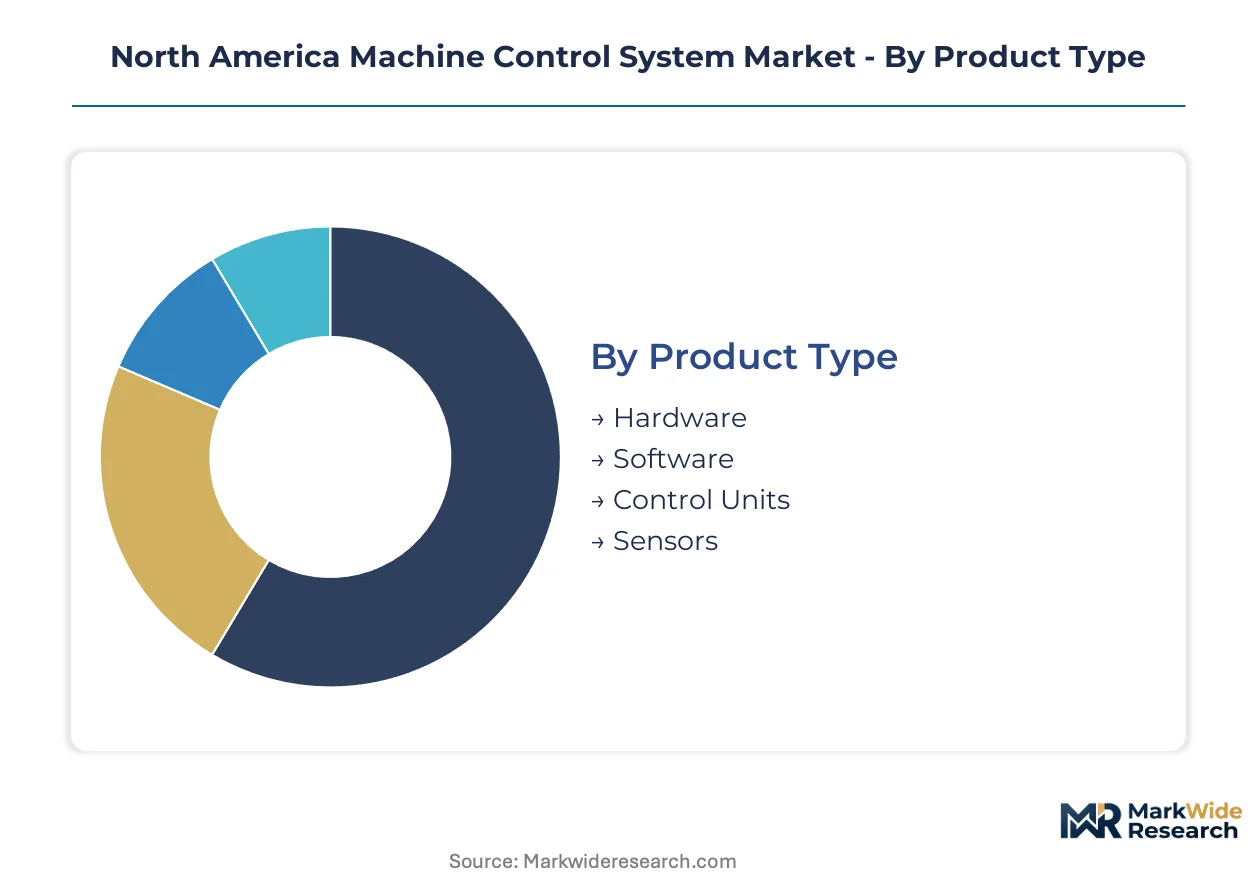
Machine control system procurement patterns diver sharply across buyer profiles, with capital-intensive earthmoving contractors prioritizing durability and subscription-averse municipal fleets demanding cloud flexibility. Understanding these fault lines reveals where specification power concentrates and how vendors must architect their go-to-market approaches.
Product Type:
Hardware buyers prioritize integration speed with existing hydraulic platforms, while software purchasers weight recurring cost predictability against feature refresh cycles.
- Hardware:GNSS receivers, machine-mounted tablets, and angle sensors constitute the installed base foundation. Demand clusters in the Texas-Oklahoma energy corridor where pipeline contractors specify military-grade shock resistance for rough-terrain deployment.
- Software:Firmware platforms and operator interface applications enable real-time design surface visualization. Canadian prairie contractors in Manitoba and Saskatchewan are expanding adoption fastest as drainage project complexity outpaces manual staking capacity.
- Control Units:Electro-hydraulic valve controllers translate positioning data into blade and bucket automation.
- Sensors:Inertial measurement units and optical encoders provide motion feedback independent of satellite visibility.
Hardware leads volumes today; software is gaining share fastest.
Technology:
Control architecture selection tracks the sophistication of surrounding automation infrastructure, with isolated earthmoving fleets favoring simplicity and integrated plant environments requiring protocol interoperability.
- PID Control:Proportional-integral-derivative loops govern repetitive earthworks with minimal computational overhead. Municipal grading contractors across the southeastern United States specify these systems for subdivision work where design surfaces change infrequently.
- PLC:Programmable logic controllers synchronize machine movements with batch processing and material handling systems. Demand concentrates in Great Lakes manufacturing belt aggregate operations where crushing and conveying equipment must coordinate with mobile fleet positioning.
- SCADA:Supervisory control platforms enable centralized fleet monitoring across dispersed job sites.
- HMI:Human-machine interfaces streamline operator training and reduce calibration error rates.
PID control anchors current deployment; PLC architectures are climbing the fastest as quarry and plant integration requirements intensify.
End User:
Sector-specific safety and precision mandates reshape specification priorities, with regulated industries demanding audit trails and commercial contractors prioritizing speed-to-cut.
- Construction:Heavy civil and residential earthmoving commands the deepest precision control penetration. OSHA excavation standards drive automated depth limiting adoption among utility contractors in the Great Lakes manufacturing belt.
- Manufacturing:Industrial plant environments require machine control synchronization with production scheduling systems. Automotive stamping facilities in the southeastern United States specify PLC-based architectures for press line material positioning.
- Automotive:Assembly line automation and test track surveying applications.
- Aerospace:Runway grading and hangar foundation work demanding millimeter-grade elevation tolerance.
Construction dominates current revenue; manufacturing is expanding most quickly as plant automation convergence accelerates.
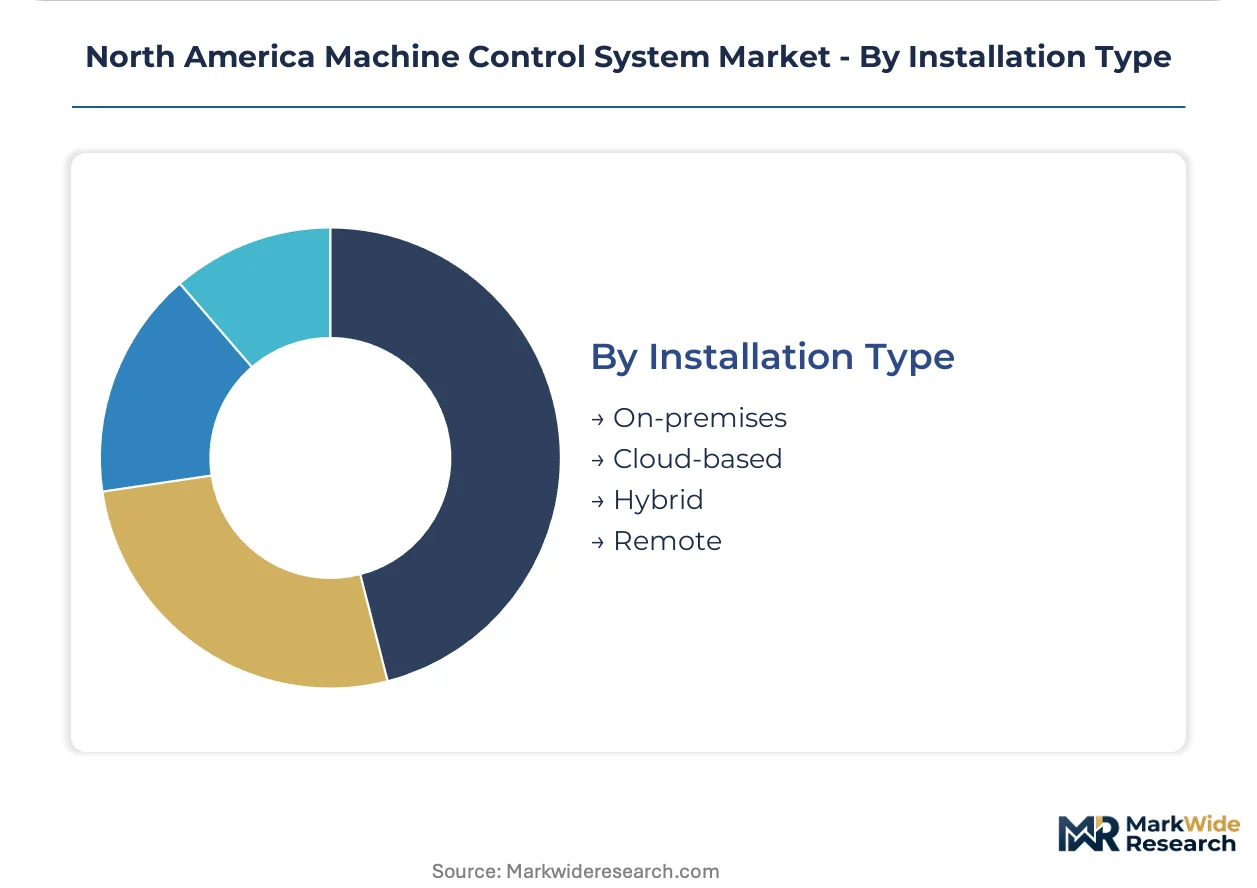
Installation Type:
IT governance maturity and fleet dispersion determine whether buyers favor localized control or centralized management portals.
- On-premises:Local server installations retain full data sovereignty and minimize connectivity dependency. Large integrated contractors in the Texas-Oklahoma energy corridor favor this model for competitive isolation of terrain survey data.
- Cloud-based:Over-the-air firmware updates and remote diagnostic access reduce field technician dispatch frequency. Municipal fleets across Canadian prairie provinces specify these platforms to manage geographically dispersed equipment pools.
- Hybrid:Edge computing with cloud synchronization for sensitive operations.
- Remote:Fully centralized configuration management for rental fleet standardization.
On-premises retains the largest installed base; cloud-based deployment is showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's machine control adoption trails the United States by approximately three years, though Prairie Provinces drainage contractors are closing the gap faster than Ontario's municipal fleets. Mexico's infrastructure pipeline is accelerating precision equipment imports through Nuevo León's industrial corridor.
United States
Pipeline construction in the Texas-Oklahoma energy corridor demands millimeter-grade elevation control for pad and trench work. FAA Part 107 waivers for beyond-visual-line-of-sight drone operations compress survey-to-cut cycles from weeks to days across the Great Plains. Earthmoving contractors in the southeastern United States now specify fused GNSS-IMU systems for subdivision grading that previously relied on laser-only guidance.
Canada
Drainage project complexity in Manitoba and Saskatchewan outpaces manual staking capacity, pulling RTK-equipped dozers into mid-tier fleet specifications. Health Canada's evolving guidelines for unmanned aerial surveying in agricultural applications directly shape how prairie contractors generate machine-guidance terrain models. Sensor module producers in Ontario are repositioning assembly lines toward tighter integration with OEM hydraulic platforms serving Alberta's oil sands remediation.
Mexico
Federal infrastructure spending through the Secretariat of Communications and Transportation is accelerating GPS-guided earthmoving equipment procurement for highway modernization. Nuevo León's industrial corridor around Monterrey concentrates demand from automotive plant construction requiring PLC-synchronized machine control for press line material positioning. Contractors in the Bajío Region are adopting cloud-based configuration platforms to manage dispersed equipment pools across Guanajuato and Querétaro quarry operations.
Pacific Northwest
Forestry road construction in Oregon and Washington's canopy-covered terrain drives specification of laser-GNSS sensor fusion systems where satellite visibility degrades. EPA enforcement of Clean Water Act Section 404 permits for wetland impacts creates audit trail requirements that automated depth limiting functions satisfy. Seattle-area municipal contractors prioritize cloud-based remote diagnostics to manage equipment pools across dispersed watershed restoration sites.
North America Machine Control System Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in high-precision correction services and sensor fusion algorithms. The vendor base organizes around three strategic archetypes: integrated positioning service providers, hydraulic platform-agnostic control module specialists, and OEM-captive automation divisions. Consolidation pressure concentrates among mid-tier sensor manufacturers facing R&D scale disadvantages against full-stack competitors. Dominant competitive moves include strategic partnerships with rental fleet operators and technology licensing agreements that accelerate hydraulic valve calibration standardization.
Within the integrated positioning tier, Trimble Inc. and Hexagon AB exemplify full-stack competitors whose correction service infrastructure anchors pricing power across contractor bases. Topcon Corporation occupies a position among mid-tier earthmoving fleet specialists competing on total cost of ownership metrics. These three entities represent the dominant competitive anchors shaping specification influence with procurement officers rather than individual machine owners.
| Leading Market Players |
|---|
| Trimble Inc. |
| Topcon Corporation |
| Hexagon AB |
| MOBA Mobile Automation AG |
| Hemisphere GNSS Inc. |
| ABB |
| Schneider Electric SE |
| Komatsu Ltd. |
| Leica Geosystems AG |
| Others |
Value Network & Pricing Analysis
Contractor procurement patterns across the United States and Canada are forcing control system vendors to decouple hardware from software subscriptions, reshaping how fleet operators budget for precision guidance capabilities over multi-year equipment lifecycles. This shift toward recurring revenue models compresses upfront capital requirements while embedding long-term subscription dependencies that alter supplier pricing power.
Pricing Analysis
Distributor margins on GNSS correction services typically run 15-25% above hardware resale, anchoring profitability for channel partners who bundle installation support with Trimble and Hexagon subscription tiers. Three-tier pricing structure across premium, standard, and economy levels separates military-grade shock-resistant systems for Texas-Oklahoma pipeline contractors from cloud-configurable municipal packages. Pricing pressure stems from EPA Tier 4 Final compliance costs compressing capital budgets available for precision control retrofits. Municipal fleets exhibit highest price sensitivity due to constrained annual appropriations, while integrated energy corridor contractors prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs in the Great Lakes manufacturing belt mandate multi-supplier qualification for electro-hydraulic valve controllers, preventing single-source lock-in despite engineering overhead from platform fragmentation. Component manufacturing concentrates in the United States, Germany, and Japan for precision sensors, with Taiwan and South Korea anchoring semiconductor supply for GNSS receiver chipsets. The supply chain draws from rare earth elements for magnetometer calibration, high-purity aluminum for sensor housings, and specialized hydraulic fluids for actuator compatibility. Tariff exposure on Chinese-sourced angle encoders creates procurement risk for mid-tier vendors. Distribution runs through OEM captive channels, independent rental houses, and direct contractor sales in roughly equal proportion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America machine control system market represents a late-cycle quality story as infrastructure spending accelerates specification upgrades toward millimeter-grade positioning accuracy previously reserved for aerospace and energy applications.
For Market Incumbents: Extend correction service infrastructure into Canadian Prairie Provinces before regional competitors establish base station networks. Acquire specialized sensor fusion startups to defend against optical-GNSS convergence threats in canopy-covered forestry applications. Prioritize backward integration into electro-hydraulic valve manufacturing to reduce OEM platform fragmentation costs. For New Entrants and Emerging Players: Mid-tier municipal fleets in the southeastern United States remain underserved by premium-tier pricing, presenting white-space entry through equipment-as-a-service bundling. Target drainage contractors in Manitoba and Saskatchewan where manual staking capacity constraints outpace incumbent sales coverage. Pursue strategic partnerships with rental fleet operators to bypass direct OEM channel competition. For Investors and Strategic Acquirers: Asymmetric upside sits with Canadian sensor module producers repositioning toward OEM hydraulic platform integration. Long-term viability favors full-stack competitors controlling both correction services and hardware manufacturing rather than pure-play component vendors. Monitor FAA Part 107 waiver processing velocity as inflection indicator for aerial photogrammetry-to-machine-guidance workflow expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Configuration Platform Launch | Enables recurring revenue capture from dispersed municipal fleet operators across Canadian prairie provinces. |
| Laser-GNSS Sensor Fusion Development | Opens specification opportunities in Pacific Northwest forestry where satellite visibility degrades under canopy cover. |
| Strategic Partnership with Rental Fleet Operators | Concentrates specification influence with procurement officers rather than individual machine owners in Texas-Oklahoma corridor. |
| Backward Integration into Electro-Hydraulic Valve Manufacturing | Reduces engineering overhead from OEM platform fragmentation and accelerates calibration standardization. |
| Geographic Expansion into Canadian Prairie Provinces | Addresses drainage project complexity outpacing manual staking capacity in Manitoba and Saskatchewan. |
Research Methodology
Direct dialogue with earthmoving fleet managers, OEM procurement directors, GNSS correction service technicians, and municipal public works officials grounded qualitative insights in operational realities. Secondary validation drew from FAA Part 107 waiver databases, EPA Tier 4 Final compliance filings, equipment registration data from the Association of Equipment Manufacturers, and SEC disclosures from publicly traded positioning technology vendors. Bottom-up triangulation across contractor survey responses and top-down reconciliation against infrastructure spending flows ensured methodological robustness.
Segment-level outputs across hardware, software, and service revenue streams reflect analytical modeling throughout the forecast period. Technology segmentation incorporated PID control, PLC architecture, and emerging SCADA integration patterns alongside end-use differentiation across construction, manufacturing, and aerospace applications. CAGRs were derived from equipment replacement cycle analysis, infrastructure appropriation trajectories, and regulatory compliance deadline clustering. Industry-specific inputs included FAA drone waiver velocity, EPA emissions enforcement intensity, and OSHA excavation standard audit frequency.
Underlying measurement precision varies by segment; hardware revenue carries tighter precision than emerging software subscription flows given established sales channel reporting. Forecasts reflect documented assumptions regarding infrastructure spending continuity, regulatory enforcement timelines, and GNSS constellation operational status. Deviation in FAA Part 107 waiver processing timelines or EPA Tier 4 Final compliance cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Global SCADA Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Intralogistics Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Global Robotic Laser Cutting Machine Market