
 Manufacturing Analytics Market | 2026-2036
Manufacturing Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Analytics Market Intelligence
The modularization of analytics software into integrated platforms is recalibrating buyer preference away from standalone point solutions. Enterprise software giants like SAP SE leverage their existing ERP footprint to bundle comprehensive analytics suites. IBM Corporation competes with its Watson AI capabilities, targeting complex predictive maintenance applications. SAS Institute Inc. differentiates through its deep statistical modeling expertise for specialized quality optimization tasks.
Manufacturing analytics involves the application of statistical methods and machine learning algorithms to operational data streams from factory equipment and production systems. Its primary purpose is to identify patterns, predict failures, and optimize processes to improve yield, efficiency, and product quality. Cloud deployments represent the fastest-growing delivery model, enabling scalable data processing for predictive maintenance solutions. Discrete manufacturers, particularly in automotive and electronics, drive demand for quality optimization and defect detection applications.
Data governance frameworks, including Europe's GDPR, impose strict requirements on how manufacturers collect and process shop-floor personnel and performance data. Adherence to global standards like ISO 9001 for quality management and ISO 50001 for energy management necessitates robust data analysis and reporting capabilities. Stakeholder decisions now center on integrating AI ethically and determining whether to build in-house analytics capabilities or partner with specialized platform vendors.
Market Dynamics
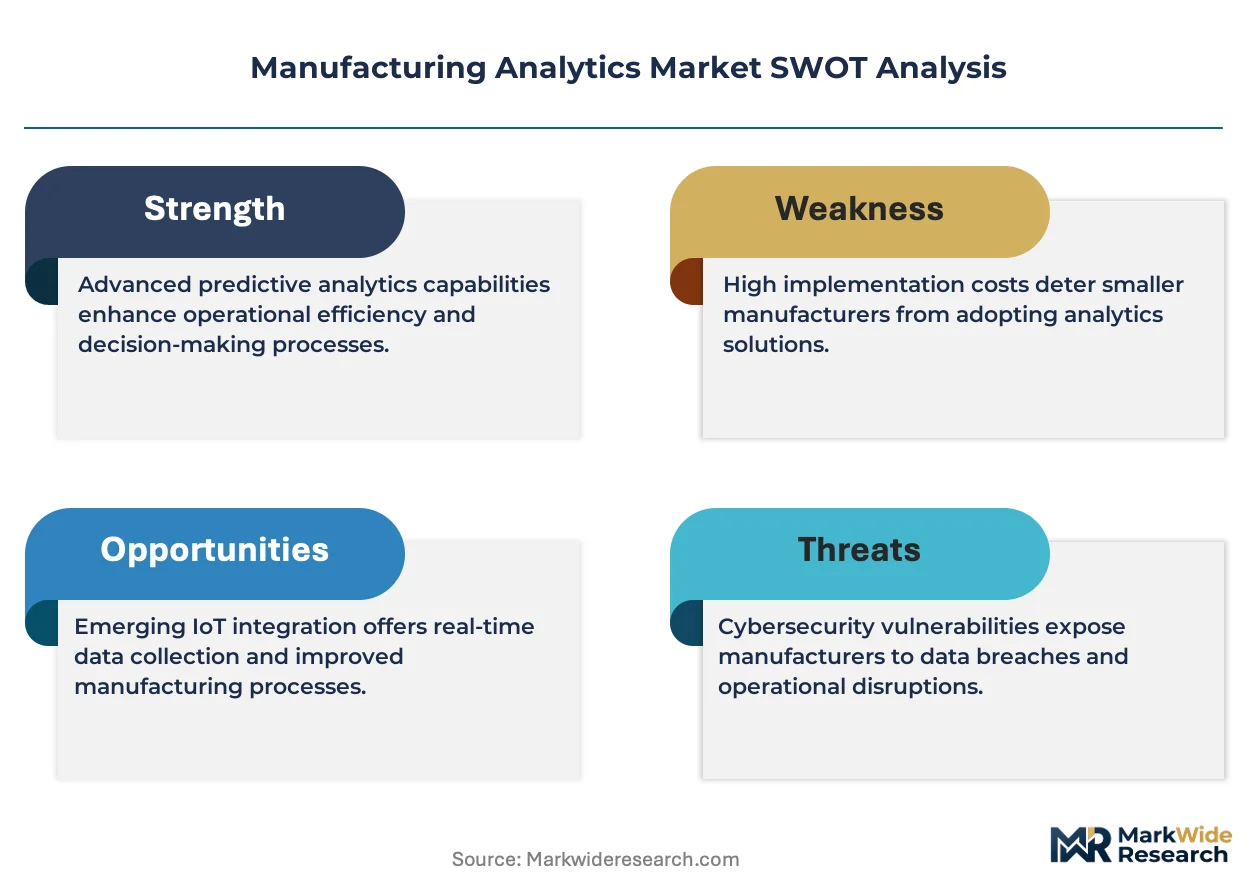
The convergence of operational technology (OT) and information technology (IT) is the central force shaping the manufacturing analytics market. This integration enables the flow of real-time data from factory floor machinery to cloud-based platforms, fueling demand for predictive and prescriptive insights.
Growth Catalysts
- Energy Efficiency Mandates:Stricter standards like ISO 50001 compel industrial operators to deploy analytics for monitoring and optimizing energy consumption, directly linking operational efficiency with regulatory compliance and cost reduction.
- Smart Factory Initiatives:The automotive sector's pursuit of Industry 4.0 drives adoption of analytics for predictive maintenance and quality optimization, aiming to reduce defect rates and minimize costly production line stoppages.
- National Decarbonization Policies:Government-led programs, such as China's 'dual carbon' goals, accelerate investment in process optimization tools and energy management systems as manufacturers seek to meet emissions targets.
Market Restraints
- High Initial Investment Costs:The significant capital outlay required for comprehensive platform deployment, including sensors, software licenses, and integration services, presents a substantial barrier for small and medium-sized manufacturers.
- Legacy System Interoperability:A lack of standardization between older, proprietary OT systems and modern IT analytics platforms creates data silos and complex integration challenges, hindering seamless data flow.
- Data Governance Complexity:Regulations like Europe's GDPR impose strict controls on collecting and processing personnel data from the shop floor, creating compliance risks and limiting certain performance monitoring applications.
Strategic Opportunities
- Emerging Market Penetration:Manufacturing hubs in Southeast Asia and Latin America represent significant growth opportunities as they begin to digitize their industrial base and invest in foundational analytics capabilities.
- Supply Chain Resilience Analytics:Expanding analytics beyond the factory to model supply chain risks and optimize logistics offers a new value proposition, addressing disruptions through predictive and prescriptive insights.
- Digital Twin Integration:The convergence of analytics with digital twin technology enables manufacturers to create virtual replicas of their production lines for simulation, stress testing, and process optimization without disrupting physical operations.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of data scientists and engineers with dual expertise in both advanced statistical modeling and specific manufacturing domain knowledge constrains effective implementation and value extraction.
- Data Quality and Integrity:Ensuring the accuracy, consistency, and timeliness of data collected from a diverse array of industrial sensors and control systems remains a fundamental operational hurdle for reliable analytics.
- Legacy Infrastructure Integration:Connecting modern cloud-based analytics platforms with entrenched, decades-old manufacturing execution systems (MES) and SCADA hardware presents significant technical and operational complexity for many enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Analytics Market |
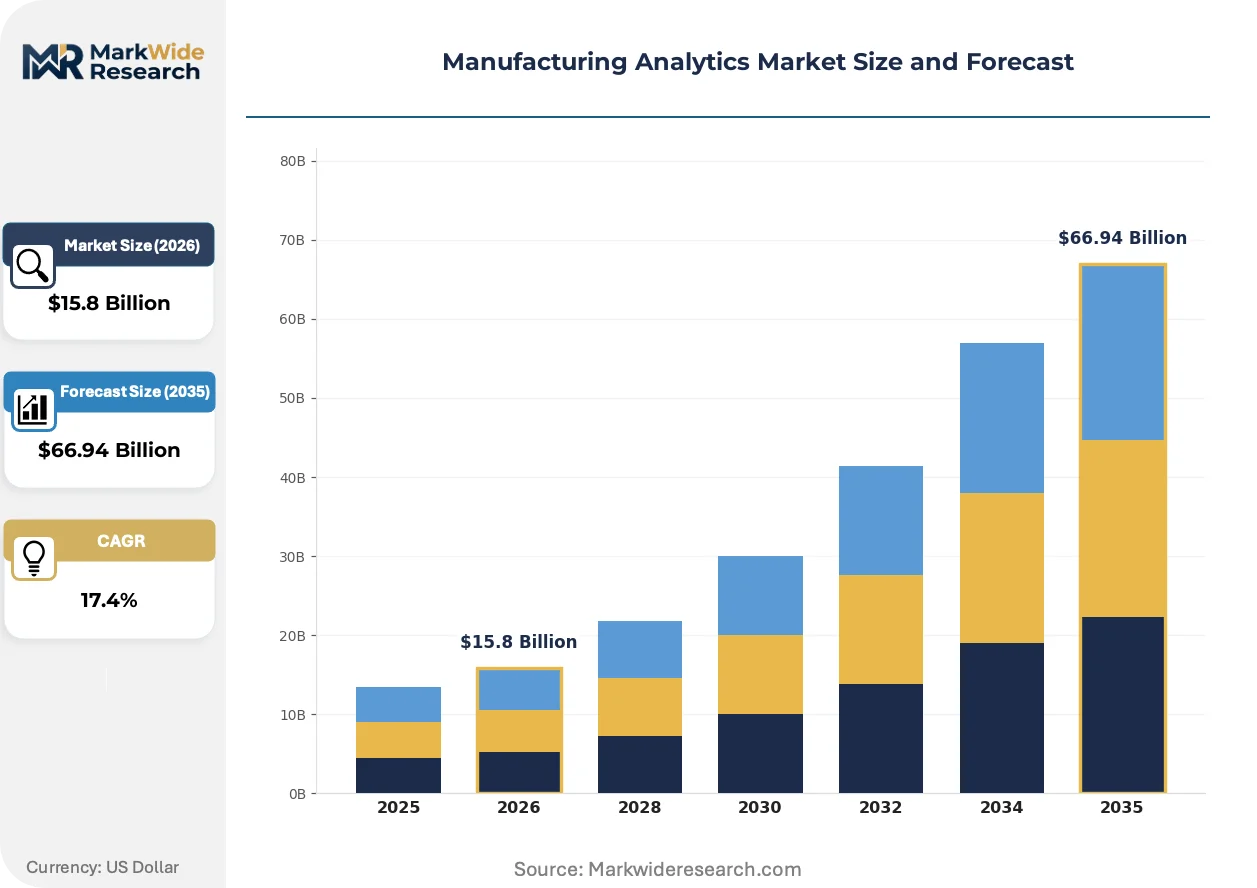
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $66.94 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Edge, Hybrid Solution Type: Predictive Maintenance, Quality Optimization, Supply Chain Analytics, Production Planning, Energy Management Application: Smart Factory, Process Optimization, Asset Tracking, Defect Detection, Demand Forecasting End User: Discrete Manufacturers, Process Manufacturers, Contract Manufacturers, Industrial Equipment Suppliers |
| Companies Covered | SAP SE, IBM Corporation, Oracle Corporation, SAS Institute Inc., TIBCO Software Inc., Salesforce.com Inc., General Electric Company, Alteryx Inc., Sisense Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Analytics Market Strategic Shifts & Innovations
The market is evolving toward AI-driven automation and greater accessibility through cloud platforms. This shift emphasizes not just identifying operational issues but predicting them, with an increasing focus on the ethical and transparent application of machine learning in production environments.
AI-powered predictive maintenance algorithms analyze real-time data from industrial equipment to forecast potential failures. Discrete manufacturers in the automotive and aerospace industries are rapidly adopting these solutions to enhance asset uptime. This capability is rewriting traditional, schedule-based maintenance practices, enabling a shift to proactive, condition-based interventions that minimize unplanned downtime and extend equipment life.
Europe’s proposed AI Act establishes a risk-based framework that classifies many industrial AI systems as high-risk. This regulation mandates stringent requirements for data quality, transparency, human oversight, and robustness for applications like automated quality control. Consequently, vendors targeting the European market must now engineer auditable and explainable AI features directly into their analytics platforms to ensure compliance.
A notable change in buying patterns shows manufacturers favoring subscription-based, Analytics-as-a-Service (AaaS) models over large, upfront software license purchases. This displaces traditional perpetual license sales, as cloud vendors provide scalable, outcome-focused solutions. This trend is particularly visible among small and mid-sized enterprises in North America and Europe seeking access to advanced analytics without prohibitive initial capital investment.
Manufacturing Analytics Market Segmentation
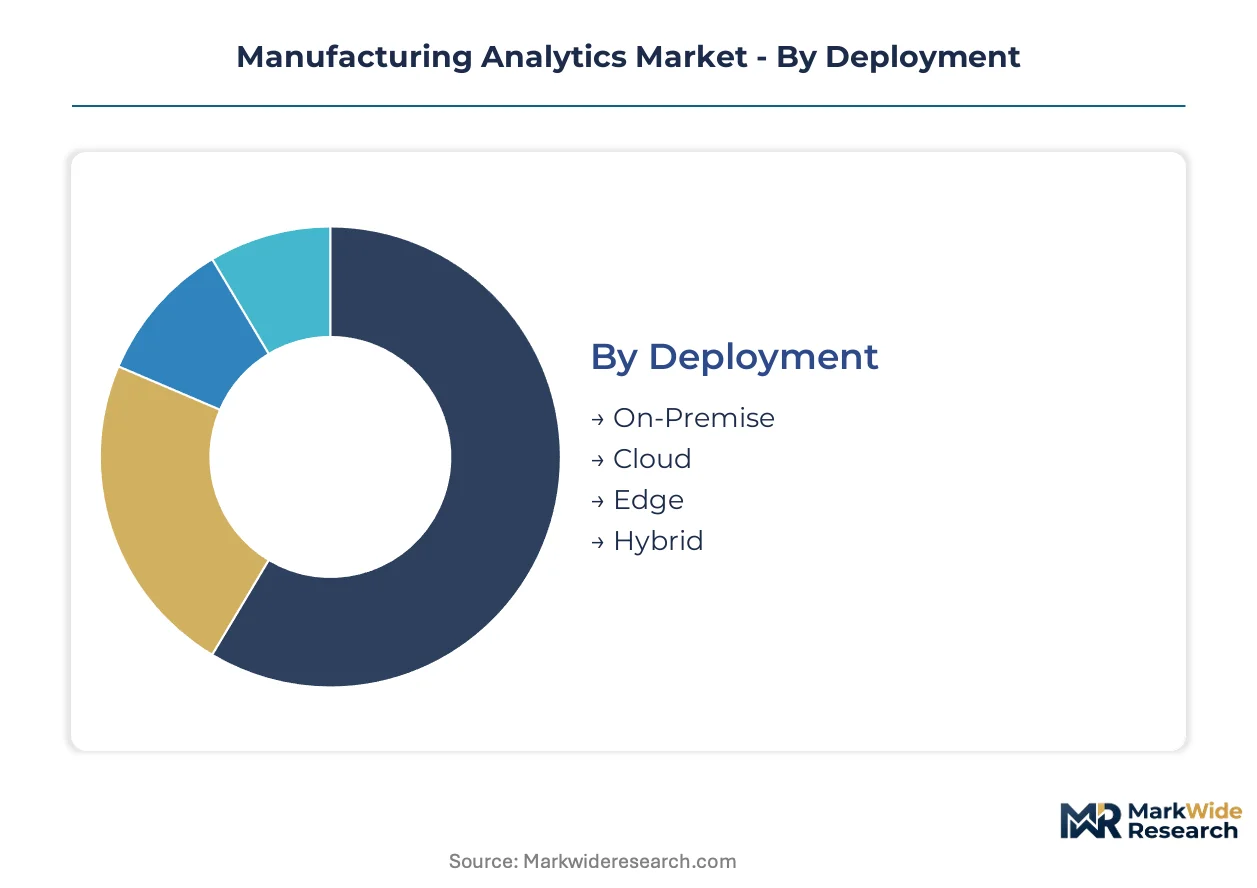
The manufacturing analytics market is segmented to provide a granular understanding of technology adoption patterns and end-user requirements. This segmentation helps identify specific growth pockets and competitive dynamics across various operational dimensions. Understanding these segments is crucial for solution providers to tailor offerings effectively.
Deployment:
The supply of manufacturing analytics deployment models is increasingly concentrated around cloud-based infrastructure, influencing how data processing capabilities are delivered to factory floors.
- Cloud:Cloud deployments involve hosting analytics software and data processing on remote servers accessible via the internet. Discrete manufacturers in North America drive demand for scalable data processing for predictive maintenance solutions.
- Edge:Edge deployments process data closer to the source, such as on factory equipment or local servers, minimizing latency. Automotive plants in Germany leverage edge analytics for real-time defect detection and rapid response on production lines.
- On-Premise:On-premise deployments involve installing software and hardware directly within a manufacturer's own data centers.
- Hybrid:Hybrid models combine elements of both on-premise and cloud deployments, offering flexibility and data control.
Today's leader: Cloud. Tomorrow's challenger: Edge.
Solution Type:
Manufacturing analytics solutions are differentiated by their specific application-centric value proposition, addressing critical operational challenges across the production lifecycle.
- Predictive Maintenance:Predictive maintenance solutions use machine learning algorithms to analyze sensor data and forecast equipment failures before they occur. Aerospace manufacturers in the United States implement these solutions to enhance asset uptime and reduce unplanned downtime.
- Quality Optimization:Quality optimization involves applying statistical and AI methods to production data to minimize defects and improve product consistency. Electronics manufacturers in South Korea utilize quality optimization for defect detection and process control.
- Supply Chain Analytics:Supply chain analytics optimizes logistics, inventory, and supplier performance through data-driven insights.
- Production Planning:Production planning solutions enhance scheduling, resource allocation, and workflow management for factory operations.
- Energy Management:Energy management analytics monitors and optimizes energy consumption to meet regulatory mandates like ISO 50001.
Predictive Maintenance represents the fastest-growing trajectory, driven by its direct impact on operational efficiency.
Application:
End-user adoption patterns for manufacturing analytics applications are shaped by the specific operational pain points manufacturers aim to resolve.
- Smart Factory:Smart factory applications integrate IoT, AI, and analytics to create highly automated and interconnected production environments. Automotive industry players in China adopt smart factory initiatives to drive overall operational efficiency and automation.
- Process Optimization:Process optimization applications analyze production workflows and parameters to identify bottlenecks and improve throughput. Chemical manufacturers in India deploy process optimization tools to enhance yield and reduce waste.
- Asset Tracking:Asset tracking applications monitor the location and status of equipment and materials within a manufacturing facility.
- Defect Detection:Defect detection uses computer vision and AI to identify flaws in products during the manufacturing process.
- Demand Forecasting:Demand forecasting leverages historical data and external factors to predict future product demand for production planning.
Market expansion is primarily led by Smart Factory applications, with Process Optimization steadily gaining traction.
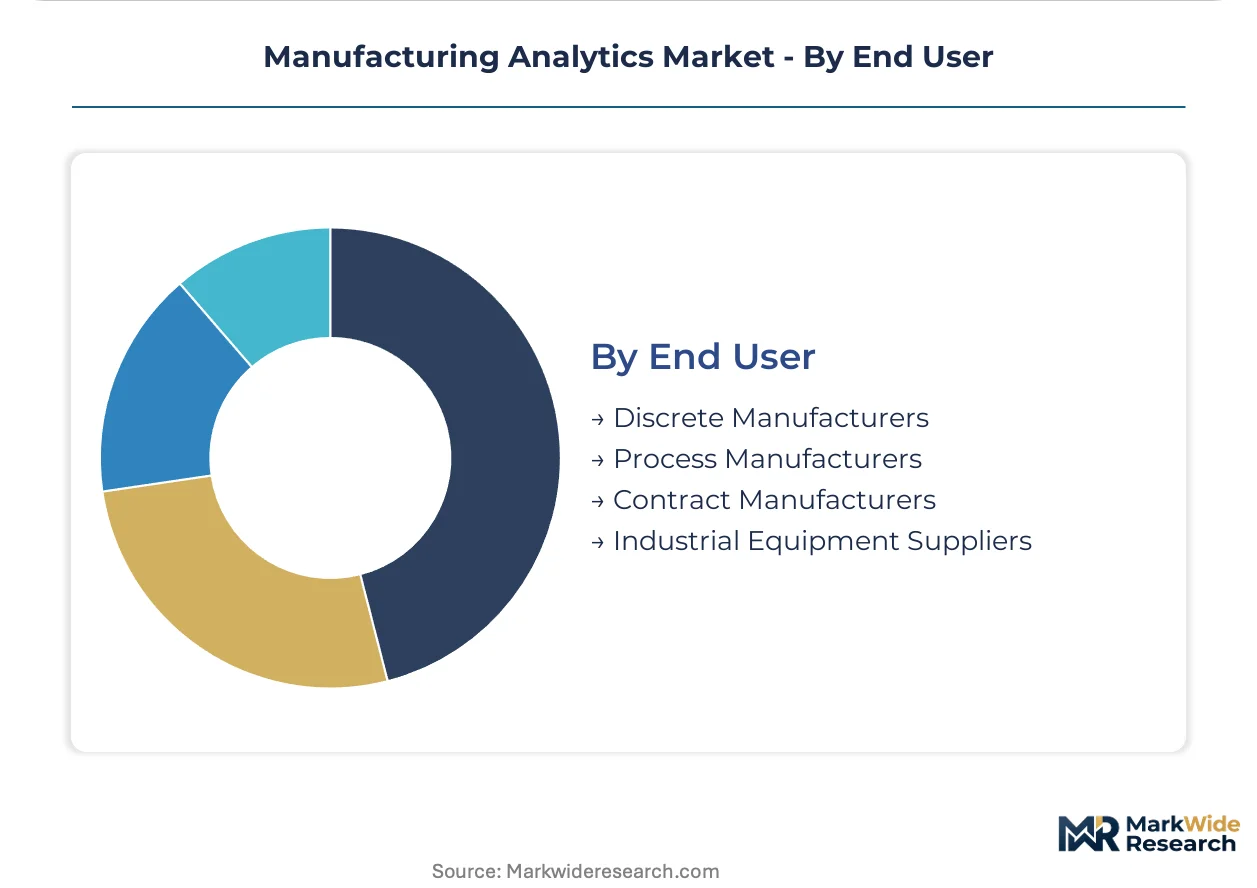
End User:
The end-user segmentation highlights how manufacturing analytics capabilities are tailored to meet segment-specific operational requirements and production characteristics.
- Discrete Manufacturers:Discrete manufacturers produce distinct, individual units, often requiring analytics for assembly line optimization and quality control. Automotive and electronics sectors in Japan demand solutions for defect detection and predictive maintenance.
- Process Manufacturers:Process manufacturers transform raw materials through chemical or physical processes, needing analytics for yield optimization and continuous flow control. Food and beverage companies in Brazil utilize analytics for energy management and quality consistency.
- Contract Manufacturers:Contract manufacturers leverage analytics to manage diverse production lines and meet client-specific quality standards.
- Industrial Equipment Suppliers:Industrial equipment suppliers use analytics to offer value-added services like predictive maintenance for their machinery.
Demand for analytics is strongest within Discrete Manufacturers, while Process Manufacturers represent a significant growth area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The manufacturing analytics market scaled significantly with the advent of Industry 4.0, integrating digital technologies into traditional factory operations. Early adoption concentrated in highly industrialized economies, leveraging existing automation infrastructure. This foundational shift enabled data-driven process optimization and predictive insights across production lines.
United States
Demand for advanced analytics in aerospace and automotive sectors drives solution adoption for efficiency gains. The EPA's environmental regulations push manufacturers toward energy efficiency analytics and sustainable practices. Silicon Valley and Detroit manufacturers actively deploy AI for predictive maintenance and quality control applications.
Germany
Strict quality control standards, such as those reinforced by ISO 9001, necessitate sophisticated analytics platforms for compliance. The country's strong commitment to Industry 4.0 initiatives fosters smart factory deployments across various industries. The automotive hub in Bavaria integrates edge analytics for real-time defect detection and rapid response on production lines.
China
Government-led 'dual carbon' goals accelerate investment in process optimization and energy management tools to meet emissions targets. Massive industrialization projects and smart factory initiatives fuel analytics demand for automation. Manufacturing centers in the Yangtze River Delta prioritize AI-driven automation for efficiency gains and yield improvement.
Japan
The automotive and electronics industries demand robust analytics for defect detection and quality optimization in complex assembly lines. METI initiatives promote digital transformation in manufacturing, emphasizing data-driven decision-making for productivity. Factories in the Kansai region implement predictive maintenance to enhance asset uptime and extend equipment life.
India
Process optimization and energy management are key demand drivers in the chemical and food & beverage sectors for cost reduction. The PLI scheme encourages domestic manufacturing, leading to increased analytics adoption for efficiency and competitiveness. Industrial clusters around Bengaluru are deploying analytics for yield improvement and waste reduction in their operations.
Manufacturing Analytics Market Key Industry Players
The competitive structure tilts toward established enterprise software providers leveraging their extensive client bases and integrated offerings. The market features a tiered landscape, with large technology conglomerates, specialized analytics vendors focusing on specific industrial applications, and agile niche solution providers. Dominant archetypes include comprehensive platform providers offering end-to-end solutions and deep statistical modeling experts catering to specialized quality optimization tasks. Companies pursue portfolio diversification through M&A and strategic partnerships to expand their market reach and integrate new AI-driven capabilities.
On the comprehensive platform vector, SAP SE exemplifies an enterprise software giant leveraging its existing ERP footprint to bundle integrated analytics suites for manufacturing clients. IBM Corporation, with its Watson AI capabilities, represents a technology conglomerate focusing on complex predictive maintenance and operational intelligence applications across various industrial verticals. SAS Institute Inc. anchors the specialized analytics vendor segment, differentiating through its deep statistical modeling expertise specifically for quality optimization tasks and process improvement.
| Leading Market Players |
|---|
| SAP SE |
| IBM Corporation |
| Oracle Corporation |
| SAS Institute Inc. |
| TIBCO Software Inc. |
| Salesforce.com Inc. |
| General Electric Company |
| Alteryx Inc. |
| Sisense Inc. |
| Others |
Cost & Logistics Intelligence
Stricter energy efficiency mandates, such as ISO 50001, compel manufacturers to deploy advanced analytics, influencing how solution providers structure their offerings. This demand-side pressure drives suppliers to innovate and modularize their platforms, recalibrating pricing away from traditional perpetual licenses.
Pricing Analysis
Subscription-based Analytics-as-a-Service (AaaS) models now dominate, displacing large, upfront software license purchases. Price differentiation stems from the level of specialized expertise offered, such as deep statistical modeling for quality optimization, and the breadth of comprehensive analytics suites. Pricing pressure intensifies on traditional license sales as manufacturers seek outcome-focused solutions without prohibitive initial capital investment. Small and mid-sized enterprises (SMEs) in North America and Europe demonstrate the highest price sensitivity for these offerings.
Supply Chain Analysis
Domestic-content mandates and national decarbonization policies, like China's 'dual carbon' goals, increasingly reshape sourcing decisions for manufacturing analytics components. The supply of advanced analytics capabilities concentrates in technologically mature regions, including the United States, Germany, and India, which provide both talent and infrastructure. The primary raw material dependencies include specialized talent (data scientists, AI/ML engineers) and robust cloud infrastructure. Specialized talent scarcity represents a significant structural risk for solution development and deployment. Distribution primarily runs through cloud-based SaaS and AaaS models, enabling scalable delivery to global factory floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The manufacturing analytics market offers substantial margin expansion opportunities, driven by AI-driven automation enabling significant operational cost reductions for end-users.
For Market Incumbents: Anticipate the continued modularization of analytics software into integrated platforms. Leverage existing ERP footprints, as SAP SE does, to bundle comprehensive analytics suites and defend against niche solution providers. Invest in strategic partnerships and M&A to integrate advanced AI capabilities, particularly for complex predictive maintenance applications, to counter the threat of specialized AI vendors. Deepen statistical modeling expertise for specialized quality optimization tasks to maintain differentiation against generalized platforms.
For New Entrants and Emerging Players: Enter via specialized applications targeting specific operational pain points in underserved segments. Focus on emerging markets in Southeast Asia and Latin America, which are beginning to digitize their industrial base. Offer subscription-based, Analytics-as-a-Service (AaaS) models to attract small and mid-sized enterprises seeking advanced analytics without prohibitive initial capital investment. Penetrate the market by providing outcome-focused solutions for digital twin integration or supply chain resilience analytics.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized analytics vendors possessing proprietary AI/ML algorithms for industrial applications. The long-term viability of this market is strong, anchored by persistent Industry 4.0 initiatives and regulatory pressures for efficiency and sustainability. Target agile niche solution providers with proven capabilities in areas like edge analytics for real-time defect detection or ethical AI compliance. The signal to watch is the successful integration of OT and IT systems within manufacturing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundles comprehensive analytics suites, leveraging existing ERP footprints for enterprise clients. |
| Acquisition of Specialist Firm | Expands portfolio with niche AI/ML expertise for complex industrial applications. |
| Geographic Expansion | Penetrates emerging manufacturing hubs, capitalizing on foundational analytics demand. |
| Strategic Partnership | Enhances solution capabilities by integrating complementary technologies like industrial IoT sensors. |
| AI-driven Product Launch | Offers advanced predictive maintenance or quality control tools, addressing critical operational needs. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. This approach combines extensive primary interviews with manufacturing plant managers, data scientists, IT procurement officers, and production engineers. Secondary validation draws from regulatory filings (e.g., ISO certifications), industry association reports, and academic research on AI/ML applications in industrial settings.
Historical trendline analysis, regression modeling, and scenario planning were applied across the analysis window to derive projections. Segmentation dimensions modeled include deployment (cloud, edge), solution type (predictive maintenance, quality optimization), application (smart factory, process optimization), end user (discrete, process manufacturers), and regional adoption patterns. Compound annual growth rates were derived by extrapolating historical growth and factoring in projected industrial IoT sensor deployment rates and AI model development cycles.
The model holds under conditions of stable regulatory environments and sustained investment in Industry 4.0 initiatives; deviation in global economic stability or faster-than-expected AI regulatory hurdles would shift forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Latin America Big Data Analytics Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Datacenter Analytics Market
Analytics
IoT Analytics Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Spend Analytics Software Market
Analytics
Predictive Analytics Market
Analytics
Japan Geospatial Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
Process Analytics Market
Analytics
Contact Center Analytics Market
Analytics
Data Wrangling Market
Analytics
North America HR Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
Data Visualization Market
Analytics
Global Data Analysis Software Market