
 Cellular Machine to Machine Market | 2026-2036
Cellular Machine to Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Machine to Machine Market Analysis
Carrier-direct distribution is rewriting how enterprises procure cellular connectivity for machine-to-machine deployments. AT&T leverages its FirstNet infrastructure to anchor public-safety and utility-grade IoT contracts across the United States. Vodafone competes through its global SIM platform, which sustains cross-border fleet management for multinational logistics operators. Deutsche Telekom dominates European industrial automation accounts with dedicated network slicing services tailored to manufacturing latency requirements.
Cellular machine-to-machine communication denotes wireless data exchange between devices over licensed mobile operator networks, typically employing standardized modules with transmit power between 23 dBm and 33 dBm and operating across sub-6 GHz spectrum allocations to enable remote monitoring, command execution, and telemetry transmission without human intervention. The technology dimension shows 4G LTE-M and NB-IoT occupying the largest volume share as carriers sunset 2G and 3G infrastructure, while 5G modules represent the fastest-expanding margin pool for high-bandwidth applications including video-enabled telematics and augmented-reality field service. Within applications, telematics leads in revenue terms due to automotive OEM mandates for connected vehicle platforms, whereas industrial automation segments are deepening module attach rates as manufacturers retrofit legacy equipment with cellular gateways.
The Federal Communications Commission governs spectrum allocation and device certification through Part 15 and Part 27 rules, directly shaping which radio technologies gain market traction in the United States. The European Telecommunications Standards Institute coordinates CE marking requirements and harmonized frequency bands, while China's Ministry of Industry and Information Technology enforces domestic GB standards and network access licenses that condition market entry for foreign module vendors. Stakeholders must monitor spectrum auction timelines and carrier sunset schedules to align module procurement cycles with network availability.
Market Dynamics
Carrier migration from legacy 2G and 3G infrastructure toward LTE-M and NB-IoT standards is compressing procurement cycles and forcing module vendors to recertify portfolios ahead of network sunsets.
Growth Catalysts
- FCC spectrum reallocation:The Federal Communications Commission's 3.5 GHz CBRS and 600 MHz auction outcomes are accelerating utility-grade IoT deployments across United States power grids and water districts.
- Automotive OEM mandates:Connected vehicle platforms in Germany's industrial corridor are embedding cellular modules into predictive maintenance systems and supply chain tracking infrastructure.
- 5G network slicing:Deutsche Telekom's manufacturing-dedicated slices are enabling sub-10 millisecond latency for industrial automation robotics and quality control systems.
Market Restraints
- Semiconductor supply concentration:Cellular baseband chipset fabrication concentrates in Taiwan and South Korea foundries, exposing module vendors to geopolitical supply interruptions.
- Certification cost escalation:PTCRB and GCF testing protocols for multi-band 5G modules now exceed legacy 4G certification expenditure by substantial margins.
- LPWA substitution threat:Unlicensed LoRa and Sigfox networks are capturing low-data-rate metering applications in European utilities where cellular coverage remains uneven.
Strategic Opportunities
- India smart city infrastructure:The Ministry of Urban Affairs' AMRUT 2.0 scheme is mandating cellular-connected street lighting and waste management systems across 4,000 municipal jurisdictions.
- Healthcare cold chain monitoring:FDA 21 CFR Part 11 compliance requirements for pharmaceutical distribution are driving temperature-logging module adoption in United States biologics logistics.
- eSIM platform convergence:Remote provisioning standards from the GSM Association are collapsing hardware SKU complexity for multinational fleet operators managing cross-border vehicle pools.
Industry Challenges
- Embedded systems firmware talent scarcity:Module vendors face acute shortages of engineers proficient in both cellular protocol stacks and real-time operating systems for constrained devices.
- Legacy SCADA integration friction:Manufacturing facilities running Modbus and Profibus networks require protocol gateway development that extends deployment timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Machine to Machine Market |
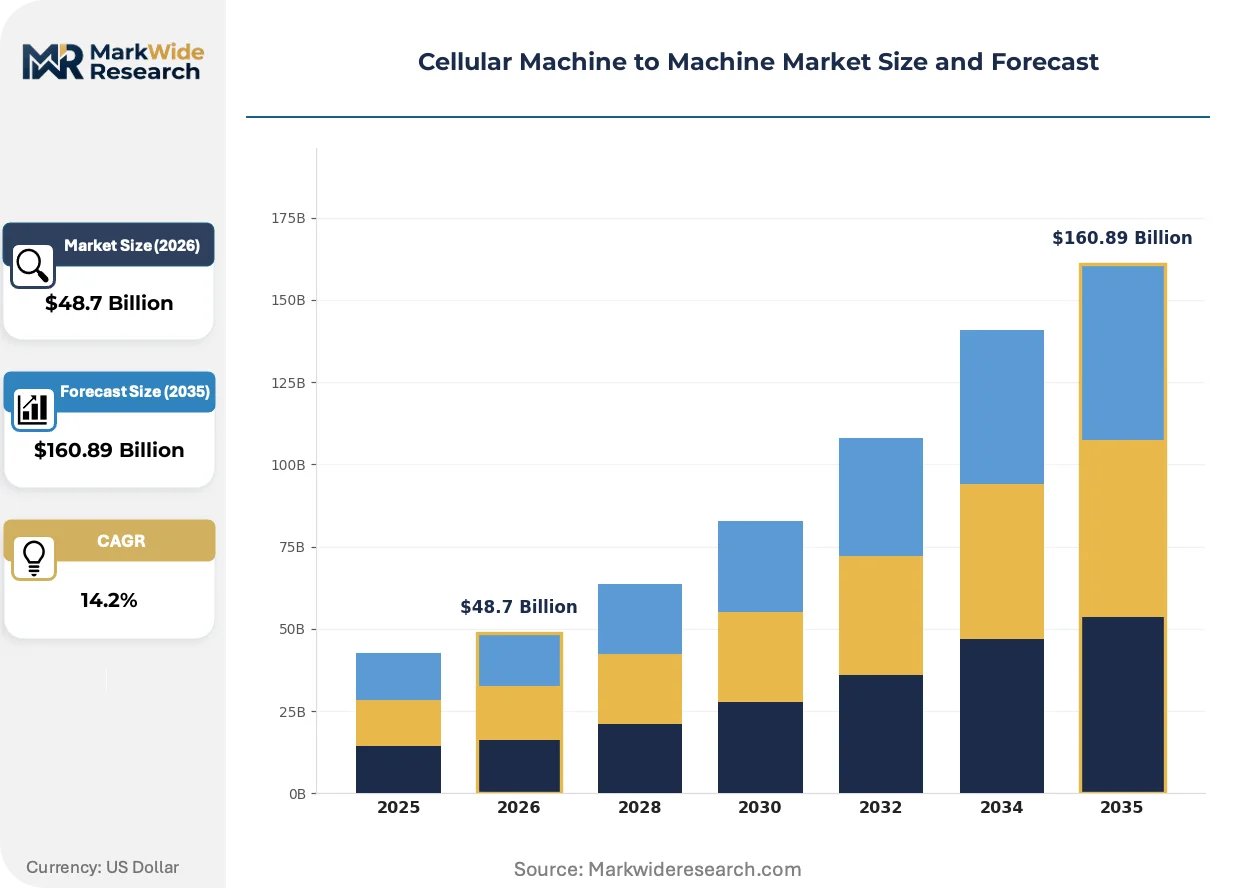
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 2G, 3G, 4G, 5G Application: Telematics, Smart Grid, Health Monitoring, Industrial Automation End User: Agriculture, Transportation, Healthcare, Utilities Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise |
| Companies Covered | AT&T, Verizon, Vodafone, Telefónica, Deutsche Telekom, China Mobile, China Telecom, Quectel, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Machine to Machine Market Emerging Trajectories
Module architecture is bifurcating between ultra-low-power narrowband designs for metering and high-throughput 5G systems for video-enabled telematics, with software-defined radio approaches bridging the gap.
Integrated iSIM technology is collapsing discrete component count in cellular modules by embedding subscriber identity credentials directly into system-on-chip designs. Automotive Tier 1 suppliers are adopting iSIM-enabled telematics control units for connected vehicle platforms ahead of 2025 model year launches. This integration is compressing bill-of-materials costs and eliminating physical SIM tray reliability failures in vibration-intensive transportation environments.
The European Union's Cyber Resilience Act is mandating security-by-design requirements for IoT devices with network connectivity, including cellular machine-to-machine modules. Manufacturers must implement secure boot mechanisms and vulnerability disclosure procedures or face CE marking withdrawal. Industrial automation vendors in Germany and France are restructuring firmware development pipelines to satisfy conformity assessment timelines before the 2027 enforcement deadline.
Fleet operators are consolidating connectivity procurement under single global SIM contracts rather than managing multiple national roaming agreements. Multinational logistics groups are pressuring carriers for unified billing platforms and API-driven usage visibility across regional subsidiaries. This concentration is most visible in cross-border European trucking and Asia-Pacific maritime container tracking, where fragmented legacy arrangements created administrative overhead exceeding connectivity costs.
Cellular Machine to Machine Market Segmentation
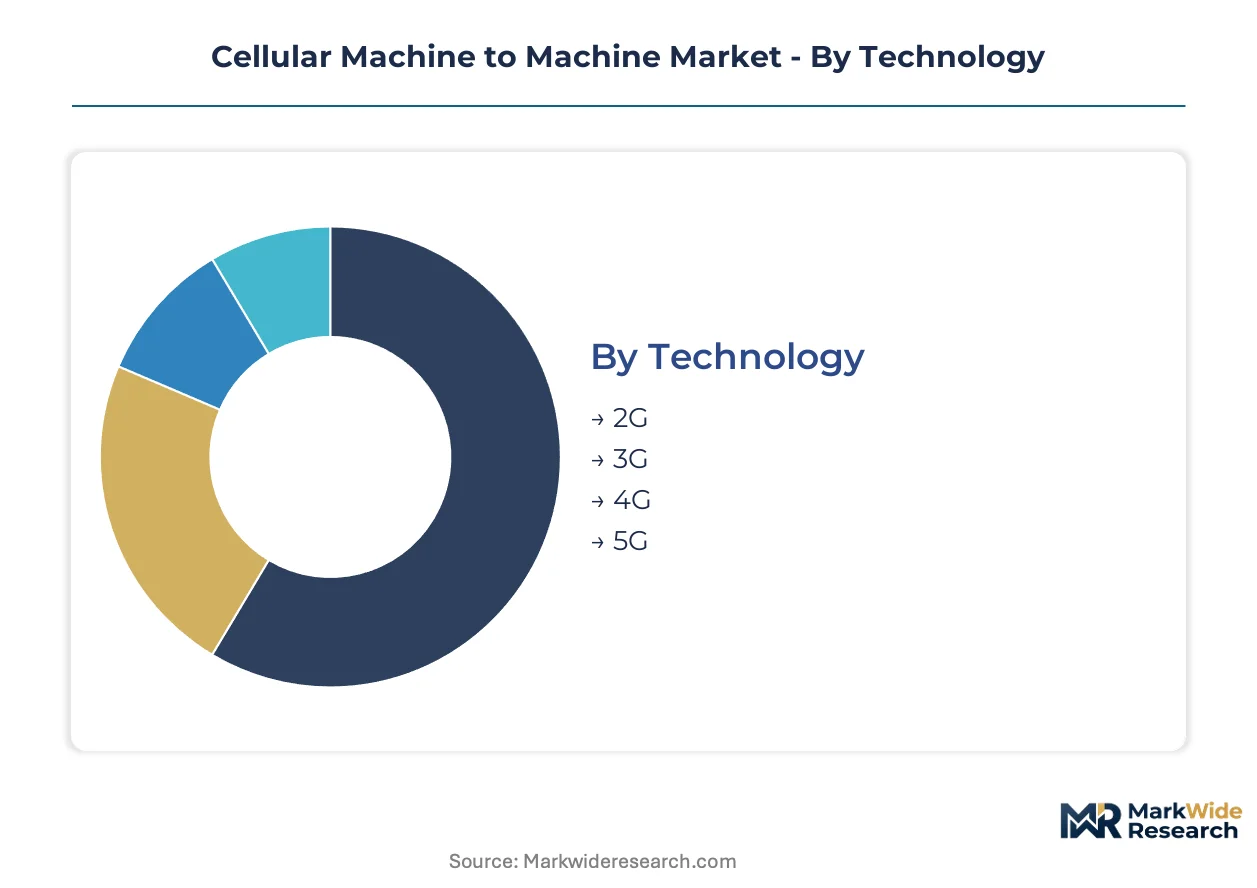
Segmentation in cellular machine-to-machine markets reveals how procurement complexity varies across technology generations and deployment models. Understanding these divides helps vendors align certification investments with carrier sunset schedules and enterprise migration timelines.
Technology:
After-sales-service intensity escalates dramatically with newer radio generations, as 5G modules demand ongoing firmware patches for security vulnerabilities and carrier aggregation updates that 2G deployments never required.
- 2G:Legacy GPRS and EDGE modules still power basic tracking devices in remote agricultural zones where carriers maintain limited coverage. Demand concentrates in India's rural districts and African markets where network operators delay full 2G shutdowns due to low-replacement-cost device economics.
- 3G:HSPA modules bridge coverage gaps in transitional markets, though carrier support is contracting rapidly. Brazil's utilities and Southeast Asian logistics operators represent residual demand pockets where 3G backhaul suffices for low-bandwidth metering applications.
- 4G:LTE-M and NB-IoT variants now dominate volume shipments as carriers sunset older infrastructure. Germany's automotive OEMs and United States utility districts are standardizing on 4G modules for predictive maintenance and smart grid endpoints, drawn by decade-long carrier support commitments and mature certification pathways.
- 5G:Sub-6 GHz and mmWave modules enable video-enabled telematics and augmented-reality field service with sub-10 millisecond latency. Deutsche Telekom's manufacturing network slices and Verizon's private 5G deployments for industrial campuses are concentrating early adoption in high-throughput robotics and quality control systems.
By volume, 4G leads. By growth pace, 5G is ahead.
Application:
Cost tier stratification separates capital-intensive industrial automation from high-volume, low-margin metering deployments, with telematics occupying the premium middle ground where automotive OEM mandates sustain pricing power.
- Telematics:Fleet management platforms embed cellular modules for real-time location tracking, driver behavior analytics, and over-the-air software updates. Connected vehicle mandates from Germany's KBA and the United States NHTSA are concentrating demand in commercial trucking and rental car fleets across North America and Europe.
- Smart Grid:Advanced metering infrastructure and distribution automation systems rely on cellular backhaul where fiber deployment proves uneconomical. United States power utilities under FERC grid modernization directives are deploying millions of cellular-connected endpoints for demand response and outage management.
- Health Monitoring:Remote patient monitoring devices and pharmaceutical cold chain trackers transmit biometric and temperature data over licensed networks. FDA 21 CFR Part 11 compliance requirements for biologics distribution are driving module adoption in United States pharmaceutical logistics.
- Industrial Automation:Cellular gateways retrofit legacy equipment for predictive maintenance and digital twin integration. Manufacturing conglomerates in Germany's industrial corridor are embedding modules into legacy SCADA systems, though Modbus and Profibus protocol conversion extends deployment timelines.
Telematics generates the highest revenue per module. Industrial automation is expanding most quickly as manufacturers retrofit legacy assets.
End User:
Customer type diversity spans price-sensitive agricultural cooperatives purchasing basic tracking devices to healthcare systems demanding HIPAA-compliant, FDA-validated connectivity platforms with 99.999% uptime guarantees.
- Agriculture:Precision farming platforms use cellular modules for soil moisture sensors, livestock tracking collars, and autonomous equipment telemetry. Large-scale farming operations in the United States Midwest and Brazil's Mato Grosso region are deploying connected machinery fleets for yield optimization.
- Transportation:Fleet operators manage cross-border vehicle pools through global SIM contracts rather than fragmented national roaming agreements. European trucking conglomerates and Asia-Pacific maritime container lines are consolidating procurement under unified billing platforms with API-driven usage visibility.
- Healthcare:Medical device manufacturers integrate cellular connectivity for remote diagnostics and emergency response systems. The United States FDA's cybersecurity guidance for networked medical devices is conditioning market entry on secure boot mechanisms and vulnerability disclosure procedures.
- Utilities:Water districts and power grids deploy cellular endpoints for smart metering, leak detection, and distribution automation. India's AMRUT 2.0 scheme is mandating cellular-connected street lighting and waste management systems across 4,000 municipal jurisdictions.
Transportation commands the largest module volumes. Healthcare is climbing the fastest as regulatory compliance deepens connectivity requirements.
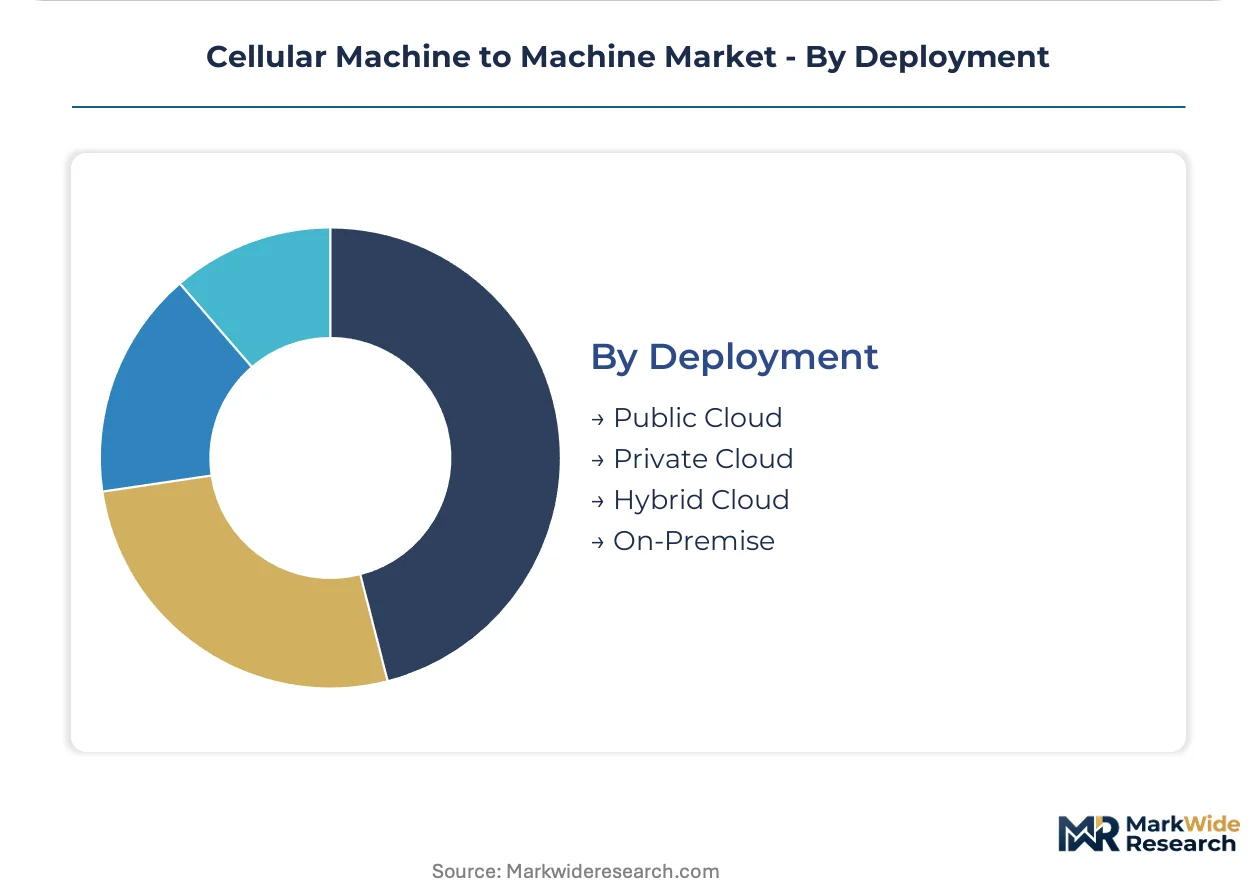
Deployment:
Supply concentration in cloud infrastructure separates hyperscale-managed deployments from on-premise installations requiring specialized systems integrators with cellular protocol expertise.
- Public Cloud:AWS IoT Core and Azure IoT Hub host device management platforms with carrier-agnostic connectivity orchestration. Mid-market enterprises without dedicated network operations teams are defaulting to public cloud deployments for rapid scaling.
- Private Cloud:Sovereign data requirements in Germany and France are pushing defense contractors and healthcare systems toward air-gapped cellular management platforms with domestic hosting.
- Hybrid Cloud:Edge computing architectures process telemetry locally while transmitting aggregated insights to cloud analytics engines. Manufacturing facilities with sub-10 millisecond latency requirements are deploying hybrid models for robotic control systems.
- On-Premise:Critical infrastructure operators in United States power generation and Saudi oil production maintain fully isolated cellular management stacks for cybersecurity air-gapping.
Public cloud leads in new deployment starts. Hybrid cloud is gaining share fastest as latency-sensitive applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial buyers command 15-20% connectivity premiums over Brazilian fleet operators due to stringent latency requirements and dedicated network slicing contracts. United States utilities under FERC directives absorb higher module costs for FirstNet-compliant deployments. Indian municipal authorities prioritize lowest-unit-cost procurement under AMRUT 2.0 budget constraints.
United States
Power utilities deploy millions of cellular endpoints for demand response and outage management under FERC grid modernization mandates. The FCC's 3.5 GHz CBRS auctions accelerate private network installations for industrial campuses. Fleet operators in Texas and California consolidate procurement under AT&T FirstNet contracts for public-safety-grade telematics.
Germany
Automotive OEMs embed cellular modules into predictive maintenance systems across Bavaria's manufacturing corridor. The KBA mandates connected vehicle platforms for commercial fleets, compressing procurement timelines. Deutsche Telekom's network slicing services in Baden-Württemberg deliver sub-10 millisecond latency for robotics applications.
China
MIIT enforces domestic GB standards and network access licenses that condition market entry for foreign module vendors. Manufacturing conglomerates in the Yangtze River Delta retrofit legacy equipment with cellular gateways for digital twin integration. State-owned carriers dominate connectivity procurement for smart city infrastructure in Shenzhen and Shanghai.
India
The Ministry of Urban Affairs' AMRUT 2.0 scheme mandates cellular-connected street lighting across 4,000 municipal jurisdictions. TRAI spectrum policies favor domestic module assembly to reduce import dependence. Karnataka and Maharashtra lead smart meter deployments for water districts with cellular backhaul where fiber proves uneconomical.
Brazil
ANVISA compliance requirements drive temperature-logging module adoption in pharmaceutical distribution networks. Utilities in São Paulo and Minas Gerais maintain residual 3G deployments for low-bandwidth metering as carriers delay full network sunsets. Agricultural cooperatives in Mato Grosso deploy basic tracking devices where limited 2G coverage persists.
Cellular Machine to Machine Market Vendor Landscape
Carrier-direct operators and module specialists split the market between connectivity provisioning and hardware supply. Tier-1 telecommunications groups anchor enterprise contracts through spectrum ownership and infrastructure scale. Pure-play module vendors compete on certification breadth and firmware customization for constrained devices. Dominant competitive moves include strategic partnerships between carriers and automotive Tier 1 suppliers, plus portfolio diversification into integrated iSIM system-on-chip designs.
Within the carrier-direct tier, AT&T and Verizon exemplify infrastructure-anchored competition for utility-grade and public-safety contracts. Among module specialists, Quectel occupies a position representing volume-shipment archetypes with broad certification coverage across radio generations. Thales Group sits within the security-integrated segment, anchoring demand from defense contractors and healthcare systems requiring sovereign data pathways.
| Leading Market Players |
|---|
| AT&T |
| Verizon |
| Vodafone |
| Telefónica |
| Deutsche Telekom |
| China Mobile |
| China Telecom |
| Quectel |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry capacity dynamics in Hsinchu Science Park directly shape module vendor pricing power, as baseband chipset fabrication bottlenecks force buyers into longer-term offtake commitments with limited spot-market flexibility.
Pricing Analysis
The customization-premium spread between configured-to-order 5G modules and standard LTE-M SKUs now exceeds three-to-one, with automotive Tier 1 suppliers absorbing the highest premiums for iSIM-integrated telematics units. Certification tier—specifically PTCRB and GCF validation depth—drives the sharpest price differentiation alongside volume scale commitments. Cost compression in standard narrowband modules is intensifying as Chinese vendors expand NB-IoT shipments under TRAI-favored domestic assembly rules. Agricultural cooperatives in Brazil's Mato Grosso region exhibit the greatest price sensitivity, while German automotive OEMs prioritize latency guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for module vendors, with Section 301 duties forcing portfolio restructuring toward Malaysia and Vietnam final-assembly alternatives. Baseband silicon draws from Taiwan Semiconductor Manufacturing and Samsung Foundry in South Korea, while RF front-end components rest on Murata and Skyworks supply allocations. Single-source vulnerability concentrates in 5G mmWave filter supply. Distribution runs through carrier-direct procurement teams for enterprise accounts, with distributor channels serving mid-market industrial automation buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellular machine-to-machine market sits at a platform-economics inflection where eSIM remote provisioning standards from the GSM Association are collapsing hardware SKU complexity and shifting value capture toward connectivity orchestration software.
For Market Incumbents: Harden firmware development pipelines against the European Union's Cyber Resilience Act security-by-design mandates, which threaten CE marking withdrawal for non-compliant modules. Deepen backward integration into secure boot credential provisioning to defend margin position against pure-play module vendors. Prioritize carrier-direct relationships with Deutsche Telekom and AT&T as these operators consolidate enterprise IoT procurement under single global SIM contracts. For New Entrants and Emerging Players: Establish a beachhead in India's AMRUT 2.0 smart city infrastructure, where 4,000 municipal jurisdictions mandate cellular-connected street lighting and waste management systems under lowest-unit-cost procurement rules. Target healthcare cold chain monitoring in the United States, where FDA 21 CFR Part 11 compliance creates certification barriers that favor specialized entrants over commodity module suppliers. Lead with temperature-logging firmware customization as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors module specialists with integrated iSIM system-on-chip capabilities and broad multi-band certification coverage. Long-term viability hinges on 5G RedCap adoption curves in industrial automation, where sub-6 GHz latency requirements displace legacy LTE-M deployments. Acquisition targets should demonstrate carrier aggregation firmware expertise and existing automotive Tier 1 supplier qualifications. The signal to watch is Deutsche Telekom's network slicing contract renewal rates with manufacturing robotics OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| iSIM System-on-Chip Integration | Eliminates physical SIM tray failures in vibration-intensive transportation environments while compressing bill-of-materials costs. |
| Carrier-Direct Enterprise Contracting | AT&T's FirstNet infrastructure anchors public-safety and utility-grade IoT procurement with decade-long support commitments. |
| Multi-Band 5G Certification Investment | PTCRB and GCF testing protocols for sub-6 GHz and mmWave modules now exceed legacy 4G expenditure substantially. |
| Network Slicing Service Development | Deutsche Telekom's manufacturing-dedicated slices deliver sub-10 millisecond latency for robotics and quality control systems. |
| Healthcare Cold Chain Module Specialization | FDA 21 CFR Part 11 compliance requirements drive temperature-logging adoption in United States biologics logistics networks. |
Methodological Framework
Desk research of carrier network sunset schedules, FCC spectrum auction filings, and ETSI harmonized frequency band documentation preceded structured interviews with IoT platform engineering directors, cellular module procurement leads at automotive Tier 1 suppliers, carrier enterprise sales executives, and industrial automation systems integrators. Secondary validation drew from PTCRB certification databases, GSM Association remote provisioning standards, and customs trade data for cellular module shipments. Bottom-up unit shipment estimates triangulated against top-down carrier-reported IoT connection growth across the analysis window.
Assumptions around 3G network sunset timelines, 5G standalone deployment pace, and eSIM platform adoption curves were held fixed while carrier pricing trajectories and semiconductor foundry capacity allocations were varied across sensitivity scenarios. Segmentation modeling spanned radio generation technology, application vertical, end-user industry, and deployment architecture dimensions. CAGRs were derived from logistic diffusion curves fitted to historical technology migration patterns, with forecast inputs including automotive OEM connected vehicle mandate schedules and FERC grid modernization directive implementation timelines.
Sensitivities concentrate around carrier 2G/3G sunset acceleration, Taiwan Strait supply disruptions, and Cyber Resilience Act enforcement timelines. Forecasts reflect documented assumptions regarding module replacement cycles and enterprise migration willingness-to-pay thresholds. Material shifts in FCC spectrum reallocation priorities or MIIT domestic standard enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Maritime Internet of Things Market