
 Asia Pacific Industrial Communication Market | 2026-2036
Asia Pacific Industrial Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Communication Market Insights
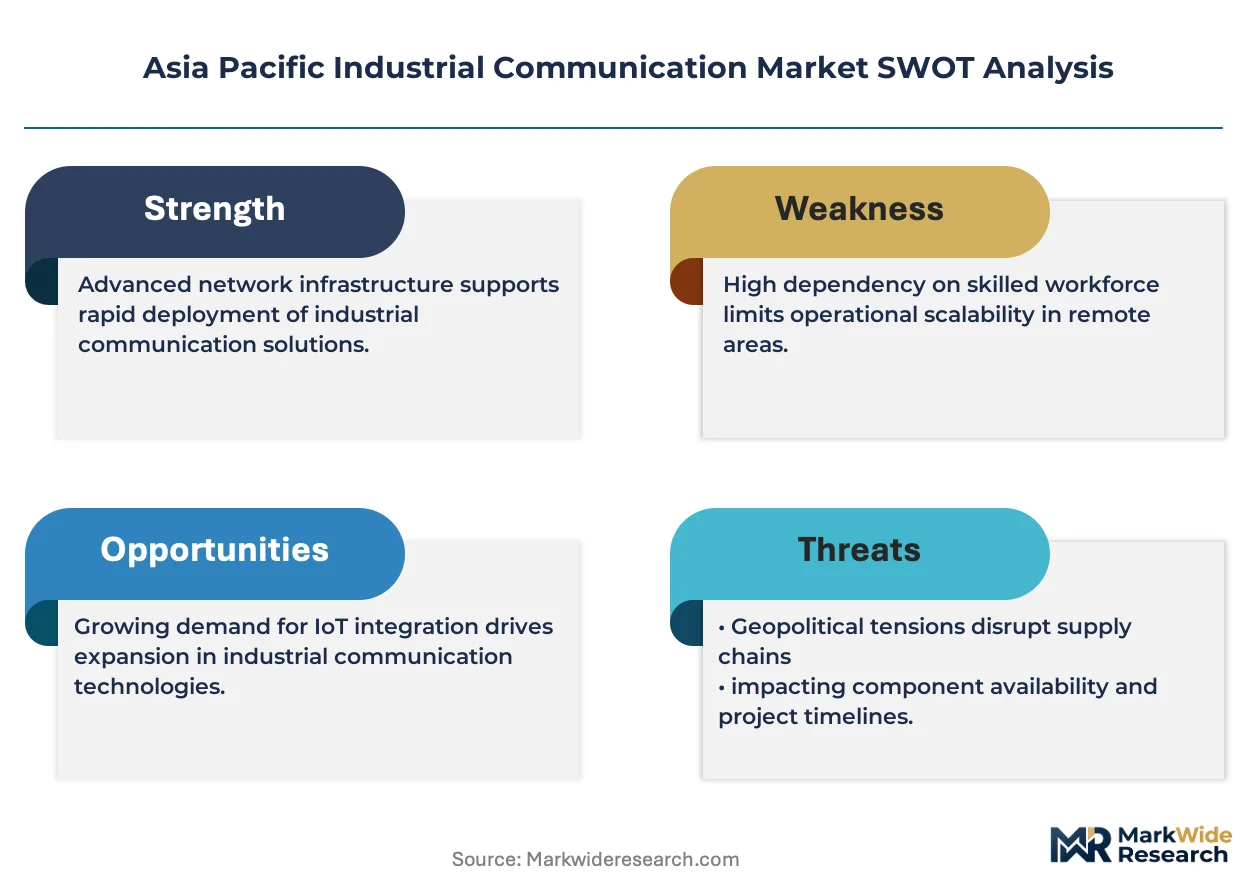
Software-defined networking subscription layers is expanding how industrial communication vendors monetize hardware deployments. Siemens AG leverages its digital twin ecosystem to anchor recurring revenue streams across factory automation installations. Huawei Technologies competes through integrated 5G private network solutions that extend its telecommunications infrastructure into industrial verticals. Rockwell Automation specializes in edge-to-cloud connectivity architectures that dominate North American-headquartered manufacturers with Asia Pacific operations.
Industrial communication encompasses the protocols, hardware interfaces, and network architectures that enable real-time data exchange between programmable logic controllers, sensors, actuators, and supervisory systems in production environments. Ethernet-based industrial protocols now transmit at gigabit speeds with deterministic latency below one millisecond, replacing legacy fieldbus systems in precision motion control applications. Fieldbus technology retains substantial installed base across process industries where intrinsic safety requirements and established device interoperability sustain replacement demand. Wireless segments are capturing fastest growth in remote monitoring deployments across offshore energy platforms and distributed solar farms where cabling costs prove prohibitive.
China's MIIT mandates GB/T standards for industrial internet security that shape product certification requirements for network equipment suppliers. Japan's METI promotes JIS-compliant open connectivity frameworks that accelerate interoperability between Mitsubishi Electric and competing automation platforms. South Korea's MFDS medical device manufacturing regulations and KOSHA industrial safety standards indirectly drive validated communication architectures in pharmaceutical production. Stakeholders must evaluate whether cloud-based deployment models or hybrid edge architectures better satisfy cross-border data sovereignty requirements as ASEAN member states develop divergent critical infrastructure protection rules.
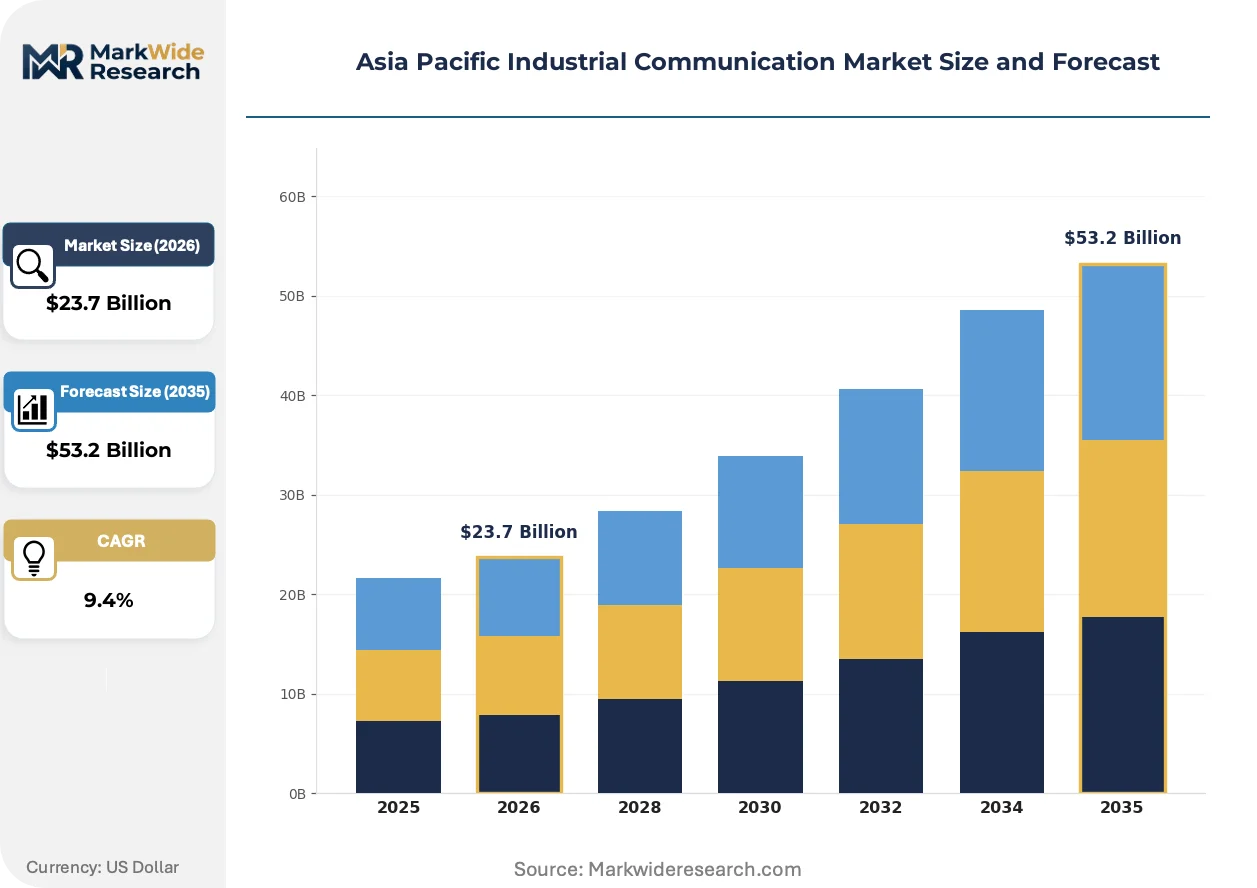
Market Dynamics
China's MIIT industrial internet standards are forcing network equipment suppliers to redesign certification pathways, while Japan's precision electronics clusters and South Korea's semiconductor corridors concentrate demand for deterministic sub-millisecond communication architectures.
Growth Catalysts
- Smart manufacturing protocols:Automotive assembly plants across China and Japan are deploying deterministic Ethernet to synchronize robotic welding cells and AGV fleets, replacing legacy fieldbus systems in greenfield facilities.
- Dual carbon mandates:China's national emissions targets are accelerating digital twin deployments that require real-time sensor networks to optimize energy consumption in steel and cement production.
- 5G private spectrum allocation:South Korea's Ministry of Science and ICT has released dedicated industrial frequencies that enable localized ultra-reliable low-latency networks for semiconductor fabrication automation.
Market Restraints
- Silicon supply concentration:Industrial Ethernet switch ASICs depend on fabrication capacity concentrated in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Copper and rare earth volatility:Shielded cable assemblies and magnetics for fieldbus termination units face input cost swings tied to Indonesian nickel and Chinese rare earth processing quotas.
- Intrinsic safety certification lag:Process industries in Australia's offshore energy sector require IECEx-certified equipment that extends procurement cycles by 8-14 months versus standard industrial ratings.
Strategic Opportunities
- Vietnam electronics manufacturing:Samsung and Foxconn expansion in Bac Ninh and Bac Giang provinces is creating demand for localized 5G private network integration without incumbent vendor lock-in.
- Edge-to-cloud convergence:Hybrid architectures combining on-premise PLCs with Alibaba Cloud and Huawei Cloud industrial platforms are opening subscription revenue models for connectivity vendors.
- India PLI scheme:Production-linked incentives for semiconductor and electronics manufacturing are attracting communication infrastructure investment to Gujarat and Tamil Nadu industrial corridors.
Industry Challenges
- OT-IT skill bifurcation:Plant engineers trained on Modbus and PROFIBUS lack proficiency in SDN configuration and cybersecurity hardening required for modern industrial Ethernet deployments.
- Legacy protocol integration:Brownfield facilities in Japan's automotive tier-one supplier base require protocol gateways that add latency and failure points to otherwise deterministic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Communication Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ethernet, Fieldbus, Wireless, Serial Communication End User: Manufacturing, Oil & Gas, Energy, Transportation Deployment: On-premise, Cloud-based, Hybrid, Edge Computing Application: Process Automation, Factory Automation, Remote Monitoring, Data Analytics |
| Companies Covered | Schneider Electric SE, ABB Ltd, Siemens AG, Rockwell Automation, Moxa Inc, Advantech Co., Ltd., Mitsubishi Electric, SICK AG, Huawei Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Communication Market Trends and Innovations
Ethernet-based deterministic protocols are compressing the performance gap between information technology and operational technology networks, enabling new control architectures that were previously exclusive to specialized fieldbus systems.
Time-Sensitive Networking is integrating IEEE 802.1Qbv time-aware shapers and 802.1CB frame replication into automotive paint shop controllers and battery assembly lines. Tier-one suppliers in Japan's Aichi prefecture are piloting TSN-enabled camera networks for AI-guided quality inspection. This convergence is integrating motion control, safety systems, and vision processing onto unified cable plants that previously required separate physical networks.
China's GB/T 33008 and GB/T 33009 industrial internet security standards are mandating encrypted device authentication and access logging for network equipment deployed in critical manufacturing sectors. Foreign suppliers must obtain MIIT cybersecurity certification that adds 6-9 months to product registration timelines. Semiconductor fabrication facilities in Shanghai and Beijing are prioritizing domestic vendors with pre-certified stacks to accelerate deployment schedules.
Asset-as-a-service contracting is displacing capital expenditure models for wireless sensor networks in Australia's offshore oil platforms and Indonesia's geothermal fields. Operators now lease vibration monitoring and corrosion sensing infrastructure from communication vendors who retain ownership and perform predictive maintenance. This shift concentrates most visibly in Southeast Asian energy projects where project finance constraints favor operational expenditure structures over upfront hardware procurement.
Asia Pacific Industrial Communication Market Segmentation
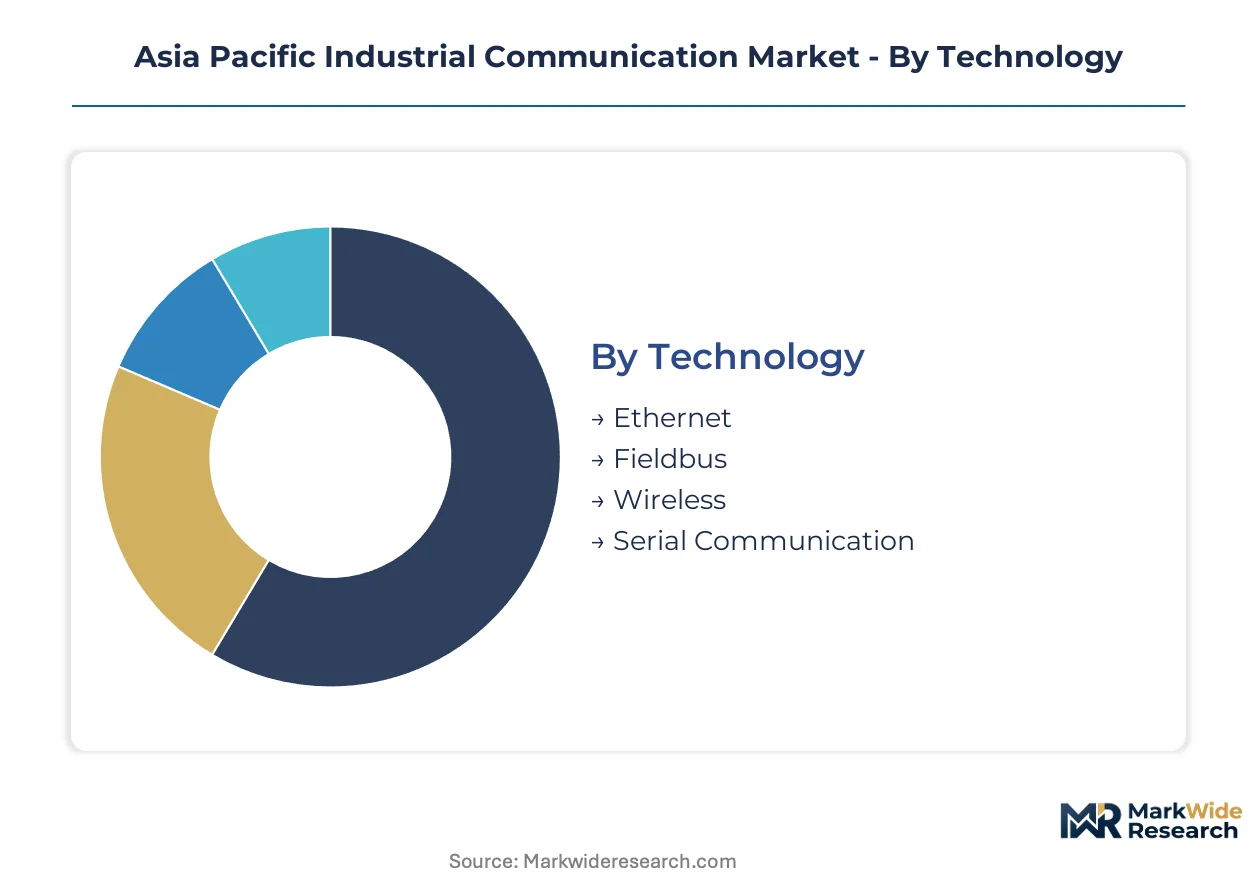
Industrial communication architectures vary dramatically across deployment contexts, with technology choices, end-user requirements, and application demands creating distinct procurement patterns. Buyers prioritize deterministic latency, cybersecurity certification, and integration complexity differently based on operational criticality and regulatory exposure.
Technology:
Cost tier separates buyers seeking premium deterministic performance from those optimizing for legacy compatibility and installation simplicity.
- Ethernet:Gigabit-speed deterministic protocols with sub-millisecond latency now dominate precision motion control in Japan's automotive paint shops and South Korea's semiconductor fabrication. China's MIIT GB/T standards mandate encrypted authentication stacks that favor pre-certified domestic suppliers in critical manufacturing sectors.
- Wireless:5G private networks and industrial Wi-Fi 6 are capturing deployment share in Australia's offshore energy platforms and Indonesia's distributed solar farms where cabling costs prove prohibitive and terrain prevents fiber trenching.
- Fieldbus:PROFIBUS and Modbus retain substantial installed base across process industries where intrinsic safety requirements and established device interoperability sustain replacement demand.
- Serial Communication:RS-485 and RS-232 persist in legacy brownfield retrofit scenarios requiring protocol gateways for Ethernet migration.
Ethernet leads volumes today; wireless is gaining share fastest.
End User:
Application maturity drives divergent network architecture requirements between continuous process industries and discrete manufacturing.
- Manufacturing:Automotive assembly plants across China and Japan deploy Time-Sensitive Networking to synchronize robotic welding cells, AGV fleets, and AI-guided quality inspection systems onto unified cable plants.
- Energy:Australia's offshore oil platforms and Indonesia's geothermal fields favor asset-as-a-service wireless sensor networks due to project finance constraints and operational expenditure preferences.
- Oil & Gas:Australia's offshore sector requires IECEx-certified equipment that extends procurement cycles versus standard industrial ratings, concentrating demand with validated suppliers.
- Transportation:Rail signaling and port automation in Singapore and Hong Kong demand redundant network architectures with failover capabilities under 50 milliseconds.
Manufacturing dominates current deployment value; energy infrastructure shows the steepest expansion trajectory.
Deployment:
Data sovereignty requirements and latency tolerance shape architecture selection across ASEAN's divergent critical infrastructure protection regimes.
- Hybrid:Architectures combining on-premise PLCs with Alibaba Cloud and Huawei Cloud industrial platforms are opening subscription revenue models for connectivity vendors in China's eastern manufacturing corridors.
- Edge Computing:Localized processing nodes address sub-10 millisecond control loops in Japan's precision electronics clusters where cloud round-trip latency violates motion control tolerances.
- On-premise:Fully isolated networks persist in defense-adjacent manufacturing and pharmaceutical production subject to MFDS medical device regulations in South Korea.
- Cloud-based:Pure cloud deployments concentrate in non-critical monitoring applications with relaxed latency requirements and established cross-border data transfer agreements.
Hybrid architectures command the largest current footprint; edge computing is climbing the fastest.
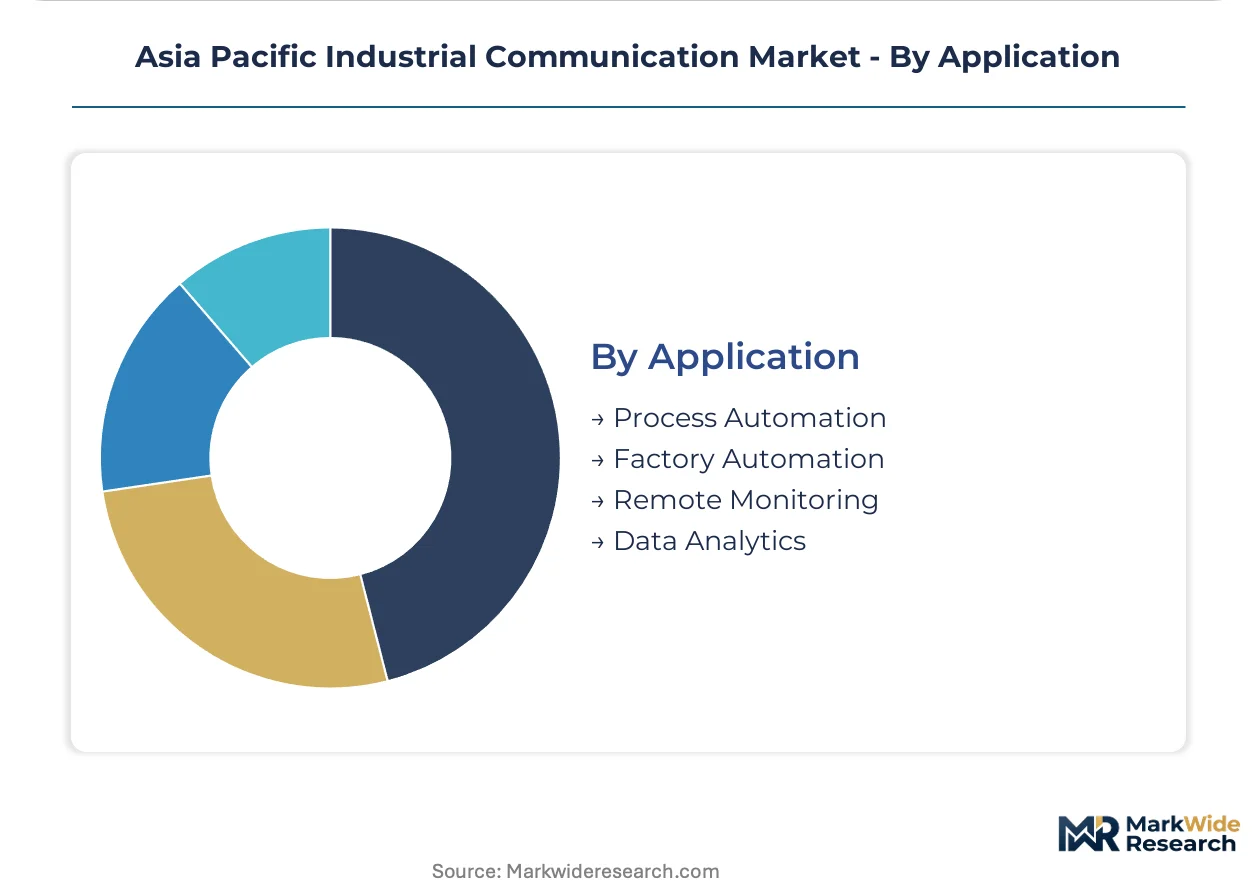
Application:
Control loop criticality determines network redundancy levels and certification rigor across operational technology environments.
- Factory Automation:Discrete manufacturing in Vietnam's Bac Ninh and Bac Giang electronics corridors demands localized 5G private network integration without incumbent vendor lock-in as Samsung and Foxconn expand capacity.
- Process Automation:Steel and cement production under China's dual carbon goals requires real-time sensor networks to optimize energy consumption and enable digital twin deployments.
- Remote Monitoring:Vibration sensing and corrosion monitoring in Southeast Asian energy projects favor leased infrastructure models over capital expenditure procurement.
- Data Analytics:Post-process optimization layers aggregate historical operational data for predictive maintenance without hard real-time constraints.
Factory automation leads installed base value; process automation is expanding most quickly under emissions compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT mandates and Japan's precision electronics clusters drive contrasting infrastructure priorities across the region, while South Korea's semiconductor corridors and Vietnam's manufacturing expansion create divergent procurement patterns for network equipment suppliers.
China
Steel and cement producers under dual carbon goals deploy real-time sensor networks to optimize energy consumption. MIIT's GB/T 33008 and GB/T 33009 standards mandate encrypted device authentication and access logging for critical manufacturing sectors. Shanghai and Beijing semiconductor fabrication facilities prioritize domestic vendors with pre-certified cybersecurity stacks to accelerate deployment timelines.
Japan
Automotive tier-one suppliers in Aichi prefecture pilot Time-Sensitive Networking for AI-guided quality inspection systems. METI promotes JIS-compliant open connectivity frameworks that accelerate interoperability between competing automation platforms. Precision electronics clusters in Nagoya and Osaka demand deterministic sub-millisecond communication architectures for motion control applications.
South Korea
Semiconductor fabrication corridors require localized ultra-reliable low-latency networks for automation equipment. The Ministry of Science and ICT has released dedicated industrial 5G frequencies that enable private spectrum deployment. Samsung and SK Hynix facilities in Gyeonggi province anchor demand for validated communication architectures meeting KOSHA industrial safety standards.
Vietnam
Samsung and Foxconn expansion in Bac Ninh and Bac Giang provinces creates demand for localized 5G private network integration. Electronics manufacturing growth favors vendors without incumbent lock-in from legacy automation platforms. Northern industrial corridors attract communication infrastructure investment as production-linked incentive schemes expand capacity.
Australia
Offshore oil platforms favor asset-as-a-service wireless sensor networks due to project finance constraints favoring operational expenditure. IECEx-certified equipment requirements extend procurement cycles versus standard industrial ratings. Western Australian energy projects concentrate demand with validated suppliers capable of meeting intrinsic safety certification timelines.
Asia Pacific Industrial Communication Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European-headquartered automation conglomerates holding established positions in process industries while Asian electronics fabricators capture wireless and edge-computing deployments. The vendor base organizes around three strategic archetypes: integrated automation platform providers, telecommunications infrastructure specialists extending into industrial verticals, and component-focused connectivity hardware manufacturers. Competitive moves concentrate on strategic partnerships for 5G private network integration and portfolio diversification into software-defined networking subscription layers.
Among European-headquartered industrial automation conglomerates, Siemens AG and ABB Ltd exemplify platform-integrated archetypes that anchor recurring revenue through digital twin ecosystems. Schneider Electric SE occupies a position bridging discrete manufacturing and energy infrastructure applications. Huawei Technologies represents the telecommunications infrastructure specialist archetype extending private 5G solutions into factory automation contexts. Mitsubishi Electric and Rockwell Automation sit within the premium-tier automation vendor category serving precision manufacturing clusters.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Siemens AG |
| Rockwell Automation |
| Moxa Inc |
| Advantech Co., Ltd. |
| Mitsubishi Electric |
| SICK AG |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive silicon sourcing from Taiwan and South Korea anchors pricing power for industrial Ethernet switch suppliers, while Chinese vendors leverage domestic rare earth processing to compress magnetics costs and undercut foreign competitors on fieldbus termination units.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for wireless sensor network deployments as local electronics manufacturing corridors absorb regional demand without incumbent vendor premiums. Three-tier pricing structure across premium, standard, and economy levels separates TSN-certified equipment for Japanese automotive paint shops from uncertified alternatives for Southeast Asian brownfield retrofits. Pricing pressure stems from Chinese domestic vendors with pre-certified MIIT cybersecurity stacks accelerating deployment timelines in Shanghai semiconductor fabrication facilities. State-owned steel and cement producers under dual carbon mandates exhibit lowest price sensitivity due to compliance-driven procurement timelines, while Vietnamese contract electronics manufacturers prioritize economy-tier solutions to preserve margin on thin assembly contracts.
Supply Chain Analysis
Engineering talent scarcity in Malaysia and Thailand constrains expansion of industrial communication hardware assembly beyond established Chinese and Taiwanese manufacturing hubs. Switch ASIC fabrication concentrates in Taiwan and South Korea, while shielded cable assemblies draw from Indonesian nickel and Chinese rare earth processing quotas. Single-source vulnerability in Taiwan semiconductor foundry capacity exposes lead times to geopolitical friction. Distribution runs through authorized automation distributors serving Japanese precision electronics clusters and direct procurement channels for Chinese state-owned enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Industrial Communication Market operates as a regulatory compounder where China's MIIT industrial internet standards and Japan's METI open connectivity frameworks create successive compliance-driven replacement cycles that sustain vendor revenue across product generations.
For Market Incumbents: Cement dominance in Japanese precision electronics clusters by deepening TSN certification portfolios for AI-guided quality inspection systems. Acquire edge-computing software specialists to counter Huawei's integrated 5G private network solutions threatening Rockwell Automation's North American-headquartered manufacturer relationships. Prioritize KOSHA-validated architectures for South Korean semiconductor fabrication corridors where Samsung and SK Hynix anchor procurement decisions.
For New Entrants and Emerging Players: Begin with Vietnam's Bac Ninh and Bac Giang electronics corridors where Samsung and Foxconn expansion creates demand without incumbent automation platform lock-in. Target asset-as-a-service wireless sensor networks in Australia's offshore energy platforms where project finance constraints favor operational expenditure structures. Pursue channel partnerships with Alibaba Cloud and Huawei Cloud for hybrid edge-to-cloud subscription revenue models.
For Investors and Strategic Acquirers: Roll-up economics work for component-focused connectivity hardware manufacturers because fragmented fieldbus gateway suppliers lack scale to absorb MIIT certification costs. Five-to-ten year viability hinges on software-defined networking subscription layers displacing capital expenditure procurement. Watch South Korea's Ministry of Science and ICT spectrum allocation pace as inflection indicator for private 5G network deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Cybersecurity Certification Investment | Pre-certified domestic vendors capture Shanghai semiconductor fabrication procurement timelines. |
| TSN Protocol Stack Development | Japanese automotive tier-one suppliers in Aichi prefecture pilot AI-guided quality inspection convergence. |
| 5G Private Spectrum Partnership | South Korea's Ministry of Science and ICT industrial frequencies enable localized ultra-reliable networks. |
| Asset-as-a-Service Model Expansion | Australia's offshore oil platforms favor leased vibration monitoring over capital expenditure procurement. |
| Edge-to-Cloud Platform Integration | Hybrid architectures with Alibaba Cloud open recurring subscription revenue for connectivity vendors. |
Research Methodology
Coverage spans China, Japan, South Korea, Vietnam, and Australia, with primary inputs from each market combining interviews with plant engineers, automation procurement managers, MIIT certification consultants, and semiconductor fabrication facility directors alongside secondary validation from SEC filings of listed automation conglomerates, MIIT GB/T standard documentation, METI industrial policy white papers, and customs data on industrial Ethernet switch imports. Bottom-up triangulation across vendor shipment disclosures and top-down reconciliation against national industrial automation expenditure surveys anchor volume estimates.
Rate-of-change decomposition separates technology substitution effects from regulatory compliance-driven replacement and greenfield expansion contributions across the projection horizon. Segmentation dimensions modeled include Ethernet versus wireless versus fieldbus technology tiers, manufacturing versus energy versus oil and gas end-use applications, hybrid versus edge versus on-premise deployment architectures, and factory automation versus process automation versus remote monitoring application criticality. CAGRs derive from fitted growth curves calibrated to historical adoption patterns in comparable industrial technology transitions, with semiconductor fabrication capacity expansion and dual carbon mandate enforcement timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor foundry operations, abrupt relaxation of China's dual carbon enforcement, and unilateral ASEAN data sovereignty rule harmonization. Forecasts reflect assumptions about regulatory continuity and supply chain configuration stability. Material deviation in MIIT certification timeline acceleration or South Korean spectrum allocation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Intralogistics Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Motion Control Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Port Equipment Automation Market