
 Industrial Internet Connectivity Tracker Market | 2026-2036
Industrial Internet Connectivity Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Internet Connectivity Tracker Market Foresight
IEC 62443 certification for industrial cybersecurity is unwinding the competitive landscape for connectivity tracker vendors. Cisco Systems, Inc. leverages its networking heritage to dominate enterprise-grade Ethernet deployments in process industries. Siemens AG anchors its position through deep integration between connectivity trackers and its PLC ecosystems. Rockwell Automation, Inc. competes by specializing in North American automotive and discrete manufacturing verticals.
The Industrial Internet Connectivity Tracker comprises hardware and software systems that monitor, log, and analyze network performance across industrial environments, typically operating at temperature ranges from minus 40 to 75 degrees Celsius with IP67 ingress protection for factory floor deployment. Its primary purpose is to ensure deterministic data transmission between sensors, controllers, and enterprise systems in time-critical operations. Cellular and LPWAN technologies are capturing the fastest expansion as oil and gas operators deploy satellite-backhauled connectivity for remote pipeline monitoring. Smart manufacturing applications concentrate margin pools where real-time tracker data feeds directly into MES and digital twin platforms.
The EU Cyber Resilience Act mandates security-by-design for connected industrial devices, compelling tracker vendors to embed hardware root-of-trust modules and maintain vulnerability disclosure programs. In the United States, NIST's Cybersecurity Framework and FCC spectrum allocations for private 5G networks shape how manufacturers license and deploy localized connectivity infrastructure. China's MIIT enforces GB standards for industrial internet platforms that dictate data localization and interface protocols for foreign equipment. Stakeholders must weigh sovereign data requirements against interoperability needs when selecting tracker architectures for multi-country deployments.
Market Dynamics
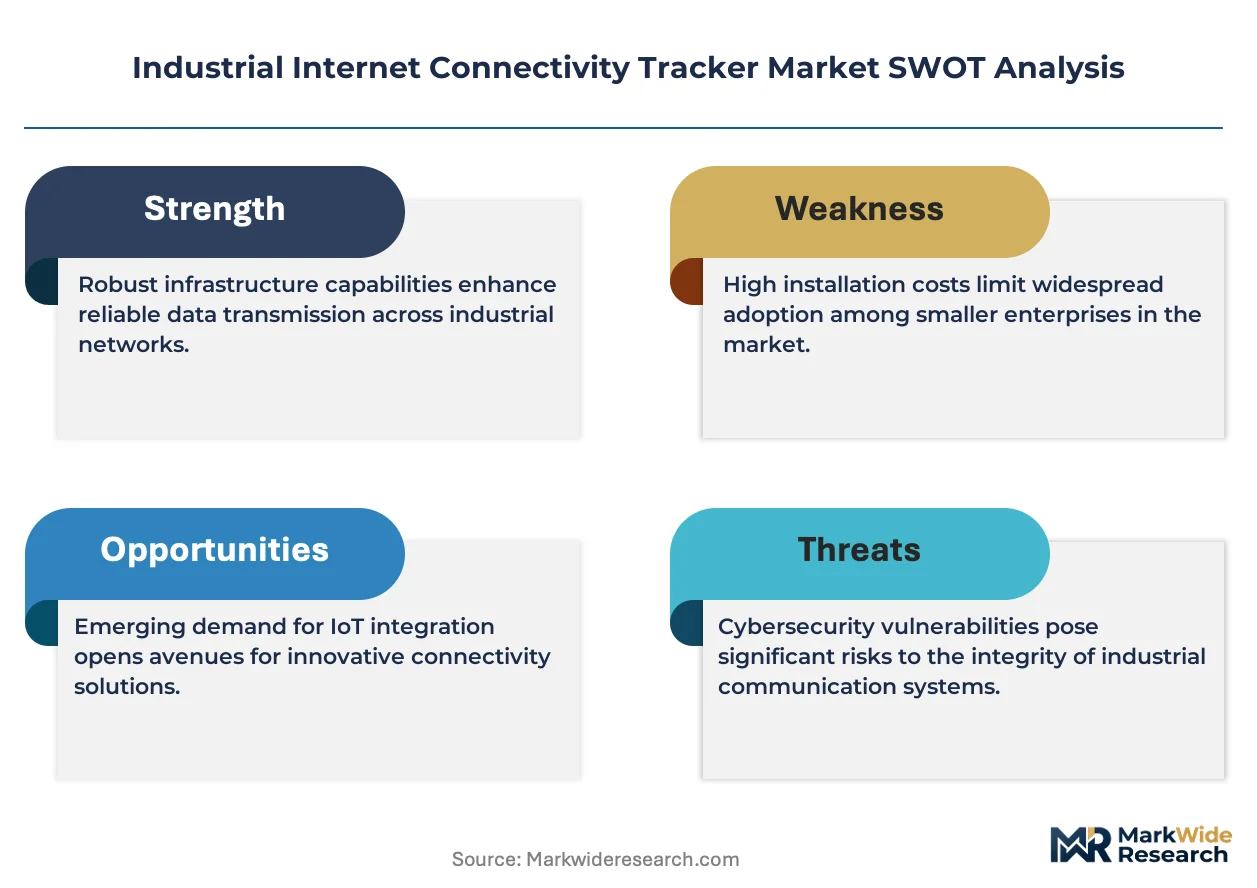
IEC 62443 certification requirements and the EU Cyber Resilience Act are compressing vendor margins while simultaneously erecting barriers to market entry. Hardware root-of-trust modules and mandatory vulnerability disclosure programs now define procurement minimums across German automotive and Japanese semiconductor clusters.
Growth Catalysts
- EU Cyber Resilience Act:Mandates security-by-design for connected industrial devices, compelling facility operators to replace legacy connectivity infrastructure with certified tracker hardware.
- LPWAN deployment in German smart manufacturing:Asset tracking systems using low-power wide-area networks are expanding across Bavarian automotive plants and Ruhr Valley process industries.
- Private 5G spectrum allocation:FCC licensing frameworks in the United States enable localized connectivity infrastructure for oil and gas pipeline monitoring with satellite backhaul.
Market Restraints
- Hardware root-of-trust cost inflation:Secure element integration adds 15-25% to bill-of-materials for IP67-rated industrial enclosures.
- East Asian semiconductor concentration:Discrete component sourcing for minus 40 to 75 degrees Celsius-rated chipsets depends heavily on Taiwan and South Korean foundry capacity.
- GB standard interface mandates:China's MIIT data localization requirements create protocol fragmentation for multinational deployments spanning Shenzhen, Shanghai, and foreign hubs.
Strategic Opportunities
- Underpenetrated Brazilian heavy industry:ANVISA-equivalent industrial safety frameworks are driving first-time connectivity tracker adoption in Minas Gerais mining operations.
- Digital twin convergence:Real-time tracker data feeding directly into MES platforms creates bundled solution opportunities with Siemens and Rockwell automation ecosystems.
- Japanese METI carbon accounting mandates:Energy consumption monitoring via connectivity trackers qualifies for subsidies under the country's green transformation initiative.
Industry Challenges
- IEC 62443 certification timeline compression:Four-stage certification for industrial cybersecurity now requires 18-24 months, delaying product launches for mid-tier vendors.
- Legacy PLC protocol integration:Deterministic data transmission requirements force custom firmware development for brownfield deployments in North American discrete manufacturing.
- Multi-country vulnerability disclosure:Maintaining coordinated response programs across EU, US, and Chinese regulatory jurisdictions strains compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Internet Connectivity Tracker Market |
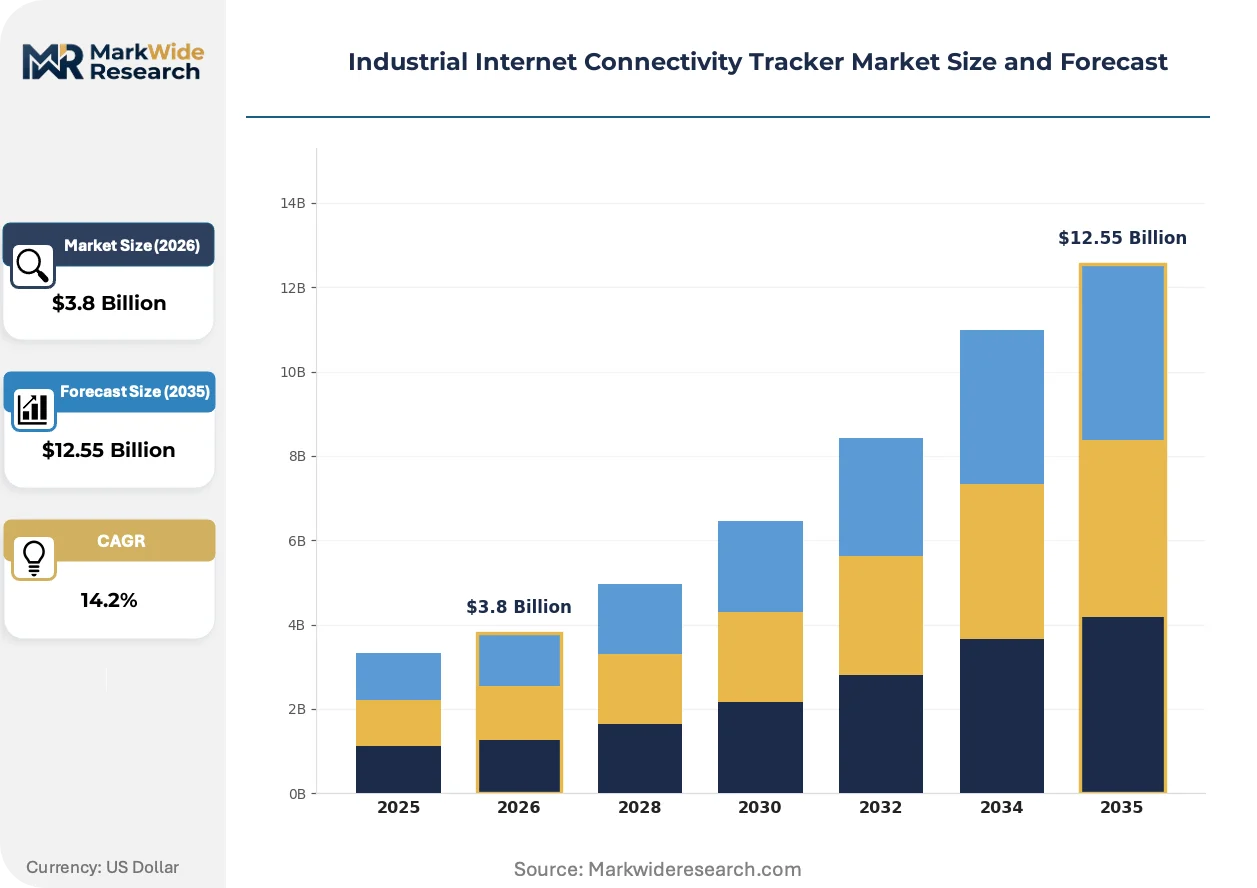
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cellular, LPWAN, Ethernet, Wi-Fi Application: Remote Monitoring, Predictive Maintenance, Asset Tracking, Smart Manufacturing End User: Manufacturing, Oil & Gas, Utilities, Transportation Deployment: On-Premise, Cloud-Based, Hybrid, Edge |
| Companies Covered | Cisco Systems, Inc., Microsoft Corporation, Rockwell Automation, Inc., Siemens AG, ABB Ltd., Honeywell International Inc., General Electric Company, Intel Corporation, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Internet Connectivity Tracker Market Shifts & Advancements
Edge computing architectures and deterministic networking protocols are converging to reshape how industrial connectivity trackers process and transmit time-critical operational data. Three developments are compressing deployment cycles and redefining competitive positioning.
Multi-protocol system-on-chip designs for industrial connectivity trackers is miniaturizing. Oil and gas operators in the Permian Basin and North Sea are adopting these consolidated chipsets for remote pipeline monitoring. Component consolidation is compressing printed circuit board real estate by 40% while maintaining IP67 ingress protection ratings.
REACH and RoHS substance restrictions are tightening material specifications for factory-floor hardware. European manufacturers must now document full material declarations for connectivity tracker enclosures and solder compositions. German automotive suppliers are responding by qualifying halogen-free PCB substrates ahead of 2026 enforcement windows.
Subscription-based firmware update models are displacing perpetual license structures for connectivity management platforms. Discrete manufacturers in Michigan and Ontario are prioritizing vendors offering continuous security patch delivery over upfront capital expenditure. This preference shift favors Cisco and Siemens with established software service organizations.
Industrial Internet Connectivity Tracker Market Segmentation
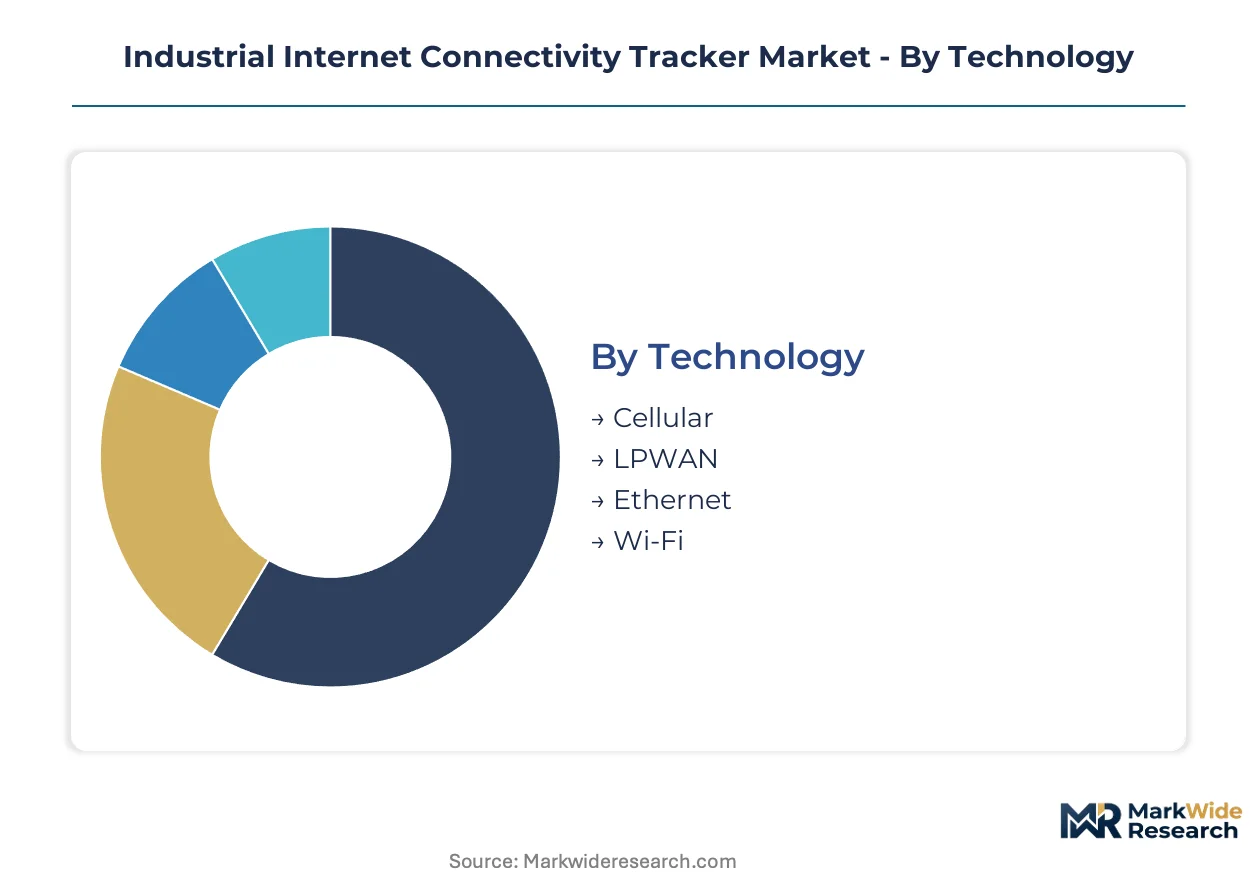
Industrial Internet Connectivity Tracker segmentation reveals how regulatory mandates reshape technology procurement across deployment environments. IEC 62443 certification requirements and the EU Cyber Resilience Act create divergent compliance burdens that vendors must navigate through specialized hardware configurations.
Technology:
IEC 62443 certification tiers differentiate connectivity protocols, with hardware root-of-trust modules now mandatory for critical infrastructure deployments in Germany and Japan.
- Cellular:Satellite-backhauled LTE and 5G modules operate across minus 40 to 75 degrees Celsius ranges with IP67 enclosures. Oil and gas operators in the Permian Basin and North Sea deploy these for remote pipeline monitoring where deterministic latency under 50 milliseconds is non-negotiable.
- LPWAN:Low-power wide-area networks using LoRaWAN and NB-IoT protocols enable decade-long battery life for dispersed asset tracking. Bavarian automotive plants and Ruhr Valley process industries in Germany are expanding LPWAN deployments to satisfy METI-equivalent energy efficiency benchmarks.
- Ethernet:Time-sensitive networking variants support microsecond-precision synchronization for motion control applications.
- Wi-Fi:Wi-Fi 6E industrial access points handle high-density sensor clusters in smart manufacturing floors.
Ethernet handles the majority of throughput in time-critical motion control; LPWAN is the fastest mover on share as German and Japanese facilities prioritize energy-efficient asset tracking.
Application:
Cost tier differentiation separates premium predictive maintenance suites from standardized remote monitoring dashboards, with bundled MES integration commanding 40-60% pricing premiums.
- Smart Manufacturing:Real-time tracker data feeds directly into digital twin platforms and MES systems, creating bundled solution opportunities with automation vendors. Semiconductor fabs in Taiwan and automotive plants in Michigan concentrate demand where deterministic data transmission synchronizes robotic cells.
- Predictive Maintenance:Vibration and thermal anomaly detection algorithms run on edge-computing modules embedded within connectivity trackers. Japanese METI carbon accounting mandates subsidize energy consumption monitoring deployments in Osaka and Nagoya industrial corridors.
- Asset Tracking:LPWAN-enabled location services monitor high-value equipment across sprawling facility footprints.
- Remote Monitoring:Satellite-backhauled connectivity serves pipeline and grid infrastructure beyond cellular coverage.
Smart Manufacturing captures the steepest expansion trajectory as digital twin convergence accelerates; Asset Tracking dominates unit volumes in brownfield facility retrofits.
End User:
Volume concentration clusters around automotive and semiconductor manufacturing hubs where deterministic networking is mission-critical, while margin pools favor oil and gas deployments requiring hazardous-area certifications.
- Manufacturing:Discrete and process industries deploy IP67-rated trackers across welding, assembly, and coating operations. German automotive suppliers in Stuttgart and Wolfsburg are qualifying halogen-free PCB substrates ahead of REACH enforcement windows.
- Oil & Gas:Explosion-proof enclosures and satellite backhaul serve remote wellhead and pipeline monitoring. FCC private 5G spectrum allocations enable localized infrastructure in the Permian Basin with 99.999% uptime requirements.
- Utilities:Grid modernization drives substation automation with IEC 61850 protocol compliance.
- Transportation:Fleet telematics and rail signaling systems demand continuous connectivity across mobile assets.
Manufacturing absorbs the highest absolute unit volumes; Oil & Gas delivers the strongest margin contribution per deployment.
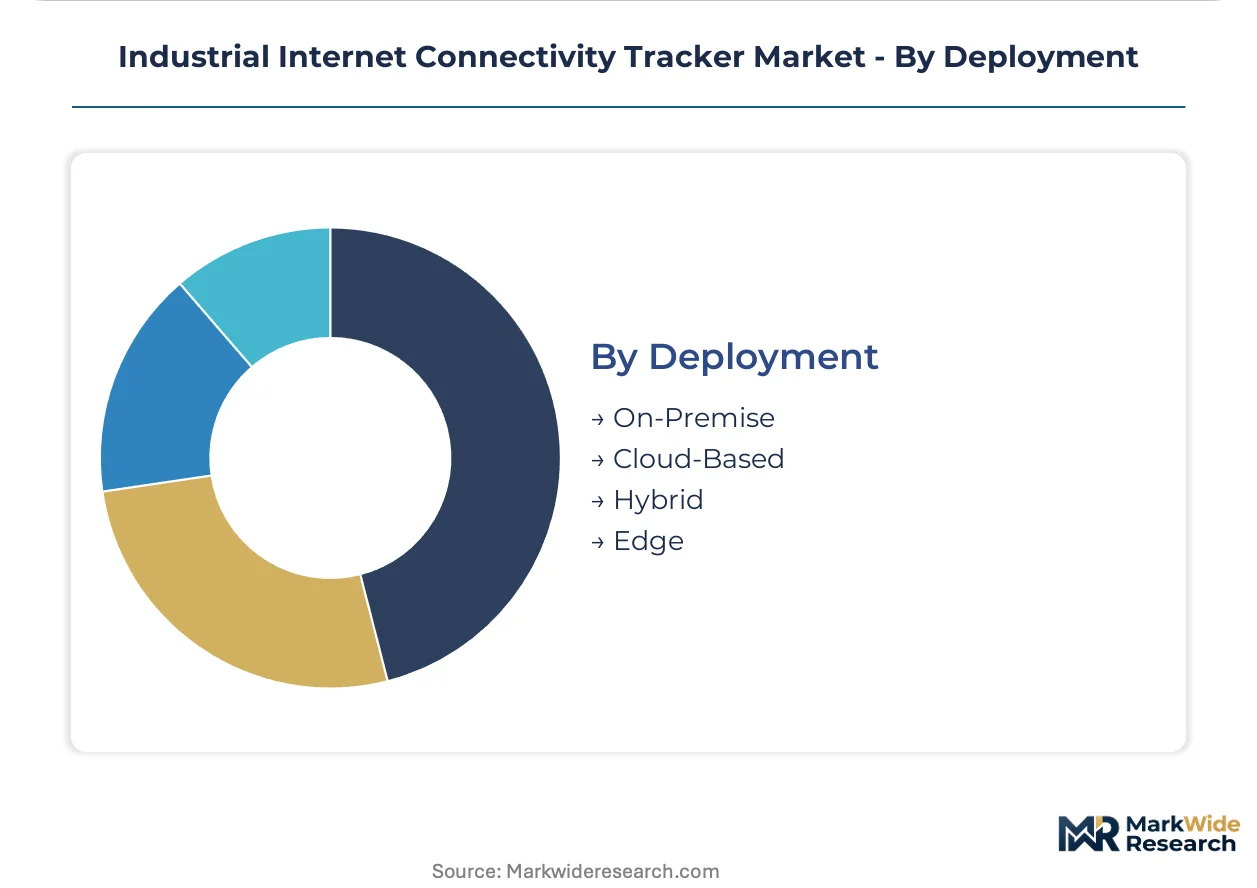
Deployment:
Customer type stratification separates asset-light subscription buyers from capital-intensive on-premise operators, with hybrid architectures gaining traction among mid-tier discrete manufacturers.
- Edge:Distributed computing nodes process time-critical data locally before cloud transmission, compressing latency to sub-10 milliseconds. Multi-protocol system-on-chip designs are miniaturizing printed circuit board real estate by 40% while maintaining IP67 ratings.
- Hybrid:Split architectures keep sensitive operational data on-premise while pushing analytics workloads to cloud infrastructure. Michigan and Ontario discrete manufacturers prioritize vendors offering continuous security patch delivery over upfront capital expenditure.
- On-Premise:Air-gapped deployments satisfy sovereign data requirements in defense and critical infrastructure sectors.
- Cloud-Based:Fully managed SaaS platforms reduce IT overhead for small and mid-sized facilities.
Edge deployment leads on revenue intensity per node; Hybrid is climbing the fastest as manufacturers balance latency against scalability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Cyber Resilience Act mandates and FCC private 5G spectrum frameworks are redirecting procurement flows toward certified industrial connectivity infrastructure across four major economies.
United States
Oil and gas operators in the Permian Basin drive satellite-backhauled connectivity deployments for remote pipeline monitoring. FCC spectrum allocations for private 5G networks enable localized infrastructure with 99.999% uptime requirements. Michigan and Ontario discrete manufacturers prioritize subscription-based firmware update models over upfront capital expenditure.
Germany
Bavarian automotive plants and Ruhr Valley process industries expand LPWAN-based asset tracking systems to satisfy energy efficiency benchmarks. REACH and RoHS substance restrictions compel Stuttgart and Wolfsburg suppliers to qualify halogen-free PCB substrates ahead of 2026 enforcement windows. IEC 62443 certification now defines procurement minimums across German automotive clusters.
Japan
METI carbon accounting mandates subsidize energy consumption monitoring deployments in Osaka and Nagoya industrial corridors. Semiconductor fabs in Kyushu and automotive plants in Toyota City concentrate demand where deterministic data transmission synchronizes robotic cells. Japanese facilities prioritize decade-long battery life for dispersed asset tracking applications.
China
MIIT enforces GB standards for industrial internet platforms that dictate data localization and interface protocols for foreign equipment. Shenzhen and Shanghai factory automation clusters drive demand for IP67-rated hardware operating across minus 40 to 75 degrees Celsius ranges. Sovereign data requirements create protocol fragmentation for multinational deployments.
Industrial Internet Connectivity Tracker Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and ecosystem integration breadth. The vendor base stratifies into three tiers: networking heritage giants with enterprise-grade Ethernet portfolios, automation incumbents anchoring through PLC ecosystem lock-in, and component specialists miniaturizing multi-protocol system-on-chip designs. Dominant competitive moves include strategic partnerships with MES platform vendors and geographic expansion into underpenetrated Brazilian and Southeast Asian heavy industry corridors.
Within the networking heritage tier, Cisco Systems, Inc. and Siemens AG exemplify divergent strategic positioning. Cisco leverages its enterprise infrastructure dominance into process industry deployments requiring deterministic latency under 50 milliseconds. Siemens anchors its competitive position through deep integration between connectivity trackers and its proprietary PLC ecosystems, creating bundled solution opportunities in German automotive and discrete manufacturing verticals. Rockwell Automation, Inc. occupies a specialized position serving North American automotive clusters with legacy protocol integration capabilities.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Rockwell Automation, Inc. |
| Siemens AG |
| ABB Ltd. |
| Honeywell International Inc. |
| General Electric Company |
| Intel Corporation |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Hardware root-of-trust module substitution for discrete security chips is compressing printed circuit board footprints while simultaneously shifting procurement gravity toward Taiwan and South Korean foundries capable of certified secure element integration. This consolidation concentrates pricing power among semiconductor vendors serving IEC 62443-compliant tracker manufacturers.
Pricing Analysis
Certification level creates the primary spread between connectivity tracker tiers, with IEC 62443-4-2 SL3 hardware commanding substantial premiums over baseline IP67-rated units. Three-tier pricing structure across premium certified, standard industrial, and economy unenclosed levels separates automotive procurement in Stuttgart from brownfield retrofits in Michigan. Cost compression in economy tiers is intensifying because Chinese GB-standard interface mandates force redundant SKU development for multinational vendors. Discrete manufacturers in Ontario exhibit highest price sensitivity, while oil and gas operators in the Permian Basin prioritize 99.999% uptime over unit economics.
Supply Chain Analysis
Taiwan Strait transit risk underwrites supply vulnerability for minus 40 to 75 degrees Celsius-rated industrial chipsets, with foundry capacity concentrated in Hsinchu and Taichung science parks. Component sourcing draws from South Korean memory suppliers, Japanese precision sensor fabricators, and German enclosure specialists. Single-source vulnerability in secure element production strains compliance timelines for mid-tier vendors seeking IEC 62443 certification. Distribution runs through automation distributor networks anchored by Siemens and Rockwell channel partnerships in Bavaria and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Internet Connectivity Tracker Market sits in early-cycle expansion as EU Cyber Resilience Act mandates trigger replacement waves across German and Japanese installed bases. Regulatory tailwinds in cybersecurity certification are accelerating first-time adoption beyond traditional automation strongholds.
For Market Incumbents: Compound ecosystem lock-in through deeper MES platform integration and accelerated certification investment to outpace 18-24 month IEC 62443 timelines. Defensive moves should prioritize captive secure element supply arrangements with Taiwanese foundries and channel control expansion into underpenetrated Brazilian mining corridors. Threat substitution from LPWAN-native entrants demands firmware differentiation in energy efficiency benchmarking. For New Entrants and Emerging Players: Anchor in Japanese METI carbon accounting subsidy flows by qualifying energy consumption monitoring SKUs for Osaka and Nagoya industrial corridors. White-space targets include halogen-free PCB substrate supply for Stuttgart automotive suppliers ahead of REACH enforcement. Most penetrable segment is hybrid deployment architectures among mid-tier Michigan discrete manufacturers seeking subscription-based security patch delivery. For Investors and Strategic Acquirers: The market sits at a standards-mandated replacement phase that favors certified hardware specialists with established vulnerability disclosure programs. Long-term viability centers on vendors capable of sustaining 18-24 month certification cycles while maintaining multi-protocol SoC miniaturization roadmaps. Acquisition target archetype: mid-tier vendors with IEC 62443-4-1 development process certification but lacking 4-2 product certification. Signal to watch is FCC private 5G spectrum auction participation rates among oil and gas operators.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Acceleration | Compresses 18-24 month timelines to capture German automotive replacement cycles ahead of competitors. |
| Multi-Protocol SoC Miniaturization | Consolidates LoRaWAN, NB-IoT, and Ethernet onto single chipsets for Permian Basin pipeline operators. |
| Halogen-Free PCB Qualification | Positions vendors for Stuttgart supplier procurement ahead of 2026 REACH substance enforcement windows. |
| Subscription Firmware Service Launch | Aligns with Michigan manufacturer preference for continuous security patch delivery over capital expenditure. |
| Brazilian Heavy Industry Expansion | Captures first-time connectivity tracker adoption in Minas Gerais mining operations under ANVISA-equivalent frameworks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, FCC spectrum allocation records, EU regulatory databases, and industrial automation trade publications. Primary interviews engaged plant engineers at German automotive facilities, procurement leads at North American discrete manufacturers, channel partners in Japanese automation distribution, and regulatory affairs specialists navigating MIIT GB standard compliance. Bottom-up unit demand modeling triangulated against top-down market sizing derived from automation vendor revenue disclosures.
Segmentation dimensions modeled span connectivity protocol, deployment architecture, end-use vertical, and geographic regulatory cluster across the projection horizon. CAGRs emerged from weighted scenario analysis incorporating IEC 62443 adoption curves, LPWAN deployment trajectories in Bavarian plants, and private 5G infrastructure buildout rates. Industry-specific forecast inputs included semiconductor foundry capacity allocation for industrial temperature-rated chipsets and METI carbon accounting subsidy uptake rates.
Material uncertainties — tariff exposure on Taiwanese components, REACH substance restriction timeline shifts, and FCC spectrum auction timing — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and foundry capacity continuity. Practitioners should keep alternative scenarios live as EU Cyber Resilience Act enforcement intensity and Chinese data localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Middle East and Africa Machine Control System Market