
 Embedded Analytics Market | 2026-2036
Embedded Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Analytics Market Intelligence
Multi-source API aggregation is pivoting from a peripheral capability to a core procurement criterion for enterprise software buyers. Microsoft Corporation leverages its Azure cloud footprint to bundle Power BI embedding across Office 365 and Dynamics workflows. SAP SE anchors its competitive stance through deep integration with S/4HANA ERP instances, while QlikTech International AB differentiates via associative engine architecture that reduces query latency for embedded scenarios.
Embedded analytics denotes the integration of data visualization, reporting, and predictive capabilities directly within business applications rather than standalone BI platforms, typically deployed through JavaScript APIs, iframe containers, or native SDKs with sub-second query response thresholds. Cloud-based deployment leads solution uptake as SaaS vendors seek to offload infrastructure maintenance and scale elastic compute for concurrent users. Predictive analytics segments command premium positioning due to specialized machine learning engineering requirements, whereas self-service dashboards have matured into a baseline expectation across enterprise software procurement.
The EU AI Act imposes transparency obligations on automated decision systems, compelling embedded analytics vendors to build explainability layers into predictive modules. HIPAA security rule enforcement by the US Department of Health and Human Services restricts data residency architectures for healthcare-facing deployments. Stakeholders must evaluate how forthcoming algorithmic accountability frameworks in the European Union and sector-specific US federal rules will reshape embedding architectures and customer liability profiles.
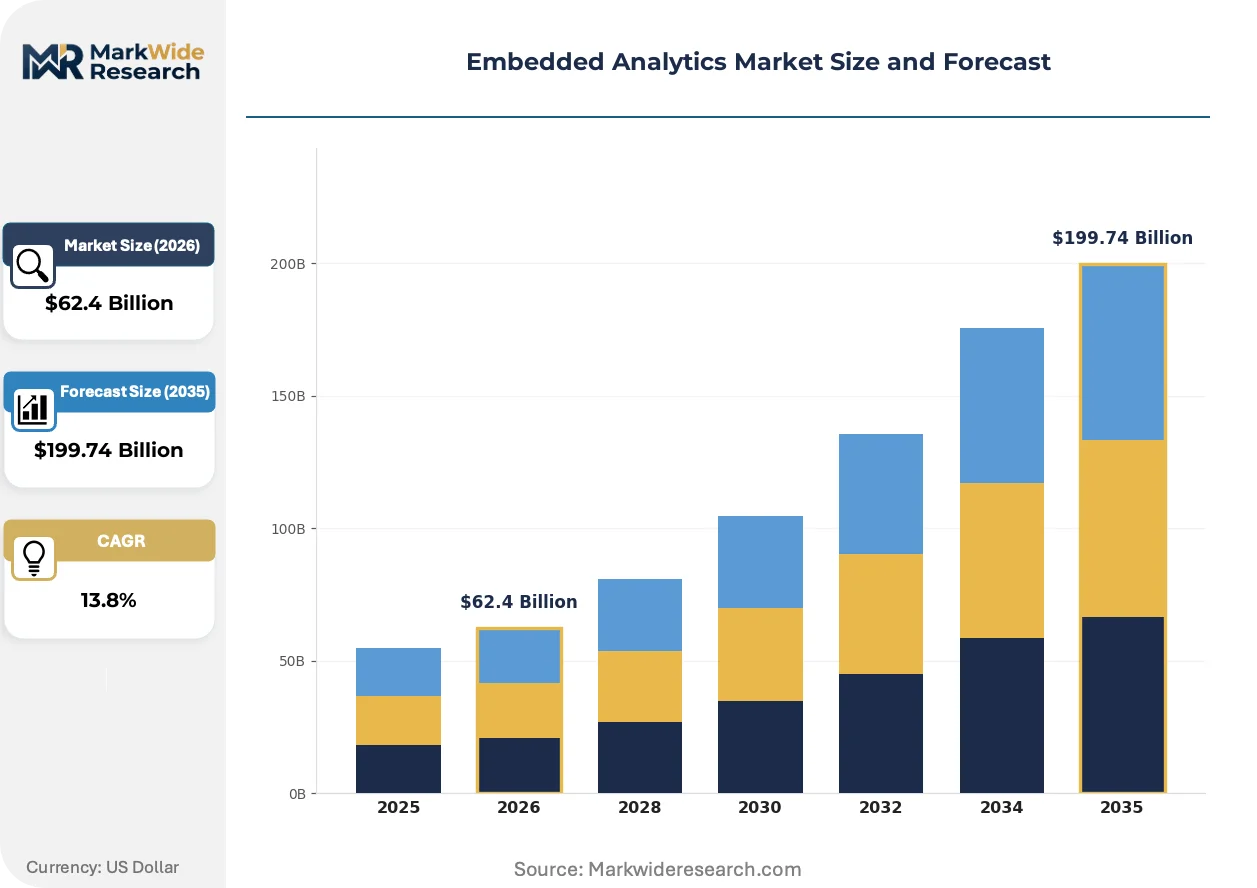
Market Dynamics
Cloud migration mandates under the EU AI Act and HIPAA security rules are forcing embedded analytics vendors to rearchitect deployment models, reshaping procurement criteria toward API-first, compliance-certified infrastructure.
Growth Catalysts
- Healthcare real-time monitoring:Hospitals deploy patient dashboards with sub-second refresh rates, embedding predictive alerts directly into electronic health record workflows.
- EU AI Act transparency obligations:Automated decision systems in finance and healthcare must incorporate explainability layers, creating pull for interpretable ML modules.
- Automotive predictive maintenance:German OEMs embed analytics modules directly into manufacturing execution systems to minimize unplanned downtime.
Market Restraints
- Specialized ML engineering scarcity:Predictive analytics segments require rare cross-functional talent, inflating implementation costs and extending deployment timelines.
- Data residency fragmentation:HIPAA enforcement by the US Department of Health and Human Services restricts cross-border architectures, complicating multi-tenant SaaS delivery.
- JavaScript API performance ceilings:Sub-second query thresholds strain browser-based rendering, limiting visualization complexity for high-cardinality datasets.
Strategic Opportunities
- India's PLI scheme for software:Production-linked incentives attract embedded analytics R&D centers targeting domestic IT services and global capability centers.
- Edge-to-cloud convergence:Hybrid architectures combining local inference with centralized model training open manufacturing and logistics applications with intermittent connectivity.
- CSRD sustainability reporting:European corporates must embed emissions tracking into operational dashboards, creating demand for ESG-integrated analytics modules.
Industry Challenges
- Legacy ERP integration friction:SAP S/4HANA and older instances require custom connector development, consuming 30-40% of implementation budgets.
- Algorithmic accountability preparation:Vendors must pre-build audit trails and bias detection before EU enforcement timelines tighten liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Analytics Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $199.74 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge, Multi-Cloud Solution/Offering: Self-Service Analytics, Real-Time Data Integration, Predictive Analytics, Dashboards, Data Visualization Use Case: Customer Insights, Operations Optimization, Fraud Detection, Risk Management, Sales Forecasting End User Industry Vertical: Telecommunications, Manufacturing, Government, Transportation, Education |
| Companies Covered | Microsoft Corporation, IBM Corporation, SAP SE, Oracle Corporation, Tableau Software, QlikTech International AB, Sisense Inc., MicroStrategy Incorporated, TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Analytics Market Strategic Shifts & Innovations
Embedded analytics is pivoting from standalone visualization toward composable, API-native intelligence layers that dissolve the boundary between analytical and transactional systems.
Natural language querying is consolidating SQL-based exploration workflows into conversational interfaces. Business users in financial services and retail adopt text-to-chart capabilities without BI training. This compression of the analytics learning curve is consolidating vendor competitive differentiation around LLM orchestration rather than traditional query engine performance.
The EU AI Act's risk-based classification system imposes documentation burdens on high-risk embedded deployments in credit scoring and medical diagnosis. Vectors of compliance investment now concentrate on model cards, training data provenance, and human-in-the-loop overrides. Healthcare technology procurement in Germany and France increasingly filters for AI Act readiness certifications.
Buyers now unbundle implementation services from software licenses, contracting specialized systems integrators for embedding architecture while negotiating direct SaaS relationships with platform vendors. This disintermediation of value-added resellers concentrates margin pressure on traditional channel partners. The pattern is most pronounced in US enterprise software procurement, where procurement teams separate infrastructure decisions from change management spend.
Embedded Analytics Market Segmentation
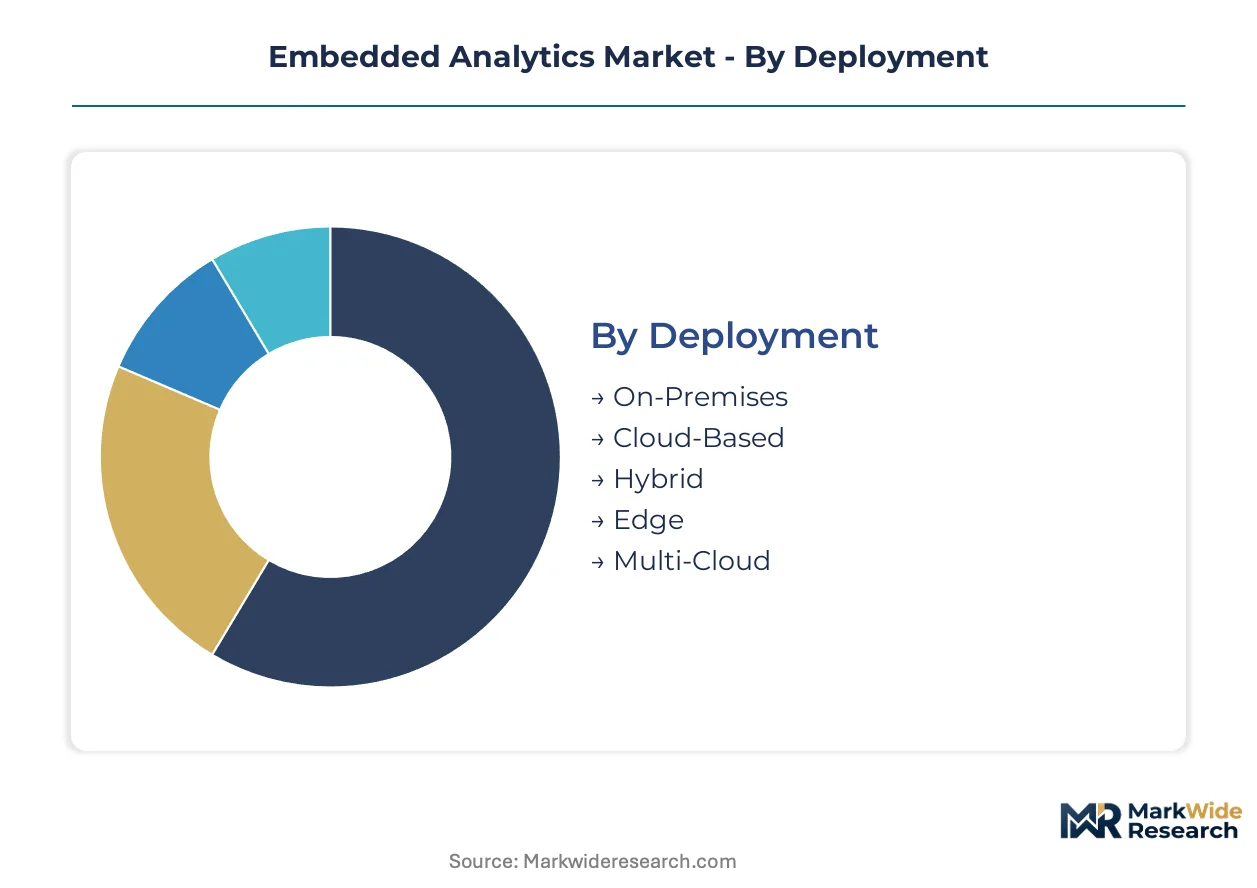
Segmentation in embedded analytics reveals how procurement priorities diverge across infrastructure maturity, analytical sophistication, and regulatory exposure. Buyers select deployment modes and solution bundles based on existing ERP upgrade cycles and sector-specific compliance burdens rather than feature comparisons alone.
Deployment:
Upgrade cycles for core enterprise systems are compressing deployment decisions, with cloud-native architectures displacing legacy on-premises estates during S/4HANA and Dynamics 365 migrations.
- On-Premises:Retained by defense contractors and classified government facilities requiring air-gapped environments with physical control over hardware stacks. German automotive suppliers maintain these installations for proprietary manufacturing data lakes subject to KBA audit protocols.
- Cloud-Based:Dominates new procurement as SaaS vendors offload infrastructure maintenance to hyperscale providers. HIPAA-covered entities in the US select HITRUST-certified Azure and AWS regions to satisfy data residency constraints without capital expenditure.
- Hybrid:Bridges transactional systems on legacy hardware with elastic compute for analytical workloads. French banking groups deploy this model to keep core banking data on-premises while bursting fraud detection models to cloud tensor clusters.
- Edge:Processes inference locally for manufacturing lines with intermittent connectivity. Japanese automotive plants embed edge nodes within welding robots to trigger predictive maintenance without cloud round-trip latency.
- Multi-Cloud:Distributes workloads across AWS, Azure, and GCP to mitigate vendor lock-in and optimize spot pricing. US healthcare technology firms adopt this architecture to maintain failover capacity during regional outages.
Cloud-Based sits at the top of the volume ranking, with Edge climbing the fastest as manufacturing digitization accelerates.
Solution/Offering:
Cost tiering separates commodity visualization from premium predictive capabilities, with machine learning engineering scarcity inflating pricing for advanced modules.
- Self-Service Analytics:Business users build reports without IT intervention through drag-and-drop interfaces. Retail chains in India deploy these tools to regional managers for inventory decisions, constrained by data literacy gaps in tier-2 cities.
- Real-Time Data Integration:Streams operational events into analytical models with sub-second latency. Telecommunications operators in South Korea embed these pipelines into network operations centers to detect fiber degradation before customer impact.
- Predictive Analytics:Applies machine learning to forecast outcomes and prescribe actions. Requires scarce cross-functional talent combining statistical modeling with domain expertise, extending implementation timelines and inflating professional services spend.
- Dashboards:Consolidated visual interfaces displaying KPIs across operational and financial metrics. Now a baseline procurement expectation rather than differentiating feature, with buyers evaluating refresh speed and mobile responsiveness.
- Data Visualization:Renders complex datasets as charts, maps, and network graphs for pattern recognition. Government agencies in Brazil deploy geospatial visualizations for public health resource allocation during vector-borne disease outbreaks.
Dashboards command the widest installed base, though Predictive Analytics is gaining share fastest as EU AI Act compliance investments concentrate on interpretable ML modules.
Use Case:
Application-specific deployment patterns reflect how deeply analytics embeds into revenue-critical versus cost-optimization workflows.
- Customer Insights:Segments behavioral data to personalize engagement and predict churn. E-commerce platforms in Southeast Asia integrate these modules into mobile app experiences, constrained by fragmented identity resolution across devices.
- Operations Optimization:Identifies inefficiencies in supply chains, production lines, and service delivery. German chemical manufacturers embed these capabilities into manufacturing execution systems to reduce energy intensity per ton output.
- Fraud Detection:Flags anomalous transactions in real-time using supervised and unsupervised models. US payment processors face SEC scrutiny over model drift in anti-money laundering algorithms, requiring continuous retraining pipelines.
- Risk Management:Quantifies exposure across credit, market, and operational categories. Basel III compliance drives European banks to embed these calculations directly into loan origination workflows for real-time capital allocation.
- Sales Forecasting:Projects revenue trajectories from pipeline data and macroeconomic indicators. Consumer goods companies in Mexico deploy these tools to adjust production schedules ahead of seasonal demand spikes.
Operations Optimization leads by deployment volume, with Fraud Detection expanding most quickly as real-time payment systems proliferate.
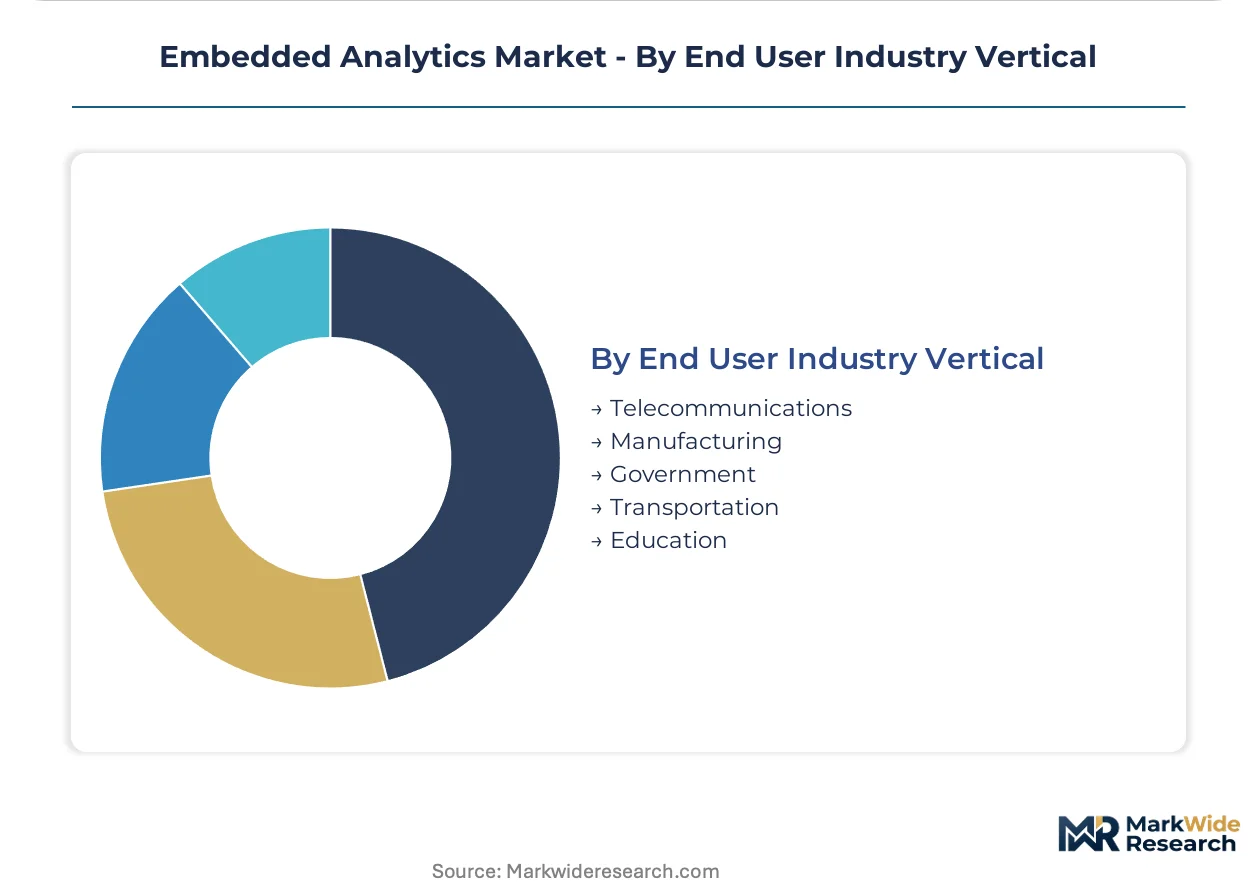
End User Industry Vertical:
Customer type segmentation reveals divergent procurement authority structures, with centralized IT governance in government contrasting business-unit-led purchasing in manufacturing.
- Telecommunications:Network operators embed analytics into customer care and infrastructure planning. 5G rollout investments in India drive demand for geospatial network optimization modules under TRAI quality-of-service mandates.
- Manufacturing:Factories integrate predictive maintenance and quality control into shop-floor systems. Japanese electronics producers embed computer vision analytics into surface-mount technology lines to detect soldering defects.
- Government:Agencies deploy citizen-facing dashboards and internal performance management tools. CSRD implementation pressures European municipalities to embed emissions tracking into procurement and facilities management systems.
- Transportation:Logistics providers optimize routing and fleet maintenance through embedded intelligence. Brazilian agribusinesses deploy these capabilities to coordinate grain truck movements from inland silos to port terminals.
- Education:Institutions track student progression and optimize resource allocation. US universities embed early-alert systems into learning management platforms to identify at-risk students for intervention.
Manufacturing holds the largest deployment base, with Government showing the steepest expansion trajectory as sustainability reporting mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters anchor embedded analytics demand through manufacturing execution system integrations. Cloud migration mandates under the EU AI Act and HIPAA security rules reshape procurement criteria across healthcare and financial services verticals.
United States
HIPAA-covered entities in healthcare accelerate real-time patient monitoring dashboard deployments. The Department of Health and Human Services enforces data residency restrictions that favor HITRUST-certified Azure and AWS regions. Boston's health technology corridor concentrates predictive analytics R&D for electronic health record workflows.
Germany
Automotive OEMs embed predictive maintenance modules directly into manufacturing execution systems to minimize unplanned downtime. The KBA audit protocols govern proprietary manufacturing data lakes for suppliers in Baden-Württemberg. Stuttgart's automotive engineering cluster drives edge-to-cloud convergence for welding robot analytics.
India
Production-linked incentive schemes attract embedded analytics R&D centers targeting domestic IT services and global capability centers. TRAI quality-of-service mandates propel 5G network optimization module demand among telecommunications operators. Bengaluru's software corridor hosts SaaS vendors developing API-first embedding architectures.
France
Banking groups deploy hybrid architectures keeping core banking data on-premises while bursting fraud detection models to cloud tensor clusters. The EU AI Act's risk-based classification system imposes documentation burdens on credit scoring deployments. Parisian fintech clusters concentrate explainable ML module development for algorithmic accountability.
Japan
Electronics producers embed computer vision analytics into surface-mount technology lines for soldering defect detection. METI industrial digitization programs subsidize edge node deployments in manufacturing facilities. Nagoya's automotive and industrial automation corridor leads predictive maintenance module integration.
Embedded Analytics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized ML engineering and edge-native architectures. The vendor base stratifies across three maturity tiers: hyperscale cloud platforms with embedded distribution advantages, ERP-anchored incumbents leveraging system integration depth, and independent specialists competing on query performance. Strategic archetypes include API-first platform vendors, compliance-certified healthcare specialists, and automotive-focused predictive maintenance providers. Dominant competitive moves encompass M&A for ML engineering talent and strategic partnerships with systems integrators to unbundle implementation services.
Among cloud-platform anchored vendors, Microsoft Corporation exemplifies the hyperscale distribution archetype through Azure-embedded bundling. SAP SE occupies the ERP-integrated tier, leveraging S/4HANA connectivity for manufacturing and financial services deployments. QlikTech International AB represents the independent specialist position, with associative engine architecture reducing query latency for embedded scenarios requiring sub-second response thresholds.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Tableau Software |
| QlikTech International AB |
| Sisense Inc. |
| MicroStrategy Incorporated |
| TIBCO Software Inc. |
| Others |
Cost & Logistics Intelligence
Machine learning engineering talent concentration in Bengaluru and Stuttgart widens pricing-tier spreads between commodity visualization modules and premium predictive analytics suites, with EU AI Act compliance certification adding a further cost differential.
Pricing Analysis
Input-cost pass-through from scarce ML engineering talent inflates professional services components within SaaS-tiered subscription models. Pricing stratifies across premium interpretable-ML tiers with EU AI Act documentation, standard self-service dashboard bundles, and economy API-only embedding licenses. Cost compression in the standard tier intensifies because hyperscale cloud vendors bundle analytics as loss-leaders for infrastructure contracts. Healthcare providers under HIPAA enforcement show least price sensitivity due to compliance liability exposure, while Indian retail chains exhibit highest sensitivity amid data literacy constraints.
Supply Chain Analysis
Certification and qualification gating through HITRUST, ISO 27001, and EU AI Act readiness documentation concentrates vendor eligibility among established cloud platforms and ERP-integrated incumbents. Component supply draws from hyperscale data center infrastructure in the United States, Germany, and India, with specialized edge hardware sourcing from Japanese and South Korean industrial automation suppliers. Single-source vulnerability in ML inference chip supply creates exposure for real-time analytics deployments. Distribution runs through direct SaaS relationships with enterprise procurement teams, bypassing traditional value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act enforcement timelines and HIPAA security rule expansions continuously expand addressable demand for compliance-certified embedding architectures.
For Market Incumbents: Lock in ERP integration depth through S/4HANA and Dynamics 365 connector roadmaps that consume 30-40% of rival implementation budgets. Pre-build audit trails and bias detection modules before EU enforcement tightens liability exposure, neutralizing emerging specialist threats in explainable ML.
For New Entrants and Emerging Players: Capture edge-native manufacturing analytics in Baden-Württemberg and Nagoya where intermittent connectivity demands hybrid architectures incumbent cloud vendors underserve. Target automotive predictive maintenance modules with welding robot inference nodes as the most penetrable wedge, selling through systems integrators unbundled from platform vendor relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among compliance-certified healthcare specialists with HITRUST validation and existing hospital system deployments. Long-term viability over the next decade hinges on algorithmic accountability infrastructure becoming table stakes. Watch EU AI Act high-risk system designations as the inflection signal triggering consolidation urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Microsoft Azure embeds Power BI across Office 365 workflows, consolidating distribution advantage. |
| Compliance Certification Investment | HITRUST and EU AI Act readiness documentation gates healthcare and finance procurement eligibility. |
| Acquisition of ML Engineering Talent | Specialist teams in Bengaluru and Paris accelerate interpretable model development timelines. |
| Edge-to-Cloud Hybrid Architecture | German automotive OEMs deploy welding robot inference nodes with centralized training pipelines. |
| Strategic Systems Integrator Partnership | Unbundled implementation services separate infrastructure decisions from change management spend. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists alongside secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory documentation databases. Bottom-up deployment volume estimates triangulated against top-down market sizing from vendor revenue disclosures and systems integrator project pipelines.
Segment-weighting across deployment models, organization size tiers, vertical industries, integration complexity levels, and regional adoption patterns shaped the analytical framework over the projection horizon. CAGRs derived from deployment velocity curves and professional services intensity by solution tier, with EU AI Act compliance investment schedules and HIPAA enforcement trajectories as embedded analytics-specific forecast inputs.
Regulatory enforcement delays, ML engineering talent availability shocks, and hyperscale bundling strategy shifts are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about compliance timeline adherence and cloud migration velocity across healthcare and manufacturing verticals. A model refresh is warranted upon material change in EU AI Act high-risk system designation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe HR Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Digital Analytics Solutions Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Global Recommendation Engine Market
Analytics
Global Customer Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Multichannel Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
RAN Analytics and Monitoring Market
Analytics
France Contact Center Analytics Market
Analytics
Global Data Analysis Software Market
Analytics
US Predictive Analytics Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
Manufacturing Analytics Market