
 Global Industrial Automation and Control Systems Market | 2026-2036
Global Industrial Automation and Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Automation and Control Systems Market Intelligence
The shift towards automation-as-a-service (AaaS) and equipment leasing models is reconfiguring the competitive landscape by lowering upfront capital barriers for smaller manufacturers. Siemens AG leverages its extensive financing arm to offer integrated hardware and service packages. Rockwell Automation Inc. competes by focusing on scalable software platforms adaptable to these flexible procurement models. ABB Ltd. differentiates through its deep domain expertise in robotics and process automation for heavy industries.
Industrial automation and control systems integrate hardware and software to manage industrial processes without direct human command. These systems, from PLCs to complex DCS, use real-time protocols to ensure operational synchronicity and safety across a plant. While PLCs and HMIs constitute the high-volume core of the market, the integration of AI and IoT technologies is creating new value in predictive analytics. The manufacturing end-user segment drives volume, whereas specialized SCADA systems for the oil and gas sector command higher margins.
System safety and interoperability are governed by a matrix of standards, including IEC 61508 for functional safety and ISO/IEC 27001 for cybersecurity. In the European Union, compliance with CE marking and the Machinery Directive is mandatory. The US EPA influences system design in industries requiring environmental monitoring. Stakeholders must decide whether to pursue proprietary, closed-loop systems or adopt open-architecture platforms to maximize future integration.
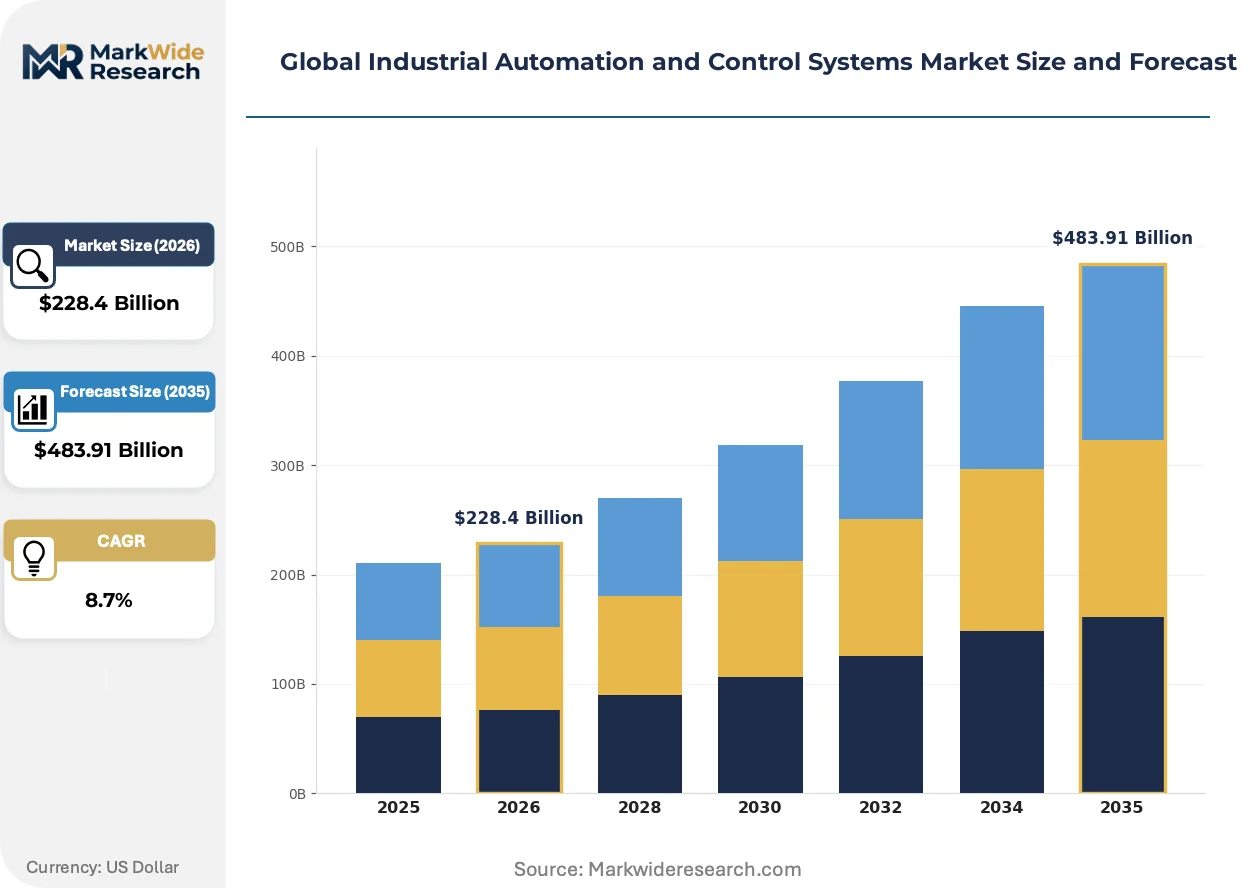
Market Dynamics
The central structural force is the pivot from large, one-time capital expenditures to flexible, operational expense models like Automation-as-a-Service. This shift lowers entry barriers and intensifies competition based on service integration and software scalability across the industrial landscape.
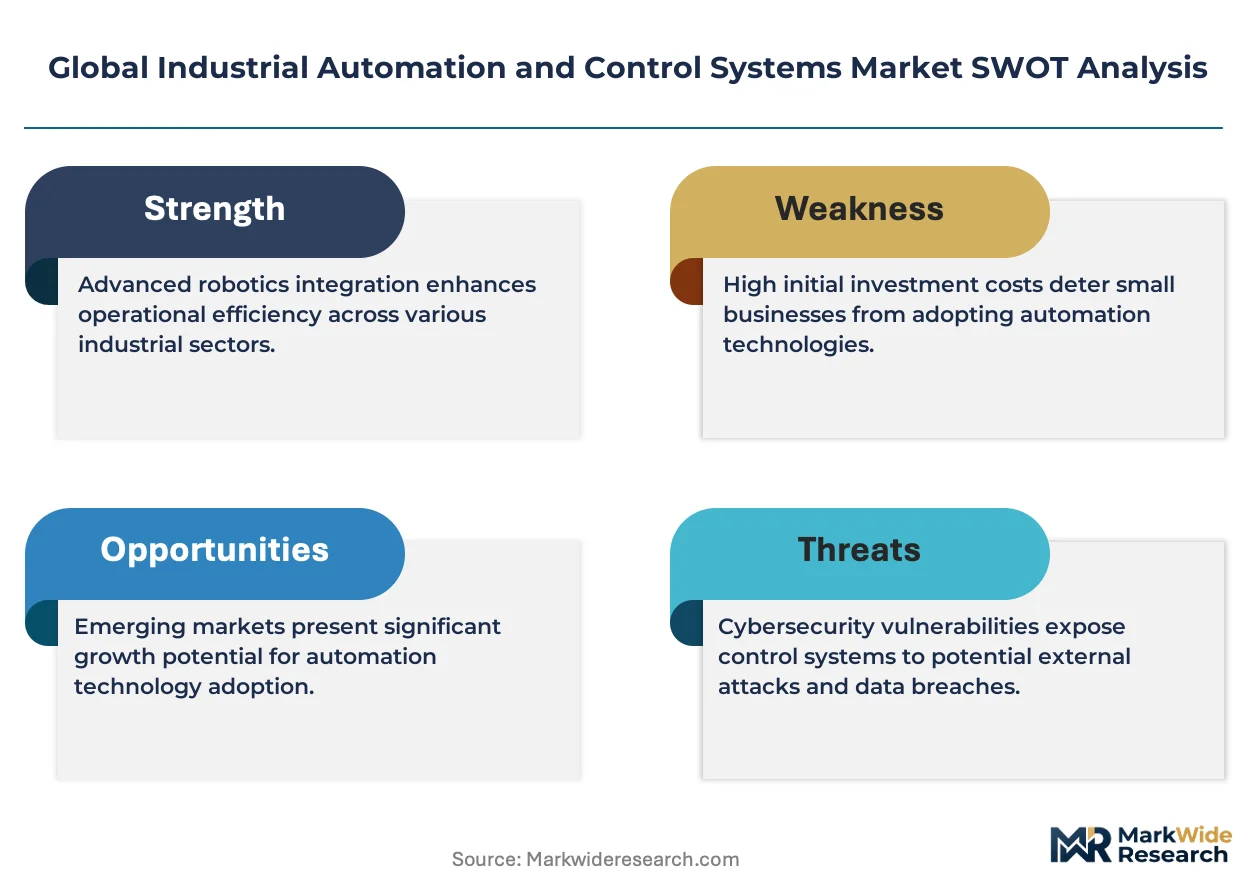
Growth Catalysts
- US Incentive Programs:The Inflation Reduction Act stimulates domestic manufacturing, boosting demand for automation systems in new US factories.
- AI-Driven Uptime:The integration of IoT and AI enables predictive maintenance, reducing downtime in the energy and process manufacturing sectors.
- Automotive Sector Demand:High-volume automotive manufacturing in Germany and China drives adoption of robotics and PLCs for higher throughput and quality.
Market Restraints
- High Capital Outlay:The significant upfront investment for comprehensive Distributed Control Systems (DCS) remains a barrier for smaller manufacturers.
- Proprietary System Friction:A lack of interoperability between vendor-specific platforms creates integration challenges and risks of technology lock-in.
- Complex Compliance Matrix:Adhering to diverse standards for functional safety (IEC 61508) and cybersecurity (ISO/IEC 27001) increases project costs.
Strategic Opportunities
- Service Model Expansion:Automation-as-a-Service (AaaS) models can be extended beyond manufacturing into logistics, agriculture, and building management sectors.
- Digital Twin Integration:Combining digital twin simulations with AI-driven controls creates opportunities for self-optimizing production lines and virtual commissioning.
- SME Market Penetration:Developing scalable, lower-cost automation packages targets underpenetrated small and medium-sized manufacturers in Southeast Asia.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers skilled in integrating modern IT with legacy operational technology (OT) slows project deployment.
- Legacy System Integration:Integrating modern IoT devices and AI platforms with aging, non-standardized industrial equipment is a significant technical and financial hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Automation and Control Systems Market |
| Market Size in 2026 | $228.4 Billion |
| Market Size in 2035 | $483.91 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLCs, SCADA, DCS, HMI Technology: IoT, AI, Cloud Computing, Robotics End User: Manufacturing, Oil & Gas, Chemicals, Food & Beverage Application: Process Automation, Factory Automation, Building Automation, Energy Management |
| Companies Covered | Siemens AG, ABB Ltd., Schneider Electric, Honeywell International Inc., Rockwell Automation Inc., Emerson Electric Co., Mitsubishi Electric Corporation, OMRON Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Automation and Control Systems Market Strategic Shifts & Innovations
The convergence of information technology (IT) and operational technology (OT) is the primary theme, transforming isolated factory hardware into interconnected, data-generating assets. This shift enables real-time optimization and new analytical capabilities across the industrial landscape.
Edge computing processes sensor data locally on the factory floor, significantly reducing latency compared to cloud-only architectures. Discrete manufacturing and logistics sectors are adopting edge devices for real-time quality control and asset tracking. This shift toward localized intelligence is rendering obsolete the traditional, centralized control models that rely on distant data centers.
Forthcoming regulations like the EU AI Act classify certain industrial automation applications as high-risk, imposing strict rules on data governance and transparency. This affects AI algorithms used in safety-critical manufacturing and process control. System integrators serving Europe are now embedding compliance-by-design principles into their AI-driven analytics platforms.
A preference for open-architecture platforms over proprietary systems is altering purchasing decisions to avoid vendor lock-in. This change disrupts the sales models of vendors reliant on tightly integrated hardware and software ecosystems. This demand for interoperability is most visible in the automotive and electronics sectors in Germany and China.
Global Industrial Automation and Control Systems Market Segmentation
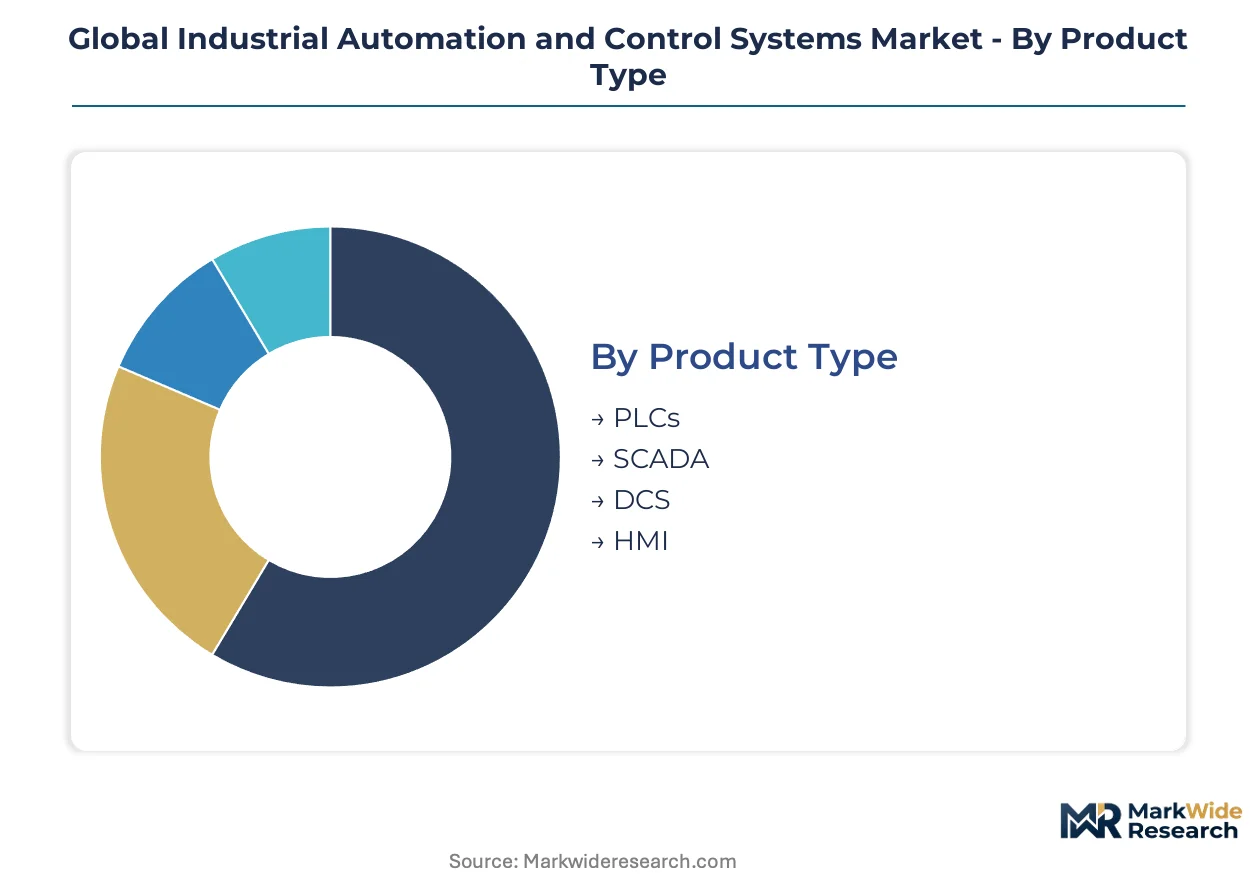
The industrial automation and control systems market exhibits diverse segmentation, reflecting varied operational needs and technological adoption across industries. Understanding these distinct segments is crucial for manufacturers to tailor solutions effectively and for stakeholders to identify areas of concentrated demand. Each segment presents unique growth trajectories and competitive dynamics.
Product Type:
The product type segment showcases a blend of mature control components alongside evolving interface technologies. Programmable Logic Controllers (PLCs) represent a foundational, established technology, while Human-Machine Interfaces (HMIs) continue to adapt to new user experience demands.
- PLCs:Programmable Logic Controllers are robust industrial computers that automate electromechanical processes, providing sequential control and operational logic. Demand for PLCs concentrates heavily within high-volume automotive manufacturing facilities in Germany and China, driving precise and repeatable assembly line operations.
- SCADA:Supervisory Control and Data Acquisition systems manage and monitor industrial processes across vast geographical areas, integrating data from various field devices. The oil and gas sector relies on SCADA for critical infrastructure oversight, commanding higher margins due to complex data integration and safety requirements.
- DCS:Distributed Control Systems offer centralized control over complex processes, distributing control elements throughout a plant.
- HMI:Human-Machine Interfaces provide graphical user interfaces for operators to interact with and monitor industrial equipment.
PLCs retain volume leadership; SCADA holds the steepest expansion curve.
Technology:
Technological integration within industrial automation is primarily driven by the need for enhanced data processing and operational efficiency across various applications. Advanced technologies are transforming how industrial processes are monitored, controlled, and optimized.
- AI:Artificial Intelligence algorithms are integrated into control systems to enable predictive maintenance, anomaly detection, and self-optimization of production processes. The energy and process manufacturing sectors increasingly deploy AI for reducing downtime and improving resource utilization.
- Robotics:Industrial robots perform repetitive tasks with high precision and speed, enhancing productivity and safety in manufacturing environments. Automotive manufacturing, particularly in the United States, drives significant robotics adoption for assembly, welding, and painting operations.
- IoT:The Internet of Things connects sensors and devices across industrial environments, facilitating real-time data collection and remote monitoring.
- Cloud Computing:Cloud platforms provide scalable infrastructure for data storage, processing, and advanced analytics for industrial applications.
AI solutions are rapidly gaining traction, while robotics continues to expand its footprint in automated production lines.
End User:
The end-user segment reflects the diverse industries adopting industrial automation, with adoption patterns influenced by production scale, regulatory compliance, and operational complexity. Each sector presents distinct requirements for control systems and automation solutions.
- Manufacturing:This segment encompasses discrete and process manufacturing, utilizing automation for production efficiency, quality control, and reduced labor costs. The automotive and electronics sectors in China and the United States represent significant demand centers for advanced automation systems.
- Oil & Gas:The oil and gas industry deploys specialized automation systems for exploration, extraction, refining, and distribution, emphasizing safety, remote monitoring, and asset integrity. SCADA and DCS systems are critical for managing geographically dispersed operations and ensuring environmental compliance.
- Chemicals:The chemicals sector relies on automation for precise process control, safety management, and batch processing in complex chemical reactions.
- Food & Beverage:Automation in food and beverage ensures hygiene, consistency, and traceability across production lines, from processing to packaging.
Manufacturing consistently drives the largest volume of automation system purchases, while the Oil & Gas sector demands highly specialized, high-value solutions.
Application:
The application segment delineates the primary functional areas where industrial automation and control systems are deployed, ranging from direct production management to broader facility optimization. Each application addresses specific operational challenges and efficiency goals.
- Process Automation:This application manages continuous or batch-oriented processes in industries like chemicals, oil & gas, and pharmaceuticals, ensuring precise control over variables such as temperature and pressure. DCS systems are fundamental to maintaining stability and efficiency in these complex environments.
- Factory Automation:Factory automation focuses on discrete manufacturing operations, including assembly, material handling, and quality inspection, primarily using PLCs and robotics. The automotive sector in Germany extensively utilizes factory automation for high-speed, precision manufacturing.
- Building Automation:Building automation systems manage HVAC, lighting, security, and access control within commercial and industrial facilities.
- Energy Management:This application optimizes energy consumption across industrial operations, integrating control systems with utility grids and renewable sources.
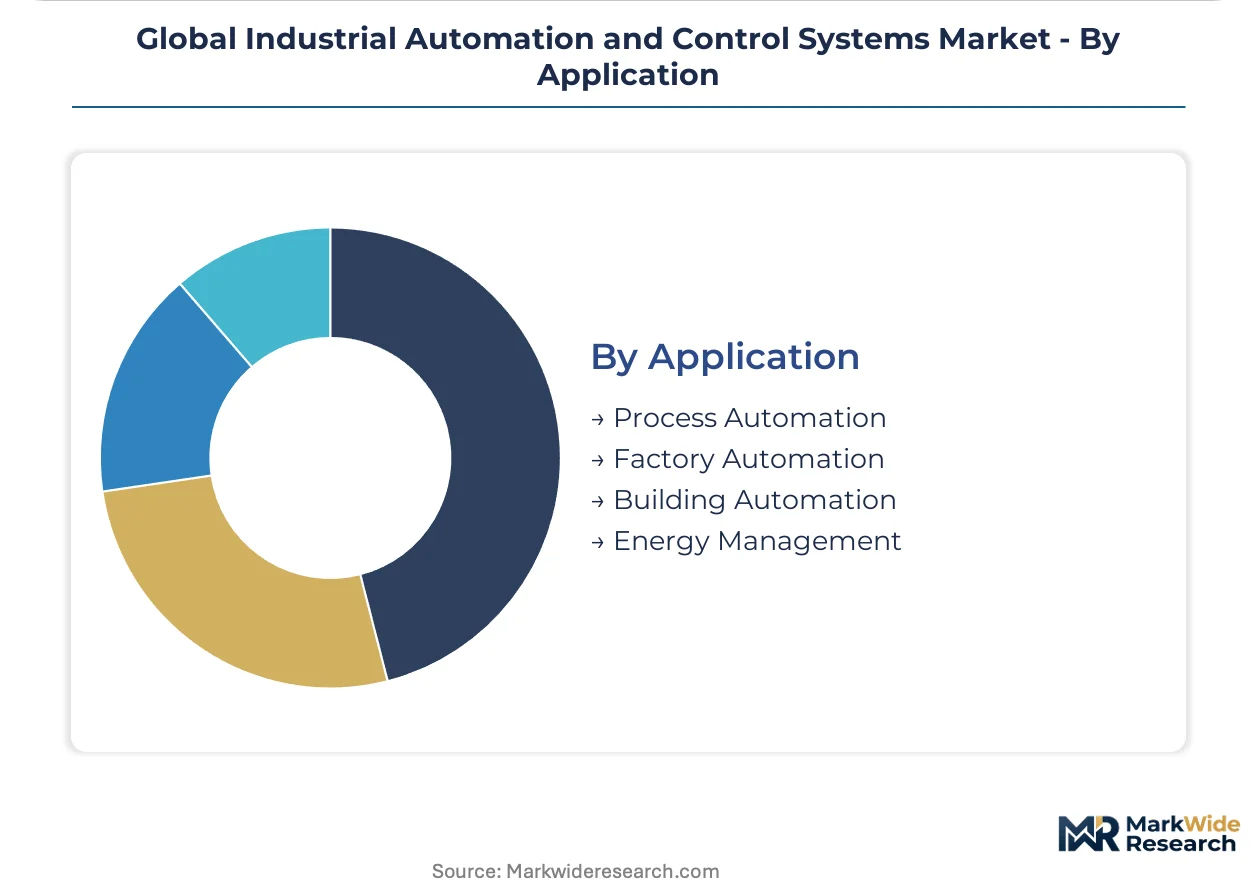
Factory Automation represents a significant expenditure area; Energy Management applications are poised for substantial growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global industrial automation market sees countries balancing domestic manufacturing capacity with the import of specialized control systems. This dynamic influences investment in advanced production technologies. Regional policies often shape these trade-offs.
United States
The United States experiences strong demand for automation systems from its automotive manufacturing sector and new factory constructions. The US Inflation Reduction Act incentivizes significant domestic production and advanced manufacturing investments. Industrial clusters in the Midwest, particularly around Michigan, leverage robotics and PLCs for higher throughput.
China
China's industrial automation demand is propelled by high-volume automotive and electronics manufacturing. Compliance with GB standards and dual carbon goals influences system design and energy efficiency requirements. Established industrial clusters in the Yangtze River Delta drive significant adoption of advanced control systems.
Germany
Germany's automotive sector and heavy industries drive substantial demand for sophisticated factory automation and robotics. Adherence to CE marking and the EU Machinery Directive ensures high safety and quality standards. Manufacturing hubs in Bavaria utilize advanced PLCs for precision production lines.
Japan
Japanese industries demand high-precision robotics and advanced control systems for their electronics and automotive production. METI policies encourage smart factory initiatives and digitalization across various sectors. The Kanto region, including Tokyo, remains a center for developing and deploying cutting-edge automation technologies.
India
India's growing manufacturing sector, particularly automotive and infrastructure projects, fuels demand for industrial automation. The PLI scheme stimulates domestic production and adoption of advanced technologies. Industrial zones in Maharashtra increasingly integrate IoT and AI for operational efficiency improvements.
Global Industrial Automation and Control Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential hardware and software modules. The market exhibits a tiered structure, with large conglomerates offering comprehensive solutions alongside specialized technology providers. Key archetypes include full-suite industrial automation providers, niche software developers, and robotics manufacturers. Strategic partnerships and technology licensing are dominant competitive moves, alongside continuous portfolio diversification.
Within the full-suite industrial automation provider archetype, Siemens AG and ABB Ltd. exemplify broad portfolio offerings spanning hardware, software, and services. Rockwell Automation Inc. occupies a strong position focusing on scalable software platforms and integrated control systems, adaptable to flexible procurement models. These entities anchor comprehensive solutions for diverse industrial end-users, from process manufacturing to discrete assembly lines. They often compete on service integration, ecosystem depth, and the ability to lower upfront capital barriers through flexible models like Automation-as-a-Service.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Schneider Electric |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| OMRON Corporation |
| Yokogawa Electric Corporation |
| Others |
Cost & Logistics Intelligence
High capacity utilization in automotive manufacturing hubs, like those in Germany and China, directly influences supplier pricing power for PLCs and robotics. This utilization also dictates investment in new production lines and component availability.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing for complex integrated systems, while per-unit transactional models dominate high-volume components. Price differentiation stems from software scalability and functional safety certifications like IEC 61508. Pricing pressure stems from the shift towards Automation-as-a-Service (AaaS) models, intensifying competition among vendors. Small and medium-sized manufacturers are highly price-sensitive, whereas large enterprises prioritize long-term total cost of ownership.
Supply Chain Analysis
Key contract manufacturers in China and Taiwan hold significant capacity for essential electronic components and microcontrollers used in industrial automation systems. The supply chain relies heavily on semiconductors, specialized sensors, and certain rare earth elements for advanced robotics. Single-source vulnerability for advanced microprocessors creates a significant disruption risk. Distribution typically runs through direct sales channels for complex integrated systems and a network of specialized distributors for standard components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial automation market represents a defensive-moat story, primarily due to high switching costs associated with integrating complex operational technology into existing infrastructure.
For Market Incumbents: Insulate core offerings by investing heavily in cybersecurity standards (ISO/IEC 27001) and functional safety (IEC 61508) certifications across all product lines. This defends against emerging software-only entrants and regulatory scrutiny. Deepen vertical integration into specialized sensor manufacturing to control critical component supply.
For New Entrants and Emerging Players: Southeast Asia's manufacturing sector exhibits significant underpenetration for advanced automation, presenting a clear white-space target for scalable, lower-cost solutions. Focus on developing modular, open-architecture platforms tailored for smaller manufacturers. A direct-to-consumer digital sales model can bypass established distribution channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Automation-as-a-Service providers and software platform specialists, offering predictable long-term cash flows. Target mid-cap software companies with strong intellectual property in AI-driven predictive maintenance or digital twin integration. The signal to watch is the customer churn rate for AaaS contracts, indicating market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Automation-as-a-Service (AaaS) Offerings | Lowers upfront capital barriers for smaller manufacturers, intensifying competition based on service integration. |
| Invest in AI-Driven Predictive Maintenance | Reduces downtime in energy and process manufacturing sectors, enhancing operational efficiency. |
| Develop Open-Architecture Control Platforms | Addresses demand for interoperability in automotive and electronics sectors, avoiding vendor lock-in. |
| Acquire Specialized Robotics Firms | Enhances capabilities in high-volume automotive manufacturing, driving higher throughput and quality. |
| Pursue IEC 61508 Functional Safety Certification | Ensures system safety and compliance with mandatory European Union regulations for critical applications. |
Research Approach
The analysis maps discrete manufacturing, process automation, and energy management sub-sectors, each validated through industry executives. Primary interviews with plant managers, automation engineers, procurement officers, and CTOs informed qualitative insights. Secondary validation utilized industry association reports, government economic surveys, SEC filings, and technical journals, with bottom-up market sizing and top-down validation.
Assumptions regarding macroeconomic stability and regulatory frameworks were held fixed, while technological adoption rates varied by segment. The analytical framework integrated supply-side capabilities with demand-side adoption patterns across the modeling period. Segmentation dimensions modeled included product type, technology, end-user, application, and regional economic growth. CAGRs were derived from historical growth trends and projected technological advancements, using industrial production indices and capital expenditure trends as key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major industrial conglomerates or disruptive software firms would shift outcomes. Geopolitical trade tensions or rapid shifts in raw material costs represent specific risk factors. Quarterly review of industrial production volumes and technology investment indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Automatic Screw Feeding System Market