
 Smart Sorting Machine Market | 2026-2036
Smart Sorting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sorting Machine Market Insights
Asian sensor module production is realigning toward higher-resolution imaging arrays for waste and food applications. TOMRA Systems ASA leverages its Nordic R&D base to sustain technology leadership in near-infrared detection. Bühler AG anchors global food-sorting deployments through integrated process lines. Steinert GmbH competes on magnetic and sensor-based separation for metal recovery streams.
Smart sorting machines integrate multi-spectral cameras, electromagnetic sensors, and pneumatic ejection mechanisms to classify materials by physical or chemical properties at throughput rates exceeding multiple tons per hour. Machine vision systems paired with deep learning algorithms now enable real-time defect detection below millimeter scale in food and pharmaceutical processing. Optical sorters occupy the largest installed base across recycling and food sectors, while artificial intelligence and sensor fusion segments capture expanding margin pools as retrofit demand rises. Robotics applications in postal and logistics sortation represent the fastest-growing deployment category, driven by e-commerce volume expansion and labor availability constraints.
FDA food safety modernization rules and EU machinery directives shape equipment certification requirements for cross-border sales. China's GB standards and MEE circular economy mandates enforce domestic recycling technology upgrades. Stakeholders must monitor evolving AI liability frameworks and energy-efficiency regulations as jurisdictions draft machine-specific compliance obligations.
Market Dynamics
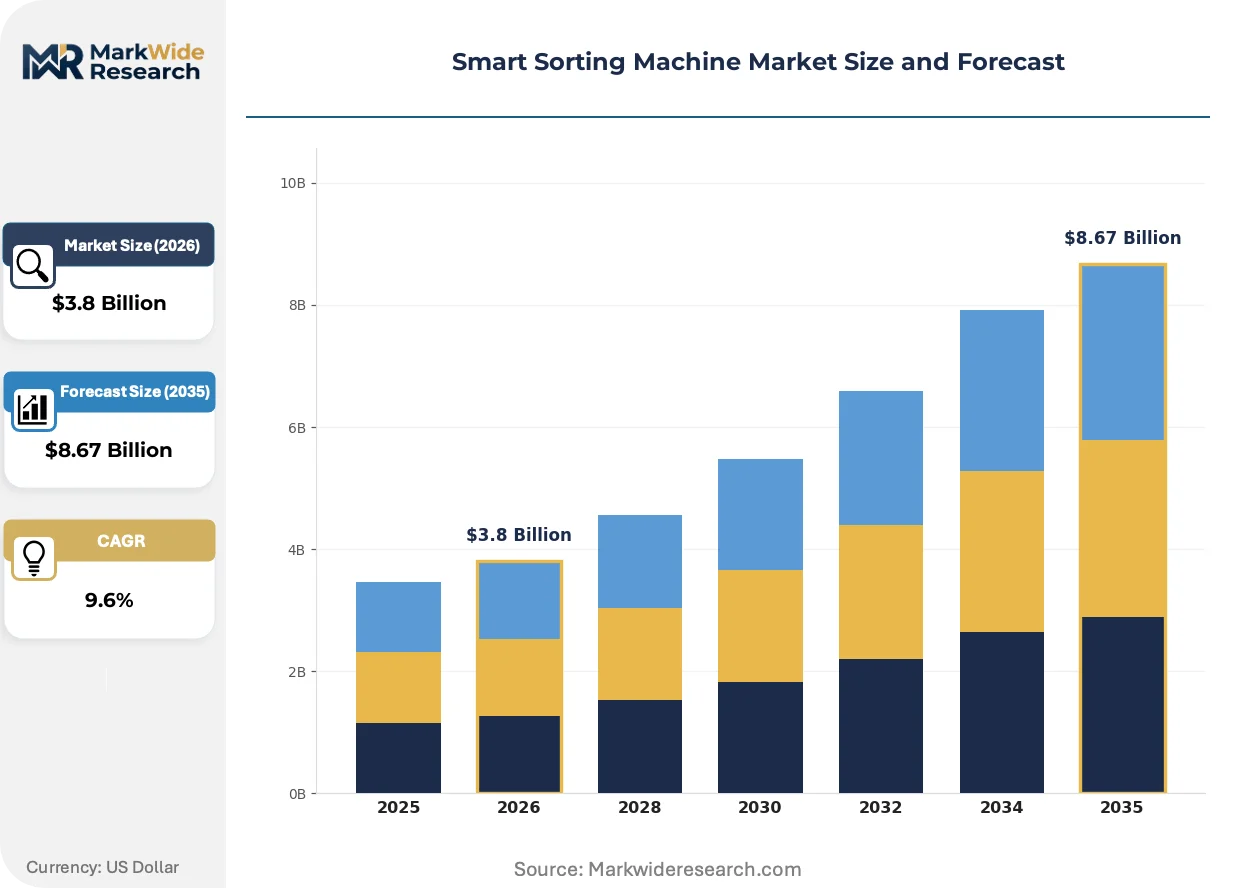
AI-enabled optical sorting is compressing equipment replacement cycles as food processors in Germany and Japan face simultaneous labor cost escalation and tightening EU food safety standards. The technology shift from rule-based to deep-learning vision systems is forcing capital redeployment across recycling and food processing verticals.
Growth Catalysts
- EU Food Safety Modernization:The EU machinery directive and EFSA contamination thresholds are compelling German meat and dairy processors to retrofit legacy color sorters with hyperspectral imaging arrays.
- Electronics Recycling Mandates:China's MEE circular economy enforcement is accelerating capital expenditure on sensor-based separation lines in Guangdong and Jiangsu dismantling clusters.
- Near-Infrared Spectroscopy:Advances in InGaAs detector sensitivity are extending sortable material categories to black plastics and complex polymer laminates previously rejected to landfill streams.
Market Restraints
- Sensor Module Supply Concentration:High-resolution CMOS and InGaAs array production concentrates in Japanese and South Korean fabs, exposing equipment OEMs to single-source vulnerability.
- Capital Intensity Barrier:Integrated AI-sorting lines for food processing demand seven-figure euro investments, excluding mid-tier cooperatives and regional processors from technology access.
- Technical Sorting Limitation:Current pneumatic ejection mechanisms struggle with wet, sticky, or irregularly shaped organic materials, constraining deployment in fresh produce washing operations.
Strategic Opportunities
- Pharmaceutical Optical Inspection:FDA validation protocols for AI-driven tablet and capsule sorting remain underdeveloped, creating first-mover advantage for vision system vendors with cGMP documentation capabilities.
- Post-Consumer Textile Recovery:The EU Green Deal's extended producer responsibility for apparel waste is generating demand for automated fiber identification and color sorting in Belgian and Dutch recycling hubs.
- Edge Computing Convergence:Onboard GPU acceleration is enabling millisecond-latency defect classification without cloud dependency, opening retrofit markets for facilities with limited connectivity infrastructure.
Industry Challenges
- Machine Vision Engineering Talent:The shortage of specialists capable of training convolutional neural networks on sparse, high-variance agricultural defect datasets is elongating commissioning timelines.
- Legacy Line Integration:Retrofitting AI sorters into 1990s-era food processing layouts requires custom mechanical interfaces and control system bridging, inflating project risk.
- Cross-Border Certification Burden:Equipment vendors must simultaneously satisfy FDA food contact rules, CE machinery directives, and China's GB standards, fragmenting product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sorting Machine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sorters, Magnetic Sorters, X-ray Sorters, Air Jet Sorters, Vibratory Sorters Technology: Machine Vision, Artificial Intelligence, Robotics, Sensor Fusion, Deep Learning Application: Recycling Facilities, Food Processing, Pharmaceutical Processing, Postal & Logistics, Mining Operations End User: Waste Management Firms, Food Manufacturers, Drug Manufacturers, Courier Services, Mineral Processors |
| Companies Covered | TOMRA Systems ASA, Bühler AG, Steinert GmbH, Sesotec GmbH, ZenRobotics Ltd., Key Technology LLC, Pellenc ST, REDWAVE, MSS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sorting Machine Market Trends and Innovations
Deep-learning vision architectures are compressing the performance gap between premium and mid-tier sorting equipment, eroding traditional technology tiering. Three developments are restructuring competitive dynamics and buyer value capture.
Hyperspectral imaging is decentralizing quality control authority from centralized laboratory testing to inline production decision-making. Fresh produce packers in California's Central Valley are deploying portable push-broom scanners for real-time sugar content and bruise detection. The technology is decentralizing sorting economics by enabling smaller facilities to achieve grading precision previously exclusive to large-scale operations with captive analytical laboratories.
The EU AI Act's risk classification framework for automated decision systems is mandating explainability documentation for food safety-critical sorting algorithms. Equipment vendors must now provide model training data provenance and bias audit trails to secure CE marking for high-risk applications. German optical sorter manufacturers are responding by establishing dedicated algorithm governance functions and third-party validation partnerships.
Leasing and performance-based contracting are displacing outright equipment purchase in North American recycling operations facing feedstock volatility. MRF operators in Texas and Arizona are negotiating throughput-guarantee arrangements where vendors retain ownership and bear commodity price exposure. The model is concentrating most visibly in municipal waste contracts where budget constraints and political risk aversion favor operational expenditure treatment.
Smart Sorting Machine Market Segmentation
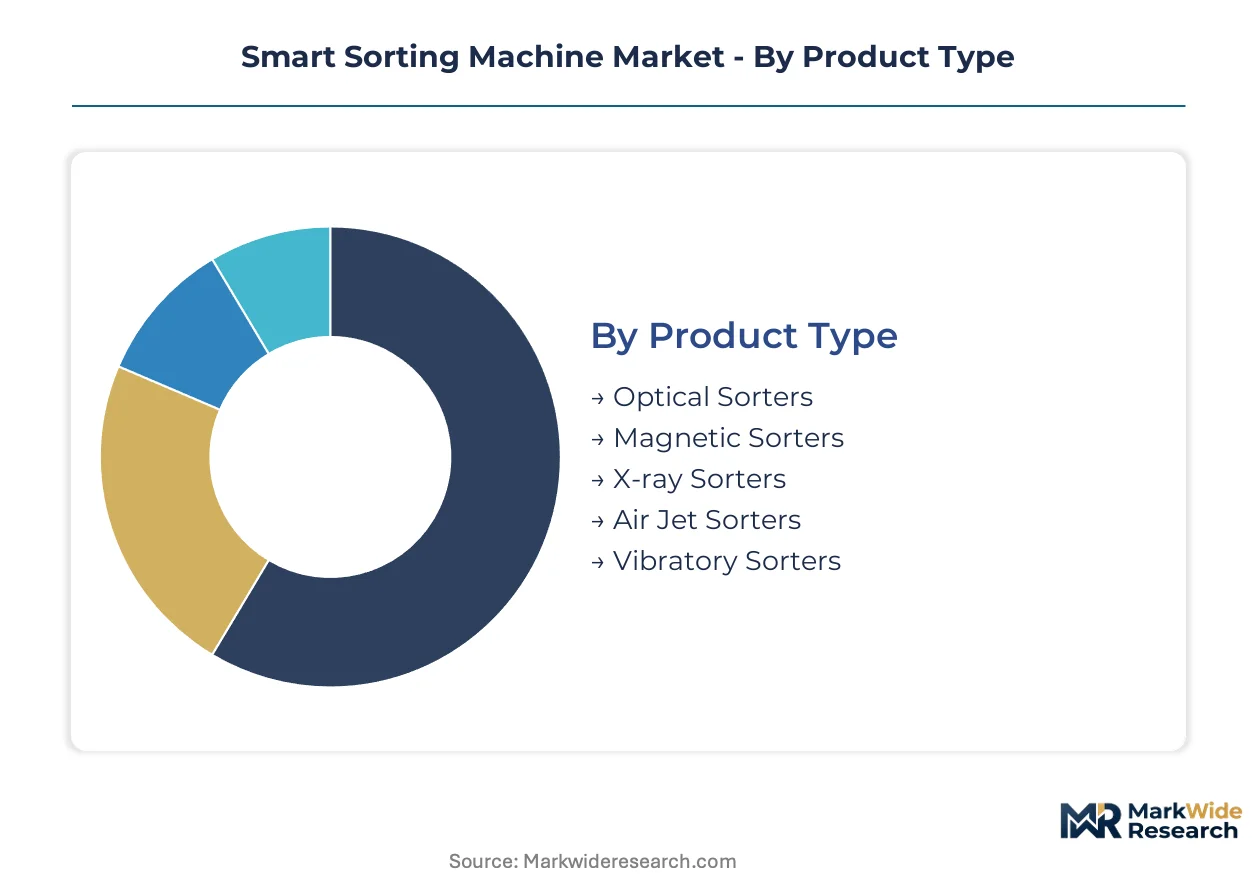
Smart sorting machine procurement follows distinct technical and regulatory pathways across end-use verticals. Equipment specification varies sharply between food-grade FDA validation requirements and the durability demands of mining environments.
Product Type:
Optical sorters face the heaviest certification burden, requiring CE machinery directives for EU food contact plus FDA food safety validation for US pharmaceutical applications. Magnetic and vibratory equipment navigate simpler electromagnetic compliance frameworks.
- Optical Sorters:Multi-spectral camera arrays paired with pneumatic ejection mechanisms classify materials by color, shape, and chemical signature at throughput rates exceeding five tons per hour. German meat processors and Japanese electronics recyclers are retrofitting legacy units with AI-enabled hyperspectral imaging to meet tightening EU food safety standards and China's MEE circular economy mandates.
- Magnetic Sorters:Eddy current and rare-earth drum configurations recover ferrous and non-ferrous metal fractions from shredded electronic waste and construction debris. Guangdong dismantling clusters are expanding sensor-based magnetic separation lines under enforcement pressure from China's Ministry of Ecology and Environment.
- X-ray Sorters:Dual-energy transmission systems detect density variations in mineral streams and foreign contaminants in packaged food.
- Air Jet Sorters:Pneumatic precision targeting removes lightweight defects from grain and seed processing lines.
- Vibratory Sorters:Mechanical screening with amplitude modulation handles coarse pre-sorting in quarry and aggregate operations.
Optical sorters sit at the top of the volume ranking, with X-ray sorters climbing the fastest as mining operators automate ore grade control.
Technology:
Technology selection maps directly to margin capture potential, with AI and deep learning commanding premium pricing against rule-based machine vision installations.
- Machine Vision:Rule-based camera systems with fixed algorithmic thresholds for color and dimensional sorting remain the installed base majority. Mid-tier food cooperatives in Spain and Italy continue specifying these units where capital constraints exclude AI retrofits.
- Artificial Intelligence:Neural network architectures trained on agricultural defect datasets enable real-time classification below millimeter scale. California Central Valley produce packers are deploying portable push-broom scanners for inline sugar content and bruise detection, decentralizing quality control from captive laboratories.
- Robotics:Articulated arm configurations with vacuum or gripper end-effectors handle irregular parcel geometries in e-commerce fulfillment.
- Sensor Fusion:Combined electromagnetic, optical, and spectroscopic inputs resolve ambiguous material signatures.
- Deep Learning:Convolutional neural networks with onboard GPU acceleration achieve millisecond-latency defect classification without cloud dependency.
Machine vision retains the largest installed footprint, though deep learning is gaining share fastest as edge computing hardware costs decline.
Application:
Application segmentation reflects divergent throughput requirements and contamination tolerance thresholds across verticals.
- Recycling Facilities:Municipal and commercial material recovery operations deploy multi-stage optical and magnetic separation to meet purity specifications for resale commodity bales. Texas and Arizona MRF operators are negotiating throughput-guarantee leasing arrangements where vendors retain ownership and bear commodity price exposure.
- Food Processing:Meat, dairy, and fresh produce operations require FDA-validated optical inspection with documented algorithm training provenance under emerging EU AI Act risk classification frameworks. German optical sorter manufacturers are establishing dedicated algorithm governance functions to secure CE marking for high-risk applications.
- Pharmaceutical Processing:cGMP-compliant tablet and capsule inspection demands validated defect detection at sub-millimeter resolution.
- Postal & Logistics:High-speed parcel sortation with dimensional weighing and destination encoding handles e-commerce volume expansion.
- Mining Operations:Bulk ore sorting by grade and mineralogy reduces downstream processing energy intensity.
Recycling facilities command the highest unit volume, with pharmaceutical processing expanding most quickly as FDA validation protocols mature for AI-driven inspection.
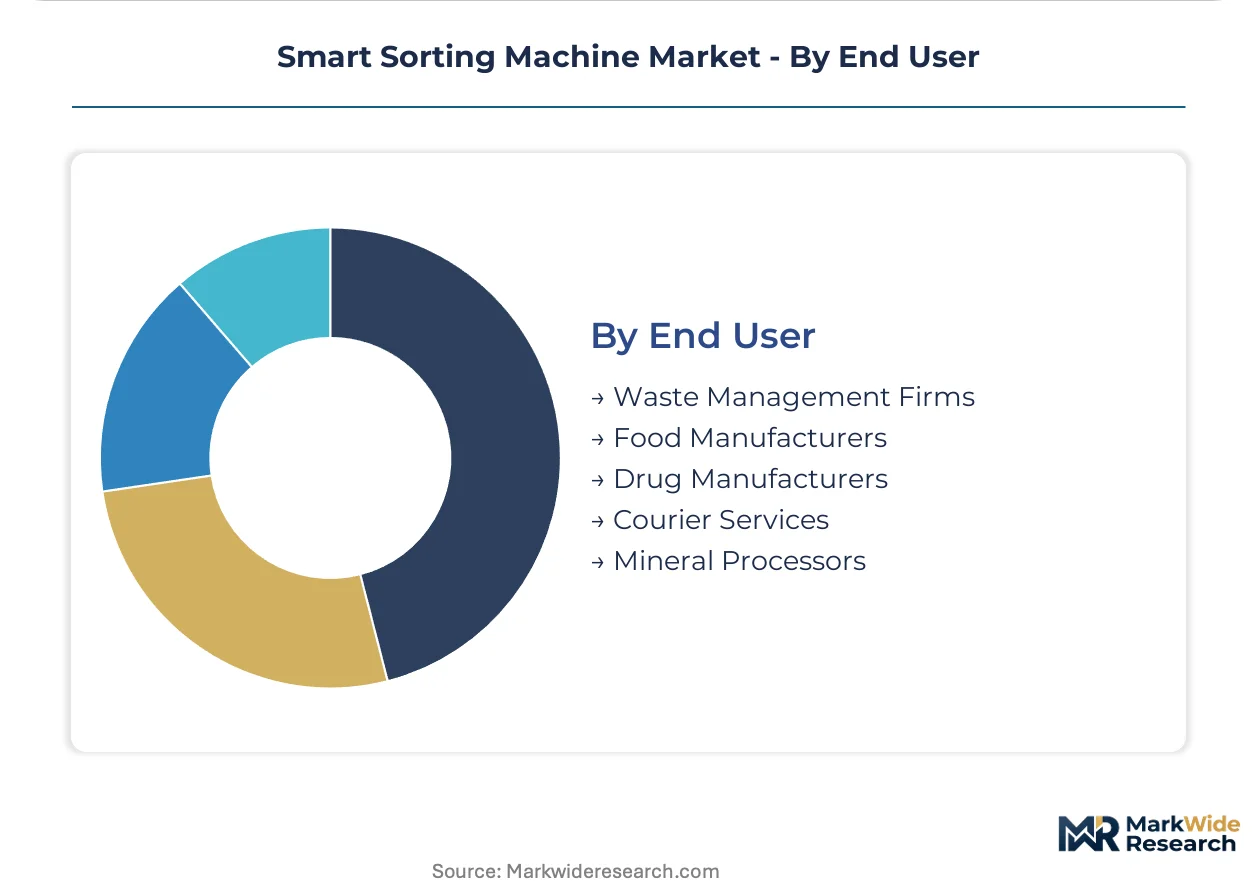
End User:
End user procurement authority concentrates in distinct organizational structures, from municipal waste authorities to integrated mining conglomerates.
- Waste Management Firms:Private and municipal operators face feedstock volatility and political risk aversion that favors operational expenditure treatment over capital purchase. Performance-based contracting with throughput guarantees is displacing outright equipment acquisition in North American markets.
- Food Manufacturers:Integrated processors and regional cooperatives drive divergent specification requirements, with seven-figure euro investments for AI-sorting lines excluding mid-tier players from technology access.
- Drug Manufacturers:cGMP documentation capabilities create vendor selection criteria distinct from food and recycling verticals.
- Courier Services:Express delivery networks automate hub sortation to address labor availability constraints.
- Mineral Processors:Copper and gold operations deploy bulk ore sorters to reduce grinding circuit energy consumption.
Waste management firms represent the largest procurement volume, with drug manufacturers showing the steepest expansion trajectory as optical inspection validation frameworks develop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement as compliance cost differentials push investment toward jurisdictions with enforceable standards but moderate certification burdens. Manufacturers migrate assembly capacity to capture these gaps while serving concentrated demand clusters.
Germany
German meat and dairy processors face simultaneous labor cost escalation and EU machinery directive enforcement. EFSA contamination thresholds compel retrofit of legacy color sorters with hyperspectral imaging arrays. Bavarian food processing clusters anchor European demand for validated optical inspection systems.
China
Guangdong and Jiangsu electronics dismantling clusters drive sensor-based separation line expansion under MEE circular economy mandates. Black plastics and complex polymer laminates previously rejected to landfill now enter sortable categories through InGaAs detector advances. Domestic OEMs compete with Nordic and Swiss suppliers for retrofit contracts.
United States
California Central Valley produce packers deploy portable push-broom scanners for inline sugar content and bruise detection. FDA food safety modernization rules shape equipment certification for cross-border pharmaceutical applications. Texas and Arizona MRF operators negotiate throughput-guarantee leasing arrangements with retained vendor ownership.
Japan
Japanese electronics recyclers accelerate AI-enabled optical sorter procurement as labor availability tightens. METI industrial efficiency programs subsidize sensor fusion upgrades in Kansai dismantling facilities. High-resolution CMOS and InGaAs array fabrication concentrates in domestic fabs, exposing equipment OEMs to single-source supply vulnerability.
Belgium
EU Green Deal extended producer responsibility for apparel waste generates demand for automated fiber identification in Belgian and Dutch recycling hubs. Post-consumer textile recovery operations require color sorting precision previously exclusive to food-grade applications. Antwerp logistics corridors integrate robotics for high-volume parcel sortation.
Smart Sorting Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native architectures and service-based revenue models. The vendor base stratifies across three tiers: integrated process line suppliers, specialized detection technology developers, and robotics-first automation specialists. Consolidation pressure concentrates among mid-tier sensor module integrators facing R&D scale disadvantages. Dominant competitive moves include geographic expansion into East Asian manufacturing clusters and strategic partnerships for algorithm training data access.
Within the Nordic detection technology tier, TOMRA Systems ASA leverages its Norwegian R&D base to sustain near-infrared spectroscopy leadership. Bühler AG, the Swiss integrated process line supplier, anchors global food-sorting deployments through captive analytical laboratory relationships. Steinert GmbH exemplifies the magnetic and sensor-based separation archetype for metal recovery streams. These three occupy distinct competitive positions without direct product overlap, reducing price-based rivalry.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| Bühler AG |
| Steinert GmbH |
| Sesotec GmbH |
| ZenRobotics Ltd. |
| Key Technology LLC |
| Pellenc ST |
| REDWAVE |
| MSS, Inc. |
| Others |
Pricing and Supply Chain Analysis
German meat and dairy processors concentrate procurement authority for AI-enabled optical sorters, driving contract structures toward performance-guarantee leasing with retained vendor ownership rather than capital purchase. Equipment vendors respond with tiered service bundling that separates hyperspectral validation tiers from baseline color-sorting configurations.
Pricing Analysis
Distributor margins on optical sorter modules compress as direct-to-OEM channels capture hyperscale food processor demand in Germany and Japan. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical inspection systems from CE-marked food-grade units and unvalidated recycling configurations. Cost compression in mid-tier sensor modules intensifies because Japanese and South Korean CMOS fabs face capacity allocation pressure. Regional cooperatives in Spain and Italy exhibit highest price sensitivity, while integrated German processors accept premium positioning for algorithm audit-trail documentation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for AI-enabled sorting lines, bypassing distribution layers for integrated process line suppliers. High-resolution InGaAs detector fabrication concentrates in Japan and South Korea, while electromagnetic sensor production anchors in Germany and Switzerland. Equipment assembly draws from Taiwanese PCB fabrication and Chinese pneumatic component sourcing. Single-source vulnerability in CMOS and InGaAs array supply exposes OEMs to allocation risk during semiconductor cycle tightness. Distribution runs through captive service networks for validation-heavy food and pharmaceutical verticals, with third-party logistics handling recycling equipment deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart sorting machine procurement is shifting toward premium specifications as EU AI Act explainability mandates and FDA validation protocols reshape buyer requirements. Equipment vendors must now bundle algorithm governance documentation with hardware sales to capture quality-tier pricing.
For Market Incumbents: Hedge against margin erosion in rule-based machine vision by accelerating backward integration into InGaAs detector supply. TOMRA Systems ASA and Bühler AG should expand Nordic and Swiss R&D capture of near-infrared spectroscopy talent before Asian fabs consolidate sensor module production. Certification investment in EU AI Act algorithm audit-trail capabilities defends positioning against emerging AI-native entrants.
For New Entrants and Emerging Players: Capture pharmaceutical optical inspection white space where FDA validation protocols remain underdeveloped and cGMP documentation capabilities create vendor selection moats. Belgian and Dutch post-consumer textile recovery operations offer penetrable retrofit demand under EU Green Deal extended producer responsibility enforcement. Edge computing convergence for millisecond-latency defect classification without cloud dependency provides go-to-market differentiation for facilities with limited connectivity infrastructure.
For Investors and Strategic Acquirers: Process automation conglomerates with captive food processing relationships are the most active acquirer in this space, seeking algorithm training data access and validation documentation capabilities. Target acquisition archetype: mid-tier sensor fusion specialists with pharmaceutical cGMP exposure and edge computing hardware integration. Watch MEE circular economy enforcement intensity in Guangdong and Jiangsu as inflection indicator for Chinese electronics recycling capital expenditure trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Governance Function Establishment | German optical sorter manufacturers secure CE marking under EU AI Act risk classification frameworks. |
| Performance-Based Contracting Expansion | Texas and Arizona MRF operators shift capital expenditure to operational expenditure treatment with throughput guarantees. |
| Edge Computing Hardware Integration | Onboard GPU acceleration enables retrofit markets for facilities with limited connectivity infrastructure in rural processing clusters. |
| Pharmaceutical Validation Partnership | Vision system vendors with cGMP documentation capabilities capture first-mover advantage in FDA tablet and capsule inspection. |
| Near-Infrared Spectroscopy R&D Expansion | TOMRA Systems ASA sustains technology leadership in black plastic and complex polymer laminate detection. |
Research Methodology
Bottom-up food processing and recycling facility modeling reconciled against top-down sensor module production tracking forms the analytical core of this study. Primary interviews with plant engineers at German meat and dairy processors, procurement leads at Guangdong electronics dismantling facilities, aftermarket service heads at Nordic OEMs, and regulatory affairs specialists navigating EU AI Act compliance were cross-validated against secondary sources including FDA 510(k) filings, EFSA contamination threshold documentation, MEE circular economy enforcement notices, and SEC 10-K equipment vendor disclosures. Triangulation between demand-side capital expenditure patterns and supply-side component allocation data ensures statistical integrity.
Input-output matrices map optical sorter, magnetic separator, and X-ray system shipments across technology tiers from rule-based machine vision through deep learning and sensor fusion configurations. Segmentation dimensions span product type, technology architecture, application vertical, and end-user procurement authority structure. CAGRs were derived from installed base replacement cycle compression analysis and retrofit demand elasticity modeling. Forecast inputs include labor cost escalation indices in Germany and Japan, MEE enforcement intensity scoring, and EU AI Act implementation timeline assumptions across the projection horizon.
Sensor module supply disruption, MEE enforcement variance, and EU AI Act liability interpretation divergence are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory implementation pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Factory Automation Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Smart Manufacturing Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Global Discrete Automation Market