
 Europe Intralogistics Automation Market | 2026-2036
Europe Intralogistics Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intralogistics Automation Market Foresight
Market Context
German conveyor system manufacturers is broadening output capacity to serve pan-European distribution networks. Vanderlande Industries BV leverages its Dutch engineering base to dominate airport and parcel sortation installations across the continent. SSI Schaefer AG anchors its position through deep specialization in modular warehouse software paired with automated hardware. KION Group AG sustains manufacturing scale through its German production footprint while extending service reach into Eastern European markets.
Technical Definition and Structural Segments
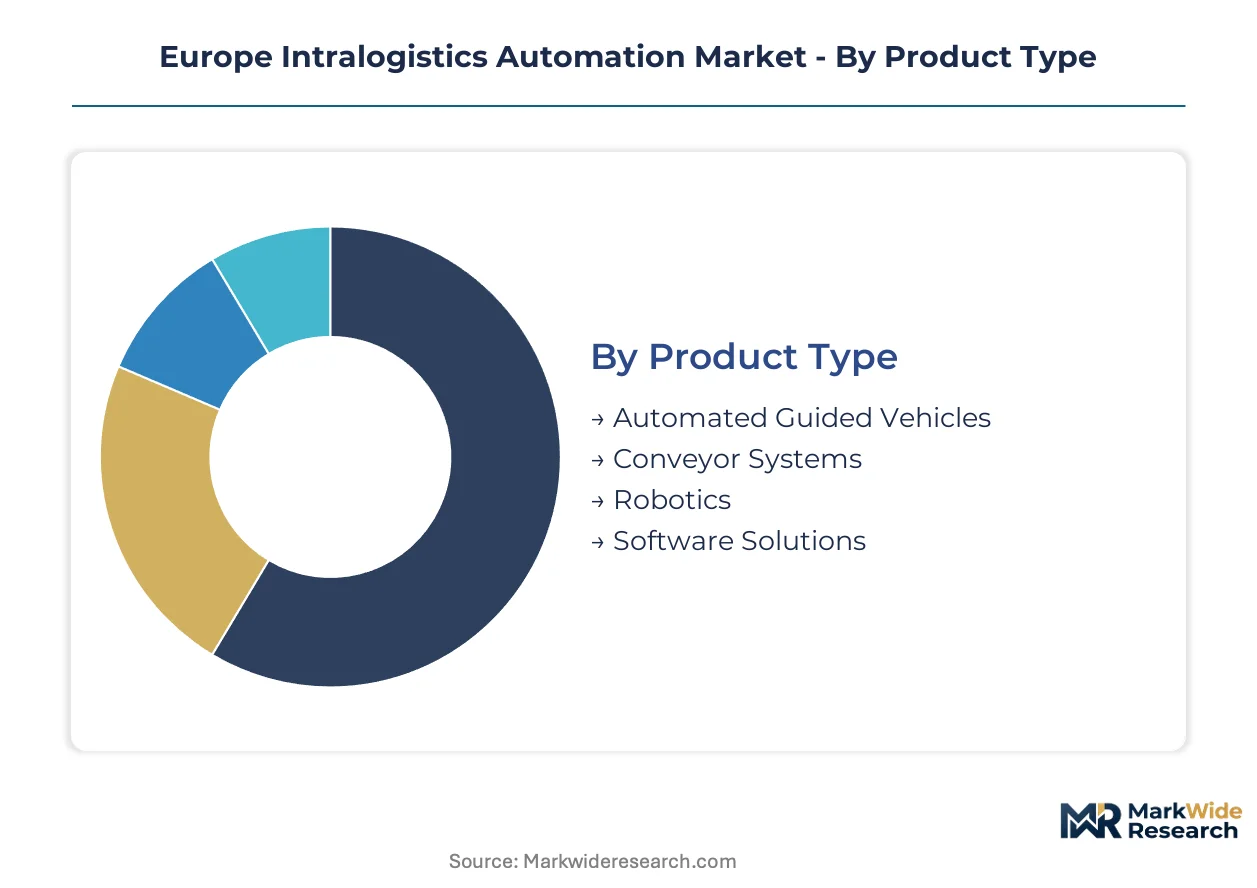
Intralogistics automation encompasses the mechanized and software-driven coordination of material handling, storage, retrieval, and sorting operations within facility boundaries, typically incorporating real-time control systems that manage throughput rates exceeding 10,000 units per hour in high-volume distribution environments. Its primary commercial purpose is to compress order cycle times and reduce labor dependency in environments where SKU proliferation and delivery velocity requirements strain manual operations. Automated Guided Vehicles and Robotics together capture the most visible expansion trajectory, as e-commerce fulfillment pressures force retailers to replace fixed conveyor footprints with flexible autonomous fleets. Software Solutions command disproportionate margin attention because warehouse execution systems and AI-driven slotting algorithms determine overall facility efficiency regardless of hardware configuration. Conveyor Systems remain the mature revenue base, particularly in food and beverage manufacturing where hygiene-rated belt specifications and washdown compatibility create sticky replacement demand.
Regulatory Framework and Outlook
The EU Machinery Directive harmonizes safety requirements across member states, compelling automation vendors to integrate force-limiting sensors and emergency stop architectures before CE marking release. REACH and RoHS frameworks restrict hazardous substance content in batteries and electronic components that power mobile robotics fleets. The EU AI Act introduces conformity obligations for automated decision systems that optimize picking sequences or predict maintenance intervals. Stakeholders must monitor how the CSRD's supply chain disclosure rules will force warehouse operators to document automation-related energy consumption and embodied carbon in capital equipment procurement decisions.
Market Dynamics
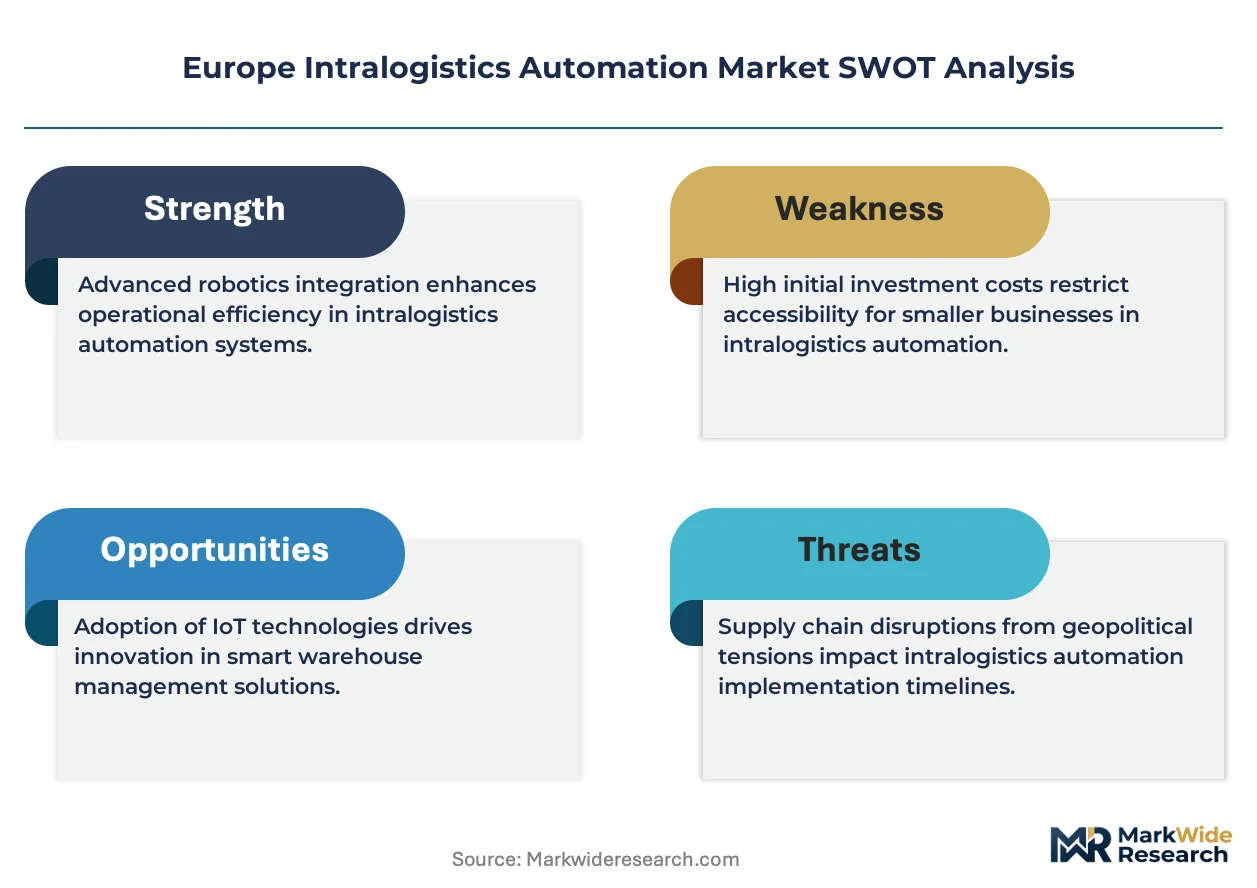
European warehouse operators face acute pressure from the EU Machinery Directive's 2023 amendments, which mandate force-limiting sensors and redundant safety architectures on all new autonomous deployments. This regulatory compression is accelerating capital replacement cycles while filtering out uncertified vendors.
Growth Catalysts
- CE Marking Acceleration:The EU Machinery Directive's harmonized safety standards eliminate country-by-country approval burdens, enabling faster cross-border deployment of automated systems.
- E-Commerce Fulfillment Density:Parcel volumes through Rotterdam and Hamburg distribution hubs strain manual sorting capacity, forcing retailers toward robotic put-wall and goods-to-person architectures.
- Pharmaceutical Cold Chain Expansion:Temperature-validated automated storage and retrieval systems address EU GDP guidelines for serialized drug distribution across the bloc.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production for mobile robotics fleets concentrates in Asian manufacturing bases, exposing European integrators to input cost volatility and extended lead times.
- Technical Ceiling on Mixed-SKU Handling:Polybagged apparel and irregular geometries exceed current robotic gripper dexterity, limiting automation penetration in fashion fulfillment.
- REACH Compliance Friction:Hazardous substance restrictions on electronic components extend vendor qualification timelines and raise non-recurring engineering costs for hardware redesigns.
Strategic Opportunities
- Polish Distribution Corridor:Under-automated third-party logistics facilities near Warsaw and Wrocław present first-mover advantages for modular goods-to-person system vendors.
- EU AI Act Convergence:Warehouse execution systems with embedded predictive maintenance algorithms qualify for streamlined conformity assessment, creating regulatory tailwinds for software-centric providers.
- Retrofit-First Positioning:Brownfield sites in Germany's Ruhr region require phased automation that preserves existing racking infrastructure, favoring vendors with modular AMR fleets over greenfield conveyor installations.
Industry Challenges
- Functional Safety Engineering Scarcity:Certified safety system designers with PLC programming and risk assessment expertise command premium compensation, constraining deployment velocity for mid-sized integrators.
- Legacy WMS Integration Complexity:Proprietary warehouse management systems at established German automotive parts distributors resist API standardization, forcing costly middleware development for automation overlay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intralogistics Automation Market |
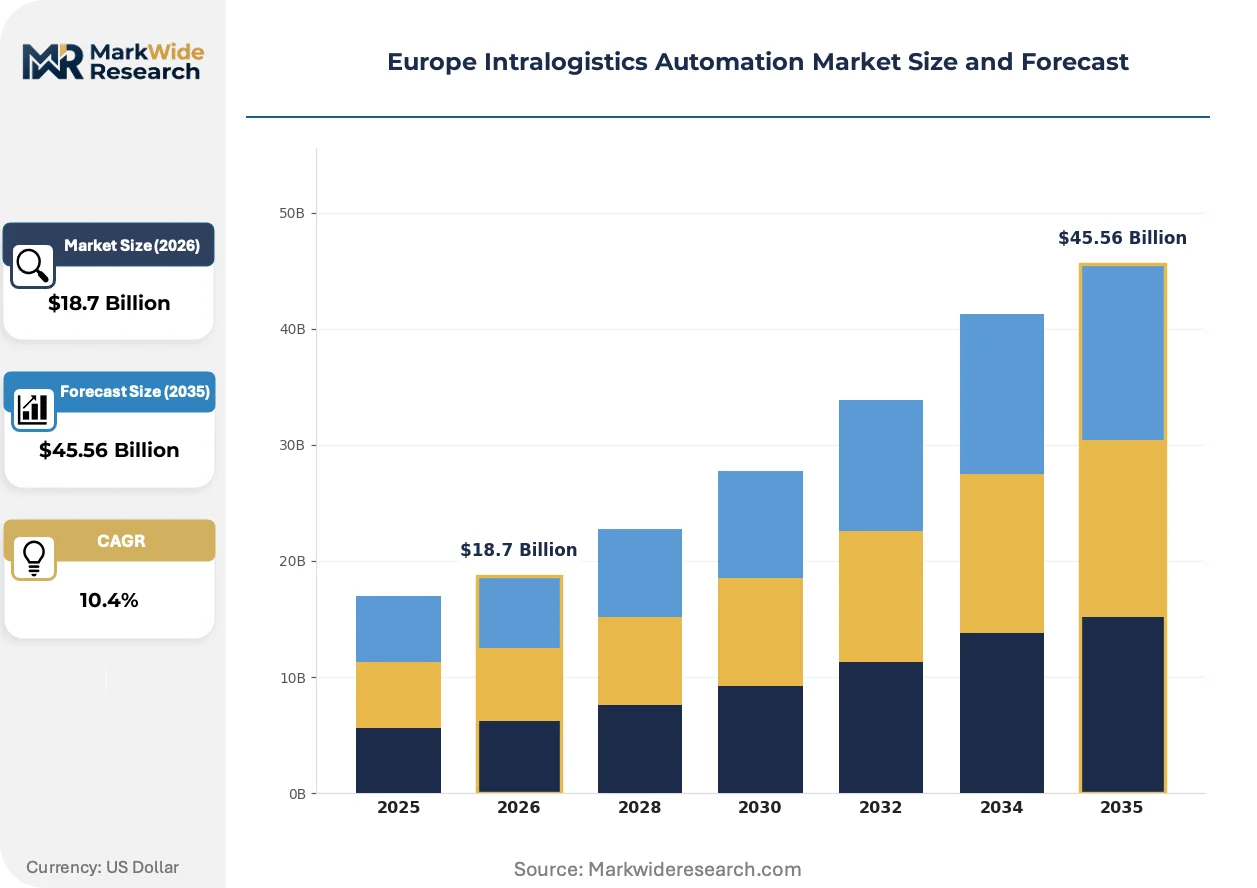
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $45.56 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Conveyor Systems, Robotics, Software Solutions End User: Retail, Manufacturing, Healthcare, E-commerce Technology: AI Integration, IoT Solutions, Cloud Computing, Big Data Analytics Installation: On-premises, Cloud-based, Hybrid Models, Outsourced |
| Companies Covered | Vanderlande Industries BV, Honeywell International Inc, Jungheinrich AG, SSI Schaefer AG, Interroll Holding AG, KION Group AG, Daifuku Co Ltd, KUKA AG, Viastore Systems GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intralogistics Automation Market Shifts & Advancements
Sensor fusion and edge computing architectures are compressing decision latencies in high-throughput environments. Three developments are restructuring competitive positioning and procurement patterns across European distribution networks.
Computer vision-guided robotic piece-picking is integrating depth-sensing arrays with machine learning models trained on European SKU databases. Pharmaceutical distributors in Switzerland and Belgium are piloting these systems for vial and blister-pack handling. The technology is integrating quality inspection directly into pick operations, eliminating separate verification stations and reducing order cycle times by consolidating process steps.
The EU AI Act's risk-based classification framework imposes documentation burdens on automated decision systems that optimize slotting or predict equipment failures. Warehouse operators must maintain technical files and human oversight protocols for high-risk AI deployments. German automotive parts hubs are responding by segregating AI-driven functions from safety-critical controls, creating dual-architecture system designs that limit algorithmic exposure.
Service contracting is unbundling hardware ownership from operational responsibility. Dutch e-commerce fulfillment centers now procure autonomous mobile robots through usage-based agreements where vendors retain asset ownership and performance risk. This model concentrates in Benelux markets with mature third-party logistics providers capable of absorbing outcome-based payment structures.
Europe Intralogistics Automation Market Segmentation
Intralogistics automation procurement patterns in Europe diverge sharply between high-volume commodity handling and precision-driven premium applications. Understanding these fault lines reveals where margin pools concentrate and which technology configurations command pricing power.
Product Type:
Volume-heavy hardware segments dominate revenue tonnage while software layers extract disproportionate margin.
- Automated Guided Vehicles:Battery-powered mobile platforms navigate via magnetic tape, laser guidance, or vision-based localization to transport pallets and totes through facility corridors. German automotive distribution hubs in Stuttgart and Wolfsburg are standardizing on laser-guided AGV fleets to replace forklift labor in 24-hour operations, driven by shift-work cost inflation and REACH compliance burdens on internal combustion equipment.
- Robotics:Articulated and collaborative arms execute piece-picking, palletizing, and depalletizing operations with force-limiting architectures mandated by EU Machinery Directive amendments. Dutch e-commerce fulfillment centers near Rotterdam are deploying computer vision-guided robotic put-walls to handle polybagged apparel, though gripper dexterity constraints still limit penetration in irregular-geometry SKUs.
- Conveyor Systems:Belt and roller configurations remain the installed base workhorse for high-throughput sortation in parcel and food processing environments.
- Software Solutions:Warehouse execution systems and AI-driven slotting algorithms determine facility efficiency regardless of underlying hardware configuration.
Today's leader: Conveyor Systems. Tomorrow's challenger: Robotics.
End User:
Application intensity varies by sector labor economics and regulatory compliance exposure.
- E-commerce:Order velocity pressures and SKU proliferation drive goods-to-person architectures and autonomous mobile robot deployments. Parcel volumes through Hamburg and Rotterdam distribution hubs strain manual capacity, forcing retailers toward robotic sortation and automated put-walls to compress cycle times.
- Manufacturing:Just-in-sequence material delivery to assembly lines requires synchronized AGV fleets and real-time inventory visibility. German automotive plants in Bavaria and Baden-Württemberg are retrofitting brownfield facilities with modular automation that preserves existing racking infrastructure.
- Retail:Store replenishment and omnichannel fulfillment operations balance throughput against footprint constraints in urban distribution centers.
- Healthcare:Temperature-validated automated storage and retrieval systems address EU GDP guidelines for serialized drug distribution across the bloc.
Manufacturing captures current deployment value. E-commerce is expanding most quickly.
Technology:
Intelligence layers are unbundling from hardware and migrating toward edge and cloud architectures.
- AI Integration:Machine learning models optimize picking sequences, predict equipment failures, and dynamically slot inventory based on velocity patterns. The EU AI Act imposes conformity obligations on high-risk automated decision systems, compelling German warehouse operators to maintain technical files and human oversight protocols.
- IoT Solutions:Sensor networks monitor equipment health, environmental conditions, and asset location in real time. Pharmaceutical cold chain operators in Belgium and Switzerland deploy temperature-validated IoT architectures to maintain GDP compliance across distribution networks.
- Cloud Computing:Scalable compute resources enable warehouse execution system deployment without on-premises infrastructure investment.
- Big Data Analytics:Historical throughput analysis informs capacity planning and labor scheduling optimization.
IoT Solutions anchor present-day connectivity investments. AI Integration is gaining share fastest.
Installation:
Deployment models reflect capital availability preferences and data sovereignty requirements.
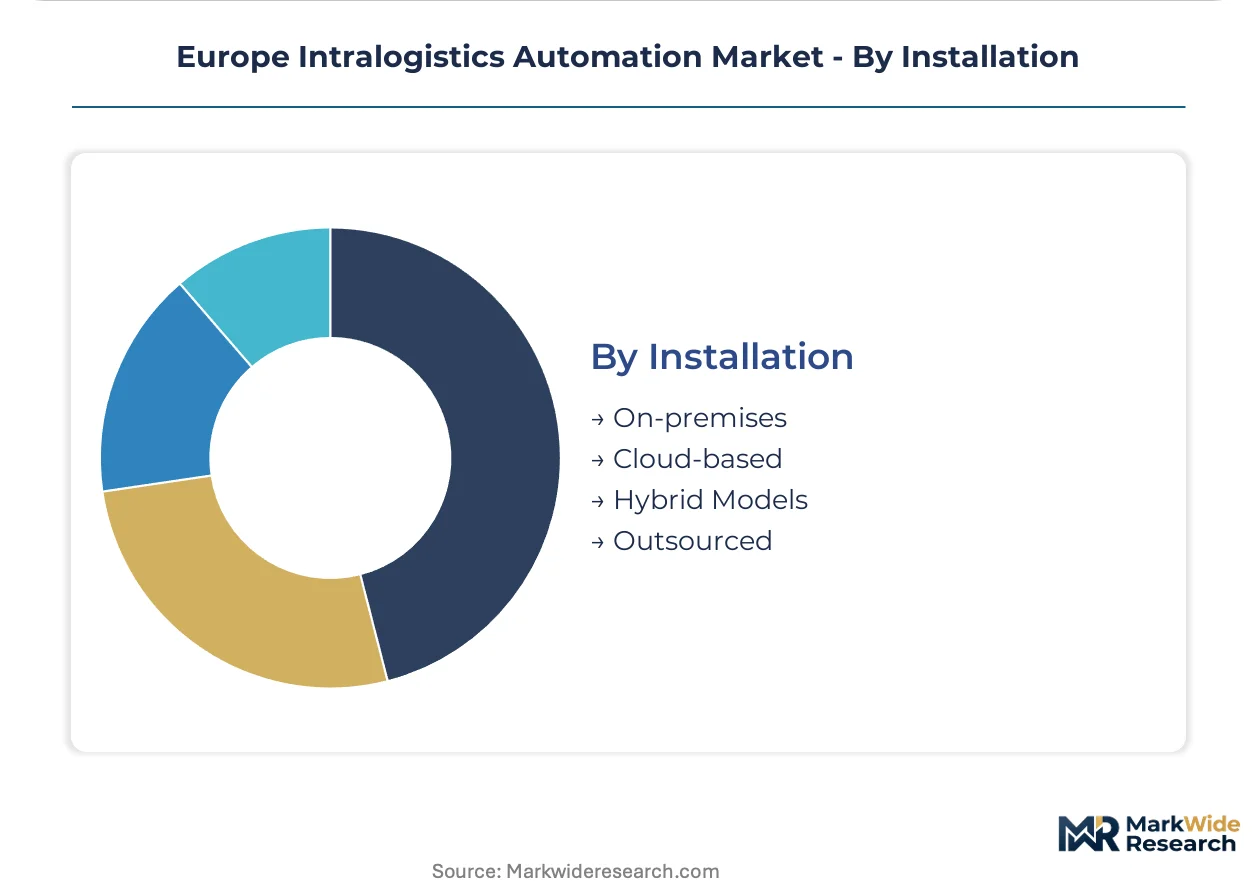
- On-premises:Local server infrastructure maintains full data control and minimizes latency for safety-critical control loops. German automotive parts distributors with proprietary legacy WMS systems favor on-premises warehouse execution systems to avoid API integration complexity and middleware development costs.
- Cloud-based:Subscription models reduce upfront capital expenditure and enable rapid scaling across multi-site networks. Benelux third-party logistics providers are piloting usage-based AMR procurement where vendors retain asset ownership and performance risk.
- Hybrid Models:Split architectures segregate safety-critical controls from optimization algorithms to limit EU AI Act exposure.
- Outsourced:Third-party automation-as-a-service arrangements transfer operational and maintenance responsibility to specialized integrators.
On-premises retains incumbent preference. Cloud-based is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting automation investment toward jurisdictions where CE marking harmonization reduces compliance friction relative to fragmented national standards. Production migration concentrates in corridors where the EU Machinery Directive's unified safety architecture accelerates deployment timelines.
Germany
Automotive distribution hubs in Stuttgart and Wolfsburg are standardizing laser-guided AGV fleets to replace forklift labor in 24-hour operations. The EU Machinery Directive's 2023 amendments mandate force-limiting sensors on all new autonomous deployments. The Ruhr industrial corridor anchors brownfield modernization, where pharmaceutical and automotive parts distributors retrofit legacy infrastructure with modular automation.
Netherlands
E-commerce fulfillment centers near Rotterdam deploy computer vision-guided robotic put-walls to handle polybagged apparel and compress order cycle times. REACH compliance requirements restrict hazardous substance content in batteries powering mobile robotics fleets. The Randstad logistics cluster leads adoption of usage-based AMR procurement models where vendors retain asset ownership.
Belgium
Pharmaceutical cold chain operators deploy temperature-validated automated storage and retrieval systems to address EU GDP guidelines for serialized drug distribution. The EU AI Act imposes conformity obligations on warehouse execution systems with predictive maintenance algorithms. Antwerp-Brussels distribution corridors pilot sensor fusion architectures for real-time environmental monitoring.
Poland
Third-party logistics facilities near Warsaw and Wrocław present first-mover opportunities for modular goods-to-person system vendors serving under-automated networks. CE marking harmonization eliminates country-by-country approval burdens for cross-border equipment deployment. The Silesian manufacturing belt attracts automation integrators targeting automotive supplier parks with just-in-sequence material delivery requirements.
Switzerland
Pharmaceutical distributors in Basel and Geneva pilot computer vision-guided piece-picking for vial and blister-pack handling with integrated quality inspection. Swissmedic regulations align with EU GDP standards for temperature-validated distribution across European networks. The Zurich-Bern corridor concentrates high-value precision automation serving luxury goods and medical device logistics.
Europe Intralogistics Automation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-centric positioning and outcome-based contracting models. The vendor base stratifies across three maturity levels: diversified industrial conglomerates with captive automation divisions, specialized intralogistics integrators with deep vertical expertise, and robotics-native challengers attacking piece-picking applications. Competitive dynamics center on M&A activity consolidating mid-tier integrators and strategic partnerships between hardware OEMs and AI software providers.
Among Dutch engineering specialists, Vanderlande Industries BV exemplifies the airport and parcel sortation archetype, while SSI Schaefer AG anchors the modular warehouse software tier. KION Group AG occupies the scale-driven position among German production-footprint players extending service reach eastward. These three entities represent distinct competitive vectors: sortation infrastructure dominance, software-hardware integration depth, and manufacturing scale with geographic expansion capability.
| Leading Market Players |
|---|
| Vanderlande Industries BV |
| Honeywell International Inc |
| Jungheinrich AG |
| SSI Schaefer AG |
| Interroll Holding AG |
| KION Group AG |
| Daifuku Co Ltd |
| KUKA AG |
| Viastore Systems GmbH |
| Others |
Supply & Pricing Matrix
E-commerce fulfillment operators in the Netherlands and Germany are consolidating procurement around CE-certified safety-integrated systems, forcing vendors to absorb compliance engineering costs or surrender margin to qualified competitors.
Pricing Analysis
Distributor margins on automated guided vehicles compress when systems integrators bundle hardware with multi-year software subscriptions. Pricing stratifies across premium laser-guided fleets, standard magnetic-tape configurations, and economy-grade collaborative robots with limited payload capacity. Cost compression in the economy tier intensifies because Asian battery suppliers command pricing power on lithium-ion cells. Third-party logistics providers in Poland exhibit the highest price sensitivity, while pharmaceutical distributors in Switzerland prioritize validation documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean battery cell manufacturers that feed mobile robotics production lines across Europe. European integrators draw from German servo motor suppliers, Taiwanese sensor component vendors, and Japanese precision bearing producers. Tariff exposure on electronic components extends vendor qualification timelines and raises non-recurring engineering costs. Distribution runs through Rotterdam and Hamburg logistics corridors before final integration at Benelux and German assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's intralogistics automation market functions as a stable compounder, with regulatory harmonization under the EU Machinery Directive creating predictable replacement cycles that sustain vendor revenue visibility.
For Market Incumbents: Hedge against margin erosion in conveyor hardware by deepening software attachment rates through warehouse execution system licensing. Prioritize certification investment for EU AI Act conformity on predictive maintenance algorithms to filter out uncertified challengers. Extend service reach into Poland's under-automated third-party logistics corridors before modular AMR specialists establish beachheads. For New Entrants and Emerging Players: Launch via usage-based contracting models where asset ownership remains with the vendor, targeting Dutch e-commerce fulfillment centers already comfortable with outcome-based payment structures. Exploit white-space opportunity in pharmaceutical cold chain automation across Belgium and Switzerland, where GDP compliance requirements create sticky demand for temperature-validated systems. Position around retrofit-first architectures that preserve existing racking infrastructure in Germany's Ruhr brownfield sites. For Investors and Strategic Acquirers: Asymmetric upside sits with software-centric warehouse execution providers whose AI-driven slotting algorithms qualify for streamlined EU AI Act conformity assessment. The five-to-ten year viability thesis rests on automation penetration rates in Eastern European logistics networks still operating manual workflows. Monitor CE marking backlog durations at notified bodies as an inflection indicator for deployment velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Harmonized safety standards under the EU Machinery Directive eliminate country-by-country approval burdens for cross-border deployment. |
| Software-Defined Warehouse Investment | Warehouse execution systems with embedded AI slotting algorithms extract disproportionate margin regardless of underlying hardware configuration. |
| Backward Integration into Battery Supply | Captive cell production or long-term offtake agreements with Asian manufacturers mitigates input cost volatility for mobile robotics fleets. |
| Retrofit-First System Architecture | Modular AMR designs that preserve existing racking infrastructure unlock brownfield modernization demand in Germany's industrial corridors. |
| Regulatory Convergence Partnership | Collaboration with notified bodies on EU AI Act technical file preparation creates competitive moats against uncertified software entrants. |
Research Methodology
Multiple input streams — primary interviews with warehouse operations directors, automation procurement leads, and systems integration engineers, alongside secondary validation against EU regulatory filings and customs trade data — were reconciled through bottom-up facility deployment tallies and top-down vendor revenue cross-checks.
Segmentation-level projections across product type, end user, technology, and installation model were stress-tested against e-commerce parcel volume growth trajectories and automotive production schedules throughout the forecast period. CAGRs were derived from logistic curve fitting on technology adoption rates, with explicit modeling of regulatory compliance cost pass-through effects on pricing dynamics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of prolonged lithium-ion supply disruption or accelerated EU AI Act enforcement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Global Motion Controller Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Europe ICS Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
United States Human Machine Interface Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Utility Automation Market
Industrial Automation
Motion Control Market
Industrial Automation
North America and Europe Retail Automation Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Motion Positioning Stages Market