
 Global Automated Truck Loading System Market | 2026-2036
Global Automated Truck Loading System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Truck Loading System Market Intelligence
The availability of equipment leasing and automation-as-a-service financing models is tilting the competitive landscape toward broader accessibility. Established players like Daifuku Co., Ltd. leverage their extensive installed base and global service networks to secure large-scale projects. Dematic GmbH & Co. KG specializes in integrated warehouse solutions, combining loading systems with broader intralogistics automation. Joloda Hydraroll Ltd focuses on specialized and retrofit solutions for non-standard cargo, occupying a key niche.
An automated truck loading system is engineered equipment that loads or unloads trailers with minimal human intervention. Functionality relies on components like chain conveyors, robotic arms, or automated guided vehicles (AGVs) to handle palletized freight. Conveyor systems form the largest technology segment, while robotic arms and AGVs represent the fastest-growing categories for mixed-pallet handling. Application in warehousing and distribution centers dominates, driven by operational needs within the e-commerce and food & beverage sectors.
Safety regulations like the EU's Machinery Directive and OSHA standards in the United States shape equipment design and operational protocols. Compliance with standards such as ISO 3691-4 for automated guided vehicles is also critical for market access and user trust. Looking ahead, the key decision for adopters involves choosing between standardized turnkey solutions and highly customized systems tailored to specific facility layouts.
Market Dynamics
The imperative to increase logistics throughput while mitigating labor dependency in the e-commerce and food & beverage sectors is the central force shaping the automated truck loading system market. This pressure moves automation from a cost-saving option to an operational necessity for maintaining competitiveness.
Growth Catalysts
- Workplace Safety Mandates:Regulations including the US OSHA's guidelines on material handling and the EU's Machinery Directive incentivize the replacement of manual loading with automated systems to reduce ergonomic injuries and forklift-related accidents in warehouses.
- E-commerce Fulfillment Pressure:The operational demands of e-commerce distribution centers for 24/7 uptime, high-speed sorting, and rapid trailer turnaround are a primary catalyst for adopting fixed conveyor and mobile robotic loading solutions.
- Advancements in AGV Technology:Improvements in sensor fusion, SLAM navigation, and battery technology for automated guided vehicles (AGVs) and autonomous mobile robots (AMRs) expand their applicability in dynamic, less-structured warehouse environments.
Market Restraints
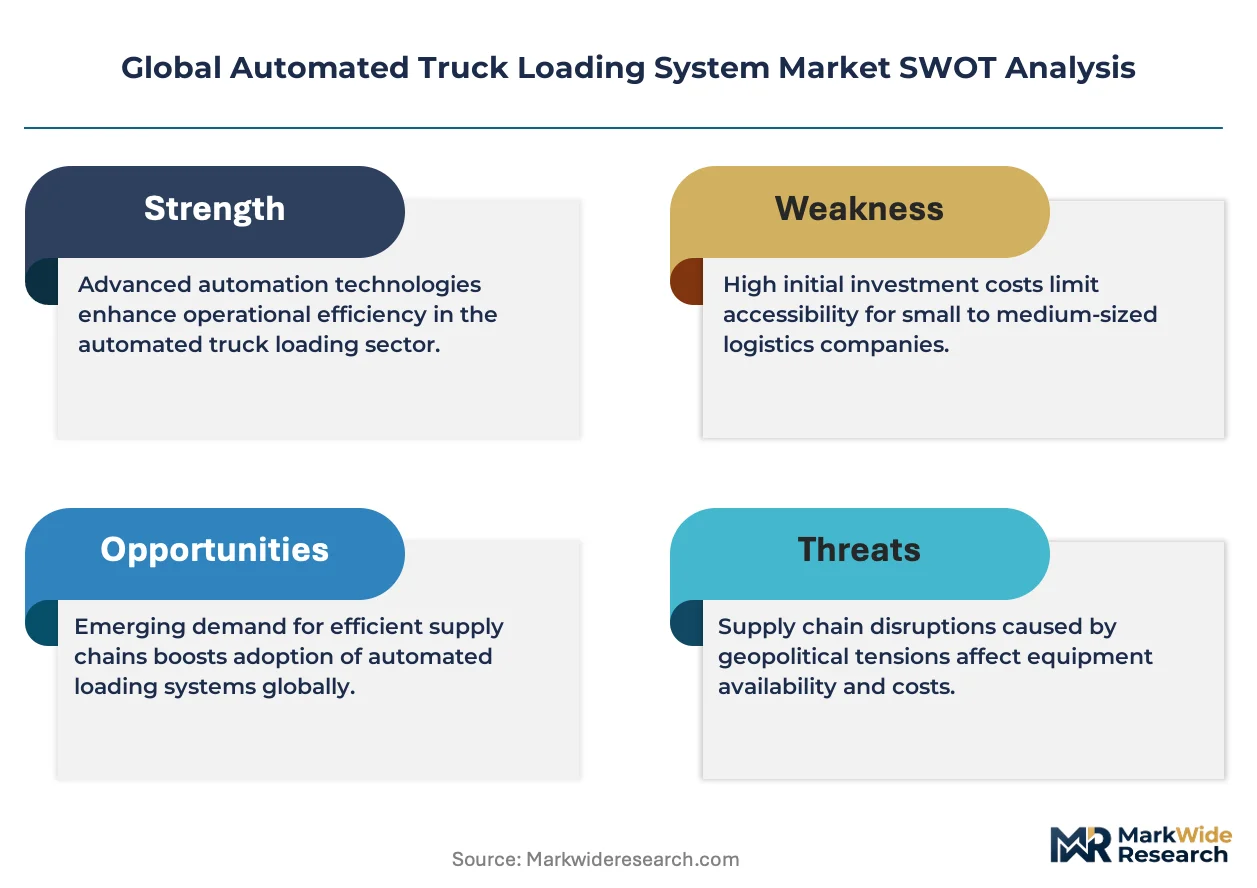
- High Initial Capital Outlay:The significant upfront investment required for system hardware, software, and facility modifications remains a primary adoption barrier, particularly for small to medium-sized logistics enterprises and warehouse operators.
- Non-Standardized Freight Handling:Many automated systems struggle to efficiently handle non-uniform pallet sizes, mixed-SKU pallets, or floor-loaded goods, limiting their use in supply chains with high cargo variability. *Legacy Infrastructure Constraints: The physical layout of older warehouses and distribution centers, including non-level floors, insufficient dock space, and low ceiling heights, often requires costly retrofitting to accommodate automated loading equipment.
Strategic Opportunities
- Emerging Market Logistics Hubs:Underpenetrated markets in Southeast Asia and Latin America, where new warehouse construction is accelerating and labor costs are rising, present significant greenfield opportunities for system deployment.
- AI-Powered Vision Integration:The convergence of AI-based machine vision with robotic arms creates an opportunity to develop systems capable of handling damaged or irregularly shaped parcels, a key unmet need in reverse logistics.
- Automation-as-a-Service (AaaS) Models:Offering systems via subscription or usage-based pricing models lowers the financial barrier to entry, converting capital expenditures to operating expenses and expanding the addressable market.
Industry Challenges
- Systems Integration Complexity:Integrating new automated loading systems with a client's existing, often proprietary, Warehouse Management Systems (WMS) and ERP software is a major technical and operational hurdle during implementation.
- Technical Skill Gaps:A shortage of technicians and engineers with the requisite expertise in robotics, mechatronics, and software to install, maintain, and troubleshoot these complex systems constrains the industry's growth capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Truck Loading System Market |
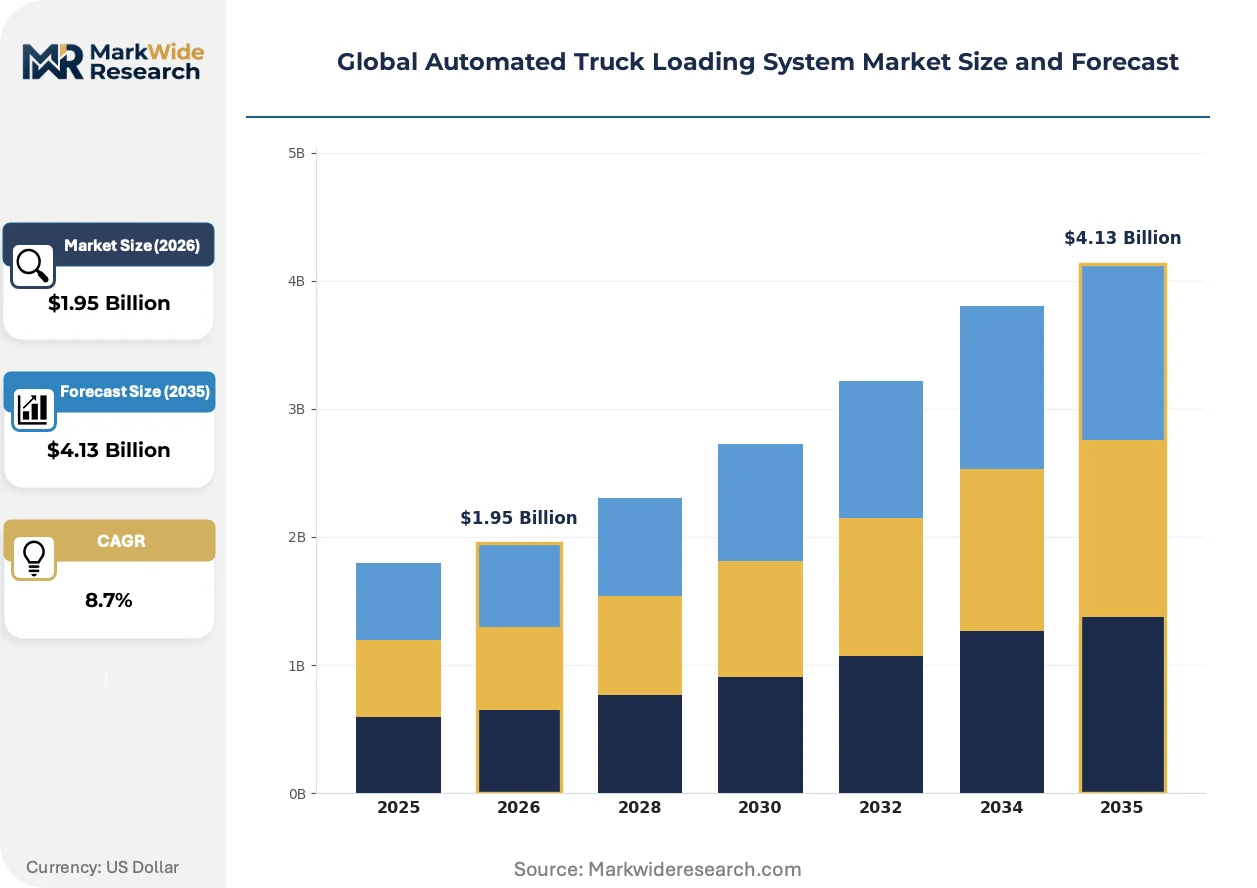
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Arms, Conveyor Systems, Automated Guided Vehicles, Sortation Systems, Palletizers, Vision Systems Application: Warehousing, Cold Storage, Manufacturing Facilities, Distribution Centers, Third-Party Logistics, Fulfillment Centers End User: Retailers, E-commerce Companies, Food & Beverage Manufacturers, Automotive Suppliers, Electronics Producers, Packaging Firms Deployment: On-Premises, Cloud-Enabled Control, Hybrid Systems, Standalone Consoles, Remote Monitoring Platforms |
| Companies Covered | Daifuku Co., Ltd., Dematic GmbH & Co. KG, Vanderlande Industries B.V., SSI Schaefer GmbH, Honeywell International Inc., Bastian Solutions LLC, BEUMER Group, GEBHARDT Fördertechnik GmbH, Joloda Hydraroll Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Truck Loading System Market Strategic Shifts & Innovations
Software-driven flexibility is reshaping the market, shifting focus from rigid, fixed-path hardware to intelligent, adaptable systems. The value is concentrating in the ability of AI and advanced sensors to manage the inherent variability of modern logistics operations.
Vision-guided robotics (VGR) technology combines 3D cameras and machine learning algorithms to autonomously identify and manipulate cartons on mixed-load pallets. Major third-party logistics providers and grocery distributors are actively deploying VGR for complex decanting and unloading tasks. This technology's capacity to work in unstructured settings is rendering obsolete the strict requirement for pre-sorted, uniform loads that constrained earlier automation.
The forthcoming EU AI Act establishes a risk-based framework for artificial intelligence systems, directly impacting the robotics used in logistics. This regulation is forcing equipment manufacturers to build in greater transparency, data governance, and safety validation for autonomous decision-making. The AGV and collaborative robot segments are most affected, as they must provide extensive documentation to prove compliance for European market access.
A clear behavioral change from outright capital purchase to subscription-based financing is underway. This model disrupts the traditional equipment sales cycle by replacing large, one-time investments with recurring operational fees tied to system performance and uptime. This trend is most prominent within the fast-paced e-commerce fulfillment sector in the United States and Germany, where operational agility is valued more than asset ownership.
Global Automated Truck Loading System Market Segmentation
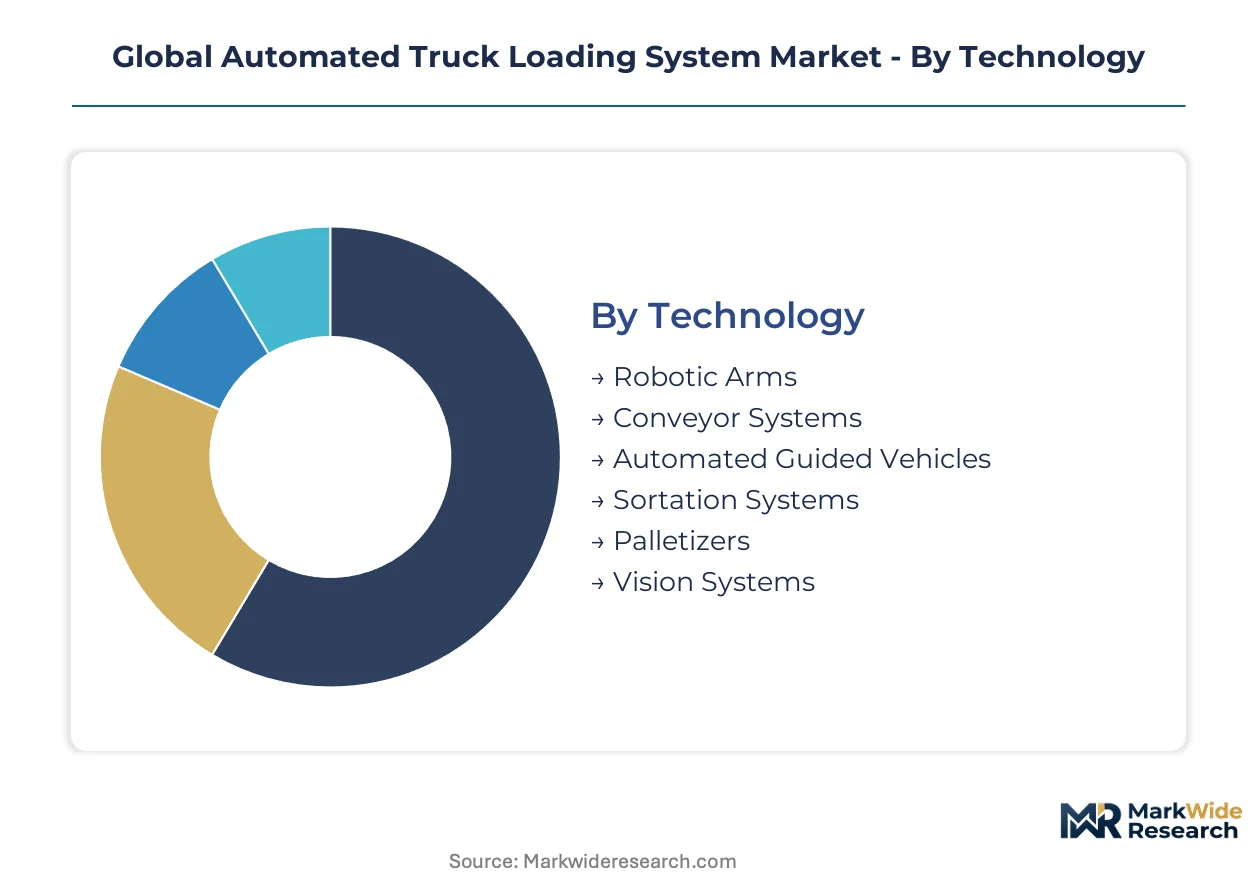
The Global Automated Truck Loading System Market exhibits diverse operational and technological requirements, necessitating a granular understanding of its various segments. This segmentation analysis dissects the market based on the core technologies, their applications, the end-user profiles, and prevalent deployment models.
Technology:
The technological underpinnings of automated truck loading systems define their operational capabilities and integration potential.
- Conveyor Systems:These engineered systems move pallets or packages along a fixed path using rollers, belts, or chains. Warehousing and distribution centers demand these systems for high-volume, continuous material flow.
- Robotic Arms:Articulated manipulators equipped with grippers or suction cups for precise handling of varied cargo. E-commerce fulfillment operations increasingly deploy robotic arms for mixed-pallet handling and complex decanting tasks.
- Automated Guided Vehicles:Self-driving platforms transport loads autonomously within a facility, enhancing internal logistics flow.
- Sortation Systems:Automated mechanisms separate and direct items to specific destinations, critical for package distribution.
- Palletizers:Machines automatically stack or unstack products onto or from pallets, optimizing storage and transport.
- Vision Systems:Cameras and software interpret visual data for object recognition, quality control, and guidance of robotic operations.
Conveyor Systems hold installed capacity. Robotic Arms are rotating up the share rankings.
Application:
Operational contexts dictate the specific automated truck loading solutions implemented across various industrial settings.
- Warehousing:Centralized storage facilities utilize automated systems for efficient inbound receiving and outbound dispatch of goods. Logistics providers in Germany prioritize these solutions for optimizing space utilization and labor efficiency.
- Distribution Centers:Hubs for sorting and consolidating goods before onward shipment, requiring rapid throughput and precise loading sequences. E-commerce companies in the United States rely heavily on automated systems to meet stringent delivery timelines.
- Cold Storage:Temperature-controlled environments demand specialized automation to maintain product integrity and reduce human exposure to extreme conditions.
- Manufacturing Facilities:Production sites integrate automated loading to streamline material flow between manufacturing lines and transport vehicles.
- Third-Party Logistics:Providers offer outsourced logistics services, deploying automation to manage diverse client cargo and optimize supply chains.
- Fulfillment Centers:Facilities dedicated to processing online orders, requiring high-speed, accurate loading of individual parcels and consolidated shipments.
The demand for efficiency in Warehousing operations drives significant investment, while Fulfillment Centers require specialized automation approaches for parcel handling.
End User:
The diverse requirements of different customer types influence the customization and scale of automated truck loading deployments.
- Retailers:Brick-and-mortar stores and chains use automation for efficient stock replenishment and distribution from their warehouses.
- E-commerce Companies:Online retailers require high-speed, 24/7 loading capabilities to manage vast order volumes and rapid trailer turnaround. These companies in the United States invest in advanced mobile robotic solutions to handle mixed-SKU pallets.
- Food & Beverage Manufacturers:Producers of perishable goods demand precise, hygienic, and often temperature-controlled loading solutions to maintain product quality and safety. European food distributors adopt automated systems to comply with strict regulatory standards and reduce product damage.
- Automotive Suppliers:Component manufacturers utilize automated loading to ensure just-in-time delivery to assembly plants and optimize inventory.
- Electronics Producers:High-value, fragile electronic goods necessitate gentle and secure automated handling during transport.
- Packaging Firms:Companies producing packaging materials employ automated systems to manage high volumes of bulky, often non-standardized, finished products.
Customer segments like E-commerce Companies prioritize speed and throughput, whereas Automotive Suppliers focus on precision and inventory management.
Deployment:
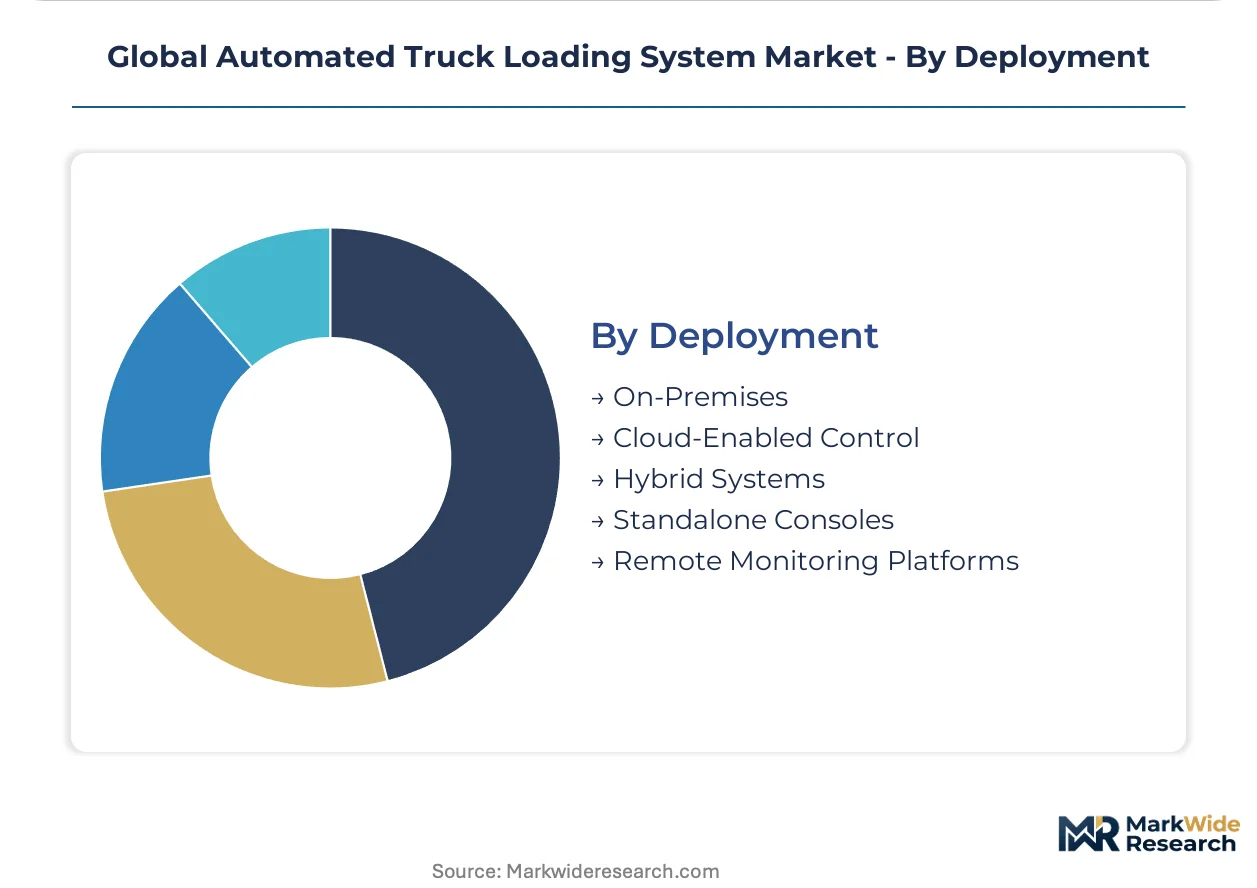
The maturity of deployment models for automated truck loading systems ranges from established on-site installations to advanced, remotely managed platforms.
- On-Premises:Systems installed and managed directly within the user's physical facility, offering full control over hardware and data. Large manufacturing facilities in Germany often prefer on-premises solutions for data security and direct operational oversight.
- Cloud-Enabled Control:Automation systems managed and optimized via cloud-based software, enabling remote monitoring and data analytics. This model gains traction among third-party logistics providers in the United States for its scalability and reduced IT infrastructure burden.
- Hybrid Systems:Combinations of on-premises hardware with cloud-based software for enhanced flexibility and data integration.
- Standalone Consoles:Localized control units for managing individual automated loading equipment, common in smaller operations.
- Remote Monitoring Platforms:Software solutions allowing off-site observation and diagnostics of automated loading system performance and status.
The shift towards Cloud-Enabled Control models reflects a broader industry trend toward flexible and scalable automation solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automated truck loading system market reflects a dynamic interplay of logistics needs across diverse economies. Regions with high import-export volumes and advanced manufacturing bases drive demand for sophisticated automation. Conversely, emerging markets with burgeoning e-commerce sectors and rising labor costs represent significant greenfield opportunities for system deployment.
United States
The imperative for rapid e-commerce fulfillment and labor dependency reduction drives demand for automated truck loading systems in the United States. US OSHA guidelines on material handling incentivize the replacement of manual loading with automated systems to reduce workplace injuries. The Dallas-Fort Worth region, a major logistics hub, sees significant investment in mobile robotic solutions for high-speed trailer turnaround.
Germany
German logistics operators prioritize operational efficiency and space utilization in warehousing, fueling demand for automated loading systems. The EU's Machinery Directive shapes equipment design and operational protocols, ensuring safety and compliance for European market access. The Rhine-Ruhr area, with its dense industrial and logistics networks, integrates advanced intralogistics automation for optimized material flow.
China
Rapid growth in e-commerce and a vast manufacturing base propel the adoption of automated truck loading systems across China. National GB standards for industrial machinery guide the development and deployment of automated solutions, ensuring performance and safety. The Yangtze River Delta, a manufacturing and distribution powerhouse, deploys high-speed conveyor systems to manage immense cargo volumes.
Japan
Japan's focus on high-precision manufacturing and an aging workforce stimulates demand for advanced automation in logistics. METI initiatives for industrial automation encourage technological innovation and adoption in the supply chain sector. The Tokyo Bay area, a major port operation and industrial cluster, adopts robotic arms for complex and varied cargo handling tasks.
Brazil
Emerging market logistics hubs in Brazil present significant greenfield opportunities due to new warehouse construction and rising labor costs. Brazil's national labor laws increasingly encourage automation for worker safety and ergonomic improvements. São Paulo state, a key economic center, attracts investment in automated systems to enhance distribution efficiency for its growing consumer market.
Global Automated Truck Loading System Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, combining established global players with specialized solution providers. Strategic archetypes include large-scale integrators offering comprehensive warehouse solutions, niche players focusing on specific cargo types, and technology-driven innovators pushing robotic and AI capabilities. Dominant competitive moves involve leveraging extensive installed bases and strategic partnerships to expand market reach and solution portfolios.
Established players, such as Japan-based Daifuku Co., Ltd., anchor the market with extensive installed bases and global service networks, securing large-scale projects. German entity Dematic GmbH & Co. KG exemplifies providers specializing in integrated warehouse solutions, combining loading systems with broader intralogistics automation for complex client needs. UK-based Joloda Hydraroll Ltd. occupies a key niche, focusing on specialized and retrofit solutions tailored for non-standard cargo handling requirements, addressing specific operational challenges. These different approaches reflect the varying demands across diverse customer segments, from high-volume general cargo to unique freight profiles.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Dematic GmbH & Co. KG |
| Vanderlande Industries B.V. |
| SSI Schaefer GmbH |
| Honeywell International Inc. |
| Bastian Solutions LLC |
| BEUMER Group |
| GEBHARDT Fördertechnik GmbH |
| Joloda Hydraroll Ltd |
| Others |
Cost & Logistics Intelligence
Underutilization in legacy warehouse infrastructure influences supplier behavior, as vendors adapt offerings to retrofit older facilities. This dynamic directly impacts pricing postures, favoring solutions that minimize disruption and capital expenditure for facility upgrades.
Pricing Analysis
Industrial OEM buyers anchor hybrid project-based and subscription pricing models within the automated truck loading system market. Price differentiation stems from the customization level required for specific facility layouts and the extent of bundled after-sales service. Pricing softness reflects the increasing adoption of Automation-as-a-Service models, which convert capital expenditures to operating expenses. Small to medium-sized logistics enterprises exhibit the highest price sensitivity, while large e-commerce companies prioritize high-speed throughput over initial cost.
Supply Chain Analysis
Geopolitical tensions impacting critical robotic components create a structural risk for the automated truck loading system supply chain. Supply concentration centers in manufacturing hubs like Germany, Japan, and China. The industry relies on specialized steel, sensor technology, and precision mechanical parts for system fabrication. Distribution runs through direct sales channels to large enterprises and extensive integrator networks serving diverse client needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated truck loading system market offers a defensive moat, primarily driven by high switching costs associated with integrating complex solutions into existing warehouse management systems. This structural advantage ensures long-term client relationships and predictable revenue streams for established providers.
For Market Incumbents: Build regulatory compliance moats by actively shaping and adhering to evolving standards like the EU AI Act and ISO 3691-4. Expand global service networks to leverage existing installed bases, countering the threat from agile, technology-driven innovators. Invest heavily in R&D for software-driven flexibility, enhancing system adaptability and integration with diverse client ERPs. This secures large-scale projects against emerging AI-powered vision system entrants. For New Entrants and Emerging Players: Specialized and retrofit solutions for non-standard cargo handling represent a penetrable entry point, particularly for Joloda Hydraroll Ltd. Emerging market logistics hubs in Southeast Asia and Latin America, with accelerating new warehouse construction, offer significant greenfield opportunities. Automation-as-a-Service (AaaS) models provide a compelling go-to-market angle, lowering financial barriers for smaller operators. This approach targets specific operational challenges rather than broad market competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across the AGV and robotic arm segments, driven by technology advancements and AaaS adoption. The market demonstrates strong long-term viability over a 5-10 year window, fueled by e-commerce expansion and persistent labor scarcity. Acquisition targets should focus on niche players specializing in AI-powered vision integration or highly customized retrofit solutions. Increased adoption rates of Automation-as-a-Service models serve as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Expand Global Service Network | Established players like Daifuku Co., Ltd. leverage service networks for large-scale project execution. |
| Invest in AI-Powered Vision Integration | AI-based machine vision with robotic arms addresses handling of damaged or irregularly shaped parcels. |
| Develop Automation-as-a-Service Models | Subscription-based financing lowers financial barriers for small to medium-sized logistics enterprises. |
| Secure EU AI Act Compliance | Equipment manufacturers must provide extensive documentation for European market access. |
| Acquire Niche Retrofit Specialists | Joloda Hydraroll Ltd. demonstrates the value of specialized solutions for non-standard cargo. |
Research Approach
Cross-validation between primary interviews and secondary market reports anchors the qualitative findings within the automated truck loading system analysis. Discussions with warehouse managers, logistics directors, automation engineers, and equipment procurement specialists provided crucial insights. Secondary validation utilized industry association reports, patent databases, and financial filings of public companies. Bottom-up data aggregation and top-down market sizing approaches ensured triangulation and robustness across all data points.
Historical market data and expert consensus calibrated the analytical framework across the analysis window. Segmentation dimensions modeled included technology, application, end-user, deployment, and specific trailer type compatibility. Compound annual growth rates were derived from historical growth trends and projected technological advancements in robotics. E-commerce growth rates and regional labor availability indices served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or capital investment cycles would shift the trajectory. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Supply chain disruptions or unforeseen shifts in workplace safety mandates represent risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Intralogistics Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market