
 North America Smart Manufacturing Market | 2026-2036
North America Smart Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Manufacturing Market Analytics
Multi-source procurement for industrial software stacks is shifting toward vertically integrated platform contracts as manufacturers seek unified data architectures. Rockwell Automation leverages its FactoryTalk ecosystem to anchor control-layer dominance across Midwest automotive plants. Siemens competes through its Xcelerator portfolio, which extends digital thread capabilities from design to operations. Honeywell International Inc. specializes in process safety and advanced process control for refining and chemicals complexes along the Gulf Coast.
Smart manufacturing denotes the integration of cyber-physical production systems, industrial IoT sensors, and AI-driven analytics to enable real-time optimization of factory operations with sub-millisecond control loop response times. Its primary purpose is to synchronize material flows, equipment health, and quality parameters across distributed production networks. IoT Platforms and Control Software command the deepest margin pools because recurring software licenses generate higher lifetime value than hardware sales. Artificial Intelligence applied to Predictive Maintenance represents the fastest-expanding technology-application intersection, while Automation Hardware retains the largest installed base. Aerospace and Automotive end users currently absorb the majority of capital deployment in this space.
The US Occupational Safety and Health Administration and the Federal Energy Regulatory Commission shape equipment certification and grid-interconnection standards for connected industrial assets, while NIST cybersecurity frameworks mandate resilience protocols for operational technology networks. These requirements compel vendors to embed compliance features directly into platform architectures, raising barriers for non-domestic suppliers. Stakeholders must track how evolving EPA emissions rules for manufacturing facilities will force retrofit demand across existing brownfield installations.
Market Dynamics
Digital twin deployments across automotive assembly lines are compressing design-to-production cycles and forcing control-system vendors to unify hardware-software architectures. The US Inflation Reduction Act's battery factory incentives are accelerating demand for advanced process control in new domestic gigafactories.
Growth Catalysts
- Industrial IoT sensor density:Sub-millisecond control loop requirements in automotive paint shops and battery electrode coating lines are mandating edge-computing upgrades across Michigan and Texas manufacturing belts.
- OSHA equipment certification:New connected-asset safety protocols are compelling brownfield retrofits in Gulf Coast chemical complexes, expanding the addressable base for compliant control platforms.
- Battery cell factory construction:Domestic gigafactory buildouts under IRA tax credits are creating concentrated demand for synchronized material-flow systems and predictive quality analytics.
Market Restraints
- Semiconductor input volatility:Industrial controller chip supply remains concentrated in East Asian foundries, exposing North American system integrators to lead-time volatility.
- Legacy equipment lock-in:Proprietary communication protocols in installed automation bases create technical friction for unified data architecture deployments.
- Skilled technician scarcity:Shortages of OT-cybersecurity specialists and AI-operations engineers are extending deployment timelines for integrated smart manufacturing platforms.
Strategic Opportunities
- Canadian battery supply chain:Ontario and Quebec mineral processing and cell manufacturing investments are opening new geography for process control vendors beyond US borders.
- EPA emissions retrofit mandate:Evolving manufacturing facility emissions rules will force control-system upgrades across existing brownfield installations.
- Digital twin-to-ERP convergence:Integration between virtual commissioning environments and enterprise resource planning systems is creating new software subscription revenue pools.
Industry Challenges
- OT-IT security integration:NIST cybersecurity framework compliance for operational technology networks requires specialized cross-functional teams that manufacturers struggle to staff.
- Multi-vendor system harmonization:Heterogeneous equipment bases from decades of incremental automation investments complicate unified data architecture implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Manufacturing Market |
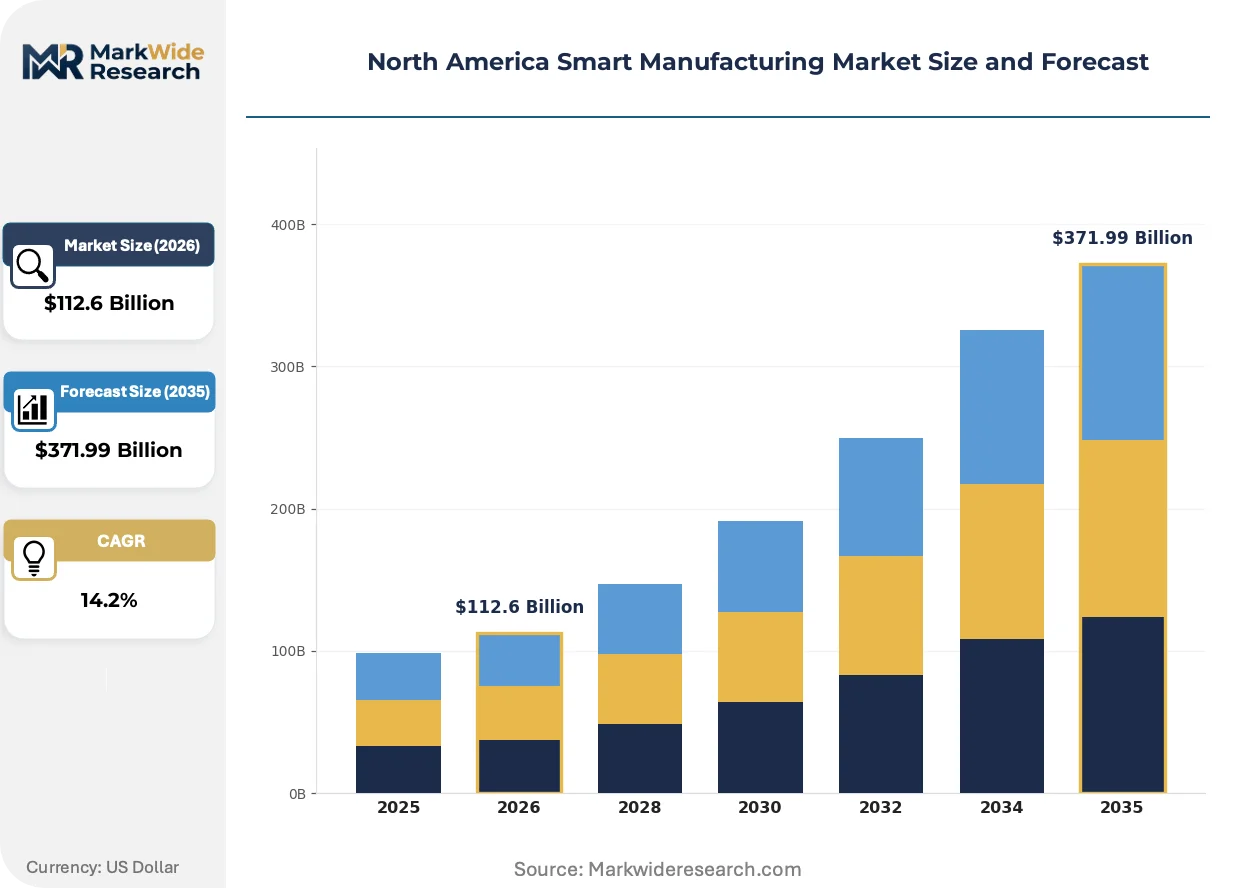
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $371.99 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automation Hardware, Robotics, IoT Platforms, Control Software Technology: Artificial Intelligence, Big Data Analytics, Cloud Computing, Cybersecurity End User: Aerospace, Automotive, Electronics, Pharmaceuticals Application: Process Optimization, Predictive Maintenance, Quality Control, Inventory Management |
| Companies Covered | Rockwell Automation, Siemens, ABB Ltd., Schneider Electric, Emerson Electric Co., Honeywell International Inc., General Electric Co., FANUC Corp., Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Manufacturing Market Evolving Landscape
Artificial intelligence is migrating from pilot programs to production-critical applications, reshaping how manufacturers prioritize capital allocation between hardware and software layers.
Edge AI inference engines are overtaking cloud-dependent analytics for real-time defect detection and equipment health monitoring. Automotive OEMs in Michigan's automation corridor are deploying these systems at line speed for weld quality verification. The shift is compressing latency requirements and favoring vendors with integrated edge-to-control-layer architectures.
The US Inflation Reduction Act's domestic content bonuses are restructuring supplier qualification criteria for battery and clean-tech manufacturing equipment. Vendors must now document North American assembly and software development to access gigafactory procurement pipelines. This policy mechanism is accelerating regionalization of control-system supply chains beyond tariff considerations alone.
Platform-based procurement contracts are displacing multi-source software stacks as manufacturers seek unified data architectures. Midwest automotive plants and Texas semiconductor fabs are consolidating vendor relationships around integrated ecosystems. The consolidation is visible most acutely in Michigan, where single-platform contracts now dominate new line installations.
North America Smart Manufacturing Market Segmentation
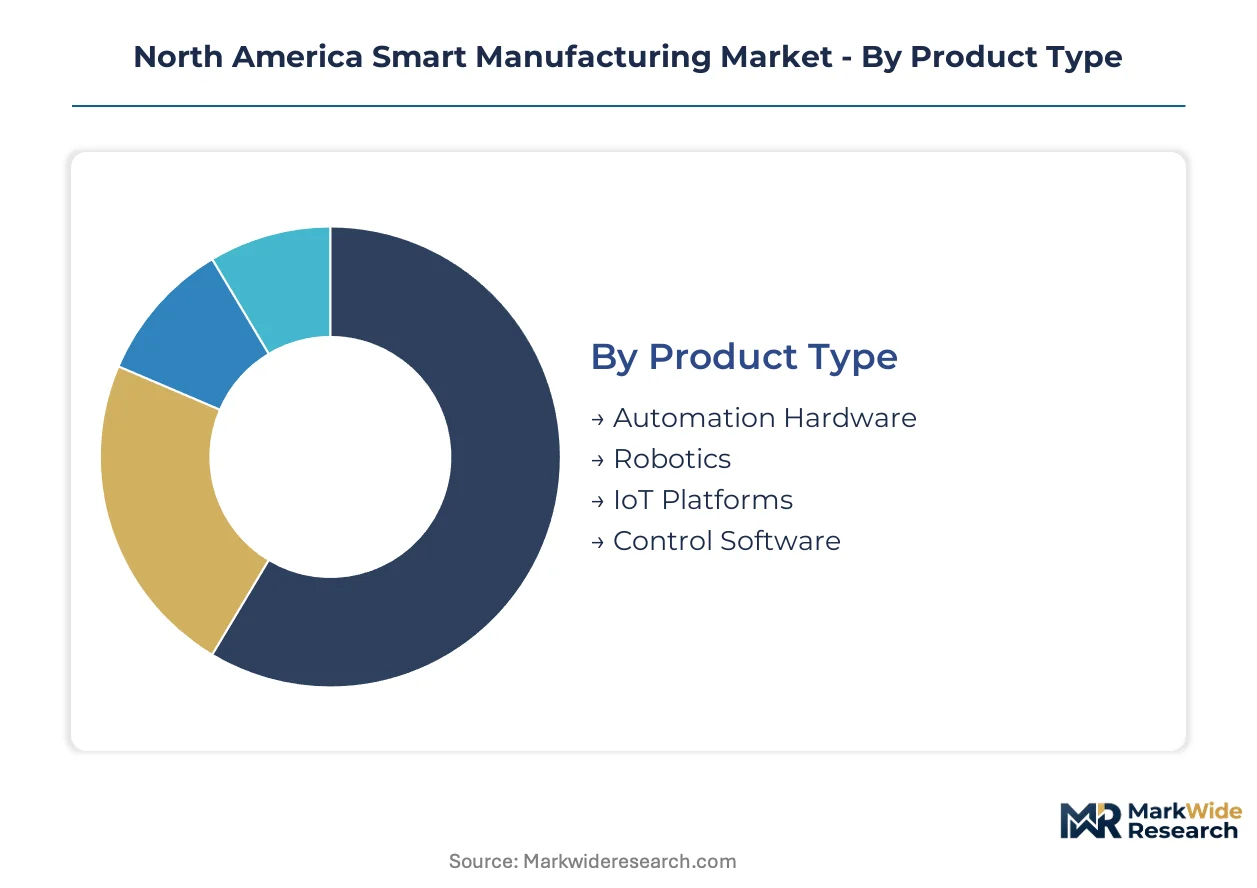
Segmentation in smart manufacturing reveals how capital allocation splits between physical infrastructure layers and intelligence systems. Understanding these divisions exposes where margin pools concentrate and which technology intersections command strategic priority.
Product Type:
Physical systems versus software platforms define the capital deployment axis across automotive and battery manufacturing corridors.
- Automation Hardware:Programmable logic controllers, industrial PCs, and motion control systems form the execution layer. Demand concentrates in Texas semiconductor fabs and Michigan automotive assembly where sub-millisecond response requirements mandate dedicated processing hardware. Brownfield retrofit cycles sustain replacement revenue despite software margin compression.
- IoT Platforms:Device management, data ingestion, and edge orchestration software enable sensor-to-cloud pipelines. Battery gigafactories in the US Midwest and Ontario are deploying these systems for synchronized material-flow tracking under IRA domestic content incentives. Recurring license structures generate superior lifetime value versus hardware sales.
- Robotics:Articulated arms and autonomous mobile robots execute precision handling tasks. Collaborative robot deployments are accelerating in electronics assembly and pharmaceutical packaging lines.
- Control Software:Distributed control systems and manufacturing execution systems coordinate production workflows. Gulf Coast chemical complexes under EPA emissions mandates drive upgrade demand for advanced process control suites.
Mature deployment sits with Automation Hardware. Newer deployment is concentrated in IoT Platforms.
Technology:
Intelligence layers determine competitive differentiation as manufacturers prioritize real-time decision-making over retrospective reporting.
- Artificial Intelligence:Machine learning models for defect detection, predictive maintenance, and process optimization. Michigan automotive paint shops and weld verification stations are deploying edge AI inference for line-speed quality decisions. The technology-application intersection with Predictive Maintenance is expanding most quickly across the analysis window.
- Cybersecurity:Network segmentation, anomaly detection, and zero-trust architectures for operational technology environments. NIST framework compliance mandates are compelling integrated security features in new platform deployments. Skilled OT-cybersecurity specialist shortages extend implementation timelines.
- Big Data Analytics:Historical pattern recognition and batch optimization for supply chain and energy management. Process industries leverage these tools for yield improvement across multi-site production networks.
- Cloud Computing:Scalable compute and storage for non-time-critical applications including digital twin simulation and enterprise integration. Hybrid architectures predominate as latency-sensitive workloads remain on-premise.
Established integration sits with Big Data Analytics. Steepest expansion trajectory belongs to Artificial Intelligence.
End User:
Capital intensity and regulatory exposure shape how distinct manufacturing verticals prioritize smart manufacturing investments.
- Automotive:OEMs and tier suppliers deploying digital twins, edge AI, and synchronized robotics across assembly and powertrain operations. Michigan's automation corridor and emerging battery belt facilities absorb the majority of regional capital deployment in this segment.
- Aerospace:Precision manufacturing and regulatory traceability requirements drive quality system investments. Defense contractor demand concentrates in southwestern US manufacturing clusters with ITAR compliance constraints.
- Electronics:Semiconductor fabrication and electronics assembly requiring cleanroom automation and defect detection at micron scales. Texas fabrication buildouts are accelerating demand for advanced process control.
- Pharmaceuticals:Batch processing, serialization, and FDA validation requirements shape system specifications. Continuous manufacturing transitions are creating upgrade cycles in legacy oral solid dose facilities.
Volume concentration sits with Automotive. Regulatory complexity peaks in Pharmaceuticals.
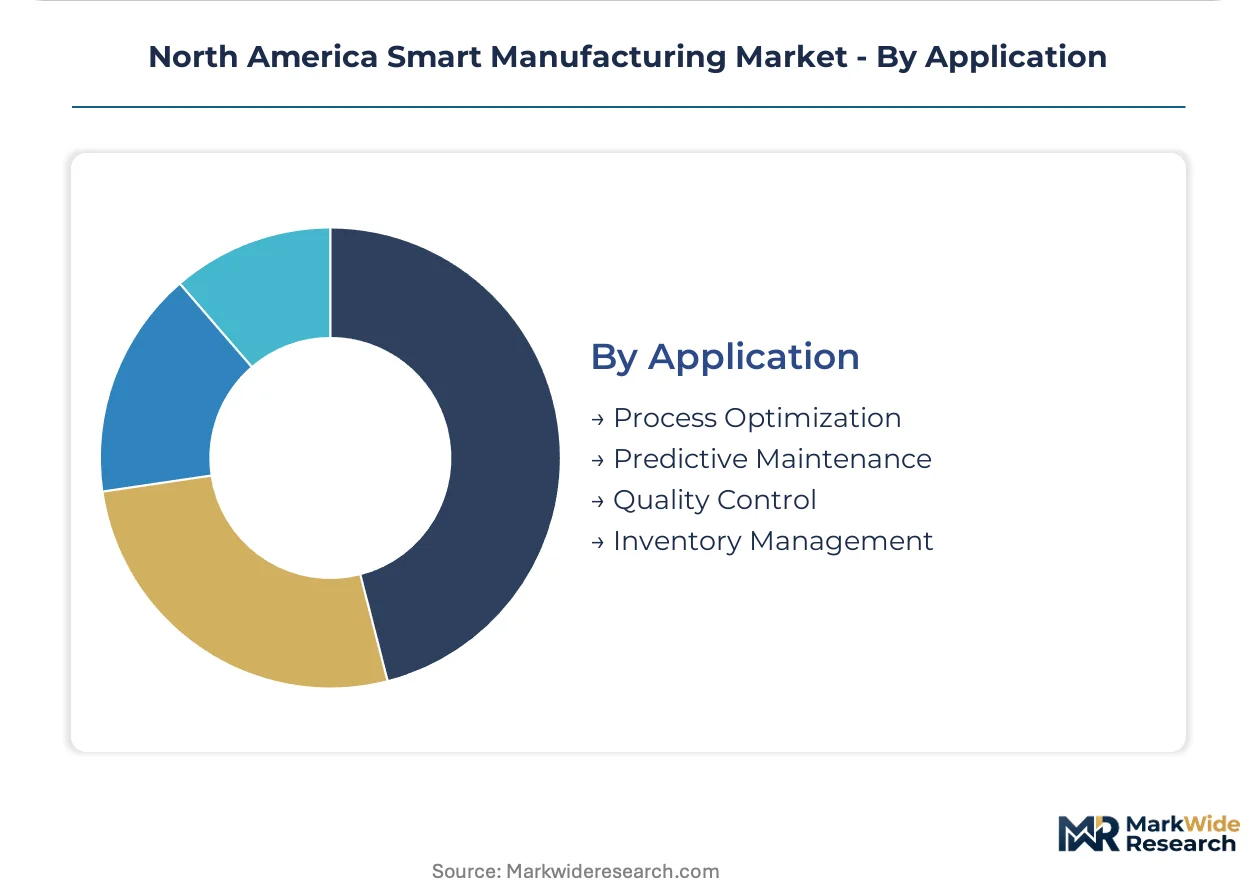
Application:
Use-case prioritization reveals where manufacturers extract measurable return versus experimental deployment.
- Predictive Maintenance:Vibration analysis, thermal monitoring, and oil analysis for equipment health forecasting. The AI-technology intersection is climbing the fastest as automotive and aerospace facilities quantify downtime avoidance value.
- Quality Control:Machine vision, in-process gauging, and statistical process control for defect prevention. Real-time weld verification and battery electrode coating inspection are critical use cases in Michigan and Texas manufacturing belts.
- Process Optimization:Energy management, throughput balancing, and recipe optimization for continuous and batch processes. Refining and chemicals complexes along the Gulf Coast prioritize these applications.
- Inventory Management:Automated storage, retrieval systems, and warehouse management integration. E-commerce fulfillment and automotive sequencing operations drive deployment.
Proven ROI sits with Quality Control. Emerging validation sits with Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment for smart manufacturing concentrates heavily in the United States, with Canada and Mexico playing specialized but growing roles in battery supply chains and nearshored electronics assembly.
United States
Michigan's automation corridor and Texas's semiconductor manufacturing belt absorb the majority of domestic investment in digital twin deployments and edge AI systems. OSHA equipment certification requirements and NIST cybersecurity frameworks compel brownfield retrofits across Gulf Coast chemical complexes. The Inflation Reduction Act channels capital into domestic battery cell factories requiring advanced process control systems, with new gigafactory construction concentrated in the Midwest and Southwest.
Canada
Ontario and Quebec mineral processing and cell manufacturing investments are opening new geography for process control vendors beyond US borders. Health Canada and PMRA regulations shape pharmaceutical serialization and validation requirements for smart manufacturing platforms in the Great Lakes region. Toronto-Waterloo tech corridor companies are deploying IoT platforms for synchronized material-flow tracking in automotive supplier networks.
Mexico
Nuevo León and the Bajío Region are attracting electronics assembly and automotive component manufacturing requiring collaborative robotics and machine vision systems. Mexican labor regulations and PROFEPA environmental standards influence automation deployment patterns in maquiladora operations. Monterrey industrial parks are integrating predictive maintenance systems to support just-in-sequence delivery to Texas and Michigan assembly plants.
North America Smart Manufacturing Market Competitive Landscape
Platform consolidation dominates the current landscape as manufacturers abandon multi-source procurement for vertically integrated contracts. The vendor base organizes around three tiers: diversified industrial conglomerates with full-stack portfolios, specialized control-system providers with deep vertical expertise, and emerging edge-AI specialists attacking specific use cases. M&A activity concentrates on software capabilities and cybersecurity assets, while strategic partnerships between automation hardware vendors and cloud providers accelerate hybrid architecture deployment.
Within the diversified conglomerate tier, Rockwell Automation, Siemens, and Honeywell International Inc. exemplify contrasting geographic anchoring and vertical specialization patterns. Rockwell Automation represents the Midwest automotive corridor incumbent with FactoryTalk ecosystem dominance. Siemens occupies a position as the European-headquartered competitor extending digital thread capabilities through its Xcelerator portfolio. Honeywell International Inc. anchors Gulf Coast process industries with advanced process control specialization for refining and chemicals complexes.
| Leading Market Players |
|---|
| Rockwell Automation |
| Siemens |
| ABB Ltd. |
| Schneider Electric |
| Emerson Electric Co. |
| Honeywell International Inc. |
| General Electric Co. |
| FANUC Corp. |
| Bosch |
| Others |
Value Network & Pricing Analysis
Industrial controller chip costs cascade through three distinct pricing tiers as Taiwanese and South Korean foundry output feeds North American system integrators serving Michigan automotive corridors and Texas semiconductor fabrication belts.
Pricing Analysis
Volume concentration in Automation Hardware trades margin for installed-base retention while IoT Platforms and Control Software capture recurring-license premiums. Price differentiation separates ISO-certified safety platforms from uncertified alternatives, with NIST cybersecurity compliance adding further tier separation. Cost compression in hardware tiers is intensifying as semiconductor input volatility forces integrators to absorb lead-time risk. Tier 1 automotive OEMs exhibit lowest price sensitivity given downtime-avoidance value, while mid-tier suppliers face acute budget constraints on brownfield retrofit projects.
Supply Chain Analysis
Reverse-logistics flows for refurbished PLCs and remanufactured motion controllers create secondary supply channels that buffer lead-time volatility for critical spares. Upstream supply concentrates in Taiwan, South Korea, and Japan for advanced process nodes and specialized industrial semiconductors. The ecosystem draws from concentrated rare-earth processing for servo motors, silicon carbide substrates for power electronics, and precision bearings from German and Japanese specialists. Single-source vulnerability in advanced-node foundries exposes North American integrators to allocation risk during demand surges. Distribution runs through authorized distributor networks with technical support capabilities rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American smart manufacturing sits at a technology-transition phase where edge AI inference engines displace cloud-dependent analytics for line-speed quality decisions.
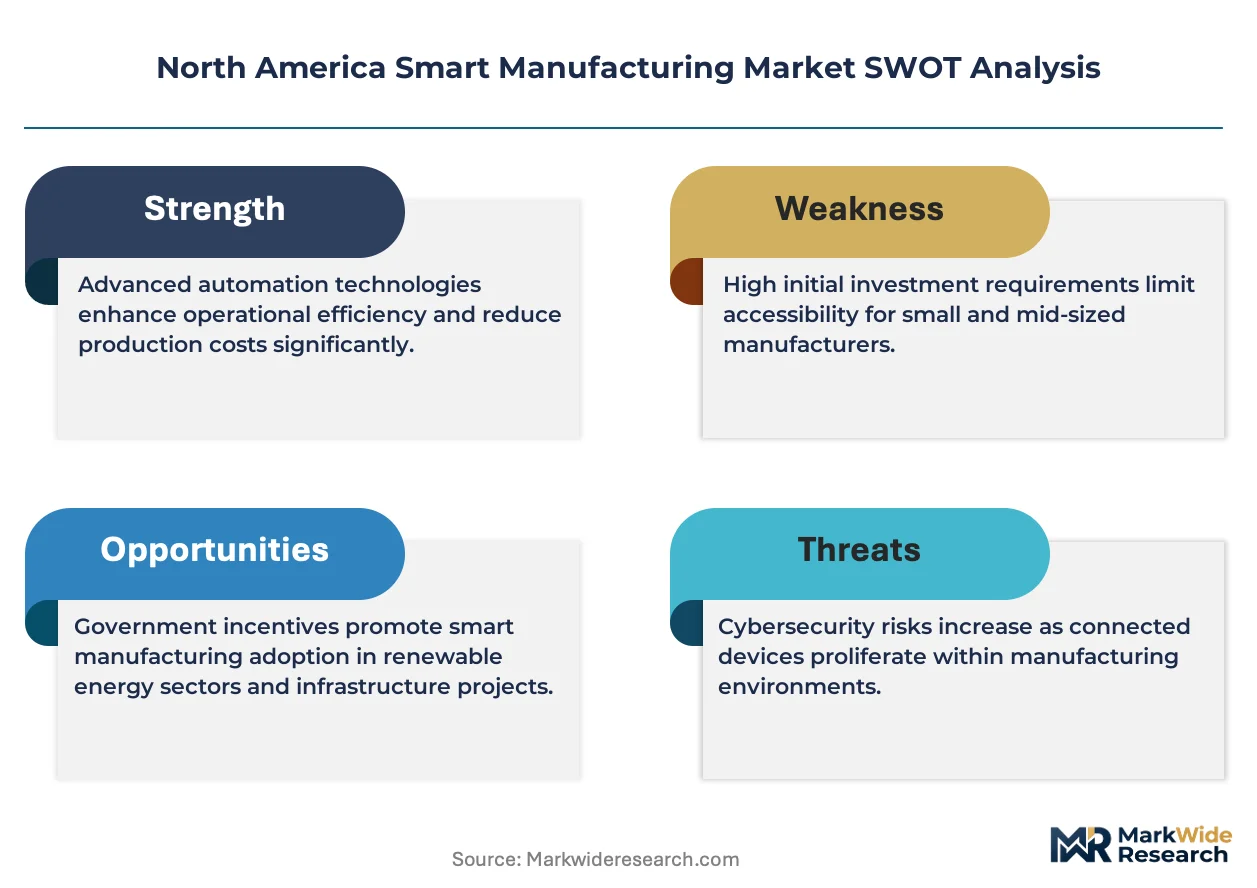
For Market Incumbents: To counter platform consolidation pressure from vertically integrated competitors, anchor ecosystem dominance through captive edge-AI development and deepen FactoryTalk-style architecture control across Midwest automotive procurement pipelines. Prioritize NIST cybersecurity framework pre-certification to accelerate brownfield retrofit sales cycles against non-compliant rivals. For New Entrants and Emerging Players: Begin with Canadian battery supply chain entry points in Ontario and Quebec mineral processing corridors where incumbent presence remains thinner than US Midwest saturation. Target predictive maintenance software for mid-tier automotive suppliers lacking in-house AI-operations engineering capacity, selling through system integrator channel partnerships rather than direct OEM pursuit. For Investors and Strategic Acquirers: Distressed-cycle entries favor OT-cybersecurity specialists with Health Canada or FDA validation experience in the Great Lakes corridor, where compliance moats sustain premium multiples. Long-term viability hinges on software-recurring revenue exceeding hardware exposure; monitor IRA domestic-content bonus qualification rates as inflection indicator for battery belt vendor selection trends.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies data architectures across Rockwell FactoryTalk and Siemens Xcelerator ecosystems for single-vendor procurement dominance. |
| Acquisition of Specialist Firm | Adds edge-AI inference capabilities or OT-cybersecurity assets to fill portfolio gaps in predictive maintenance suites. |
| Geographic Expansion | Establishes Ontario and Quebec presence to capture Canadian battery supply chain investments beyond US border concentration. |
| Strategic Partnership | Links automation hardware vendors with cloud providers for hybrid edge-to-cloud architectures in Texas semiconductor fabs. |
| Product Launch | Introduces NIST-compliant control platforms embedding cybersecurity features mandatory for Gulf Coast chemical complex retrofits. |
Research Methodology
Independent corroboration across plant engineers at Michigan automotive OEMs, procurement leads at Texas semiconductor fabrication facilities, and OT-cybersecurity specialists at Gulf Coast chemical complexes underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings of diversified industrial conglomerates, NIST cybersecurity framework documentation, and US Department of Energy battery factory incentive disclosures. Bottom-up equipment shipment analysis triangulates against top-down capital expenditure tracking across the automotive, aerospace, and electronics verticals.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology layer, end-user vertical, and application use case, with additional granularity on IRA domestic-content qualification status for battery belt investments. CAGRs derive from installed-base replacement cycles, greenfield construction pipelines, and software-subscription conversion rates in legacy hardware accounts. Edge-computing upgrade intensity and AI-operations engineering labor scarcity feed directly into deployment timeline assumptions.
Underlying measurement precision varies by segment; IoT Platforms and Control Software carry tighter precision than Automation Hardware given recurring-revenue visibility. Forecasts reflect assumptions on IRA incentive continuity, OSHA equipment certification timeline enforcement, and semiconductor foundry allocation stability. Practitioners should monitor EPA emissions rule finalization dates, NIST framework revision schedules, and Taiwanese foundry capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Motion Control Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Smart Manufacturing Market
Industrial Automation
Smart Factory Market
Industrial Automation
North America Process Automation Market