
 Middle East and Africa Machine Control System Market | 2026-2036
Middle East and Africa Machine Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Machine Control System Market Foresight
Composite sensor housings are hardening as the preferred alternative to machined aluminum in ruggedized machine control enclosures, cutting unit weight and corrosion risk for desert deployments. Trimble Inc leverages its GNSS correction network density to dominate high-precision earthmoving contracts across Gulf Cooperation Council megaprojects. Leica Geosystems AG anchors its regional position through calibrated total station integration with third-party OEM hydraulic controllers. Hexagon AB competes by extending its mine automation software stack into construction fleet orchestration.
A machine control system integrates positioning sensors, hydraulic actuators, and real-time kinematic correction software to automate blade, bucket, or drill positioning within sub-centimeter tolerances. These systems rely on multi-constellation GNSS receivers, inertial measurement units, and machine-specific valve controllers to eliminate rework in cut-and-fill operations. GPS Systems lead product type revenue by serving as the foundational positioning layer for nearly all automated grading and excavation workflows, while Motion Control Systems represent the fastest-growing category as hydraulic valve electrification replaces mechanical linkages. Construction dominates end user demand through giga-project earthwork volumes, though Mining commands the highest per-unit system values due to blasthole drilling precision requirements.
SFDA equipment safety frameworks in Saudi Arabia and UAE construction codes are mandating fail-safe hydraulic lockouts and encrypted telematics logging for autonomous machinery, effectively raising technical barriers to market entry. South Africa's Department of Mineral Resources and Energy enforces mine automation safety standards that require redundant positioning validation before personnel exclusion zone activation. Stakeholders must monitor how Gulf sovereign wealth infrastructure commitments reshape procurement specifications for interoperable fleet management platforms.
Market Dynamics
Gulf sovereign wealth infrastructure commitments are compressing procurement cycles for interoperable fleet management platforms, forcing vendors to pre-certify systems against SFDA-aligned safety protocols before contract bidding.
Growth Catalysts
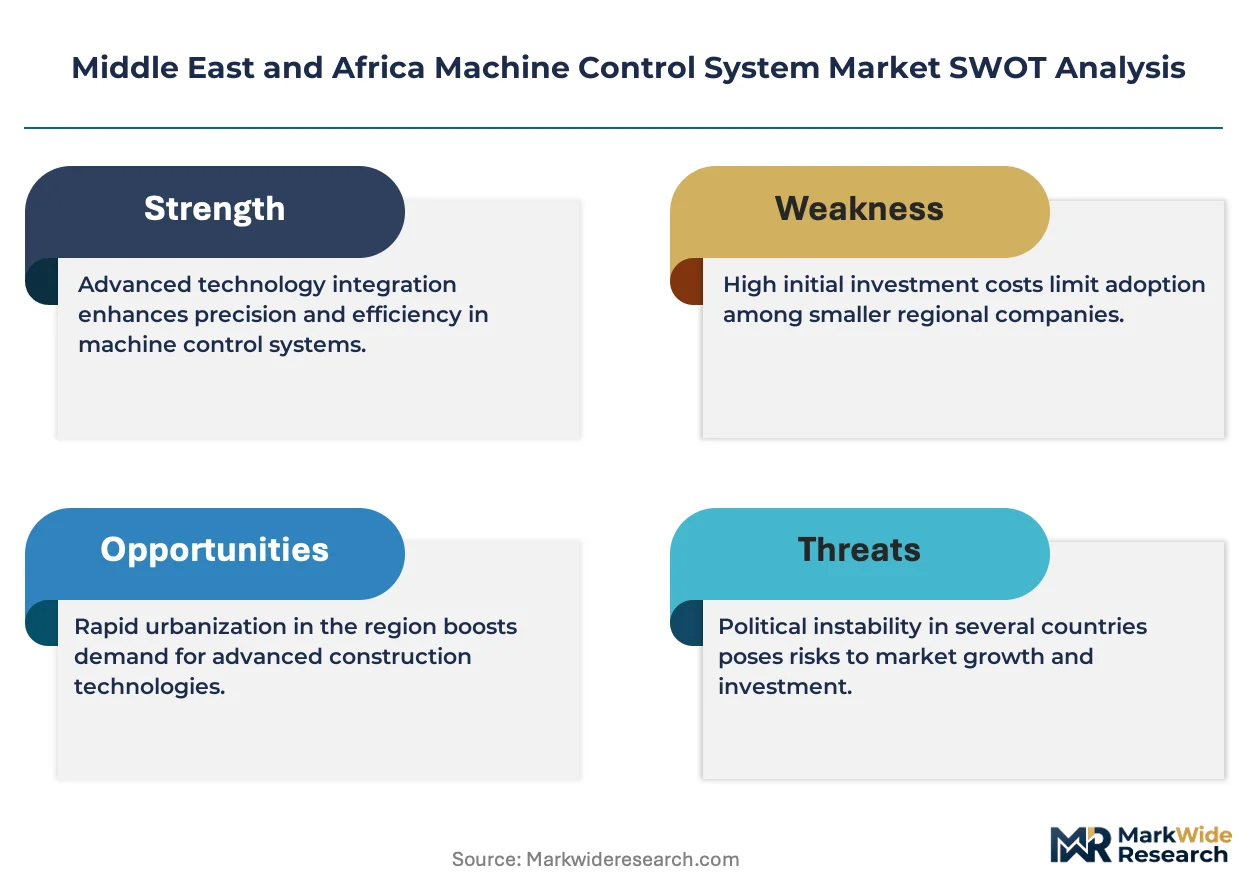
- Saudi giga-project pipeline:NEOM and Red Sea Project earthwork volumes are mandating GPS-guided fleet deployment for cut-and-fill precision at scale.
- SFDA equipment safety frameworks:Fail-safe hydraulic lockout mandates in Saudi Arabia and UAE construction codes are accelerating replacement of legacy mechanical control systems.
- Platinum belt automation:South Africa's open-pit mines are retrofitting manual grading operations with machine control systems to meet Department of Mineral Resources and Energy safety standards.
Market Restraints
- Multi-constellation GNSS receiver cost concentration:Precision positioning hardware depends on concentrated semiconductor supply chains in East Asia, exposing margins to input volatility.
- Redundant positioning validation requirements:South African mine automation standards mandate dual-sensor confirmation before personnel exclusion zone activation, doubling system complexity.
- Mechanical linkage installed base:Existing hydraulic fleets with cable-actuated valve controls present high retrofit friction against electrified motion control architectures.
Strategic Opportunities
- UAE autonomous machinery certification:Encrypted telematics logging mandates for construction fleets create first-mover advantage for vendors with pre-integrated data architectures.
- Composite sensor housing adoption:Desert corrosion environments are driving specification shifts from machined aluminum to hardened polymer enclosures in ruggedized machine control systems.
- Mine-to-construction software convergence:Blasthole drilling precision algorithms developed for platinum operations are transferable to giga-project excavation workflows.
Industry Challenges
- RTK correction network density gaps:Sparse CORS infrastructure outside Gulf urban corridors limits sub-centimeter positioning availability for remote earthmoving sites.
- Calibrated total station integration complexity:Third-party OEM hydraulic controller compatibility testing extends deployment timelines for mixed-fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Machine Control System Market |
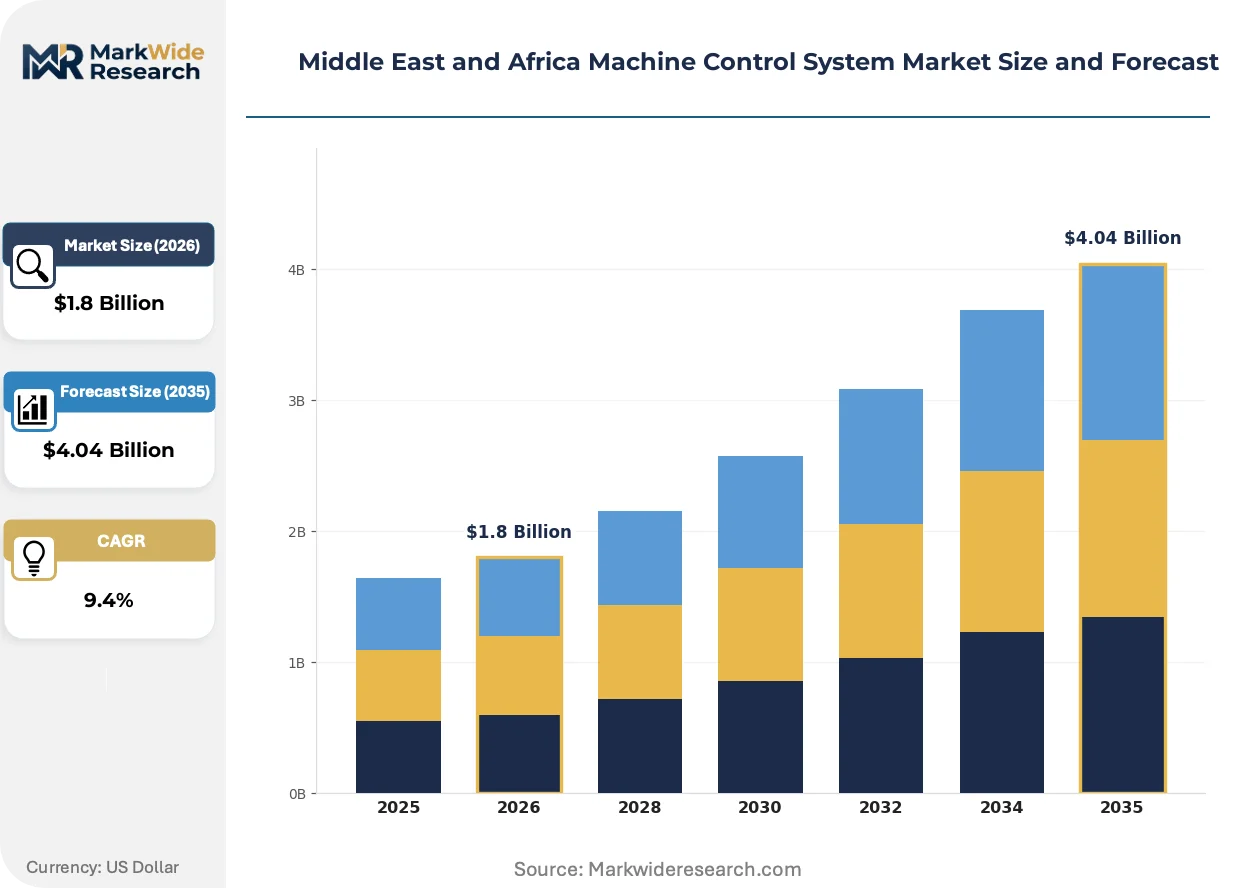
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Systems, Laser Systems, RFID Systems, Motion Control Systems End User: Construction, Agriculture, Mining, Aerospace Technology: Software-Based, Hardware-Based, Hybrid, Wireless Application: Field Management, Fleet Management, Resource Allocation, Surveying |
| Companies Covered | Trimble Inc, Leica Geosystems AG, Topcon Corp, Hexagon AB, MOBA Mobile Automation AG, Schneider Electric SE, Andritz AG, Hemisphere GNSS Inc, Komatsu Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Machine Control System Market Shifts & Advancements
Electrification of hydraulic valve architectures is compressing mechanical component supply chains while enabling software-defined blade positioning. Regulatory alignment with Gulf safety protocols is reshaping vendor certification roadmaps.
Electrified valve controllers are replacing mechanical linkages in earthmoving hydraulics. Saudi and UAE fleet operators are specifying these architectures for new giga-project equipment procurement. This shift is electrifying the motion control category fastest within the regional product mix.
SFDA-aligned equipment safety protocols now mandate encrypted telematics logging and fail-safe hydraulic lockouts for autonomous machinery. These requirements are raising technical barriers to market entry for uncertified vendors. Construction fleets in Saudi Arabia and UAE are responding by pre-qualifying suppliers against these frameworks in tender specifications.
Outcome-based fleet performance contracts are displacing capital equipment purchases for earthmoving operations. Rental and managed service providers are capturing procurement decision authority from project owners. This pattern concentrates most visibly in UAE megaproject contracting, where sovereign wealth entities prefer operational expenditure structures.
Middle East and Africa Machine Control System Market Segmentation
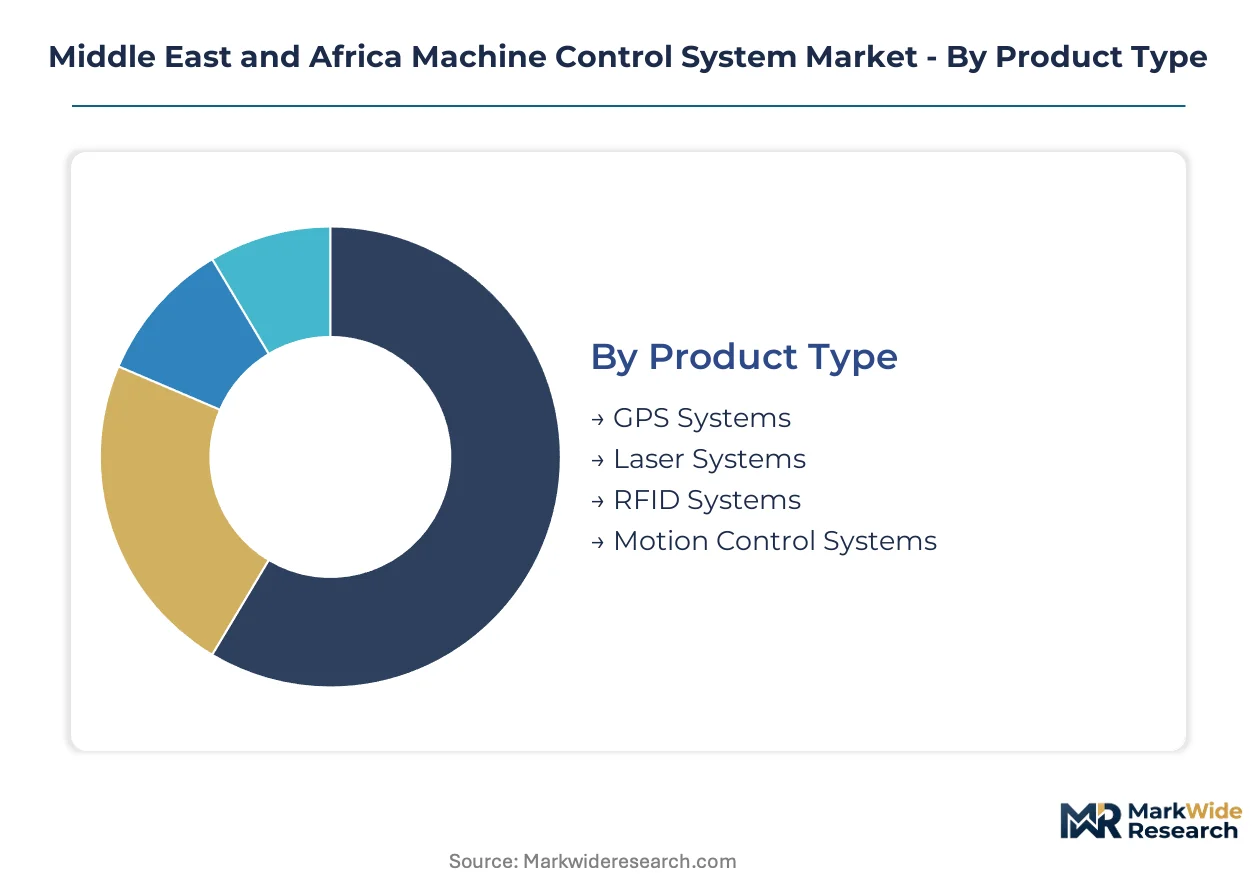
Machine control system procurement patterns across the Middle East and Africa diverge sharply by operational environment and regulatory exposure. Understanding these segment boundaries clarifies why GPS-guided earthmoving dominates Gulf construction while hybrid architectures penetrate South African mining.
Product Type:
Supply concentration in precision positioning hardware tilts procurement leverage toward vendors with captive GNSS correction networks.
- GPS Systems:Multi-constellation receivers with real-time kinematic correction serve as the foundational positioning layer for automated grading and excavation workflows. Demand concentrates in Saudi Arabia's NEOM and Red Sea Project earthwork fleets, where SFDA-mandated sub-centimeter tolerances exclude uncorrected satellite positioning.
- Motion Control Systems:Electrified hydraulic valve controllers replace mechanical linkages to enable software-defined blade positioning. South Africa's platinum belt mines are retrofitting cable-actuated fleets with these architectures to satisfy Department of Mineral Resources and Energy safety standards for personnel exclusion zones.
- Laser Systems:Grade control via rotating laser transmitters provides localized elevation reference for fine grading operations in urban UAE construction corridors.
- RFID Systems:Proximity-based machine identification supports asset tracking and operator authentication in mixed-fleet earthmoving deployments.
Today's leader: GPS Systems. Tomorrow's challenger: Motion Control Systems.
End User:
Application-specific safety mandates reshape vendor certification priorities across operational verticals.
- Construction:Giga-project earthwork volumes in Saudi Arabia and the UAE mandate GPS-guided fleet deployment for cut-and-fill precision at scale. SFDA-aligned equipment safety protocols now require fail-safe hydraulic lockouts and encrypted telematics logging, effectively pre-qualifying suppliers before tender participation.
- Mining:Blasthole drilling precision requirements command the highest per-unit system values in the regional product mix. South African open-pit platinum operations are retrofitting manual grading with redundant positioning validation before personnel exclusion zone activation.
- Agriculture:Precision planting and irrigation control applications in Morocco and Egypt drive demand for cost-optimized guidance systems.
- Agriculture:Autonomous tractor steering and implement control are gaining traction in large-scale commercial farming operations.
Construction commands current volume. Mining commands value per unit. Agriculture offers expansion bandwidth.
Technology:
Cost tier differentiation separates premium hybrid architectures from commodity hardware deployments.
- Hybrid:Integrated software-hardware stacks combine GNSS positioning with inertial measurement and machine-specific valve control. Gulf sovereign wealth infrastructure commitments are compressing procurement cycles for these interoperable platforms, forcing vendors to pre-certify against SFDA-aligned safety protocols before contract bidding.
- Software-Based:Cloud-connected fleet orchestration platforms enable outcome-based performance contracts that displace capital equipment purchases in UAE megaproject contracting.
- Hardware-Based:Standalone positioning receivers and valve controllers serve price-sensitive retrofit markets with limited connectivity requirements.
- Wireless:Mesh network architectures for real-time data transmission between machines and central coordination systems.
Hybrid architectures dominate premium tenders. Software-based solutions are climbing fastest in rental and managed service structures.
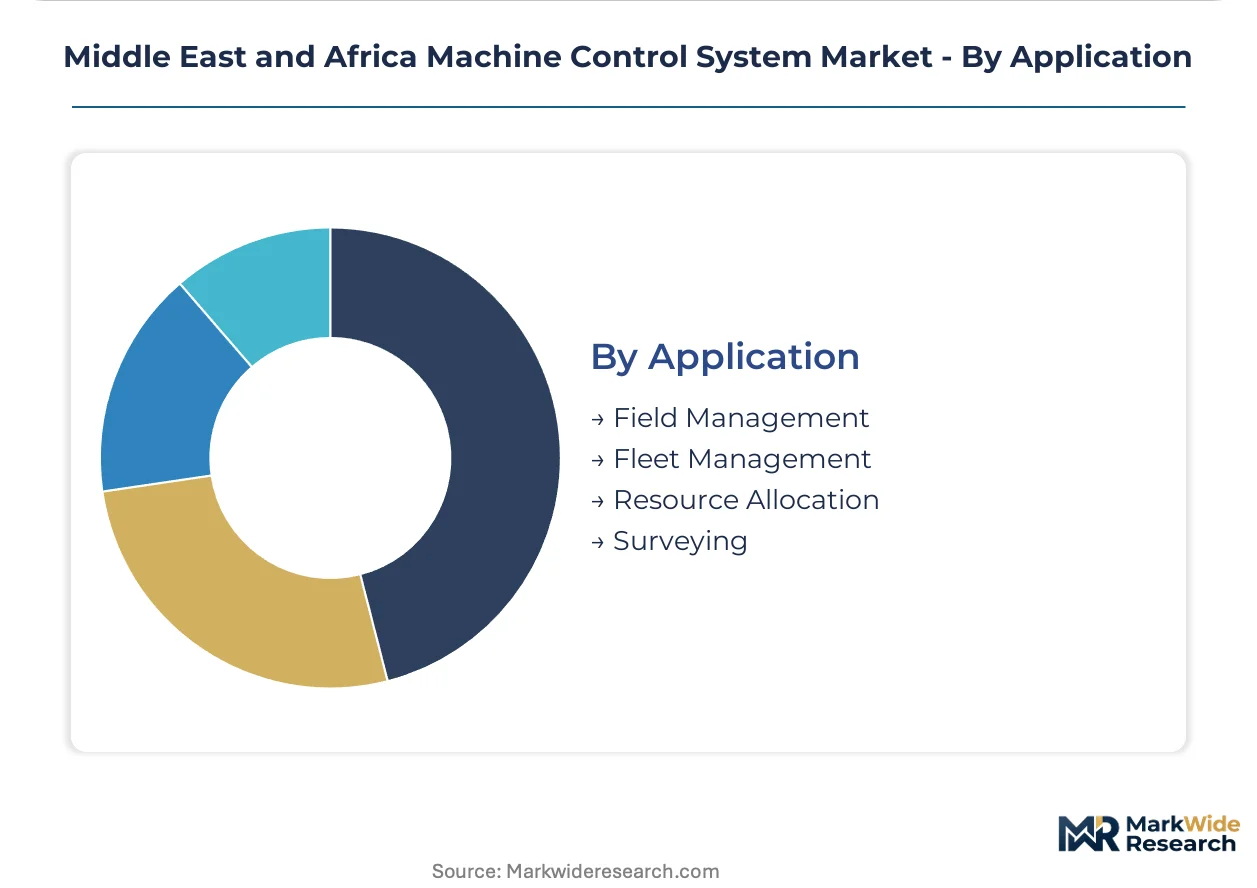
Application:
Customer type fragmentation separates project owner procurement from rental provider fleet management decisions.
- Fleet Management:Centralized coordination of machine positioning, maintenance scheduling, and operator assignment across distributed earthmoving assets. UAE sovereign wealth entities prefer operational expenditure structures that concentrate decision authority with rental and managed service providers.
- Field Management:Real-time cut-and-fill monitoring with automated grade verification eliminates rework in desert construction environments where material transport costs compound precision errors.
- Resource Allocation:Dynamic dispatch of earthmoving assets based on progress telemetry and soil condition feedback.
- Surveying:Calibrated total station integration with machine control systems for initial site characterization and as-built verification.
Fleet Management anchors procurement reform. Field Management delivers immediate productivity returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEOM anchors machine control system procurement across the Middle East and Africa, with Saudi Arabia's giga-project pipeline compressing vendor certification timelines against SFDA-aligned safety frameworks.
Saudi Arabia
NEOM and the Red Sea Project drive GPS-guided fleet deployment for cut-and-fill precision at unprecedented scale. SFDA equipment safety mandates now require fail-safe hydraulic lockouts and encrypted telematics logging before tender qualification. Riyadh-based earthmoving contractors are pre-certifying suppliers against these protocols to secure giga-project contracts.
United Arab Emirates
Dubai's megaproject contracting concentrates procurement authority with rental and managed service providers preferring operational expenditure structures. MOHAP-aligned construction codes mirror Saudi SFDA requirements for autonomous machinery certification. Abu Dhabi sovereign wealth infrastructure commitments are forcing vendors to pre-integrate data architectures for encrypted telematics compliance.
South Africa
The platinum belt around Rustenburg and Johannesburg drives open-pit automation retrofits replacing manual grading operations. Department of Mineral Resources and Energy safety standards mandate redundant positioning validation before personnel exclusion zone activation. Cape Town-based mining technology integrators are deploying hybrid GNSS-inertial systems to satisfy dual-sensor confirmation requirements.
Egypt
New Administrative Capital construction is accelerating demand for laser-guided fine grading in urban corridor earthworks. Egyptian building codes are tightening equipment safety specifications for autonomous machinery on government-funded infrastructure. Cairo-Giza metropolitan contractors are specifying motion control retrofits for legacy hydraulic fleets to meet emerging compliance deadlines.
Israel
Tel Aviv's precision agriculture sector deploys cost-optimized guidance systems for autonomous tractor steering in commercial farming operations. Israeli standards for agricultural machinery automation align with European CE marking protocols for electromagnetic compatibility. Haifa-based technology providers are integrating multi-constellation GNSS receivers with cloud-connected fleet orchestration platforms.
Middle East and Africa Machine Control System Market Competitive Landscape
Pre-certification against SFDA-aligned safety protocols dominates the current landscape as Gulf sovereign wealth infrastructure commitments compress procurement cycles. The vendor base stratifies between precision positioning specialists with captive GNSS correction networks and hydraulic control integrators with OEM valve controller partnerships. Two archetypes occupy distinct competitive positions: GNSS network operators leveraging correction density for high-precision earthmoving contracts, and motion control specialists electrifying legacy mechanical linkages. M&A activity concentrates on software-defined fleet orchestration capabilities, while strategic partnerships between positioning hardware vendors and hydraulic controller manufacturers accelerate mixed-fleet deployment timelines.
Within the precision positioning tier, Trimble Inc and Leica Geosystems AG exemplify contrasting geographic anchoring strategies. Sunnyvale-based Trimble Inc occupies a position tied to GNSS correction network density across Gulf Cooperation Council megaprojects. Swiss Leica Geosystems AG represents the calibrated total station integration approach, anchoring regional presence through third-party OEM hydraulic controller compatibility. Stockholm-based Hexagon AB sits within the mine-to-construction software convergence archetype, extending automation algorithms from South African platinum operations into Saudi giga-project excavation workflows.
| Leading Market Players |
|---|
| Trimble Inc |
| Leica Geosystems AG |
| Topcon Corp |
| Hexagon AB |
| MOBA Mobile Automation AG |
| Schneider Electric SE |
| Andritz AG |
| Hemisphere GNSS Inc |
| Komatsu Ltd |
| Others |
Supply & Pricing Matrix
Gulf sovereign wealth procurement programs concentrate buyer power among rental and managed service providers, locking pricing into outcome-based fleet performance contracts that displace per-unit transactional models across UAE megaprojects.
Pricing Analysis
Multi-constellation GNSS receiver cost concentration in East Asian semiconductor supply chains feeds input volatility directly into motion control system margins. Pricing stratifies across SFDA-certified premium tiers, redundant-sensor mining configurations, and economy-grade retrofit hardware for legacy mechanical fleets. Cost compression in standard-tier valve controllers is intensifying because electrified hydraulic architectures are displacing mechanical linkages faster than scale economies can absorb R&D amortization. Agriculture contractors in Morocco and Egypt exhibit highest price sensitivity, while platinum belt mining operations show least sensitivity due to personnel exclusion zone compliance mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Saudi giga-project earthmoving fleets, while third-party mining technology integrators in South Africa manage retrofit deployment for mixed-fleet operators. Precision positioning hardware draws from concentrated semiconductor fabrication in Taiwan, South Korea, and Japan. Composite sensor housing polymers and rare-earth magnet components for electrified valve actuators constitute critical input dependencies. Single-source vulnerability in RTK correction network infrastructure exposes remote earthmoving sites outside Gulf urban corridors to positioning availability gaps. Distribution runs through certified system integrators pre-qualified against SFDA-aligned safety protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreversible regulatory mandates for autonomous machinery safety certification across Gulf construction codes.
For Market Incumbents: Anticipate compressed procurement cycles by pre-integrating encrypted telematics architectures before tender release. SFDA equipment safety framework evolution threatens uncertified product lines; defend by accelerating backward integration into captive GNSS correction network density. Prioritize composite sensor housing manufacturing partnerships to secure desert corrosion-resistant enclosure supply. For New Entrants and Emerging Players: Rental and managed service providers represent the most accessible channel archetype for bypassing incumbent OEM relationships. White-space concentrates in Egyptian New Administrative Capital laser-guided fine grading retrofits and Israeli precision agriculture cost-optimized guidance systems. Pursue calibrated total station integration partnerships with third-party hydraulic controller manufacturers to accelerate mixed-fleet deployment timelines. For Investors and Strategic Acquirers: Construction technology divisions of multinational industrial conglomerates are the most active acquirer in this space, seeking software-defined fleet orchestration capabilities. Long-term viability rests on mine-to-construction algorithm transferability across operational verticals. Target acquisition profile centers on hybrid GNSS-inertial system developers with redundant positioning validation architectures. Monitor Gulf sovereign wealth infrastructure commitment acceleration as primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pre-Certification Investment | Accelerates tender qualification timelines for NEOM and Red Sea Project contracts. |
| Composite Sensor Housing Manufacturing Partnership | Secures supply of corrosion-resistant enclosures for desert deployment environments. |
| RTK Correction Network Density Expansion | Extends sub-centimeter positioning availability to remote earthmoving sites beyond Gulf urban corridors. |
| Mine-to-Construction Software Convergence | Transfers blasthole drilling precision algorithms from South African platinum operations into Saudi giga-project workflows. |
| Encrypted Telematics Architecture Integration | Satisfies UAE MOHAP-aligned autonomous machinery certification mandates for construction fleets. |
Research Methodology
Multiple input streams — earthmoving contractor procurement directors, mining technology integrators, OEM hydraulic controller engineering teams, and SFDA regulatory affairs specialists — were reconciled against equipment safety framework filings, customs import records for precision positioning hardware, and Gulf sovereign wealth infrastructure commitment disclosures. Secondary validation drew from construction fleet telematics databases, mining automation safety standard documentation, and regional trade association equipment deployment surveys. Bottom-up unit economics for GPS-guided fleet deployments were cross-checked against top-down market sizing from giga-project earthwork volume announcements.
Historical adoption curves for electrified hydraulic valve architectures were cross-referenced against panel input from rental provider fleet managers regarding outcome-based contract structuring. Segmentation modeling spanned product type, end user vertical, technology tier, and application function across the projection horizon. CAGRs were derived from elasticity-adjusted penetration assumptions tied to regulatory compliance deadlines and infrastructure commitment acceleration patterns. Forecast inputs incorporated SFDA equipment safety framework implementation timelines and Department of Mineral Resources and Energy mine automation standard enforcement intensity.
Revisions become necessary when Gulf sovereign wealth infrastructure commitment schedules shift, SFDA safety protocol technical specifications change, or semiconductor supply chain disruptions alter multi-constellation GNSS receiver availability. Forecasts reflect assumptions regarding regulatory enforcement consistency and giga-project earthwork volume realization. Periodic stress-testing of base assumptions against platinum belt automation retrofit completion rates and UAE megaproject operational expenditure structuring preferences is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Intralogistics Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Digital Industrial Scales Market