
 Luxury Kitchen Appliances Market | 2026-2036
Luxury Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Kitchen Appliances Market Analysis
Specialty retail and direct-to-consumer channels for premium kitchen equipment is fragmenting as digital showrooms and brand-owned flagship stores compete for high-touch customer relationships. Miele sustains its position through intensive R&D investment in sensor-driven cooking systems. Wolf anchors North American demand with its manufacturing scale in domestic production facilities. Gaggenau differentiates through European design heritage and modular built-in configurations.
Luxury kitchen appliances encompass high-performance domestic cooking, refrigeration, and cleaning equipment engineered to commercial-grade specifications with premium material compositions such as surgical-grade stainless steel and solid copper cores, designed for residential and semi-professional environments demanding precision temperature control and extended operational lifespan. Refrigerators and built-in ovens command the largest margin pools due to their central role in kitchen architecture and replacement cycles. Smart functionality represents the fastest-expanding dimension as connectivity protocols and app-based remote operation become standard expectations among luxury condominium developers.
The U.S. Department of Energy sets minimum efficiency thresholds that manufacturers must exceed to access the premium tier, while the EU Ecodesign Directive and REACH framework constrain material choices and energy consumption profiles for products sold in member states. China's GB standards and SAMR certification requirements create additional compliance layers for imported luxury brands seeking market entry. Stakeholders must monitor how evolving interoperability standards between smart home ecosystems reshape product development roadmaps and partnership strategies.
Market Dynamics
Energy efficiency mandates from the EU Ecodesign Directive and U.S. DOE appliance standards are compressing replacement cycles among high-net-worth homeowners, forcing manufacturers to accelerate R&D timelines for sensor-integrated cooking platforms.
Growth Catalysts
- EU Ecodesign Framework:Tightening energy efficiency thresholds are compelling luxury condominium developers to specify premium appliances that exceed baseline compliance, creating specification pull-through in Germany and France.
- Chef-driven hospitality:Michelin-starred restaurants and boutique hotels are sourcing residential-grade commercial equipment, blurring the line between professional and domestic kitchen specifications.
- Solid copper core induction:Advances in thermal conductivity materials are enabling precision temperature control that attracts semi-professional home cooks seeking commercial-grade performance.
Market Restraints
- Surgical-grade stainless steel supply:Concentration of specialty steel production in select European and East Asian foundries creates input cost volatility and extended lead times for premium finishes.
- REACH material constraints:The EU's chemical registration framework restricts certain coating compounds and solder materials, forcing reformulation of legacy product lines.
- Smart home ecosystem fragmentation:Proprietary connectivity protocols from competing platforms prevent seamless integration, reducing perceived value of connected appliance suites.
Strategic Opportunities
- China's GB standards evolution:Rising domestic certification requirements for imported luxury brands create first-mover advantage for early compliance investments in tier-one cities.
- Digital showroom channels:Augmented reality configuration tools and virtual kitchen visualization are displacing traditional dealer networks for initial specification decisions.
- Modular built-in configurations:Flexible appliance architectures that adapt to compact urban kitchens address space constraints in dense metropolitan housing stock.
Industry Challenges
- Embedded systems engineering talent:Scarcity of firmware developers with appliance-specific expertise delays smart functionality deployment timelines.
- Interoperability certification backlog:Testing queue congestion at certification bodies for Matter and Thread protocol compliance extends product launch windows.
- Legacy kitchen infrastructure retrofit:Electrical panel upgrades and ventilation modifications required for high-performance induction and steam ovens create installation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Kitchen Appliances Market |
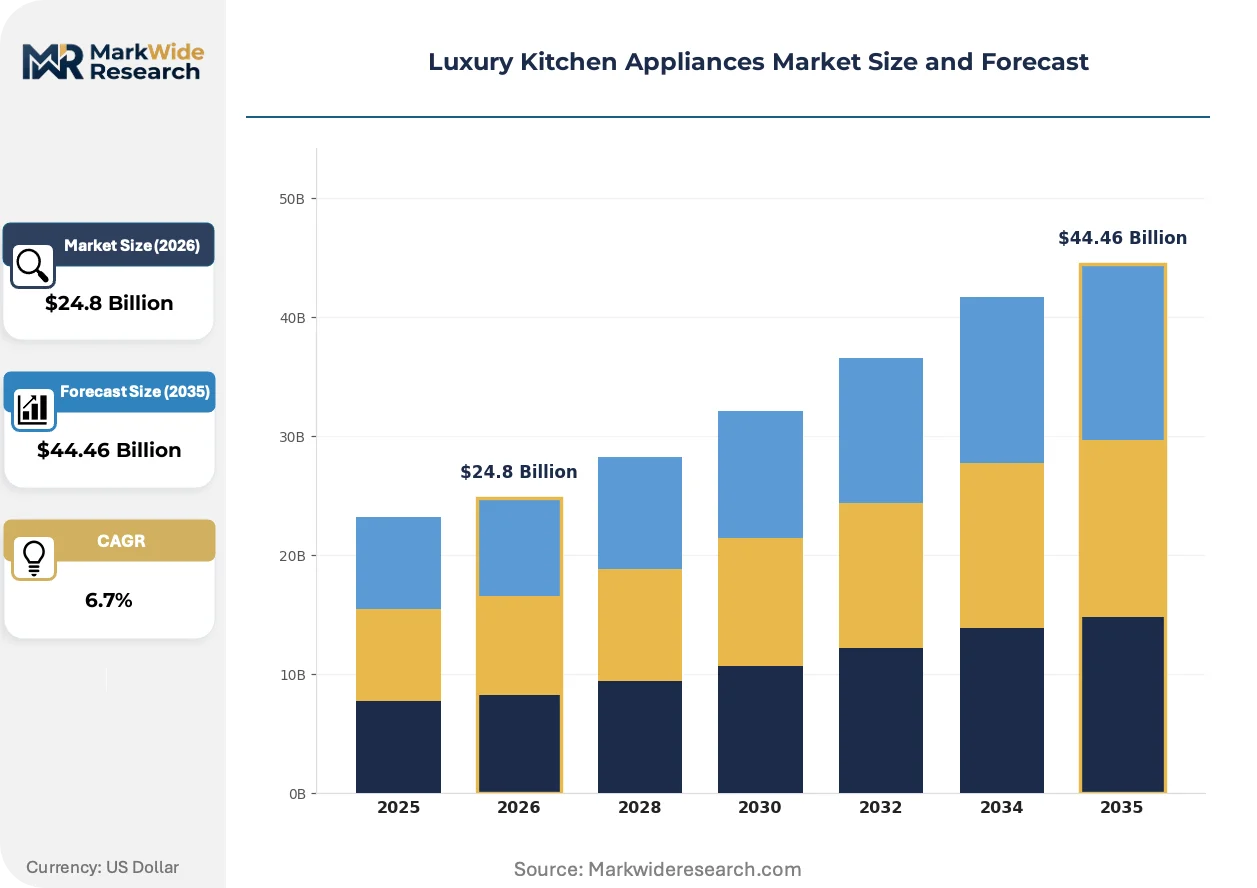
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Cooktops Material: Stainless Steel, Glass, Copper, Cast Iron Functionality: Smart Features, Energy Efficiency, Multi-Cooking, Built-In End User: Homeowners, Luxury Condominiums, Chefs, Hospitality |
| Companies Covered | Miele, Monogram, Sub-Zero, BlueStar, SKS, Wolf, Thermador, Fisher & Paykel, Gaggenau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Kitchen Appliances Market Emerging Trajectories
Sensor-driven automation and predictive maintenance algorithms are redefining the ownership experience, shifting competitive advantage from hardware durability to software-enabled performance optimization.
AI-powered cooking assistants that adjust temperature and timing based on real-time food recognition are collapsing the expertise gap between amateur and professional home preparation. Luxury developers in Manhattan and London are specifying these systems as standard amenities. The technology is collapsing the traditional segmentation between entry-level and premium appliance tiers by democratizing precision cooking.
The U.S. DOE appliance standards are tightening minimum efficiency thresholds for refrigeration and cooking equipment, forcing manufacturers to redesign compressor architectures and insulation systems. Products that barely cleared prior thresholds now face market exclusion. Built-in refrigerator categories face the steepest compliance cost increases, with engineering teams prioritizing variable-speed compressor deployment.
Direct-to-consumer configuration platforms are displacing traditional kitchen design studios for initial appliance selection. High-net-worth buyers in Miami and Dubai are completing entire kitchen specifications through brand-owned digital interfaces before engaging contractors. This channel shift concentrates customer data with manufacturers, enabling predictive inventory positioning and personalized upgrade cycles.
Luxury Kitchen Appliances Market Segmentation
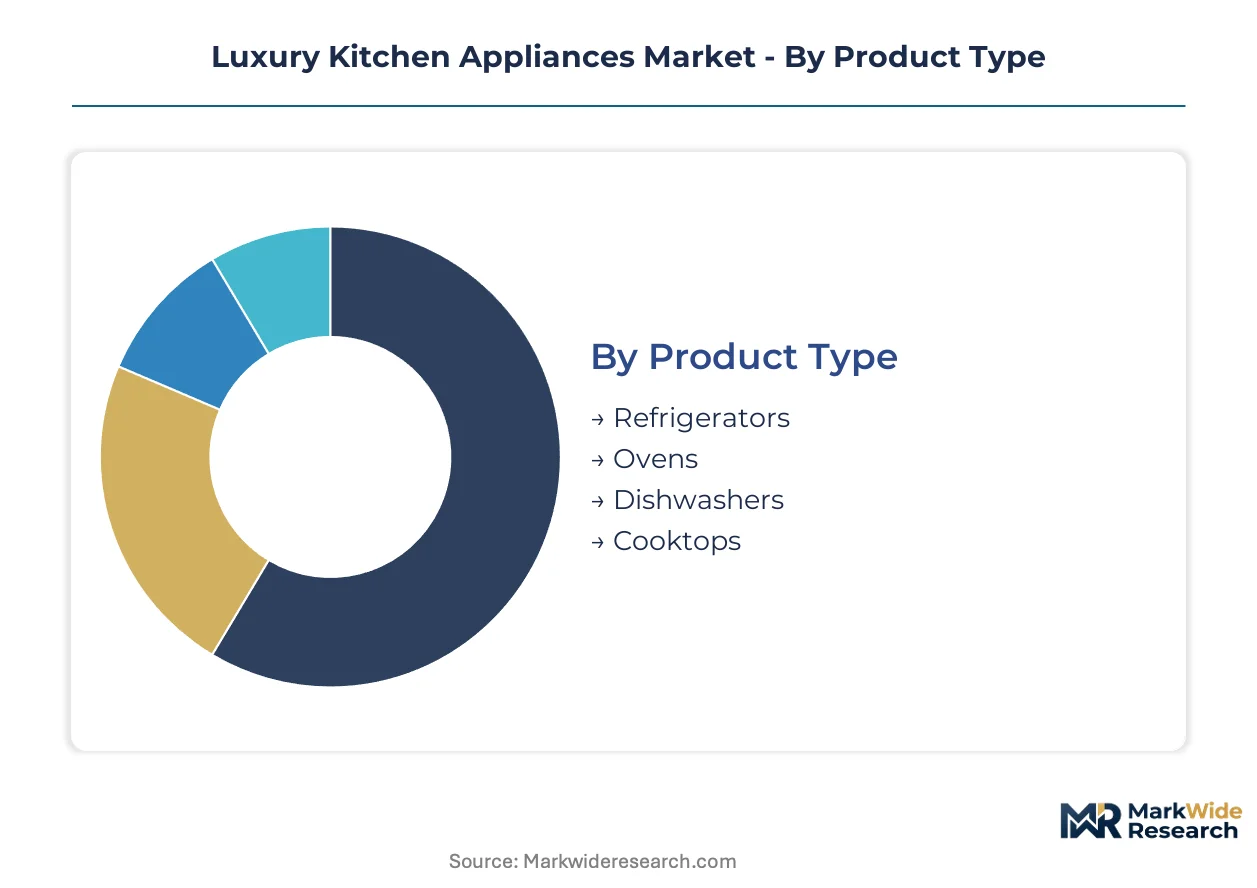
Segmentation in luxury kitchen appliances reveals how replacement cycles, material costs, and specification authority vary dramatically across buyer types and product categories. Understanding these divides helps manufacturers allocate R&D investment and channel resources where margin concentration and growth velocity align.
Product Type:
Refrigerators and ovens command the longest replacement cycles at 12-15 years, while cooktops and dishwashers turn over faster as technology refresh and finish preferences shift.
- Refrigerators:Built-in column and French door configurations anchor kitchen architecture decisions. Demand concentrates in luxury condominium developments across Manhattan and Miami, where developers specify variable-speed compressor systems to meet U.S. DOE efficiency thresholds.
- Ovens:Steam-assisted and precision thermal systems define the premium tier. German and French residential markets drive specification of sensor-driven cooking platforms that exceed EU Ecodesign baseline compliance.
- Dishwashers:Quiet-operation ratings and third-rack flexibility differentiate premium offerings. Urban kitchen retrofits in London and Dubai prioritize compact footprints with commercial-grade wash cycles.
- Cooktops:Induction with solid copper core construction enables professional-grade temperature response. Semi-professional home cooks in California and Sydney specify these for precision control.
Refrigerators dominate installed base value. Cooktops are where expansion concentrates as induction conversion accelerates.
Material:
Input cost volatility and finish durability create divergent margin profiles across material tiers, with specialty metals commanding premium positioning.
- Stainless Steel:Surgical-grade compositions with brushed or polished finishes remain the default for professional aesthetics. REACH compliance constraints on coating compounds force European manufacturers toward electropolished alternatives.
- Glass:Ceramic and tempered glass surfaces enable seamless countertop integration. Chinese luxury developments in Shanghai and Shenzhen specify these for minimalist kitchen architectures.
- Copper:Solid core induction elements deliver unmatched thermal conductivity. Supply concentration in select European foundries creates lead time volatility for premium cooktop producers.
- Cast Iron:Traditional enameled surfaces persist in heritage-design segments. French country-style residential specifications in Provence and Normandy sustain niche demand.
Stainless steel commands volume share. Copper is climbing the fastest as performance specifications tighten.
Functionality:
Smart connectivity and energy compliance represent the primary axes of product differentiation, with built-in configurations commanding specification priority.
- Smart Features:App-based remote operation and AI-powered cooking assistants integrate with home automation ecosystems. Matter protocol certification delays create launch friction for connected suites.
- Energy Efficiency:Variable-speed compressors and advanced insulation systems exceed regulatory baselines. EU Ecodesign Directive thresholds force redesign of legacy refrigeration platforms.
- Multi-Cooking:Combination steam-convection and sous-vide capabilities collapse multiple appliances into single units. Compact urban kitchens in Tokyo and Singapore drive adoption.
- Built-In:Panel-ready and modular configurations integrate with custom cabinetry. German kitchen studios specify these for seamless aesthetic continuity.
Built-in dominates specification value. Smart features are gaining share fastest as developer standards evolve.
End User:
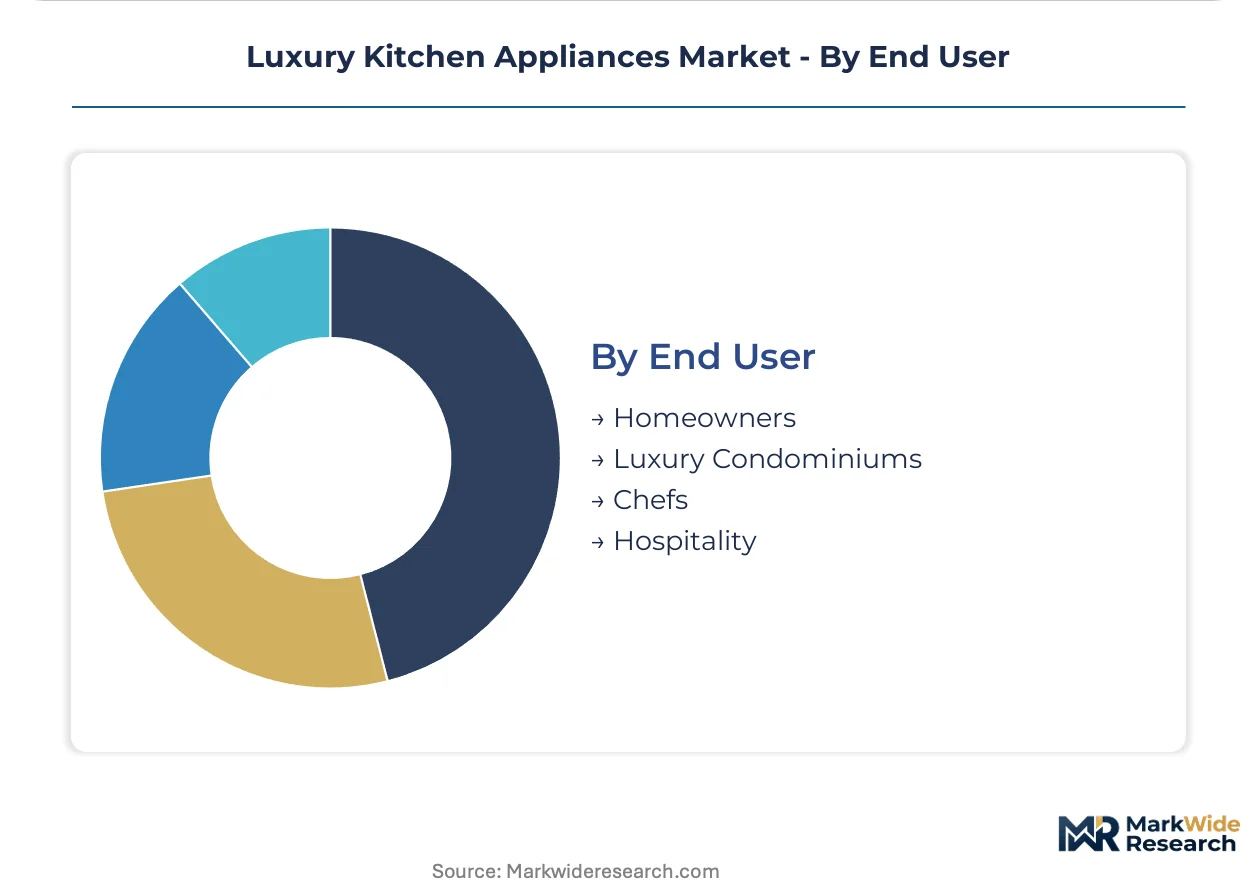
Specification authority and replacement timing diverge sharply between owner-occupied and developer-driven purchase cycles.
- Homeowners:Discretionary upgrade decisions respond to kitchen renovation timelines and technology refresh. U.S. high-net-worth households in Texas and Florida drive replacement of pre-efficiency-mandate appliances.
- Luxury Condominiums:Developers specify appliance suites as standard amenities during pre-construction. Manhattan and London projects now mandate smart-enabled cooking platforms.
- Chefs:Semi-professional home cooks seek commercial-grade performance in residential footprints. Michelin-starred restaurant alumni in California and New York influence specification trends.
- Hospitality:Boutique hotels and chef-driven restaurants source residential-grade equipment for suite kitchens. Dubai and Miami hospitality developments blur professional-domestic boundaries.
Homeowners anchor replacement volume. Luxury condominiums are where specification standards concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium appliance pricing power concentrates in Manhattan and London condominium developments, while cost-sensitive retrofit demand in secondary U.S. metros compresses margin structures. This geographic asymmetry shapes manufacturer channel strategies and specification priorities across the analysis window.
United States
High-net-worth homeowners in Texas and Florida are accelerating replacement cycles ahead of U.S. DOE efficiency mandate deadlines. The Department of Energy's tightening appliance standards are disqualifying legacy refrigeration platforms from premium positioning. Miami luxury developments specify smart-enabled cooking suites as standard amenities, pulling specification authority toward developers.
Germany
EU Ecodesign Directive thresholds are compelling luxury condominium developers in Berlin and Munich to specify appliances that exceed baseline compliance. The REACH framework constrains coating compounds and solder materials, forcing reformulation of legacy product lines. Bavarian kitchen studios anchor demand for modular built-in configurations with seamless cabinetry integration.
China
Tier-one city developers in Shanghai and Shenzhen specify glass-surface appliances for minimalist luxury architectures. SAMR certification requirements and evolving GB standards create compliance layers for imported brands seeking market entry. Yangtze River Delta manufacturing clusters are expanding domestic production capacity for premium induction systems.
United Kingdom
London residential developments mandate connected appliance suites as amenities for international buyer pools. The UK's post-Brexit regulatory alignment with EU Ecodesign frameworks maintains efficiency pressure on imported equipment. Greater Manchester and Birmingham retrofit markets face installation friction from legacy electrical infrastructure requiring panel upgrades.
United Arab Emirates
Dubai hospitality developments source residential-grade commercial equipment for suite kitchens, blurring professional-domestic boundaries. MOHAP and local standards bodies are developing certification frameworks for smart home interoperability. Abu Dhabi luxury residential towers specify European heritage brands for prestige positioning in Gulf buyer segments.
Luxury Kitchen Appliances Market Vendor Landscape
Heritage European manufacturers and North American scale producers split the market along design-authenticity versus manufacturing-efficiency axes. The vendor base concentrates around three strategic archetypes: R&D-intensive sensor-platform specialists, domestic-production-scale anchors, and European design-heritage modularists. Competitive moves center on digital showroom channel expansion and smart home ecosystem partnership formation.
Within the heritage-tier, Gaggenau exemplifies European design-authenticity positioning through modular built-in specialization. Miele occupies the R&D-intensive archetype with sensor-driven cooking platform investment. Wolf anchors North American demand through domestic manufacturing scale. These three represent the strategic poles around which specification decisions cluster in luxury condominium developments.
| Leading Market Players |
|---|
| Miele |
| Monogram |
| Sub-Zero |
| BlueStar |
| SKS |
| Wolf |
| Thermador |
| Fisher & Paykel |
| Gaggenau |
| Others |
Supply Flow & Price Mechanics
European specialty steel foundries in Germany and Italy concentrate production of surgical-grade stainless steel and solid copper cores, anchoring margin pools in built-in refrigerator and precision cooktop categories where material composition commands specification premiums. This upstream concentration transfers pricing power to manufacturers with captive supplier relationships or long-term offtake agreements, while buyers without such arrangements absorb volatility through configured-to-order premiums.
Pricing Analysis
Configured-to-order pricing spreads 25-40% above standard SKUs for panel-ready refrigerator columns and modular oven stacks. Three-tier pricing structure across premium, standard, and economy levels segments by smart functionality depth and energy efficiency certification tier. Cost compression in entry-level induction cooktops is intensifying because Yangtze River Delta manufacturing clusters are expanding domestic capacity. Luxury condominium developers show lowest price sensitivity, while individual homeowners in secondary U.S. metros drive hardest bargain on replacement cycles.
Supply Chain Analysis
Export-control regimes on advanced sensor arrays and semiconductor components for AI-powered cooking platforms limit technology flows from U.S. and EU suppliers to Chinese manufacturing partners. Component sourcing draws from Germany for precision thermal sensors, Italy for compressor systems, and South Korea for display modules. Single-source vulnerability concentrates in solid copper core supply from select European foundries. Distribution runs through brand-owned flagship stores and digital showrooms displacing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxury kitchen appliances sit in early-cycle expansion as smart functionality penetration in new condominium developments accelerates specification pull-through ahead of replacement-driven demand. Induction conversion and AI-assisted cooking platforms are expanding addressable premium tiers beyond traditional hardware upgrade cycles.
For Market Incumbents: Build switching-cost moats through proprietary smart home ecosystem integration and predictive maintenance subscription bundles. Deepen backward integration into surgical-grade stainless steel finishing to secure supply continuity against REACH reformulation costs. Expand domestic production footprint in South Carolina or Tennessee to hedge tariff exposure on European-sourced refrigeration platforms. Sensor-integrated cooking patents and Matter protocol certification backlog create defensive barriers against Asian appliance conglomerates.
For New Entrants and Emerging Players: Build out direct-to-consumer configuration platforms with augmented reality visualization tools to bypass entrenched dealer relationships in Miami and Dubai. Target hospitality suite kitchen specifications where professional-domestic boundaries blur and brand heritage requirements relax. White-space exists in compact modular systems for Tokyo and Singapore urban kitchens where incumbent portfolios over-index on large-format built-in configurations. Go-to-market through chef-influencer partnerships leverages credibility transfer from Michelin-starred alumni.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European design-heritage brands struggling to fund smart platform R&D against Miele and Wolf scale advantages. Five-to-ten-year viability hinges on successful ecosystem partnership formation rather than standalone software development. Acquisition targets with Matter protocol certification completion and existing luxury condominium developer relationships offer fastest path to specification relevance. Watch for inflection when tier-one city developers in Shanghai and Shenzhen mandate AI-powered cooking assistants as standard amenities.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Ecosystem Partnership | Matter protocol integration with Apple HomeKit and Google Nest collapses connectivity fragmentation for specification pull-through. |
| Domestic Manufacturing Scale-Up | South Carolina production expansion insulates Wolf and Sub-Zero from EU Ecodesign compliance cost pass-through. |
| Direct-to-Consumer Platform Launch | Brand-owned digital showrooms in Miami and Dubai capture customer data for predictive inventory positioning. |
| Backward Integration into Specialty Metals | Captive supply of surgical-grade stainless steel secures margin against REACH coating compound restrictions. |
| Modular Built-In Configuration Extension | Flexible appliance architectures address space constraints in Manhattan and London luxury condominium retrofits. |
Methodological Framework
Initial hypotheses were tested against primary input from luxury condominium developers, kitchen studio specification consultants, hospitality procurement directors, and high-net-worth homeowner renovators and refined through secondary validation. Primary fieldwork encompassed structured interviews across Manhattan, Miami, London, Berlin, and Shanghai markets. Secondary sources included U.S. DOE appliance standard filings, EU Ecodesign Directive implementation reports, SAMR certification databases, and trade customs data for surgical-grade steel and copper component flows. Bottom-up unit economics and top-down macroeconomic triangulation converged on segment-level demand estimates.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, material composition, functionality tier, and end-user specification authority. CAGRs derived from replacement cycle velocity, regulatory compliance deadline clustering, and smart feature adoption curves. Industry-specific inputs incorporated U.S. DOE efficiency threshold phase-in schedules and EU REACH substance restriction timelines.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem exclusivity moves by Amazon Alexa or Google Nest would shift outcomes beyond modeled parameters. Material shifts in China's GB standards evolution or U.S. tariff regime on European steel would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Toaster Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Residential Induction Cooktops Market