
 Toaster Market | 2026-2036
Toaster Market Size, Share, and Industry Trends Forecast 2026-2036
Toaster Market Intelligence
REACH compliance is recalibrating the cost-of-entry calculus for toaster manufacturers seeking European market access. Panasonic Corporation leverages its vertical integration in heating element production to absorb regulatory testing costs without margin erosion. Hamilton Beach Brands anchors its competitive stance through mass-market channel control across North American big-box retailers, while Breville Group Ltd. differentiates via R&D intensity in smart-toaster interfaces and premium material specifications.
A toaster is an electric appliance employing resistive heating elements, typically nichrome wire rated between 600 and 1800 watts, to brown bread slices through radiant and convective heat transfer. Its primary commercial purpose spans residential breakfast preparation and high-throughput foodservice operations in hotels, cafeterias, and quick-service restaurants. Pop-up toasters occupy the largest volume share in residential settings due to compact footprint and price accessibility, while toaster ovens command the fastest expansion as consumers prioritize multi-function countertop appliances. Conveyor toasters dominate margin pools in commercial channels where throughput requirements and durability standards justify premium pricing.
The EU Ecodesign Regulation and CE marking framework shape product standards by mandating standby power limits and material recyclability disclosures for small domestic appliances sold across member states. The US EPA ENERGY STAR program and state-level California Energy Commission standards further segment market access by efficiency tier. Stakeholders must monitor divergence between regional efficiency test protocols and embedded carbon reporting rules when configuring platform architectures for cross-border deployment.
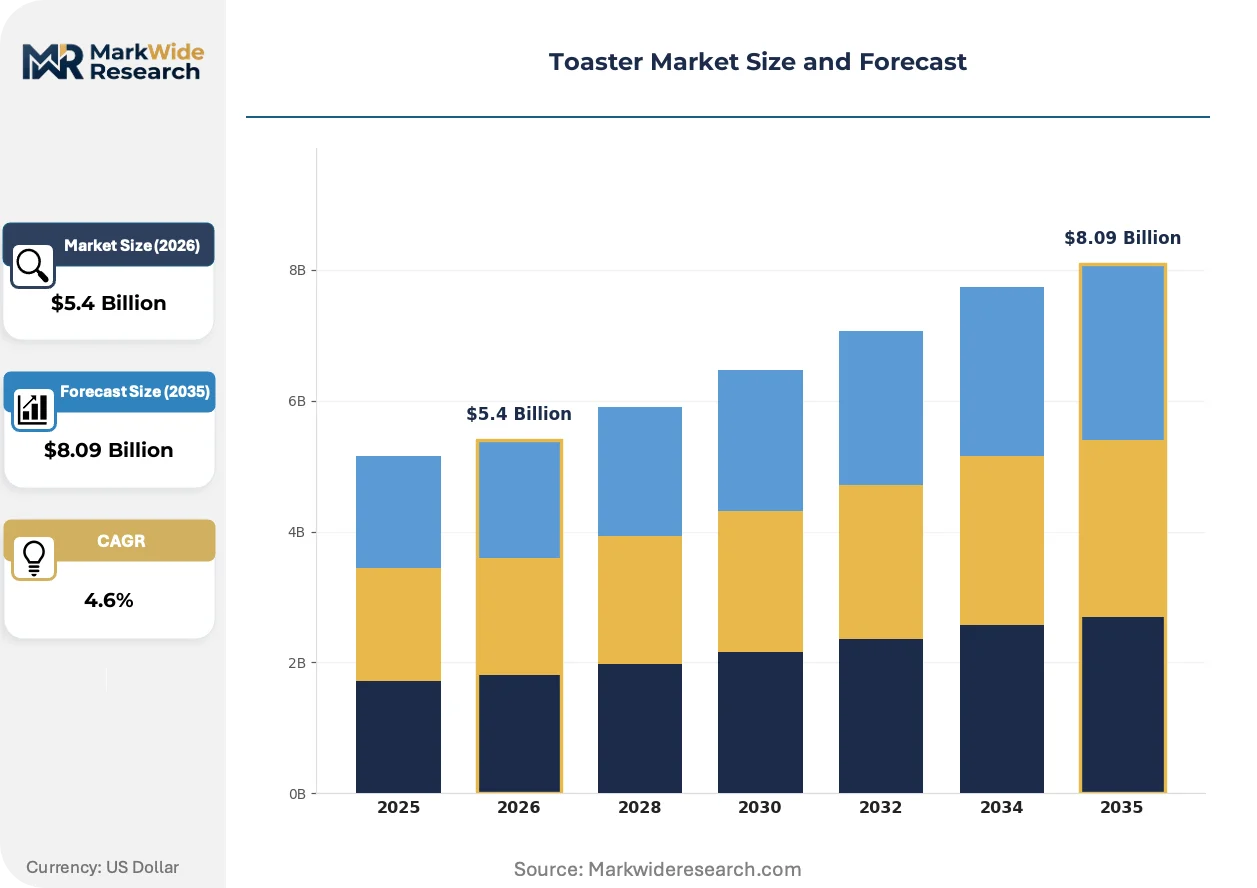
Market Dynamics
The EU Ecodesign Regulation is compressing replacement cycles for energy-inefficient units while simultaneously raising capital requirements for compliance testing, forcing manufacturers to absorb margin pressure or exit the European market entirely.
Growth Catalysts
- Residential kitchen renovations:Urban apartment complexes in Germany are accelerating unit turnover as sustainability-certified housing stock mandates appliance upgrades.
- Multi-function appliance demand:Consumer preference for countertop versatility is expanding toaster oven penetration beyond traditional pop-up formats.
- CE marking harmonization:Unified EU product standards are reducing cross-border certification friction for small domestic appliances.
Market Restraints
- Nichrome wire cost volatility:Heating element raw material prices fluctuate with nickel and chromium spot markets, squeezing component margins.
- Supply concentration in East Asian component hubs:Resistive element and electronic control module production clusters create single-source vulnerability.
- Standby power limits:EU Ecodesign standby thresholds add engineering complexity for entry-tier products.
Strategic Opportunities
- Connected kitchen ecosystems:Smart-toaster interfaces integrating with voice assistants and recipe apps open premium pricing tiers.
- Commercial foodservice throughput gaps:Conveyor toaster durability specifications exceed current supply in high-volume hotel and cafeteria channels.
- Material recyclability mandates:EU material disclosure rules favor manufacturers with established circular supply chains.
Industry Challenges
- Embedded firmware certification timelines:CE marking for software-controlled heating algorithms extends product development cycles.
- Cross-regional efficiency test protocol divergence:EU Ecodesign, US EPA ENERGY STAR, and California Energy Commission standards require parallel validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toaster Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.09 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pop-Up Toaster, Conveyor Toaster, Toaster Oven, Specialty Toaster, Extra-Wide Slot Toaster Technology: Electrical Heating, Quartz Heating, Halogen Heating, Convection Heating, Infrared Heating Power Rating: Low Power, Medium Power, High Power, Ultra High Power Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales, Home Appliance Dealers |
| Companies Covered | Panasonic Corporation, Hamilton Beach Brands, Koninklijke Philips N.V., Black+Decker, Cuisinart, Breville Group Ltd., De'Longhi Appliances S.r.l., Smeg, KitchenAid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toaster Market Strategic Shifts & Innovations
Heating element architecture and control system integration are the primary vectors of product differentiation, with regulatory pressure on standby consumption and material traceability accelerating R&D investment intensity.
Silicon carbide heating element technology is modularizing traditional nichrome wire configurations. Premium residential buyers and commercial foodservice operators are adopting these elements for faster thermal response and extended duty cycles. This shift is modularizing the supplier base as semiconductor-grade ceramic manufacturers enter appliance component markets.
REACH substance restrictions are tightening disclosure requirements for coatings and adhesives in heating element assemblies. Industrial consequence includes mandatory supply chain auditing for chromium compounds and nickel alloys. German and French housing renovation subsidies are most affected, with distributors now requiring full material passports before stocking.
Buyer concentration among big-box retailers is compressing manufacturer margin structures. Direct-to-consumer channels and specialty kitchen retailers are displacing traditional wholesale relationships for premium and smart-enabled units. This pattern is most visible in North American and German urban markets where online research precedes purchase decisions.
Toaster Market Segmentation
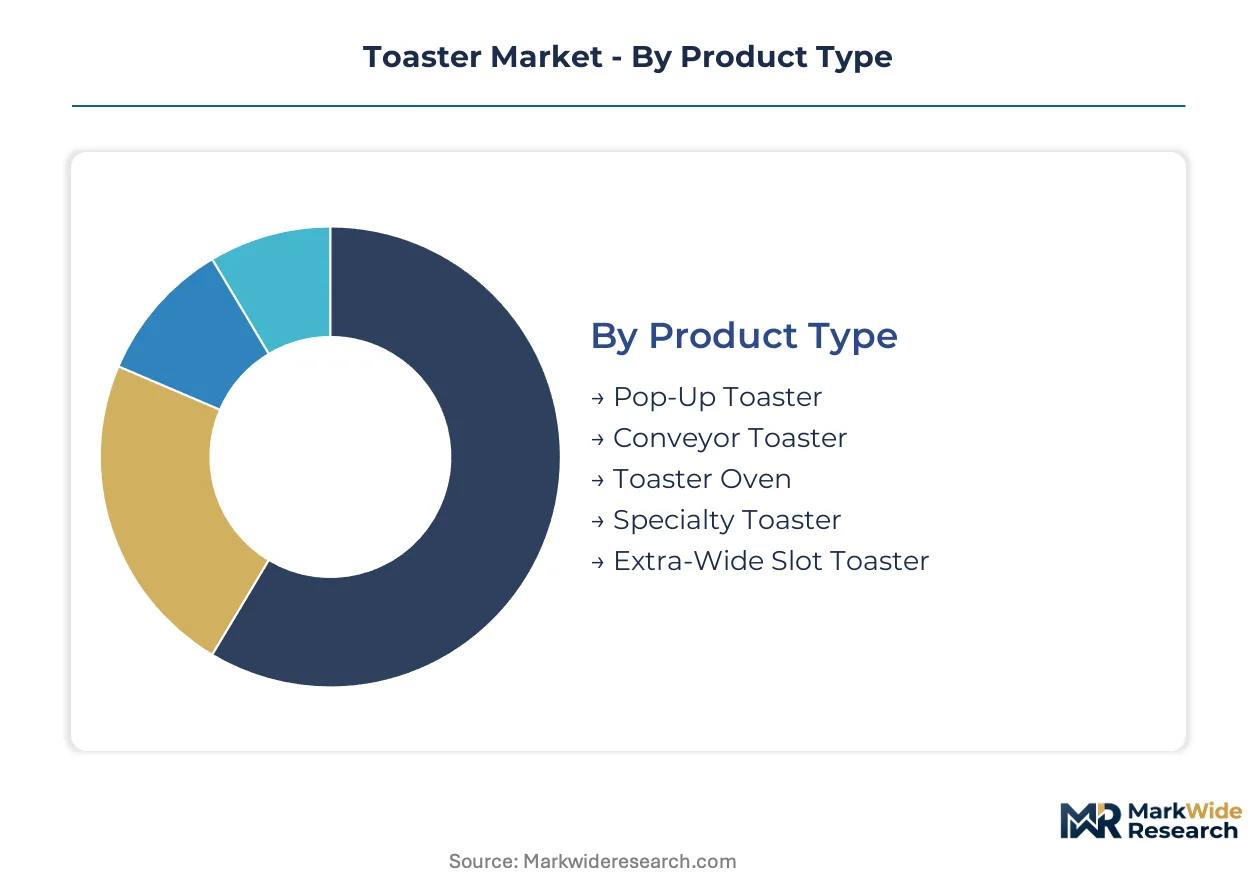
Toaster market segmentation reveals how heating technology, power architecture, and channel configuration shape procurement decisions across residential and commercial end-uses. Product format and distribution access determine margin capture and replacement cycle velocity in distinct buyer environments.
Product Type:
Heating element architecture and footprint dimensions define functional utility across residential breakfast preparation and commercial foodservice throughput requirements.
- Pop-Up Toaster:Vertical slot configuration with nichrome wire elements rated 600-1200 watts dominates residential volume due to compact countertop footprint and sub-$50 price accessibility. German urban apartment renovations and sustainability-certified housing stock in France are accelerating replacement cycles for energy-rated units.
- Conveyor Toaster:Continuous belt feed systems with extended-duty nichrome or silicon carbide elements rated 1800-3500 watts serve hotel breakfast buffets and cafeteria high-throughput operations. Commercial channel durability specifications justify premium pricing tiers unavailable to residential formats.
- Toaster Oven:Enclosed cavity with multiple heating element configurations enables baking, broiling, and toasting functions in countertop footprint. Multi-function appliance demand is expanding penetration beyond traditional pop-up formats.
- Specialty Toaster:Dedicated designs for bagels, artisan breads, or sandwich preparation with modified slot geometry and element positioning. Niche positioning limits volume but sustains margin through specialized utility claims.
- Extra-Wide Slot Toaster:Expanded slot dimensions accommodate thick-cut artisan breads and bagels with modified spring-loaded carriage mechanisms. Premium material specifications differentiate offerings in German and North American specialty retail channels.
Pop-Up Toaster leads on scale; Toaster Oven leads on momentum.
Technology:
Power conversion efficiency and thermal response characteristics determine energy compliance positioning and end-user operating economics across regulatory jurisdictions.
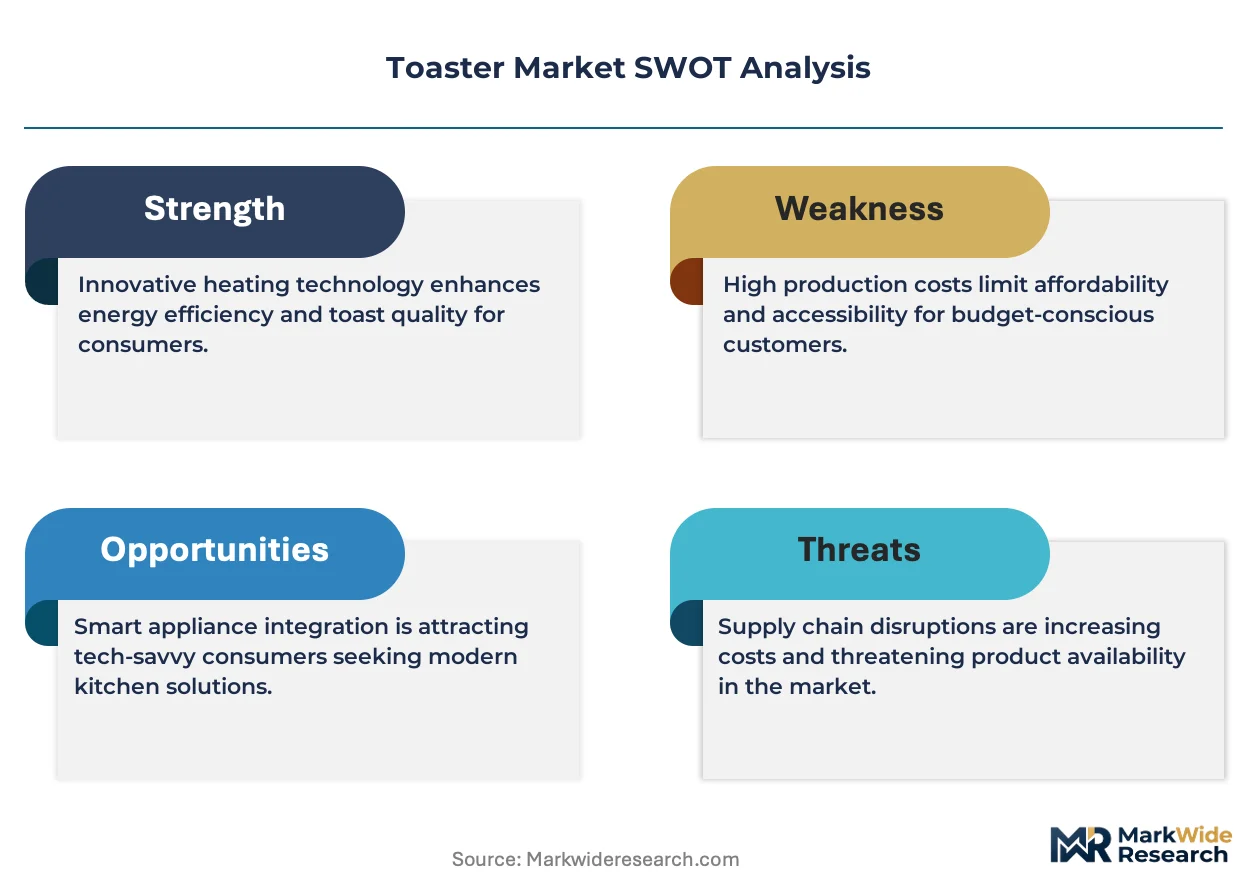
- Electrical Heating:Resistive nichrome wire elements remain the baseline configuration for cost-optimized residential units. REACH compliance and EU Ecodesign standby power thresholds are recalibrating engineering specifications for entry-tier products.
- Quartz Heating:Sealed quartz tubes with coiled tungsten filaments deliver rapid thermal response for premium toaster ovens. Faster preheat cycles attract time-sensitive residential buyers in Japanese and South Korean urban markets.
- Halogen Heating:Tungsten-halogen cycle lamps provide instant radiant heat with visible browning feedback. Energy efficiency positioning struggles against convection alternatives in EU efficiency-rated procurement.
- Convection Heating:Forced-air circulation with auxiliary heating elements enables uniform temperature distribution for baking functions. Toaster oven penetration is climbing fastest where countertop versatility displaces full-size oven usage.
- Infrared Heating:Ceramic or quartz infrared emitters deliver targeted radiant energy with minimal preheat latency. Commercial foodservice operators in high-volume hotel channels are adopting for throughput consistency.
Electrical Heating dominates installed base; Convection Heating is gaining share fastest in multi-function segments.
Power Rating:
Wattage tiers correlate with heating speed, energy consumption profiles, and applicable efficiency regulatory thresholds.
- Low Power:Units rated below 800 watts target single-slice or energy-conscious residential applications. EU Ecodesign standby limits compress engineering margins for this tier.
- Medium Power:800-1200 watt configurations balance heating speed with circuit compatibility in standard residential electrical infrastructure. This tier captures the majority of replacement demand in German apartment renovations.
- High Power:1200-1800 watt ratings enable rapid toasting for family-size loads and commercial light-duty applications. California Energy Commission standards segment market access by efficiency tier in this range.
- Ultra High Power:Exceeding 1800 watts, these units serve commercial conveyor systems and heavy-duty toaster ovens with extended duty cycles. Specialized electrical requirements limit residential penetration.
Medium Power leads on scale; High Power leads on momentum.
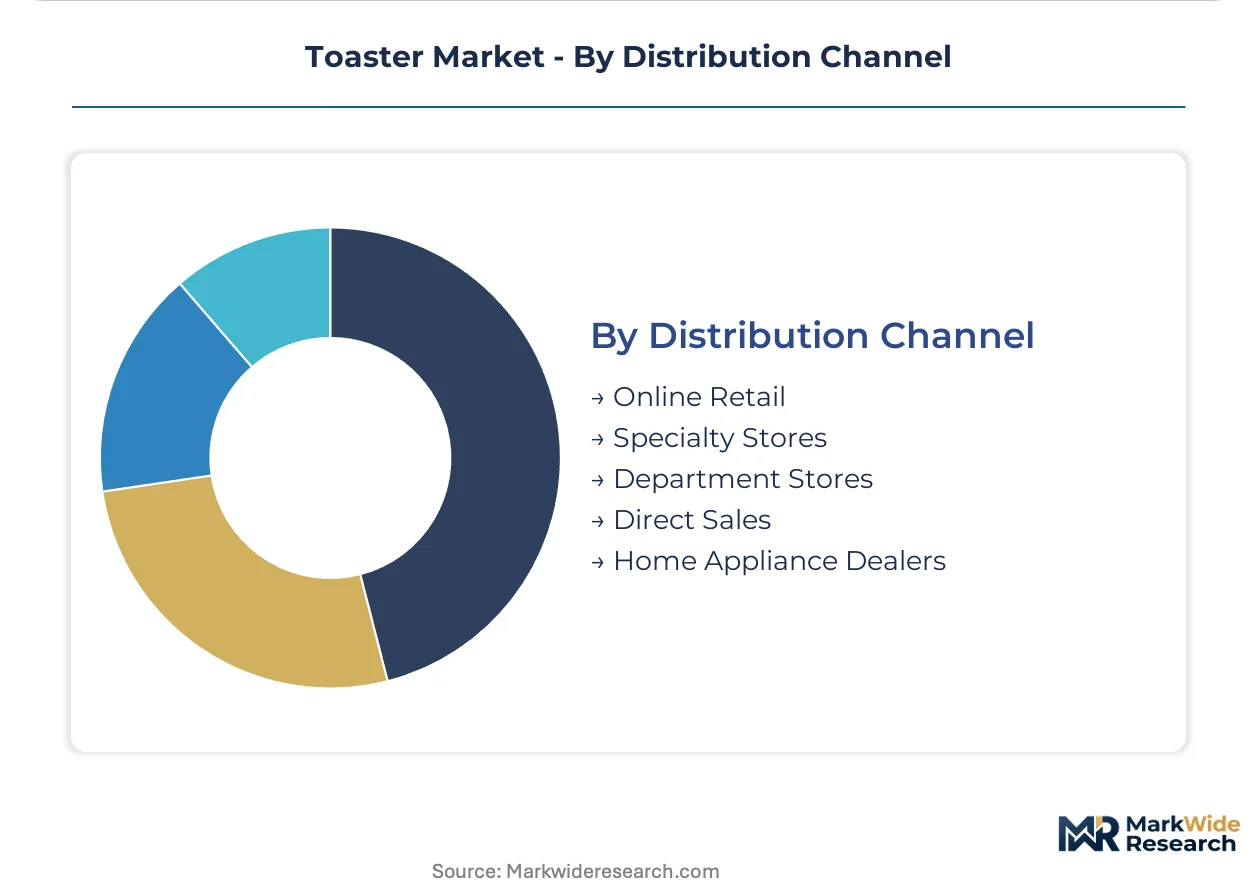
Distribution Channel:
Channel selection determines margin structure, brand positioning, and access to replacement versus new purchase demand.
- Online Retail:E-commerce platforms enable direct-to-consumer access with review-driven purchase decisions. Buyer concentration is displacing traditional wholesale relationships for smart-enabled and premium units.
- Specialty Stores:Kitchen-focused retailers provide tactile evaluation and staff consultation for premium material specifications. German urban markets show strongest specialty channel persistence.
- Department Stores:General merchandise retailers offer mass-market accessibility with promotional pricing velocity. Big-box retailer concentration compresses manufacturer margin structures.
- Direct Sales:Manufacturer-owned channels bypass wholesale markups for connected kitchen ecosystem bundles. Smart-toaster interfaces integrating voice assistants open premium pricing tiers through this channel.
- Home Appliance Dealers:Independent and chain dealers service replacement demand with installation and warranty support. Regional coverage gaps create vulnerability in secondary markets.
Online Retail leads on momentum; Department Stores lead on scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The toaster industry traces its commercial origins to early 20th-century American manufacturing, with General Electric and Westinghouse establishing the first mass-production lines in the United States. This historical foundation shaped subsequent regional specialization patterns across North America, Europe, and Asia-Pacific.
Germany
Premium kitchen renovations in Munich and Hamburg drive replacement demand for energy-rated units. The EU Ecodesign Regulation mandates standby power limits below one watt for new appliance registrations. The Stuttgart industrial corridor hosts component testing facilities certifying heating element assemblies for pan-European distribution.
United States
Mass-market channel concentration through big-box retailers sustains volume throughput for entry-tier pop-up configurations. The EPA ENERGY STAR program segments procurement eligibility by verified efficiency test protocols. The Chicago metropolitan area anchors distribution logistics for North American countertop appliance supply chains.
China
Component manufacturing clusters in Guangdong and Zhejiang provinces supply resistive heating elements and electronic control modules to global assembly operations. The GB standards framework governs domestic appliance safety and electromagnetic compatibility certification. The Pearl River Delta concentrates OEM fabrication capacity serving export markets.
Japan
Quartz and halogen heating technologies command premium positioning among time-sensitive urban consumers in Tokyo and Osaka. METI energy efficiency labeling requirements accelerate replacement of legacy resistive element models. The Nagoya industrial zone maintains precision ceramics manufacturing for advanced heating component substrates.
France
Housing renovation subsidies in Île-de-France and Auvergne-Rhône-Alpes mandate sustainability-certified appliance specifications for subsidized projects. REACH substance restrictions require full material passports documenting chromium compound and nickel alloy sourcing. The Lyon logistics hub coordinates specialty retail distribution for premium toaster oven configurations.
Toaster Market Key Industry Players
The competitive structure tilts toward diversified appliance conglomerates with captive component supply capabilities. Market concentration remains moderate, with no single entity commanding dominant volume share across all product tiers. Three strategic archetypes define positioning: vertically integrated electronics manufacturers, mass-market brand licensors, and premium kitchen specialists. Competitive dynamics center on regulatory compliance cost absorption and direct-to-consumer channel expansion.
Among diversified conglomerates with captive heating element production, Panasonic Corporation occupies a position exemplifying backward integration into core component manufacturing. Hamilton Beach Brands and Breville Group Ltd. represent contrasting archetypes—mass-market channel density versus premium R&D intensity—each anchoring distinct pricing tiers without overlapping positioning.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Hamilton Beach Brands |
| Koninklijke Philips N.V. |
| Black+Decker |
| Cuisinart |
| Breville Group Ltd. |
| De'Longhi Appliances S.r.l. |
| Smeg |
| KitchenAid |
| Others |
Cost & Logistics Intelligence
Silicon carbide heating element modularization is simultaneously compressing thermal response costs and fragmenting supplier power away from traditional nichrome wire producers. This technology transition concentrates procurement leverage among semiconductor-grade ceramic manufacturers in Japan and Germany while eroding margins for legacy heating element assemblers in Guangdong.
Pricing Analysis
Unbundled component sales dominate commercial foodservice procurement, while bundled smart-toaster ecosystems with voice assistant integration command premium residential positioning. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked energy-rated units from uncertified entry-tier products and connected kitchen bundles. Cost compression in sub-800-watt entry tiers is intensifying because EU Ecodesign standby power limits add engineering complexity without pricing power. Mass-market big-box buyers exhibit highest price sensitivity; commercial hotel and cafeteria operators show lowest sensitivity due to throughput durability requirements.
Supply Chain Analysis
Single-source vulnerability sits with resistive heating element and electronic control module production clusters in China, South Korea, and Japan. Nichrome wire supply draws from nickel and chromium spot market volatility; silicon carbide substrates and quartz tube assemblies rest on precision ceramics manufacturing concentrated in Nagoya and Stuttgart. Tariff exposure on component imports into the EU and North America threatens margin structures for non-vertically integrated assemblers. Distribution runs through big-box retail consolidation in the United States, specialty kitchen retailers in Germany, and direct-to-consumer e-commerce platforms displacing traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Toaster Market reads as a late-cycle quality story where replacement demand tilts toward energy-certified and connected specifications rather than commodity volume. German sustainability-certified housing stock and North American smart kitchen adoption are accelerating this premium shift.
For Market Incumbents: Anchor defensive positioning through captive nichrome wire or silicon carbide heating element production to absorb REACH compliance testing costs without margin erosion. Deepen channel control in specialty kitchen retail to offset big-box buyer concentration. Silicon carbide technology substitution and direct-to-consumer entrants threaten legacy cost structures; backward integration into component manufacturing is the critical lever. For New Entrants and Emerging Players: Capture white-space in commercial conveyor toaster durability specifications exceeding current supply for high-volume hotel and cafeteria channels. Target smart-toaster interface development for voice assistant integration where incumbent R&D intensity lags. A direct-to-consumer go-to-market angle with material passport transparency bypasses wholesale margin compression. For Investors and Strategic Acquirers: Valuations sit cheapest among mass-market brand licensors without captive component supply or energy certification positioning. Long-term viability favors manufacturers with established circular supply chains and EU Ecodesign compliance infrastructure. Watch German housing renovation subsidy renewal cycles as the inflection signal for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Heating Element Adoption | Modularizes supplier base as Nagoya ceramics manufacturers enter appliance component markets. |
| CE Marking and EU Ecodesign Compliance Investment | Creates regulatory moat against uncertified competitors in German and French housing renovation channels. |
| Direct-to-Consumer Channel Expansion | Bypasses big-box retailer margin compression for smart-enabled and premium material specification units. |
| Material Passport and Circular Supply Chain Development | Meets REACH disclosure requirements for chromium compounds and nickel alloys in German distribution. |
| Smart-Toaster Voice Assistant Integration | Opens premium pricing tiers through connected kitchen ecosystem bundles in North American urban markets. |
Research Approach
Direct dialogue with product development engineers at heating element manufacturers, category buyers at big-box retailers, regulatory compliance officers at appliance brands, and procurement managers at commercial foodservice operators grounded this analysis. Secondary validation drew from EU Ecodesign regulation filings, EPA ENERGY STAR certified product databases, customs records for nichrome wire and silicon carbide substrate trade flows, and SEC 10-K disclosures from diversified appliance conglomerates. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segmented outputs across product format, heating technology, power rating tier, and distribution channel calibrated penetration rates and replacement cycle velocities. Modeled CAGRs incorporated housing renovation subsidy trajectories, standby power limit phase-in schedules, and smart appliance adoption curves. Heating element raw material spot price volatility, firmware certification timeline extensions, and cross-regional efficiency test protocol divergence served as key forecast sensitivity inputs.
Raw material cost spikes, regulatory timeline accelerations, and smart-toaster interface standardization failures are the dominant revision risks for projection accuracy. Forecasts embed assumptions about subsidy continuity and certification harmonization that may shift with policy changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Kitchen Appliances Market